
 Inland Water Freight Transport Market | 2026-2036
Inland Water Freight Transport Market Size, Share, and Industry Trends Forecast 2026-2036
Inland Water Freight Transport Market Foresight
Licensed marine pilots and towboat deckhands is reorganizing fleet deployment schedules across North American waterways. Ingram Barge leverages its integrated terminal network to control origination points for coal and grain movements. Kirby Inland Marine anchors liquid cargo transport through its tank barge fleet serving petrochemical corridors along the Gulf Intracoastal Waterway. Rhenus Group operates multimodal hubs connecting Rhine barge services to continental rail and road networks.
Inland water freight transport encompasses the movement of goods via navigable rivers, canals, lakes, and inland seas using vessels with draft depths typically under four meters, operating within confined waterway systems rather than open ocean routes. The primary purpose centers on bulk commodity logistics, where single tows moving fifteen to forty barges achieve fuel efficiency metrics roughly five to seven times lower per ton-mile than comparable truck movements. Bulk cargo commands the dominant share of volume moved, reflecting structural reliance on waterborne corridors for coal, grain, and ore movements where delivery speed remains secondary to unit cost minimization. Containerized cargo represents the fastest-expanding segment, driven by shippers seeking relief from highway congestion and chassis shortages through 53-foot box-on-barge services on select corridors.
The U.S. Coast Guard enforces Subchapter M towing vessel regulations mandating inspection regimes and safety management systems that elevate operating costs for smaller fleet operators. The European Union's F-Gas Regulation and Green Deal framework push vessel operators toward emission-reduction retrofits and alternative fuel trials on Rhine and Danube corridors. The International Maritime Organization's inland navigation standards shape design certifications for cross-border European operations. Stakeholders must weigh fleet renewal cycles against regulatory compliance timelines while monitoring lock infrastructure funding decisions that determine effective network capacity.
Market Dynamics
Lock-and-dam modernization across the Mississippi River Basin is compressing transit times for bulk commodity movements while reshaping fleet deployment economics for barge operators serving grain export corridors.
Growth Catalysts
- EU Green Deal framework:The European Union's emission-reduction mandates are accelerating retrofits and alternative fuel trials on Rhine and Danube corridors, expanding addressable fleet capacity for compliant operators.
- Containerized cargo conversion:Shippers seeking relief from highway congestion are migrating 53-foot box volumes to barge services on select waterways, opening new revenue streams beyond traditional bulk.
- China:Dual carbon goals under MEE oversight are redirecting domestic coal and ore movements toward inland waterway networks to reduce trucking emissions across the Yangtze River Basin.
Market Restraints
- Steel price volatility:New barge construction and hull maintenance face input cost pressure from fluctuating steel plate markets, squeezing fleet renewal timelines for smaller operators.
- Subchapter M compliance:The U.S. Coast Guard's towing vessel inspection rules mandate safety management systems that elevate fixed costs disproportionately for sub-fifty-vessel fleets.
- Truck-rail substitution:Intermodal rail corridors and autonomous trucking pilots on parallel freight routes threaten price-sensitive cargo segments where waterborne transit times already lag.
Strategic Opportunities
- Battery-electric propulsion:Converging lithium-ion storage density gains and shore-charging infrastructure trials on European canals are creating zero-emission service tiers for ESG-mandated shippers.
- Midwest manufacturing reshoring:Industrial facility relocations to Ohio River Valley states are generating new origin-destination pairs for chemical and steel feedstock movements.
- India:PLI scheme incentives for domestic manufacturing are expanding containerized cargo volumes on the National Waterway-1 corridor connecting Haldia to Varanasi.
Industry Challenges
- Licensed marine pilot scarcity:Towboat deckhand training pipelines and Coast Guard credentialing backlogs are constraining crew availability during peak grain harvest windows.
- Subchapter M audit preparation:Smaller operators face documentation and third-party organizational burden to achieve towing safety management system certification before enforcement deadlines.
- Legacy dispatch system integration:Fleet management software modernization requires capital outlay and operational downtime that conflicts with utilization-maximization imperatives.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Inland Water Freight Transport Market |
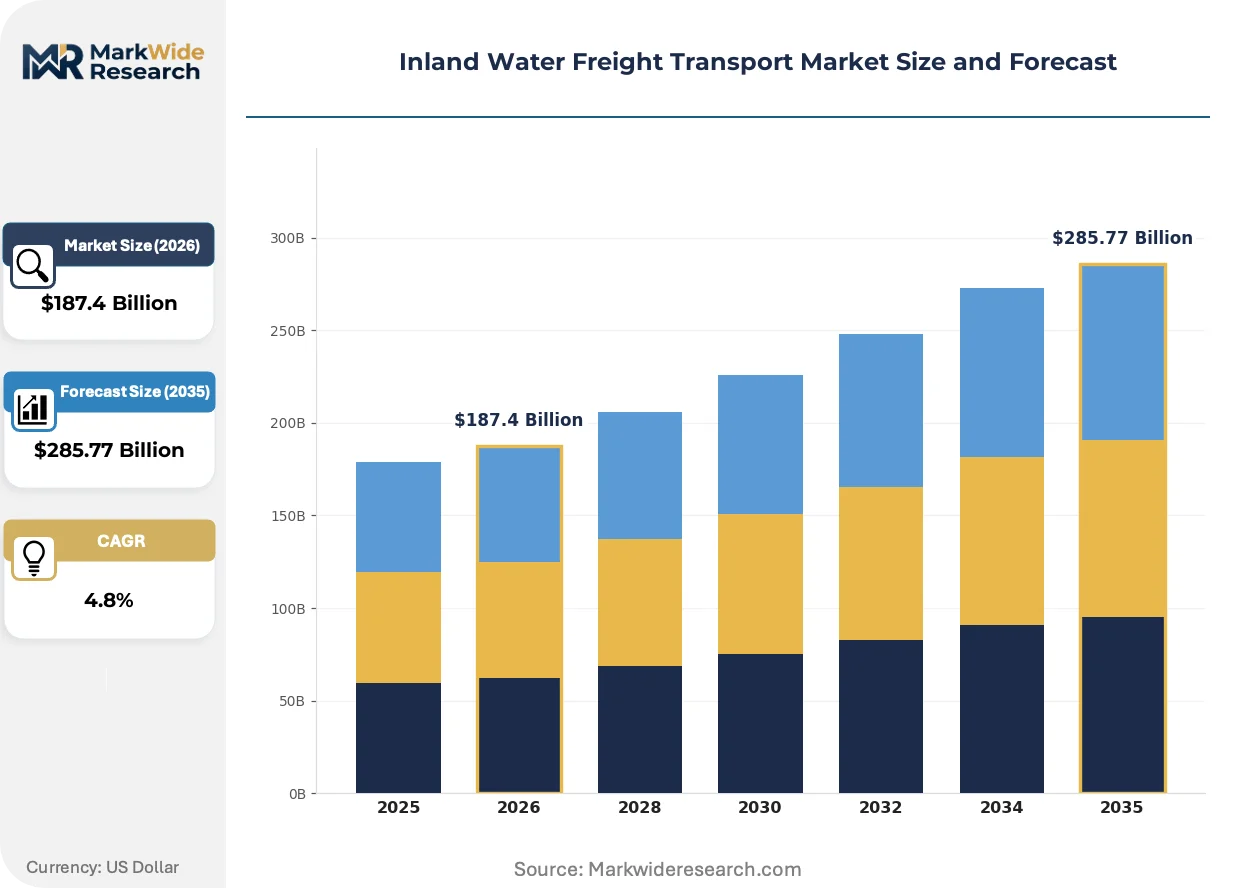
| Market Size in 2026 | $187.4 Billion |
| Market Size in 2035 | $285.77 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Bulk Cargo, Containerized Cargo, Project Cargo, Liquid Cargo Vessel Type: Barges, Tugs, Tankers, Cargo Ships End User: Agriculture Sector, Manufacturing Industry, Mining Sector, Retail Sector Load Capacity: Small Scale, Medium Scale, Large Scale, Extra Large |
| Companies Covered | Ingram Barge, Kirby Inland Marine, American Commercial Barge Line, CMA CGM Group, Rhenus Group, American River Transportation, A P Moller – Maersk A/S, Contargo, Danser Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Inland Water Freight Transport Market Shifts & Advancements
Digital fleet optimization and emission-control technologies are compressing operating cost structures while regulatory compliance mandates are accelerating capital deployment into vessel retrofits and alternative propulsion systems.
Hybrid diesel-electric propulsion architectures are supplanting conventional single-engine towboat configurations on high-frequency routes. Kirby Inland Marine and European operators on the Rhine are retrofitting existing hulls with battery-assist systems to reduce fuel consumption during lock transits. This technology is supplanting traditional horsepower-per-ton metrics as the primary fleet efficiency benchmark among petrochemical and agricultural shippers.
The EU F-Gas Regulation and companion Green Deal framework are mandating refrigerant phase-downs and emission monitoring equipment on refrigerated barge units serving food and pharmaceutical corridors. Operators face retrofit deadlines that compress vessel downtime windows during already constrained navigation seasons. Rhine-based cold-chain services are responding by consolidating refrigerated volumes onto dedicated vessel classes to amortize compliance costs across higher payload factors.
Shipper procurement patterns are migrating from annual rate contracts toward index-linked agreements tied to diesel fuel benchmarks and lock queue duration metrics. Agricultural exporters in the Mississippi River Basin are negotiating volume commitments with barge operators that incorporate weather-derived delivery window flexibility. This behavioral shift is most visible among grain traders supplying Gulf Coast export terminals, where basis risk management now extends to waterborne freight cost volatility.
Inland Water Freight Transport Market Segmentation
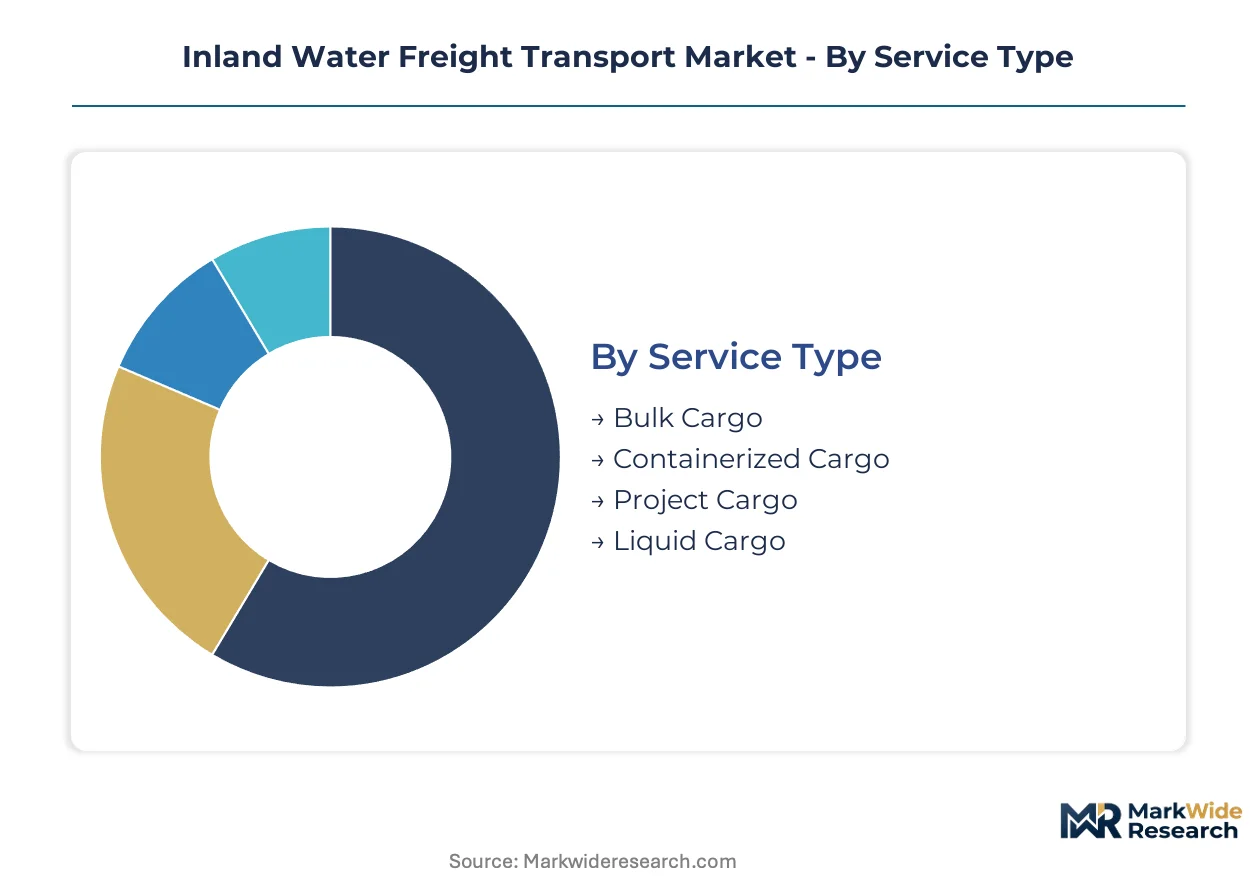
Segmentation in inland water freight transport reveals how regulatory frameworks and infrastructure constraints reshape service economics across cargo types and vessel classes. Operators align fleet composition with specific corridor capabilities and end-user compliance requirements.
Service Type:
EU F-Gas Regulation and U.S. Coast Guard Subchapter M rules create divergent compliance burdens across cargo categories, elevating fixed costs for temperature-controlled and liquid bulk movements.
- Bulk Cargo:Coal, grain, and ore movements dominate tonnage on the Mississippi River Basin and Yangtze River corridors. Agricultural exporters in Iowa and Illinois concentrate harvest-season demand through Gulf Coast grain terminals, though lock queue delays compress delivery windows during peak periods.
- Liquid Cargo:Petrochemical feedstocks and refined products move via dedicated tank barge fleets along the Gulf Intracoastal Waterway. The U.S. Coast Guard mandates double-hull configurations and vapor recovery systems that extend vessel construction timelines and elevate capital deployment thresholds for operators serving Houston Ship Channel refineries.
- Containerized Cargo:53-foot box-on-barge services expand on European canals and select U.S. corridors as shippers seek highway congestion relief.
- Project Cargo:Oversized industrial equipment and wind turbine components require specialized deck barges with reinforced loading configurations.
Established volume favors bulk cargo; emerging adoption favors containerized cargo.
Vessel Type:
Cost tier differentiation separates capital-intensive tanker newbuilds from modular barge fleets that permit incremental capacity expansion.
- Barges:Flat-deck and hopper configurations constitute the modular building blocks of inland tows, with fifteen to forty units lashed behind single towboats on the Mississippi River system. Agricultural shippers in the Ohio River Valley prioritize covered hopper barges for grain protection, while petrochemical corridors demand heated tank barges for viscosity-sensitive cargoes.
- Tugs:Towboats ranging from 1,000 to 10,000 horsepower propel barge tows through lock chambers and against river currents. The U.S. Coast Guard's updated towing vessel inspection rules mandate safety management systems that disproportionately burden operators with sub-fifty-vessel fleets, accelerating consolidation among independent operators.
- Tankers:Self-propelled liquid cargo vessels serve shorter-haul chemical corridors where towboat-barge assembly proves uneconomical.
- Cargo Ships:Larger self-propelled vessels operate on Great Lakes and European inland sea routes with draft restrictions above standard riverine limits.
Modular economics favor barges; integrated operations favor self-propelled tankers and cargo ships.
End User:
Application-specific requirements determine fleet deployment patterns, with agricultural harvest windows and manufacturing just-in-time schedules imposing conflicting utilization pressures.
- Agriculture Sector:Grain and oilseed movements concentrate during September through November harvest windows, demanding surge capacity from barge operators serving Mississippi River export terminals. Basis risk management now incorporates waterborne freight cost volatility through index-linked contracting structures.
- Manufacturing Industry:Chemical, steel, and automotive feedstock movements require scheduled delivery precision that conflicts with agricultural seasonality. Midwest manufacturing reshoring to Ohio River Valley states generates new origin-destination pairs for chemical and steel feedstock barge movements.
- Mining Sector:Coal and ore movements redirect toward inland waterways under China's MEE dual carbon goals to reduce trucking emissions.
- Retail Sector:Containerized consumer goods movements remain nascent but expand as chassis shortages and highway congestion elevate intermodal barge competitiveness.
Seasonal intensity favors agriculture; schedule reliability favors manufacturing.
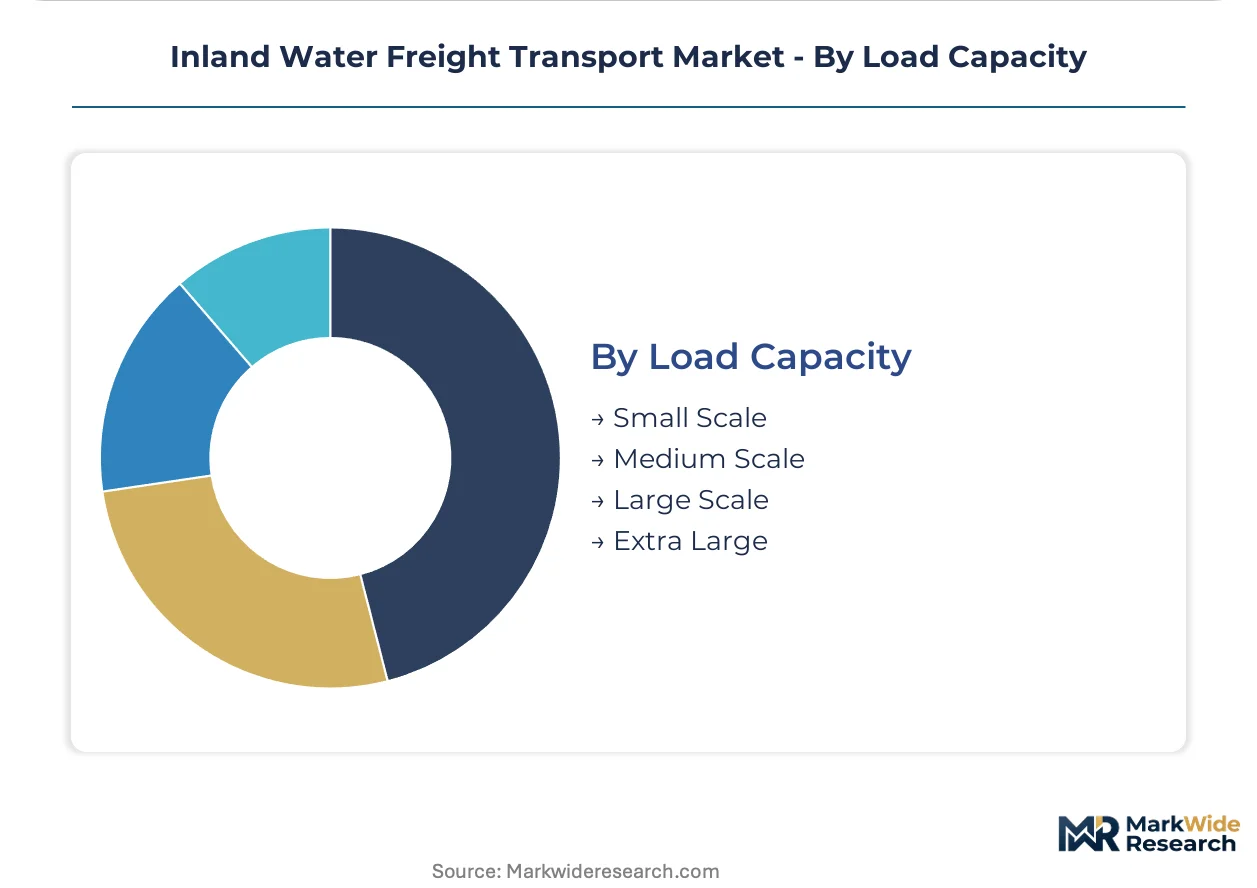
Load Capacity:
Lock chamber dimensions and draft restrictions constrain optimal vessel sizing, with infrastructure bottlenecks determining effective payload economics.
- Large Scale:Fifteen-barge tows moving 22,500 tons represent the throughput-optimized configuration for modernized Mississippi River lock chambers. Grain exporters negotiate volume commitments incorporating weather-derived delivery flexibility to manage basis risk across harvest windows.
- Medium Scale:Eight to twelve barge tows serve tributary rivers and European canals with restrictive lock dimensions. Rhine corridor operators consolidate refrigerated volumes onto dedicated vessel classes to amortize EU F-Gas Regulation compliance costs.
- Small Scale:Single to four barge tows access shallow-draft tributaries and urban canal networks.
- Extra Large:Maximum-tow configurations push lock chamber capacity limits on select corridors.
Infrastructure compatibility favors large scale; network access favors medium and small scale.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States moves bulk commodities through riverine corridors where fuel efficiency outweighs speed, while European operators prioritize emission-compliant refrigerated services and China's inland network redirects heavy industrial cargo away from highways.
United States
Grain exporters in Iowa and Illinois concentrate harvest-season demand through Gulf Coast terminals, while petrochemical shippers along the Houston Ship Channel require specialized tank barge configurations. The U.S. Coast Guard's Subchapter M towing vessel regulations mandate safety management systems that elevate fixed costs disproportionately for smaller fleet operators. Lock-and-dam modernization across the Mississippi River Basin is compressing transit times and reshaping fleet deployment economics for barge operators serving agricultural export corridors.
Germany
Rhine corridor operators consolidate refrigerated cargo volumes onto dedicated vessel classes to amortize compliance costs across higher payload factors. The EU F-Gas Regulation mandates refrigerant phase-downs and emission monitoring equipment on temperature-controlled barge units serving pharmaceutical and food supply chains. Industrial chemical movements concentrate around the BASF Ludwigshafen complex and surrounding Rhineland-Palatinate manufacturing clusters, where multimodal hubs connect barge services to continental rail networks.
China
Domestic coal and ore movements are redirecting toward inland waterway networks under MEE dual carbon goals to reduce trucking emissions across the Yangtze River Basin. The Ministry of Ecology and Environment oversees carbon intensity targets that favor waterborne freight over highway alternatives for heavy bulk commodities. Manufacturing reshoring in Sichuan-Chongqing and the Yangtze River Delta is expanding containerized cargo volumes on integrated river-sea routes.
Netherlands
Rotterdam's hinterland connectivity demands high-frequency barge services linking Europe's largest seaport to inland distribution terminals across the Rhine-Meuse-Scheldt delta. The EU Green Deal framework accelerates retrofits and alternative fuel trials on Dutch canal networks, expanding addressable fleet capacity for compliant operators. Contargo operates multimodal hubs in the Randstad region connecting Rhine barge services to continental rail and road networks.
India
PLI scheme incentives for domestic manufacturing are expanding containerized cargo volumes on the National Waterway-1 corridor connecting Haldia to Varanasi. The Inland Waterways Authority of India oversees infrastructure development along the Ganga-Bhagirathi-Hooghly river system. Steel and cement movements concentrate around the Jharkhand-West Bengal industrial belt, where shallow-draft barges access tributary rivers during monsoon navigation windows.
Inland Water Freight Transport Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with consolidation pressures accelerating among sub-fifty-vessel operators facing disproportionate compliance burdens. The market structure reflects capital intensity differentials between modular barge fleets and self-propelled tanker newbuilds. Strategic archetypes include integrated terminal-network operators, liquid cargo specialists with dedicated tank barge fleets, and multimodal hub managers connecting waterborne services to continental rail networks. Competitive moves concentrate on fleet renewal cycles aligned with regulatory compliance timelines and strategic partnerships securing origination point control.
Among North American integrated operators, Ingram Barge and Kirby Inland Marine exemplify contrasting strategic positions within the sector. Ingram Barge occupies a position emphasizing terminal network control over agricultural and coal origination points, while Kirby Inland Marine anchors liquid cargo transport through specialized tank barge configurations. European multimodal specialists include Rhenus Group, which sits within the hub-management archetype connecting Rhine barge services to continental rail and road networks. These three companies represent distinct capital deployment models—terminal-integrated bulk, dedicated liquid cargo, and multimodal hub coordination—that define competitive positioning across regional corridor economics.
| Leading Market Players |
|---|
| Ingram Barge |
| Kirby Inland Marine |
| American Commercial Barge Line |
| CMA CGM Group |
| Rhenus Group |
| American River Transportation |
| A P Moller – Maersk A/S |
| Contargo |
| Danser Group |
| Others |
Supply & Pricing Matrix
Lithium-ion battery propulsion retrofits are displacing conventional diesel towboat configurations across European canal networks, simultaneously redrawing equipment supplier geographies and compressing capital recovery timelines for fleet operators weighing emission compliance against utilization rates.
Pricing Analysis
Long-term offtake contracts tied to diesel fuel benchmarks dominate agricultural bulk movements on the Mississippi River Basin, while index-linked agreements incorporating lock queue duration metrics are displacing annual rate structures among grain traders supplying Gulf Coast export terminals. Price differentiation separates ESG-mandated shippers paying premiums for battery-electric service tiers from price-sensitive coal and ore buyers prioritizing unit cost minimization over transit speed. Pricing pressure stems from steel plate volatility squeezing new barge construction timelines and Subchapter M compliance elevating fixed costs for sub-fifty-vessel fleets. Agricultural exporters exhibit highest price sensitivity during harvest windows, whereas petrochemical shippers along the Houston Ship Channel demonstrate lower elasticity due to specialized tank barge requirements.
Supply Chain Analysis
Lock chamber bottlenecks at Mississippi River dams constitute the critical chokepoint constraining effective network capacity for fifteen-barge tows moving grain to Gulf Coast terminals. Steel plate fabrication draws from mills in the United States, China, and Germany, while lithium-ion battery systems for electric propulsion retrofits rest on South Korean and Japanese cell manufacturers. Single-source vulnerability pervades specialized towboat engine suppliers serving inland marine corridors. Distribution runs through integrated terminal networks controlled by major barge operators, with origination point access determining competitive positioning for agricultural and coal movements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Interoperability between digital fleet optimization platforms and shore-charging infrastructure is creating platform-economics dynamics where ecosystem participation determines access to ESG-mandated shipper contracts.
For Market Incumbents: Compound terminal network control by securing origination points for Midwest manufacturing reshoring flows to Ohio River Valley states, while accelerating safety management system certification ahead of Subchapter M enforcement deadlines to capture distressed fleet capacity from smaller operators facing disproportionate compliance burdens. Vertical integration into shore-charging infrastructure along high-frequency European canal routes locks in zero-emission service tier premiums. For New Entrants and Emerging Players: Lead with battery-electric propulsion offerings targeting ESG-mandated pharmaceutical and food shippers on Rhine refrigerated corridors, where EU F-Gas Regulation compliance costs have consolidated incumbent refrigerated volumes onto dedicated vessel classes. Containerized 53-foot box-on-barge services between congested highway corridors and inland distribution terminals represent the most penetrable white space. A go-to-market angle emphasizing weather-derived delivery flexibility through index-linked contracting structures differentiates against incumbent annual rate structures. For Investors and Strategic Acquirers: The market sits at a regulatory-compliance inflection phase that favors sub-fifty-vessel fleet consolidation targets with modernized hull configurations and documented safety management systems. Long-term viability across the analysis window hinges on exposure to agricultural export corridor modernization and alternative fuel trial participation. The signal to watch is lock-and-dam appropriation funding decisions determining effective Mississippi River Basin throughput capacity.| Strategic Initiative | Industry Significance |
|---|---|
| Battery-Electric Fleet Retrofit | EU Green Deal compliance unlocks ESG-mandated shipper premiums on Rhine corridors. |
| Terminal Network Expansion | Ohio River Valley positioning captures manufacturing reshoring feedstock flows. |
| Safety Management Certification | Subchapter M compliance separates consolidators from distressed smaller operators. |
| Index-Linked Contract Structuring | Weather-derived flexibility attracts agricultural exporters managing basis risk. |
| Multimodal Hub Integration | Rhine barge-rail connectivity expands addressable cargo beyond pure waterborne origins. |
Research Methodology
Desk research of customs trade databases, SEC vessel operator filings, and EU transport emission registries preceded structured interviews with towboat fleet managers, agricultural commodity traders, petrochemical procurement leads, and lock infrastructure engineers. Primary fieldwork across Mississippi River Basin terminals and Rhine corridor multimodal hubs validated secondary volume and rate assumptions. Bottom-up barge movement tallies triangulated against top-down commodity flow estimates from national grain export statistics and petrochemical refinery throughput disclosures.
Variance decomposition across cargo type, vessel class, and corridor-specific lock capacity constraints shaped the analytical framework throughout the projection horizon. Segmentation dimensions modeled include service type differentiation between bulk, liquid, containerized, and temperature-controlled cargo; load capacity tiers constrained by lock chamber dimensions; and end-user seasonality patterns across agricultural harvest windows versus manufacturing just-in-time schedules. CAGRs derived from fleet renewal cycle timing against regulatory compliance deadlines, with infrastructure funding appropriations and steel plate price indices serving as key forecast sensitivity inputs.
Forecasts assume regulatory continuity in U.S. Coast Guard Subchapter M enforcement and EU F-Gas Regulation refrigerant phase-down schedules; material policy shifts in towing vessel inspection regimes or emission retrofit mandates would require re-modeling effective fleet capacity and compliance cost structures. Practitioners should keep alternative scenarios live as lock modernization appropriation timelines and alternative fuel infrastructure deployment rates evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Transportation & Logistics
Saudi Arabia Land-Based Fuel Transportation Market
Transportation & Logistics
United States Short Haul Road Freight Transport Market
Transportation & Logistics
Perishable Goods Transportation Market
Transportation & Logistics
Global Fourth Party Logistics Market
Transportation & Logistics
India Road Freight Transport Market
Transportation & Logistics
Slovakia Road Freight Transport Market
Transportation & Logistics
Hong Kong Customs Brokerage Market
Transportation & Logistics
Road Haulage Market
Transportation & Logistics
Refrigerated Road Transportation Market
Transportation & Logistics
Indonesia Refrigerated Trailer Market
Transportation & Logistics
Customs Brokerage Market
Transportation & Logistics
Latin America Inland Waterway Transport Market
Transportation & Logistics
Europe Freight and Logistics Market
Transportation & Logistics
US Reverse Logistics Market
Transportation & Logistics
Chile Road Freight Transport Market
Transportation & Logistics
United States less than-Truck-Load (LTL) Market