
 Welding Chemicals Market | 2026-2036
Welding Chemicals Market Size, Share, and Industry Trends Forecast 2026-2036
Welding Chemicals Market Analytics
China is reshaping capacity dynamics through expanded argon and carbon dioxide production for domestic shielding gas supply. ESAB leverages its electrode manufacturing footprint across Asia to sustain regional availability of specialty filler metals. Linde plc anchors industrial gas distribution through on-site generation contracts with major automotive stamping plants. Air Liquide competes via merchant liquid supply networks that extend into secondary fabrication clusters.
Welding chemicals encompass consumable and ancillary materials that enable or improve fusion joining processes, including fluxes with specified basicity indices, alloyed filler wires meeting tensile strength grades, and inert or active shielding gases with defined purity thresholds. These formulations protect molten weld pools from atmospheric contamination, control bead geometry, and determine final joint mechanical properties. Filler metal commands the largest value share due to alloy complexity and volume pull from automated MIG/MAG lines, while shielding gas generates recurring revenue through bulk tanker and cylinder refill programs. Cleaning agents represent a smaller but faster-growing segment as pre-weld surface preparation standards tighten across aerospace sub-tier suppliers.
OSHA exposure limits for hexavalent chromium and manganese fume directly influence flux and consumable design priorities in the United States. REACH substance restrictions and the EU F-Gas Regulation constrain formulation choices for European producers, particularly for fluorinated components in flux-cored products. ECHA evaluations of metal oxide classifications further pressure suppliers to document safe-use scenarios. Stakeholders must monitor how evolving weld fume reclassification as carcinogenic in multiple jurisdictions redirects procurement specifications toward low-emission process alternatives.
Market Dynamics
Flux-cored wire technology is displacing solid wire in automated shipyard welding, compressing cycle times while triggering reformulation of slag chemistry to meet fume emission thresholds. This shift concentrates procurement power among tier-one shipbuilders capable of validating new consumable specifications.
Growth Catalysts
- Automotive lightweighting mandates:OEMs in Germany and the United States specify high-strength steel grades requiring specialized filler metal alloys that command premium positioning.
- REACH substance restrictions:ECHA evaluations of manganese oxide classifications push European fabricators toward low-fume flux formulations that reduce ventilation retrofit costs.
- Shipyard automation:Korean and Chinese yards deploy robotic MAG welding at scale, sustaining bulk demand for shielding gas mixtures with precise argon-carbon dioxide ratios.
Market Restraints
- Argon supply concentration:Air separation capacity clusters in industrial corridors near steel mills, exposing distant fabrication clusters to tanker logistics premiums.
- Fluorite input volatility:Basic flux formulations depend on acid-grade fluorspar from concentrated mining districts, transmitting price swings into electrode coating costs.
- Substitution by friction stir welding:Aerospace tier-one suppliers qualify solid-state joining for aluminum fuselage sections, eliminating consumable demand in select applications.
Strategic Opportunities
- India infrastructure build-out:National highway and metro rail projects generate first-time specification of rutile flux-cored wire among domestic contractors.
- EU F-Gas Regulation phase-down:Restrictions on fluorinated greenhouse gases create openings for fluorine-free flux formulations in structural steel fabrication.
- Remote gas monitoring:IoT-enabled cylinder telemetry allows distributors to unbundle predictive refill services from commodity gas contracts.
Industry Challenges
- Welding engineer shortage:Qualified procedure writers capable of qualifying WPS/PQR documentation for exotic alloys remain scarce in emerging fabrication hubs.
- Dual certification timelines:Suppliers must synchronize AWS A5 and EN ISO 17632 approvals to serve transatlantic OEMs, extending product launch cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Welding Chemicals Market |
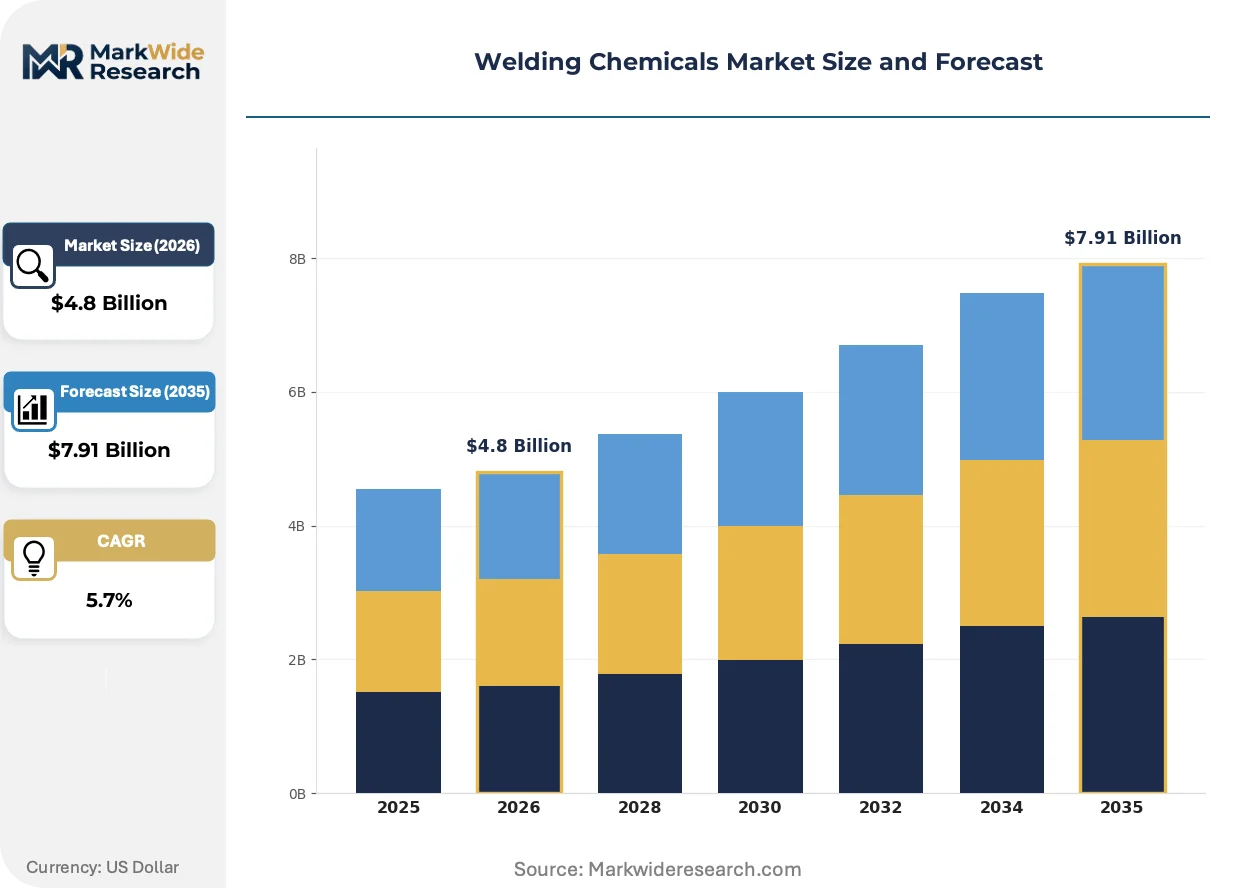
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flux, Filler Metal, Shielding Gas, Cleaning Agent Application: Automotive Manufacturing, Construction, Aerospace, Shipbuilding End User: Fabricators, OEMs, Repair Shops, Maintenance Providers Distribution Channel: Direct Sales, Online Sales, Distributors, Retailers |
| Companies Covered | Air Liquide, Air Products & Chemicals, Inc., Linde plc, ESAB, Illinois Tool Works Inc., The Lincoln Electric Company, Messer Group GmbH, Taiyo Nippon Sanso Corporation, Iwatani Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Welding Chemicals Market Evolving Landscape
Weld process data is becoming a tradable asset, with arc parameter logging enabling predictive quality systems that reshape how fabricators contract for consumable supply. This convergence of metallurgy and analytics redefines value capture across the value chain.
Wire arc additive manufacturing is digitizing deposition control in aerospace repair operations. NASA and ESA contractors deploy robotic cold metal transfer to rebuild titanium compressor blades. Real-time seam tracking algorithms adjust travel speed and weave pattern, compressing qualification timelines for flight-critical components.
ECHA's ongoing evaluation of weld fume carcinogenicity is forcing reformulation of manganese-bearing consumables across European structural steel. Fabricators in the Netherlands and Denmark now specify low-manganese solid wire for indoor construction. Suppliers accelerate development of nickel-titanium transfer modes that reduce fume generation rates without sacrificing deposition efficiency.
Consolidated buying groups at German automotive stamping plants are displacing spot purchases with multi-year consumable management contracts. Tier-one suppliers bundle filler metal, shielding gas, and technical support into single-source agreements. This pattern concentrates vendor qualification decisions among procurement teams in Stuttgart and Wolfsburg.
Welding Chemicals Market Segmentation
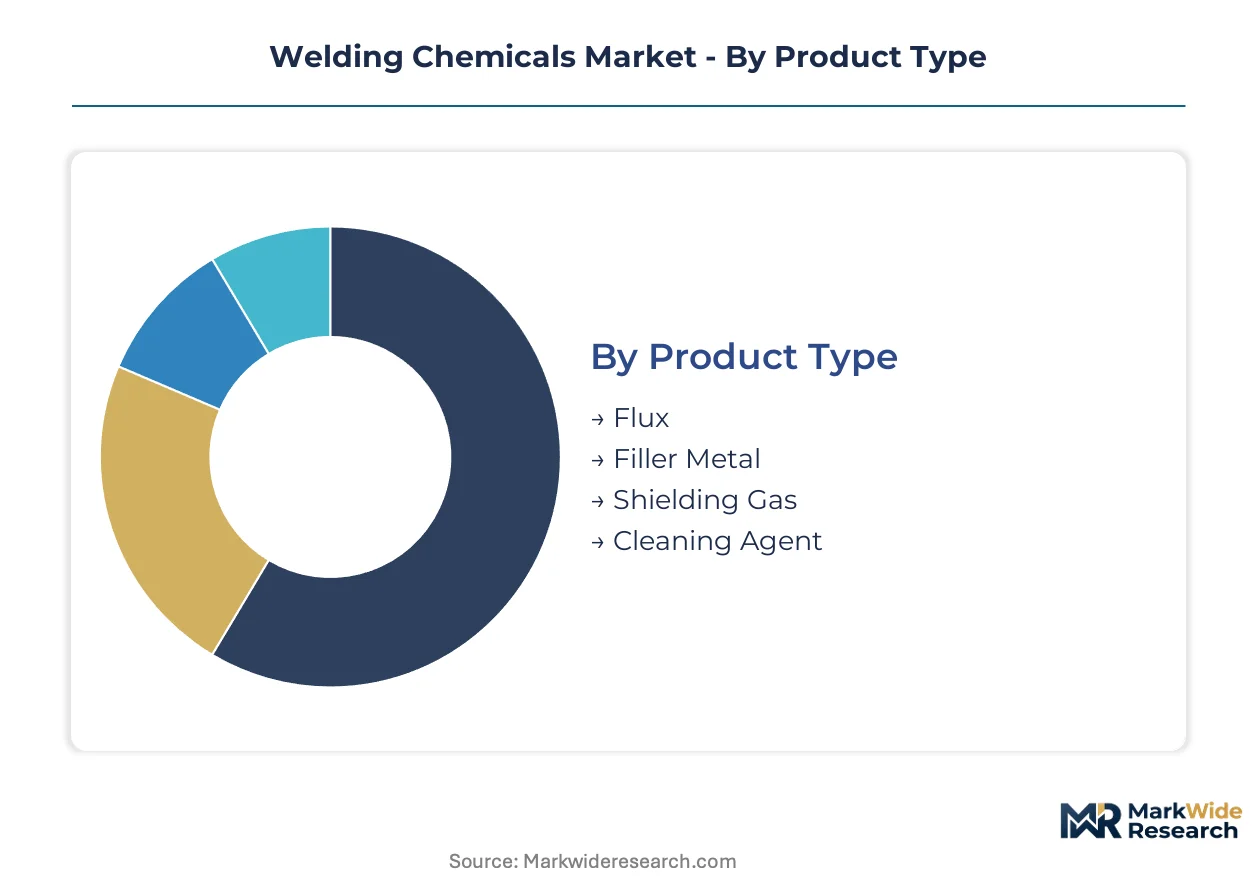
Welding chemicals segment along four intersecting dimensions that determine specification rigor, procurement cadence, and margin structure. Product chemistry dictates performance thresholds, while application verticals impose distinct certification and fume emission requirements. End-user scale shapes contract terms, and channel choice reflects inventory velocity versus technical service needs.
Product Type:
Mature categories dominate revenue tonnage while emerging formulations capture reformulation premiums driven by regulatory pressure.
- Filler Metal:Alloyed wires and electrodes meeting tensile strength grades from AWS A5 and EN ISO specifications command the largest value share. Demand concentrates in German and United States automotive stamping plants where OEMs specify high-strength steel grades requiring specialized compositions.
- Shielding Gas:Argon-carbon dioxide mixtures and pure inert gases with defined purity thresholds protect molten weld pools from atmospheric contamination. Chinese shipyards and Korean yards sustain bulk consumption through robotic MAG welding lines that require precise gas ratios.
- Flux:Formulations with specified basicity indices control bead geometry and slag removal. REACH substance restrictions on manganese oxide classifications push European fabricators toward low-fume alternatives.
- Cleaning Agent:Pre-weld surface preparation chemicals remove oxides and contaminants before fusion joining. Aerospace sub-tier suppliers in France and Italy drive specification tightening as cleanliness standards escalate for flight-critical joints.
Filler Metal retains volume leadership; Cleaning Agent holds the steepest expansion curve.
Application:
Cost tier separation runs from premium-certified aerospace work to price-sensitive infrastructure construction.
- Automotive Manufacturing:OEM welding lines in Stuttgart, Wolfsburg, and Detroit specify consumable bundles combining filler metal, shielding gas, and technical support. Lightweighting mandates for high-strength steel grades require specialized alloys that command premium positioning.
- Shipbuilding:Korean and Chinese yards deploy flux-cored wire technology at scale to compress cycle times in automated hull welding. Procurement power concentrates among tier-one shipbuilders capable of validating new consumable specifications.
- Aerospace:Tier-one suppliers qualify solid-state joining alternatives for aluminum fuselage sections, eliminating consumable demand in select applications. NASA and ESA contractors deploy robotic cold metal transfer for titanium compressor blade repair.
- Construction:Structural steel fabrication in the Netherlands and Denmark now specifies low-manganese solid wire for indoor work following ECHA carcinogenicity evaluations.
Automotive Manufacturing retains volume leadership; Shipbuilding holds the steepest expansion curve.
End User:
Customer type determines contract structure from multi-year framework agreements to spot purchases.
- OEMs:Consolidated buying groups at automotive stamping plants displace spot purchases with bundled consumable management contracts spanning filler metal, shielding gas, and technical support.
- Fabricators:Independent metalworking shops across India's national highway and metro rail projects generate first-time specification of rutile flux-cored wire among domestic contractors.
- Repair Shops:Maintenance welding operations require rapid availability of standard electrodes and MIG wire through distributor networks.
- Maintenance Providers:Industrial facility contractors source cleaning agents and specialty alloys for turnaround campaigns and equipment life extension.
OEMs retain volume leadership; Fabricators hold the steepest expansion curve.
Distribution Channel:
Supply concentration varies from direct mill relationships to fragmented retail counters.
- Distributors:Merchant liquid supply networks extend into secondary fabrication clusters across France, Germany, and northern Italy. IoT-enabled cylinder telemetry allows predictive refill services to unbundle from commodity gas contracts.
- Direct Sales:On-site generation contracts with major automotive stamping plants anchor industrial gas supply through dedicated air separation units.
- Online Sales:Digital procurement platforms serve small fabricators and repair shops with standard electrodes and MIG wire.
- Retailers:Local welding supply stores provide immediate availability for maintenance providers and independent contractors.
Distributors retain volume leadership; Direct Sales holds the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China consumes welding chemicals through shipyard automation and infrastructure build-outs, while Germany and the United States anchor automotive demand through high-strength steel specifications. Regulatory divergence—REACH fume restrictions in Europe versus OSHA exposure limits in North America—drives distinct formulation priorities across these markets.
China
Yangtze River Delta shipyards deploy robotic MAG welding at scale, sustaining bulk demand for argon-carbon dioxide shielding gas mixtures. MIIT industrial upgrading directives accelerate flux-cored wire adoption over solid wire in automated hull construction. Shanghai and Ningbo fabrication clusters concentrate procurement power among tier-one shipbuilders validating new consumable specifications.
Germany
Stuttgart and Wolfsburg automotive stamping plants specify bundled consumable contracts combining filler metal, shielding gas, and technical support. ECHA evaluations of manganese oxide classifications push fabricators toward low-fume flux formulations under REACH substance restrictions. Bavarian and Baden-Württemberg industrial corridors host consolidated buying groups displacing spot purchases with multi-year framework agreements.
United States
Detroit OEM welding lines drive specification of specialized alloys for high-strength steel grades in lightweighting programs. OSHA exposure limits for hexavalent chromium and manganese fume directly influence flux and consumable design priorities. Midwest fabrication clusters near steel mills benefit from air separation capacity concentration, while distant regions face tanker logistics premiums.
South Korea
Ulsan and Geoje shipyards compress cycle times through flux-cored wire technology in automated hull welding. Korean yards sustain demand for precise argon-carbon dioxide shielding gas ratios in robotic MAG lines. Domestic suppliers synchronize AWS A5 and EN ISO 17632 dual certifications to serve transatlantic OEM qualification requirements.
India
National highway and metro rail projects generate first-time specification of rutile flux-cored wire among domestic contractors. BIS standards alignment with EN ISO specifications accelerates formal adoption of automated welding processes. Maharashtra and Gujarat infrastructure build-outs concentrate demand among fabricators upgrading from manual stick electrode methods.
Welding Chemicals Market Competitive Landscape
Capability concentration sits with specialty alloy developers; scale advantage sits with industrial gas distributors with captive air separation networks. The market structures around three tiers: integrated gas-chemical conglomerates with on-site generation contracts, consumable specialists with dual-certification portfolios, and regional distributors with IoT-enabled cylinder telemetry. Dominant competitive moves include backward integration into fluorspar sourcing and geographic expansion through distributor acquisitions in emerging fabrication hubs.
Among industrial gas conglomerates, Air Liquide and Linde plc occupy positions anchored by merchant liquid supply networks and on-site generation contracts with major automotive stamping plants. ESAB exemplifies the consumable specialist archetype with electrode manufacturing footprints sustaining regional availability of specialty filler metals. Taiyo Nippon Sanso Corporation represents Asia-Pacific gas distribution capabilities extending into secondary fabrication clusters.
| Leading Market Players |
|---|
| Air Liquide |
| Air Products & Chemicals, Inc. |
| Linde plc |
| ESAB |
| Illinois Tool Works Inc. |
| The Lincoln Electric Company |
| Messer Group GmbH |
| Taiyo Nippon Sanso Corporation |
| Iwatani Corporation |
| Others |
Value Network & Pricing Analysis
Yangtze River Delta tanker corridors transmit argon logistics premiums to distant Chinese fabrication clusters, compressing margins for shielding gas distributors while enabling price differentiation between on-site generation contracts and merchant liquid supply. This freight-cost gradient concentrates procurement power among automotive stamping plants with direct air separation unit access, forcing spot buyers into cylinder refill programs with embedded delivery surcharges.
Pricing Analysis
Long-term offtake agreements anchor industrial gas supply to major automotive OEMs, while spot purchases dominate small fabricator procurement through distributor networks. Price differentiation separates premium-certified filler metals meeting dual AWS A5 and EN ISO 17632 standards from economy-grade electrodes serving repair shops. Cost compression in standard consumables intensifies as Chinese capacity expansion floods regional markets with rutile flux-cored wire. OEM procurement teams exhibit lowest price sensitivity due to bundled technical service requirements, whereas independent contractors face acute margin pressure from commodity electrode pricing.
Supply Chain Analysis
Electrode manufacturing concentrates in China, India, and Germany, with specialty alloy wire production anchored in Baden-Württemberg and Pennsylvania industrial corridors. Raw material flows draw from Mongolian fluorspar districts for basic flux formulations, Ukrainian titanium sponge for aerospace filler metals, and Qatari helium for precision shielding mixtures. Single-source vulnerability persists in acid-grade fluorspar supply, where concentrated mining districts transmit price volatility directly into electrode coating costs. Distribution runs through merchant liquid networks extending from air separation corridors into secondary fabrication clusters, supplemented by IoT-enabled cylinder telemetry for predictive refill scheduling.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Friction stir welding and other solid-state joining technologies threaten consumable demand in aerospace aluminum fabrication, forcing incumbents to defend their core fusion joining franchise through chemistry innovation and process integration.
For Market Incumbents: Insulate market position by accelerating fluorine-free flux development ahead of EU F-Gas Regulation phase-down deadlines, and secure backward integration into fluorspar sourcing to buffer input cost volatility from Mongolian supply concentration. Dual certification investment in AWS A5 and EN ISO 17632 approvals protects transatlantic OEM relationships from emerging Asian competitor qualification campaigns. For New Entrants and Emerging Players: India's national highway and metro rail contractors represent the most penetrable entry point, where first-time rutile flux-cored wire specification among domestic fabricators creates procurement relationships before established suppliers consolidate. Technical training partnerships with welding engineering institutes overcome qualified procedure writer scarcity in Maharashtra and Gujarat infrastructure clusters. For Investors and Strategic Acquirers: Consumable specialists with captive electrode manufacturing footprints and established dual-certification portfolios offer durable cash flow visibility through recurring filler metal demand from automated MIG/MAG lines. Monitor ECHA weld fume carcinogenicity rulings as the critical inflection signal, where accelerated manganese oxide restrictions would force rapid industry-wide reformulation and concentrate procurement among suppliers with pre-qualified low-emission alternatives.| Strategic Initiative | Industry Significance |
|---|---|
| Fluorine-Free Flux Development | Eliminates regulatory exposure from EU F-Gas Regulation phase-down constraints on structural steel fabrication. |
| Dual Certification Investment | Synchronizes AWS A5 and EN ISO 17632 approvals to serve transatlantic OEM qualification requirements without launch delays. |
| IoT Cylinder Telemetry Deployment | Enables predictive refill services that unbundle technical support from commodity gas contracts for distributor margin protection. |
| Fluorspar Backward Integration | Secures captive acid-grade supply from Mongolian mining districts to buffer electrode coating cost volatility. |
| Welding Engineer Training Partnerships | Addresses qualified WPS/PQR documentation scarcity in India's emerging Maharashtra and Gujarat fabrication hubs. |
Research Methodology
A standing panel of welding consumable procurement managers, plant engineers at automotive stamping facilities, distributor technical sales directors, and ECHA regulatory affairs specialists provided ongoing calibration across primary interview cycles. Secondary validation drew from SEC 10-K filings of industrial gas conglomerates, customs trade data tracking fluorspar and titanium sponge flows, ACC and Cefic chemical industry reports, and AWS/ISO certification registry updates. Bottom-up demand modeling from end-use application segments was triangulated against top-down industrial gas production capacity data.
Scenario-bracketing around argon supply concentration, REACH substance restriction timelines, and friction stir welding penetration rates bounded value projections across the analysis window. Segmentation dimensions modeled include product chemistry tier, end-use vertical certification requirements, customer contract structure, and regional production hub concentration. CAGRs were derived from slope analysis of historical consumption patterns adjusted for regulatory inflection points and automation adoption curves in shipyard and automotive welding lines.
Stress conditions across fluorspar price volatility bands, ECHA fume reclassification timelines, and Korean shipyard automation deployment rates were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding MIIT industrial upgrading directive implementation and BIS standards alignment progress in India. Quarterly review of ECHA substance evaluation dockets, OSHA hexavalent chromium enforcement patterns, and Chinese air separation capacity announcements is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemicals
Malonic Acid Market
Chemicals
3-Dimethylacrylic Acid Methyl Ester Market
Chemicals
Sunscreen Ingredients Market
Chemicals
Triisopropanolamine (TIPA) Market
Chemicals
Coagulant Market
Chemicals
6 Hexanediol Market
Chemicals
Global Lactate Salts Market
Chemicals
Flooring Chemicals Market
Chemicals
North America Ethylene Dichloride (EDC) Market
Chemicals
Chemical As a Service Market
Chemicals
Sodium Hydride Market
Chemicals
Non-Halogenated Flame Retardant Chemicals Market
Chemicals
Amine Oxide Market
Chemicals
p-Coumaric Acid Market
Chemicals
Asia-Pacific Construction Chemicals Market
Chemicals
Superphosphoric Acid (SPA) Market