
 Epoxidized Soybean Oil Market | 2026-2036
Epoxidized Soybean Oil Market Size, Share, and Industry Trends Forecast 2026-2036
Epoxidized Soybean Oil Market Analysis
Technical service agreements for formulation support and regulatory compliance documentation are broadening what suppliers deliver beyond commodity volumes. CHS Inc. leverages its integrated soybean crushing and oilseed processing infrastructure to secure feedstock cost advantages. Arkema differentiates through specialized epoxidation catalyst technology and tailored plasticizer grades for high-performance PVC applications. Cargill anchors North American supply with its origination network and refined oil logistics capabilities.
Epoxidized soybean oil is a chemically modified vegetable oil produced through the epoxidation of soybean oil's unsaturated fatty acid chains, yielding oxirane oxygen content typically between 6.0% and 7.2% that functions primarily as a non-phthalate plasticizer and heat stabilizer in polyvinyl chloride formulations. Plasticizers within the product type dimension command the dominant volume position due to PVC's ubiquity across construction and consumer goods, while polymer modification under application is gaining structural importance as compounders seek multifunctional additives that simultaneously enhance flexibility and thermal stability. Flexible packaging represents a concentrated margin pool where food-contact compliance requirements filter out lower-grade suppliers and reward certified producers.
EPA regulations under the Toxic Substances Control Act and FDA food-contact substance notifications govern product safety and market access in the United States, while REACH registration and RoHS substance restrictions in Europe mandate rigorous chemical hazard documentation and limit certain conventional plasticizer alternatives. China's GB standards and SAMR oversight impose parallel technical specifications on domestic and imported epoxidized soybean oil grades. Stakeholders must monitor evolving phthalate ban timelines and bio-based content certification schemes to align product portfolios with shifting compliance thresholds.
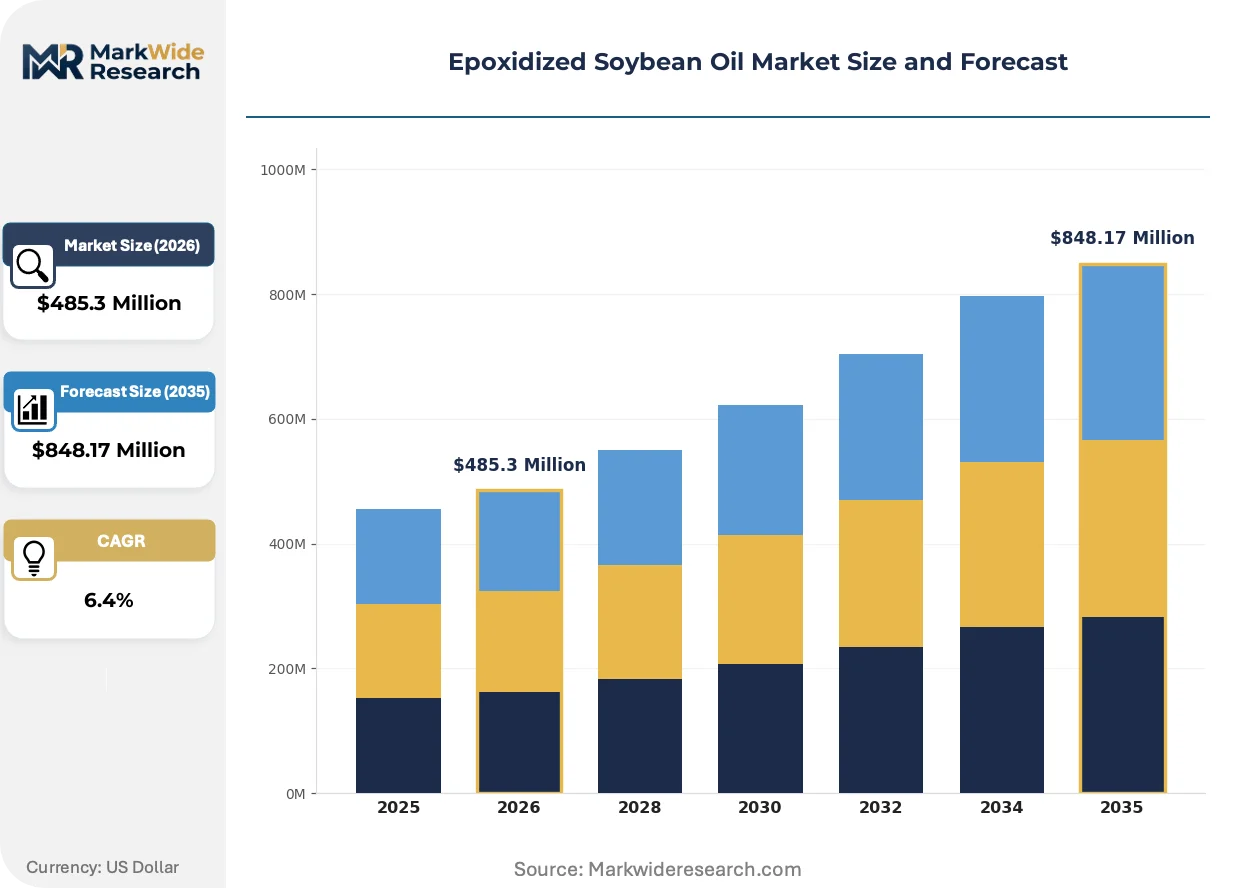
Market Dynamics
REACH and RoHS frameworks are systematically dismantling phthalate plasticizer incumbency across European PVC compounding, forcing formulation houses to rebuild supply chains around bio-based alternatives with verified oxirane content and food-contact migration compliance.
Growth Catalysts
- REACH substance restrictions:Annex XVII phthalate limitations are disqualifying conventional plasticizers from medical device and toy applications, redirecting specification authority toward epoxidized soybean oil with documented hazard profiles.
- Flexible packaging migration:Food-contact compliance requirements in laminated films are filtering specification decisions toward certified bio-based plasticizers with FDA food-contact substance notifications and EFSA positive opinions.
- China domestic capacity:Integrated soybean crushing and epoxidation infrastructure along the Yangtze River Delta is capturing regional PVC additive demand and coating export volumes.
Market Restraints
- Soybean oil feedstock volatility:Crush margins and vegetable oil futures transmit directly to epoxidized soybean oil production economics, compressing margin visibility for non-integrated compounders.
- Epoxidation catalyst supply concentration:Specialized peracid and ion-exchange catalyst technologies remain concentrated among limited technology licensors, creating input dependency for capacity expansion.
- Performance ceiling in high-temperature wire:Oxirane thermal stability limits restrict substitution rates in automotive under-hood cable compounds where trimellitate esters retain specification lock-in.
Strategic Opportunities
- India BIS standardization gap:Absence of harmonized national standards for bio-based plasticizers in flexible PVC creates first-mover positioning for compliant importers ahead of formalized technical specifications.
- Polymer modification convergence:Multifunctional additive positioning—simultaneous plasticization and heat stabilization—is expanding addressable chemistry beyond commodity PVC into engineering resin compatibilization.
- EU Green Deal bio-based content mandates:Emerging public procurement rules and packaging waste directives are embedding minimum renewable content thresholds that favor domestically produced epoxidized vegetable oils.
Industry Challenges
- Food-contact notification timelines:FDA food-contact substance dossier preparation and EPA premanufacture review cycles extend commercialization lead times for novel epoxidation grades.
- Epoxidation reactor fabrication:Corrosion-resistant vessel construction and peracid handling infrastructure demand specialized capital deployment that mid-scale entrants struggle to sequence.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Epoxidized Soybean Oil Market |
| Market Size in 2026 | $485.3 Million |
| Market Size in 2035 | $848.17 Million |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Epoxidized Vegetable Oils, Epoxidized Esters, Surfactants, Plasticizers End User: Paints & Coatings, Adhesives, Plastics, Textiles Application: Polymer Modification, Coating Applications, Flexible Packaging, Agricultural Chemicals Distribution Channel: Direct Sales, Distributors, Online Channels, Retailers |
| Companies Covered | CHS Inc., Galata Chemicals LLC, Arkema, Cargill, NAN YA Plastics Corporation, Adeka Corporation, Valtris Specialty Chemicals, Hairma Chemicals (GZ) Ltd., Shandong Longkou Longda Chemical Industry Co. Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Epoxidized Soybean Oil Market Emerging Trajectories
Formulation science and regulatory chemistry are converging to redefine competitive position in plasticizer markets, with oxirane functionality, bio-based verification, and migration performance becoming inseparable specification criteria.
High-oxirane epoxidized soybean oil grades are expanding into medical-grade PVC compounds where DEHP displacement is accelerating. German and Benelux compounders are adopting these grades for blood bag and tubing applications. The technology is expanding into historically phthalate-locked segments by delivering equivalent plasticization efficiency with superior thermal stability profiles.
REACH authorization requirements for phthalate plasticizers are tightening substitution timelines across European automotive and construction sectors. ECHA's ongoing restriction proposals for additional ortho-phthalates are forcing compounders to validate alternative plasticizers through comprehensive migration and aging studies. Wire and cable manufacturers in Eastern Europe are responding fastest, rebuilding formulation libraries around epoxidized vegetable oil systems.
Certificate-driven procurement is restructuring buyer-supplier relationships in food-contact packaging. Brand owners and converters are unbundling traditional additive supply agreements to require standalone bio-based content certification and third-party migration testing. This pattern is most visible in Nordic and German flexible packaging markets, where retailer sustainability scorecards directly influence specification authority.
Epoxidized Soybean Oil Market Segmentation
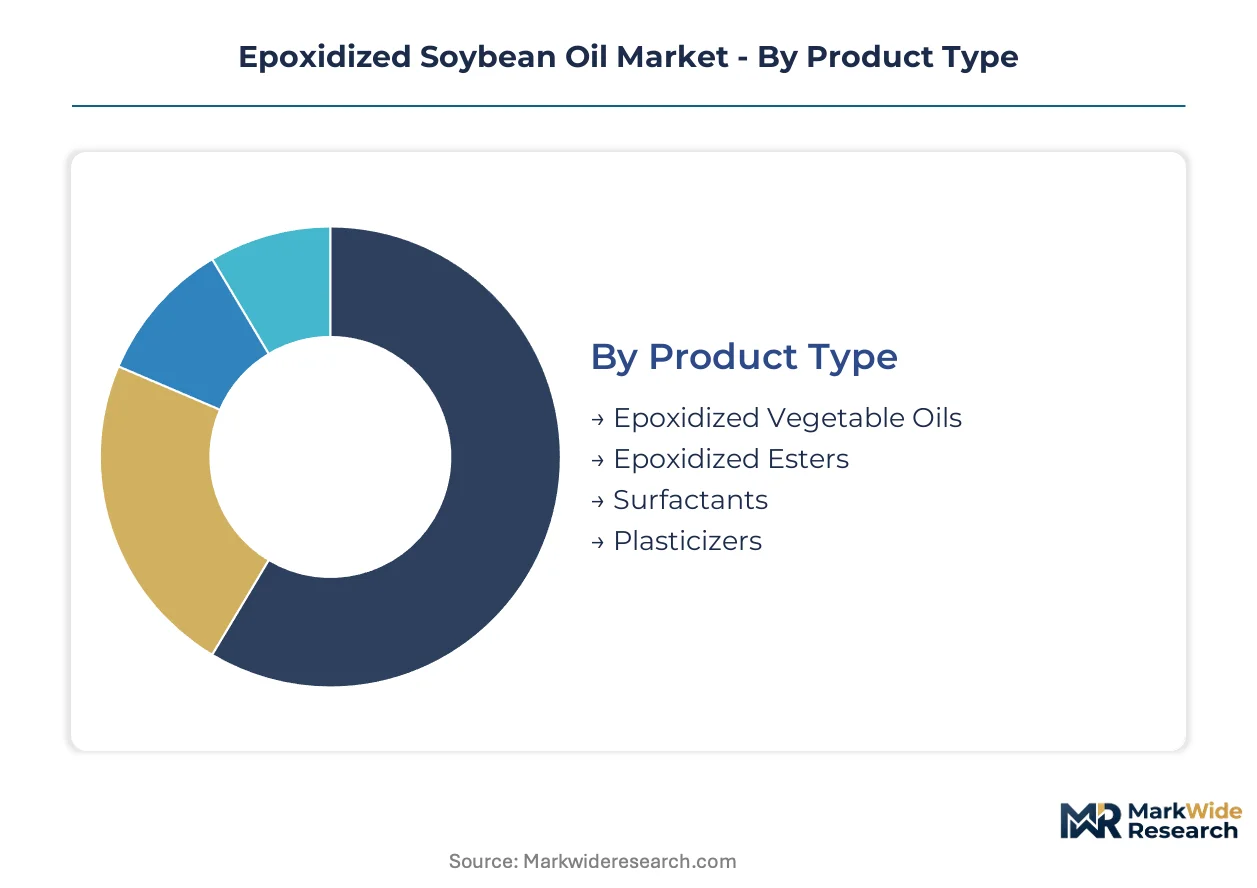
Segmentation in epoxidized soybean oil markets separates commodity-grade volumes from certified food-contact and medical-grade premiums. Specification authority concentrates where regulatory compliance intersects with performance requirements in PVC compounding and flexible packaging.
Product Type:
Upgrade cycles differentiate commodity plasticizers from high-oxirane specialty grades that command formulation premiums.
- Plasticizers:These grades deliver oxirane content between 6.0% and 7.2% to soften PVC without phthalate regulatory exposure. Demand concentrates in European medical device tubing where REACH Annex XVII phthalate bans have displaced DEHP formulations.
- Epoxidized Vegetable Oils:Soybean-derived feedstock dominates volume, though rapeseed and linseed variants gain traction where cold-flexibility specifications exceed soybean performance limits. German automotive cable compounders are trialing these alternatives for under-hood applications.
- Epoxidized Esters:Secondary ester modifications improve compatibility with polar engineering resins.
- Surfactants:Epoxidation creates amphiphilic structures for agricultural emulsion systems.
Volume placements concentrate in Plasticizers; the faster expansion belongs to Epoxidized Vegetable Oils.
End User:
Cost tier stratification separates specification-grade buyers from price-sensitive commodity purchasers.
- Plastics:PVC compounding absorbs the dominant volume share across construction profiles, flooring, and medical devices. Chinese processors along the Yangtze River Delta leverage domestic epoxidation capacity to serve both local extruders and export coating manufacturers.
- Paints & Coatings:Epoxidized soybean oil functions as a reactive diluent and coalescing aid in low-VOC architectural formulations. Italian and Spanish decorative coating producers specify these grades to meet EU Green Deal bio-based content thresholds in public procurement.
- Adhesives:Pressure-sensitive and hot-melt systems utilize oxirane functionality for crosslink density control.
- Textiles:Fabric softeners and finishing agents employ epoxidized oils for hand modification.
Volume concentrates in Plastics; Paints & Coatings is climbing the fastest on sustainability certification requirements.
Application:
Application maturity varies from established polymer modification to emerging multifunctional additive positioning.
- Polymer Modification:Simultaneous plasticization and heat stabilization in PVC compounds creates formulation efficiency. REACH authorization pressures on conventional stabilizers are redirecting specification authority toward bio-based alternatives with documented hazard profiles.
- Flexible Packaging:Food-contact compliance requirements filter specification decisions toward certified producers with FDA food-contact substance notifications and EFSA positive opinions. Nordic retailer sustainability scorecards directly influence converter procurement.
- Coating Applications:Reactive diluents and UV-curable oligomers utilize oxirane rings for polymerization sites.
- Agricultural Chemicals:Emulsifier and adjuvant applications leverage epoxidized oil surfactant properties.
Volume concentrates in Polymer Modification; Flexible Packaging shows the steepest expansion trajectory on migration compliance premiums.
Distribution Channel:
Supply concentration shapes channel selection between integrated direct relationships and fragmented distributor networks.
- Direct Sales:Large PVC compounders and multinational coating manufacturers negotiate technical service agreements and regulatory compliance documentation. CHS Inc. and Cargill leverage origination networks to anchor these relationships with feedstock security.
- Distributors:Regional specialty chemical distributors serve mid-scale compounders lacking volume thresholds for direct supplier contracts. These intermediaries concentrate in Benelux and Northern Italy where formulation houses cluster.
- Online Channels:E-procurement platforms capture spot purchases and sample orders from smaller processors.
- Retailers:Limited presence in consumer-facing epoxy resin and coating additive segments.
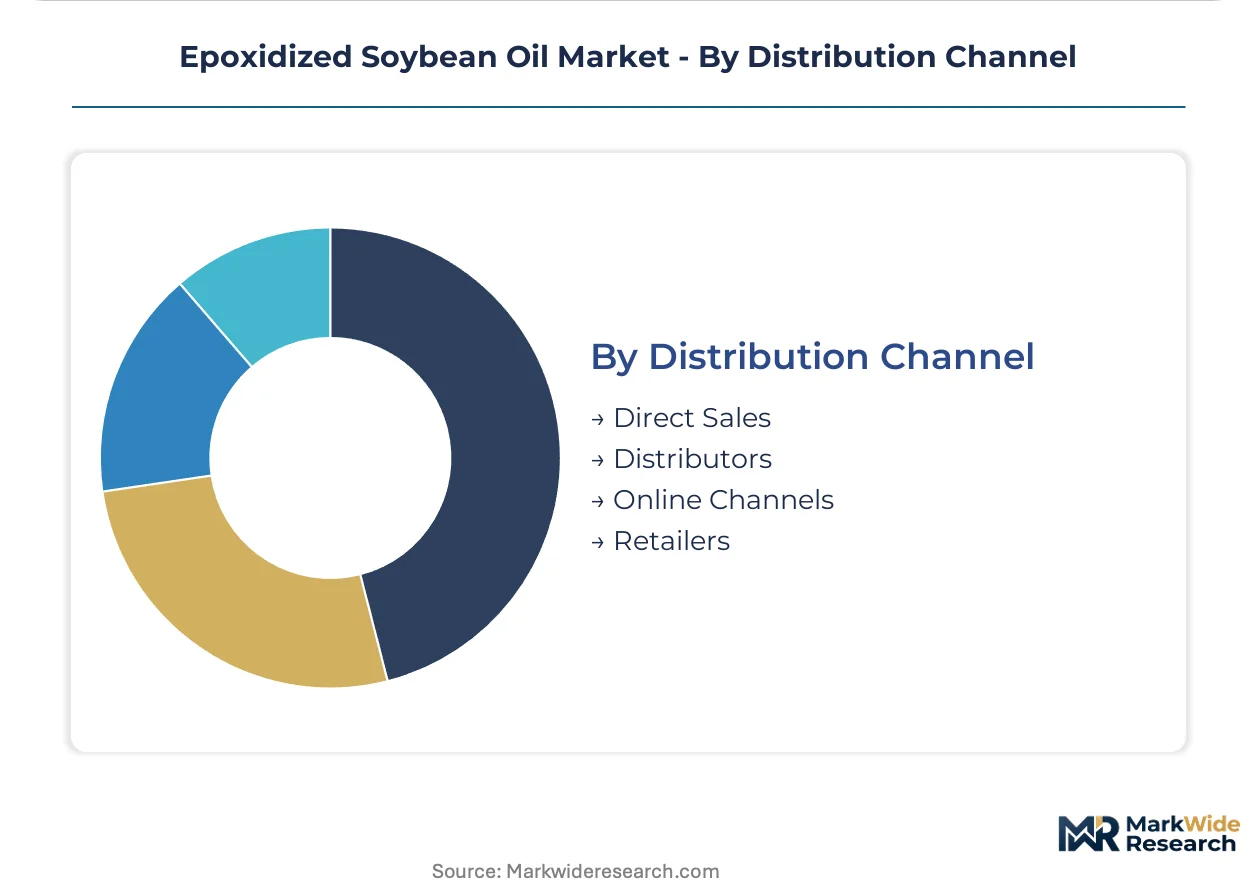
Volume concentrates in Direct Sales; Distributors is gaining share fastest as mid-tier compounders seek formulation support services.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Yangtze River Delta anchors global epoxidized soybean oil production capacity, with integrated soybean crushing and epoxidation infrastructure serving both domestic PVC processors and export-oriented coating manufacturers. Regional demand patterns diverge sharply between REACH-regulated European medical device markets and price-sensitive Asian construction sectors.
China
Domestic epoxidation capacity along the Yangtze River Delta captures regional PVC additive demand and coating export volumes. GB standards and SAMR oversight impose parallel technical specifications on domestic and imported grades. Shanghai and Jiangsu province host integrated soybean crushing facilities that supply feedstock to captive epoxidation plants.
Germany
REACH Annex XVII phthalate limitations redirect specification authority toward epoxidized soybean oil with documented hazard profiles. ECHA's ongoing restriction proposals for additional ortho-phthalates force compounders to validate alternatives through migration studies. Benelux-bordering industrial clusters in North Rhine-Westphalia rebuild formulation libraries around bio-based systems.
United States
Construction and consumer goods sectors drive PVC compounding demand across the Midwest and Southeast. EPA regulations under the Toxic Substances Control Act and FDA food-contact substance notifications govern product safety and market access. CHS Inc. and Cargill leverage origination networks to anchor supply relationships with feedstock security.
India
Absence of harmonized national standards for bio-based plasticizers in flexible PVC creates first-mover positioning for compliant importers. Maharashtra and Gujarat industrial corridors absorb growing construction sector demand. The country's national chemical regulator has yet to formalize technical specifications equivalent to REACH or FDA frameworks.
Japan
Automotive under-hood cable compounders trial rapeseed and linseed variants where cold-flexibility specifications exceed soybean performance limits. METI oversees industrial chemical standards while JIS certification requirements filter supplier qualification. Osaka-Kobe industrial zone hosts specialty PVC compounders serving automotive tier-1 suppliers.
Epoxidized Soybean Oil Market Vendor Landscape
Capital-heavy producers compete with asset-light distributors across distinct competitive strata. Integrated agribusiness conglomerates control upstream feedstock economics through captive soybean crushing operations. Specialized chemical manufacturers differentiate through proprietary catalyst technologies and formulation support services. Regional distributors capture mid-scale compounder relationships lacking volume thresholds for direct supplier contracts. Dominant competitive moves include backward integration into oilseed processing and technical service agreement expansion.
Within the integrated agribusiness tier, CHS Inc. and Cargill represent North American supply anchors with origination network advantages. Arkema occupies a position among specialty chemical manufacturers leveraging differentiated catalyst technology. Chinese producers including Hairma Chemicals (GZ) Ltd. and Shandong Longkou Longda Chemical Industry Co. Ltd. exemplify regional capacity concentration serving export markets.
| Leading Market Players |
|---|
| CHS Inc. |
| Galata Chemicals LLC |
| Arkema |
| Cargill |
| NAN YA Plastics Corporation |
| Adeka Corporation |
| Valtris Specialty Chemicals |
| Hairma Chemicals (GZ) Ltd. |
| Shandong Longkou Longda Chemical Industry Co. Ltd. |
| Others |
Supply Flow & Price Mechanics
Captive integration into soybean crushing and epoxidation infrastructure anchors supply security and pricing power for North American and Chinese producers, while non-integrated compounders absorb feedstock volatility through contract structures. REACH-driven phthalate substitution in European medical devices creates specification premiums that reward certified grades with documented oxirane content and migration compliance.
Pricing Analysis
Margin tightening in commodity plasticizer tiers reflects crush margin volatility transmitted through vegetable oil futures, while premium medical-grade formulations command stability through long-term offtake agreements with PVC compounders. Three-tier pricing structure across premium, standard, and economy levels separates FDA-notified food-contact grades from industrial PVC modifiers, with price differentiation driven by certification level and volume scale. Cost-down pressure on standard grades accelerates as Yangtze River Delta capacity expands into export markets. Mid-scale European compounders show highest price sensitivity due to feedstock import dependency, while integrated agribusiness buyers leverage origination networks for cost visibility.
Supply Chain Analysis
Single-source vulnerability sits with specialized peracid and ion-exchange catalyst licensors concentrated in Germany and Japan, creating input dependency for epoxidation capacity expansion. Manufacturing concentrates in China, the United States, and Germany, with raw material dependencies on soybean oil crush output, hydrogen peroxide supply, and formic acid availability. Supply chain risk centers on regulatory restriction as REACH authorization timelines extend qualification periods for novel grades. Distribution runs through direct technical service agreements for large PVC compounders and regional specialty distributors for mid-scale formulation houses.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Epoxidized soybean oil markets are transitioning from phthalate displacement to multifunctional additive positioning, with high-oxirane grades replacing legacy DEHP formulations in medical-grade PVC compounds.
For Market Incumbents: Lock in feedstock security through backward integration into oilseed crushing or long-term origination contracts with agricultural cooperatives. Defend specification authority in European medical devices by accelerating FDA food-contact substance notifications and EFSA positive opinions ahead of REACH Annex XVII expansion. Prioritize catalyst technology licensing to capture margin from capacity-constrained entrants.
For New Entrants and Emerging Players: The premium-economy price-point gap in Indian flexible PVC creates white-space positioning ahead of BIS standardization. Target Maharashtra and Gujarat industrial corridors with import-compliant grades certified to REACH-equivalent specifications. Pursue technical partnership routes with regional distributors lacking formulation support capabilities.
For Investors and Strategic Acquirers: Exit pathways concentrate in specialty chemical manufacturers with proprietary epoxidation catalyst IP and established food-contact regulatory dossiers. Long-term viability hinges on bio-based content verification systems aligning with EU Green Deal procurement thresholds. Monitor ECHA restriction proposal timelines as inflection indicators for substitution acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Oilseed Crushing | CHS Inc. and Cargill leverage captive soybean supply to secure feedstock cost advantages against volatile crush margins. |
| High-Oxirane Grade Development | Arkema's specialized catalyst technology enables medical-grade PVC formulations displacing DEHP in blood bag applications. |
| FDA Food-Contact Notification Expansion | Certified producers capture flexible packaging premiums as Nordic retailer scorecards mandate bio-based verification. |
| Joint Venture with Yangtze River Delta Producers | Western compounders access Chinese domestic capacity to serve coating export volumes and regional PVC demand. |
| Green Manufacturing Transition | Peracid handling infrastructure investments align with EU Green Deal bio-based content thresholds in public procurement. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with PVC compounding plant managers, procurement leads at flexible packaging converters, specialty chemical distribution partners, and technical R&D directors at epoxidation catalyst suppliers. SEC 10-K disclosures from integrated agribusiness conglomerates, ECHA restriction proposal documentation, FDA food-contact substance inventories, and Chinese customs export statistics provided demand-side validation. Bottom-up volume estimates from end-use consumption patterns reconciled with top-down capacity assessments across the analysis window.
Data-stream reconciliation across supply-side capacity buildouts and demand-side formulation shifts informed the analytical framework. Segmentation dimensions modeled include product type tier, end-use industry concentration, application maturity, and regional regulatory cluster. CAGRs were derived from elasticity-adjusted consumption trajectories, with oxirane content specifications and migration compliance thresholds serving as industry-specific forecast inputs throughout the projection horizon.
Inputs from ECHA regulatory proceedings and FDA notification databases were available through the study window; gaps in real-time Chinese SAMR enforcement data introduce uncertainty bands around domestic capacity utilization assumptions. Forecasts reflect documented assumptions on phthalate ban timelines and bio-based procurement mandate adoption. Soybean oil price volatility, catalyst technology access constraints, and food-contact notification approval delays represent specific risk factors that could revise trajectory projections. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Chemicals
US Post Laser Recovery Products Market
Specialty Chemicals
4-Propyl-1,3,2-Dioxathiolane 2,2-Dioxid Market
Specialty Chemicals
Europe Aerosol Cans Market
Specialty Chemicals
Technical Aerosol Market
Specialty Chemicals
Europe Malic Acid Market
Specialty Chemicals
Inorganic Flame Retardants Market
Specialty Chemicals
Global Caffeic Acid Market
Specialty Chemicals
Medical Propellants Market
Specialty Chemicals
Ferrous Gluconate Market
Specialty Chemicals
Cellulose Derivatives Market
Specialty Chemicals
Global Non-Halogenated Flame Retardants Market
Specialty Chemicals
Food Grade Paraffin Market
Specialty Chemicals
Microcrystalline Wax Market
Specialty Chemicals
13X Molecular Sieve Activated Powder Market
Specialty Chemicals
Global Chemical Vapor Deposition (CVD) Market
Specialty Chemicals
Eco-Friendly Plasticizers Market