
 Carbocernaite Market | 2026-2036
Carbocernaite Market Size, Share, and Industry Trends Forecast 2026-2036
Carbocernaite Market Analysis
Buyer concentration among specialty coatings formulators is shifting as mid-sized industrial paint producers fragment procurement across multiple qualified mineral suppliers. Omya AG leverages its vertical integration into high-purity calcium carbonate networks to sustain consistent feedstock quality for carbocernaite derivatives. Imerys anchors European supply through its established processing infrastructure in France and Belgium. Minerals Technologies Inc. competes on manufacturing scale, operating specialized precipitation facilities that control particle size distribution for electronics-grade applications.
Carbocernaite is a rare carbonate mineral composed primarily of calcium, sodium, and carbonate ions, typically occurring in fine-grained crystalline formations with Mohs hardness near 3 and thermal decomposition beginning near 550°C; manufacturers synthesize it through controlled carbonation of lime-soda solutions to achieve pharmaceutical and electronic-grade purity. The mineral serves as a functional filler, pH buffer, and precursor material in catalyst supports and thin-film coatings. Powders dominate current volume as established milling infrastructure supports bulk industrial consumption, while crystals command premium positioning in pharmaceutical and electronics applications where lattice integrity determines performance. Pellets represent the fastest-growing format as automated dosing systems in chemical processing plants require free-flowing feedstock with minimal dust generation. Solutions remain niche, confined to specialized coating baths and electroplating formulations where colloidal dispersion stability matters.
EPA standards under the Toxic Substances Control Act govern mineral filler purity thresholds in United States industrial coatings, while REACH registration requirements in Europe mandate full toxicological dossiers for carbocernaite imports above one tonne annually. The FDA's indirect food contact regulations shape demand from packaging coating producers seeking mineral additives with established safety profiles. Stakeholders must monitor evolving purity certifications and regional registration timelines to secure uninterrupted market access as regulatory divergence between North American and European frameworks intensifies.
Market Dynamics
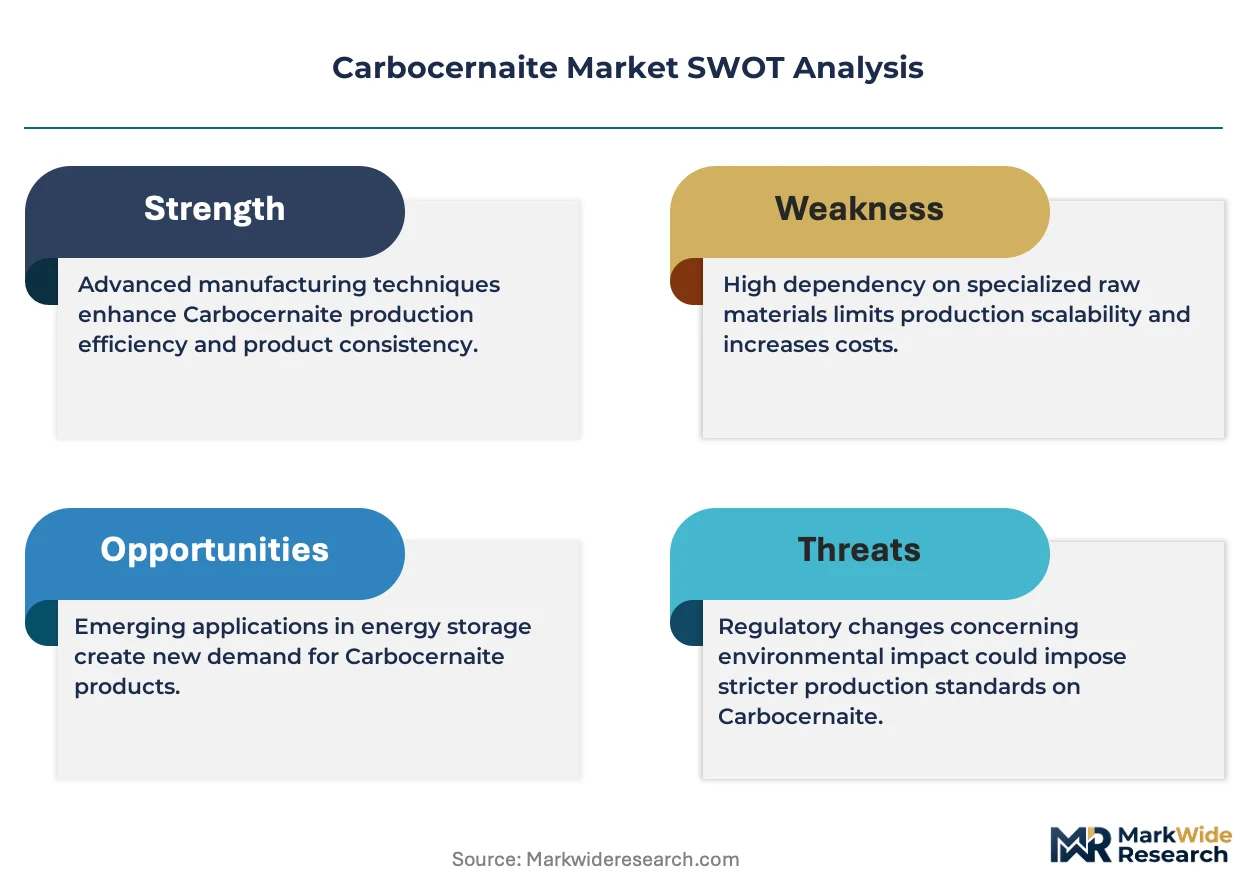
REACH compliance deadlines and EPA purity thresholds are forcing specialty coatings formulators to requalify mineral filler suppliers, compressing procurement timelines and consolidating qualified vendor pools across Western supply chains.
Growth Catalysts
- Electronics-grade precipitation:Semiconductor packaging manufacturers demand lattice-controlled carbocernaite crystals for thin-film dielectric layers, pulling investment into precision carbonation infrastructure.
- REACH registration thresholds:ECHA mandates above one tonne annually are eliminating unregistered mineral traders, directing volume toward compliant chemical processors in Germany's industrial corridor.
- Pellet format automation:Chemical processing plants deploying robotic dosing systems require free-flowing feedstock with minimal dust generation, accelerating format conversion from powders.
Market Restraints
- High-purity calcium carbonate feedstock volatility:Captive supply of pharmaceutical-grade lime-soda precursors concentrates among integrated chemical majors, squeezing independent carbocernaite processors.
- Thermal decomposition threshold:Carbocernaite's 550°C decomposition ceiling restricts high-temperature catalyst support applications, ceding share to more thermally stable rare earth carbonates in petrochemical refining.
- REACH dossier costs:Full toxicological registration requirements for European market access impose six-figure compliance burdens on sub-tonne specialty mineral traders.
Strategic Opportunities
- India packaging coatings:FSSAI indirect food contact regulations are creating first-mover advantage for mineral additive suppliers with established safety dossiers against domestic unregistered competitors.
- Japan electronics reshoring:METI semiconductor supply chain initiatives are redirecting precision-grade carbonate demand toward domestic chemical processors with JIS-certified particle size control.
- Solution-phase coating baths:Electroplating formulators seeking colloidal dispersion stability represent untapped niche demand for stabilized carbocernaite suspensions.
Industry Challenges
- Particle size distribution expertise:Electronics-grade applications require sub-micron control that legacy industrial mineral milling operations cannot achieve without capital-intensive precipitation retrofit.
- Multi-jurisdiction registration synchronization:Divergent EPA and REACH purity certification timelines force dual-track compliance investments, stretching regulatory affairs capacity at mid-sized chemical processors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Carbocernaite Market |
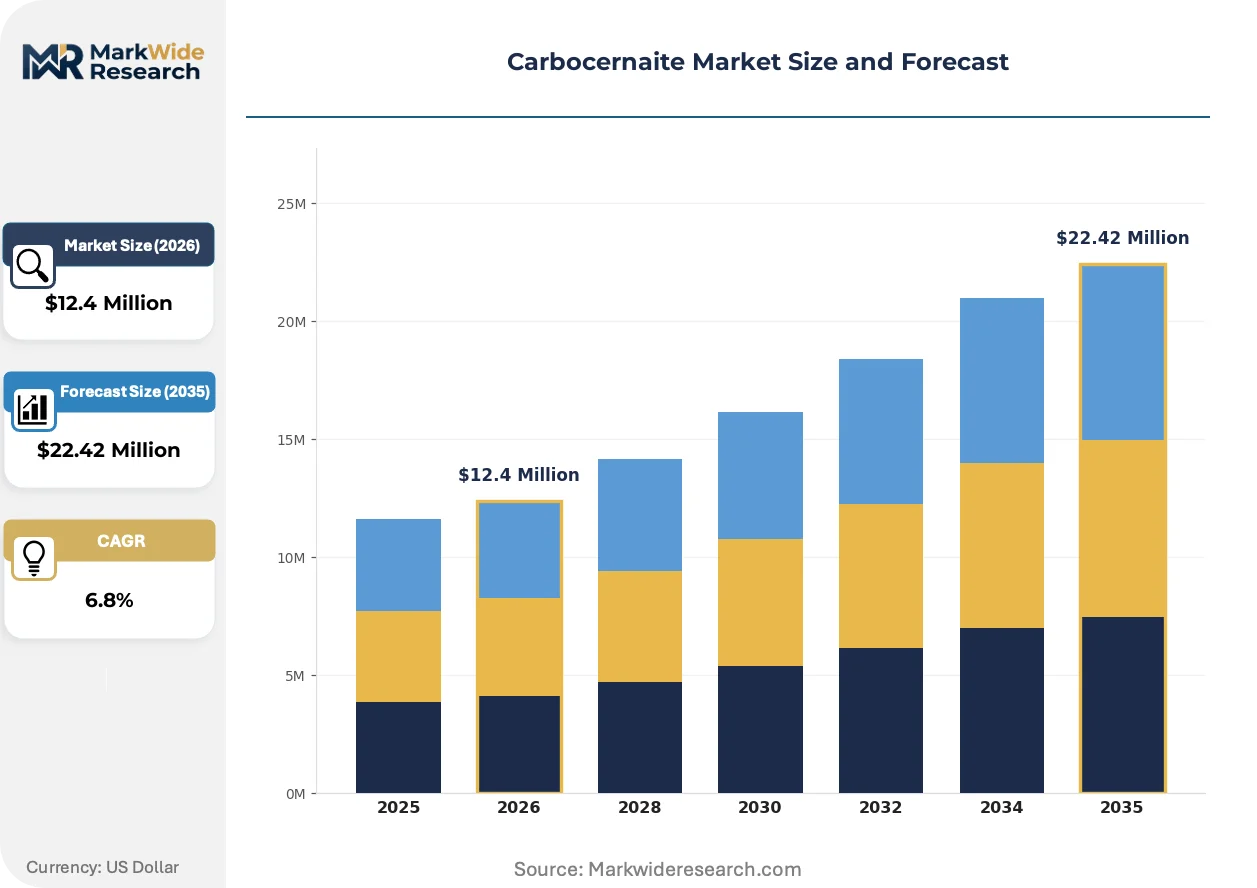
| Market Size in 2026 | $12.4 Million |
| Market Size in 2035 | $22.42 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Crystals, Powders, Pellets, Solutions Application: Catalysts, Coatings, Electronics, Pharmaceuticals End User: Aerospace, Automotive Components, Electronics Manufacturers, Chemical Processing Packaging Type: Bulk Bags, Drums, Totes, Containers |
| Companies Covered | Omya AG, Imerys, Minerals Technologies Inc., Huber Engineered Materials, Mississippi Lime Company, Carmeuse, Sibelco, Lhoist Group, GLC Minerals, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Carbocernaite Market Emerging Trajectories
Continuous carbonation reactor technology is collapsing batch-to-batch variability in synthetic carbocernaite production, enabling real-time quality adjustment that static precipitation vessels cannot match.
Membrane-assisted carbonation is unifying pH control and particle nucleation into single-stage processing, eliminating intermediate filtration steps. Specialty coatings formulators in Germany's chemical corridor are adopting this technology fastest, drawn by consistent lattice integrity in pharmaceutical-grade output. The compression of process steps is collapsing capital requirements for entry-level electronics-grade production.
EPA standards under the Toxic Substances Control Act are tightening mineral filler purity thresholds in industrial coatings, extending testing protocols to heavy metal traces previously unregulated. Coating manufacturers serving food packaging applications face the steepest compliance ramps, diverting procurement toward suppliers with pre-validated FDA indirect food contact dossiers. German chemical processors with dual EPA-REACH registration are capturing displaced volume from single-jurisdiction competitors.
Automated dosing system integration is fragmenting bulk powder contracts into pellet-format supply agreements with precise flow-rate specifications. Chemical processing plants in Belgium's industrial heartland are leading this specification shift, penalizing dust-generating powders through handling cost penalties. Specialty coatings formulators with legacy pneumatic conveying infrastructure face accelerated capital decisions on format conversion.
Carbocernaite Market Segmentation
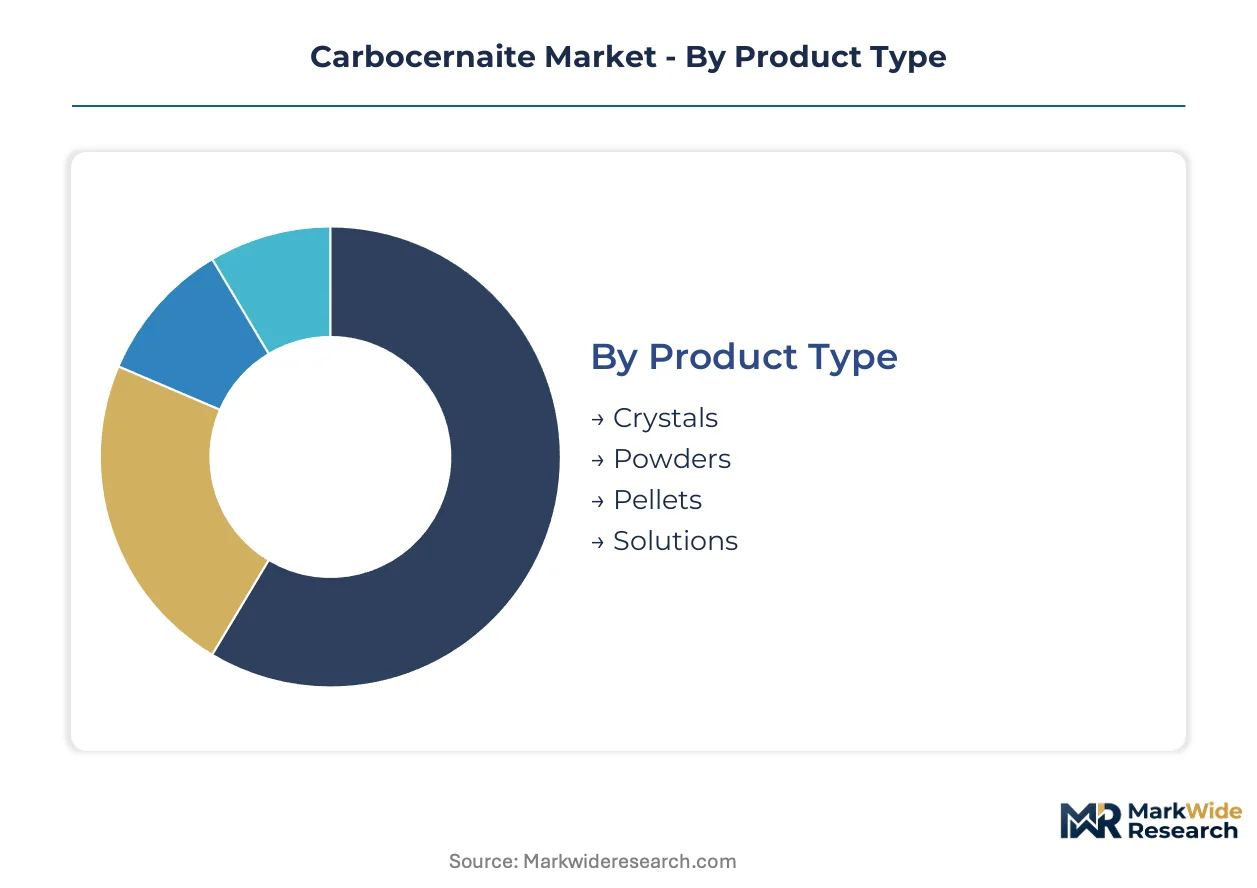
Carbocernaite procurement decisions split across four distinct axes: physical form determines handling infrastructure, application dictates purity thresholds, end-user verticals set volume scales, and packaging configurations influence logistics economics. Each segmentation layer creates vendor qualification barriers that reshape competitive positioning.
Product Type:
Buyers select physical formats based on downstream automation requirements and dust containment obligations.
- Powders:Fine-milled particulate with established bulk handling infrastructure dominates industrial coatings and catalyst manufacturing. Demand concentrates in Germany's chemical processing corridor where pneumatic conveying systems predominate, though dust generation penalties are accelerating format migration.
- Pellets:Free-flowing agglomerated spheres engineered for robotic dosing systems in automated chemical plants. Belgium's industrial heartland leads specification adoption as handling cost penalties reshape procurement contracts away from dusty alternatives.
- Crystals:Lattice-controlled formations command premium positioning in pharmaceutical and electronics applications where structural integrity determines thin-film dielectric performance.
- Solutions:Stabilized colloidal suspensions serve niche electroplating baths and coating formulations requiring dispersion stability.
Powders lead on scale; pellets lead on momentum.
Application:
End-use specifications stratify purity requirements and registration burdens across customer portfolios.
- Electronics:Semiconductor packaging manufacturers demand sub-micron particle control for thin-film dielectric layers. Japan's METI reshoring initiatives redirect precision-grade demand toward domestic processors with JIS-certified precipitation infrastructure.
- Pharmaceuticals:Lattice integrity and heavy metal trace compliance shape FDA indirect food contact dossier requirements. REACH registration thresholds above one tonne annually eliminate unregistered traders from European supply chains.
- Catalysts:Thermal decomposition near 550°C restricts high-temperature petrochemical applications, ceding share to thermally stable rare earth carbonates in refining operations.
- Coatings:Specialty industrial paint formulators fragment procurement across qualified mineral suppliers as EPA purity thresholds force requalification cycles.
Coatings lead on scale; electronics lead on momentum.
End User:
Customer verticals determine volume concentration and technical service intensity.
- Chemical Processing:Automated plants in Germany and Belgium drive pellet-format conversion with precise flow-rate specifications and robotic dosing integration.
- Electronics Manufacturers:Semiconductor fabricators demand precipitation-grade crystals with real-time quality adjustment capabilities that continuous carbonation reactors enable.
- Automotive Components:Coating applications for underhood and structural components require REACH-compliant mineral fillers with established toxicological dossiers.
- Aerospace:Specialized thin-film and thermal protection applications represent low-volume, high-specification demand with extended qualification timelines.
Chemical processing leads on scale; electronics manufacturers lead on momentum.
Packaging Type:
Logistics configurations align with customer automation levels and inventory turnover economics.
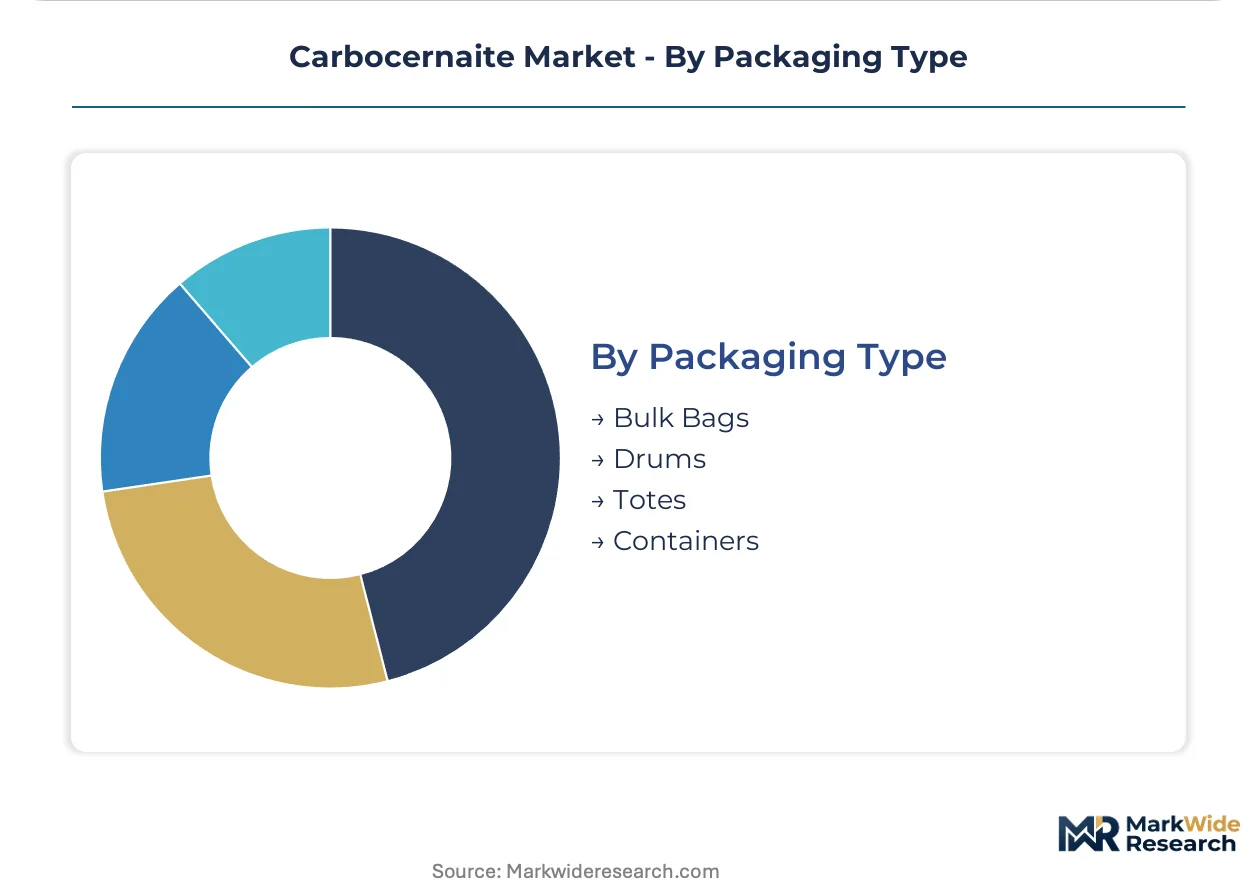
- Bulk Bags:Flexible intermediate bulk containers serve high-volume powder consumers with pneumatic unloading infrastructure in Germany's Ruhr industrial cluster.
- Drums:Steel and fiber containers protect moisture-sensitive crystals and pellets for pharmaceutical and electronics customers requiring lot traceability.
- Totes:Intermediate rigid intermediate bulk containers bridge bulk and drum volumes for mid-tier coatings formulators with mixed automation.
- Containers:Standardized shipping containers consolidate multi-origin supply for large chemical processors with dedicated unloading facilities.
Bulk bags lead on scale; totes lead on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized chemical processing talent concentrates in Germany's industrial corridor, anchoring European precision-grade carbocernaite demand. Technical expertise in controlled carbonation and particle engineering drives regional capability gaps. Workforce migration toward automated chemical plants is reshaping production geography across Western supply chains.
Germany
Specialty coatings formulators and pharmaceutical-grade processors drive precision carbonate consumption. ECHA REACH registration mandates above one tonne annually eliminate unregistered mineral traders from supply chains. The Ruhr industrial cluster hosts automated chemical plants deploying robotic dosing systems that demand pellet-format feedstock specifications.
United States
Semiconductor packaging manufacturers and electronics-grade precipitators pull investment into lattice-controlled crystal production. EPA Toxic Substances Control Act purity thresholds force industrial coatings producers to requalify mineral filler suppliers. Texas and Arizona chemical processing corridors concentrate new precipitation facility investments serving domestic electronics reshoring.
Japan
Domestic semiconductor fabricators and thin-film dielectric producers redirect precision-grade carbonate demand toward local processors. METI supply chain initiatives mandate JIS-certified particle size control for strategic material inputs. The Kansai region anchors domestic precipitation infrastructure with real-time quality adjustment capabilities.
Belgium
Chemical processing plants with automated dosing integration fragment bulk powder contracts into precise flow-rate pellet agreements. EU Green Deal industrial decarbonization programs incentivize process efficiency investments in mineral carbonation. The Port of Antwerp cluster leads specification shifts penalizing dust-generating powders through handling cost structures.
India
Packaging coating producers and food-contact material formulators create first-mover openings for registered mineral additive suppliers. FSSAI indirect food contact regulations disadvantage domestic unregistered competitors lacking established safety dossiers. Maharashtra and Gujarat industrial corridors concentrate import substitution investments in pharmaceutical-grade mineral processing.
Carbocernaite Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered supply positions. Integrated chemical majors leverage captive lime-soda feedstock networks to sustain consistent input quality, while independent processors face sourcing volatility. Three archetypes dominate: vertically integrated mineral conglomerates with carbonate network control, specialized precipitation technology licensors, and regional toll processors serving qualified coatings formulators. Competitive moves concentrate on backward integration into high-purity calcium carbonate supply and continuous carbonation reactor licensing.
Within the integrated conglomerate tier, Omya AG and Imerys exemplify archetypes leveraging established mineral processing infrastructure across European chemical corridors. Minerals Technologies Inc. occupies a position among specialized precipitation-scale operators controlling particle size distribution for electronics-grade applications. These three anchors represent distinct strategic postures: Omya AG with Swiss-based carbonate network depth, Imerys with French-Belgian processing footprint, and Minerals Technologies Inc. with North American precipitation specialization.
| Leading Market Players |
|---|
| Omya AG |
| Imerys |
| Minerals Technologies Inc. |
| Huber Engineered Materials |
| Mississippi Lime Company |
| Carmeuse |
| Sibelco |
| Lhoist Group |
| GLC Minerals |
| Others |
Supply Flow & Price Mechanics
Continuous carbonation reactor deployment is collapsing batch-to-batch variability while concentrating production economics among operators with capital to retrofit legacy precipitation infrastructure, compressing margins for batch-dependent independents and rewarding scale-advantaged integrated majors with pricing power in pharmaceutical-grade tiers.
Pricing Analysis
Service bundling separates registered REACH dossier support from bare mineral supply, with German chemical processors commanding premiums for compliance-inclusive contracts while unregistered traders compete on spot powder pricing. Three-tier pricing structure across pharmaceutical-grade crystals, industrial-grade pellets, and commodity powders reflects certification burden and particle engineering intensity. Cost compression in electronics-grade tiers is intensifying because semiconductor packaging manufacturers are consolidating qualified supplier pools. Mid-sized coatings formulators exhibit highest price sensitivity due to fragmented procurement authority, while semiconductor fabricators prioritize lattice consistency over unit cost.
Supply Chain Analysis
Dual-sourcing mandates from REACH-registered buyers are fragmenting volume across qualified German, Belgian, and French processors to mitigate registration-lapse risk. Captive supply of pharmaceutical-grade lime-soda precursors rests on integrated chemical majors in Switzerland and France, while independent carbocernaite processors source from spot carbonate markets. Single-source vulnerability concentrates in high-purity calcium carbonate feedstock where backward integration barriers protect incumbent positions. Distribution runs through Antwerp and Rotterdam port clusters for European chemical corridor delivery, with drum-format crystals moving through specialized chemical distributors serving electronics and pharmaceutical end-users.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play between REACH-registered European supply and FSSAI-regulated Indian demand, where compliance cost differentials create first-mover rent extraction opportunities for dossier-holding suppliers against domestic unregistered competitors.
For Market Incumbents: Lock in backward integration into high-purity calcium carbonate networks to neutralize feedstock volatility that squeezes independent processors. Secure dual EPA-REACH registration to capture volume displaced from single-jurisdiction competitors as regulatory divergence intensifies between American and European purity certification timelines. For New Entrants and Emerging Players: Enter via membrane-assisted carbonation technology licensing to bypass capital-intensive precipitation retrofit barriers that exclude legacy millers from electronics-grade qualification. Target India's packaging coatings corridor with pre-validated FSSAI safety dossiers, exploiting regulatory asymmetry against domestic competitors lacking established toxicological profiles. For Investors and Strategic Acquirers: Valuations sit cheapest among regional toll processors serving qualified coatings formulators, where registration compliance investments have compressed exit multiples below integrated conglomerate levels. Long-term viability hinges on continuous carbonation reactor adoption curves across the analysis window. Watch for pellet-format specification adoption rates in Belgium's automated chemical plants as inflection signal for format-migration capex cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Lime-Soda Networks | Captive feedstock quality secures pharmaceutical-grade output consistency against spot-market volatility. |
| Continuous Carbonation Reactor Licensing | Real-time quality adjustment enables electronics-grade crystal production that batch vessels cannot match. |
| Dual EPA-REACH Registration Investment | Dual-jurisdiction compliance captures volume from single-registered competitors as purity thresholds diverge. |
| Pellet-Format Production Conversion | Free-flowing feedstock specifications align with robotic dosing adoption in Belgium's automated chemical plants. |
| Membrane-Assisted Carbonation Deployment | Single-stage pH control collapses filtration steps, reducing capital requirements for precision-grade entry. |
Methodological Framework
Direct dialogue with specialty coatings formulators, pharmaceutical-grade processors, semiconductor packaging procurement leads, and chemical plant automation engineers grounded qualitative insights, cross-validated against ECHA registration databases, EPA TSCA filing records, SEC 10-K disclosures from integrated mineral conglomerates, and German chemical industry association trade statistics. Bottom-up volume estimates from end-use consumption patterns were triangulated against top-down production capacity assessments across identified precipitation facilities.
Top-down macroeconomic drivers were reconciled with bottom-up segment trajectories across physical format, application purity tier, end-user vertical, and packaging configuration dimensions over the projection horizon. CAGRs were derived from slope-intercept modeling of historical volume trends adjusted for regulatory inflection points. Forecast inputs incorporated REACH registration timeline assumptions, pellet-format adoption curves in automated chemical plants, and semiconductor reshoring policy impacts on precision-grade demand.
Inputs from ECHA registration databases and EPA filing records were available through the study window; gaps in real-time precipitation capacity utilization data introduce uncertainty bands around near-term supply elasticity assumptions. Deviation in REACH dossier approval timelines or EPA purity threshold enforcement intensity would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Chemicals
Aerosol Cans Market
Specialty Chemicals
Myrcene Market
Specialty Chemicals
Precipitated Barium Sulfate Market
Specialty Chemicals
Magnesium Chelates Market
Specialty Chemicals
US Antimicrobial Plastics Market
Specialty Chemicals
Palm Methyl Ester Derivatives Market
Specialty Chemicals
Global Fabric Softener Sheet Market
Specialty Chemicals
High-K and CVD ALD Metal Precursors Market
Specialty Chemicals
Plastic Stabilizer Market
Specialty Chemicals
Enzyme Inhibitors Market
Specialty Chemicals
Ethyl Ascorbic Acid Market
Specialty Chemicals
Polyquaternium 6 Market
Specialty Chemicals
Specialty Plasticizer Market
Specialty Chemicals
Global Caffeic Acid Market
Specialty Chemicals
Monomethylsilanetriol Market
Specialty Chemicals
Structure Directing Agents Market