
 Acrylic Powder Market | 2026-2036
Acrylic Powder Market Size, Share, and Industry Trends Forecast 2026-2036
Acrylic Powder Market Analysis
Buyer concentration among professional nail salon chains is restructuring procurement patterns across cosmetic-grade acrylic powder. PPG Industries leverages its coatings heritage to supply industrial-grade formulations, while BASF SE anchors European supply through its Ludwigshafen polymer complex. Mitsubishi Chemical Corporation dominates Asian electronics-grade acrylics through captive monomer production.
Acrylic powder consists of polymethyl methacrylate (PMMA) or copolymer resins ground to 50-150 micron particle size, polymerized through suspension or emulsion processes to create thermoplastic binders for coatings, adhesives, and cosmetic applications. Polymer acrylics sustain the largest volume share in architectural coatings where weatherability commands premium positioning, while specialty acrylics lead margin pools in electronics encapsulants requiring optical clarity. Copolymer acrylics compete aggressively in automotive refinish through flexibility and adhesion balance.
EPA oversees volatile organic compound limits in architectural coatings, while FDA governs monomer residual thresholds in cosmetic nail applications, and REACH mandates registration of methacrylic acid esters across EU member states. These frameworks elevate compliance costs for smaller compounders while rewarding integrated manufacturers with in-house toxicology and analytical capabilities. Stakeholders must monitor evolving per- and polyfluoroalkyl substance restrictions that could displace certain acrylic modifiers in food-contact and textile coatings.
Market Dynamics
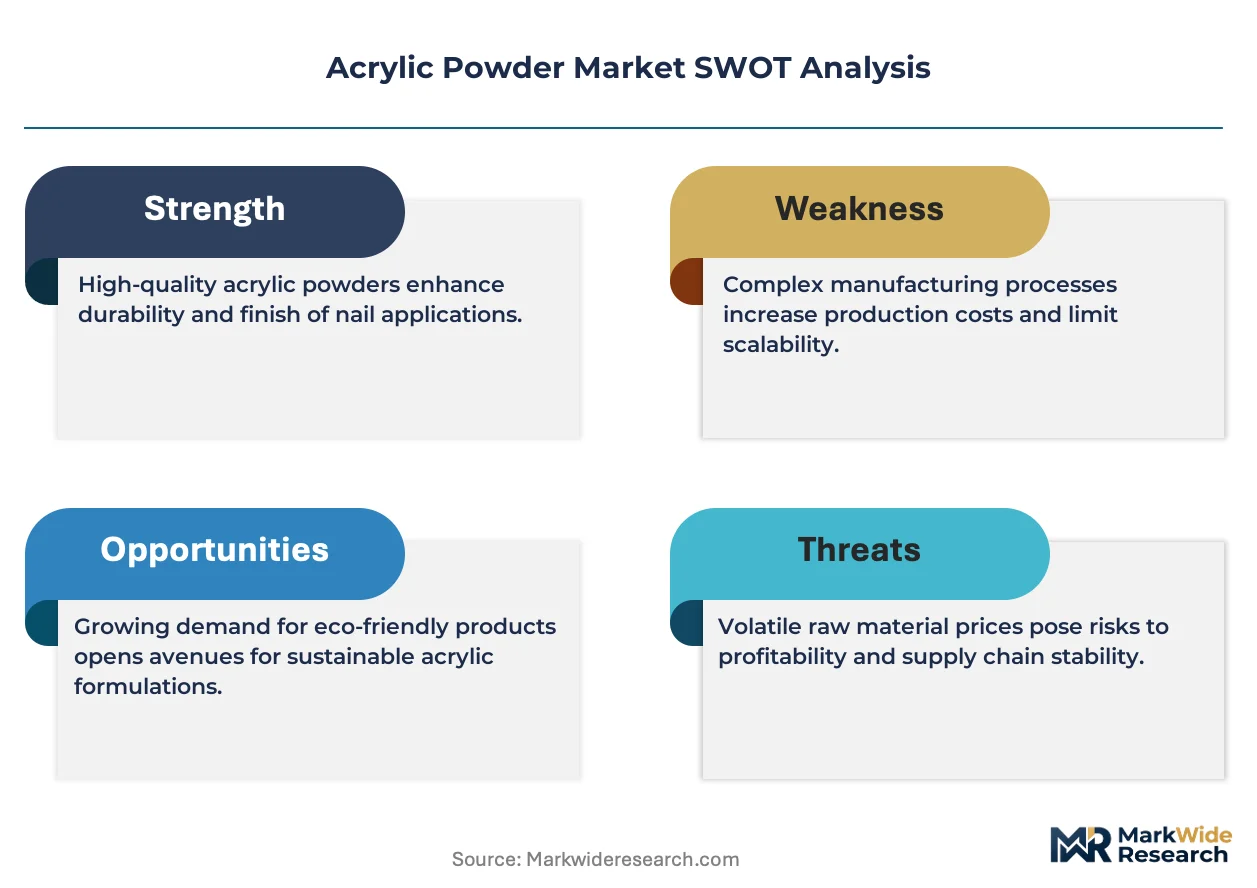
Professional nail salon chains in the United States are consolidating procurement volumes and demanding cosmetic-grade acrylic powder with verified monomer purity documentation, compressing margins for non-integrated compounders while rewarding manufacturers with captive monomer production and in-house toxicology laboratories.
Growth Catalysts
- REACH Phase-In Substances:ECHA's tightening purity thresholds for methacrylic acid esters are accelerating replacement cycles in European professional nail services as salons upgrade to compliant formulations.
- Guangdong Export Manufacturing:Cosmetic-grade powder production clusters in China's southern province dominate international supply, creating scale economies that lower unit costs for professional-grade acrylic services.
- UV-Cured Copolymer Systems:Faster-curing polymer technologies are reducing salon service times and expanding throughput capacity for high-volume nail chains.
Market Restraints
- Methyl Methacrylate Price Volatility:Feedstock cost fluctuations for primary monomers squeeze compounder margins during crude oil price spikes.
- Guangdong Supply Concentration:Overreliance on a single Chinese province for export-grade powder creates geopolitical and logistics vulnerability for international buyers.
- Residual Monomer Thresholds:FDA's strict cosmetic nail application limits require costly purification equipment that smaller manufacturers cannot afford.
Strategic Opportunities
- Indian Professional Salon Expansion:Underpenetrated metro markets in Mumbai and Delhi present first-mover positioning for compliant cosmetic-grade supply.
- 3D-Printed Nail Prosthetics:Convergence of additive manufacturing with acrylic powder binders opens medical-grade aesthetic reconstruction applications.
- Direct-to-Salon Digital Platforms:E-procurement channels bypass traditional distributor markups and capture margin from fragmented professional buyers.
Industry Challenges
- Polymerization Chemistry Expertise Gap:Shortage of suspension process engineers limits capacity expansion for mid-tier compounders seeking scale.
- Dual Certification Timelines:Simultaneous FDA cosmetic and EPA coatings compliance extends product launch cycles by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Acrylic Powder Market |
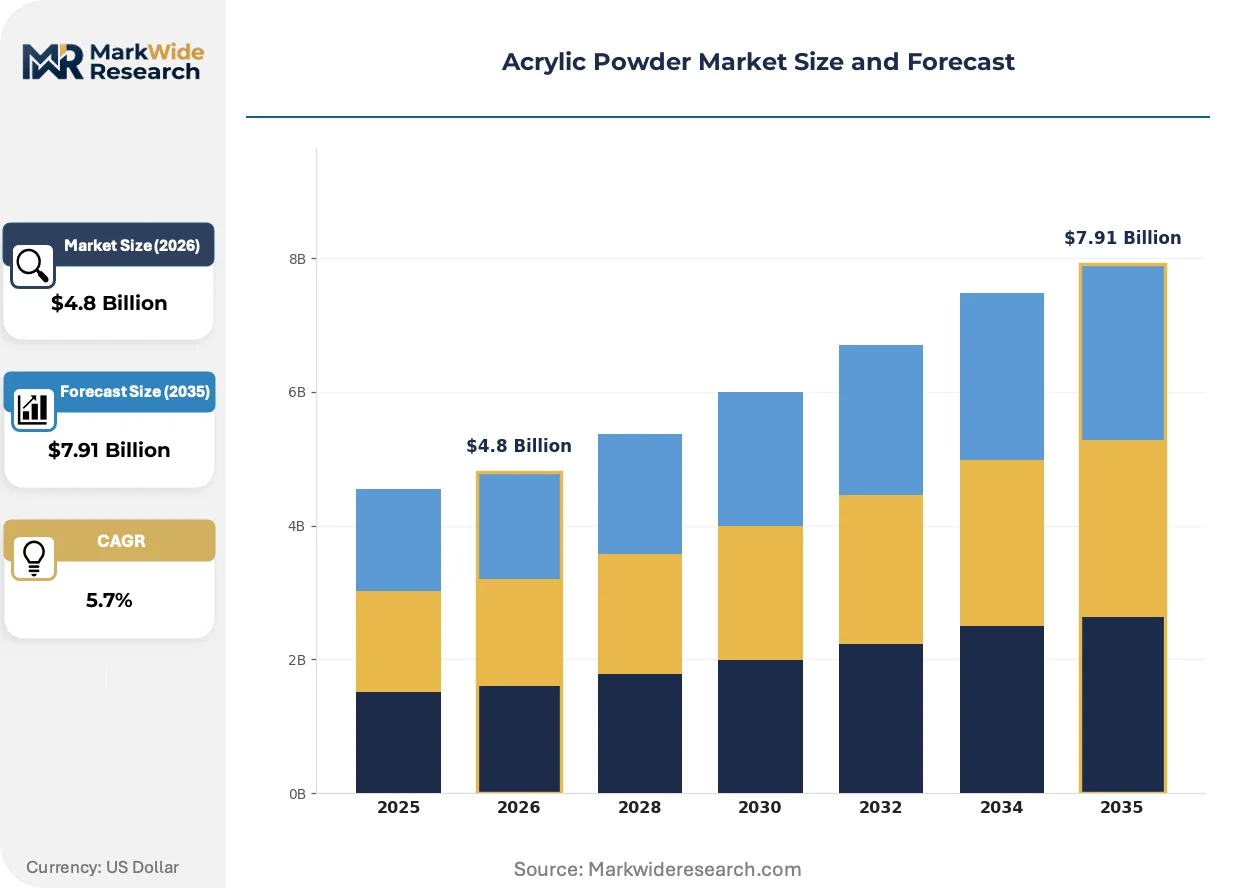
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polymer Acrylics, Copolymer Acrylics, Specialty Acrylics, Liquid Acrylics End User: Construction, Automotive, Cosmetics, Electronics Form: Powder, Granule, Liquid, Sheet Application: Paint & Coating, Adhesives, Sealants, Ink Production |
| Companies Covered | PPG Industries, BASF SE, Mitsubishi Chemical Corporation, Axalta Coating Systems, Covestro AG, AkzoNobel, Wanhua Chemical Group, DIC Corporation, Arkema, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Acrylic Powder Market Emerging Trajectories
Acrylic powder manufacturing is experiencing simultaneous pressure from regulatory purity mandates and demand-side consolidation, forcing technology investments that alter competitive positioning across professional cosmetic and industrial coatings segments.
Atomized particle size control below 75 microns is decentralizing quality differentiation away from large integrated manufacturers toward specialized grinding houses with precision classification equipment. Professional nail salon chains in California and Texas are sourcing directly from these specialized processors, bypassing traditional branded compounders. This fragmentation is compressing brand premium capture and shifting margin toward particle engineering capability.
REACH authorization requirements for methacrylic acid esters are forcing reformulation investments across European supply chains. Manufacturers with Ludwigshafen-scale polymer complexes absorb compliance costs through volume, while smaller compounders exit or seek toll manufacturing arrangements. Professional-grade cosmetic applications face the steepest purity documentation burdens, accelerating consolidation among EU-based suppliers.
Subscription-based inventory replenishment is replacing spot purchasing among North American salon chains with 50-plus locations. Distributors are unbundling technical service from product supply, converting to pure logistics plays. This behavioral shift concentrates negotiating leverage with procurement consortia in Florida and New York, where multi-location operators negotiate master supply agreements directly with Guangdong manufacturers.
Acrylic Powder Market Segmentation
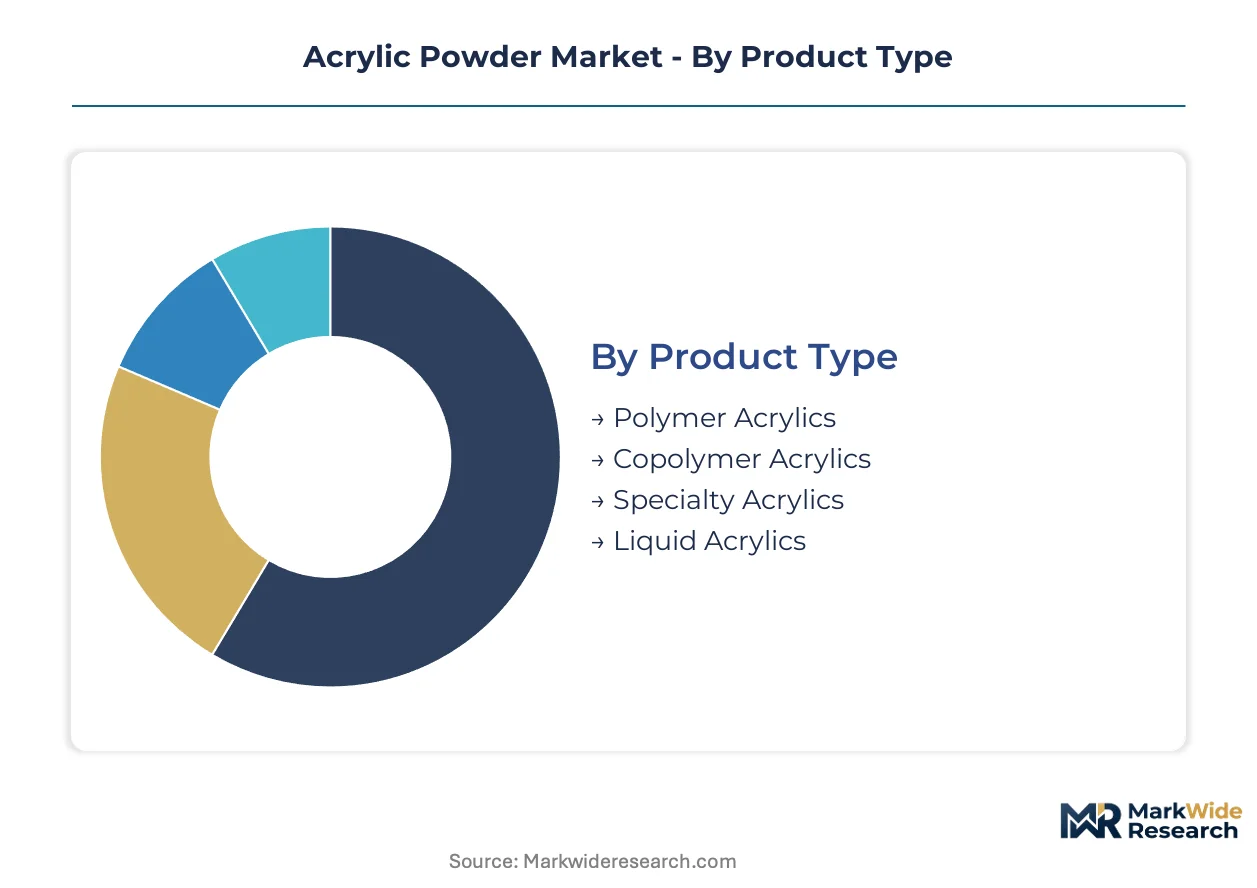
Acrylic powder segmentation reveals divergent purity requirements and formulation standards across professional nail services, industrial coatings, and medical-grade applications. Each dimension carries distinct regulatory burdens and margin structures that reshape procurement patterns among integrated manufacturers and specialized compounders.
Product Type:
Replacement cycles for professional-grade formulations are accelerating as REACH Phase-In substances force upgrades across European salon networks.
- Polymer Acrylics:Polymethyl methacrylate resins manufactured through suspension polymerization dominate architectural coatings where weatherability specifications command premium positioning. Demand concentrates in United States commercial construction projects where EPA VOC compliance drives specification upgrades.
- Copolymer Acrylics:Modified methacrylate formulations balance flexibility and adhesion for automotive refinish applications. Professional collision repair chains in Germany and Texas are consolidating procurement around compliant supply with verified monomer purity documentation.
- Specialty Acrylics:Electronics-grade formulations requiring optical clarity for encapsulant applications.
- Liquid Acrylics:Pre-monomer solutions serving rapid-cure nail service formats in high-throughput salon environments.
Polymer acrylics sit at the top of the volume ranking, with specialty acrylics climbing the fastest.
End User:
Cost tier differentiation separates specification-grade supply from commodity formulations across construction and cosmetics segments.
- Construction:Architectural coatings and sealant applications requiring weather-resistant PMMA binders. Demand clusters in United States commercial building refurbishment cycles where EPA VOC limits accelerate compliant product adoption.
- Cosmetics:Professional nail salon services demanding cosmetic-grade powder with residual monomer documentation below FDA thresholds. Chains in California and Florida negotiate master supply agreements directly with Guangdong manufacturers.
- Automotive:Refinish coatings and adhesive bonding for collision repair networks.
- Electronics:Optical encapsulants and display substrates requiring ultra-high purity.
Construction commands the largest volume position, while cosmetics generates the steepest expansion trajectory.
Form:
Application requirements dictate physical state selection across coating viscosity specifications and cure-time constraints.
- Powder:50-150 micron particle size for thermoplastic binder applications in coatings and nail services. Guangdong manufacturing clusters dominate export supply for professional-grade cosmetic applications.
- Liquid:Pre-polymerized solutions enabling UV-cure systems that reduce salon service times.
- Granule:Intermediate processing feedstock for industrial compounding operations.
- Sheet:Cast acrylic for signage and architectural glazing applications.
Powder form maintains volume leadership, with liquid formulations expanding most quickly in professional cosmetic segments.
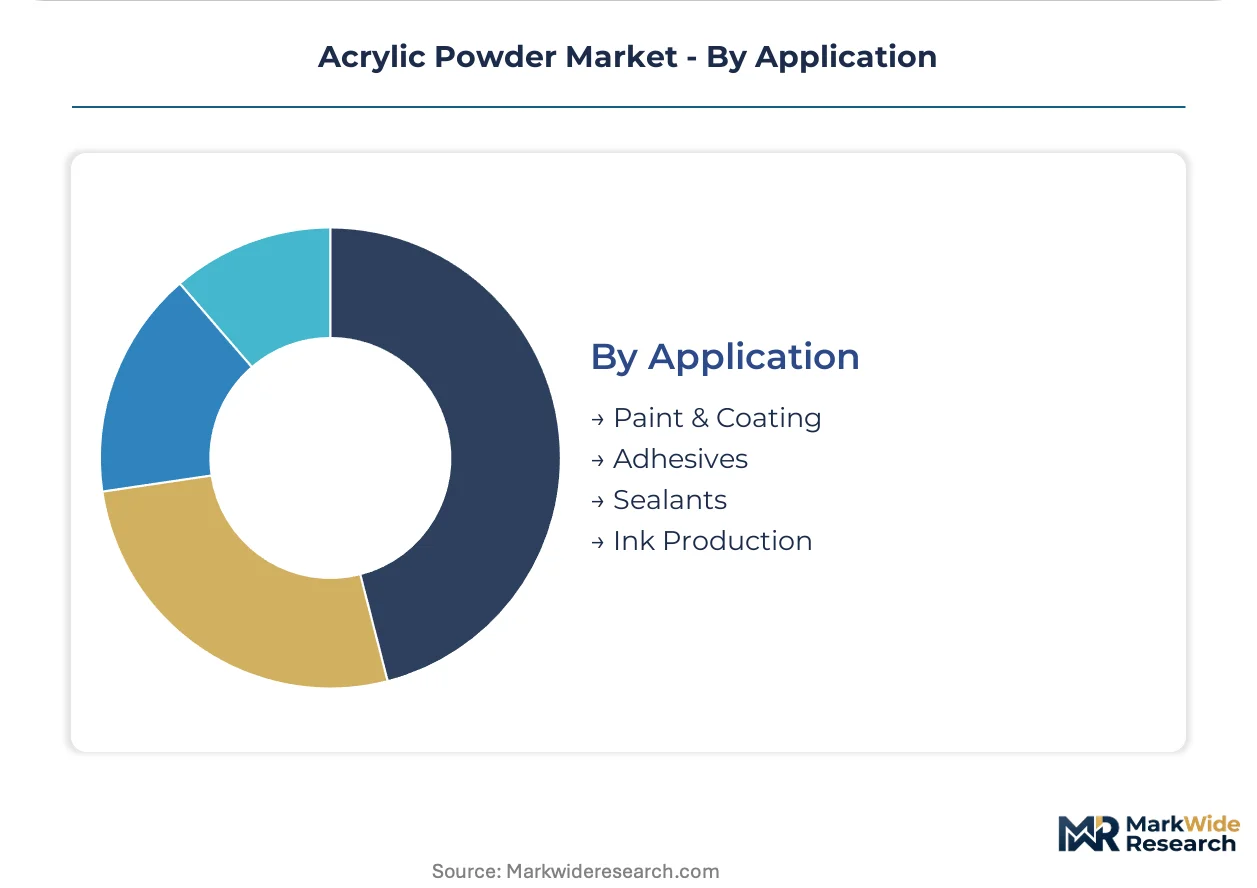
Application:
Margin concentration varies sharply between commodity architectural coatings and specialized electronics encapsulants.
- Paint & Coating:Architectural and industrial finishes representing the largest volume outlet. United States commercial construction procurement favors suppliers with integrated monomer production and in-house toxicology capabilities.
- Adhesives:Structural bonding applications in automotive and electronics assembly.
- Sealants:Weatherproofing formulations for building envelope applications.
- Ink Production:Specialty printing applications requiring precise particle size distribution.
Paint and coating sits at the top of the volume ranking, with adhesives climbing the fastest in automotive assembly applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Skilled polymerization chemists and suspension process engineers concentrate in Germany's Rhine-Neckar industrial corridor and China's Pearl River Delta manufacturing belt. These talent pools anchor acrylic powder production networks serving professional nail services and industrial coatings.
United States
Professional nail salon chains in California and Florida consolidate procurement volumes for cosmetic-grade acrylic powder. FDA enforces residual monomer thresholds below strict cosmetic application limits. Dallas-Fort Worth hosts distribution hubs serving multi-location operators negotiating master supply agreements directly with Asian manufacturers.
Germany
Automotive refinish networks in Bavaria and North Rhine-Westphalia drive copolymer acrylic demand for collision repair applications. ECHA's REACH Phase-In substances mandate tightening purity documentation for methacrylic acid esters. The Ludwigshafen polymer complex anchors European supply with integrated monomer production and in-house toxicology capabilities.
China
Export manufacturing clusters in Guangdong province dominate international cosmetic-grade powder supply for professional nail services. The country's national chemical regulator enforces GB standards for industrial coatings while cosmetic-grade production follows dual carbon goals emission targets. Shenzhen and Dongguan house precision grinding houses with atomized particle size control below 75 microns.
Japan
Electronics-grade specialty acrylics for optical encapsulants concentrate in the Kansai and Chubu industrial regions. METI oversees chemical substance management aligning with international frameworks. Osaka-based manufacturers supply display substrate applications requiring ultra-high purity formulations.
India
Underpenetrated professional salon markets in Mumbai and Delhi present expansion opportunities for compliant cosmetic-grade supply. BIS certification requirements for imported chemical products create entry barriers for non-integrated compounders. Maharashtra's Thane-Belapur industrial belt hosts emerging toll manufacturing arrangements for mid-tier regional suppliers.
Acrylic Powder Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across distinct margin tiers in acrylic powder supply. The market structure shows moderate consolidation among integrated manufacturers with captive monomer production, while specialized grinding houses fragment the precision particle size segment. Three archetypes dominate: coatings heritage conglomerates with polymer complex scale, Asian electronics-grade specialists with optical clarity capabilities, and Chinese export manufacturers with Guangdong cluster economics. Competitive moves center on backward integration into monomer production and direct-to-salon digital platform development bypassing traditional distribution markups.
Among coatings heritage conglomerates, PPG Industries and BASF SE exemplify integrated manufacturers absorbing regulatory compliance costs through volume scale. Mitsubishi Chemical Corporation occupies a position within the electronics-grade specialty tier, representing Asian producers with captive monomer supply chains. These three anchors illustrate how competitive positioning separates specification-grade suppliers from commodity compounders across professional cosmetic and industrial coatings applications.
| Leading Market Players |
|---|
| PPG Industries |
| BASF SE |
| Mitsubishi Chemical Corporation |
| Axalta Coating Systems |
| Covestro AG |
| AkzoNobel |
| Wanhua Chemical Group |
| DIC Corporation |
| Arkema |
| Others |
Supply Flow & Price Mechanics
Certification-grade divergence between FDA-compliant cosmetic formulations and industrial coatings creates parallel pricing architectures that fragment procurement leverage across buyer archetypes. Premium cosmetic-grade supply commands documentation premiums through captive monomer production and in-house toxicology capabilities, while commodity architectural coatings compete on scale economies from integrated polymer complexes.
Pricing Analysis
Capacity additions in Guangdong are reshaping price floors for professional-grade cosmetic powder as precision grinding houses with atomized particle control below 75 microns bypass traditional branded compounders. Three-tier pricing structure across premium, standard, and economy levels separates specification-grade supply with verified purity documentation from commodity architectural formulations. Pricing pressure stems from methyl methacrylate feedstock volatility during crude oil spikes, compressing compounder margins. Professional nail salon chains with 50-plus locations exhibit lowest price sensitivity through subscription-based replenishment contracts, while mid-tier independent salons remain highly price-sensitive to spot purchasing fluctuations.
Supply Chain Analysis
Dual-sourcing requirements from North American salon chains now mandate qualified backup supply from both Guangdong clusters and Ludwigshafen-scale European manufacturers. Geographic concentration centers on China, Germany, and the United States for differentiated grade production. Raw material dependencies rest on methyl methacrylate monomer, suspension-grade PMMA resins, and optical-grade methacrylic acid esters. Single-source vulnerability concentrates in Guangdong export manufacturing, where geopolitical friction or logistics disruption threatens international cosmetic-grade supply. Distribution runs through direct-to-salon digital platforms that bypass traditional distributor markups and capture margin from fragmented professional buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The acrylic powder market reads as a late-cycle quality story as REACH Phase-In substances and FDA residual monomer thresholds force professional nail services toward premium compliant formulations with verified documentation.
For Market Incumbents: Anchor defensive positioning through backward integration into captive monomer production and in-house toxicology laboratories that absorb regulatory compliance costs smaller compounders cannot bear. Threat from specialized grinding houses with precision particle engineering capability fragments brand premium capture and shifts margin toward technical service unbundling. Prioritize certification investment across simultaneous FDA cosmetic and EPA coatings compliance to extend product launch cycle advantages. For New Entrants and Emerging Players: Begin with underpenetrated metro markets in Mumbai and Delhi where BIS certification barriers filter non-integrated compounders and first-mover compliant supply secures professional salon expansion. Target toll manufacturing arrangements in Maharashtra's Thane-Belapur industrial belt to bypass capital-intensive purification equipment requirements. Deploy direct-to-salon digital procurement platforms that capture margin from fragmented professional buyers bypassing traditional distribution. For Investors and Strategic Acquirers: Consolidation pressure builds where dual certification timelines and monomer purity documentation burdens exceed smaller compounder capabilities, forcing exit or acquisition by integrated manufacturers. Long-term viability favors Ludwigshafen-scale polymer complexes with captive monomer production and established toxicology infrastructure over mid-tier regional suppliers. Signal to watch is subscription-based inventory replenishment penetration among North American salon chains with 50-plus locations, indicating procurement leverage concentration that favors scale players.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Monomer Production | Captive methyl methacrylate supply absorbs REACH and FDA compliance cost volatility for integrated manufacturers. |
| Direct-to-Salon Digital Platform Development | E-procurement channels bypass distributor markups and capture margin from fragmented professional nail salon buyers. |
| Precision Particle Engineering Capability | Atomized particle size control below 75 microns decentralizes quality differentiation toward specialized grinding houses. |
| Dual Certification Investment | Simultaneous FDA cosmetic and EPA coatings compliance extends product launch cycles and filters smaller compounders. |
| Guangdong Manufacturing Cluster Expansion | Scale economies in cosmetic-grade powder production dominate international export supply for professional nail services. |
Methodological Framework
Multiple input streams — primary interviews with plant managers at polymer complexes, procurement leads at professional nail salon chains, distribution channel partners, and technical R&D directors, alongside secondary validation through customs/trade data, ACC and Cefic industry reports, and SEC 10-K filings from coatings heritage conglomerates — were reconciled through bottom-up and top-down triangulation to construct market estimates.
Data-stream reconciliation across product type segmentation by grade tier, end-use industry differentiation between cosmetics and construction, form factor variation across powder and liquid states, and regional production hub analysis generated volume and value outputs throughout the forecast period. CAGRs were derived from modeled substitution effects between polymer, copolymer, and specialty acrylic formulations and feedstock cost trajectory assumptions for methyl methacrylate monomer.
Caveats apply where methyl methacrylate price volatility, REACH authorization timeline extensions, or geopolitical disruption to Guangdong export logistics could materially shift the outlook. Deviation in professional nail salon chain consolidation velocity or dual certification regulatory burden intensity would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Chemicals
Flame-Retardant Synergist Systems with Low Smoke Toxicity Market
Specialty Chemicals
1,2 Hexanediol Market
Specialty Chemicals
US Post Laser Recovery Products Market
Specialty Chemicals
Avobenzone Market
Specialty Chemicals
Perfluoropolyether (PFPE) Market
Specialty Chemicals
Carnauba Wax Market
Specialty Chemicals
Preparative Chromatography Market
Specialty Chemicals
Isoeicosane Market
Specialty Chemicals
Eitelite Market
Specialty Chemicals
Polyglycerol Sebacate (PGS) Market
Specialty Chemicals
Ethyl Polysilicate Market
Specialty Chemicals
Global Baking Soda Substitute Market
Specialty Chemicals
Bio-Based Phenol Market
Specialty Chemicals
Global Tetrahexyldecyl Ascorbate Market
Specialty Chemicals
Global Specialty Resins Market
Specialty Chemicals
Nucleotides Market