
 Monomethylsilanetriol Market | 2026-2036
Monomethylsilanetriol Market Size, Share, and Industry Trends Forecast 2026-2036
Monomethylsilanetriol Market Analytics
Technical support subscriptions for formulation guidance is restructuring how monomethylsilanetriol suppliers monetize relationships beyond commodity chemical sales. Silicium Laboratories LLC leverages its vertical integration from silicon metal to finished silanol to sustain cost advantages in pharmaceutical-grade batches. Exsymol anchors European supply through its specialized cosmetic active ingredient channel, while Seppic competes by extending its surfactant expertise into silicon-based delivery systems for skincare brands.
Monomethylsilanetriol is a trihydroxysilane compound with the molecular formula CH3Si(OH)3, synthesized through controlled hydrolysis of methyltrichlorosilane under acidic conditions to preserve reactive Si-OH groups for crosslinking applications. The liquid product type dominates current volume due to its ease of incorporation into aqueous cosmetic and coating formulations, though powder grades command margin premiums in pharmaceutical tableting where moisture sensitivity governs specification. Aerospace end users represent the fastest-growing demand pool as thermal protection systems adopt ceramic precursors derived from organosilanol oligomers.
REACH registration requirements in the European Union and FDA cosmetic ingredient safety assessments in the United States shape purity documentation burdens that smaller suppliers struggle to meet. China's NMPA now requires pre-market notification for new cosmetic ingredients containing silicon compounds, adding compliance layers for cross-border suppliers. Stakeholders must monitor evolving per- and polyfluoroalkyl substance restrictions that could redirect fluoropolymer demand toward silicon-based alternatives in sealant and coating applications.
Market Dynamics
REACH compliance in the European Union is compressing supplier margins as ECHA tightens purity thresholds for silanol-based cosmetic ingredients, forcing batch-level documentation upgrades that smaller manufacturers cannot absorb.
Growth Catalysts
- MFDS cosmetic ingredient notifications:South Korean formulators now specify monomethylsilanetriol for bioactive silicon delivery in anti-aging skincare, creating specification pull from Seoul-based R&D centers.
- Aerospace thermal protection systems:Ceramic precursors derived from organosilanol oligomers are displacing legacy ablative materials in next-generation re-entry vehicle shielding.
- German cGMP certification tiers:Pharmaceutical-grade manufacturing clusters in Bavaria and Hesse distinguish supply quality, concentrating premium volume in FDA-inspected facilities.
Market Restraints
- Methyltrichlorosilane feedstock volatility:Chlorosilane pricing swings tied to polysilicon solar demand create margin compression for hydrolysis-based producers.
- REACH registration documentation burdens:ECHA data requirements for tonnage band upgrades impose six-figure compliance costs that exclude sub-scale European suppliers.
- Fluoropolymer substitution ceiling:Per- and polyfluoroalkyl substance restrictions redirect some sealant demand, but silicon-based alternatives face performance gaps in extreme chemical exposure environments.
Strategic Opportunities
- China NMPA pre-market notification pathway:Cross-border suppliers who establish Shanghai-based regulatory liaison capabilities gain first-mover positioning in cosmetic ingredient filings.
- Technical support subscription models:Formulation guidance services monetize relationships beyond commodity chemical sales, locking in specification control with mid-sized cosmetic brands.
- Powder-grade pharmaceutical tableting:Moisture-sensitive grades command margin premiums in oral solid dosage manufacturing where aqueous liquid grades fail stability protocols.
Industry Challenges
- Silanol stability expertise scarcity:Formulation chemists with crosslinking kinetics specialization command premium compensation, constraining R&D throughput at emerging suppliers.
- Dual-use export control alignment:Aerospace ceramic precursor applications trigger ITAR and EAR classification reviews that extend order-to-delivery timelines by 90-120 days.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Monomethylsilanetriol Market |
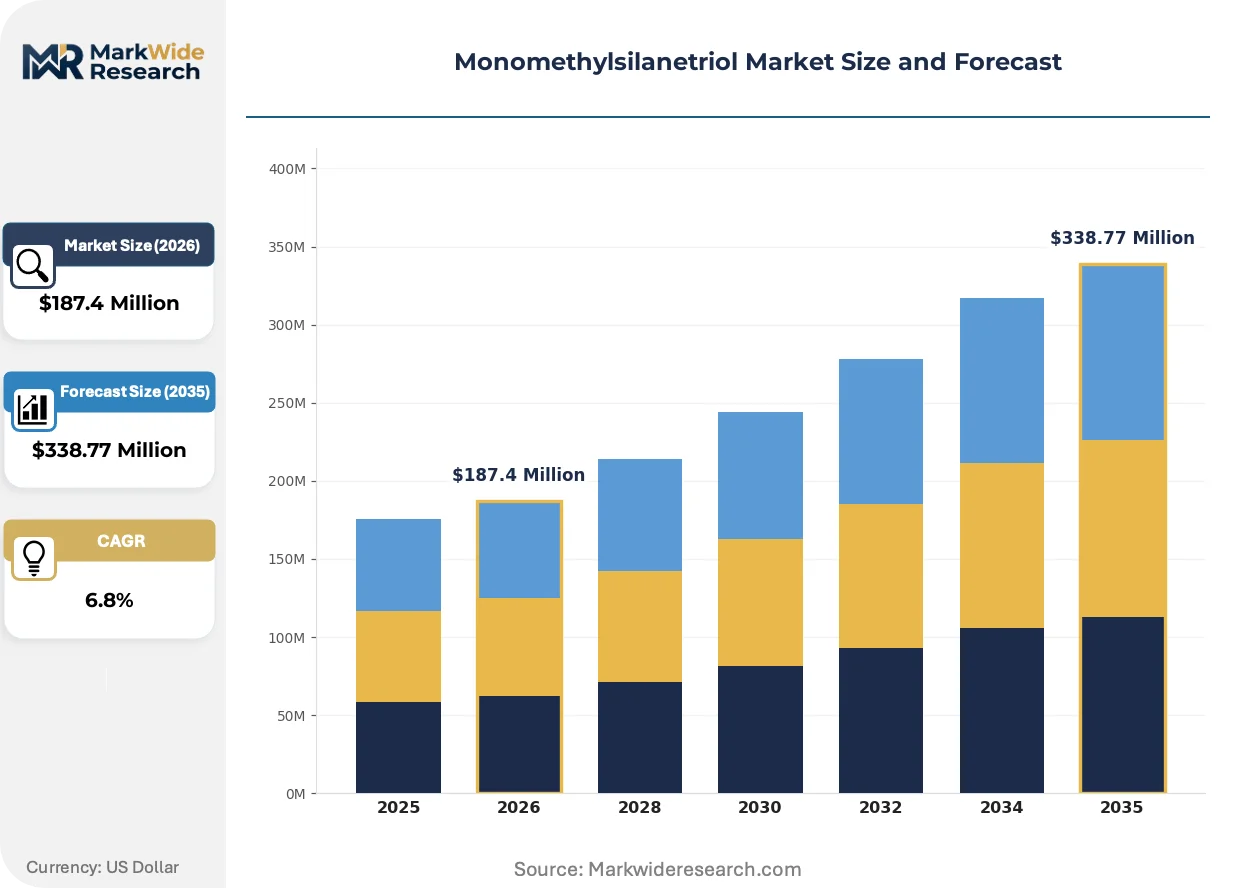
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid, Powder, Gel, Paste Application: Adhesives, Sealants, Coatings, Insulation End User: Construction, Electronics, Automotive, Aerospace Distribution Channel: Online, Offline, Direct Sales, Distributor |
| Companies Covered | Silicium Laboratories LLC, Exsymol, Seppic, Dr. Paul Lohmann, Laboratoires Innothera, Wallach Laboratories, BioSil, NutriDyn, Silica Laboratories, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Monomethylsilanetriol Market Evolving Landscape
Silicon-based delivery systems are displacing conventional surfactant carriers in premium skincare, while regulatory documentation requirements reshape competitive moats around purity verification capabilities.
Organosilanol oligomer synthesis is converging with sol-gel ceramic processing for thermal protection applications. NASA and ESA contractors are adopting methyl-substituted silanol precursors for ablative heat shield matrices. This convergence is compressing qualification timelines for legacy phenolic resin suppliers in the defense supply base.
ECHA's 2024 update to REACH Annex XVII restrictions on siloxane compounds is tightening residual D4/D5/D6 limits in cosmetic-grade monomethylsilanetriol. German and French formulators now require sub-ppm certification that only vertically integrated silicon metal-to-silanol producers can economically deliver. The compliance burden is filtering distributor-heavy supply chains out of premium cosmetic channels.
Cosmetic brands are unbundling technical formulation support from ingredient procurement, subscribing to silanol suppliers for guided silicon bioavailability optimization. South Korean and Japanese skincare houses lead this shift, replacing spot purchasing with annual formulation partnership contracts. The service layer is most developed in Seoul and Tokyo, where MFDS and PMDA notification requirements already demand ongoing regulatory collaboration.
Monomethylsilanetriol Market Segmentation
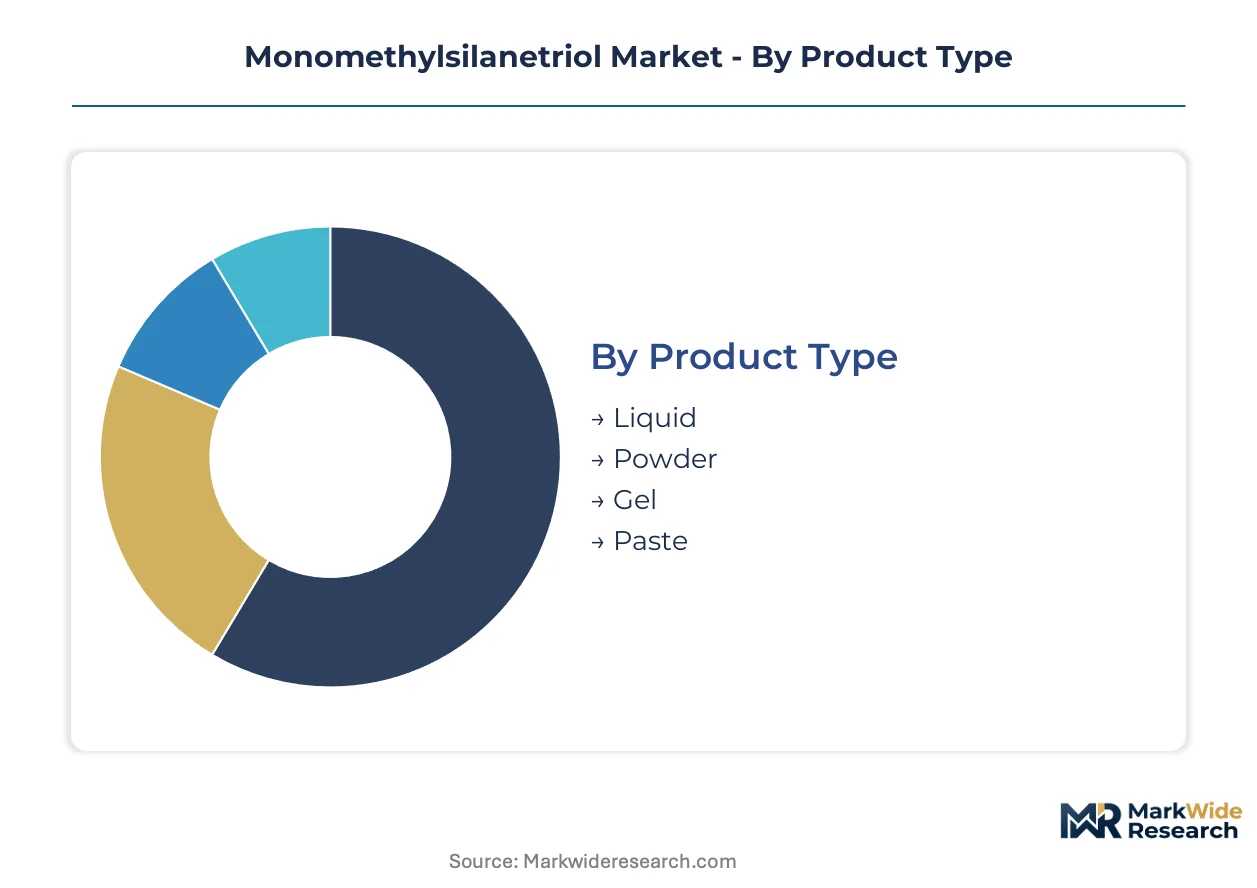
Monomethylsilanetriol procurement patterns diverge sharply across product forms and end-use specifications. REACH registration tiers and aerospace ITAR classifications fragment supplier capabilities, making segment-specific compliance the primary vendor selection filter.
Product Type:
Liquid grades require FDA cosmetic ingredient safety assessments for skincare applications, while powder specifications trigger pharmaceutical cGMP certification burdens that only captive silicon metal producers absorb profitably.
- Liquid:Aqueous solution with preserved Si-OH reactivity enables direct incorporation into cosmetic emulsions and waterborne coatings. South Korean formulators in Seoul R&D centers specify this grade for MFDS-notified anti-aging serums, though moisture sensitivity constrains shelf life.
- Powder:Spray-dried or crystallized solid with sub-ppm residual siloxane certification demanded by German pharmaceutical tableting operations. Bavarian cGMP facilities command margin premiums for moisture-stable oral solid dosage applications where liquid grades fail stability protocols.
- Gel:Thixotropic semisolid for controlled-release topical delivery systems requiring rheology modification.
- Paste:High-viscosity compound for gap-filling sealant formulations in industrial assembly.
Liquid sits at the top of the volume ranking, with powder climbing the fastest.
Application:
Cost tiers separate commodity construction sealants from aerospace thermal protection systems where ceramic precursor qualification absorbs six-figure development investment.
- Adhesives:Structural bonding formulations leverage silanol crosslinking kinetics for moisture-cure systems. Automotive assembly plants in Stuttgart and Detroit specify these for lightweight vehicle bonding where phenolic alternatives add weight.
- Sealants:Joint-filling compounds for construction and transportation applications. Japanese infrastructure contractors favor methyl-substituted silanol bases for their hydrophobic durability in coastal environments.
- Coatings:Surface protection films with sol-gel ceramic conversion capability.
- Insulation:Thermal and electrical barrier materials for high-temperature electronics.
Sealants generate the highest shipment volumes, with coatings gaining share fastest in thermal protection applications.
End User:
Customer maturity separates specification-driven aerospace primes from price-sensitive construction distributors.
- Construction:Volume buyers of commodity sealant grades with minimal purity documentation. Chinese infrastructure stimulus drives regional demand concentration, though NMPA notification requirements now filter cross-border suppliers.
- Electronics:Semiconductor packaging and thermal interface material formulators. Taiwan-based substrate manufacturers specify ultra-low ionic content grades for chip-scale reliability.
- Automotive:Lightweighting adhesive applications with OEM qualification timelines.
- Aerospace:Ceramic matrix composite precursors for re-entry vehicle heat shields. NASA and ESA contractors adopt methyl-substituted silanol oligomers, triggering ITAR and EAR classification reviews that extend order-to-delivery timelines substantially.
Construction dominates current volume, with aerospace expanding most quickly on thermal protection system adoption.
Distribution Channel:
Margin structures favor direct technical partnerships over distributor markups in regulated cosmetic and pharmaceutical channels.
- Online:E-procurement platforms for standardized industrial grades with published specifications. Small-batch cosmetic formulators in Tokyo and Seoul leverage digital channels for rapid sampling.
- Offline:Traditional chemical distributor networks serving construction and general industrial accounts. German distributors face margin compression from REACH batch-documentation requirements they cannot pass to sub-scale customers.
- Direct Sales:Annual formulation partnership contracts with technical support subscriptions. South Korean skincare houses subscribe to guided silicon bioavailability optimization, locking in specification control.
- Distributor:Multi-product chemical wholesalers with regional logistics coverage.
Direct sales commands the steepest expansion trajectory as cosmetic brands unbundle formulation support from ingredient procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German pharmaceutical-grade manufacturing clusters concentrate premium supply, while South Korean cosmetic formulators drive specification innovation for bioactive silicon delivery systems.
United States
Aerospace contractors at NASA and ESA adopt methyl-substituted silanol precursors for thermal protection systems. FDA cosmetic ingredient safety assessments shape purity documentation burdens for cross-border suppliers. California-based formulators leverage direct sales channels with technical support subscriptions to lock in specification control.
Germany
Bavarian and Hessian cGMP-certified facilities distinguish pharmaceutical-grade supply tiers with FDA-inspected manufacturing. ECHA REACH registration requirements tighten residual siloxane limits in cosmetic-grade monomethylsilanetriol. Frankfurt-area distributors face margin compression from batch-level documentation upgrades they cannot pass to sub-scale customers.
South Korea
Seoul-based R&D centers specify monomethylsilanetriol for MFDS-notified anti-aging skincare with bioactive silicon delivery. MFDS cosmetic ingredient notifications create specification pull from domestic formulators. Seoul and Tokyo lead the shift toward annual formulation partnership contracts replacing spot purchasing.
China
Infrastructure stimulus drives construction sealant demand concentration for commodity grades. NMPA pre-market notification requirements for new cosmetic ingredients add compliance layers for cross-border suppliers. Shanghai-based regulatory liaison capabilities offer first-mover positioning for cosmetic ingredient filings.
Japan
PMDA notification requirements demand ongoing regulatory collaboration with silanol suppliers. Tokyo-based skincare houses subscribe to guided silicon bioavailability optimization services. Osaka-area electronics manufacturers specify ultra-low ionic content grades for semiconductor packaging reliability.
Monomethylsilanetriol Market Competitive Landscape
Top-tier vendors anchor pharmaceutical-grade certification tiers, while mid-scale cosmetic specialists compete through formulation partnerships. The vendor base stratifies across cGMP-certified silicon metal producers, regional cosmetic active ingredient channels, and technical service integrators. Three archetypes dominate: backward-integrated silicon metal-to-silanol producers, specialized cosmetic ingredient distributors, and surfactant-technology extenders. Competitive moves concentrate on regulatory compliance capacity expansion and technical support subscription monetization.
Within the backward-integrated tier, Silicium Laboratories LLC represents captive silicon metal-to-silanol production capabilities. Exsymol and Seppic occupy positions in the specialized cosmetic ingredient and surfactant-technology extension archetypes respectively, anchoring European supply through differentiated channel strategies.
| Leading Market Players |
|---|
| Silicium Laboratories LLC |
| Exsymol |
| Seppic |
| Dr. Paul Lohmann |
| Laboratoires Innothera |
| Wallach Laboratories |
| BioSil |
| NutriDyn |
| Silica Laboratories |
| Others |
Value Network & Pricing Analysis
MFDS cosmetic ingredient notifications in South Korea are forcing suppliers to absorb batch-level documentation costs that commodity-grade producers cannot shoulder, compressing margins in liquid grades while powder specifications capture premium positioning through Bavarian cGMP certification.
Pricing Analysis
Capacity additions in China's chlorosilane corridor are reshaping price floors for methyltrichlorosilane feedstock, transmitting volatility through hydrolysis-based producers. Three-tier pricing structure across pharmaceutical-grade, cosmetic-grade, and industrial-grade levels separates FDA-inspected facilities from construction sealant suppliers. Pricing pressure stems from REACH registration documentation burdens that smaller European manufacturers cannot pass downstream. Construction distributors exhibit highest price sensitivity, while Seoul-based skincare houses prioritize specification compliance over unit cost.
Supply Chain Analysis
Freight cost differentials between German pharmaceutical clusters and Asian cosmetic formulators are widening as batch-level certification requirements add documentation weight to cross-border shipments. Supply concentrates in Germany, China, and South Korea, with Bavarian cGMP facilities anchoring premium pharmaceutical output. Production draws from methyltrichlorosilane hydrolysis, silicon metal smelting, and controlled atmosphere packaging inputs. Single-source vulnerability in aerospace ceramic precursor channels extends order-to-delivery timelines through ITAR classification reviews. Distribution runs through direct technical partnerships for regulated cosmetic and pharmaceutical grades, with distributor networks serving commodity construction applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds value through regulatory layering, with ECHA's 2024 REACH Annex XVII update on residual siloxane limits creating certification moats that vertically integrated silicon metal producers exploit.
For Market Incumbents: Hedge against methyltrichlorosilane feedstock volatility through captive silicon metal production or long-term offtake agreements with polysilicon solar suppliers. Defend specification control in Seoul and Tokyo cosmetic channels by embedding formulation chemists with subscriber brands, locking out distributor-heavy competitors from premium anti-aging serum supply. For New Entrants and Emerging Players: Enter via Shanghai-based regulatory liaison capabilities to capture first-mover positioning in NMPA pre-market notification pathways for cosmetic ingredient filings. Target powder-grade pharmaceutical tableting specifications where moisture-stable grades command margin premiums and Bavarian cGMP certification filters incumbent competition. Lead with technical support subscription models rather than commodity spot pricing. For Investors and Strategic Acquirers: Asymmetric upside sits with backward-integrated silicon metal-to-silanol producers holding FDA-inspected manufacturing and sub-ppm residual siloxane certification capacity. Long-term viability rests on regulatory compliance infrastructure rather than scale economics alone. Monitor ECHA tonnage band upgrade timelines as inflection indicators for supplier consolidation windows.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Silicon Metal | Captive methyltrichlorosilane supply insulates margins from polysilicon solar demand swings. |
| Shanghai Regulatory Liaison Establishment | NMPA notification capabilities unlock first-mover positioning in Chinese cosmetic ingredient filings. |
| Technical Support Subscription Launch | Annual formulation partnerships with Seoul skincare houses monetize relationships beyond commodity sales. |
| Powder-Grade cGMP Certification Investment | Bavarian FDA-inspected facilities command margin premiums in moisture-sensitive pharmaceutical tableting. |
| Aerospace Ceramic Precursor Qualification | NASA and ESA contractor adoption displaces legacy phenolic resin suppliers in thermal protection systems. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with cosmetic formulators, pharmaceutical procurement leads, chlorosilane plant managers, and aerospace materials engineers with secondary validation from ECHA registration databases, FDA cosmetic ingredient filings, customs trade data, and SEC chemical company disclosures. Bottom-up volume modeling and top-down value triangulation cross-checked segment outputs.
Segment-weighting approaches applied across product type, application, end user, and distribution channel dimensions, with regional production hub clustering layered in for supply-side calibration. CAGRs were derived from trajectory fitting to historical volume patterns and elasticity-adjusted demand projections. Forecast inputs incorporated REACH compliance cost absorption rates and aerospace ceramic precursor qualification timelines.
Inputs from ECHA registration databases and FDA cosmetic ingredient filings were available through the study window; gaps in proprietary aerospace contractor procurement data introduce uncertainty bands around thermal protection system adoption curves. Forecasts reflect documented assumptions about regulatory enforcement intensity and feedstock price transmission mechanisms. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Chemicals
Protein Purification Resin Market
Specialty Chemicals
GLDA Market
Specialty Chemicals
Bemotrizinol Market
Specialty Chemicals
Specialty Oxidants Market
Specialty Chemicals
India Prussian Blue Market
Specialty Chemicals
Global Anti-Static Agents Market
Specialty Chemicals
Marula Oil Market
Specialty Chemicals
Global Foam Blowing Agents Market
Specialty Chemicals
UK Insect Repellent Market
Specialty Chemicals
Fluorinated Plasma Surface Treatment Market
Specialty Chemicals
Free-From Titanium Dioxide Market
Specialty Chemicals
Ethylhexane Diol Market
Specialty Chemicals
Rosin Press Market
Specialty Chemicals
Ascorbic Acid Market
Specialty Chemicals
Global Non-Phthalate Plasticizers Market
Specialty Chemicals
Biodegradable Chelating Agents Market