
 Tetrabromobisphenol a (TBBPA) Market | 2026-2036
Tetrabromobisphenol a (TBBPA) Market Size, Share, and Industry Trends Forecast 2026-2036
Tetrabromobisphenol a (TBBPA) Market Analysis
Chinese bromine compounders is pivoting toward higher-purity TBBPA grades for epoxy resin laminates. Albemarle Corporation leverages its integrated bromine supply chain to sustain cost competitiveness across North American and Asian markets. ICL anchors its position through specialized flame retardant portfolios serving electrical laminators, while LANXESS competes on REACH-certified product lines for European polymer blenders.
Tetrabromobisphenol A functions as a brominated aromatic compound containing four bromine atoms attached to a bisphenol A backbone, primarily serving as a reactive flame retardant in epoxy resin systems for printed circuit boards. The flame retardant product type dominates volume flows due to embedded demand from multilayer PCB manufacturing, while polymer blends application segments attract margin premiums from automotive electronics specification requirements. Coatings applications represent the fastest-expanding structural pocket as electric vehicle battery enclosures drive intumescent formulation demand.
EPA oversight under the Toxic Substances Control Act shapes permissible TBBPA import thresholds and domestic blending requirements in the United States. ECHA's persistent organic pollutant screening criteria and REACH authorization lists constrain formulation choices across European electrical and electronics value chains. China's MEE enforcement of dual carbon goals pressures Shandong province bromine refiners to adopt cleaner extraction processes. Stakeholders must monitor regulatory divergence between jurisdictions to determine certification investment sequencing and regional capacity allocation priorities.
Market Dynamics
REACH authorization pressures and China's dual carbon enforcement are fragmenting formulation strategies across electrical laminators, forcing producers to maintain parallel certified and uncertified product lines while bromine refiners absorb extraction compliance costs.
Growth Catalysts
- Multilayer PCB proliferation:High-density interconnect boards in 5G infrastructure and automotive electronics embed TBBPA as a reactive flame retardant in epoxy laminates, sustaining volume pull from fabrication facilities in China and Taiwan.
- RoHS exemptions for brominated compounds:The European directive's continued allowance for specific brominated flame retardants in critical electronics preserves formulation continuity for EU-bound circuit board exporters.
- Electric vehicle battery enclosure specifications:Intumescent coating mandates for thermal runaway protection in EV battery packs are opening new demand channels for TBBPA-modified epoxy systems.
Market Restraints
- Bromine supply concentration:Over 70 percent of elemental bromine derives from Shandong province salt lake operations, exposing downstream compounders to weather-induced extraction disruptions and provincial environmental enforcement volatility.
- ECHA POP screening criteria:Persistent organic pollutant evaluation pathways for brominated aromatics create formulation uncertainty for European electrical laminators, delaying long-term procurement commitments.
- Phosphorus-nitrogen synergist substitution:Non-halogenated flame retardant systems are capturing specification share in consumer electronics enclosures where thermal performance requirements permit lower loadings.
Strategic Opportunities
- India electronics manufacturing clusters:PLI scheme incentives for semiconductor and PCB fabrication in Gujarat and Tamil Nadu are attracting laminators seeking localized flame retardant supply chains outside China.
- Recyclable epoxy resin platforms:Thermally reversible network chemistries compatible with TBBPA reactive incorporation address end-of-life recovery mandates in the EU Circular Economy Action Plan.
- Battery energy storage systems:Utility-scale BESS installations in the United States and Germany are specifying fire-resistant encapsulation systems that leverage brominated epoxy formulations for thermal barrier performance.
Industry Challenges
- REACH authorization dossier preparation:The technical and toxicological data compilation required for continued TBBPA use in European electrical applications demands specialized regulatory affairs capabilities that mid-size compounders struggle to resource.
- Legacy equipment revalidation:Laminators operating continuous press lines face production interruption risks when transitioning between certified and standard TBBPA grades due to resin rheology variations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tetrabromobisphenol a (TBBPA) Market |
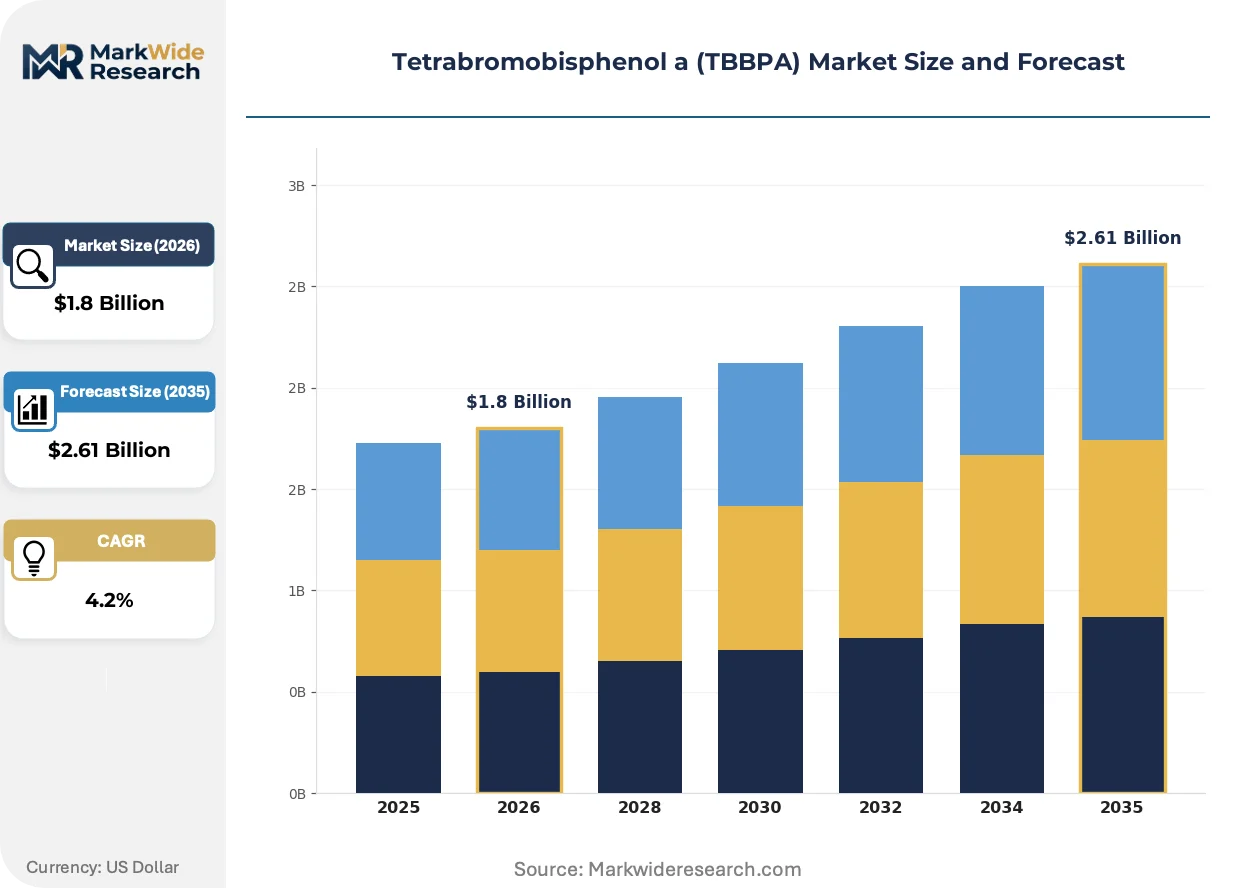
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.61 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flame Retardant, Additive, Catalyst, Intermediate End Use Industry: Electrical & Electronics, Automotive, Building & Construction, Textiles Sales Channel: Direct Sales, Distributors, Online Retail, Wholesalers Application: Polymer Blends, Coatings, Resins, Adhesives |
| Companies Covered | Albemarle Corporation, ICL, Jordan Bromine Company, LANXESS, Kingboard Holdings Limited, Shandong Brother Sci. & Tech. Co., Ltd., Shandong Futong Chemical Co., Ltd., Tianjin Changlu Hangu Saltern Co., Ltd., Shandong Moris, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tetrabromobisphenol a (TBBPA) Market Emerging Trajectories
Formulation chemistry and regulatory compliance protocols are diverging across jurisdictions, forcing producers to maintain multiple product qualification tracks while advancing reactive processing technologies for next-generation laminates.
High-purity TBBPA grades with controlled hydrolyzable bromine content are expanding into aerospace and medical electronics laminates where outgassing specifications are tightening. Tier-one PCB fabricators in Japan and Germany are qualifying these materials for satellite and implantable device substrates. This purity tier is expanding into premium market segments previously served by alternative chemistries, compressing the addressable market for standard industrial grades.
ECHA's 2024 update to substance evaluation priorities places enhanced scrutiny on brominated flame retardants in articles, accelerating substitution assessments among European OEMs. Laminators serving automotive and industrial control markets are preemptively diversifying formulation portfolios to reduce authorization risk exposure. The electrical laminate segment is responding by accelerating alternative qualification timelines while maintaining TBBPA lines for export markets with divergent regulatory timelines.
Specification-driven procurement now dominates flame retardant selection for EV battery enclosures, with OEM technical service teams embedding directly at compounder R&D facilities. Direct engagement between laminators and bromine suppliers is displacing traditional distributor channels for high-volume, certified-grade contracts. This pattern is most visible in Germany and South Korea where battery pack integrators enforce vertical traceability from raw material to finished enclosure.
Tetrabromobisphenol a (TBBPA) Market Segmentation
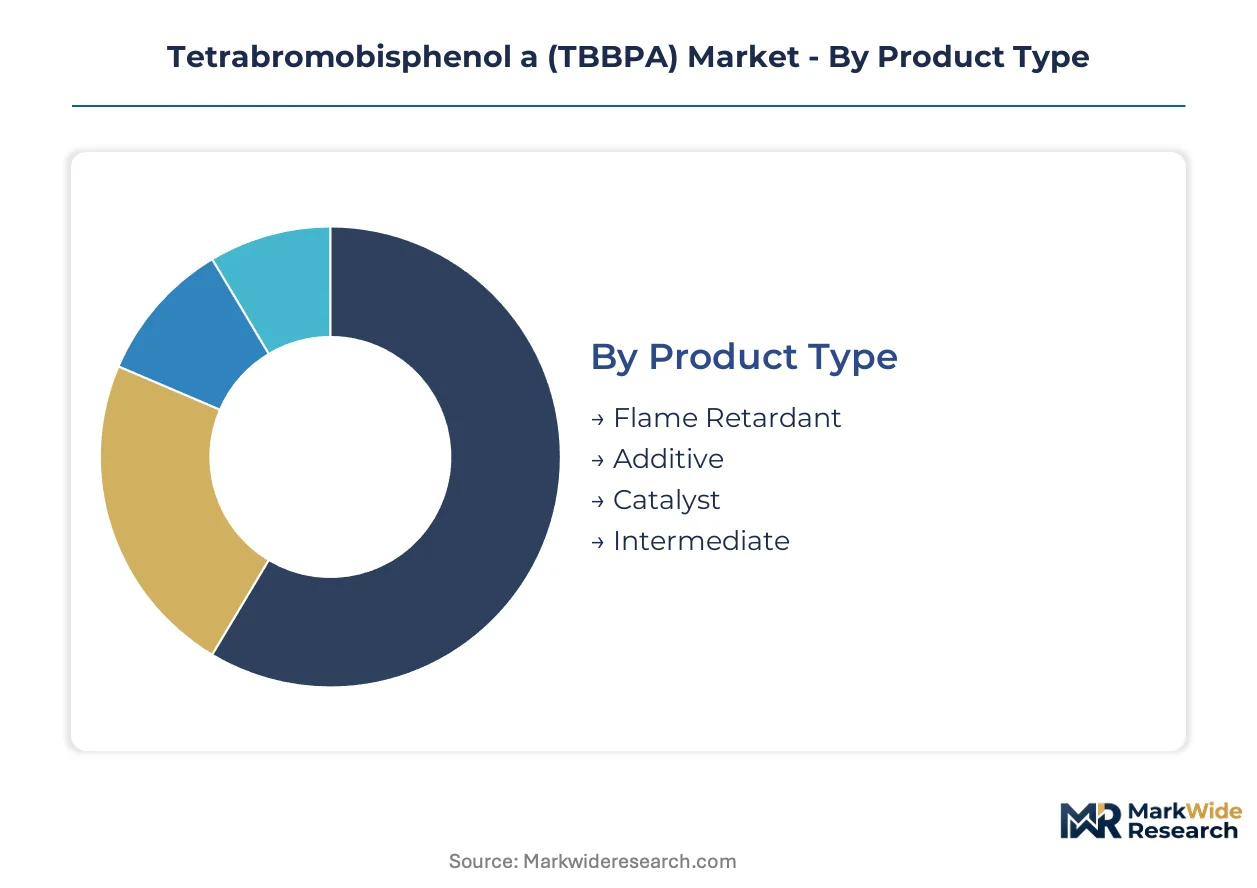
TBBPA segmentation reveals how formulation chemistry, procurement channels, and end-use specifications fragment demand across distinct value pools. Each dimension carries divergent margin profiles and regulatory exposure, forcing producers to prioritize capacity allocation across incompatible certification requirements.
Product Type:
Upgrade cycles in epoxy laminate manufacturing are pushing compounders toward higher-specification grades that reduce hydrolyzable bromine content for sensitive electronics applications.
- Flame Retardant:Reactive incorporation into epoxy resin backbones for printed circuit board laminates dominates volume flows. Multilayer PCB fabricators in China and Taiwan specify this grade for 5G infrastructure and automotive control modules where thermal performance thresholds are tightening.
- Additive:Physical blending into thermoplastic matrices serves polymer compounders seeking lower-cost fire protection for consumer electronics housings. Specification pressure from OEMs in Germany and South Korea is narrowing the addressable market to REACH-certified additive grades with full traceability documentation.
- Catalyst:Specialty epoxy curing applications in aerospace prepreg systems leverage controlled bromine release kinetics. Japanese laminators qualify these materials for satellite substrate manufacturing.
- Intermediate:Derivative synthesis feedstock for advanced brominated compounds serves pharmaceutical and agrochemical pipelines. Batch chemical producers in India source intermediate grades for captive downstream processing.
Flame Retardant sits at the top of the volume ranking, with Additive climbing the fastest as polymer blenders seek lower-load alternatives to reactive systems.
End Use Industry:
Cost tier differentiation separates specification-intensive segments where certification premiums apply from commodity applications competing on halogen loading efficiency.
- Electrical & Electronics:Circuit board laminators embed TBBPA in epoxy prepregs for multilayer PCB manufacturing. Taiwan-based fabricators serving Apple and NVIDIA supply chains enforce sub-100 ppm hydrolyzable bromine specifications that compress margins for standard-grade producers.
- Automotive:EV battery enclosure specifications are opening intumescent coating channels as thermal runaway protection mandates expand. German pack integrators require vertical traceability from bromine extraction to finished enclosure, displacing distributor relationships.
- Building & Construction:Structural insulation panels and electrical conduit applications face substitution pressure from phosphorus-nitrogen systems in EU jurisdictions. French and Italian compounders are diversifying formulations to reduce POP screening exposure.
- Textiles:Technical fabric back-coating for transportation seating represents a contracting niche as transport OEMs eliminate halogenated chemistries from interior specifications. Automotive textile laminators in Turkey and Mexico are transitioning to phosphorus-based alternatives.
Electrical & Electronics commands the steepest expansion trajectory through the forecast period, while Building & Construction faces the sharpest volume pressure from regulatory substitution mandates.
Sales Channel:
Customer type fragmentation is bifurcating procurement between high-volume direct contracts with traceability requirements and spot-market distributor purchases for uncertified applications.
- Direct Sales:Tier-one PCB fabricators and battery pack integrators negotiate multi-year supply agreements with embedded technical service support. Korean and German OEMs now require quarterly extraction-site audits as contract conditions.
- Distributors:Regional chemical distributors serve mid-size compounders lacking regulatory affairs capabilities for REACH dossier preparation. Inventory risk is shifting to distributors as authorization uncertainty extends procurement timelines.
- Online Retail:Small-batch specialty chemical platforms cater to R&D laboratories and prototype manufacturers seeking rapid qualification samples. Chinese B2B marketplaces are capturing share from traditional distributor networks for sub-tonnage orders.
- Wholesalers:Bulk commodity flows to industrial compounders in Southeast Asia and Latin America operate on price-transparent tenders with minimal specification enforcement. Brazilian and Indonesian polymer blenders dominate offtake through this channel.
Direct Sales captures the fastest volume gain as battery enclosure specifications tighten, with Wholesalers retreating to lowest-specification applications outside REACH jurisdictions.
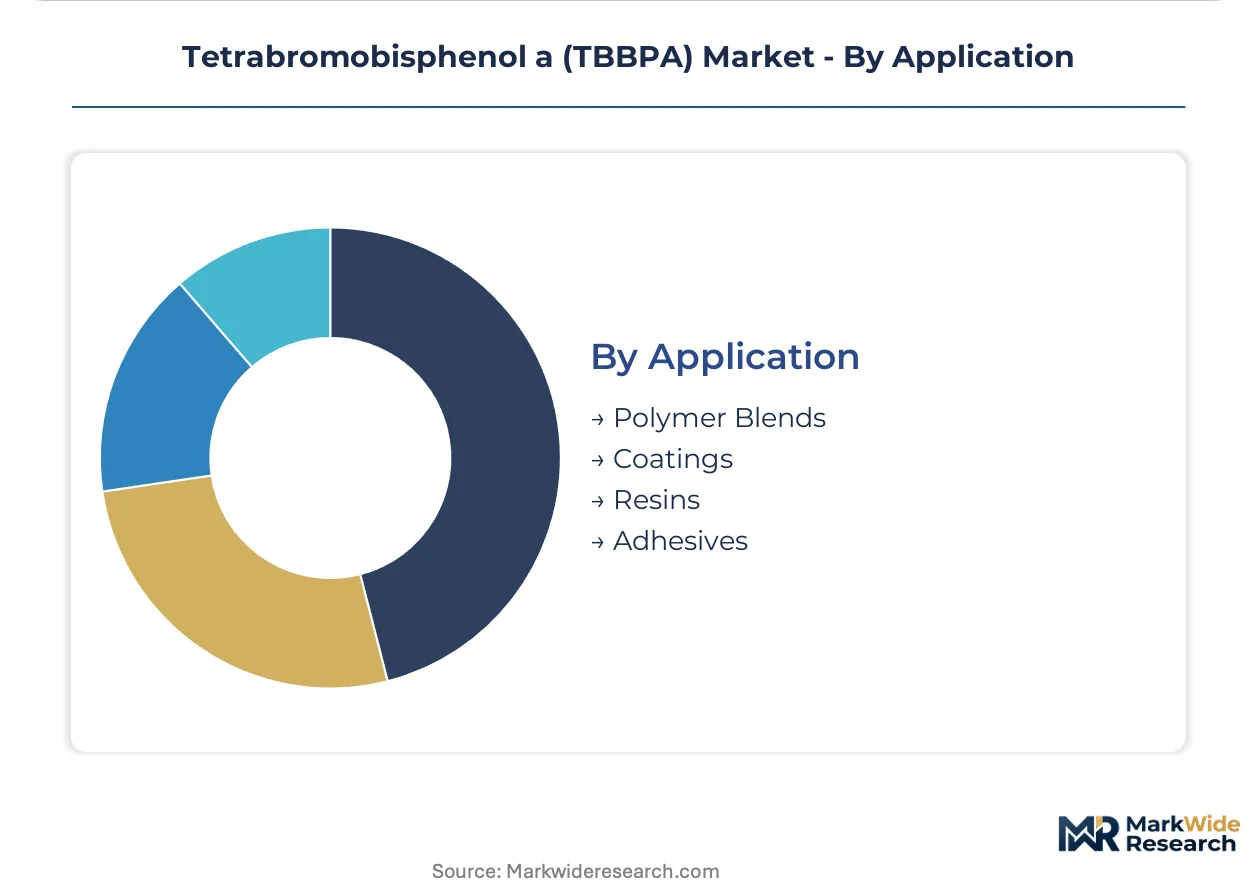
Application:
Supply concentration in Shandong province bromine extraction is shaping formulation availability across application segments with divergent purity requirements.
- Polymer Blends:Thermoplastic masterbatch incorporation serves electronics housing and connector manufacturers. Japanese compounders are qualifying high-purity grades for medical device applications previously closed to brominated chemistries.
- Coatings:Intumescent epoxy formulations for EV battery enclosures represent the steepest demand expansion. German and US battery pack integrators are embedding technical teams at compounder R&D facilities to accelerate qualification timelines.
- Resins:Reactive incorporation into epoxy backbone structures for PCB laminates remains the foundational application. Chinese laminators operating continuous press lines face production interruption risks when transitioning between certified and standard grades.
- Adhesives:Specialty bonding systems for aerospace and military electronics serve narrow specification windows. French and Israeli defense contractors enforce lot-level bromine isotope analysis for supply chain security.
Resins maintains volume leadership through PCB demand, with Coatings gaining share fastest as EV thermal protection specifications proliferate across automotive OEMs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redirecting TBBPA production toward jurisdictions with lower compliance-cost burdens. Shandong province refiners leverage integrated bromine extraction while European compounders absorb REACH authorization expenses. This divergence fragments formulation strategies across electrical laminators serving divergent export markets.
China
Shandong province salt lake operations supply over 70 percent of elemental bromine globally. MEE enforcement of dual carbon goals pressures refiners to adopt cleaner extraction processes. Kingboard Holdings and Shandong-based producers operate integrated bromine-to-TBBPA facilities serving domestic PCB fabricators.
Germany
ECHA's persistent organic pollutant screening criteria create formulation uncertainty for electrical laminators. RoHS exemptions for brominated compounds in critical electronics preserve some TBBPA demand. Battery pack integrators in Stuttgart and Munich require vertical traceability from bromine extraction to finished enclosure.
United States
EPA oversight under the Toxic Substances Control Act shapes import thresholds and domestic blending requirements. Electric vehicle battery enclosure specifications from Detroit and Austin OEMs drive intumescent coating demand. Albemarle Corporation leverages integrated bromine supply chains across North American markets.
South Korea
Seoul-based PCB fabricators serving Apple and NVIDIA supply chains enforce sub-100 ppm hydrolyzable bromine specifications. MFDS chemical substance registration adds compliance layers for imported flame retardants. Battery pack integrators embed technical teams at compounder R&D facilities for qualification acceleration.
India
PLI scheme incentives for semiconductor and PCB fabrication in Gujarat and Tamil Nadu attract laminators seeking localized supply chains. BIS standards for flame retardant specifications remain less stringent than REACH equivalents. Mumbai and Chennai distributors serve mid-size compounders lacking regulatory affairs capabilities.
Tetrabromobisphenol a (TBBPA) Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue high-purity certification for aerospace and medical electronics applications. The vendor base stratifies across integrated bromine refiners, specialized flame retardant compounders, and regional distributors serving spot-market demand. Two strategic archetypes dominate: upstream-integrated players controlling bromine extraction through finished TBBPA production, and formulation specialists qualifying certified grades for specification-intensive end uses. Capacity expansion and REACH dossier preparation represent the dominant competitive moves, with producers maintaining parallel product lines for divergent regulatory jurisdictions.
Among North American and Israeli integrated players, Albemarle Corporation and ICL exemplify the upstream-control archetype through bromine supply chain leverage. LANXESS occupies a position within the European certification-focused tier, while Shandong-based producers including Kingboard Holdings Limited represent the scale-driven Chinese supply base. Jordan Bromine Company anchors Middle Eastern bromine sourcing for regional compounders. These named entities illustrate how geographic origin and corporate structure map onto divergent strategic postures across regulatory environments.
| Leading Market Players |
|---|
| Albemarle Corporation |
| ICL |
| Jordan Bromine Company |
| LANXESS |
| Kingboard Holdings Limited |
| Shandong Brother Sci. & Tech. Co., Ltd. |
| Shandong Futong Chemical Co., Ltd. |
| Tianjin Changlu Hangu Saltern Co., Ltd. |
| Shandong Moris |
| Others |
Supply Flow & Price Mechanics
Bromine extraction specialists concentrated in Shandong province anchor labor-cost differentials that widen spreads between REACH-certified premium grades and standard industrial tiers. These workforce pools enable integrated refiners to absorb compliance investments while maintaining cost discipline across uncertified product lines.
Pricing Analysis
Distributor margin compression is intensifying as Korean and German battery pack integrators negotiate direct-to-OEM contracts with embedded technical service support. Pricing stratifies across premium, standard, and economy tiers based on hydrolyzable bromine content and REACH certification status. Cost compression in the standard grade runs through phosphorus-nitrogen substitution pressure in consumer electronics housings. Mid-size compounders lacking regulatory affairs capabilities exhibit highest price sensitivity, while tier-one PCB fabricators serving Apple supply chains prioritize specification compliance over unit cost.
Supply Chain Analysis
REACH certification gating is fragmenting supplier qualification tracks as European electrical laminators demand full traceability documentation from bromine extraction through finished TBBPA delivery. Production gravity centers on China, with secondary concentrations in Jordan and the United States serving regional compounders. Raw material flows draw from Shandong salt lake bromine, liquid chlorine feedstock, and bisphenol A monomer supplies. Single-source vulnerability in Shandong extraction exposes downstream compounders to weather-induced disruptions and provincial environmental enforcement volatility. Distribution runs through direct sales channels for high-volume certified contracts and regional distributors for spot-market uncertified purchases.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
TBBPA margin expansion hinges on purification technology investments that unlock aerospace and medical electronics premiums while standard-grade producers absorb phosphorus-nitrogen substitution pressure.
For Market Incumbents: Deploy backward integration into captive bromine extraction to defend cost position against Shandong-based competitors. Albemarle Corporation and ICL should accelerate high-purity grade capacity additions in North American and Israeli production hubs. ECHA POP screening criteria threaten authorization continuity; incumbents must maintain parallel certified and uncertified product lines to serve divergent regulatory jurisdictions without production interruption. For New Entrants and Emerging Players: Online specialty chemical platforms offer the lowest-friction route to wedge into small-batch R&D laboratory demand. India electronics manufacturing clusters in Gujarat and Tamil Nadu present the most penetrable white-space target, with PLI scheme incentives attracting laminators seeking localized supply chains outside China. Target mid-size compounders lacking REACH dossier preparation capabilities through distributor partnerships with embedded regulatory affairs support. For Investors and Strategic Acquirers: Specialty chemical conglomerates with flame retardant portfolios are the most active acquirer in this space, seeking certification capabilities and regional production footprints. Long-term viability favors targets with demonstrated REACH authorization dossier expertise and established relationships with tier-one PCB fabricators. The signal to watch is ECHA substance evaluation priority updates that could accelerate substitution timelines and compress premium-grade windows.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bromine Extraction | Albemarle Corporation leverages captive supply from Arkansas brine operations to sustain cost competitiveness. |
| REACH Certification Investment | LANXESS qualifies product lines for European polymer blenders facing ECHA persistent organic pollutant screening. |
| High-Purity Grade Capacity Expansion | Japanese laminators qualify materials for satellite substrate manufacturing with sub-100 ppm hydrolyzable bromine. |
| Long-term Supply Agreement | Korean battery pack integrators embed technical teams at compounder R&D facilities for qualification acceleration. |
| Joint Venture in India | PLI scheme incentives in Gujarat attract laminators seeking localized flame retardant supply chains. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary engagement captured plant managers at Shandong bromine refineries, procurement leads at Taiwan-based PCB fabricators, distribution channel partners serving European polymer compounders, and technical R&D directors at flame retardant formulators. Secondary validation drew from customs and trade data, ACC and Cefic industry reports, SEC 10-K filings, and ECHA substance evaluation databases. Bottom-up capacity and demand modeling triangulated against top-down macroeconomic drivers.
Segment-weighting approaches distributed volume and value projections across product type, end-use industry, application, and sales channel dimensions. The analytical framework modeled grade tier differentiation, regional production hub concentration, and certification status splits across the projection horizon. CAGRs derived from historical trajectory analysis and forward-looking regulatory scenario planning incorporated EV battery enclosure specification proliferation and phosphorus-nitrogen substitution elasticity.
The model assumes a particular technology adoption path; alternative pathways for non-halogenated flame retardant systems would alter the outlook. Forecasts reflect assumptions about REACH authorization continuity, Shandong extraction stability, and RoHS exemption durability. A model refresh is warranted upon material change in ECHA substance evaluation priorities or China's dual carbon enforcement intensity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Chemicals
UV/IR Blocker Market
Specialty Chemicals
Medical Propellants Market
Specialty Chemicals
Calcium D-Pantothenate Market
Specialty Chemicals
Fabric Softener and Conditioner Market
Specialty Chemicals
Dimethylolpropionic Acid (DMPA) Market
Specialty Chemicals
Antioxidant 412S Market
Specialty Chemicals
Insoluble Fibers Market
Specialty Chemicals
Fragrance-Release Control Agents for Long-Lasting Home Care Scents Market
Specialty Chemicals
Bismuth Oxychloride Market
Specialty Chemicals
LAMEA Metal Biocides Market
Specialty Chemicals
Demethylase Inhibitor Market
Specialty Chemicals
Global Chemical Vapor Deposition (CVD) Market
Specialty Chemicals
Cellulose Ether and Derivatives Market
Specialty Chemicals
Cyclomethicone Market
Specialty Chemicals
Global Non-Halogenated Flame Retardants Market
Specialty Chemicals
Spiroglycol Market