
 Europe Hydrocarbon Refrigerants Market | 2026-2036
Europe Hydrocarbon Refrigerants Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Hydrocarbon Refrigerants Market Intelligence
Technician certification capacity is rotating toward flammable refrigerant handling qualifications across the EU, unlocking installation throughput for hydrocarbon systems. Nidec Secop leverages its compressor technology leadership to anchor the European supply base for propane-compatible units. Arkema competes through specialized refrigerant gas formulations that meet evolving purity standards under the F-Gas framework. Linde plc sustains industrial-scale distribution networks that dominate bulk hydrocarbon supply to OEMs and service contractors.
Hydrocarbon refrigerants comprise zero-ozone-depletion, low-global-warming-potential substances—primarily propane, isobutane, and propylene—typically specified with purity thresholds exceeding 95% and formulated with moisture content below 10 ppm for thermal stability in closed-loop vapor compression cycles. These fluids serve as direct replacements for hydrofluorocarbon working fluids in commercial and residential cooling equipment where charge size limits permit flammable material use. Isobutane occupies the residential cooling segment as the dominant product type, reflecting mature supply chains and established safety protocols in small-charge domestic refrigerators. Propane leads commercial refrigeration applications where larger charge sizes align with centralized rack systems in supermarkets and food retail, while propylene differentiates within niche industrial process cooling where specific thermodynamic properties match custom engineering requirements.
The EU F-Gas Regulation mandates phased HFC quota reductions, while ECHA classifies hydrocarbon refrigerants under REACH and CLP frameworks that govern flammable substance handling, storage, and worker exposure limits. CE marking under the Pressure Equipment Directive governs system integrity for hydrocarbon-charged assemblies, creating compliance thresholds that filter market access for equipment manufacturers and service providers. Stakeholders must monitor the trajectory of charge size limit revisions under EN 378 and IEC 60335-2-89 standards, as these technical boundaries will determine addressable market scope across application categories.
Market Dynamics
The EU F-Gas Regulation phase-down is compressing HFC supply quotas and forcing cold chain operators to re-engineer equipment architectures around flammable refrigerant compatibility. This regulatory compression is redrawing competitive boundaries across compressor manufacturing, technician certification infrastructure, and distribution network configuration.
Growth Catalysts
- EU F-Gas Regulation phase-down:Mandated HFC quota reductions are eliminating synthetic refrigerant alternatives and redirecting capital expenditure toward hydrocarbon-compatible system designs across commercial refrigeration.
- Propane rack systems:Centralized supermarket refrigeration architectures are scaling charge-optimized propane deployments that match cooling load density with flammability risk mitigation protocols.
- Benelux corridor concentration:Cold chain logistics density across Belgium, Netherlands, and Luxembourg is creating installation volume that amortizes technician certification costs and accelerates service ecosystem maturity.
Market Restraints
- Charge size limitations:EN 378 and IEC 60335-2-89 standards cap permissible refrigerant quantities per circuit, restricting hydrocarbon viability in large industrial process cooling applications.
- Technician certification scarcity:Flammable refrigerant handling qualifications remain concentrated in Germany and France, creating installation bottlenecks in Southern and Eastern Europe.
- Steel and aluminum input volatility:Pressure vessel and heat exchanger material costs fluctuate with energy-intensive metal production cycles, compressing margin predictability for OEMs.
Strategic Opportunities
- Poland and Czech Republic cold chain expansion:Underpenetrated Eastern European markets present first-mover advantages for hydrocarbon system deployment as F-Gas compliance deadlines approach.
- Heat pump convergence:Propane-based residential heating systems are converging with cooling applications, opening cross-seasonal equipment utilization models for compressor manufacturers.
- CE marking streamlining:Pressure Equipment Directive harmonization is reducing multi-national certification redundancy, lowering market access friction for equipment suppliers.
Industry Challenges
- Flammable refrigerant technician pipeline:Vocational training capacity lags equipment deployment velocity, particularly in markets where HFC service infrastructure dominates contractor relationships.
- Retrofit integration complexity:Legacy HFC system architectures require complete circuit replacement rather than drop-in refrigerant substitution, extending payback periods for end-users.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Hydrocarbon Refrigerants Market |
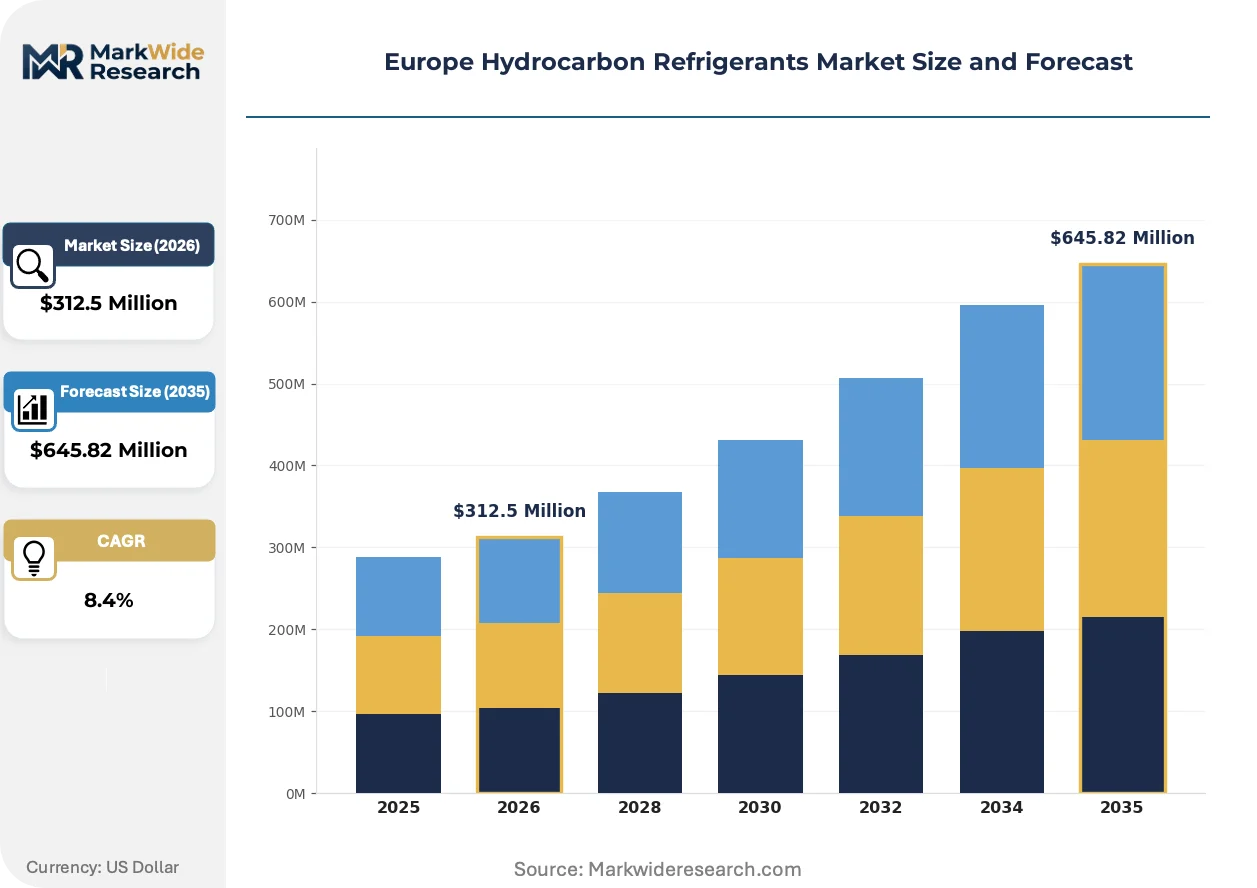
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $645.82 Million |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Propane, Isobutane, Butane, Propylene Application: Commercial Refrigeration, Residential Cooling, Industrial Cooling, Automotive Air Conditioning End User: Retail, Food Processing, Automotive, HVAC Technology: Direct Expansion, Cascade, Secondary Loop, Vapour Compression |
| Companies Covered | Nidec Secop, Arkema, Linde plc, Harp International, Air Liquide, A-Gas International Limited, Beijer REF, Tazzetti Group, SRS Frigadon, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Hydrocarbon Refrigerants Market Strategic Shifts & Innovations
Equipment miniaturization and charge optimization are converging with regulatory pressure to reshape how hydrocarbon systems achieve thermal performance within flammability constraints. Three forces are reconfiguring competitive positioning.
Micro-channel heat exchanger technology is miniaturizing refrigerant charge requirements while maintaining heat transfer coefficients. Supermarket refrigeration OEMs are adopting these architectures to compress propane quantities below EN 378 thresholds. The technology is enabling larger system capacities within regulatory charge limits.
ECHA classification updates under REACH and CLP frameworks are tightening storage and transport documentation for hydrocarbon refrigerants. Industrial gas distributors must reconfigure warehouse segregation protocols and labeling systems. Bulk supply chains in Northern Italy and Northern Germany are investing in dedicated flammable substance handling infrastructure.
End-users are compressing equipment replacement cycles as F-Gas quota prices escalate HFC service costs. Food retail chains are unbundling after-sales service contracts from equipment procurement, selecting specialized hydrocarbon service providers. This pattern concentrates in France and Germany where technician certification density supports competitive service markets.
Europe Hydrocarbon Refrigerants Market Segmentation
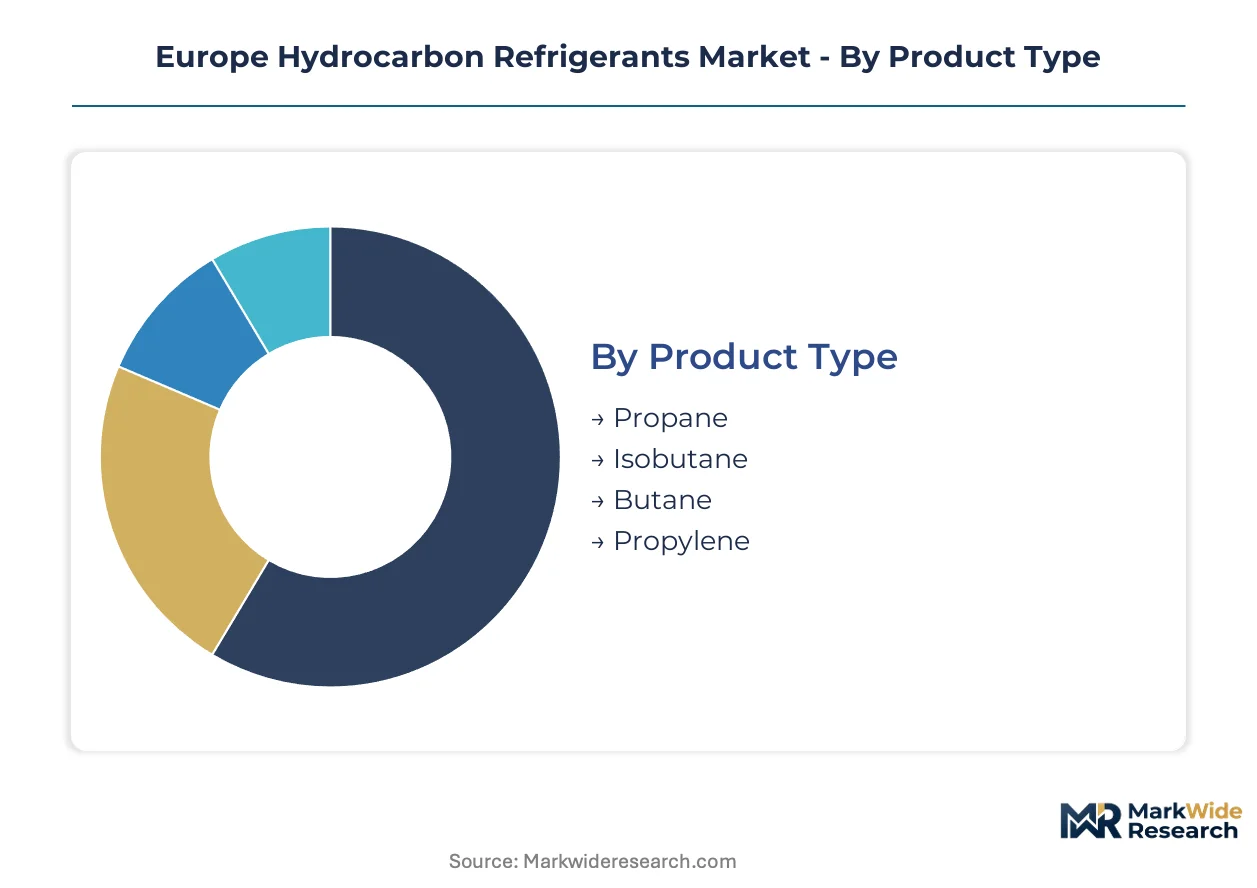
Segmentation in the Europe Hydrocarbon Refrigerants Market reveals how regulatory pressure and application-specific charge limits fragment demand across distinct technical and commercial channels. Equipment manufacturers configure product portfolios around flammability classifications that vary sharply between residential appliances and commercial installations.
Product Type:
Channel distribution varies by flammability grade and charge optimization requirements, with industrial gas suppliers dominating bulk propane flows while packaged isobutane moves through appliance OEM direct procurement.
- Propane:Zero-ozone-depletion refrigerant with thermodynamic properties matching R-404A performance in low-temperature applications. Supermarket rack systems across Germany and France concentrate demand as F-Gas quota prices escalate HFC service costs.
- Isobutane:Saturated hydrocarbon specified at purity thresholds exceeding 95% with moisture content below 10 ppm. Domestic refrigerator manufacturers in Italy and Poland anchor volume, leveraging mature safety protocols for small-charge hermetic compressors.
- Butane:Blending component for custom refrigerant formulations addressing specific glide requirements in industrial process cooling.
- Propylene:Unsaturated hydrocarbon with distinct thermodynamic profile for niche industrial applications requiring precise temperature control.
Isobutane dominates installed base. Propane is where expansion concentrates.
Application:
Cost tier differentiation separates premium-specified commercial systems from standardized residential units, with charge size limits acting as the primary price discrimination mechanism.
- Commercial Refrigeration:Centralized rack architectures and distributed display cases across food retail chains. The Benelux corridor generates installation density that amortizes technician certification investments.
- Residential Cooling:Small-charge hermetic systems governed by IEC 60335-2-89 safety standards. Northern Italian appliance clusters source isobutane through established supply contracts.
- Industrial Cooling:Custom-engineered process cooling with propylene and propane blends. Charge size restrictions under EN 378 limit addressable market scope.
- Automotive Air Conditioning:Limited penetration due to mobile application safety protocols and alternative refrigerant competition.
Commercial Refrigeration commands premium pricing tiers. Residential Cooling maintains volume leadership.
End User:
Customer type fragmentation reflects divergent procurement sophistication, with multinational food retail chains driving standardization while regional HVAC contractors negotiate spot supply terms.
- Retail:Supermarket and convenience store operators with centralized procurement functions. French and German chains unbundle service contracts to access certified hydrocarbon technicians.
- Food Processing:Cold storage and blast freezing operations with continuous cooling requirements. Poland and Czech Republic expansion projects create first-mover opportunities.
- Automotive:Vehicle manufacturers and aftermarket service networks with limited current uptake.
- HVAC:Building services contractors navigating charge limits for heat pump convergence applications.
Retail concentrates procurement leverage. Food Processing is climbing the fastest.
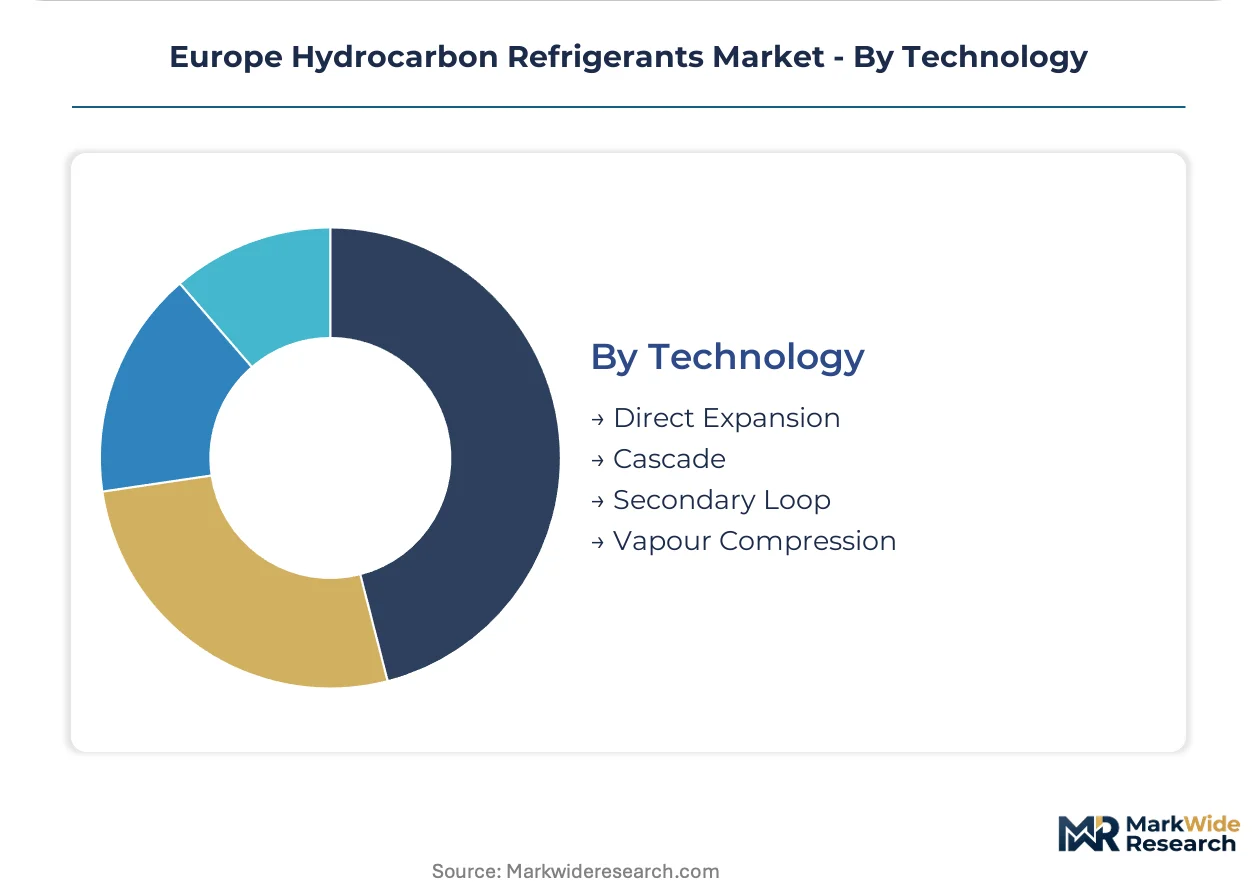
Technology:
Supply concentration in compressor manufacturing favors direct expansion architectures, while secondary loop systems require specialized engineering capabilities concentrated in Germany.
- Direct Expansion:Standard vapor compression cycle with refrigerant evaporation directly in heat exchangers. Secop and other compressor OEMs optimize units for propane charge limits.
- Cascade:Staged refrigeration systems isolating hydrocarbon circuits from CO2 or HFC lower stages. Industrial applications in Northern Italy adopt this architecture.
- Secondary Loop:Glycol or salt brine distribution reducing refrigerant inventory in occupied spaces. High installation complexity limits contractor availability.
- Vapour Compression:Fundamental thermodynamic cycle underlying all hydrocarbon system designs.
Direct Expansion dominates equipment shipments. Cascade systems are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany deploys hydrocarbon refrigerants predominantly in centralized supermarket rack systems, while Italy channels isobutane into domestic appliance manufacturing and France prioritizes cold chain logistics networks. This consumption-mix differential reflects divergent industrial specializations and regulatory enforcement timelines across the region.
Germany
Supermarket operators in Bavaria and North Rhine-Westphalia are retrofitting centralized refrigeration racks with propane-based architectures. The Federal Environment Agency enforces strict F-Gas quota compliance timelines that accelerate equipment replacement cycles. The Cologne-Düsseldorf corridor concentrates technician certification programs that service cross-border installations into the Benelux region.
France
Food retail chains unbundle service contracts to access certified hydrocarbon technicians in the Île-de-France and Auvergne-Rhône-Alpes regions. ANSM oversees workplace safety protocols for flammable substance handling under transposed CLP frameworks. Lyon hosts specialized training institutes that supply qualified installers to cold storage operations across the Rhône corridor.
Italy
Domestic refrigerator manufacturers in Lombardy and Veneto anchor isobutane demand through established supply contracts with compressor OEMs. The Ministry of Environment coordinates F-Gas phase-down implementation with regional industrial associations. The Milan-Bergamo industrial cluster sustains mature safety protocols for small-charge hermetic systems.
Netherlands
Cold chain logistics density across the Randstad generates installation volume that amortizes technician certification investments for propane rack systems. The Human Environment and Transport Inspectorate monitors transport documentation for bulk hydrocarbon distribution. Rotterdam's port infrastructure supports dedicated flammable substance handling facilities for Northern European supply chains.
Poland
Food processing and cold storage expansion projects in the Warsaw and Wrocław metropolitan areas create first-mover opportunities for hydrocarbon system deployment. The Chief Inspectorate of Environmental Protection enforces EU F-Gas transposition with accelerating compliance deadlines. Silesian industrial zones attract equipment suppliers establishing Eastern European service footprints.
Europe Hydrocarbon Refrigerants Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier, with compressor manufacturers and industrial gas distributors commanding distinct value chain positions. The upper tier consolidates around technology ownership and bulk supply infrastructure, while mid-tier players compete on regional service density and certification proximity. Two archetypes dominate: integrated compressor-technology providers and industrial-scale refrigerant distributors. Competitive moves center on technician training network expansion and charge-optimized equipment platform development.
Within the integrated technology tier, Nidec Secop anchors European compressor supply for propane-compatible units, while Arkema represents specialized refrigerant formulation capabilities under evolving purity standards. Linde plc exemplifies industrial-scale distribution architecture, sustaining bulk hydrocarbon flows to OEMs and service contractors across Northern Europe. These three entities occupy positions that bridge equipment manufacturing, chemical supply, and logistics infrastructure.
| Leading Market Players |
|---|
| Nidec Secop |
| Arkema |
| Linde plc |
| Harp International |
| Air Liquide |
| A-Gas International Limited |
| Beijer REF |
| Tazzetti Group |
| SRS Frigadon |
| Others |
Cost & Logistics Intelligence
Compressor manufacturing scale economies in Germany and Northern Italy concentrate production capacity among three dominant OEMs, creating price floors that smaller fabricators cannot breach while anchoring long-term contract structures for bulk refrigerant procurement.
Pricing Analysis
Long-term offtake agreements dominate propane supply contracts between industrial gas distributors and supermarket refrigeration OEMs, while spot market purchases serve regional HVAC contractors with irregular demand patterns. Three-tier pricing structure across premium, standard, and economy levels separates CE-marked certified installations from uncertified service work and commodity refrigerant supply. Cost compression in standard-tier equipment is intensifying because steel and aluminum input volatility squeezes pressure vessel margins. Regional food retail chains exhibit highest price sensitivity, whereas multinational cold chain operators prioritize technician certification proximity over unit economics.
Supply Chain Analysis
Just-in-time inventory strategies prevail among domestic refrigerator manufacturers in Lombardy and Veneto, while strategic stockpiling characterizes bulk propane handling at Rotterdam port facilities serving Northern European supermarket operators. Supply concentration rests on Germany, Italy, and the Netherlands for compressor manufacturing, refrigerant formulation, and port logistics respectively. Raw material dependencies center on high-purity hydrocarbon feedstocks, hermetic compressor castings, and micro-channel aluminum heat exchanger tubing. Single-source vulnerability concentrates in specialized flammable refrigerant compressor production. Distribution runs through industrial gas distributors with dedicated flammable substance handling certifications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Europe's hydrocarbon refrigerants market sits in early-cycle expansion as F-Gas quota compression accelerates equipment replacement timelines across food retail and cold storage infrastructure.
For Market Incumbents: Fortify technician certification network density in Poland and Czech Republic before compliance deadlines concentrate demand. Expand backward integration into high-purity hydrocarbon blending capabilities to capture margin from refrigerant formulation. Compressor OEMs face emerging threat from heat pump convergence applications diverting engineering resources.
For New Entrants and Emerging Players: Lead with specialized service contracts for flammable refrigerant maintenance in underpenetrated Eastern European markets. Food processing cold storage in Silesian industrial zones offers most penetrable entry point. Develop partnerships with established compressor distributors to bypass certification infrastructure gaps.
For Investors and Strategic Acquirers: Regional refrigerant distributors with captive flammable substance handling infrastructure represent priority acquisition targets for platform consolidation. Long-term viability hinges on charge size limit revisions under EN 378 expanding addressable market scope. Watch ECHA classification updates for storage regulation tightening that favors scaled distributors over fragmented service networks.
| Strategic Initiative | Industry Significance |
|---|---|
| Technician Certification Network Expansion | Unlocks installation throughput in Poland and Czech Republic where qualified labor remains scarce. |
| Backward Integration into Hydrocarbon Blending | Captures margin from refrigerant formulation under tightening ECHA purity standards. |
| Micro-Channel Heat Exchanger Platform Development | Enables larger system capacities within EN 378 charge limits for supermarket rack systems. |
| Long-Term Service Contract Unbundling | Separates equipment procurement from aftermarket maintenance, opening specialized hydrocarbon technician markets. |
| CE Marking Harmonization Investment | Reduces multi-national certification redundancy under Pressure Equipment Directive convergence. |
Research Approach
Two parallel data streams informed the analysis: structured primary interviews with compressor OEM technical directors, industrial gas procurement leads, supermarket refrigeration maintenance heads, and ECHA regulatory affairs specialists; and secondary validation through EU F-Gas Regulation implementation reports, SEC filings of listed refrigerant distributors, customs trade data for hydrocarbon refrigerant flows, and CE marking notification databases. Bottom-up equipment shipment triangulation against top-down refrigerant consumption estimates anchored volume figures.
Across the analysis window, forecasts applied segmented growth rate derivation by product type, application tier, end-user category, and national regulatory enforcement timeline. CAGRs emerged from equipment replacement cycle modeling, F-Gas quota price elasticity assumptions, and technician certification pipeline projections. Charge size limit scenarios under IEC 60335-2-89 revision consultations shaped upside and downside cases.
The analysis sits within stated boundaries; outcomes outside sustained F-Gas enforcement intensity or accelerated charge limit relaxation would require recalibration. Forecasts assume ECHA storage classification stability and uninterrupted bulk propane supply through Rotterdam and Hamburg port infrastructure. Revision becomes warranted when technician certification velocity crosses thresholds that eliminate installation bottlenecks.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Chemicals
Non-PVC Waterstop Market
Industrial Chemicals
Global Continuous Stirred Tank Reactors Market
Industrial Chemicals
Emulsion Explosive Market
Industrial Chemicals
Food Grade Grease Market
Industrial Chemicals
Ethoxy Propanol Market
Industrial Chemicals
Aminic Antioxidants Market
Industrial Chemicals
Metalworking Treating Fluid Market
Industrial Chemicals
Bio Derived Enzymes for Detergents Market
Industrial Chemicals
Industrial Grade Urea Market
Industrial Chemicals
North America Paper Machine Oil Market
Industrial Chemicals
Backing Material Market
Industrial Chemicals
Swimming Pool Salt Chlorinator Market
Industrial Chemicals
Lithium Hexafluorophosphate Market
Industrial Chemicals
Global Dodecanedioic Acid Market
Industrial Chemicals
Diesel Exhaust Fluid Market
Industrial Chemicals
Global Acid Proof Lining Market