
 Global Cleaner and Degreaser Aftermarket Market | 2026-2036
Global Cleaner and Degreaser Aftermarket Market Size, Share, and Industry Trends Forecast 2026-2036
Global Cleaner and Degreaser Aftermarket Market Foresight
The EPA National Volatile Organic Compound Emission Standards for Consumer and Commercial Products is rebalancing demand toward low-VOC and water-based formulations across North American industrial channels. BASF SE leverages its specialty chemicals portfolio to supply bio-surfactant technologies for next-generation degreasers. CRC Industries, Inc. anchors its position through deep distribution into automotive and aviation maintenance networks. 3M Company differentiates via fluorine-free cleaning chemistries that comply with evolving state-level environmental mandates.
Cleaner and degreaser aftermarket products comprise formulated chemical solutions designed to dissolve, emulsify, or mechanically remove oils, greases, carbon deposits, and particulate contaminants from metal, plastic, and composite substrates, typically operating within pH ranges of 3.0 to 13.0 depending on substrate compatibility. These formulations serve essential functions in preventive maintenance, surface preparation for coatings, and regulatory compliance across capital-intensive industries. Water-based cleaners now command the largest volume share within product type categories, while citrus-based degreasers are gaining fastest in food processing and marine applications where biodegradability requirements intensify. Industrial equipment and automotive maintenance represent the most deeply penetrated application segments, though electronics cleaning is emerging as a high-margin niche driven by precision residue standards.
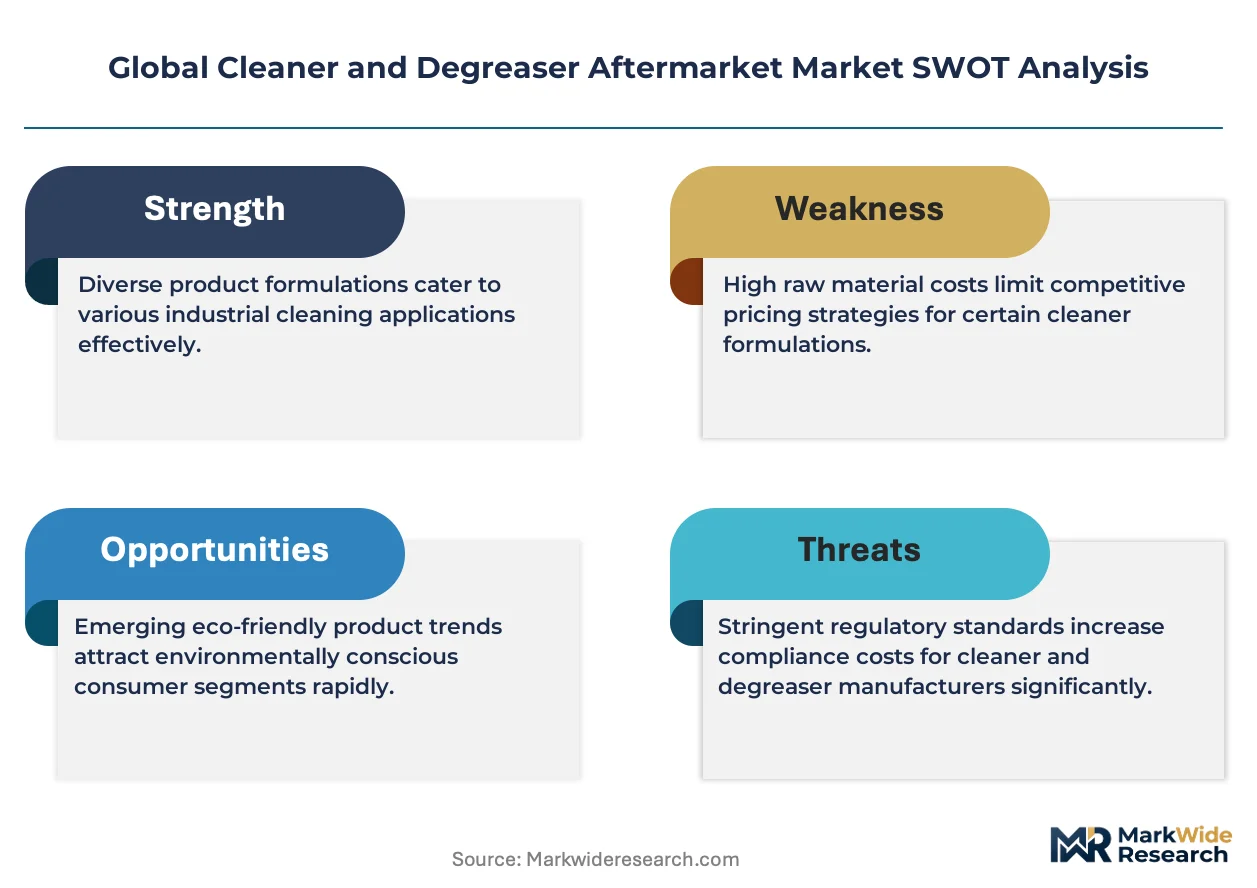
REACH restrictions on chlorinated solvents in Europe, EPA Significant New Alternatives Policy evaluations in the United States, and China's GB standards for industrial wastewater discharge collectively constrain formulation choices and accelerate substitution cycles. Compliance costs favor suppliers with integrated regulatory affairs capabilities and regional testing infrastructure. Stakeholders must monitor pending amendments to F-Gas Regulation and state-level PFAS restrictions that could disqualify incumbent chemistries without warning.
Market Dynamics
EPA VOC emission standards are compressing formulation windows for solvent-based cleaners while simultaneously expanding addressable demand for water-based and bio-surfactant alternatives across North American industrial maintenance channels.
Growth Catalysts
- REACH solvent restrictions:ECHA classification of chlorinated hydrocarbons as substances of very high concern is accelerating substitution demand for aqueous and semi-aqueous cleaning systems in European metal fabrication.
- Aviation MRO expansion:Fleet renewal cycles and extended maintenance intervals for narrow-body aircraft are amplifying consumption of precision degreasers in turbine engine overhaul facilities.
- GB wastewater standards:China's Ministry of Ecology and Environment discharge limits for industrial effluent are compelling manufacturing plants to adopt closed-loop cleaning systems with recyclable chemistries.
Market Restraints
- Feedstock volatility:D-limonene and citrus terpene supply fluctuations from Brazilian and Florida agricultural regions create margin compression for bio-based degreaser manufacturers.
- Specialty surfactant concentration:Global production of ethoxylated alcohols and alkyl polyglucosides clusters among a limited supplier base in Germany and the United States, exposing formulators to allocation risk.
- Technical performance gaps:Water-based systems face persistent limitations in removing heavy carbonized deposits and synthetic lubricants without extended soak times or mechanical agitation.
Strategic Opportunities
- India industrial corridor penetration:Automotive and textile clusters in Gujarat and Tamil Nadu remain underserved by formulated maintenance chemical distributors, creating first-mover positioning for technical service-oriented suppliers.
- Electronics precision cleaning:Semiconductor packaging and PCB assembly operations are generating demand for ultra-low residue formulations compatible with ionic contamination testing protocols.
- F-Gas Regulation phase-down:The European Union's accelerated hydrofluorocarbon quota reductions are disqualifying solvent-based vapor degreasing equipment, opening conversion revenue for aqueous system providers.
Industry Challenges
- Formulation chemist scarcity:The specialized knowledge required to balance surfactant synergy, corrosion inhibition, and regulatory compliance across multiple jurisdictions is concentrating among an aging workforce in Western Europe and North America.
- Multi-jurisdiction registration timelines:Obtaining EPA Safer Choice, EU Ecolabel, and Nordic Swan concurrent certification extends product launch cycles and strains regional regulatory affairs capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Cleaner and Degreaser Aftermarket Market |
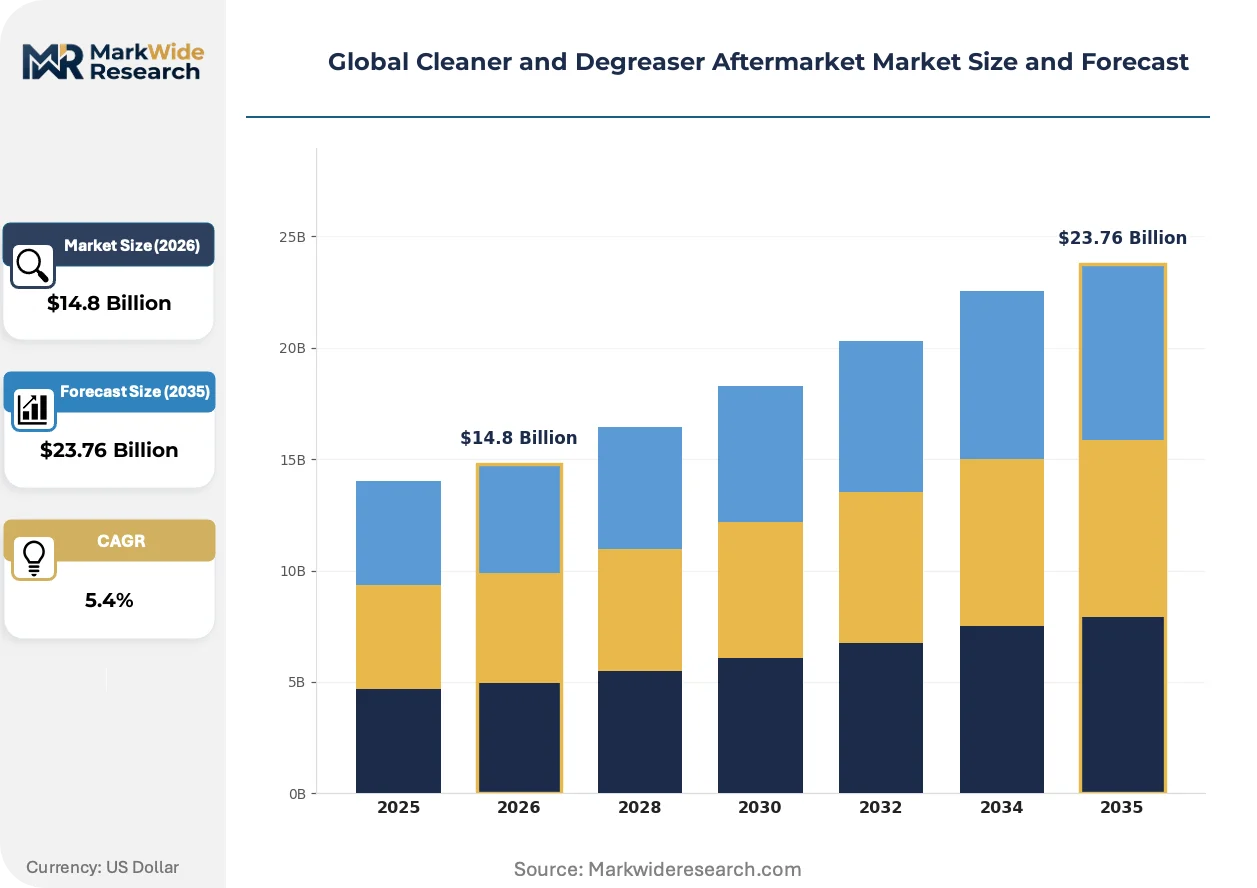
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $23.76 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Solvent-Based Cleaners, Water-Based Cleaners, Citrus-Based Degreasers, Detergent Cleaners, Abrasive Cleaners, Enzymatic Cleaners Application: Industrial Equipment, Metal Surface Preparation, Automotive Maintenance, Food Processing, Marine Cleaning, Electronics Cleaning End User Industry: Manufacturing Plants, Vehicle Repair Shops, Food & Beverage Processing Units, Shipyards, Electronics Assembly Plants, Facility Management Distribution Channel: Direct Sales, Retail Stores, E-Commerce Platforms, Wholesalers, Distributors, Specialty Dealers |
| Companies Covered | WD-40 Company, CRC Industries, Inc., Zep, Inc., BASF SE, The Clorox Company, 3M Company, RSC Brands, Kafko International Ltd., DuPont de Nemours, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Cleaner and Degreaser Aftermarket Market Shifts & Advancements
Formulation science is converging with digital monitoring systems to enable predictive maintenance scheduling and chemistry optimization, compressing the traditional separation between chemical supply and equipment service.
Micro-emulsion technology is unifying the cleaning performance of solvent-based systems with the safety and disposal advantages of water-based formulations. Automotive transmission rebuilders and hydraulic equipment servicers are adopting these systems at accelerating rates. The technology is unifying what were previously distinct product categories into single-tank process solutions, reducing capital footprint for maintenance workshops.
The F-Gas Regulation's stepped phase-down of hydrofluorocarbon quotas is forcing industrial users to retire vapor degreasing equipment ahead of depreciation schedules. Metal stamping and aerospace component manufacturers face capital decisions between aqueous conversion and emerging modified alcohol systems. German and Italian equipment suppliers are capturing this replacement cycle with integrated process guarantees.
Maintenance departments are consolidating chemical procurement through integrated supply contracts that bundle inventory management, waste handling, and technical training. Automotive dealership groups and multi-site fleet operators are displacing traditional distributor relationships with direct manufacturer partnerships. This concentration is most visible in the United States, where national account structures now govern specification decisions previously made at individual facility level.
Global Cleaner and Degreaser Aftermarket Market Segmentation
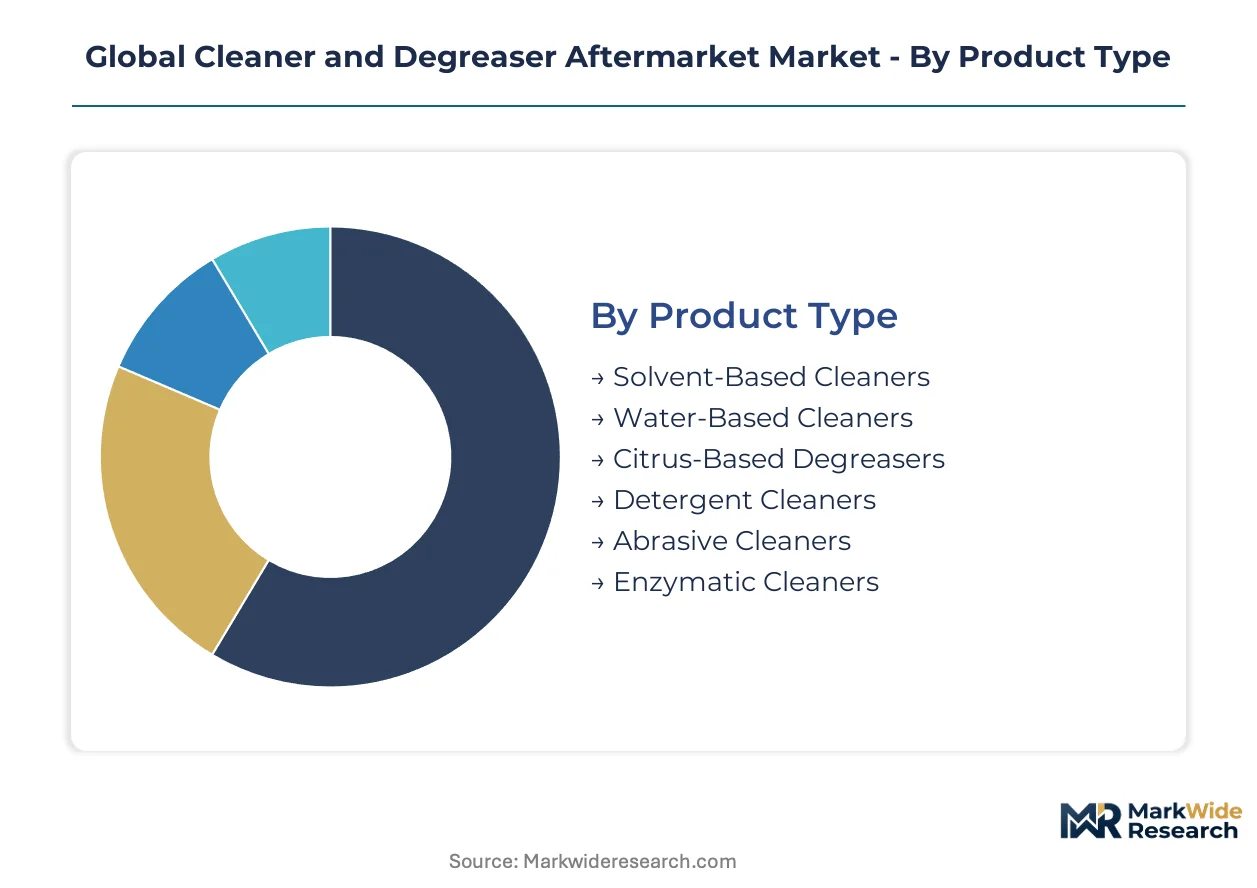
Formulation chemistry and application environment dictate product selection across this aftermarket, with regulatory pressure and substrate compatibility creating sharp segment boundaries. Procurement patterns diverge between capital-intensive industrial users seeking process guarantees and fragmented maintenance channels prioritizing shelf availability.
Product Type:
Water-based formulations command volume leadership while citrus-based systems capture premium expansion in regulated environments.
- Water-Based Cleaners:These formulations employ surfactant packages, corrosion inhibitors, and pH buffers within aqueous carriers to dissolve oils and particulates without volatile organic compound emissions. Manufacturing plants in Germany and China's industrial corridors specify these systems to comply with tightening effluent discharge mandates from MEE and ECHA. EPA VOC regulations in the United States continue compressing solvent alternatives, positioning water-based chemistries as the default specification for open-surface cleaning operations.
- Citrus-Based Degreasers:D-limonene and terpene extracts deliver solvent-strength cleaning performance with biodegradability profiles suitable for food processing and marine applications. Shipyards in Brazil and seafood processing facilities in the Pacific Northwest specify these formulations where wastewater toxicity restrictions apply. Supply concentration in Florida and São Paulo agricultural regions creates periodic allocation risk during harvest disruptions.
- Solvent-Based Cleaners:Chlorinated and hydrocarbon solvents retain niche demand for heavy carbonized deposit removal where aqueous systems require excessive dwell times.
- Detergent Cleaners:Synthetic surfactant blends serve general-purpose maintenance across facility management and light industrial applications with moderate soil loads.
- Abrasive Cleaners:Mineral or polymer particulate suspensions address rust removal and surface profiling requirements in metal fabrication preprocessing.
- Enzymatic Cleaners:Protease and lipase formulations target organic residue in food processing equipment where thermal sanitization cycles follow cleaning protocols.
Today's leader: Water-Based Cleaners. Tomorrow's challenger: Citrus-Based Degreasers.
Application:
Industrial equipment maintenance generates recurring volume while electronics cleaning commands specification premiums.
- Industrial Equipment:Preventive maintenance of pumps, compressors, and hydraulic systems drives steady consumption of heavy-duty degreasers across capital-intensive operations. Metal fabrication facilities in Germany and automotive stamping plants in the United States specify alkaline cleaners for weekly maintenance schedules. REACH restrictions on chlorinated solvents have accelerated aqueous system conversions across European metalworking.
- Electronics Cleaning:Precision removal of flux residues, particulates, and ionic contaminants from PCBs and semiconductor packages demands ultra-low residue formulations with controlled evaporation profiles. Assembly plants in South Korea and Taiwan specify these chemistries for ionic contamination testing compliance. The F-Gas Regulation phase-down is disqualifying solvent vapor degreasing equipment, opening conversion opportunities for aqueous precision systems.
- Automotive Maintenance:Transmission rebuilders and fleet service bays consume multi-purpose degreasers for engine compartment and undercarriage cleaning.
- Metal Surface Preparation:Pretreatment cleaning for coating adhesion requires controlled etching and residue-free substrates in aerospace and appliance manufacturing.
- Food Processing:USDA and FDA-compliant cleaners address grease accumulation on processing machinery with approved incidental food contact ratings.
- Marine Cleaning:Bilge degreasing and deck maintenance in commercial shipping faces MARPOL discharge constraints favoring biodegradable formulations.
Industrial Equipment anchors current procurement volumes. Electronics Cleaning offers the steepest expansion trajectory.
End User Industry:
Manufacturing scale determines contract structure, with vehicle repair shops driving spot purchase velocity.
- Manufacturing Plants:Integrated production facilities specify cleaners through centralized procurement with technical service attachments. Automotive OEM plants in Germany and electronics contract manufacturers in China negotiate multi-year supply agreements bundling chemistry, equipment, and waste handling. GB wastewater standards from China's MEE compel closed-loop system investments with chemistry optimization services.
- Vehicle Repair Shops:Fragmented automotive maintenance channels purchase through distributors and retail with price-sensitive brand switching. Independent garages in the United States and Brazil select products based on immediate availability and familiar packaging rather than technical specifications. National account consolidation among dealership groups is displacing traditional distributor relationships.
- Food & Beverage Processing Units:Dairy, meat, and beverage plants require NSF-registered cleaners with validated sanitation protocols.
- Shipyards:Commercial vessel construction and repair operations face coastal discharge restrictions driving biodegradable specification.
- Electronics Assembly Plants:Semiconductor packaging and PCB manufacturing demand ionic contamination control with documented cleanliness validation.
- Facility Management:Commercial building maintenance contracts specify general-purpose cleaners for HVAC, flooring, and common area upkeep.
Manufacturing Plants dominate contract value. Vehicle Repair Shops generate transaction frequency.
Distribution Channel:
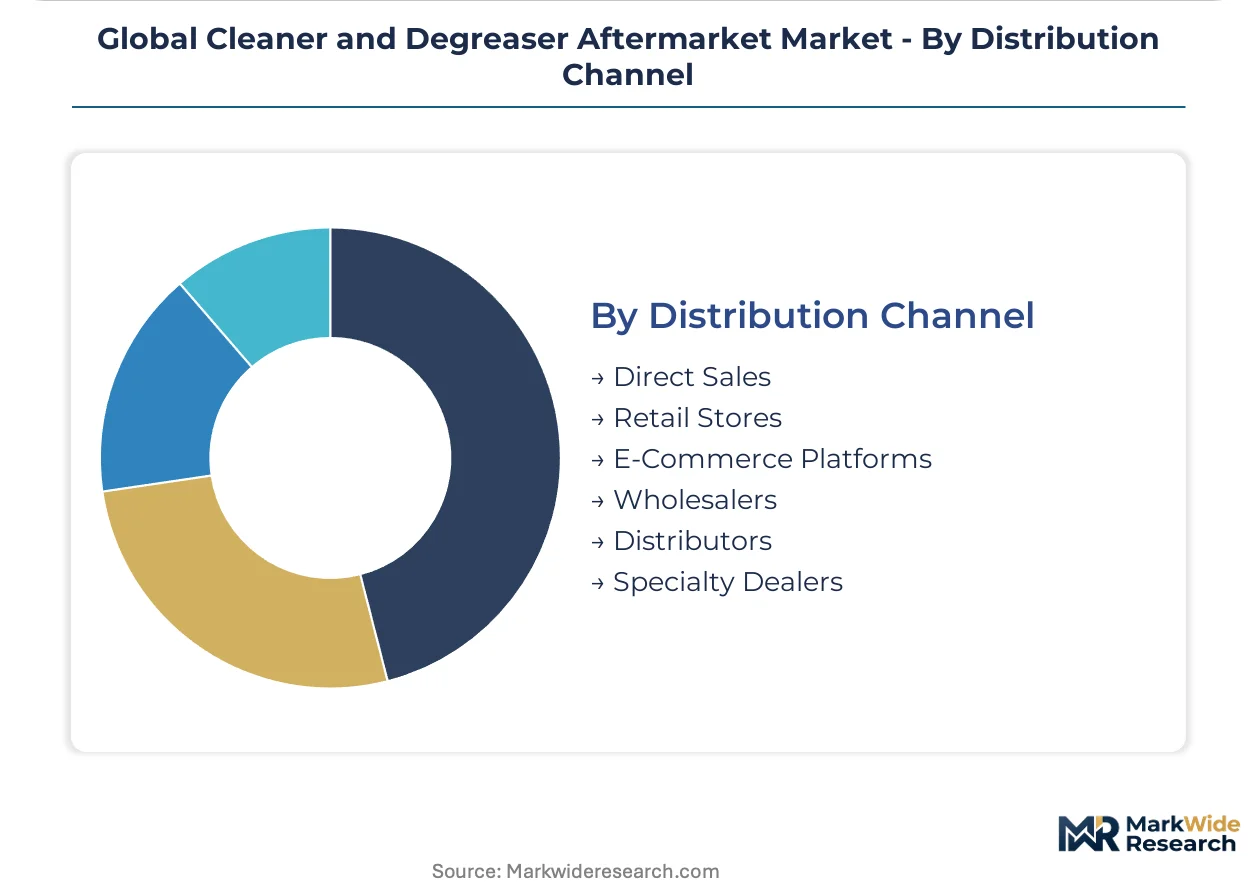
Direct manufacturer relationships are consolidating specification authority while e-commerce captures fragmented spot demand.
- Direct Sales:National account teams from BASF SE, CRC Industries, and 3M Company negotiate integrated supply contracts with automotive dealership groups and multi-site manufacturers. These arrangements bundle inventory management, technical training, and waste compliance documentation. The United States shows the most advanced concentration, with specification decisions migrating from facility level to corporate procurement.
- Distributors:Regional chemical distributors maintain formulation blending capabilities and local technical service presence for mid-sized manufacturing accounts. German and Italian equipment suppliers leverage distributor networks to capture F-Gas Regulation-driven vapor degreasing replacement cycles.
- E-Commerce Platforms:Amazon Business and specialized industrial marketplaces serve small repair shops and facility managers with immediate fulfillment and transparent pricing.
- Retail Stores:Auto parts chains and home improvement centers stock consumer-grade degreasers for DIY maintenance applications.
- Wholesalers:Bulk chemical handlers supply private-label formulations to regional distributors and large institutional buyers.
- Specialty Dealers:Aviation and marine-focused distributors carry MIL-spec and IMO-compliant formulations for regulated transportation segments.
Direct Sales commands strategic accounts. E-Commerce Platforms are gaining share fastest among underserved small users.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Industrial degreaser formulations first achieved commercial scale in German metalworking centers during the 1950s, establishing technical protocols that diffused through European manufacturing and later into North American and Asian industrial corridors. Today's aftermarket geography reflects both this historical lineage and divergent regulatory enforcement patterns across major economies.
United States
Automotive maintenance workshops in Michigan and Ohio industrial belts are converting solvent-based parts washers to aqueous systems. EPA National Volatile Organic Compound Emission Standards for Consumer and Commercial Products compress formulation windows for traditional chemistries. Fleet operators in the Southeast now specify low-VOC alternatives through consolidated national procurement contracts.
Germany
Metal fabrication facilities in North Rhine-Westphalia and Baden-Württemberg drive specification demand for REACH-compliant aqueous cleaning systems. ECHA classification of chlorinated hydrocarbons as substances of very high concern accelerates substitution cycles. Stuttgart-area automotive stamping plants negotiate multi-year supply agreements bundling chemistry, equipment, and waste handling services.
China
Electronics contract manufacturers in the Yangtze River Delta and Pearl River Delta generate precision cleaning demand for semiconductor packaging operations. Ministry of Ecology and Environment GB wastewater discharge standards compel closed-loop system investments with recyclable chemistries. Shenzhen and Suzhou assembly plants specify ultra-low residue formulations for ionic contamination testing compliance.
Brazil
Shipyards in Rio de Janeiro and São Paulo coastal zones specify biodegradable degreasers where MARPOL discharge constraints apply. D-limonene supply concentration in São Paulo agricultural regions creates periodic allocation risk during harvest disruptions. Independent automotive garages in Minas Gerais purchase through distributors with price-sensitive brand switching patterns.
India
Automotive and textile clusters in Gujarat and Tamil Nadu remain underserved by formulated maintenance chemical distributors. Central Pollution Control Board effluent discharge norms are tightening enforcement across manufacturing corridors. First-mover technical service-oriented suppliers are establishing presence in Ahmedabad and Chennai industrial zones.
Global Cleaner and Degreaser Aftermarket Market Competitive Landscape
Capital-heavy chemical producers compete with asset-light formulation specialists across distinct value chain positions. The aftermarket structure shows moderate consolidation at the formulation level with fragmentation among regional distributors and service providers. Three archetypes dominate: integrated specialty chemical suppliers with captive surfactant production, focused maintenance chemical formulators with deep distribution networks, and diversified industrial conglomerates leveraging cross-selling capabilities. Competitive dynamics center on regulatory compliance bundling and geographic expansion through distributor acquisition.
Within the integrated specialty chemical tier, BASF SE and 3M Company exemplify archetypes combining material science capabilities with multi-jurisdiction regulatory affairs infrastructure. CRC Industries, Inc. occupies a position representing focused formulators with concentrated presence in automotive and aviation maintenance channels. These three entities anchor the competitive landscape through differentiated approaches to compliance documentation, technical service attachment, and channel access strategies.
| Leading Market Players |
|---|
| WD-40 Company |
| CRC Industries, Inc. |
| Zep, Inc. |
| BASF SE |
| The Clorox Company |
| 3M Company |
| RSC Brands |
| Kafko International Ltd. |
| DuPont de Nemours, Inc. |
| Others |
Supply & Pricing Matrix
Private-equity-rolled-up specialty chemical distributors have consolidated regional formulation capacity across the United States and Germany, tightening pricing discipline while compressing procurement leverage for mid-sized industrial buyers. This ownership pattern concentrates supply-side bargaining power among entities with captive surfactant sourcing and integrated regulatory affairs infrastructure.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates NSF-registered food-grade formulations from general industrial cleaners and private-label commodity alternatives. Price differentiation rests on certification tier and volume scale, with automotive dealership groups extracting steepest discounts through consolidated national contracts. Cost compression in the economy tier is intensifying because Brazilian d-limonene supply fluctuations force margin absorption. Vehicle repair shops exhibit highest price sensitivity, while electronics assembly plants prioritize residue compliance over unit cost.
Supply Chain Analysis
Formulation chemist shortages in German and United States manufacturing regions constrain batch scheduling flexibility and extend custom order lead times. Production gravity centers on Germany, China, and the United States for ethoxylated alcohols and alkyl polyglucoside surfactants. Raw material flows draw from Florida citrus terpene harvests, São Paulo d-limonene extraction, and Gulf Coast petrochemical feedstocks. Single-source vulnerability in Brazilian agricultural inputs creates periodic allocation risk. Distribution runs through direct manufacturer national accounts, regional chemical distributors with blending capabilities, and emerging e-commerce platforms for fragmented spot demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Cleaner and Degreaser Aftermarket Market functions as a stable compounder, with recurring preventive maintenance cycles across capital-intensive manufacturing generating predictable replacement demand regardless of macroeconomic volatility.
For Market Incumbents: Anchor market position through backward integration into bio-surfactant production and acquisition of regional distributors with EPA Safer Choice certification capabilities. Water-based formulation startups threaten share in automotive maintenance channels. Capacity addition in China's Yangtze River Delta industrial corridor captures electronics cleaning expansion. For New Entrants and Emerging Players: EPA Significant New Alternatives Policy evaluations in the United States open a window for fluorine-free precision degreasers in aerospace MRO facilities. India's Gujarat automotive cluster remains underserved by technical service-oriented suppliers. Electronics precision cleaning offers the most penetrable application segment. Go-to-market through direct partnerships with semiconductor packaging plants in South Korea and Taiwan bypasses entrenched distributor relationships. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-cap formulators with concentrated citrus-terpene exposure and limited regulatory affairs infrastructure. Long-term viability favors entities with multi-jurisdiction certification portfolios and closed-loop system service capabilities. Acquisition targets include regional distributors with captive customer relationships in automotive dealership groups. The signal to watch is accelerated F-Gas Regulation phase-down announcements that would force aqueous conversion capex and expand addressable market for integrated system providers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bio-Surfactant Production | BASF SE and specialty chemical suppliers secure captive supply of REACH-compliant alkyl polyglucosides against allocation risk. |
| Regional Distributor Acquisition | CRC Industries consolidates channel control in automotive maintenance networks across the United States Southeast. |
| Multi-Jurisdiction Certification Investment | Formulators compress launch timelines by securing concurrent EPA Safer Choice, EU Ecolabel, and Nordic Swan approval. |
| Closed-Loop System Service Expansion | Equipment-chemistry bundling captures F-Gas Regulation-driven vapor degreasing replacement cycles in German metal stamping. |
| Electronics Precision Cleaning Formulation Launch | Ultra-low residue chemistries penetrate semiconductor packaging operations in Shenzhen and Suzhou assembly plants. |
Research Methodology
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region combined with secondary validation across regulatory filings and trade databases. Primary interviews engaged formulation chemists at specialty chemical producers, procurement leads at automotive OEM plants, distribution channel partners in Germany and the United States, and technical service directors at maintenance chemical suppliers. Secondary sources include EPA VOC emission standard filings, ECHA REACH restriction updates, China MEE wastewater discharge records, customs trade data, and SEC 10-K disclosures from listed chemical companies. Bottom-up demand modeling triangulates against top-down market sizing.
Rate-of-change decomposition separates volume growth from pricing dynamics and mix shifts across the analysis window. Segmentation dimensions include formulation chemistry, application environment, end-user industry scale, and distribution channel structure. CAGRs derive from regression analysis of historical procurement patterns against regulatory enforcement timelines and industrial production indices. Industry-specific forecast inputs incorporate aviation MRO fleet renewal schedules and semiconductor packaging capacity expansion pipelines.
Forecast precision tightens around the base case; tail outcomes carry wider variance under sudden PFAS restriction announcements or Brazilian citrus harvest disruptions. Projections reflect assumptions regarding steady EPA enforcement continuity, phased REACH implementation, and stable surfactant feedstock availability. Material deviation in F-Gas Regulation phase-down speed or China GB wastewater standard amendments warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cleaning Chemicals
Aviation Cabin Cleaning Chemical Market
Cleaning Chemicals
Global Cationic Reagent Market
Cleaning Chemicals
Micellar Cleansing Water Market
Cleaning Chemicals
Multifunctional Cleaner Market
Cleaning Chemicals
Commercial Deodorizers Market
Cleaning Chemicals
Purging Compound Market
Cleaning Chemicals
Glass Cleaner Market
Cleaning Chemicals
Dust Control Systems and Suppression Chemicals Market
Cleaning Chemicals
Chlorinating Agents Market
Cleaning Chemicals
High-Performance Descaling and Deliming Chemicals for HoReCa Equipment Market
Cleaning Chemicals
Sponge and Scouring Pads Market
Cleaning Chemicals
Global Dust Suppression and Control Chemicals Market
Cleaning Chemicals
Chlorhexidine Gluconate (CHG) Cloth Market
Cleaning Chemicals
South Africa Cleaning Products Market
Cleaning Chemicals
Cement Surface Treatment Chemicals Market
Cleaning Chemicals
Surface Cleaning Products Market