
 3-Butylene Glycol Market | 2026-2036
3-Butylene Glycol Market Size, Share, and Industry Trends Forecast 2026-2036
3-Butylene Glycol Market Analysis
Maintenance and technical support contracts for specialty chemical synthesis equipment is repositioning how producers monetize 3-butylene glycol output. Daicel Corporation leverages its integrated acetic acid derivatives platform to sustain captive supply advantages. Godavari Biorefineries Ltd. anchors its position through fermentation-based routes from molasses feedstock. OXEA GmbH competes via controlled oxidation technology leadership in C4 chemistry.
3-Butylene glycol, also known as 1,3-butanediol, is a four-carbon diol with molecular formula C4H10O2, produced industrially through aldol condensation of acetaldehyde followed by hydrogenation, serving primarily as a humectant, solvent, and precursor for polyester plasticizers. The cosmetics product type segment captures the dominant margin pool as formulators prioritize multifunctional ingredients with moisturizing and antimicrobial properties. The skin care application segment leads volume absorption, while food preservation represents an emerging pathway as clean-label trends intensify. Liquid form dominates manufacturing throughput due to handling efficiencies in bulk chemical logistics.
EPA oversight of chemical manufacturing under TSCA shapes facility permitting and emission controls for U.S.-based producers, while REACH registration requirements in Europe mandate comprehensive toxicological dossiers for import authorization. FDA food additive regulations and cosmetic ingredient safety assessments further constrain formulation choices for suppliers targeting North American consumer brands. Stakeholders must track evolving biobased certification schemes and carbon intensity disclosures as procurement criteria harden across downstream sectors.
Market Dynamics
REACH compliance in Europe is redirecting procurement toward certified suppliers with verified toxicological dossiers, compressing the viable supplier base while elevating purity premiums across cosmetics and food-grade segments.
Growth Catalysts
- Clean-label food preservation:Consumer brands are reformulating away from synthetic preservatives toward 3-butylene glycol's antimicrobial properties, accelerating adoption in sauces and beverages.
- East Asian production clustering:Manufacturing concentrates in chemical parks near Shanghai and Osaka, yielding feedstock integration advantages and shorter logistics loops for regional personal care brands.
- Fermentation technology maturation:Molasses-to-diol bioconversion routes achieve cost parity with petrochemical pathways, opening capacity expansion without fossil feedstock exposure.
Market Restraints
- Acetaldehyde price volatility:The aldol condensation feedstock fluctuates with ethylene derivative markets, compressing margins for non-integrated producers during crude price spikes.
- Supplier concentration risk:Captive supply from integrated acetic acid producers limits merchant market liquidity, forcing buyers into long-term offtake commitments with Japanese and German chemical groups.
- Propylene glycol substitution:Lower-cost C3 diols compete in industrial solvent applications where humectant performance requirements allow formulation flexibility.
Strategic Opportunities
- Biobased certification premiums:USDA BioPreferred and EU Green Deal aligned schemes enable price differentiation for fermentation-derived material in North American and European cosmetics procurement.
- Polyester plasticizer precursor demand:Flexible PVC compounders are sourcing 3-butylene glycol for adipate ester synthesis as phthalate restrictions tighten under REACH and state-level U.S. regulations.
- Direct-to-brand distribution:Specialty chemical platforms are disintermediating traditional distributors for mid-sized cosmetics formulators, capturing margin and customer data.
Industry Challenges
- Fermentation scale-up expertise:Bioprocess engineering talent shortages delay commissioning of commercial molasses-to-diol facilities, extending payback periods for capital deployments.
- REACH dossier maintenance:Toxicological study updates and substance evaluation responses consume regulatory affairs bandwidth, particularly for multi-site suppliers with varying feedstock sources.
- Legacy equipment retrofit costs:Hydrogenation reactor upgrades for higher-purity output require significant capital outlays at plants originally configured for industrial-grade production.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | 3-Butylene Glycol Market |
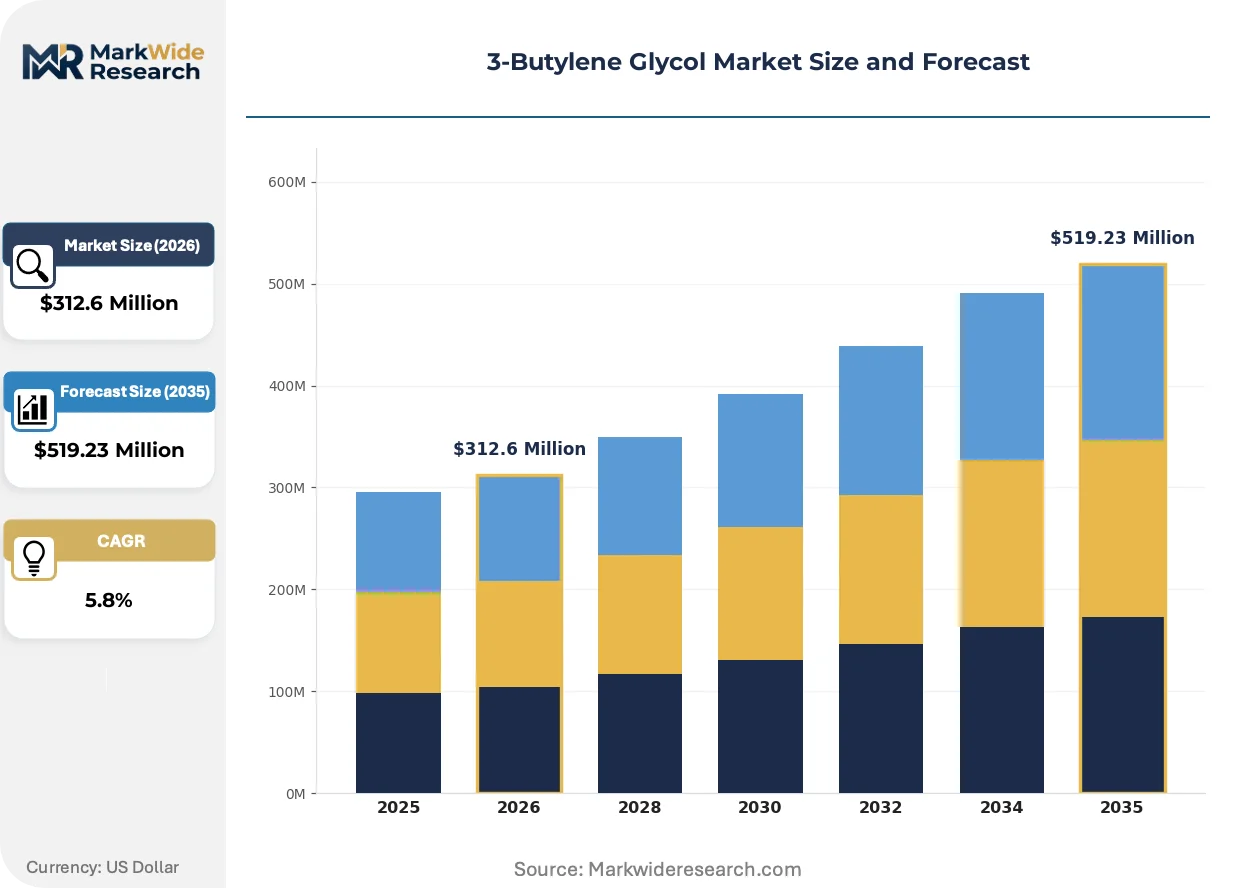
| Market Size in 2026 | $312.6 Million |
| Market Size in 2035 | $519.23 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cosmetics, Pharmaceuticals, Food Additives, Industrial Solvents Application: Skin Care, Hair Care, Makeup, Food Preservation Form: Liquid, Gel, Powder, Emulsion End User: Consumers, Manufacturers, Retailers, Wholesalers |
| Companies Covered | Daicel Corporation, Godavari Biorefineries Ltd., Shanghai Jinjin Industry Co., Ltd., Penta Manufacturing Company, OXEA GmbH, MMP Inc., Whyte Chemicals Limited, Rita Corporation, KH Neochem Co. Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
3-Butylene Glycol Market Emerging Trajectories
Continuous processing technology and biobased feedstock validation are compressing batch cycle times and carbon intensity disclosures simultaneously, reshaping how producers compete on both cost and sustainability credentials.
Continuous hydrogenation reactor designs are rewriting throughput economics for aldol-derived 3-butylene glycol. Japanese engineering firms are licensing skid-mounted units to mid-scale producers seeking to debottleneck batch operations. The technology is rewriting the minimum efficient scale for merchant market entry, eroding the captive supply advantage of integrated petrochemical complexes.
ECHA's 2023 REACH restriction proposal on skin-sensitizing impurities is tightening analytical specifications for cosmetic-grade material. Third-party certification bodies in Germany and France are expanding testing capacity to verify sub-ppm contaminant thresholds. European formulators are consolidating supplier lists to those with in-house GC-MS verification, marginalizing traders without laboratory infrastructure.
Beauty brands are unbundling ingredient procurement from finished goods manufacturing, establishing direct relationships with diol producers for custom purity grades. South Korean cosmetics houses are leading this disintermediation, negotiating specification-lock contracts that bypass regional distributors. The shift concentrates volume with producers capable of technical service support and regulatory documentation in Hangul and English.
3-Butylene Glycol Market Segmentation
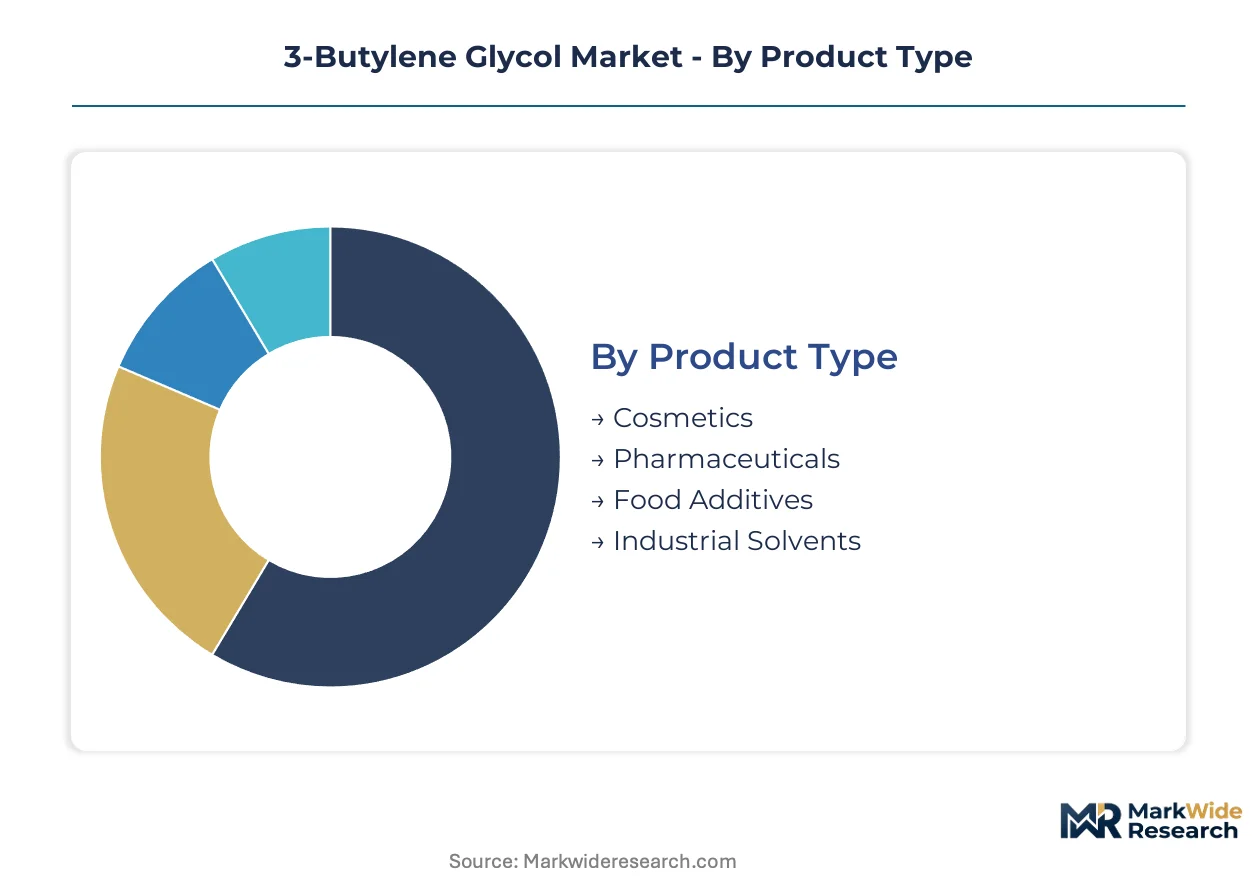
Segmentation in 3-butylene glycol reveals how purity grades and formulation requirements split procurement patterns across cosmetics, food, and industrial channels. Each dimension carries distinct margin structures and regulatory burdens that reshape supplier selection criteria.
Product Type:
Cosmetics-grade material commands premium pricing over industrial solvents, while food-additive certification opens margin pools unavailable to standard technical grades.
- Cosmetics:Multifunctional humectant and antimicrobial properties meet formulator demand for clean-label moisturizers. South Korean and Japanese beauty houses drive specification-lock contracts for sub-ppm impurity thresholds verified through in-house GC-MS protocols.
- Pharmaceuticals:USP-grade material serves as excipient in oral and topical drug delivery systems. FDA compliance documentation and batch-level traceability requirements compress the viable supplier base to fermentation-based producers with dedicated GMP facilities.
- Food Additives:Clean-label preservation in sauces and beverages leverages antimicrobial functionality without synthetic preservative stigma.
- Industrial Solvents:Technical-grade material competes against lower-cost propylene glycol in polyester plasticizer and coating applications.
Mature deployment sits with Cosmetics. Newer deployment is concentrated in Food Additives.
Application:
Skin care formulations absorb the highest absolute volumes, though food preservation represents the steepest expansion trajectory as clean-label trends intensify.
- Skin Care:Serums, lotions, and creams incorporate 3-butylene glycol for sustained hydration and formulation stability. East Asian personal care brands in Shanghai and Osaka chemical parks anchor regional demand concentration.
- Hair Care:Conditioners and styling products utilize humectant properties for moisture retention in humid climates. Southeast Asian procurement is climbing fastest as regional formulators reformulate away from silicones.
- Makeup:Long-wear foundations and primers employ solvent characteristics for pigment dispersion and film-forming.
- Food Preservation:Sauces, dressings, and ready-to-drink beverages adopt antimicrobial functionality under USDA and EFSA safety assessments.
Volume leadership belongs to Skin Care. Regulatory tailwinds are strongest for Food Preservation.
Form:
Liquid dominance in bulk chemical logistics creates handling efficiencies that powder and emulsion variants cannot replicate at scale.
- Liquid:Standard bulk delivery format enables seamless integration into continuous manufacturing processes. Tanker-truck economics favor liquid for high-throughput cosmetics and food-grade production.
- Gel:Pre-thickened systems reduce formulation complexity for small-batch personal care manufacturers.
- Powder:Spray-dried material addresses shipping cost constraints for distant formulators lacking local liquid supply infrastructure.
- Emulsion:Oil-in-water dispersions target specialty applications requiring controlled release or enhanced skin penetration.
Operational scale favors Liquid. Niche customization concentrates in Emulsion.
End User:
Manufacturer procurement patterns diverge sharply from retail and wholesale channels on specification control and volume commitment terms.
- Consumers:Direct purchasing of pure 3-butylene glycol remains negligible, confined to DIY cosmetics hobbyists and small-scale formulators.
- Manufacturers:Integrated personal care and food production facilities negotiate multi-year offtake agreements with certified suppliers. REACH dossier maintenance and toxicological study updates figure prominently in supplier scorecards.
- Retailers:Specialty chemical distributors serve mid-sized formulators with blended minimum order quantities and regulatory documentation packages.
- Wholesalers:Bulk traders handle industrial-grade material without certification value-add, competing primarily on logistics efficiency.
Contract sophistication is highest with Manufacturers. Margin compression is severest among Wholesalers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shanghai anchors the densest concentration of 3-butylene glycol manufacturing capacity, with chemical parks along the Yangtze River Delta feeding regional cosmetics formulators. Procurement patterns diverge sharply across major economies as regulatory frameworks reshape supplier viability.
China
Cosmetics-grade demand from domestic beauty brands drives volume absorption in Jiangsu and Zhejiang provinces. SAMR's cosmetic ingredient safety assessments tighten purity documentation requirements for imported formulations. The Yangtze River Delta chemical corridor concentrates hydrogenation capacity serving both local skin care manufacturers and export-oriented compounders.
Japan
Integrated acetic acid producers sustain captive supply advantages for high-purity pharmaceutical and cosmetic grades. METI's chemical substance management framework under CSCL mandates rigorous toxicological dossier maintenance for domestic manufacturers. Osaka-based engineering firms license continuous hydrogenation reactor designs to mid-scale regional producers seeking throughput expansion.
United States
Food preservation applications accelerate as clean-label reformulation penetrates sauces and ready-to-drink beverages. EPA oversight under TSCA shapes emission controls and facility permitting for domestic hydrogenation operations. The Gulf Coast petrochemical corridor hosts aldol condensation feedstock integration serving technical-grade solvent markets.
Germany
REACH registration requirements and ECHA's 2023 restriction proposals on skin-sensitizing impurities compress the viable supplier base for cosmetic-grade material. EU Green Deal alignment pressures carbon intensity disclosures across procurement scorecards. The Rhine-Ruhr industrial region concentrates specialty chemical distribution infrastructure linking certified producers to European formulators.
South Korea
Beauty houses pioneer direct-to-procurement relationships, disintermediating traditional distributors for specification-lock contracts. MFDS cosmetic ingredient safety assessments parallel FDA documentation requirements for export-oriented manufacturers. Seoul-based formulators drive sub-ppm impurity thresholds through in-house analytical verification protocols.
3-Butylene Glycol Market Vendor Landscape
Capital-heavy integrated producers compete with asset-light fermentation specialists for margin pool capture across purity grades. The supplier base concentrates around three strategic archetypes: petrochemical-integrated hydrogenation operators, molasses-to-diol bioconversion platforms, and regional merchant distributors with analytical certification capabilities. Capacity expansion and biobased certification acquisition dominate competitive positioning as procurement criteria harden on carbon intensity disclosures.
Among Japanese chemical conglomerates, Daicel Corporation anchors the integrated petrochemical tier, while Godavari Biorefineries Ltd. exemplifies the fermentation-based specialist archetype. OXEA GmbH occupies a position within the European C4 chemistry platform segment. These three entities represent the structural diversity of supply-side configuration: acetic acid derivative integration, agricultural feedstock bioconversion, and controlled oxidation technology leadership respectively.
| Leading Market Players |
|---|
| Daicel Corporation |
| Godavari Biorefineries Ltd. |
| Shanghai Jinjin Industry Co., Ltd. |
| Penta Manufacturing Company |
| OXEA GmbH |
| MMP Inc. |
| Whyte Chemicals Limited |
| Rita Corporation |
| KH Neochem Co. Ltd. |
| Others |
Supply Flow & Price Mechanics
REACH-mandated purity documentation from European cosmetics formulators is compressing the viable supplier base, forcing procurement toward certified producers with in-house analytical capabilities and elevating premiums for compliant material.
Pricing Analysis
Margin tightening in cosmetic-grade tiers reflects acetaldehyde feedstock volatility and the capital burden of hydrogenation reactor upgrades for sub-ppm impurity compliance. Three-tier pricing structure across pharmaceutical, cosmetic, and industrial grades separates USP-certified material commanding the highest premiums from technical-grade solvents competing with propylene glycol. Cost-down pressure on standard cosmetic grades accelerates as South Korean beauty houses consolidate supplier lists to three certified partners. Industrial buyers exhibit the highest price sensitivity, while pharmaceutical formulators demonstrate inelastic demand for USP documentation.
Supply Chain Analysis
Tanker-truck freight economics from Shanghai and Osaka chemical parks favor liquid bulk delivery over powder alternatives for distant formulators. Manufacturing concentrates in China, Japan, and Germany, with feedstock integration advantages tethering high-volume output to Yangtze River Delta and Rhine-Ruhr infrastructure. Molasses feedstock dependence for fermentation routes and ethylene derivative exposure for petrochemical pathways create dual commodity vulnerabilities. Single-source risk concentrates in Japanese integrated acetic acid producers supplying captive pharmaceutical grades. Distribution runs through specialty chemical platforms disintermediating traditional traders for mid-sized cosmetics manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around REACH-compliant producers as regulatory dossier maintenance costs force sub-scale fermentation operators toward acquisition or exit.
For Market Incumbents: Cement supply security through backward integration into acetic acid derivatives or molasses feedstock sourcing, while acquiring third-party GC-MS certification capacity to capture distributor margin pools. Daicel-style captive integration and Godavari's fermentation expertise represent defensible moats against merchant market commoditization. For New Entrants and Emerging Players: Launch via direct-to-brand distribution partnerships with mid-sized South Korean cosmetics houses seeking specification-lock contracts bypassing regional traders. Food preservation applications in North American sauces and beverages offer the most penetrable white-space, with USDA compliance documentation as the entry credential. For Investors and Strategic Acquirers: The window for entry favors fermentation-based specialists with commercial molasses-to-diol scale and pending biobased certification. Long-term viability hinges on carbon intensity disclosure capabilities aligning with EU Green Deal procurement criteria. Watch ECHA substance evaluation timelines as the signal for regulatory-driven supplier list compression.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Acetic Acid Feedstock | Captive supply security insulates Daicel-style producers from ethylene derivative volatility. |
| USDA BioPreferred Certification Acquisition | Fermentation-derived material commands procurement preference from North American clean-label brands. |
| Continuous Hydrogenation Reactor Deployment | Osaka-based engineering licenses compress batch cycle times for mid-scale merchant entrants. |
| Direct-to-Brand Distribution Platform | Disintermediation captures margin and customer data from South Korean cosmetics houses. |
| REACH Dossier Maintenance Investment | Toxicological study updates preserve European market access as ECHA tightens impurity thresholds. |
Methodological Framework
Multi-period observation of acetaldehyde pricing spreads, REACH registration timelines, and biobased certification adoption anchored the trend analysis, supplemented by interviews with hydrogenation plant managers, cosmetics procurement leads, specialty chemical distributors, and fermentation R&D directors. Secondary validation drew from ECHA substance evaluation databases, SAMR cosmetic ingredient filings, customs trade flows, and SEC disclosures from listed chemical producers. Bottom-up capacity assessments triangulated against top-down demand modeling from personal care and food preservation end-use segments.
Input-output matrices mapped feedstock conversion yields, purity grade premiums, and regional logistics costs across the modeling period. Segmentation dimensions included grade tier, end-use industry, and regional production hub. CAGRs derived from installed capacity expansion schedules, substitution elasticity estimates for propylene glycol, and regulatory-driven supplier consolidation trajectories. Molasses-to-diol bioconversion cost curves and carbon intensity disclosure requirements informed scenario weighting.
Acetaldehyde price spikes, ECHA restriction proposal acceleration, and fermentation scale-up delays are the dominant revision risks to capacity and demand assumptions. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solvents
Reactive Diluents Market
Solvents
Aliphatic Hydrocarbon Solvents and Thinners Market
Solvents
Aprotic Solvents Market
Solvents
Aromatic Solvents Market
Solvents
Japan Acetonitrile Market
Solvents
Acetone Market
Solvents
Green Solvents Market
Solvents
Methyl Undecylenate Market
Solvents
4-Dichlorobenzyl Alcohol (DCBA) Market
Solvents
Epoxy Thinner Market
Solvents
2-Butanone Market
Solvents
Europe Hydrocarbon Solvents Market
Solvents
Diethanolamine (DEA) Market
Solvents
Dimethyl Ether (DME) Market
Solvents
Nitrobenzene Market
Solvents
Piperylene Market