
 Europe Chemical Anchors Market | 2026-2036
Europe Chemical Anchors Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Chemical Anchors Market Analytics
German adhesive anchor production is restructuring capacity toward dual-cartridge hybrid systems serving seismic-rated infrastructure. Fischer Group leverages captive resin compounding to control epoxy cure profiles across Nordic temperature extremes. Sika AG anchors its position through construction chemicals distribution density in Alpine tunneling corridors. Hilti Corporation differentiates via direct-channel technical support teams embedded with major German contractors.
Europe chemical anchors are injection-bonded fastening systems comprising resin cartridges, hardener pastes, and threaded steel elements that develop load capacity through adhesion to drilled concrete or masonry substrates; typical epoxy systems achieve pull-out strengths exceeding 80 kN in C30/37 concrete. Their primary purpose is structural load transfer in reinforced concrete where mechanical anchors risk substrate fracture or where reduced edge distances apply. Epoxy formulations dominate premium infrastructure specifications due to creep resistance under sustained tension loads, while hybrid systems represent the fastest-growing category as contractors seek faster cure times without sacrificing performance thresholds. Polyester resins occupy economy-tier construction segments where temporary or non-structural fastening suffices, with margin pools thinnest in this commoditized tier.
CE marking under the Construction Products Regulation and ECHA REACH compliance on styrene and isocyanate content shape formulation roadmaps and market access conditions across EU member states. Germany's DIBt approvals and France's CSTB technical assessments create divergent national certification burdens that fragment product portfolios. Stakeholders must monitor evolving Eurocode 2 anchoring design provisions and national transposition timelines to align R&D pipelines with code-mandated performance verification protocols.
Market Dynamics
EU Green Deal embodied carbon requirements are forcing specification shifts toward low-VOC hybrid resin formulations across European infrastructure procurement, compressing polyester's share while elevating certified epoxy systems.
Growth Catalysts
- Infrastructure Retrofitting Mandates:Aging bridge and tunnel portfolios across Germany, France, and Italy require high-load fastening systems for seismic upgrades and load-bearing reinforcement. Federal transport investment programs in Germany specifically prioritize DIN-certified anchoring solutions.
- REACH Compliance Evolution:ECHA restrictions on styrene and isocyanate content are accelerating R&D investment in bio-based hardener alternatives. Formulators achieving early compliance capture specification lock-in from public infrastructure tenders.
- Alpine Tunneling Expansion:Swiss and Austrian transalpine corridor projects demand specialized hybrid systems capable of rapid cure at sub-zero temperatures. Contractors specify products with validated performance data across thermal extremes.
Market Restraints
- Raw Material Concentration:Epoxy resin supply chains concentrate in Belgian and Dutch petrochemical clusters, exposing formulators to naphtha derivative volatility and force majeure disruptions.
- Divergent National Certification:Germany's DIBt approvals and France's CSTB technical assessments create fragmented product portfolios, raising inventory carrying costs and delaying cross-border market entry.
- Mechanical Anchor Substitution:Wedge and expansion anchors retain cost advantage in temporary applications and non-structural building services, capping chemical anchor penetration in commercial construction tiers.
Strategic Opportunities
- Polish and Romanian Infrastructure Buildout:EU cohesion fund absorption in Eastern European member states is accelerating highway and rail modernization, creating first-mover advantage for hybrid system suppliers establishing local distribution.
- Offshore Wind Foundation Anchoring:North Sea and Baltic offshore wind installations require corrosion-resistant fastening for transition piece connections. Hybrid vinyl ester formulations validated for marine exposure command specification premiums.
- Digital Specification Platforms:BIM-integrated anchor selection tools are displacing traditional catalog-based procurement. Manufacturers embedding calculation modules within Autodesk and Nemetschek workflows capture design-phase influence.
Industry Challenges
- Eurocode 2 Transposition Delays:National implementation timelines for updated anchoring design provisions vary across EU member states, complicating product validation protocols and creating market access uncertainty.
- Specialized Application Engineering Talent:Seismic-rated installation supervision and pull-out testing certification require field engineers with combined structural and resin chemistry expertise. Training pipeline gaps constrain contractor scaling.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Chemical Anchors Market |
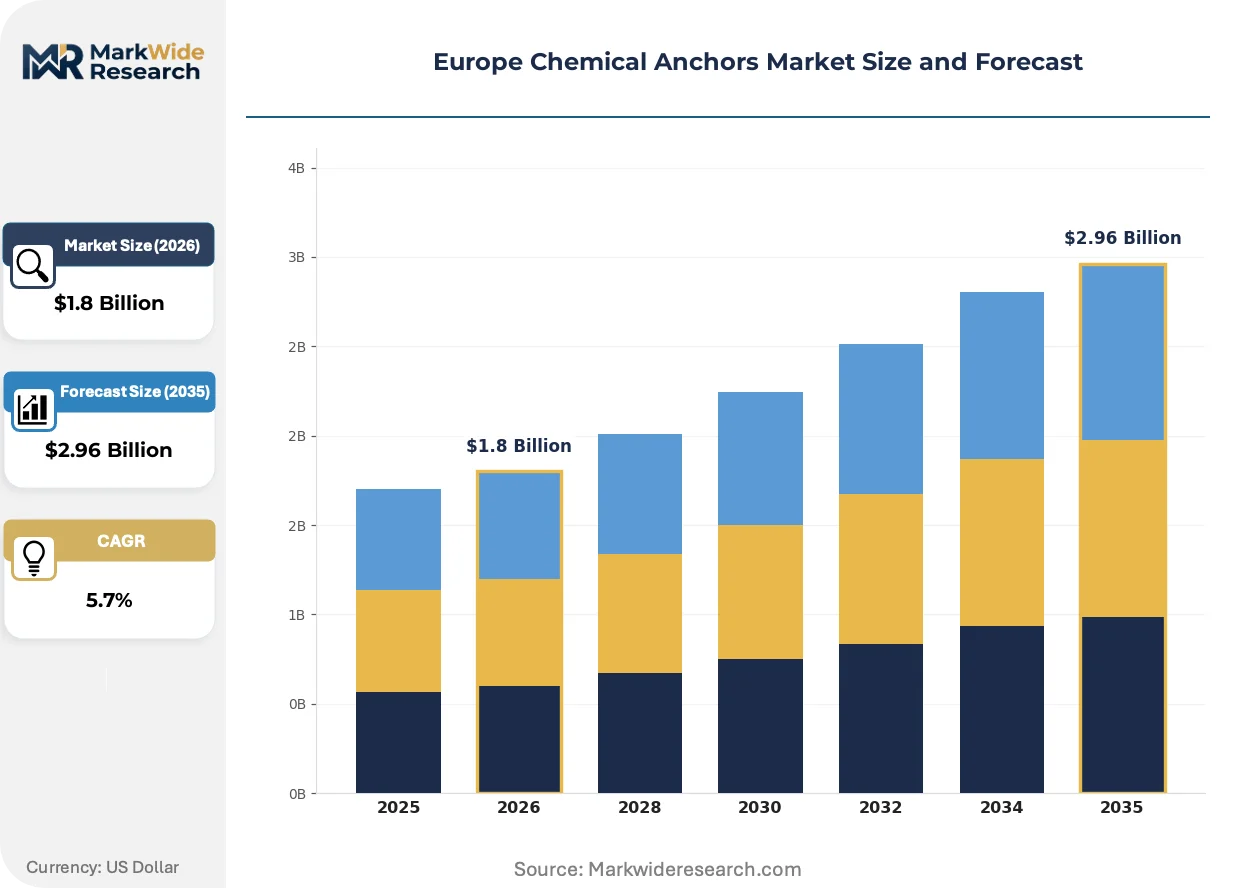
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Epoxy, Hybrid, Polyester, Acrylic End Use Industry: Construction, Infrastructure, Oil & Gas, Automotive Packaging Type: Cartridges, Buckets, Drums, Pails Application: Fastening, Sealing, Bonding, Anchoring |
| Companies Covered | Fischer Group, Illinois Tool Works Inc., Sika AG, HALFEN, Mungo AG, Hilti Corporation, Simpson Strong-Tie Company, Inc., Chemfix, Henkel AG & Co. KGaA, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Chemical Anchors Market Evolving Landscape
Formulation chemistry, regulatory compliance architecture, and procurement digitization are converging to reshape competitive positioning across European specification channels.
Hybrid vinyl ester-epoxy systems is consolidating performance tier boundaries by delivering sub-30-minute cure times without sacrificing sustained load capacity. German and Swiss infrastructure contractors are specifying these platforms for round-the-clock tunneling operations where mechanical anchor drilling windows are compressed. The technology is consolidating mid-tier epoxy and premium vinyl ester categories into a single specification grade, pressuring pure-play epoxy margins.
EU Green Deal embodied carbon reporting requirements are mandating Environmental Product Declarations for construction materials in public tenders above defined thresholds. Chemical anchor manufacturers must now validate cradle-to-gate carbon footprints through third-party verification. German transport authorities are embedding these declarations within technical approval conditions, effectively excluding non-compliant suppliers from federal project pipelines.
Specification influence is migrating upstream from procurement departments to structural engineering consultancies equipped with anchor calculation software. Nordic and Alpine infrastructure specialists now require manufacturers to provide ETAG-compliant performance datasets directly within design workflows. This behavioral shift concentrates vendor selection authority among a narrow cohort of engineering firms, compressing traditional distributor influence over project-level decisions.
Europe Chemical Anchors Market Segmentation
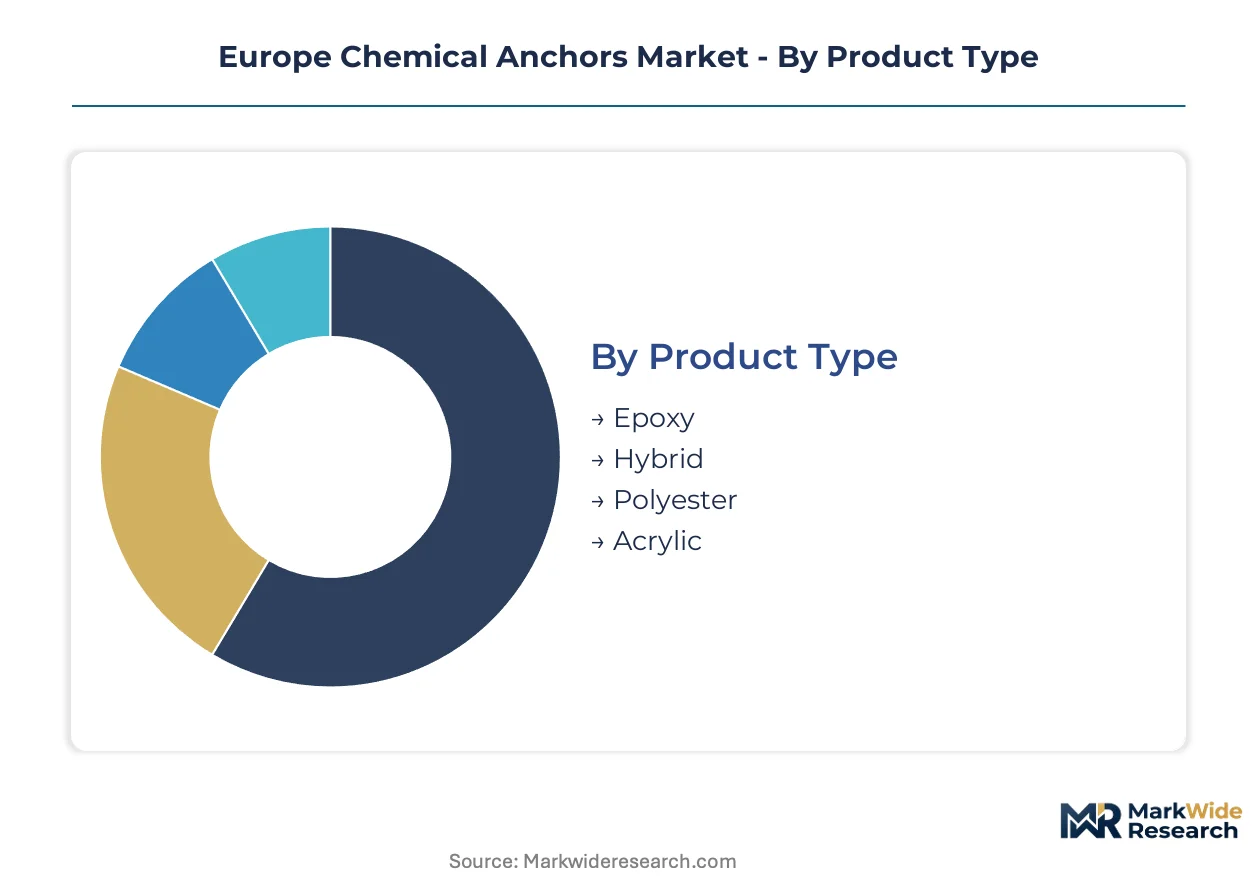
Chemical anchor specification in Europe follows rigid performance hierarchies tied to substrate conditions, load requirements, and cure-time constraints. Segmentation reveals where formulation premiums command price authority versus commodity substitution risk.
Product Type:
Upgrade cycles from polyester to hybrid and epoxy systems accelerate as infrastructure owners face DIN certification mandates and Green Deal carbon disclosure requirements.
- Epoxy:Two-component thermosetting systems based on bisphenol-A or bisphenol-F resins with amine hardeners deliver sustained load capacity exceeding 80 kN in C30/37 concrete. German federal bridge retrofit programs specify epoxy for seismic-rated connections where creep resistance under permanent tension is mandatory.
- Hybrid:Vinyl ester-epoxy copolymer formulations achieve sub-30-minute cure profiles while retaining post-cure mechanical properties. Swiss and Austrian tunnel contractors specify these for continuous excavation schedules where drilling windows are compressed by ground stabilization protocols.
- Polyester:Unsaturated polyester-styrene systems serve temporary fastening and non-structural building services where cost minimization outweighs performance durability.
- Acrylic:Methacrylate-based rapid-cure platforms tolerate moist concrete substrates; demand clusters in repair applications where water ingress precludes epoxy installation.
Volume placements concentrate in epoxy systems for infrastructure; the faster expansion belongs to hybrid formulations displacing both premium epoxy and economy polyester tiers.
End Use Industry:
Cost tier differentiation separates specification-grade public infrastructure from commercial construction where mechanical anchors compete on installed cost.
- Construction:Commercial and residential building envelopes drive cartridge-format consumption for curtain wall connections and structural steel erection. German and French building codes mandate ETAG-compliant anchors for life-safety applications.
- Infrastructure:Highway bridges, rail tunnels, and airport terminals require pull-out tested installations with certified installation supervision. Federal transport investment programs in Germany and Italy specify DIN-approved systems with documented cure temperature ranges.
- Oil & Gas:Refinery maintenance and petrochemical facility upgrades specify corrosion-resistant formulations for equipment anchoring in aggressive chemical environments.
- Automotive:Manufacturing line reconfigurations and paint shop installations use rapid-cure systems to minimize production downtime during facility modifications.
Revenue margins peak in infrastructure applications; automotive procurement exerts the strongest downward pressure on unit pricing.
Packaging Type:
Application scale and site logistics dictate format selection across project types and contractor procurement patterns.
- Cartridges:Dual-barrel coaxial cartridges with static mixing nozzles dominate structural fastening where precise resin-hardener ratios and controlled dispensing are essential.
- Buckets:Bulk containers serve large-scale grouting and rebar doweling operations in foundation work where continuous mixing equipment is deployed.
- Drums:Industrial-volume packaging supports manufacturing-scale consumption for OEM anchor assembly and pre-packaged kit production.
- Pails:Mid-volume format bridges cartridge convenience and bucket economy for medium-scale commercial projects with variable daily consumption rates.
Cartridge formats capture the highest value per kilogram; pail volumes are climbing fastest as mid-tier contractors standardize on scalable procurement units.
Application:
Functional purpose determines resin selection, installation protocol, and performance validation requirements across European specification channels.
- Fastening:Structural load transfer to concrete substrates through threaded rod or rebar elements bonded into drilled holes; governed by Eurocode 2 anchoring design provisions with national annex variations.
- Sealing:Crack injection and waterstop applications in tunnel linings and basement structures; requires low-viscosity formulations with verified penetration into micro-cracks.
- Bonding:Structural adhesive connections between concrete elements and steel plates; demands formulations with validated bond strength to both substrate types under combined stress states.
- Anchoring:Heavy equipment baseplates and structural column connections requiring combined shear and tension resistance with documented seismic performance.
Fastening commands the broadest specification footprint; sealing applications are expanding most quickly as water ingress remediation intensifies across aging European tunnel portfolios.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Belgian and Dutch petrochemical clusters supply epoxy resin feedstocks that anchor formulation activity across northwestern Europe. German transport investment programs and Alpine tunneling corridors concentrate specification-grade demand. Regulatory divergence between national approval bodies fragments product portfolios across member states.
Germany
Federal bridge retrofit programs specify DIN-certified epoxy systems for seismic-rated connections. DIBt technical approvals mandate documented cure temperature ranges and sustained load validation. The Rhine-Ruhr industrial corridor hosts captive resin compounding facilities serving infrastructure contractors with just-in-time cartridge supply.
Switzerland
Transalpine tunneling projects demand hybrid systems with sub-zero temperature cure validation. Swissmedic-aligned construction product regulations require third-party performance certification for public infrastructure tenders. The Gotthard Base Tunnel corridor anchors specification pull-through for rapid-cure formulations serving continuous excavation schedules.
France
High-speed rail modernization and nuclear facility maintenance drive demand for corrosion-resistant anchoring systems. CSTB technical assessments create divergent certification burdens from German DIBt protocols, complicating cross-border product standardization. The Paris-Saclay research cluster concentrates ETAG-compliant testing laboratories serving specification-grade manufacturers.
Italy
Aging highway bridge portfolios require seismic upgrade fastening systems with verified pull-out performance. National transposition of Eurocode 2 anchoring provisions lags northern member states, delaying product validation protocol alignment. The Milan-Turin industrial corridor concentrates automotive manufacturing line reconfigurations using rapid-cure acrylic systems.
Poland
EU cohesion fund absorption accelerates highway and rail corridor modernization with specification-grade hybrid systems. REACH compliance evolution on styrene content pressures domestic distributors to source certified low-VOC formulations. The Silesian industrial region hosts emerging distribution hubs serving eastern European infrastructure buildout.
Europe Chemical Anchors Market Competitive Landscape
Global majors compete with regional champions across certification density and technical support embedding. The vendor base stratifies into three tiers: integrated construction chemical conglomerates with captive resin supply, specialized fastening system houses with DIN-focused approval portfolios, and regional distributors serving economy-tier polyester segments. Dominant competitive moves include backward integration into resin compounding and strategic embedding of application engineering teams with major contractors.
Within the integrated construction chemical tier, Sika AG and Hilti Corporation exemplify divergent channel strategies. Sika anchors its position through distribution density in Alpine tunneling corridors, while Hilti differentiates via direct-channel technical support teams embedded with major German contractors. Among specialized fastening houses, Fischer Group represents the captive resin compounding archetype controlling cure profiles across Nordic temperature extremes. Illinois Tool Works Inc. sits within the diversified industrial conglomerate category leveraging cross-divisional procurement relationships.
| Leading Market Players |
|---|
| Fischer Group |
| Illinois Tool Works Inc. |
| Sika AG |
| HALFEN |
| Mungo AG |
| Hilti Corporation |
| Simpson Strong-Tie Company, Inc. |
| Chemfix |
| Henkel AG & Co. KGaA |
| Others |
Value Network & Pricing Analysis
German federal transport procurement programs concentrate specification-grade demand for DIN-certified epoxy systems, anchoring a project-based pricing model where technical approval status commands premium positioning over commodity resin tiers.
Pricing Analysis
Warranty-bundled installation supervision and pull-out testing certification separate premium epoxy quotations from unbundled polyester cartridge pricing. Three-tier pricing structure across certification-grade, performance-validated, and economy resin tiers reflects DIN approval investment and cure-temperature validation range. Cost compression in polyester segments intensifies as REACH-compliant low-VOC formulations raise input costs without corresponding specification pull-through. Automotive manufacturing line procurement exhibits the strongest price sensitivity; infrastructure contractors with federal mandate backing accept premium positioning for seismic-rated hybrid systems.
Supply Chain Analysis
Cartridge collection and hardener paste refurbishment flows remain underdeveloped, with most spent resin containers entering construction waste streams rather than reverse logistics networks. Epoxy resin feedstock production concentrates in Belgian and Dutch petrochemical clusters, with amine hardener sourcing anchored in German specialty chemical manufacturing. Naphtha derivative volatility and force majeure exposure at Rotterdam-Antwerp hub facilities present structural supply risk. Distribution runs through construction chemicals wholesalers serving regional contractor networks, with direct-channel technical support reserved for flagship infrastructure accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Competitive positioning in Europe chemical anchors is consolidating around backward integration into resin compounding and captive control over cure profile customization, with upstream chemical capabilities becoming the decisive margin lever.
For Market Incumbents: Hedge against hybrid formulation margin erosion by securing captive amine hardener supply agreements with Rhine-Ruhr specialty chemical producers. Deepen DIBt approval portfolios to lock out non-compliant competitors from German federal bridge retrofit pipelines. Counter mechanical anchor substitution in commercial construction through embedded application engineering teams with major French and Italian contractors.
For New Entrants and Emerging Players: Begin with Polish and Romanian highway modernization corridors where EU cohesion fund absorption is accelerating specification-grade hybrid demand ahead of established distribution density. Target rapid-cure acrylic systems for Italian automotive manufacturing line reconfigurations where DIN certification is not mandatory. Pursue BIM-integrated anchor selection tool partnerships with Nordic structural engineering consultancies to capture design-phase specification influence.
For Investors and Strategic Acquirers: The window for entry favors mid-cap fastening system houses with concentrated DIN-focused approval portfolios and underexploited Alpine tunneling corridor relationships. Long-term viability hinges on REACH compliance execution ahead of ECHA styrene restriction deadlines. Monitor Eurocode 2 national transposition timelines as the signal for product validation protocol alignment and cross-border market access expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Compounding | Fischer Group's captive cure profile control across Nordic temperature extremes demonstrates margin protection. |
| DIBt Certification Portfolio Expansion | German federal transport procurement mandates DIN-approved systems with documented cure temperature ranges. |
| BIM-Integrated Specification Tools | Autodesk and Nemetschek workflow embedding displaces traditional distributor influence over project decisions. |
| Low-VOC Hybrid Formulation Development | EU Green Deal embodied carbon requirements exclude non-compliant suppliers from public tender pipelines. |
| Alpine Tunneling Distribution Density | Sika AG's construction chemicals network in Swiss and Austrian corridors anchors specification pull-through. |
Research Methodology
Multi-period observation of DIBt approval timelines, REACH compliance evolution, and Eurocode 2 national transposition progress anchored the trend analysis, supplemented by interviews with resin formulation R&D directors, infrastructure procurement officers at German federal transport agencies, construction chemicals distribution channel partners, and Alpine tunneling project engineers. Secondary validation drew from ECHA regulatory filings, ETAG technical assessment databases, Cefic construction chemicals sector reports, and customs trade data on epoxy resin feedstock flows. Bottom-up cartridge volume estimates triangulated against top-down infrastructure investment program allocations.
Segment-weighting across product type, end-use industry, packaging format, and regional certification hub distribution shaped the analytical framework across the projection horizon. CAGRs derived from infrastructure retrofit mandate intensity, Green Deal procurement threshold expansion, and hybrid formulation displacement curves. Forecast inputs included Rhine-Ruhr petrochemical capacity utilization rates and EU cohesion fund absorption velocity in Eastern European member states.
REACH restriction acceleration on styrene and isocyanate content, Eurocode 2 transposition delays in Southern European markets, and naphtha feedstock price volatility are the dominant revision risks to modeled outputs. Practitioners should monitor ECHA regulatory consultation timelines and national building code amendment publications for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
Anti-Seize Compounds Market
Adhesives & Sealants
Isobornyl Acrylate Market
Adhesives & Sealants
Wood to Metal Glue Market
Adhesives & Sealants
US Tile Adhesive Market
Adhesives & Sealants
Epoxy Active Diluent Market
Adhesives & Sealants
Global Isobutyl Acrylate Market
Adhesives & Sealants
Global Footwear Adhesives Market
Adhesives & Sealants
Global Adhesive Coating Market
Adhesives & Sealants
Hydrophobic Pore-Blocking Agents for Waterproof Concrete Market
Adhesives & Sealants
High Temperature Sealants Market
Adhesives & Sealants
North America & Europe Adhesives and Sealants Market
Adhesives & Sealants
Australia Sealants Market
Adhesives & Sealants
Global Human Fibrin Glue Market
Adhesives & Sealants
Specialty Adhesives Market
Adhesives & Sealants
Indonesia Adhesives Market
Adhesives & Sealants
Industrial Adhesives Market