
 Global Adhesives Market | 2026-2036
Global Adhesives Market Size, Share, and Industry Trends Forecast 2026-2036
Global Adhesives Market Intelligence
Reactive hot-melt and UV-curable chemistries is rewriting assembly protocols across transportation and electronics manufacturing. Henkel AG & Co. KGaA leverages its European R&D base to dominate automotive structural bonding applications. 3M anchors its position through tape-adhesive hybrid platforms serving electronics miniaturization. H.B. Fuller Company specializes in packaging adhesives with formulated hot-melts that compete on speed-to-set and bond flexibility.
Adhesives are non-metallic substances applied to substrate surfaces that develop structural or semi-structural attachment through chemical polymerization, physical drying, or pressure-sensitive tack, with formulations typically comprising 40-60% base polymer, 20-35% tackifier resin, and 5-15% curing agent or catalyst by weight. Their primary industrial purpose replaces mechanical fasteners to reduce weight, distribute stress, and enable bonding of dissimilar materials. Acrylic formulations lead consumer and electronics applications where optical clarity and rapid room-temperature cure offset lower shear strength versus epoxies. Polyurethane adhesives occupy the fastest-growing position in automotive and construction segments due to flexibility across temperature extremes and compatibility with composite substrates. Epoxy systems retain the highest margin pools in aerospace and medical end uses where certification cycles and performance specifications create substantial barriers to substitution.
REACH in Europe, EPA regulations in the United States, and China's MEE standards collectively restrict solvent content and mandate hazard communication, forcing reformulation investments that favor suppliers with integrated resin production. ECHA substance-of-very-high-concern listings have eliminated specific isocyanate and formaldehyde-releasing chemistries from multiple adhesive categories, redirecting R&D spending toward bio-based feedstocks and waterborne alternatives. Stakeholders must monitor regulatory divergence between jurisdictions, as compliance strategies effective in one geography may not satisfy emerging restrictions elsewhere, particularly for products destined for medical device or food-contact applications where FDA and EMA pathways differ substantially.
Market Dynamics
Automotive lightweighting mandates and electronics miniaturization cycles are compressing cure times and elevating performance specifications across adhesive categories, forcing suppliers to retool resin platforms faster than certification cycles permit.
Growth Catalysts
- REACH SVHC listings:ECHA restrictions on isocyanate and formaldehyde-releasing chemistries are redirecting R&D budgets toward waterborne and bio-based alternatives, opening substitution windows for compliant suppliers.
- EV battery assembly:Thermal interface bonding requirements in electric vehicle powertrains are generating demand for thermally conductive structural adhesives with dielectric stability.
- China's eastern manufacturing corridor:Electronics and EV assembly clusters in Jiangsu and Guangdong provinces are concentrating high-volume procurement of UV-curable and reactive hot-melt systems.
Market Restraints
- Petrochemical feedstock volatility:Crude-derived tackifier resins and isocyanate precursors expose margins to naphtha and propylene price swings without full pass-through mechanisms.
- Specialty resin supply concentration:Controlled production of high-purity epoxy hardeners and acrylic monomers concentrates in German and Japanese chemical complexes, creating single-source vulnerabilities.
- Cure-rate limitations:Two-part epoxy systems require 24-72 hour fixture times that conflict with automotive and electronics takt-time targets, constraining penetration in high-throughput lines.
Strategic Opportunities
- India's PLI scheme for electronics:Production-linked incentives for semiconductor and mobile device manufacturing are attracting adhesive suppliers to establish local formulation capacity.
- UV-LED convergence with robotics:Instant-cure adhesive dispensing integrated with automated assembly cells enables bonding of heat-sensitive substrates in medical device production.
- SAMR green product certification:China's national standard for environmentally friendly adhesives creates preferential procurement status for low-VOC formulations in government-backed infrastructure projects.
Industry Challenges
- Polymer chemist scarcity:Formulation expertise combining rheology control, substrate compatibility, and regulatory compliance is concentrating at mid-career specialists nearing retirement.
- Aerospace certification timelines:FAA and EASA qualification protocols for structural bonding in commercial aviation extend 18-36 months, freezing product iterations and locking out iterative improvements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Adhesives Market |
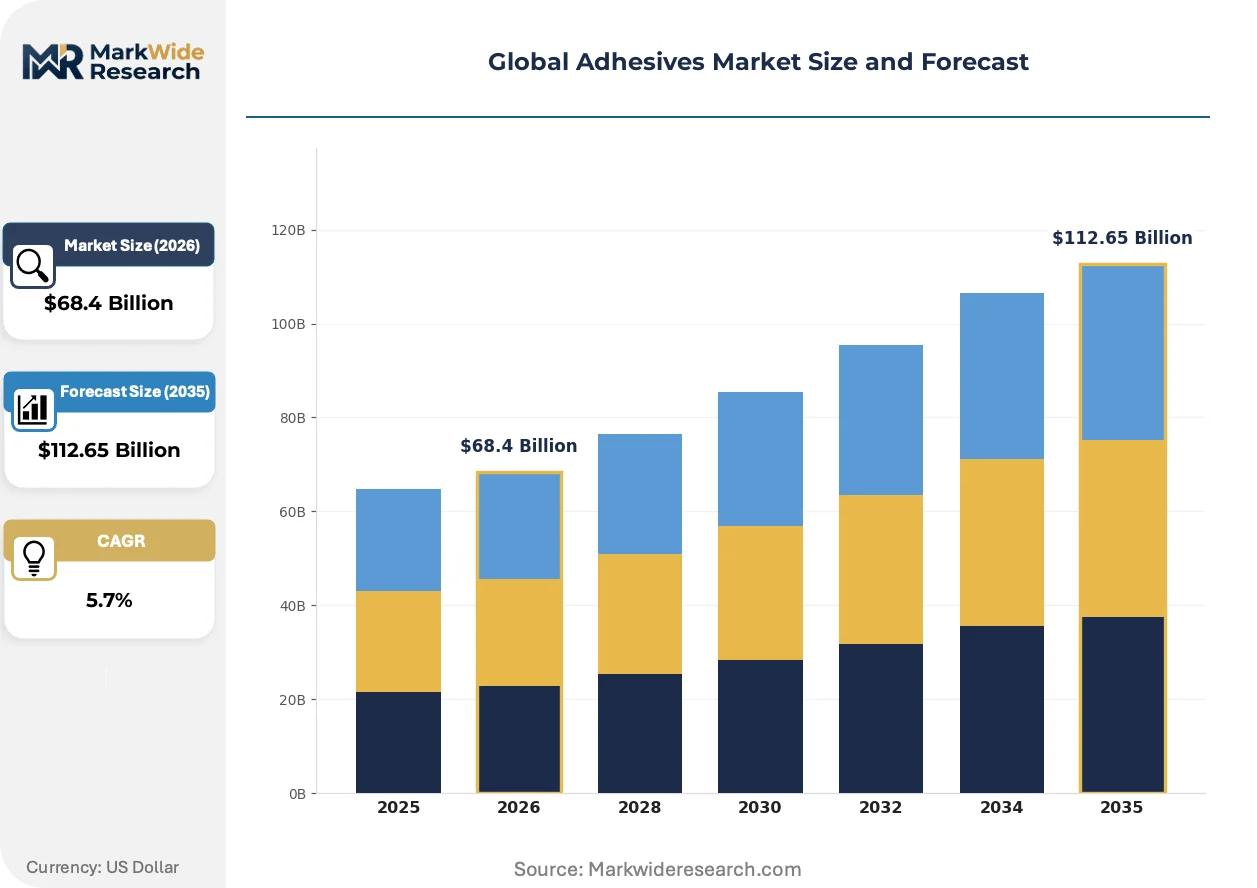
| Market Size in 2026 | $68.4 Billion |
| Market Size in 2035 | $112.65 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyurethane, Epoxy, Acrylic, Silicone Application: Automotive, Construction, Packaging, Electronics Form: Liquid, Solid, Paste, Film End User: Manufacturing, Furniture, Aerospace, Medical |
| Companies Covered | Henkel AG & Co. KGaA, 3M, H.B. Fuller Company, Sika AG, Dow Inc., Arkema, Huntsman Corporation, Avery Dennison Corporation, Wacker Chemie AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Adhesives Market Strategic Shifts & Innovations
Reactive chemistries and curing technologies are compressing assembly cycle times while regulatory pressure on volatile organic compounds forces simultaneous reformulation of legacy resin platforms.
UV-LED curable acrylics is rendering obsolete thermal-cure systems in electronics display bonding. Smartphone and tablet manufacturers in South Korea and Taiwan are converting assembly lines to instant-cure stations. The technology is rendering obsolete batch oven processes that previously required 30-60 minute thermal cycles, collapsing work-in-process inventory and freeing factory floor space.
China's MEE standards on industrial VOC emissions are tightening solvent-content thresholds in adhesive formulations used across construction and packaging sectors. Manufacturers serving the domestic market are accelerating transitions to hot-melt and waterborne platforms ahead of enforcement deadlines. Medical device exporters face additional compliance layers as SAMR requirements diverge from FDA 510(k) pathways for skin-contact adhesives.
Direct procurement from formulation specialists is displacing distributor intermediaries in high-volume automotive and electronics accounts. Tier-1 suppliers in Germany and Japan are establishing vendor-managed inventory programs with adhesive producers to secure supply continuity and technical service proximity. This pattern concentrates procurement leverage with buyers possessing internal materials engineering capabilities, marginalizing smaller assemblers dependent on distributor technical support.
Global Adhesives Market Segmentation
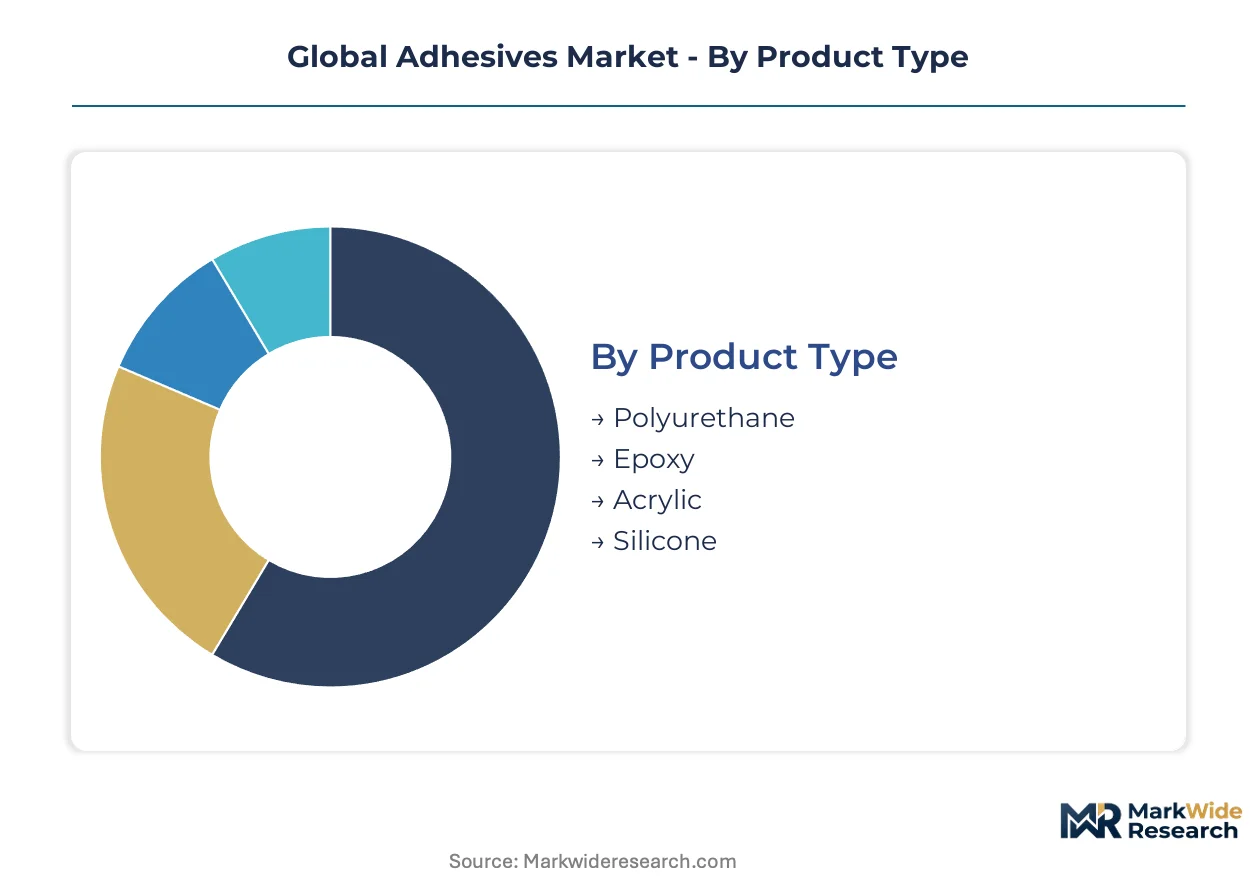
Adhesive segmentation reveals divergent value capture across cure-rate requirements and certification intensity. Cycle-time compression in automotive and electronics assembly favors segments with instant or ambient cure profiles, while aerospace and medical end uses reward segments with extended qualification barriers.
Product Type:
Polyurethane and acrylic formulations turn inventory fastest through room-temperature cure, while epoxy and silicone segments lock capital in longer production cycles.
- Polyurethane:Two-part systems combining isocyanate prepolymers with polyol curatives deliver flexibility across temperature extremes from -40°C to 120°C. Demand concentrates in German automotive lightweighting programs bonding composite body panels, where crash-durability specifications and takt-time pressures favor rapid-fixture formulations. REACH SVHC restrictions on residual isocyanate monomers are forcing reformulation toward blocked prepolymer architectures.
- Acrylic:UV-curable and cyanoacrylate instant-bonding chemistries achieve fixture in seconds under LED irradiation or ambient moisture. South Korean electronics assemblers in Gyeonggi Province specify optical-grade acrylics for display lamination, where clarity above 90% transmittance and low yellowing index override shear strength considerations. Monomer supply concentration in Japanese petrochemical complexes creates feedstock vulnerability.
- Epoxy:Rigid thermoset networks formed from bisphenol-A or bisphenol-F resins with amine or anhydride hardeners. Chinese wind turbine blade manufacturers specify toughened epoxies for structural bonding of glass-fiber spar caps.
- Silicone:Room-temperature-vulcanizing systems based on polydimethylsiloxane with condensation or addition cure chemistry. Indian medical device exporters specify platinum-catalyzed grades for skin-contact applications under CDSCO guidance.
Epoxy dominates installed base across certified structural applications. Polyurethane is where expansion concentrates as OEMs balance flexibility with process speed.
Application:
Volume scales inversely with margin across these four end-use clusters, with packaging and construction commanding lowest per-kilogram pricing and electronics extracting premium for miniaturization tolerance.
- Automotive:Structural bonding of aluminum-intensive body-in-white assemblies and battery module thermal interface materials. Japanese OEMs in Nagoya and Toyota City specify crash-stable adhesives with 25-35 MPa lap shear strength for front-end modules, where mechanical rivet elimination saves 4-7 kilograms per vehicle. Dual carbon compliance timelines are accelerating solvent-free transitions.
- Electronics:Die attach, underfill, and display lamination requiring precision dispense and low outgassing. Taiwan Semiconductor Manufacturing Company suppliers in Hsinchu demand adhesives with ionic purity below 10 ppm for flip-chip packaging, where corrosion of aluminum bond pads threatens yield. UV-LED cure stations are displacing batch ovens.
- Construction:Structural glazing, flooring installation, and insulation panel bonding. German facade engineers specify movement-capable silicones for curtain wall adhesion.
- Packaging:Case and carton sealing with hot-melt and waterborne systems. Brazilian corrugated converters favor metallocene polyolefin hot-melts for freezer-grade adhesion.
Construction dominates installed base by volume. Electronics is where expansion concentrates as semiconductor packaging complexity intensifies.
Form:
Physical state determines capital equipment requirements and skilled labor intensity, with liquid systems demanding precision dispense robotics and solid forms enabling manual application.
- Liquid:Low-viscosity systems for spray, roll, or precision needle dispense. US automotive Tier-1 suppliers in Michigan operate closed-loop metering systems for two-part polyurethane windshield bonding, where bead geometry consistency determines leak-test pass rates. EPA VOC limits are restricting solvent-borne liquid formulations.
- Solid:Hot-melt pellets, sticks, and slugs for extrusion or handheld application. Italian furniture manufacturers in Brianza specify EVA and polyamide hot-melts for edgebanding, where open time and set speed determine line throughput.
- Paste:Thixotropic formulations for vertical surface application and gap filling. UAE construction contractors specify non-sag polyurethanes for cladding panel installation.
- Film:Unsupported or carrier-supported adhesive layers for lamination and surface protection. Japanese flexible circuit manufacturers in Yamanashi specify acrylic film adhesives for coverlay bonding.
Liquid dominates installed base across industrial automation. Film is where expansion concentrates as electronics miniaturization demands thickness control below 25 micrometers.
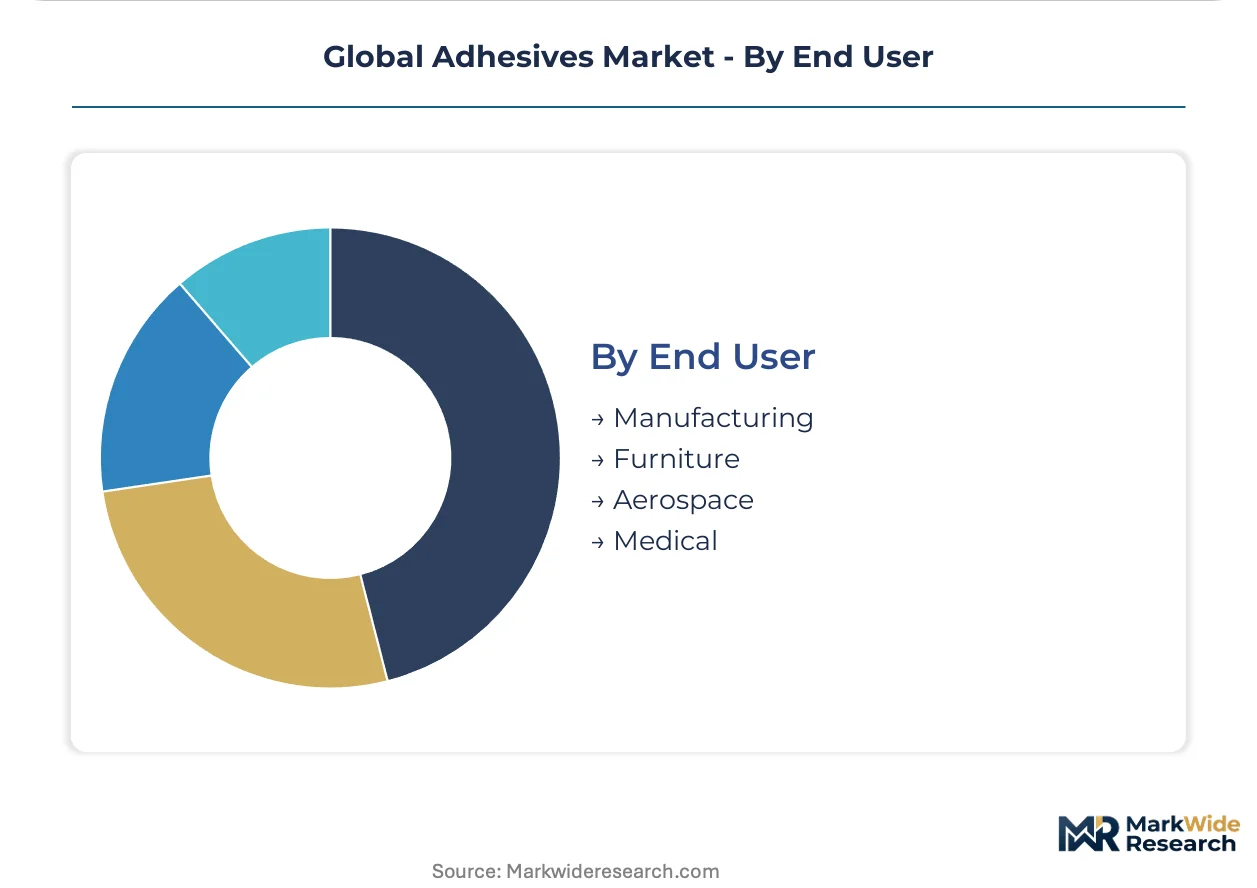
End User:
Certification burden and technical service intensity separate these four customer types, with aerospace and medical requiring 18-36 month qualification cycles that freeze supplier relationships.
- Manufacturing:High-volume assembly across automotive, appliance, and industrial equipment. German whitegoods producers in Bielefeld specify moisture-cure polyurethanes for refrigerator cabinet bonding, where foam compatibility and thermal cycling resistance determine warranty exposure.
- Furniture:Wood, panel, and upholstery bonding with emphasis on aesthetics and manual application speed. Polish upholstered furniture exporters specify low-odor waterborne contact cements to meet ECHA restrictions on neoprene solvent systems.
- Aerospace:Primary and secondary structural bonding under FAA and EASA qualification. French aerostructures suppliers in Toulouse specify film adhesives for composite fuselage sections, where porosity control and out-time tolerance govern autoclave scheduling.
- Medical:Skin-contact, device assembly, and sterile packaging applications. US contract manufacturers in Minnesota specify ISO 10993-tested cyanoacrylates for catheter assembly, where biocompatibility and sterilization stability override cost considerations.
Manufacturing dominates installed base by consumption volume. Medical is where expansion concentrates as wearable device proliferation multiplies skin-contact adhesive specifications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German adhesive exports supply automotive assembly lines across Central Europe and North America, with specialty formulations commanding premium pricing in structural bonding applications.
United States
EPA VOC regulations under the National Emission Standards for Hazardous Air Pollutants are accelerating solvent-to-hot-melt conversions in packaging and construction adhesives. Michigan-based automotive Tier-1 suppliers operate closed-loop metering systems for polyurethane windshield bonding, where bead geometry consistency determines leak-test pass rates. Minnesota medical device contract manufacturers specify ISO 10993-tested formulations for catheter assembly.
Germany
REACH SVHC listings on residual isocyanate monomers are forcing polyurethane reformulation toward blocked prepolymer architectures. ECHA restrictions on formaldehyde-releasing chemistries redirect R&D budgets toward waterborne alternatives. Bielefeld whitegoods producers specify moisture-cure systems for refrigerator cabinet bonding, where foam compatibility and thermal cycling resistance determine warranty exposure.
China
MEE standards on industrial VOC emissions tighten solvent-content thresholds in construction and packaging adhesive formulations. SAMR green product certification creates preferential procurement status for low-VOC formulations in government-backed infrastructure projects. Jiangsu and Guangdong electronics and EV assembly clusters concentrate high-volume procurement of UV-curable and reactive hot-melt systems.
Japan
METI carbon neutrality roadmaps accelerate solvent-free formulation transitions in automotive and electronics manufacturing. Nagoya and Toyota City OEMs specify crash-stable adhesives with 25-35 MPa lap shear strength for aluminum-intensive front-end modules. Yamanashi flexible circuit manufacturers specify acrylic film adhesives for coverlay bonding applications.
India
PLI scheme production-linked incentives for semiconductor and mobile device manufacturing attract adhesive suppliers to establish local formulation capacity. CDSCO guidance governs skin-contact medical device applications for export markets. Maharashtra and Karnataka electronics manufacturing zones drive procurement of precision dispense systems for die attach and underfill operations.
Global Adhesives Market Key Industry Players
Channel-controlling players compete with product-specialist players across formulation categories, with the market consolidating around suppliers possessing integrated resin production and regulatory compliance capabilities. Three archetypes dominate: diversified chemical conglomerates with captive raw material supply, mid-cap formulation specialists serving single end-use verticals, and regional compounders competing on logistics proximity. M&A activity concentrates on acquiring bio-based feedstock capabilities and UV-cure technology platforms, while capacity expansion targets China's eastern manufacturing corridor and India's PLI-subsidized electronics zones.
Within the diversified chemical conglomerate tier, Henkel AG & Co. KGaA and 3M exemplify players leveraging European and North American R&D bases to dominate automotive structural bonding and electronics miniaturization applications respectively. H.B. Fuller Company occupies a position among mid-cap formulation specialists competing on speed-to-set and bond flexibility in packaging segments. These three anchors represent distinct strategic postures: integrated resin production with regulatory compliance infrastructure, tape-adhesive hybrid platform development, and formulated hot-melt specialization for high-throughput packaging lines.
| Leading Market Players |
|---|
| Henkel AG & Co. KGaA |
| 3M |
| H.B. Fuller Company |
| Sika AG |
| Dow Inc. |
| Arkema |
| Huntsman Corporation |
| Avery Dennison Corporation |
| Wacker Chemie AG |
| Others |
Cost & Logistics Intelligence
Petrochemical feedstock volatility in naphtha and propylene markets determines both margin compression in commodity-grade formulations and the geographic clustering of high-purity resin production. This volatility widens pricing spreads between solvent-borne legacy systems and waterborne alternatives while concentrating supply chain investments in integrated chemical complexes with captive raw material supply.
Pricing Analysis
UV-curable next-generation acrylics command substantial premiums over thermal-cure prior-generation systems, with reactive hot-melt current-generation formulations occupying a mid-tier position. Three-tier pricing structure across aerospace-certified epoxies, automotive structural polyurethanes, and packaging hot-melts reflects certification intensity and cure-rate performance. Pricing pressure stems from REACH SVHC compliance costs and bio-based feedstock premiums that compress margins in standard-grade segments. Packaging converters exhibit highest price sensitivity due to volume procurement leverage, while medical device manufacturers demonstrate lowest sensitivity given biocompatibility certification requirements.
Supply Chain Analysis
Contract manufacturing concentration resides with Foxconn and Pegatron electronics assembly networks, plus Magna and Continental automotive Tier-1 systems. Raw material supply concentrates in German and Japanese chemical complexes for high-purity epoxy hardeners, Chinese petrochemical bases for acrylic monomers, and US Gulf Coast facilities for isocyanate precursors. Feedstock dependency rests on crude-derived tackifier resins and propylene oxide derivatives. Single-source vulnerability in specialty resin hardeners creates qualification bottlenecks. Distribution runs through direct vendor-managed inventory programs with high-volume OEMs, displacing traditional distributor channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Adhesive markets are approaching a platform-economics inflection where UV-LED cure standardization and robotics integration create winner-take-most dynamics. Interoperability between dispensing equipment and formulation chemistries is locking in supplier relationships before certification cycles complete.
For Market Incumbents: Insulate margin pools by securing captive supply of bio-based feedstocks ahead of ECHA substance restrictions, and deepen technical service proximity through embedded formulation labs at customer assembly sites. Waterborne polyurethane R&D investments counter isocyanate regulatory pressure. Channel control through vendor-managed inventory programs locks out reformulation switching. For New Entrants and Emerging Players: Pursue white-space opportunities in India's PLI-subsidized electronics zones where local formulation capacity remains underdeveloped, and target medical device skin-contact segments where CDSCO export pathways create qualification arbitrage. Precision dispense system integration offers a go-to-market angle against incumbent technical service models. For Investors and Strategic Acquirers: REACH SVHC expansion timelines reshape the acquisition landscape toward compliant waterborne and bio-based technology platforms. Five-to-ten year viability favors suppliers with integrated resin production and regulatory affairs infrastructure over pure formulation compounders. Acquisition target archetype: mid-cap specialists with SAMR green certification and UV-cure patent positions. Signal to monitor: ECHA substance-of-very-high-concern listing velocity for additional isocyanate restrictions.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bio-based Feedstocks | ECHA SVHC restrictions on petrochemical precursors elevate compliant resin supply security. |
| UV-LED Cure Platform Standardization | South Korean electronics assemblers in Gyeonggi Province demand instant-cure dispensing interoperability. |
| Vendor-Managed Inventory Expansion | German automotive Tier-1 suppliers in Bielefeld and Stuttgart prioritize supply continuity over unit pricing. |
| Medical Device Certification Investment | ISO 10993 and FDA 510(k) pathways create margin pools inaccessible to commodity compounders. |
| Joint Venture in India's PLI Zones | Maharashtra and Karnataka electronics manufacturing clusters require localized formulation capacity. |
Research Approach
Initial hypotheses were tested against primary input from adhesive R&D directors, automotive Tier-1 procurement leads, electronics manufacturing engineers, and medical device regulatory affairs specialists, and refined through secondary validation across customs trade data, ECHA substance registration databases, SEC 10-K chemical segment disclosures, and ACC industry shipment reports. Bottom-up volume estimates from end-use consumption patterns were triangulated against top-down capacity assessments from major chemical producers.
Demand-supply balance modeling across the projection horizon incorporated cure-rate technology generations, regulatory compliance tier segmentation, and regional manufacturing cluster concentration. CAGRs were derived from segment-level volume trajectories weighted by value-per-kilogram differentials. Industry-specific forecast inputs included EV battery thermal interface material specifications and semiconductor packaging ionic purity thresholds.
Sensitivities concentrate around ECHA SVHC listing velocity, naphtha-propylene feedstock spreads, and automotive takt-time compression targets. Forecasts reflect assumptions regarding regulatory enforcement timelines and substitution elasticity in certified applications. Quarterly review of REACH substance evaluation schedules and MEE VOC emission audit results is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
Thailand Sealants Market
Adhesives & Sealants
Amine Curing Agents Market
Adhesives & Sealants
Dibutyl Maleate (DBM) Market
Adhesives & Sealants
Europe Construction Adhesives Market
Adhesives & Sealants
Flooring Installation Adhesives Market
Adhesives & Sealants
Paper-Backing Abrasive Adhesive Discs Market
Adhesives & Sealants
North America Contact Adhesives Market
Adhesives & Sealants
Asia-Pacific Adhesives Market
Adhesives & Sealants
Saudi Arabia Adhesives Market
Adhesives & Sealants
Middle East & Africa Adhesives and Sealants Market
Adhesives & Sealants
Flooring Adhesive Market
Adhesives & Sealants
North America Acrylic Adhesives Market
Adhesives & Sealants
Europe Polyurethane Adhesives Market
Adhesives & Sealants
Joint Sealants Market
Adhesives & Sealants
Global Medical Adhesives and Sealants Market
Adhesives & Sealants
Asia-Pacific Urea-Formaldehyde Glues and Resins Market