
 Tobacco and Cigarette Adhesives Market | 2026-2036
Tobacco and Cigarette Adhesives Market Size, Share, and Industry Trends Forecast 2026-2036
Tobacco and Cigarette Adhesives Market Insights
Single-source procurement of specialty tobacco adhesives is recalibrating toward multi-source qualification programs as manufacturers seek supply resilience. Henkel leverages its European formulation expertise to anchor premium filter-assembly contracts across regulated markets. HB Fuller competes through backward integration into ethylene-vinyl acetate supply chains, sustaining cost advantages in hot melt categories. Pidilite Industries dominates South Asian distributor networks, controlling access points for regional cigarette manufacturers.
Tobacco and cigarette adhesives comprise thermoplastic and thermoset formulations engineered for bonding paper, filter tow, and packaging substrates at speeds exceeding 8,000 cigarettes per minute. These adhesives must maintain tack stability across humidity ranges of 40-70% RH while meeting burn-additive restrictions and food-contact migration limits. Hot melt adhesives lead volume share due to instant set times compatible with high-speed tipping and plug-wrap operations, though water-based systems are gaining share where volatile organic compound thresholds tighten. Pressure-sensitive adhesives occupy niche positions in labeling applications where repositionability commands price premiums over permanent bonding chemistries.
FDA oversight of tobacco product constituents extends to adhesive residuals and pyrolysis byproducts, compelling reformulation investments from suppliers serving US manufacturers. REACH registration requirements and the EU Green Deal's chemical sustainability targets are restricting certain solvent-based formulations across European supply chains. China's SAMR enforces GB standards on adhesive components in consumer goods, including tobacco packaging materials. Stakeholders must monitor evolving combustion-product testing protocols and pre-qualify alternative chemistries before regulatory deadlines eliminate incumbent formulations from approved substance lists.
Market Dynamics
Filter-assembly line speeds now exceed 8,000 cigarettes per minute, forcing adhesive suppliers to engineer thermoplastic formulations with sub-100 millisecond set times without sacrificing tack stability across 40-70% relative humidity bands.
Growth Catalysts
- China's SAMR enforcement of GB standards:Domestic cigarette manufacturers are qualifying local adhesive suppliers to replace imported formulations, accelerating technical capability building among regional specialty chemical producers.
- Hot melt instant-set chemistry:Tipping and plug-wrap operations demand adhesives with zero open time, pushing EVA and metallocene polyolefin formulations into volume leadership across high-speed assembly lines.
- Filter tow bonding performance thresholds:Acetate fiber-to-paper adhesion requirements are tightening as slim and super-slim cigarette formats multiply, creating specification premiums for suppliers mastering low-additive, high-shear formulations.
Market Restraints
- Ethylene-vinyl acetate feedstock volatility:Crude-linked monomer pricing swings compress margin predictability for hot melt specialists lacking backward integration into polymer supply chains.
- REACH authorization timelines:ECHA substance evaluation windows extending 18-36 months delay reformulation launches, freezing incumbent chemistry commitments while alternatives await pre-registration.
- Water-based curing speed ceilings:Aqueous adhesive moisture evaporation rates cap line speeds at roughly 60% of hot melt equivalents, constraining adoption in tipping operations despite VOC compliance advantages.
Strategic Opportunities
- India's BIS certification pathway:Unmet demand from domestic cigarette and bidi manufacturers favors suppliers establishing local blending facilities with in-house testing laboratories.
- Biodegradable filter adhesion:Cellulose acetate replacement fibers from wood pulp and hemp require novel chemistries with tunable biodegradation profiles aligned to compostability certifications.
- Pressure-sensitive label repositionability:Premium tobacco packaging segments value clean-removal adhesives for promotional over-label applications, commanding price multiples over permanent bonding alternatives.
Industry Challenges
- Pyrolysis byproduct characterization:FDA combustion-product testing protocols demand adhesive suppliers fund third-party toxicology studies to document thermal decomposition profiles under simulated smoking conditions.
- Legacy water-based line conversion:Capital expenditure for hot melt tank, hose, and applicator retrofits strains mid-tier manufacturers balancing compliance deadlines against equipment replacement cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tobacco and Cigarette Adhesives Market |
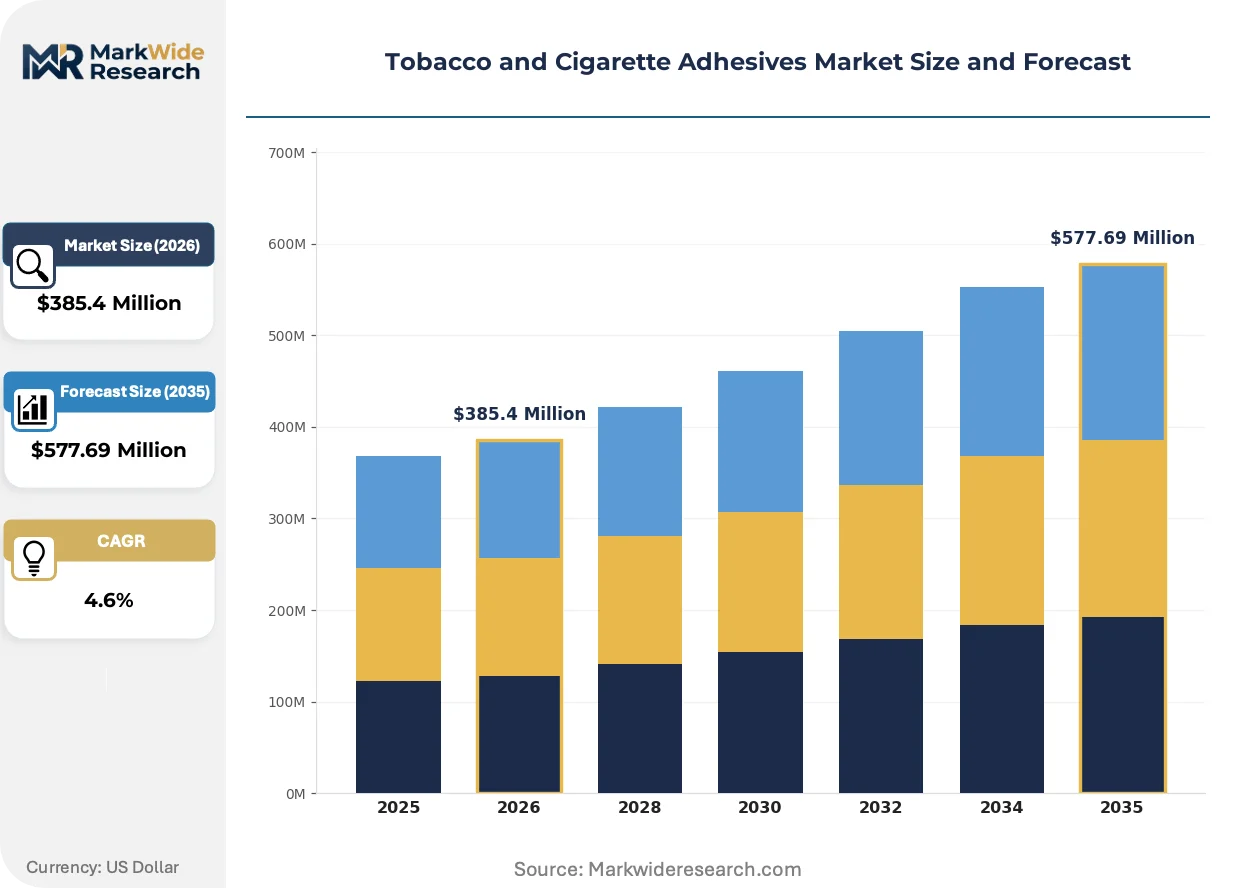
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $577.69 Million |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hot Melt Adhesives, Water-Based Adhesives, Solvent-Based Adhesives, Pressure-Sensitive Adhesives End User: Manufacturers, Distributors, Retailers, Wholesalers Application: Cigarette Packaging, Filter Assembly, Wrapper Bonding, Labeling Formulation: Polymeric, Natural, Synthetic, Hybrid |
| Companies Covered | Techbond Group, Siag Chemicals Group, Henkel, Helios Kemostik, HB Fuller, Nordson, Intercol Adhesives, DuPont, Pidilite Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tobacco and Cigarette Adhesives Market Trends and Innovations
Adhesive formulation strategies are bifurcating between instant-set thermoplastics for speed-critical tipping and precision-controlled water-based systems for burn-additive-restricted markets.
Metallocene-catalyzed polyolefin hot melts are modularizing filter-assembly bonding architectures by enabling discrete temperature zones within single production lines. Major cigarette manufacturers in Germany and Poland are retrofitting existing EVA-based systems with narrow-melt-range metallocene grades to isolate high-temperature plug-wrap zones from cooler tipping stations. This thermal zoning is modularizing equipment design standards, allowing OEMs to sell configurable line segments rather than integrated monolithic systems.
REACH's restriction roadmap for persistent organic pollutants is forcing reformulation of certain tackifier resins used in cigarette tipping adhesives. ECHA's 2023-2025 evaluation window targets rosin ester derivatives with elevated PAH content, compelling suppliers to accelerate hydrogenated hydrocarbon resin substitution programs. European filter-assembly specialists are pre-qualifying alternative tackifier systems ahead of sunset dates to avoid supply discontinuities during authorization transitions.
Multi-source qualification programs are displacing single-source procurement contracts among tier-one cigarette manufacturers. Procurement teams at major producers in China and Indonesia now mandate dual-approved suppliers for critical tipping and plug-wrap chemistries, spreading volume across qualified alternatives to mitigate concentration risk. This supplier portfolio approach is most visible in filter-tow bonding applications where line stoppage costs exceed adhesive material spend by orders of magnitude.
Tobacco and Cigarette Adhesives Market Segmentation
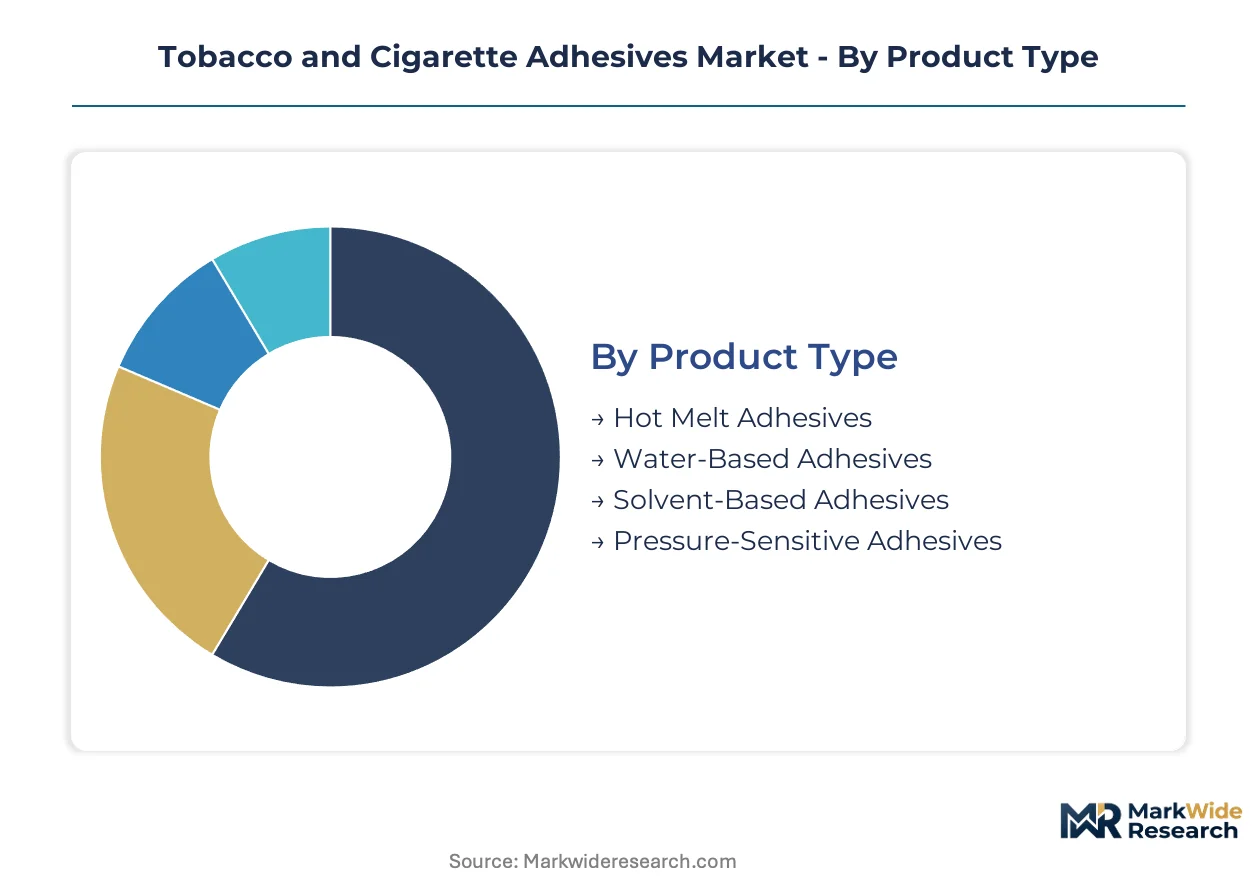
Adhesive specification varies sharply across cigarette manufacturing workflows, with tipping speeds, burn-additive restrictions, and filter-format complexity driving divergent formulation requirements. Procurement teams segment suppliers by set-time performance, regulatory pre-qualification status, and humidity-band stability rather than chemistry alone.
Product Type:
Equipment upgrade cycles dominate adhesive selection, as manufacturers weigh hot-melt tank retrofits against water-based line preservation for VOC compliance.
- Hot Melt Adhesives:Ethylene-vinyl acetate and metallocene polyolefin formulations deliver sub-100 millisecond set times essential for tipping lines exceeding 8,000 cigarettes per minute. Demand concentrates in Germany and Poland where thermal zoning retrofits isolate high-temperature plug-wrap stations from cooler tipping zones.
- Water-Based Adhesives:Acrylic and polyurethane dispersions meet REACH and FDA volatile organic compound thresholds but cure at roughly 60% of hot-melt line speeds. Adoption clusters in European markets facing ECHA authorization timelines for solvent alternatives.
- Solvent-Based Adhesives:Declining share in regulated markets due to pyrolysis byproduct scrutiny; residual demand persists in regions with deferred emission standards.
- Pressure-Sensitive Adhesives:Repositionable chemistries command price premiums in premium packaging over-label applications where clean removal protects brand equity.
Hot melt adhesives sit at the top of the volume ranking, with water-based formulations climbing the fastest as regulatory deadlines approach.
End User:
Supply chain position determines specification authority, with manufacturers holding formulation veto power while distributors shape regional availability.
- Manufacturers:Tier-one cigarette producers mandate dual-source qualification for critical tipping and plug-wrap chemistries, spreading volume across approved suppliers to mitigate line-stoppage risk. Technical teams in China and Indonesia now pre-qualify local adhesive specialists alongside incumbent multinationals.
- Distributors:Pidilite Industries and regional networks control access points across South Asia, warehousing inventory to buffer manufacturers against supply discontinuities during reformulation transitions.
- Retailers:Minimal direct procurement; specification influence limited to private-label packaging aesthetics.
- Wholesalers:Bulk logistics handlers with no formulation input; volume aggregates through distributor-tier consolidation.
Manufacturers command the specification hierarchy, with distributors gaining leverage fastest as multi-source programs expand.
Application:
Line-speed differentials create tiered performance requirements, with filter assembly demanding the most precise rheological control.
- Filter Assembly:Acetate fiber-to-paper adhesion specifications tighten for slim and super-slim formats, creating qualification barriers for suppliers lacking low-additive, high-shear formulation mastery. Henkel anchors premium contracts across regulated markets through European formulation expertise.
- Cigarette Packaging:Wrapper bonding and carton sealing prioritize food-contact migration compliance over speed, favoring water-based systems where burn-additive restrictions apply.
- Wrapper Bonding:Tipping paper-to-tobrod adhesion requires tack stability across 40-70% relative humidity bands; failures trigger line stops costing multiples of adhesive material spend.
- Labeling:Pressure-sensitive repositionability commands price premiums in promotional over-label segments where clean removal enables reuse.
Filter assembly sits at the top of the volume ranking, with labeling applications expanding most quickly in premium packaging segments.
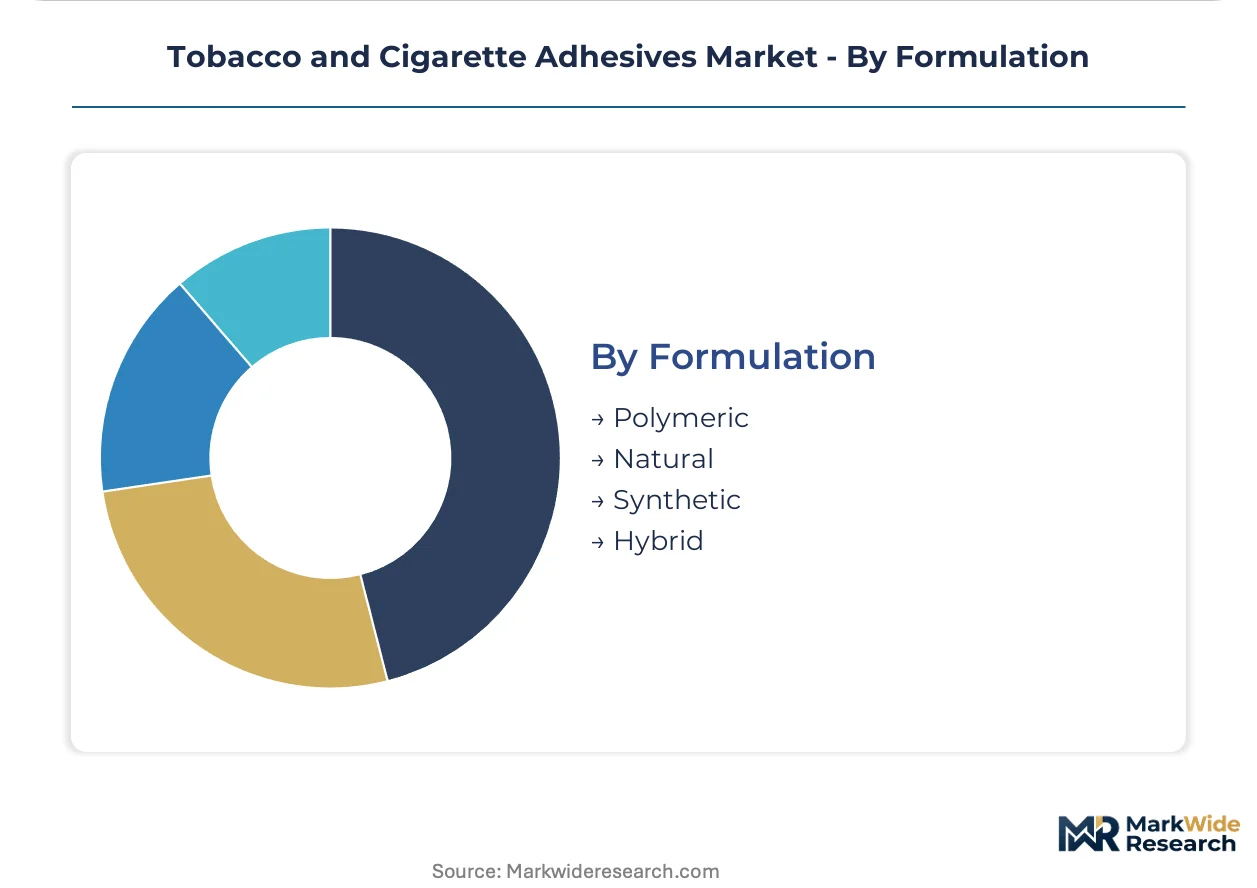
Formulation:
Feedstock integration strategies separate margin leaders from price-takers, with synthetic and polymeric categories benefiting from captive supply chains.
- Synthetic:Hydrogenated hydrocarbon resins displace rosin ester tackifiers as ECHA evaluates persistent organic pollutant content; suppliers with in-house resin production sustain margin predictability against crude-linked monomer volatility.
- Polymeric:EVA and metallocene polyolefins dominate hot-melt volume; HB Fuller's backward integration into ethylene-vinyl acetate supply chains sustains cost advantages against non-integrated competitors.
- Natural:Starch and dextrin derivatives retain niche positions where biodegradability certifications command specification premiums; cellulose acetate replacement fibers from wood pulp and hemp require novel tunable-degradation chemistries.
- Hybrid:Blended systems balance instant-set performance with regulatory compliance, emerging as bridge solutions during authorization transitions.
Polymeric formulations sit at the top of the volume ranking, with natural chemistries gaining share fastest as biodegradable filter mandates advance.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Yangtze River Delta anchors adhesive demand through China's concentrated cigarette manufacturing base, where domestic producers scale technical capabilities to displace imported formulations across high-speed filter-assembly lines.
China
Domestic cigarette manufacturers in Jiangsu and Zhejiang provinces are qualifying local adhesive specialists to replace European imports, driven by SAMR enforcement of GB standards on packaging materials. Shanghai-based technical centers now validate low-additive, high-shear formulations for slim-format filter bonding at line speeds exceeding 8,000 units per minute.
Germany
Filter-assembly specialists in Baden-Württemberg and North Rhine-Westphalia retrofit thermal zoning systems to isolate high-temperature plug-wrap stations from cooler tipping zones. ECHA's 2023-2025 evaluation window for rosin ester tackifiers compels hydrogenated hydrocarbon resin substitution programs ahead of REACH authorization deadlines.
United States
FDA combustion-product testing protocols demand third-party toxicology studies documenting thermal decomposition profiles under simulated smoking conditions. North Carolina and Virginia manufacturing clusters face reformulation investments to address pyrolysis byproduct scrutiny while maintaining tack stability across 40-70% relative humidity bands.
India
Unmet demand from cigarette and bidi manufacturers concentrates in Maharashtra and Gujarat, where BIS certification pathways favor suppliers establishing local blending facilities with in-house testing laboratories. Mumbai distributor networks control access points for regional manufacturers seeking supply resilience through multi-source qualification.
Indonesia
Procurement teams at major producers now mandate dual-approved suppliers for critical tipping chemistries, spreading volume across qualified alternatives to mitigate line-stoppage risk. Java-based manufacturing clusters drive specification authority for filter-tow bonding applications where downtime costs exceed adhesive material spend.
Tobacco and Cigarette Adhesives Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue biodegradable filter adhesion and repositionable packaging chemistries. The market structure concentrates among integrated polymer suppliers, regional formulation specialists, and distributor-controlled access networks. Three archetypes dominate: backward-integrated resin producers sustaining margin predictability, European regulatory specialists anchoring premium contracts, and South Asian distributors warehousing inventory to buffer reformulation transitions. Competitive moves center on multi-source qualification programs and thermal zoning equipment partnerships.
Within the integrated-resin tier, HB Fuller exemplifies upstream control over ethylene-vinyl acetate supply chains. Among European regulatory specialists, Henkel occupies a position anchored by REACH-compliant formulation expertise. Pidilite Industries represents the distributor-archetype, sitting within South Asian networks that control regional access points for qualified adhesive supply.
| Leading Market Players |
|---|
| Techbond Group |
| Siag Chemicals Group |
| Henkel |
| Helios Kemostik |
| HB Fuller |
| Nordson |
| Intercol Adhesives |
| DuPont |
| Pidilite Industries |
| Others |
Pricing and Supply Chain Analysis
Specialized polymer chemists concentrated in Germany's Baden-Württemberg region command wage premiums that widen pricing spreads between REACH-compliant premium formulations and standard EVA grades sourced from Asian production hubs.
Pricing Analysis
Input-cost pass-through from crude-linked ethylene-vinyl acetate monomers compresses margins for non-integrated hot melt suppliers while rewarding backward-integrated competitors. Three-tier pricing structure across premium metallocene polyolefins, standard EVA formulations, and economy-grade natural resins reflects certification grade and volume scale differentials. Pricing pressure stems from SAMR-driven local supplier qualification in China displacing import premiums. Mid-tier cigarette manufacturers exhibit highest price sensitivity as they balance equipment retrofit costs against compliance deadlines.
Supply Chain Analysis
Dual-sourcing requirements now mandated by tier-one manufacturers in China and Indonesia are fragmenting volume concentration across qualified alternatives. Supply concentrates in Germany, China, and India, with polymer resin production drawing from naphtha crackers and bio-based feedstock pilots. Raw material dependencies center on ethylene-vinyl acetate copolymers, hydrogenated hydrocarbon tackifiers, and metallocene catalyst systems. Single-source vulnerability persists in specialized metallocene polyolefin grades where only two European suppliers hold validated formulations. Distribution runs through regional blending facilities and Pidilite-controlled South Asian warehouse networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a late-cycle quality story where specification premiums for low-additive, high-shear filter-bonding formulations are displacing commodity-grade volume as slim-format cigarette production accelerates.
For Market Incumbents: Lock in multi-year qualification contracts with Chinese manufacturers before SAMR-driven local supplier technical capabilities mature. Deepen backward integration into hydrogenated hydrocarbon resin production to insulate margin predictability against ECHA authorization timelines for rosin ester derivatives. Prioritize thermal zoning equipment partnerships that embed adhesive specifications into OEM line configurations.
For New Entrants and Emerging Players: Capture biodegradable filter adhesion white space by developing tunable-degradation chemistries aligned to cellulose acetate replacement fibers from wood pulp and hemp sources. Target India's BIS certification pathway where unmet demand from cigarette and bidi manufacturers exceeds domestic blending capacity. Pursue co-development agreements with filter-tow producers to validate formulations ahead of manufacturer qualification cycles.
For Investors and Strategic Acquirers: Specialty chemical conglomerates with existing polymer platforms are the most active acquirers in this space, seeking REACH-compliant formulation capabilities to anchor European tobacco contracts. Long-term viability hinges on regulatory pre-qualification assets rather than volume scale, favoring targets with validated low-additive portfolios over commodity hot melt producers. Watch ECHA substance evaluation outcomes for rosin ester tackifiers as the inflection signal that would accelerate hydrogenated hydrocarbon resin substitution programs and reshape competitive positioning.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into EVA Supply | HB Fuller's captive polymer production sustains cost advantages against non-integrated hot melt competitors. |
| Multi-Source Qualification Programs | Henkel's dual-approved supplier status with Chinese manufacturers mitigates line-stoppage risk across high-speed filter-assembly lines. |
| Biodegradable Filter Chemistry Development | Novel adhesives for cellulose acetate replacement fibers align with compostability certifications advancing in European markets. |
| Thermal Zoning Equipment Partnerships | Metallocene polyolefin suppliers embedding specifications into OEM line segments capture retrofit cycles in Germany and Poland. |
| Local Blending Facility Establishment | BIS-certified Indian facilities with in-house testing laboratories control access points for regional cigarette and bidi manufacturers. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with adhesive R&D directors, cigarette manufacturer procurement leads, filter-tow technical specialists, and South Asian distributor network managers with secondary validation from customs trade data, SEC filings of listed chemical producers, ECHA substance registration databases, and SAMR GB standard documentation. Bottom-up volume modeling from individual production line specifications and top-down market sizing from regional cigarette manufacturing statistics were cross-referenced for triangulation.
Comparable-period anchoring established historical reference baselines from pre-pandemic production volumes through current qualification cycle timelines across the projection horizon. Segmentation dimensions modeled included adhesive chemistry type, application workflow, regulatory compliance tier, and regional manufacturing hub concentration. CAGRs were derived from slope analysis of technology adoption curves and equipment replacement cycles, with forecast inputs incorporating SAMR enforcement intensity and ECHA authorization timeline probabilities.
ECHA substance evaluation delays, SAMR local supplier qualification acceleration, and biodegradable filter mandate timing are the dominant revision risks to modeled outcomes. Forecasts reflect assumptions regarding regulatory deadline adherence and equipment retrofit completion rates. Deviation in ECHA rosin ester tackifier authorization outcomes would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
Hydrophobic Pore-Blocking Agents for Waterproof Concrete Market
Adhesives & Sealants
United States Construction Adhesives and Sealants Market
Adhesives & Sealants
Two Component Adhesive Market
Adhesives & Sealants
South America Electronics Adhesives Market
Adhesives & Sealants
High Temperature Adhesives Market
Adhesives & Sealants
Ethylene Butyl Acrylate Market
Adhesives & Sealants
Light Curing Adhesives Market
Adhesives & Sealants
Europe Flock Adhesives Market
Adhesives & Sealants
Adhesives and Sealants Market
Adhesives & Sealants
Global Tissue Sealants Market
Adhesives & Sealants
Global Non-Woven Adhesives Market
Adhesives & Sealants
Anti-Adhesion Products Market
Adhesives & Sealants
De-Seamable Adhesives Market
Adhesives & Sealants
North America Glue-Laminated Timber Market
Adhesives & Sealants
Metal Bonding Adhesives Market
Adhesives & Sealants
Dibutyl Maleate (DBM) Market