
 Europe High Density Polyethylene Jerrycan Market | 2026-2036
Europe High Density Polyethylene Jerrycan Market Size, Share, and Industry Trends Forecast 2026-2036
Europe High Density Polyethylene Jerrycan Market Intelligence
A shift from single-source resin contracts toward multi-source procurement is realigning supply security strategies across European HDPE jerrycan converters. WERIT Kunststoffwerke W. Schneider GmbH & Co. KG leverages captive blow-molding capacity in Germany to anchor regional delivery schedules. SCHÜTZ GmbH & Co. KGaA dominates industrial-grade UN-certified formats through integrated steel-plastic hybrid expertise. Greif, Inc. extends its reconditioning network to complement virgin container sales, reducing customer lifecycle costs.
Europe high density polyethylene jerrycans are blow-molded containers fabricated from ethylene homopolymer resins with density ranges of 0.941–0.965 g/cm³, engineered to resist chemical permeation and mechanical impact across storage and transit cycles. UN Certified Jerrycans command premium positioning due to stringent dangerous-goods compliance requirements, while Standard Jerrycans occupy high-volume, price-sensitive agricultural and lubricant segments. Collapsible Jerrycans represent the fastest-growing format as food-grade and pharmaceutical end users prioritize empty-container logistics efficiency and warehouse density.
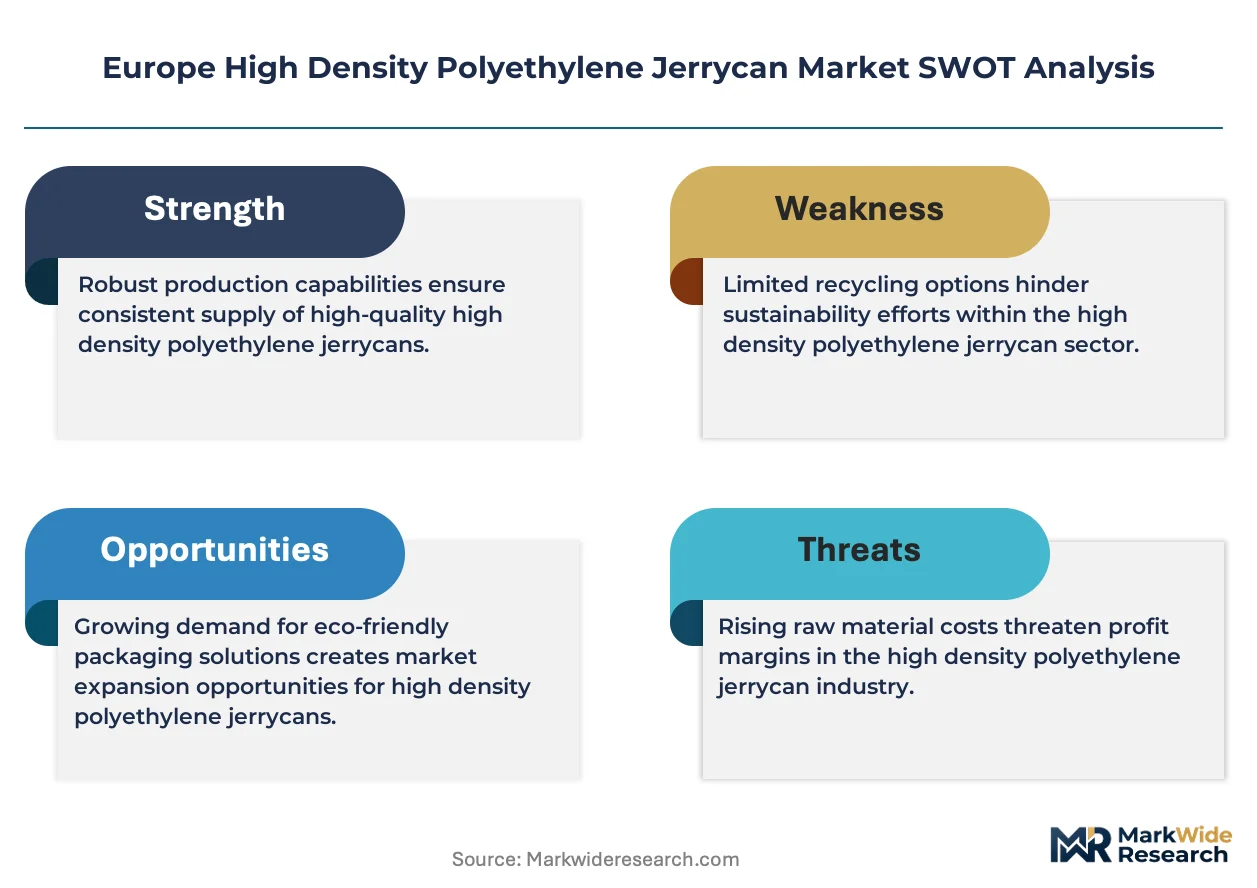
REACH compliance through ECHA governs substance restrictions in resin additives and colorants, directly influencing formulation choices for chemical-contact applications. The EU Green Deal's packaging recyclability mandates and F-Gas Regulation phasing drive converters toward monomaterial designs and post-consumer HDPE incorporation. Germany's national packaging law and France's extended producer responsibility schemes add layer-specific compliance costs that reshape margin structures. Stakeholders must monitor evolving Ecodesign for Sustainable Products Regulation thresholds to anticipate which container specifications will retain market access.
Market Dynamics
REACH compliance through ECHA is forcing converters to reformulate resin additives and colorants, compressing formulation flexibility while raising certification costs for chemical-contact applications across European HDPE jerrycan production.
Growth Catalysts
- EU Green Deal packaging recyclability mandates:These thresholds accelerate monomaterial design adoption and post-consumer HDPE incorporation, pulling converters toward circular-ready product lines.
- Agricultural chemical distributors:German and French distributors are expanding UN-certified container orders to serve Central European export corridors with compliant packaging.
- Collapsible format engineering:Food-grade and pharmaceutical end users prioritize empty-container logistics efficiency, driving warehouse density improvements and transport cost reductions.
Market Restraints
- Post-consumer resin price volatility:PCR supply fluctuations create margin compression for converters attempting to meet EU recyclability thresholds without long-term supply contracts.
- Rhine-Ruhr industrial corridor concentration:Chemical packaging cluster dependency on this single geography exposes delivery schedules to regional logistics disruptions and capacity bottlenecks.
- Steel-plastic hybrid substitution:Industrial-grade applications with extreme durability requirements sometimes bypass HDPE entirely for SCHÜTZ GmbH's integrated steel-plastic alternatives.
Strategic Opportunities
- France's extended producer responsibility schemes:Layer-specific compliance costs create first-mover advantages for converters with established take-back infrastructure and reconditioning networks.
- Pharmaceutical cold-chain expansion:Temperature-sensitive biologics distribution requires specialized HDPE formulations with thermal stability credentials currently underpenetrated in Southern Europe.
- F-Gas Regulation phase-down convergence:Refrigerant containment applications are absorbing fluorinated gas containment mandates, opening technical specification gaps for barrier-enhanced jerrycan designs.
Industry Challenges
- Ecodesign for Sustainable Products Regulation anticipation:Evolving ESPR thresholds require continuous reformulation investment without guaranteed market access retention timelines.
- UN certification testing backlog:Dangerous-goods compliance verification queues at notified bodies extend product launch cycles and freeze working capital in pre-certified inventory.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe High Density Polyethylene Jerrycan Market |
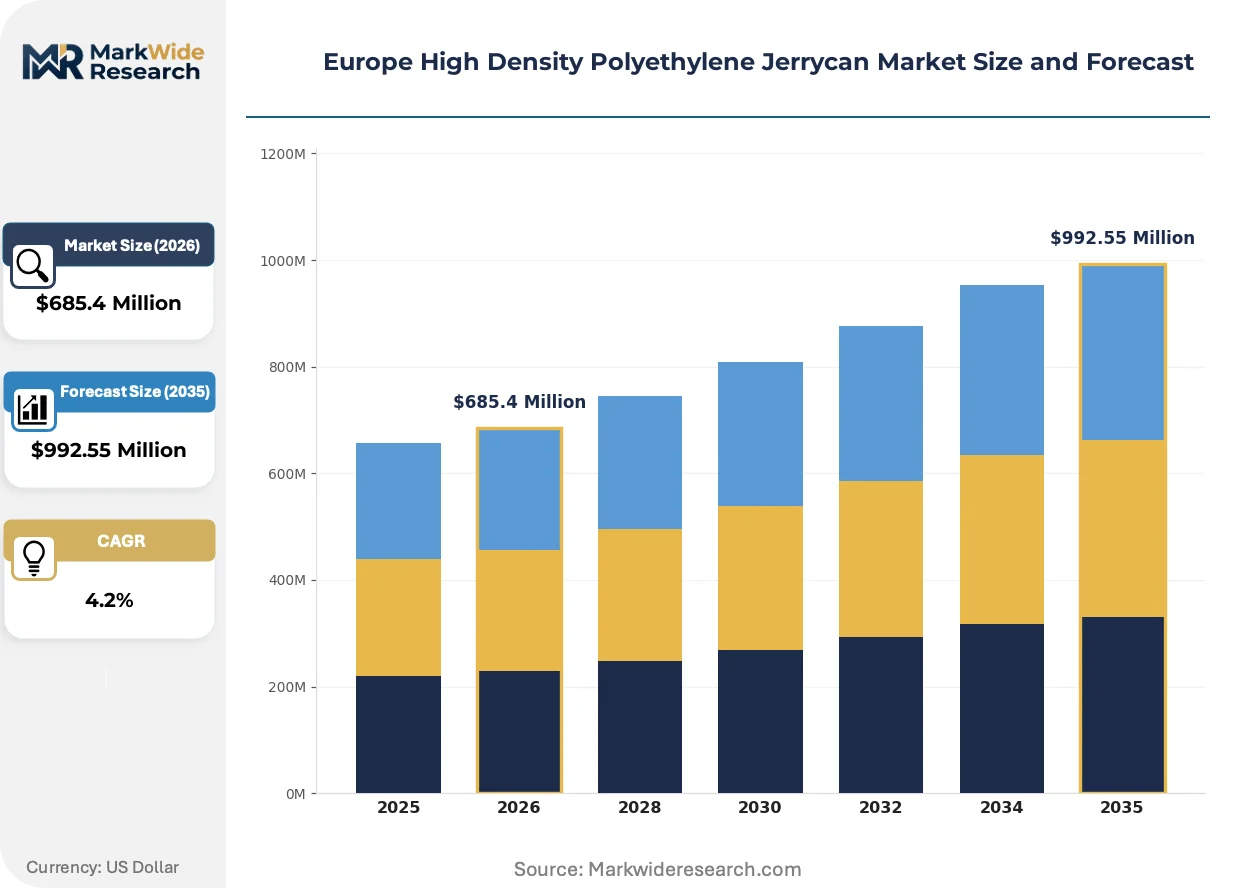
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $992.55 Million |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Jerrycans, UN Certified Jerrycans, Custom Jerrycans, Collapsible Jerrycans Capacity: 1 Liter, 5 Liters, 10 Liters, 20 Liters End User: Agricultural, Food & Beverage, Chemical, Pharmaceutical Distribution Channel: Online Retail, Wholesale, Direct Sales, Export |
| Companies Covered | WERIT Kunststoffwerke W. Schneider GmbH & Co. KG, RPC Group plc, SCHÜTZ GmbH & Co. KGaA, AST Kunststoffverarbeitung GmbH, Denios, Greif, Inc., Greiner Packaging, Kautex Textron GmbH & Co. KG, Mauser Packaging Solutions, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe High Density Polyethylene Jerrycan Market Strategic Shifts & Innovations
European HDPE jerrycan manufacturing is absorbing three concurrent pressures: resin circularity mandates, dangerous-goods certification intensification, and logistics efficiency optimization. Each pressure is generating distinct technical and commercial responses.
Monomaterial blow-molding is absorbing post-consumer HDPE at ratios previously requiring virgin resin blends. Food-grade and personal care buyers in the Benelux region are qualifying 30-50% PCR content without performance degradation. This absorption is compressing the cost premium between circular and conventional containers, eroding the green-pricing gap that sustained early-mover margins.
Germany's national packaging law and France's extended producer responsibility schemes are layering compliance costs that reshape converter margin structures. Industrial-scale producers with captive reconditioning infrastructure capture lifecycle revenue streams that pure-virgin manufacturers cannot replicate. Small-to-mid converters without reverse-logistics capabilities face margin erosion or forced partnership with specialized waste-management operators.
Empty-container logistics efficiency now dominates pharmaceutical and food-grade procurement specifications. Buyers are consolidating supplier bases around converters offering collapsible formats with nested stacking ratios exceeding 4:1 versus rigid alternatives. This consolidation is visible most acutely in Rhine-Main distribution hubs serving just-in-time chemical manufacturing, where warehouse density directly determines landed cost competitiveness.
Europe High Density Polyethylene Jerrycan Market Segmentation
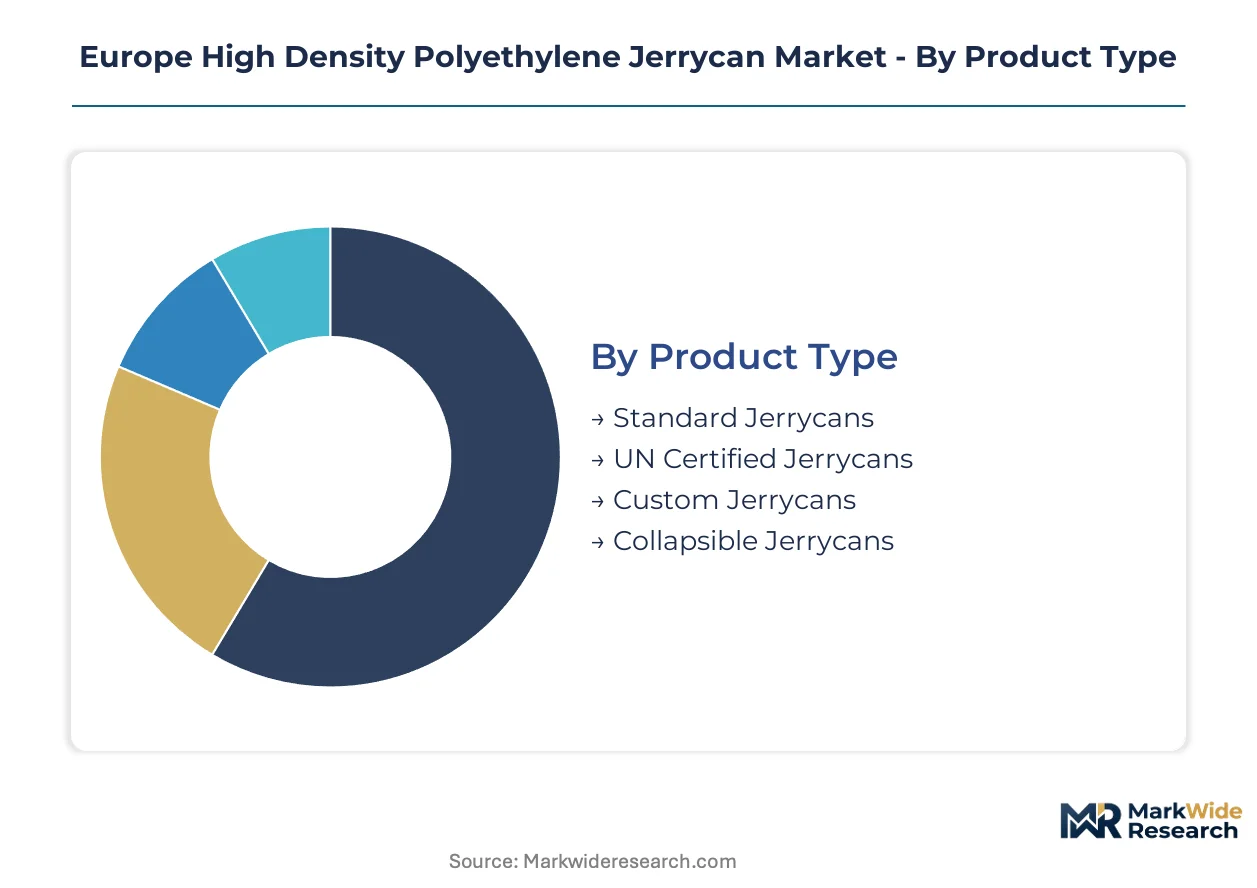
HDPE jerrycan segmentation in Europe reveals how regulatory pressure and logistics economics split demand across distinct performance tiers. Each dimension—product certification, capacity scaling, end-use chemistry, and channel structure—creates separate competitive arenas with divergent margin profiles.
Product Type:
Standalone packaging applications dominate chemical and agricultural distribution, while embedded systems integration matters less here than in industrial machinery markets. Certification depth separates premium from commodity positioning.
- UN Certified Jerrycans:Engineered to UN 3H1 and 3H2 standards for dangerous-goods transport, these containers incorporate multi-layer blow-molding with permeation barriers. German and French agricultural chemical distributors are expanding orders to serve Central European export corridors requiring compliant packaging under ADR regulations.
- Collapsible Jerrycans:Food-grade and pharmaceutical buyers prioritize nested stacking ratios exceeding 4:1 versus rigid alternatives, driving warehouse density improvements and transport cost reductions in Rhine-Main distribution hubs.
- Standard Jerrycans:Virgin HDPE formulations serve price-sensitive lubricant and general chemical segments where REACH compliance costs already compress margins.
- Custom Jerrycans:Specialized neck finishes, integrated handles, and corporate color-matching address branded chemical and personal care lines requiring differentiation at point-of-use.
Volume placements concentrate in Standard Jerrycans; the faster expansion belongs to Collapsible Jerrycans.
Capacity:
Cost tier stratification runs from single-use laboratory formats to returnable industrial bulk systems, with mid-range capacities capturing the densest procurement activity from agricultural cooperatives.
- 20 Liters:The workhorse format for agricultural chemical distribution across Germany's Rhine-Ruhr corridor, where mechanical handling compatibility and UN stack-load certification justify unit economics despite higher per-container resin content.
- 10 Liters:Preferred by specialty chemical manufacturers serving just-in-time production lines in Benelux pharmaceutical clusters, balancing manual handling ergonomics with sufficient batch volume.
- 5 Liters:Lubricant and automotive aftermarket segments favor this capacity for retail shelf presence and consumer portability in French hypermarket channels.
- 1 Liter:Laboratory reagent and high-value pharmaceutical intermediate packaging, where precision dosing necks and tamper-evident closures command formulation premiums.
Procurement density peaks at 20 Liters; the steepest expansion trajectory is visible in 10 Liter formats.
End User:
Application chemistry determines barrier specifications, with oxidizing and flammable substance categories imposing the strictest material compatibility testing under ECHA guidance.
- Chemical:Solvent, adhesive, and coating manufacturers require permeation-resistant HDPE grades with documented compatibility against aromatic hydrocarbons, driving specification intensity in Germany's industrial packaging clusters.
- Agricultural:Pesticide and fertilizer distributors across France and Poland prioritize UN-certified formats with UV-stabilized resins for outdoor storage durability and seasonal demand surges.
- Pharmaceutical:Biologics cold-chain expansion demands thermal stability credentials currently underpenetrated in Southern Europe, opening technical specification gaps for barrier-enhanced designs.
- Food & Beverage:Edible oil and concentrate producers in Italy and Spain qualify 30-50% PCR content without performance degradation, compressing the green-pricing gap versus virgin alternatives.
Revenue concentration sits with Chemical end users; Pharmaceutical applications are climbing the fastest.
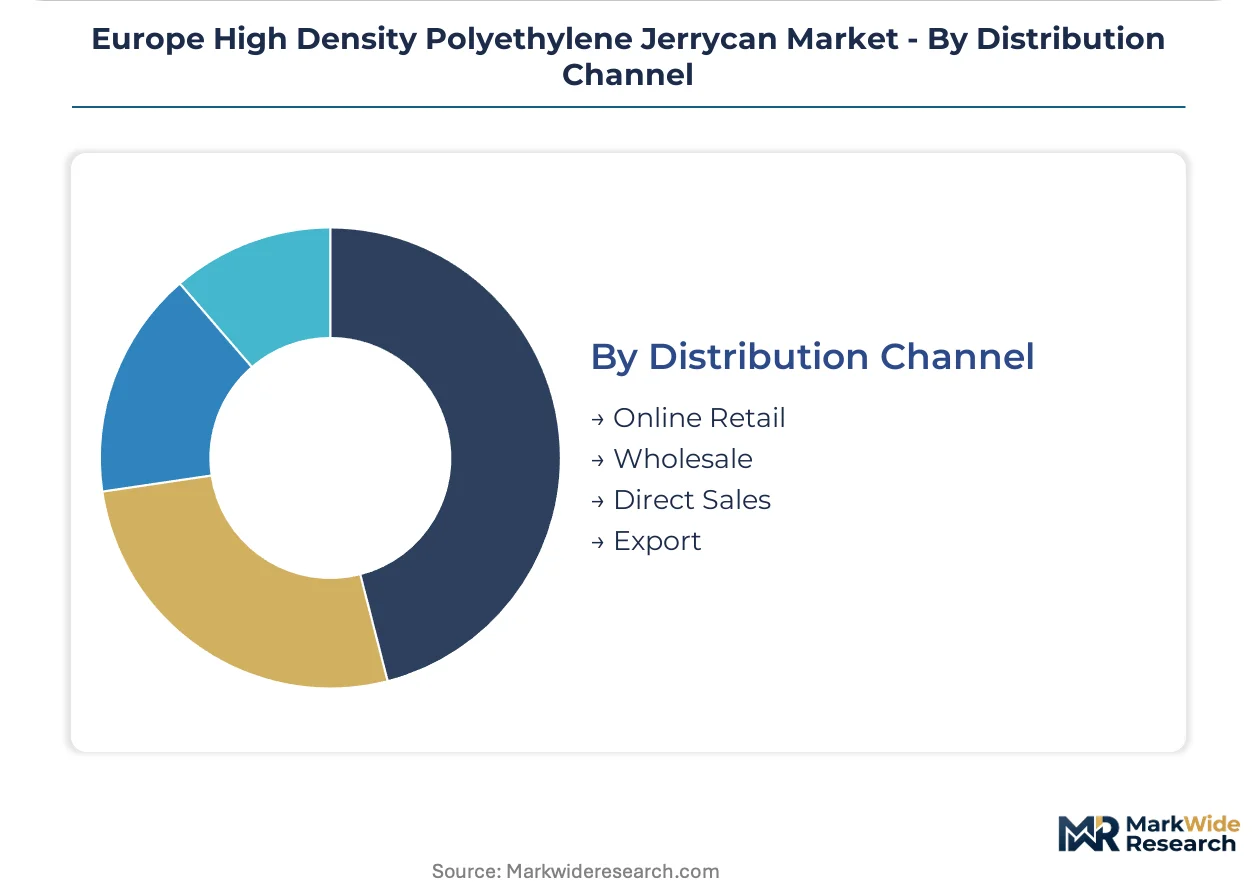
Distribution Channel:
Customer type and order scale determine channel economics, with integrated producers capturing lifecycle value through reconditioning networks that pure-virgin manufacturers cannot replicate.
- Wholesale:Agricultural cooperatives and regional chemical distributors in Eastern Europe rely on palletized bulk deliveries with seasonal credit terms, locking in volume commitments through annual frame contracts.
- Direct Sales:Large chemical manufacturers with captive blow-molding specifications negotiate resin-indexed pricing and just-in-time delivery schedules from converters with Rhine-Ruhr production proximity.
- Export:Central European packaging clusters serve non-EU markets through UN-certified container programs compliant with destination-country dangerous-goods regulations.
- Online Retail:Small-lot laboratory supply and specialty lubricant segments access fragmented demand through platform distributors, though logistics costs erode margins on sub-pallet quantities.
Shipment value aggregates in Wholesale; Direct Sales channels are gaining share fastest among integrated chemical producers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Ethylene feedstock availability through the Rhine-Ruhr chemical corridor anchors European HDPE jerrycan production geography. German converters leverage this proximity to serve Central European export routes with compressed lead times.
Germany
Agricultural chemical distributors in the Rhine-Ruhr corridor are expanding UN-certified container orders for Central European export compliance. The national packaging law imposes extended producer responsibility costs that favor converters with captive reconditioning infrastructure. Cologne-Düsseldorf industrial clusters host blow-molding operations serving just-in-time chemical manufacturing schedules.
France
Extended producer responsibility schemes under AGEC law are reshaping converter margin structures through layer-specific compliance costs. ECHA REACH enforcement drives reformulation of resin additives for chemical-contact applications. Lyon-based packaging clusters serve pharmaceutical and agrochemical end users with specialized barrier specifications.
Italy
Edible oil and concentrate producers in Northern Italy are qualifying 30-50% post-consumer HDPE content without performance degradation. EU Green Deal recyclability mandates accelerate monomaterial design adoption among Lombardy converters. Milan-Turin industrial zones concentrate food-grade jerrycan fabrication for Mediterranean distribution.
Netherlands
Benelux pharmaceutical clusters drive demand for 10-liter formats balancing manual handling ergonomics with batch volume requirements. Rotterdam port logistics enable PCR resin import diversification to offset supply volatility. Eindhoven-region converters serve just-in-time chemical production lines with resin-indexed pricing contracts.
Poland
Agricultural cooperatives in Eastern Poland rely on palletized bulk deliveries with seasonal credit terms locking annual frame contracts. EU F-Gas Regulation phase-down opens technical specification gaps for barrier-enhanced refrigerant containment designs. Warsaw-Katowice distribution corridors serve as export gateways to non-EU markets requiring UN-certified dangerous-goods compliance.
Europe High Density Polyethylene Jerrycan Market Key Industry Players
Capacity expansion dominates the current landscape as converters retrofit lines for post-consumer resin incorporation and collapsible format engineering. The vendor base stratifies across three tiers: integrated multinational producers with captive reconditioning networks, mid-scale regional specialists with Rhine-Ruhr production proximity, and niche fabricators serving custom specification segments. Strategic archetypes include lifecycle revenue capturers, PCR formulation leaders, and UN certification specialists. Geographic expansion and portfolio diversification represent the dominant competitive moves as players position for Ecodesign for Sustainable Products Regulation compliance thresholds.
Within the integrated multinational tier, WERIT Kunststoffwerke W. Schneider GmbH & Co. KG and SCHÜTZ GmbH & Co. KGaA exemplify divergent positioning strategies. WERIT represents the captive blow-molding archetype anchored in German production geography, while SCHÜTZ occupies the steel-plastic hybrid expertise position serving industrial-grade durability requirements. Greif, Inc. sits within the lifecycle revenue capturer archetype through reconditioning network extension that complements virgin container sales.
| Leading Market Players |
|---|
| WERIT Kunststoffwerke W. Schneider GmbH & Co. KG |
| RPC Group plc |
| SCHÜTZ GmbH & Co. KGaA |
| AST Kunststoffverarbeitung GmbH |
| Denios |
| Greif, Inc. |
| Greiner Packaging |
| Kautex Textron GmbH & Co. KG |
| Mauser Packaging Solutions |
| Others |
Cost & Logistics Intelligence
Family-owned mid-caps across Germany's Rhine-Ruhr corridor anchor supply discipline through long-held resin procurement relationships, while their pricing power rests on captive blow-molding capacity that insulates delivery schedules from spot-market volatility.
Pricing Analysis
Warranty and reconditioning service bundling separates integrated producers from pure-virgin manufacturers, with lifecycle revenue streams commanding premium positioning against transactional competitors. Three-tier pricing structure across UN-certified premium, standard agricultural, and collapsible economy levels reflects certification depth and format complexity. Pricing pressure stems from post-consumer resin supply volatility compressing margins for converters without long-term PCR contracts. Agricultural cooperatives exhibit highest price sensitivity due to seasonal demand surges and frame-contract volume commitments, while pharmaceutical cold-chain buyers prioritize thermal stability credentials over unit cost.
Supply Chain Analysis
UN certification and ECHA REACH qualification gating restricts viable supplier pools to converters with documented dangerous-goods compliance and additive reformulation capabilities. Manufacturing concentrates in Germany, France, and Italy, with Rhine-Ruhr chemical clusters feeding Central European distribution corridors. Raw material dependencies center on ethylene feedstock from regional crackers, post-consumer HDPE flake imports through Rotterdam, and UV-stabilized masterbatch formulations. Single-source vulnerability runs through PCR supply contracts lacking geographic diversification. Distribution runs through wholesale palletized bulk to agricultural cooperatives, direct sales to integrated chemical manufacturers, and export channels serving non-EU dangerous-goods markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market has become a backward-integration race as converters pursue captive resin reconditioning infrastructure to capture lifecycle revenues unavailable to pure-virgin competitors.
For Market Incumbents: Acquire reconditioning facility networks and PCR sorting infrastructure to defend against margin erosion from France's extended producer responsibility cost layering. Consolidate Rhine-Ruhr production proximity advantages through capacity debottlenecking rather than greenfield expansion. Prioritize Ecodesign for Sustainable Products Regulation pre-compliance to secure market access retention as thresholds tighten. For New Entrants and Emerging Players: Digital platform distribution routes into small-lot laboratory supply and specialty lubricant segments bypass incumbent wholesale lock-in. Target Southern European pharmaceutical cold-chain applications where thermal stability credentials remain underpenetrated. Pursue collapsible format engineering partnerships with Benelux food-grade buyers prioritizing warehouse density metrics. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-scale converters with established take-back infrastructure in France and Germany over asset-light pure-virgin manufacturers. Five-to-ten-year viability hinges on PCR incorporation ratios achieving cost parity with virgin resin blends. Monitor ECHA substance restriction announcements as inflection indicators for reformulation investment cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into PCR Sorting | Captures margin compression from France's AGEC compliance cost layering. |
| Collapsible Format Engineering | Addresses Rhine-Main pharmaceutical buyers' warehouse density procurement specifications. |
| UN Certification Pre-Investment | Reduces testing backlog exposure at ECHA-notified bodies for dangerous-goods launches. |
| Reconditioning Network Extension | Replicates Greif's lifecycle revenue model unavailable to virgin-only competitors. |
| Monomaterial Design Adoption | Aligns with EU Green Deal recyclability mandates eroding green-pricing premiums. |
Research Approach
Document review covered ECHA substance restriction databases, EU packaging waste directive filings, and customs trade records for HDPE resin flows, complemented by interviews with blow-molding plant managers, agricultural chemical procurement leads, pharmaceutical packaging specification directors, and Rotterdam port logistics operators. Secondary validation drew from Cefic chemical industry reports, SEC filings of listed packaging converters, and ADR dangerous-goods transport regulatory updates. Bottom-up capacity assessments across Rhine-Ruhr production clusters were triangulated against top-down demand aggregation by end-use sector.
Historical volume trajectories were cross-referenced against expert panel inputs from resin suppliers and distribution channel partners. Segmentation modeling spanned certification tier, capacity format, end-use chemistry, and regional production hub across the projection horizon. CAGRs were derived from elasticity-adjusted demand curves incorporating REACH compliance cost pass-through assumptions and PCR incorporation ratio scenarios. Industry-specific inputs included Ecodesign for Sustainable Products Regulation threshold anticipation and F-Gas Regulation phase-down convergence timelines.
The model holds under stable ethylene feedstock pricing and continued ECHA enforcement consistency; deviation in PCR supply disruption severity or UN certification testing queue extensions would shift volume and value outputs. Forecasts reflect documented assumptions regarding regulatory timeline adherence and resin technology substitution rates. A model refresh is warranted upon material change in EU Packaging and Packaging Waste Regulation recyclability threshold announcements or ECHA SVHC candidate list expansion affecting HDPE additive formulations.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Heavy Duty Packaging
Hazmat Packaging Market
Heavy Duty Packaging
High-Stress PCR HDPE Detergent Bottles Market
Heavy Duty Packaging
High Impact Corrugated Boxes Market
Heavy Duty Packaging
Global Heavy Duty Bags and Sacks Market
Heavy Duty Packaging
Heavy-Duty Corrugated Boxes Market
Heavy Duty Packaging
Heavy-Duty Paper and Multiwall Shipping Sack Market
Heavy Duty Packaging
Heavy Duty Bins Market
Heavy Duty Packaging
Hazardous Goods Packaging Market
Heavy Duty Packaging
Heavy Duty Paper Tags Market
Heavy Duty Packaging
Large Blow Molded Products Market
Heavy Duty Packaging
Heavy Duty Corrugated Packaging Market
Heavy Duty Packaging
High-Density Packaging Market