
 Global Heavy Duty Bags and Sacks Market | 2026-2036
Global Heavy Duty Bags and Sacks Market Size, Share, and Industry Trends Forecast 2026-2036
Global Heavy Duty Bags and Sacks Market Intelligence
Multi-layer co-extruded films offering enhanced puncture resistance and moisture protection is reorganizing the competitive landscape for specialty sacks. Mondi Group leverages its extensive paper and plastic production capabilities to offer a diverse product mix. Berry Global, Inc. competes on manufacturing scale and its broad geographic footprint in North America and Europe. Amcor plc differentiates through its focus on innovative and sustainable packaging solutions.
Heavy duty bags and sacks are industrial-grade containers designed for the transport and storage of bulk materials. These products are typically engineered to hold capacities ranging from 10 kg to over 50 kg, utilizing materials with high tensile strength. Plastic bags made from polyethylene and polypropylene represent the largest product type by volume due to cost-effectiveness. The construction and agriculture end-user segments command significant market share, requiring durable solutions for cement, sand, fertilizers, and animal feed.
Regulations such as the US FDA's requirements for food-contact materials and the EU's REACH framework governing chemical substances in plastics directly influence material selection. International standards like ISO 21898 for flexible intermediate bulk containers (FIBCs) set performance and safety benchmarks for manufacturers. Navigating the transition toward circular economy models and incorporating higher percentages of recycled content will be a defining strategic challenge for all market participants.
Market Dynamics
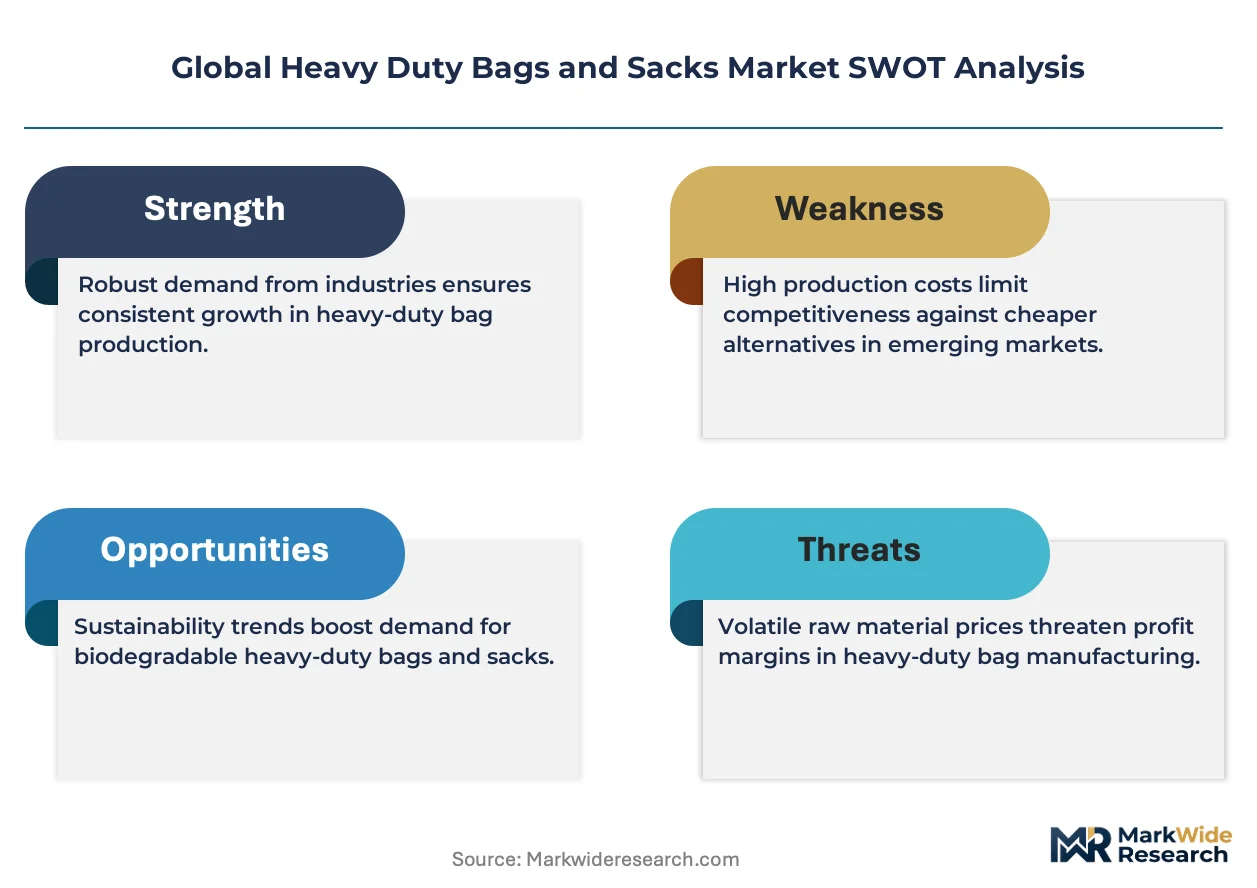
The market is defined by a fundamental tension between the industrial necessity for low-cost, high-strength bulk packaging and escalating regulatory pressures for sustainability. This dynamic forces manufacturers to innovate with materials that balance performance, cost, and environmental compliance across diverse end-use sectors.
Growth Catalysts
- Industrial Expansion in Asia:Continued growth in China's construction and agricultural sectors drives significant volume demand for cement and fertilizer sacks, supported by infrastructure projects across Southeast Asia.
- Food Safety Regulations:Stricter food-contact material standards, such as those from the US FDA, are creating demand for premium, multi-layer bags for agricultural products like seeds and grains.
- Biodegradable Polymer Adoption:EU Green Deal initiatives are accelerating the use of biodegradable and compostable polymers in specialty sacks, opening new product categories for niche agricultural applications.
Market Restraints
- Polymer Price Volatility:The market's reliance on polyethylene and polypropylene resins exposes manufacturers to significant cost instability tied to fluctuating crude oil prices, compressing margins for commodity sacks.
- FIBC Competition:The increasing adoption of flexible intermediate bulk containers (FIBCs) for larger volumes presents a direct substitution threat, eroding the market for multiple smaller sacks in logistics.
- Plastic Use Restrictions:Outright bans and levies on certain plastics create a negative public perception and regulatory uncertainty that can dampen investment, even when not directly targeting heavy-duty sacks.
Strategic Opportunities
- Specialty Chemical Packaging:An opportunity exists in developing high-barrier sacks for hygroscopic or reactive specialty chemicals, requiring advanced material science beyond standard poly-woven bags.
- African Agricultural Development:Expanding fertilizer use in sub-Saharan African nations like Nigeria and Ethiopia presents an underpenetrated market for durable, weather-resistant bags for crop inputs.
- Smart Packaging Integration:Incorporating RFID or QR codes into sacks for traceability and inventory management offers a value-added service for high-value goods like certified seeds or pharmaceuticals.
Industry Challenges
- Recycled Content Integration:A key operational challenge is consistently sourcing high-quality post-consumer recycled (PCR) plastic that meets the stringent performance and safety standards required by ISO 21898.
- Compliance with Evolving Standards:Navigating the complex and shifting landscape of chemical regulations like the EU's REACH framework requires significant ongoing investment in testing and reformulation for multi-layer films.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Heavy Duty Bags and Sacks Market |
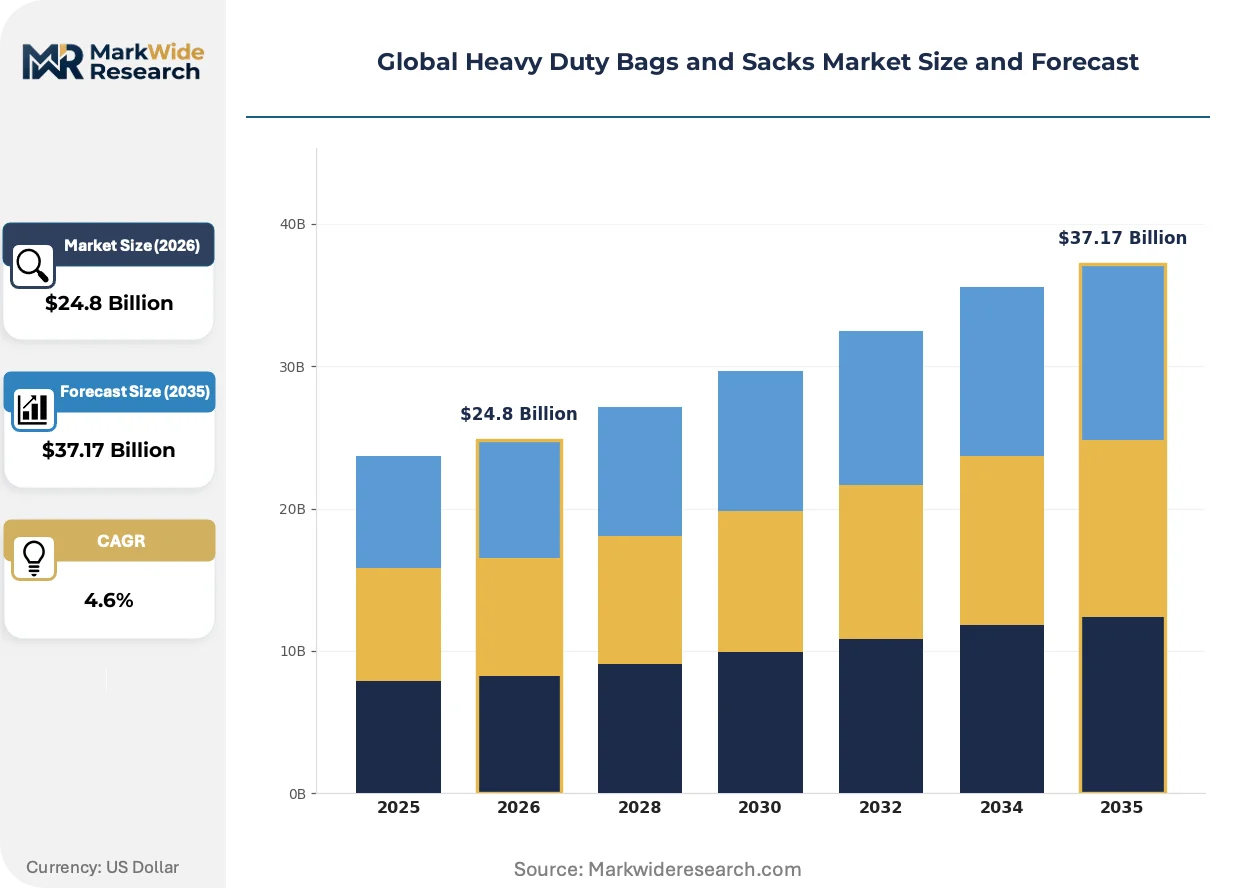
| Market Size in 2026 | $24.8 Billion |
| Market Size in 2035 | $37.17 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plastic Bags, Paper Sacks, Woven Sacks, Specialty Sacks End User: Agriculture, Construction, Retail, Waste Management Material: Polyethylene, Polypropylene, Kraft Paper, Biodegradable Materials Capacity: Up to 10 kg, 10-25 kg, 25-50 kg, Above 50 kg |
| Companies Covered | LC Packaging International BV, Novolex, Mondi Group, Inteplast Group, Segezha Group LLC, Berry Global, Inc., Sonoco Products Company, BAG Corp, Amcor plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Heavy Duty Bags and Sacks Market Strategic Shifts & Innovations
Material science advancements are fundamentally altering product capabilities and lifecycle considerations in the heavy duty bags market. These innovations are a direct response to concurrent demands for enhanced performance and improved environmental footprints across end-use sectors like agriculture and construction.
Multi-layer co-extruded films provide superior puncture resistance and moisture barriers compared to single-ply alternatives. The food and specialty chemical industries are rapidly adopting these films for high-value product protection. This adoption is bifurcating the market into high-performance specialty sacks and price-sensitive commodity bags, creating distinct value propositions.
The EU's Circular Economy Action Plan, a core part of the Green Deal, sets ambitious targets for packaging waste reduction. This policy mandates design-for-recycling principles, pushing manufacturers away from complex laminates that are difficult to process. The industrial bulk packaging segment is most affected, prioritizing mono-material polyethylene solutions to meet future compliance.
End-users in construction and agriculture are increasingly specifying bags that meet third-party sustainability certifications, such as those for recycled content. This buyer behavior moves purchasing decisions beyond simple price and performance metrics, disrupting the traditional procurement process for commodity sacks. This trend is most prominent in Europe and North America, where corporate ESG goals directly influence supply chain choices.
Global Heavy Duty Bags and Sacks Market Segmentation
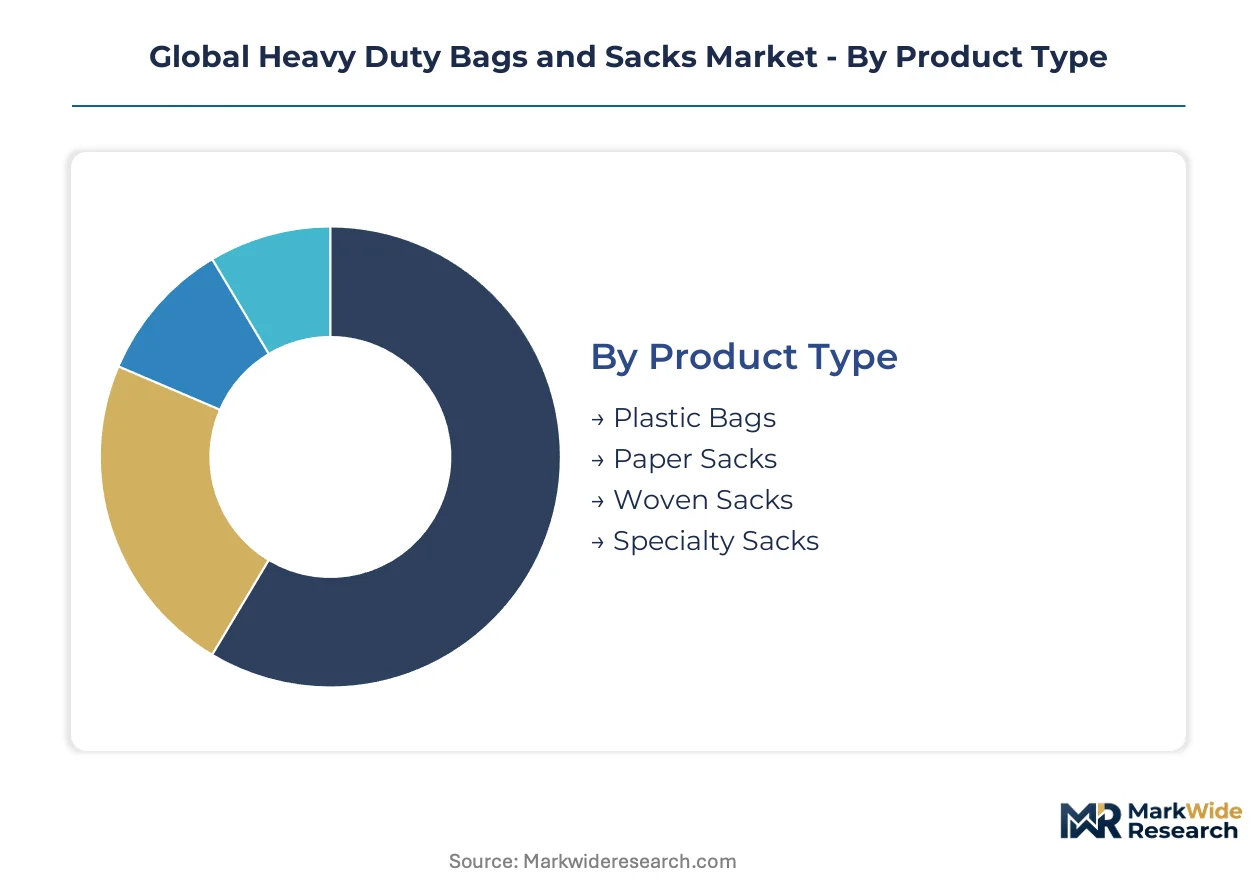
The global heavy duty bags and sacks market is segmented across several critical dimensions, each reflecting distinct material properties, end-use applications, and logistical requirements. Understanding these categories is essential for identifying specific demand drivers and competitive dynamics within the industrial packaging sector.
Product Type:
Margin pools within product types concentrate in specialty sacks due to advanced material science, while plastic bags compete on volume and cost efficiency.
- Specialty Sacks:These highly engineered containers offer enhanced barrier properties and specific chemical resistance, often incorporating multi-layer co-extruded films. Demand concentrates in the food and specialty chemical industries, driven by stringent protection requirements for high-value goods.
- Plastic Bags:Manufactured primarily from polyethylene and polypropylene, these cost-effective bags are designed for general bulk material transport. Their demand is high across construction and agriculture, particularly in China, for packaging cement and fertilizers due to their durability and low unit cost.
- Paper Sacks:Constructed from multiple plies of kraft paper, these bags are favored for dry, free-flowing goods where breathability is beneficial.
- Woven Sacks:Produced from woven polypropylene strips, these sacks provide high tensile strength and tear resistance for various industrial and agricultural commodities.
Plastic Bags hold significant installed capacity. Specialty Sacks are rotating up the share rankings.
End User:
End-user segments are differentiated by specific application requirements and the scale of bulk material handling.
- Agriculture:This segment requires durable bags for seeds, fertilizers, and animal feed, often demanding moisture protection and UV resistance. Demand is particularly strong in Asia and emerging African markets due to agricultural expansion and increased crop input usage.
- Construction:The construction sector utilizes heavy duty bags for cement, sand, aggregates, and other building materials, prioritizing strength and cost-effectiveness. Infrastructure projects in China and Southeast Asia are primary demand drivers.
- Retail:This segment uses heavy duty bags for bulk pet food, garden supplies, and charcoal, emphasizing convenience and shelf appeal.
- Waste Management:Durable sacks are employed for industrial waste, hazardous materials, and recycling collection, requiring robust puncture resistance and containment.
The Agriculture segment continues to command significant volume. Waste Management is gaining share fastest as circular economy initiatives expand.
Material:
Material choices are dictated by performance characteristics, cost structures, and evolving environmental compliance standards.
- Polyethylene:This widely used polymer offers flexibility, moisture resistance, and good sealability for various heavy duty bag applications. Its demand is concentrated due to cost-effectiveness, though polymer price volatility remains a challenge.
- Biodegradable Materials:These polymers, including PLA and PHA, offer an environmentally friendly alternative for specialty sacks, degrading under specific conditions. Demand is accelerating in Europe due to EU Green Deal initiatives and consumer preference for sustainable packaging.
- Polypropylene:Known for its high tensile strength and tear resistance, polypropylene is widely used in woven sacks for agricultural and industrial goods.
- Kraft Paper:This natural fiber material provides breathability and is often used in multi-ply constructions for cement and flour sacks, offering good printability.
Polyethylene remains the dominant material choice. Biodegradable Materials are expanding most quickly, driven by regulatory shifts.
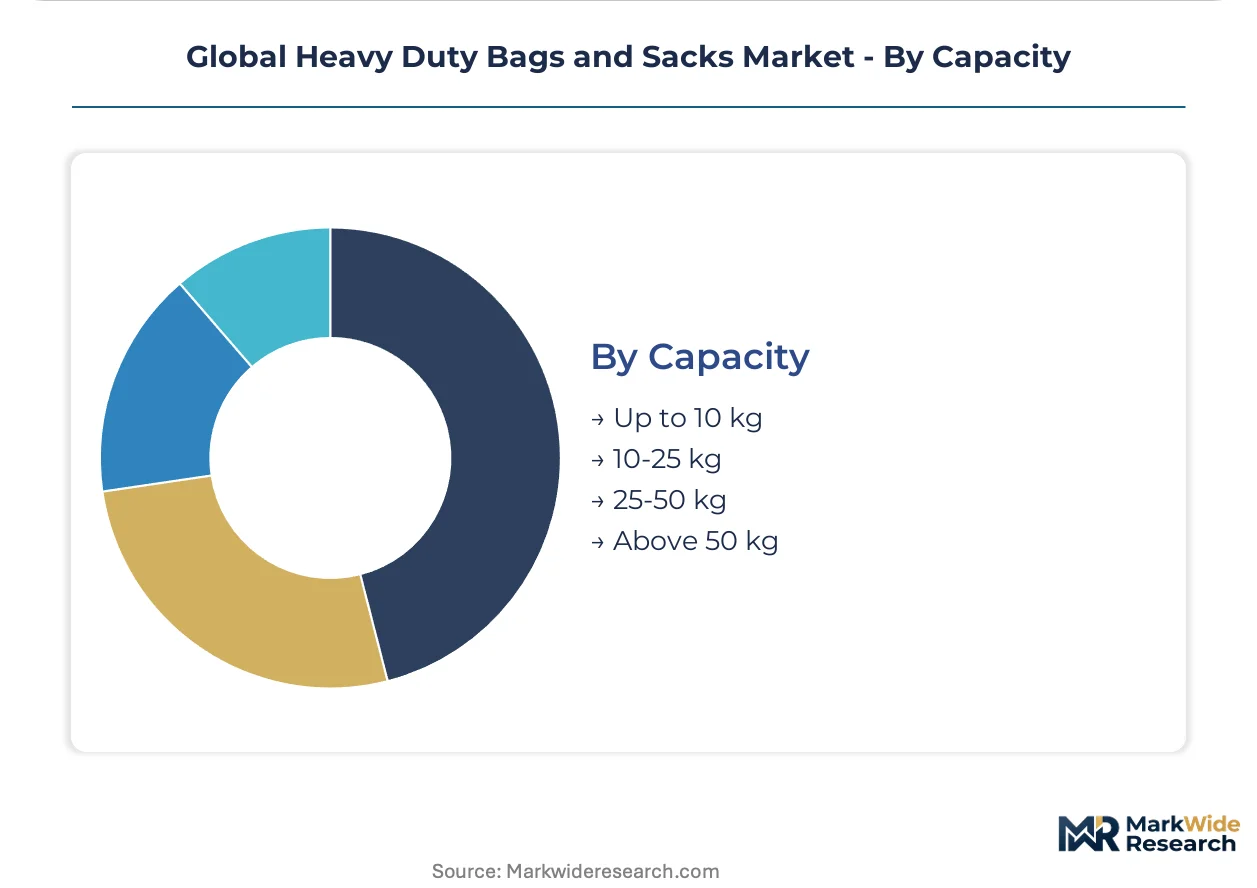
Capacity:
Capacity segments reflect diverse logistical and handling requirements across different bulk material applications.
- 25-50 kg:This capacity range represents a standard for many industrial and agricultural products, balancing manual handling with efficient bulk transport. It is a critical segment for cement, fertilizers, and animal feed, especially in emerging markets.
- Above 50 kg:These larger capacity bags, often including FIBCs, are designed for high-volume bulk transport, reducing handling costs per unit. Their demand is growing as logistics operations seek greater efficiency and consolidation for commodities like grains and chemicals.
- Up to 10 kg:Smaller bags cater to consumer-facing bulk products like pet food, garden soil, and construction aggregates in more manageable quantities.
- 10-25 kg:This intermediate capacity is common for specialized industrial chemicals and smaller agricultural product batches, offering flexibility in distribution.
The 25-50 kg segment maintains a foundational position in the market. The Above 50 kg segment is climbing the fastest due to increasing industrial scale.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Global Heavy Duty Bags and Sacks Market sees significant supply concentration in key manufacturing hubs. Material production and conversion capabilities in Asia form the bedrock of global supply. This geographic distribution directly influences pricing and product availability worldwide.
China
Demand for heavy duty bags in China stems from its expansive agricultural and construction sectors. GB standards guide material selection for industrial packaging. Major manufacturing clusters around the Yangtze River Delta actively produce cement and fertilizer sacks for domestic and export markets. This region benefits from robust infrastructure development.
United States
The United States drives demand for premium multi-layer bags, especially for agricultural products like seeds and grains. US FDA requirements for food-contact materials mandate specific barrier properties. States like California and Iowa, with large agricultural outputs, require durable packaging solutions for their vast produce.
Germany
German manufacturers focus on biodegradable and specialty sacks, driven by strong environmental policies. The EU Green Deal and REACH framework influence material innovation for sustainable packaging. Industrial centers in North Rhine-Westphalia are developing advanced polymer solutions for circular economy models.
India
Agricultural expansion and infrastructure projects in India fuel demand for cost-effective plastic and woven sacks. BIS standards ensure quality and safety for bulk packaging materials. The Gujarat region, with its chemical and textile industries, provides significant raw material and manufacturing capacity for heavy duty bags.
Nigeria
Nigeria's agricultural sector presents an expanding market for durable, weather-resistant bags for crop inputs like fertilizers. The country's national food safety regulations are gradually influencing packaging standards. Lagos, as a major port city, serves as a distribution hub for imported and domestically produced industrial sacks.
Global Heavy Duty Bags and Sacks Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes within the heavy duty bags and sacks market. The market exhibits a tiered structure, with global diversified packaging conglomerates coexisting with regional specialists and commodity producers. These archetypes compete across various product types, from high-barrier specialty films to high-volume plastic bags. Companies often pursue strategic partnerships to expand their material science capabilities and enhance product performance. Geographic expansion into emerging markets also represents a common competitive move for scale players.
On the premium-tier vector, Amcor plc exemplifies a focus on innovative and sustainable packaging solutions, including advanced multi-layer films. Mondi Group, with its extensive paper and plastic production capabilities, occupies a position as a diversified provider across various product types. Berry Global, Inc. anchors the market through its manufacturing scale and broad geographic footprint, particularly in North America and Europe, serving diverse end-user segments with cost-effective solutions. These companies collectively influence material science advancements and market standards.
| Leading Market Players |
|---|
| LC Packaging International BV |
| Novolex |
| Mondi Group |
| Inteplast Group |
| Segezha Group LLC |
| Berry Global, Inc. |
| Sonoco Products Company |
| BAG Corp |
| Amcor plc |
| Others |
Cost & Logistics Intelligence
Two-week lead times for custom specialty sacks influence pricing power for advanced barrier films. This reflects a supply chain optimized for specific industrial requirements.
Pricing Analysis
The EU Green Deal dictates the pricing tier structure for sustainable heavy duty bags. Pricing stratifies across premium, standard, and economy tiers, driven by material science advancements and volume scale. Polymer price volatility stemming from crude oil fluctuations compresses margins for commodity sacks. Food and specialty chemical industries exhibit lower price sensitivity compared to high-volume construction and agriculture segments.
Supply Chain Analysis
High-volume inventory turns for commodity bags characterize the supply chain for basic products. Geographic supply concentrates in China and India for plastic and woven sacks, with Germany leading specialty material production. The market relies on polyethylene and polypropylene resins, exposing it to commodity price volatility. Distribution runs through direct manufacturer-to-end-user contracts and regional distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The heavy duty bags and sacks market presents a defensive-moat story due to regulatory entrenchment. Strict standards from the US FDA and EU REACH create significant barriers for new material and product introductions.
For Market Incumbents: Consolidate material science capabilities to counter the threat of biodegradable polymer adoption. Invest in mono-material polyethylene solutions to meet future EU Circular Economy Action Plan compliance. Expanding capacity in sub-Saharan Africa addresses growing agricultural demand for weather-resistant bags. Control over distribution channels mitigates competition from FIBCs in bulk logistics.
For New Entrants and Emerging Players: Anchor in niche applications requiring advanced barrier properties, such as specialty chemical packaging. The biodegradable materials segment, driven by EU Green Deal initiatives, offers a penetrable market. Go-to-market strategies should emphasize value-added services like smart packaging integration for traceability. Focus on regions with less established sustainable packaging infrastructure.
For Investors and Strategic Acquirers: Long-term, this sits as a specialty materials technology play because of escalating performance and sustainability demands. Acquisition targets should be vertically integrated mid-cap specialists with strong R&D in advanced polymers. The signal to watch is a consistent increase in M&A activity within the sustainable packaging technology sector. Focus on firms with established regulatory compliance expertise.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion in Emerging Markets | Addresses growing demand for basic sacks in developing agricultural sectors like Nigeria. |
| Advanced Mono-Material R&D | Ensures compliance with EU Circular Economy mandates for design-for-recycling principles. |
| Strategic Partnerships for Biodegradable Polymers | Accelerates adoption of environmentally compliant solutions for niche agricultural applications. |
| Integration of Smart Packaging Technologies | Offers value-added services for high-value goods, enhancing traceability and inventory management. |
| Backward Integration into Polymer Production | Mitigates raw material price volatility, securing cost-effective supply for key resins. |
Research Approach
Initial hypotheses were tested against primary input from packaging manufacturers, raw material suppliers, and end-user procurement managers, and refined through iterative analysis. This involved in-depth interviews with technical R&D directors and regulatory affairs specialists. Secondary validation utilized company annual reports, trade association publications, and government environmental reports. Bottom-up and top-down triangulation ensured data consistency.
Variance decomposition isolates the impact of key drivers on market growth across the analysis window. The framework modeled segmentation dimensions including product type, end user, material, and capacity, alongside specific barrier properties. Compound annual growth rates were derived from historical trends and projected future demand. Key forecast inputs included global agricultural output and construction spending.
Material uncertainties — including geopolitical events, rapid material science breakthroughs, and unforeseen regulatory shifts — sit outside the modeled envelope. Forecasts reflect assumptions documented through extensive primary and secondary research. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Heavy Duty Packaging
High-Density Packaging Market
Heavy Duty Packaging
Hazmat Packaging Market
Heavy Duty Packaging
High-Stress PCR HDPE Detergent Bottles Market
Heavy Duty Packaging
High Impact Corrugated Boxes Market
Heavy Duty Packaging
Large Blow Molded Products Market
Heavy Duty Packaging
Heavy Duty Bins Market
Heavy Duty Packaging
Heavy-Duty Corrugated Boxes Market
Heavy Duty Packaging
Heavy Duty Paper Tags Market
Heavy Duty Packaging
Europe High Density Polyethylene Jerrycan Market
Heavy Duty Packaging
Heavy Duty Corrugated Packaging Market
Heavy Duty Packaging
Heavy-Duty Paper and Multiwall Shipping Sack Market
Heavy Duty Packaging
Hazardous Goods Packaging Market