
 Heavy Duty Corrugated Packaging Market | 2026-2036
Heavy Duty Corrugated Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Heavy Duty Corrugated Packaging Market Foresight
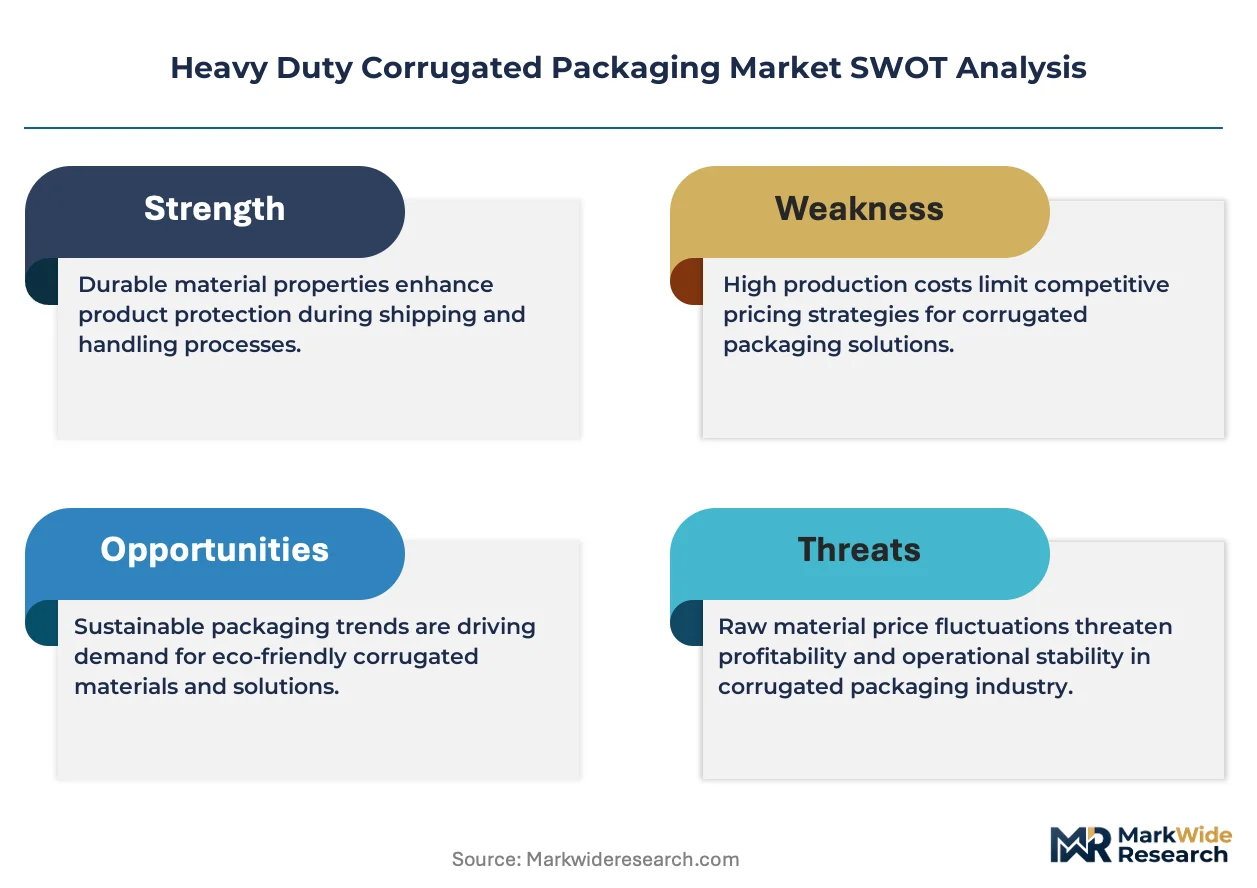
A shift from single-source to multi-source board procurement is broadening supplier rosters across the heavy duty corrugated value chain. Georgia-Pacific leverages its captive pulp supply to secure linerboard consistency for automotive and electronics customers. DS Smith anchors European demand through closed-loop recycling partnerships with grocery and beverage manufacturers.
Heavy duty corrugated packaging denotes multi-layer fibreboard structures—typically double-wall or triple-wall constructions exceeding 350 gsm total grammage—engineered to withstand stacking loads above 500 kg and moisture exposure during intermodal transit. Its primary purpose centers on protecting capital goods, dense industrial components, and bulk food shipments through distribution networks. Virgin paperboard commands premium positioning in electronics and pharmaceutical cold-chain applications where fiber cleanliness and caliper stability justify higher unit economics. Recycled paperboard competes aggressively in food and beverage trays and retail-ready displays where cost sensitivity outweighs structural precision.
The EPA regulates corrugated manufacturing emissions under Clean Air Act Title V permitting, while the EU Green Deal and F-Gas Regulation constrain energy-intensive production methods across member states. OSHA mandates govern warehouse stacking heights and worker safety protocols that directly influence box compression strength specifications. Stakeholders must monitor how divergent carbon-border adjustments between North America and Europe reshape landed costs for imported linerboard and finished containers.
Market Dynamics
Automotive parts suppliers are consolidating inbound logistics around triple-wall containers, forcing linerboard mills to recalibrate grammage specifications and moisture resistance ratings for intermodal handoffs.
Growth Catalysts
- EU Packaging and Packaging Waste Regulation:Tightened recyclability thresholds are compelling German automotive clusters to specify certified post-consumer fiber content, expanding closed-loop collection infrastructure across Stuttgart-to-Munich industrial corridors.
- Triple-wall construction:Dense industrial components exceeding 500 kg stacking loads now require crush-resistant flute profiles, pulling demand toward 800+ gsm board grades in electronics and capital goods distribution.
- Cold-chain pharmaceutical expansion:Fiber cleanliness mandates from FDA and EMA are elevating virgin kraft linerboard specifications for temperature-sensitive biologics transit.
Market Restraints
- Old corrugated container (OCC) price volatility:Recycled fiber input costs swing with municipal collection disruptions, compressing margin predictability for mid-tier converters serving retail-ready display segments.
- Energy-intensive production methods:EU F-Gas Regulation constraints on drying kiln emissions are elevating compliance costs for mills dependent on natural gas firing in Poland and Italy.
- Rigid plastic bulk containers:Returnable IBCs are capturing refillable chemical and food ingredient logistics, displacing single-trip corrugated in closed-loop fleet deployments.
Strategic Opportunities
- India's PLI scheme for manufacturing:Electronics assembly localization is creating virgin linerboard demand for semiconductor component export packaging with caliper stability requirements.
- Digital printing on heavy board:Water-based inkjet systems are converging with anti-scuff coatings, enabling lot-specific barcoding directly on triple-wall automotive containers without label adhesives.
- EU Green Deal carbon border adjustments:Imported linerboard landed cost differentials are incentivizing captive pulp integration among European integrated producers.
Industry Challenges
- Flute profile engineering talent:Specialized compression modeling for multi-wall structures requires scarce paper science expertise, elongating R&D cycles for custom automotive specifications.
- ISO 9001 and FSSC 22000 certification timelines:Food-contact board approvals demand 12-18 month audit windows, gating converter entry into beverage tray segments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Heavy Duty Corrugated Packaging Market |
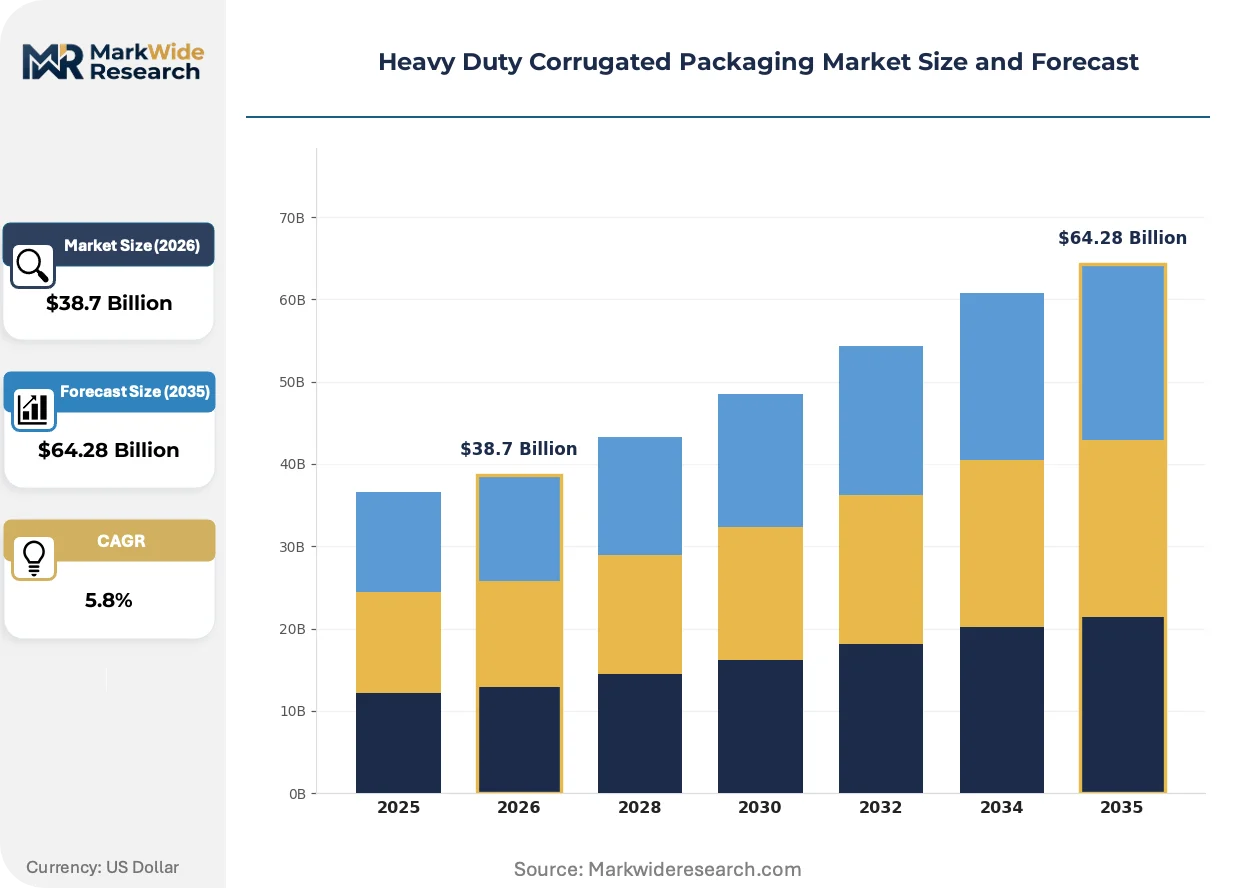
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $64.28 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Boxes, Trays, Sheets, Containers Material Type: Recycled Paperboard, Virgin Paperboard, Coated Board, Kraft Paper End User: Food & Beverage, Electronics, Automotive, Pharmaceuticals Distribution Channel: Online Sales, Direct Sales, Retail Outlets, Wholesale |
| Companies Covered | Georgia-Pacific LLC, DS Smith Plc, International Paper Company, Rengo Co. Ltd., Mondi Group Plc, Smurfit Westrock, Pratt Industries, Cascades Inc., Packaging Corporation of America, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Heavy Duty Corrugated Packaging Market Shifts & Advancements
Moisture-resistant barrier coatings and digital tracking integration are redefining performance benchmarks for heavy fiberboard, compressing the gap between single-use protection and returnable packaging economics.
Water-based polymer barrier coatings are converging with nanocellulose reinforcement layers to replace wax and polyethylene laminates in frozen food and agricultural export applications. Poultry and seafood processors in the Pacific Northwest are piloting these grades for ocean container transits exceeding 21 days. The technology is converging with RFID inlay embedding, enabling real-time humidity monitoring without compromising fiber recyclability streams.
REACH restrictions on per- and polyfluoroalkyl substances are eliminating oil-grease-resistant fluorochemical treatments from food-contact corrugated by 2025. German packaging converters are accelerating migration to bio-based sizing agents derived from plant proteins and starches. Cold-chain pharmaceutical shippers in the Benelux region are absorbing 8-12% unit cost premiums for PFAS-free certification to maintain EU market access.
Automotive tier-one suppliers are compressing supplier rosters from six board sources to two preferred mill partnerships with dedicated production lines. BMW and Mercedes-Benz logistics teams in Bavaria now require lot-traceable fiber provenance and 48-hour specification change turnaround. This consolidation is most visible in Germany's industrial corridor, where inbound container standardization is reducing dunnage complexity and warehouse slotting errors.
Heavy Duty Corrugated Packaging Market Segmentation
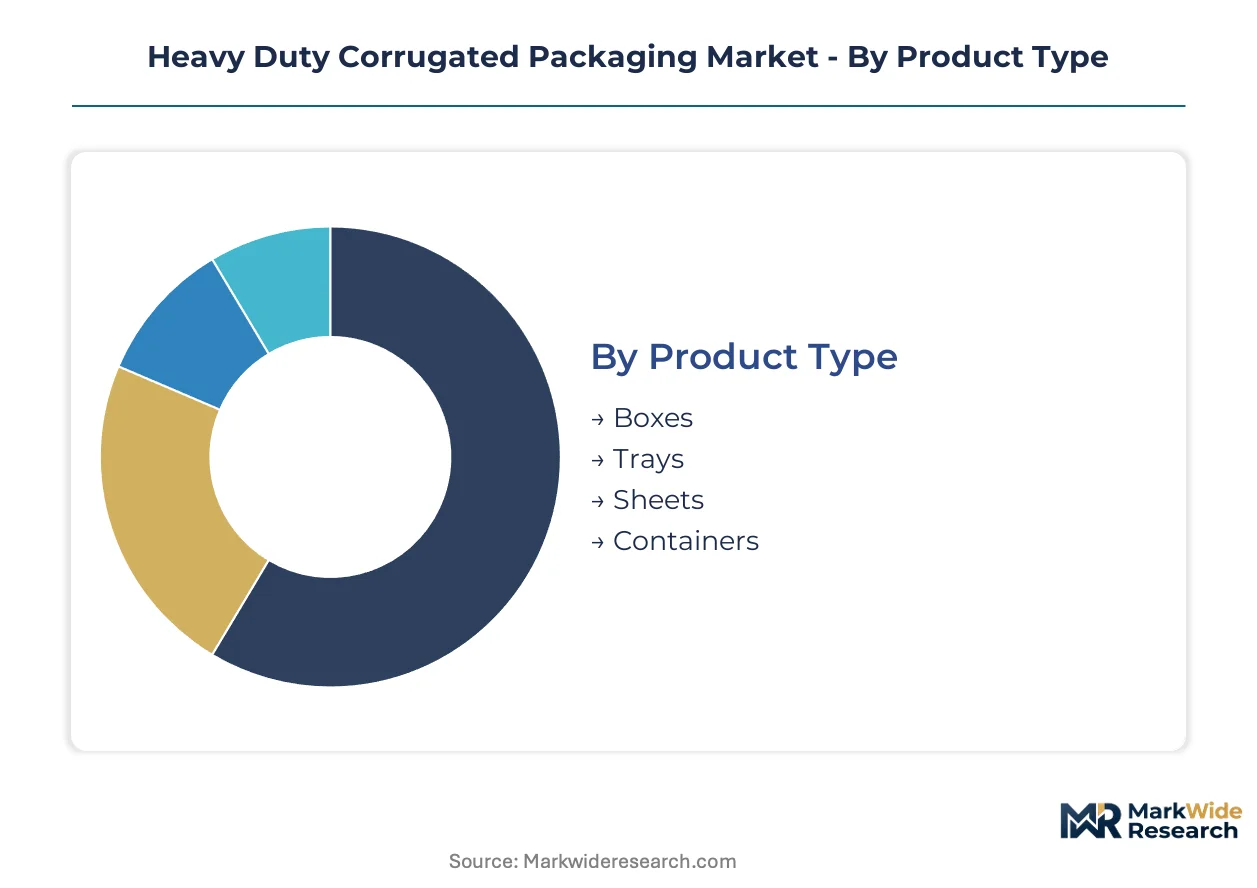
Heavy duty corrugated packaging demands precise specification matching across load-bearing requirements, fiber cleanliness standards, and moisture exposure profiles. Segmentation reveals where converters command premium pricing versus commodity competition.
Product Type:
Customization intensity spans from commodity sheets to engineered triple-wall containers with integrated dunnage.
- Boxes:Double-wall and triple-wall constructions dominate automotive inbound logistics, with BMW and Mercedes-Benz specifying 800+ gsm grades for 500 kg stacking loads across Bavarian distribution hubs. German tier-one suppliers now mandate lot-traceable fiber provenance and 48-hour specification change turnaround.
- Containers:Returnable IBC alternatives and single-trip bulk bins serve chemical and food ingredient logistics, though rigid plastic competitors are displacing volumes in closed-loop fleet deployments. Moisture-resistant barrier coatings are compressing the economics gap with reusable packaging.
- Trays:Retail-ready displays and beverage shipping platforms compete aggressively on cost sensitivity.
- Sheets:Flatboard for converter downstream processing fills commodity demand with thinner margin profiles.
Most installed capacity flows through Boxes. Expansion is steepest in Containers.
Material Type:
Cost tiers separate virgin kraft premiums from recycled fiber commoditization.
- Virgin Paperboard:Clean fiber and caliper stability command premium positioning in FDA and EMA-regulated pharmaceutical cold-chain applications. Biologics shippers absorb 8-12% unit cost premiums for fiber cleanliness certification.
- Recycled Paperboard:Post-consumer fiber content expands under EU Packaging and Packaging Waste Regulation thresholds, with German automotive clusters driving closed-loop collection infrastructure across Stuttgart-to-Munich corridors.
- Coated Board:Water-based polymer barriers with nanocellulose reinforcement replace wax laminates in Pacific Northwest seafood exports exceeding 21-day transits.
- Kraft Paper:Unbleached linerboard serves industrial wrapping and protective interleaving at economy pricing.
Volume concentrates in Recycled Paperboard. Value capture climbs fastest in Virgin Paperboard.
End User:
Application-specific performance requirements dictate board engineering complexity and certification burden.
- Automotive:Tier-one suppliers compress supplier rosters from six board sources to two preferred mill partnerships with dedicated production lines, standardizing inbound container specifications to reduce warehouse slotting errors.
- Pharmaceuticals:Temperature-sensitive biologics transit mandates fiber cleanliness from FDA and EMA regulators, elevating virgin linerboard specifications with full chain-of-custody documentation.
- Electronics:Semiconductor component export packaging from India's PLI scheme beneficiaries demands caliper stability for precision part protection.
- Food & Beverage:Trays and retail-ready displays prioritize cost efficiency over structural precision, with FSSC 22000 certification gating converter entry.
Procurement volume pools in Automotive. Margin expansion is sharpest in Pharmaceuticals.
Distribution Channel:
Customer type and order scale determine whether direct mill relationships or intermediary networks dominate fulfillment.
- Direct Sales:Automotive and pharmaceutical volume contracts flow through mill-direct relationships with specification engineering support and 48-hour turnaround commitments.
- Wholesale:Mid-tier converters and regional distributors aggregate demand from smaller food processors and agricultural exporters.
- Online Sales:Digital platforms capture spot purchasing for standardized sheet and tray grades with limited customization.
- Retail Outlets:Local packaging supply stores serve small-format businesses with immediate fulfillment needs.
Revenue weight sits with Direct Sales. Digital penetration is climbing fastest in Online Sales.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's industrial corridor from Stuttgart to Munich anchors procurement concentration for triple-wall automotive containers, while regulatory divergence between North America and Europe reshapes fiber sourcing economics across major manufacturing zones.
United States
Automotive inbound logistics in Michigan and Ohio drive specification demand for 800+ gsm board grades. EPA Clean Air Act Title V permitting constrains mill expansion timelines in the Southeast. BMW's Spartanburg assembly complex sources triple-wall containers from regional converters with 48-hour turnaround commitments.
Germany
Tier-one suppliers compress vendor rosters from six board sources to two preferred mill partnerships with dedicated production lines. EU Packaging and Packaging Waste Regulation mandates tighten post-consumer fiber thresholds. The Stuttgart-to-Munich corridor standardizes container specifications to reduce warehouse slotting errors.
China
Electronics assembly localization under industrial policy directives elevates virgin linerboard demand for semiconductor component export packaging. MEE enforcement of dual carbon goals constrains energy-intensive drying kiln operations. Yangtze River Delta converters calibrate moisture resistance ratings for intermodal handoffs.
India
PLI scheme beneficiaries for electronics manufacturing create caliper stability requirements for precision part protection. BIS fiber cleanliness standards intersect with FDA export documentation for pharmaceutical cold-chain shipments. Gujarat and Maharashtra assembly hubs pilot lot-traceable fiber provenance systems.
Japan
Automotive precision component logistics demand crush-resistant flute profiles for dense industrial parts. METI circular economy guidelines accelerate closed-loop collection infrastructure investment. Nagoya industrial zone converters integrate RFID inlay embedding for real-time humidity monitoring.
Heavy Duty Corrugated Packaging Market Competitive Landscape
Global majors compete with regional champions across fiber integration and specification engineering capabilities. The vendor base stratifies between integrated producers with captive pulp supply and independent converters dependent on spot linerboard markets. Three archetypes dominate: virgin kraft specialists serving pharmaceutical cold-chain applications, recycled fiber aggregators capturing EU regulatory compliance premiums, and automotive-dedicated engineering shops with rapid specification turnaround. Capacity expansion and backward integration into pulp assets represent the dominant competitive vectors.
Among North American integrated producers, Georgia-Pacific LLC and International Paper Company exemplify the captive supply archetype, while DS Smith Plc occupies a position within the European closed-loop recycling tier. Smurfit Westrock represents the scale-driven consolidation play, combining corrugated operations across multiple geographies.
| Leading Market Players |
|---|
| Georgia-Pacific LLC |
| DS Smith Plc |
| International Paper Company |
| Rengo Co. Ltd. |
| Mondi Group Plc |
| Smurfit Westrock |
| Pratt Industries |
| Cascades Inc. |
| Packaging Corporation of America |
| Others |
Supply & Pricing Matrix
Old corrugated container price swings cascade through converter margins, compressing mid-tier players serving retail-ready display segments while integrated mills with captive pulp supply capture premium positioning in pharmaceutical cold-chain applications. Energy costs tethered to natural gas pricing in Poland and Italy further stratify the board market across virgin kraft and recycled fiber tiers.
Pricing Analysis
Input-cost pass-through from OCC volatility and energy tariffs shapes contract structures across the value chain. Three-tier pricing structure across premium, standard, and economy levels separates FDA-certified virgin linerboard from FSSC 22000 food-contact grades and commodity recycled board. Pricing pressure stems from rigid plastic IBC displacement in closed-loop chemical logistics. Food and beverage tray buyers exhibit highest price sensitivity, while pharmaceutical shippers absorb cleanliness premiums.
Supply Chain Analysis
Single-source vulnerability sits with German automotive clusters dependent on dedicated mill partnerships along the Stuttgart-to-Munich corridor. Supply draws from integrated pulp assets in the United States, recycled fiber networks across Europe, and virgin kraft capacity in Asia-Pacific. Tariff exposure on imported linerboard under EU carbon border adjustments threatens converter margin stability. Distribution runs through direct mill relationships for automotive and pharmaceutical volume, with wholesale channels aggregating smaller food processor demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers margin expansion through captive pulp integration and premium-tier migration toward pharmaceutical cold-chain certification, offsetting commodity pressure in retail-ready segments.
For Market Incumbents: Deepen backward integration into pulp assets to secure linerboard consistency against OCC volatility, while expanding dedicated production line partnerships with BMW and Mercedes-Benz logistics teams to lock in automotive specification demand. Rigid plastic IBC competition and EU F-Gas Regulation compliance costs threaten unintegrated converters. For New Entrants and Emerging Players: Mid-tier pharmaceutical exporters in India present an underserved buyer archetype with unmet demand for BIS-FDA dual-certified virgin board with full chain-of-custody documentation. White-space targets include Gujarat and Maharashtra assembly hubs piloting lot-traceable fiber provenance systems, and Pacific Northwest seafood processors seeking PFAS-free barrier coatings for 21-day ocean transits. A certification-first go-to-market approach accelerates entry. For Investors and Strategic Acquirers: Consolidation pressure builds where converter fragmentation meets automotive supplier roster compression from six sources to two preferred mills. Long-term viability favors integrated producers with captive pulp and rapid specification turnaround capabilities. Acquisition targets include regional champions with ISO 9001 and FSSC 22000 certifications in food-contact board. Watch for EU Packaging and Packaging Waste Regulation enforcement tightening as the inflection signal for post-consumer fiber infrastructure valuation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Pulp Assets | Georgia-Pacific leverages captive supply to secure automotive and electronics customer consistency against OCC volatility. |
| Closed-Loop Recycling Partnership | DS Smith anchors European demand through grocery and beverage manufacturer circular economy alliances. |
| Digital Printing Capability Investment | Water-based inkjet systems with anti-scuff coatings enable lot-specific barcoding on triple-wall automotive containers. |
| PFAS-Free Certification Migration | German converters absorb 8-12% unit cost premiums to maintain EU market access under REACH restrictions. |
| Rapid Specification Turnaround Infrastructure | BMW and Mercedes-Benz logistics teams in Bavaria mandate 48-hour specification change capability from preferred mills. |
Research Methodology
Direct dialogue with linerboard mill procurement directors, automotive Tier 1 supplier logistics managers, pharmaceutical cold-chain packaging engineers, and corrugated converter operations heads grounded qualitative insights. Secondary validation drew from EPA Clean Air Act Title V permitting databases, EU Packaging and Packaging Waste Regulation filings, OCC price indices, and SEC 10-K disclosures from integrated producers. Bottom-up volume modeling across product type, material grade, and end-use segments triangulated with top-down macroeconomic drivers.
Bottom-up segmentation analysis tracked double-wall and triple-wall box demand, virgin versus recycled fiber mix, and automotive-pharmaceutical-electronics end-use splits across the projection horizon. Analytical frameworks incorporated grammage specification trends, moisture resistance rating evolution, and flute profile engineering intensity. CAGRs derived from shipment volume trajectories, capacity expansion announcements, and regulatory compliance cost absorption patterns.
Underlying measurement precision varies by segment; pharmaceutical cold-chain and automotive inbound logistics carry tighter precision than commodity retail-ready trays. Forecasts reflect assumptions around EU regulatory enforcement timing, OCC collection infrastructure investment, and carbon border adjustment implementation. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Heavy Duty Packaging
High-Density Packaging Market
Heavy Duty Packaging
Large Blow Molded Products Market
Heavy Duty Packaging
Hazmat Packaging Market
Heavy Duty Packaging
Global Heavy Duty Bags and Sacks Market
Heavy Duty Packaging
Europe High Density Polyethylene Jerrycan Market
Heavy Duty Packaging
Heavy Duty Paper Tags Market
Heavy Duty Packaging
Hazardous Goods Packaging Market
Heavy Duty Packaging
Heavy-Duty Paper and Multiwall Shipping Sack Market
Heavy Duty Packaging
High-Stress PCR HDPE Detergent Bottles Market
Heavy Duty Packaging
High Impact Corrugated Boxes Market
Heavy Duty Packaging
Heavy Duty Bins Market
Heavy Duty Packaging
Heavy-Duty Corrugated Boxes Market