
 Anti-Static Collapsible Tote Bins Market | 2026-2036
Anti-Static Collapsible Tote Bins Market Size, Share, and Industry Trends Forecast 2026-2036
Anti-Static Collapsible Tote Bins Market Outlook
ANSI/ESD S20.20 certification is reorganizing competitive access in the anti-static collapsible tote bins space, filtering out suppliers lacking validated electrostatic discharge control programs. ULINE leverages its North American distribution infrastructure to sustain bulk contract fulfillment for electronics OEMs. SSI Schaefer Ltd anchors European demand through automated warehouse integration capabilities. Akro-Mils differentiates via specialized conductive material formulations for pharmaceutical cleanroom protocols.
Anti-static collapsible tote bins are reusable polymer containers engineered with surface resistivity between 10^4 and 10^11 ohms per square, typically injection-molded from carbon-filled polypropylene or PVC composites to dissipate electrostatic charges during component transport. Polypropylene dominates material selection due to its chemical resistance and compliance with FDA and EFSA food-contact frameworks, while PVC retains share in heavy-duty automotive applications where flame retardancy matters. Electronics applications lead volume absorption as wafer and PCB manufacturers mandate ESD-safe material handling, though pharmaceutical segment growth is accelerating behind USP <797> cleanroom requirements and expanded biologics production.
FDA cGMP guidelines, EPA hazardous substance labeling rules, and OSHA workplace safety standards collectively shape product design and market access for domestic suppliers. ESD Association standards and IEC 61340 testing protocols define international interoperability benchmarks that cross-border vendors must satisfy. Stakeholders should monitor evolving semiconductor fab construction cycles and regional cleanroom expansion timelines to calibrate capacity and certification investments.
Market Dynamics
Semiconductor fab construction cycles in Taiwan and South Korea are compressing procurement timelines for electrostatic discharge-compliant material handling systems, forcing container suppliers to synchronize certification investments with cleanroom expansion schedules.
Growth Catalysts
- REACH substance restrictions:European ECHA mandates on halogen-free formulations are redirecting R&D budgets toward compliant polypropylene compounds, opening procurement channels for certified suppliers.
- Wafer transport protocols:Taiwan semiconductor manufacturers now specify surface resistivity between 10^6 and 10^9 ohms per square for intra-fab component movement, expanding the addressable specification window.
- Biologics cleanroom expansion:USP <797> compliance requirements in US pharmaceutical manufacturing are generating parallel demand for ESD-safe containers outside traditional electronics channels.
Market Restraints
- Carbon black feedstock volatility:Conductive polypropylene formulations depend on petroleum-derived carbon fillers, exposing margin structures to crude price swings.
- Injection molding equipment concentration:High-tonnage presses for industrial tote production cluster in Guangdong and Zhejiang provinces, creating geographic supply vulnerability.
- PVC substitution ceiling:Flame-retardant automotive applications retain material preference where halogen content remains permissible, slowing full conversion to polypropylene alternatives.
Strategic Opportunities
- Indian electronics manufacturing:PLI scheme incentives for semiconductor assembly and testing facilities in Gujarat and Karnataka are seeding greenfield demand for localized ESD container supply.
- RFID-integrated tracking:Convergence of conductive polymer formulations with embedded sensor tags enables real-time inventory visibility for automated warehouse systems.
- Reusable packaging mandates:Extended producer responsibility frameworks in Germany and France are penalizing single-use alternatives, accelerating tote adoption in cross-border logistics.
Industry Challenges
- ANSI/ESD S20.20 certification timelines:Third-party validation programs require 8-14 month completion cycles, delaying market entry for new material formulations.
- Cleanroom integration complexity:Existing automated material handling systems in Seoul and Shenzhen facilities operate on proprietary control protocols, necessitating custom adapter engineering for container compatibility.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Anti-Static Collapsible Tote Bins Market |
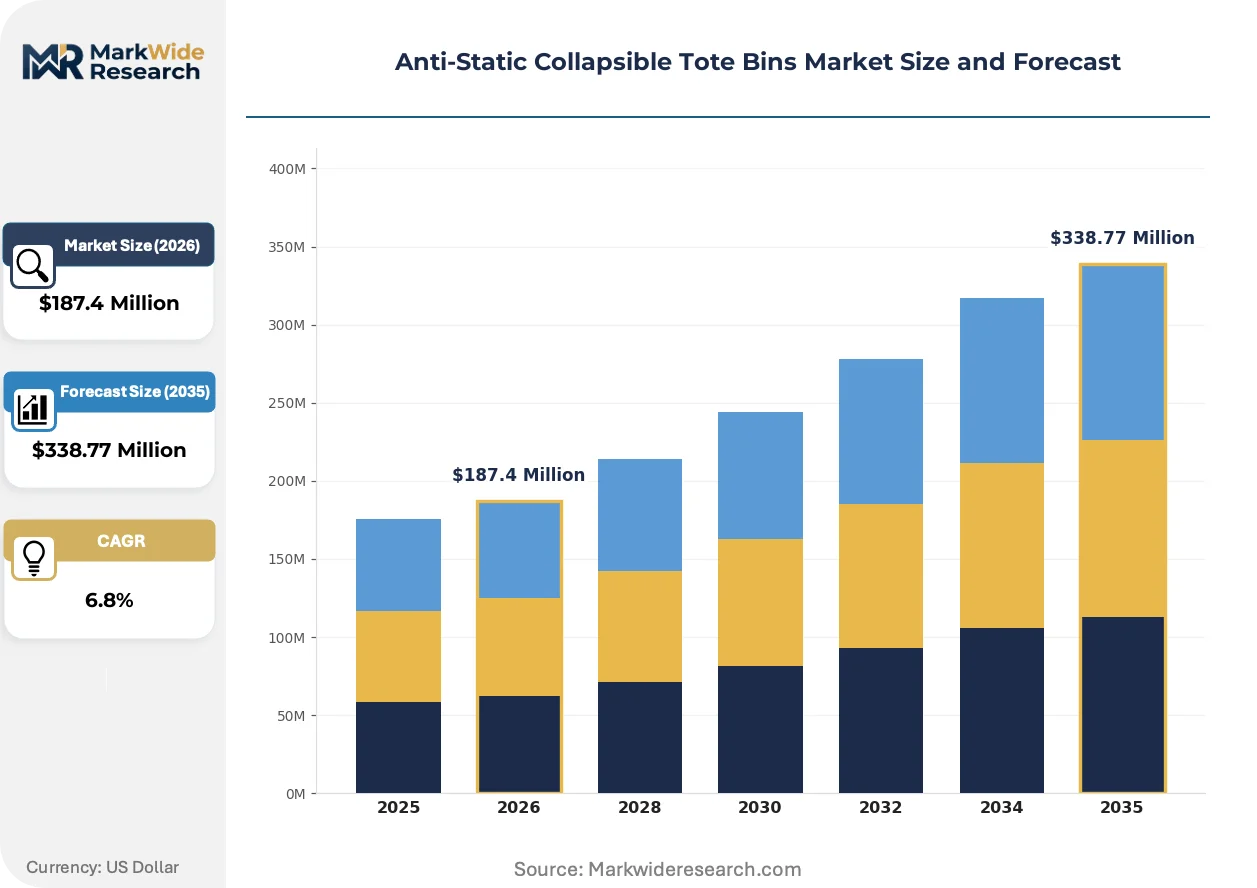
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material: Polypropylene, Polyester, PVC, Nylon Application: Electronics, Automotive, Pharmaceuticals, Retail Size: Small, Medium, Large, Extra Large Distribution Channel: Online Retail, Direct Sales, Distributors, Wholesalers |
| Companies Covered | ULINE, Elcom Ltd., GWP Group Limited, Protektive Pak, CYG TEFA CO.,LTD, SSI Schaefer Ltd, Rubbermaid Commercial Products, AUER Packaging U.K., Akro-Mils, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Anti-Static Collapsible Tote Bins Market Strategic Shifts
Material science advances and regulatory stringency are fragmenting the competitive landscape into specialized certification tiers, with differentiation increasingly anchored in validated electrostatic control rather than commodity polymer processing.
Carbon nanotube-doped polypropylene is bifurcating the conductive materials segment from traditional carbon-black composites. Wafer manufacturers in Hsinchu Science Park are specifying nanotube formulations for sub-10 nanometer process nodes where particulate contamination thresholds have tightened. This technology is compressing the viable supplier base to compounders with in-house dispersion capabilities and cleanroom extrusion infrastructure.
EU F-Gas Regulation amendments are restricting hydrofluorocarbon use in polymer foam insulation, indirectly affecting tote bin thermal management accessories. European pharmaceutical distributors are responding by eliminating auxiliary cooling inserts from standard container specifications, shifting thermal control burden to transport vehicle systems. German logistics operators have accelerated this transition ahead of the 2027 phase-down deadlines.
Buyer consolidation among contract electronics manufacturers is concentrating procurement authority at the OEM level rather than distributed across tiered supplier networks. Taiwan-based foundries now negotiate master service agreements covering ESD materials across multiple fabrication sites, displacing site-level purchasing autonomy. This pattern is most pronounced in Kaohsiung and Taichung corridor facilities where centralized supply chain functions have absorbed regional buying decisions.
Anti-Static Collapsible Tote Bins Market Segmentation
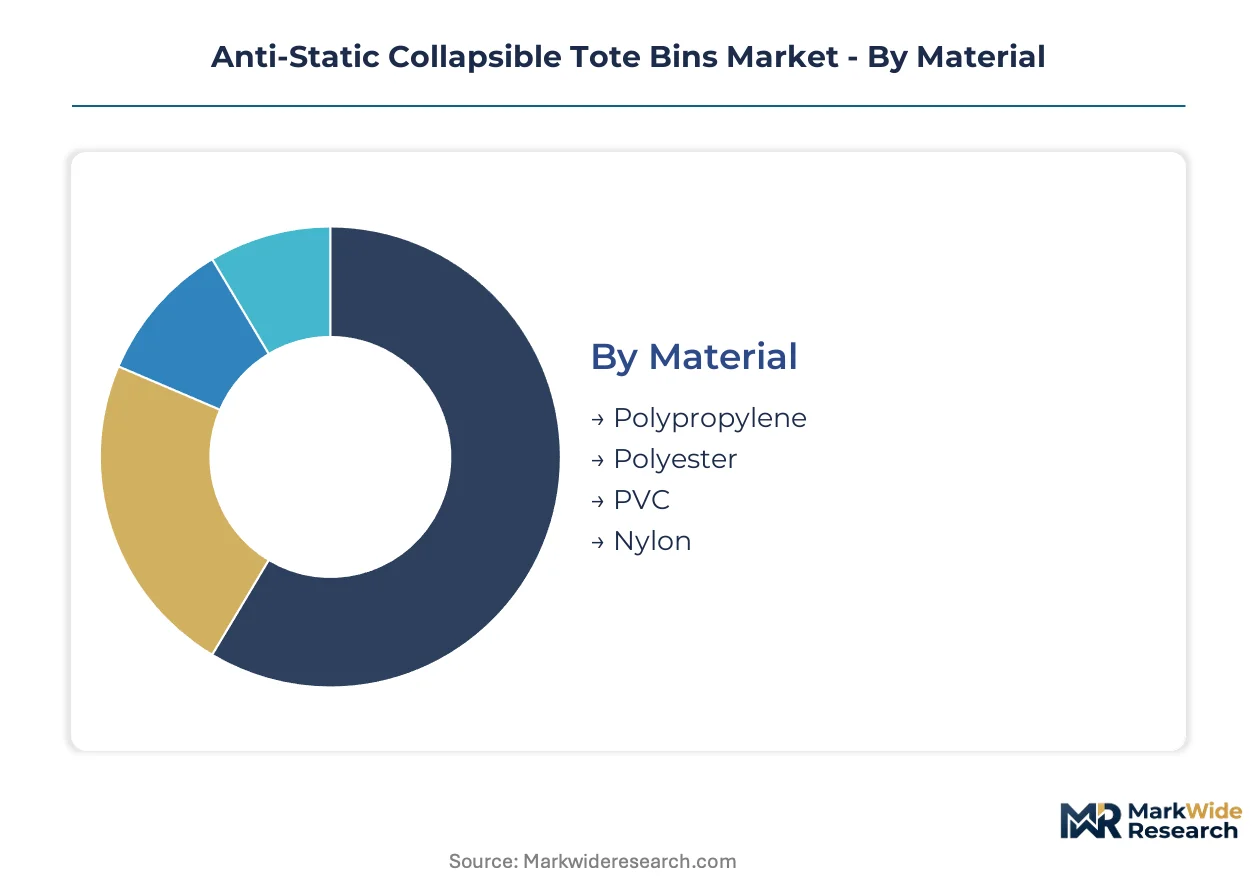
Material specifications and application requirements fragment procurement patterns across the anti-static collapsible tote bins market, with substitution pressures from alternative ESD protection methods reshaping segment viability. Understanding where specification windows tighten versus commoditize determines supplier positioning and margin sustainability.
Material:
Substitution pressure from carbon nanotube formulations and halogen-free compounds is compressing share for legacy conductive fillers, particularly where REACH and RoHS substance restrictions apply.
- Polypropylene:Injection-molded homopolymer dominates due to chemical resistance and FDA/EFSA food-contact compliance. Semiconductor cleanroom operations in Taiwan and South Korea specify this material for wafer transport protocols requiring surface resistivity between 10^6 and 10^9 ohms per square.
- PVC:Retains position in heavy-duty automotive applications where flame retardancy outweighs halogen-content concerns. German automotive suppliers continue specifying PVC for battery component handling despite EU regulatory pressure on chlorine-based formulations.
- Polyester:Woven fabric variants serve collapsible designs requiring textile flexibility for space-constrained reverse logistics.
- Nylon:Higher tensile strength supports load-bearing specifications in aerospace component transport where abrasion resistance is critical.
Polypropylene anchors the volume base while carbon nanotube-doped alternatives gain share at the steepest rate among advanced semiconductor manufacturers.
Application:
Cost tier stratification separates specification-intensive cleanroom deployments from standard industrial material handling, with certification requirements driving 3-5x pricing multiples at the premium end.
- Electronics:Wafer and PCB manufacturers mandate ANSI/ESD S20.20-certified containers with validated electrostatic discharge control programs. Taiwan-based foundries negotiate master service agreements covering multiple fabrication sites, concentrating procurement authority at the OEM level.
- Pharmaceuticals:USP <797> cleanroom requirements and expanded biologics production generate demand for ESD-safe containers outside traditional electronics channels. FDA cGMP guidelines shape product design and market access for domestic suppliers.
- Automotive:Battery assembly lines require flame-retardant formulations where thermal runaway protection intersects with static control needs.
- Retail:Reusable packaging mandates in Germany and France under extended producer responsibility frameworks accelerate tote adoption in cross-border logistics.
Electronics commands the revenue concentration while pharmaceuticals expands most quickly behind biologics cleanroom construction.
Size:
Volume concentration in medium and large formats reflects automated warehouse compatibility requirements, with dimensional standardization reducing custom engineering overhead.
- Medium:Dominates intra-fab component movement in Hsinchu Science Park facilities where conveyor system integration demands uniform footprint dimensions. Seoul-based semiconductor plants specify this format for automated material handling system compatibility.
- Large:Supports bulk substrate transport between fabrication sites, with Taiwan foundries standardizing on this format for inter-site logistics consolidation.
- Small:Serves precision component handling where individual wafer or die protection requires compartmentalized interior configurations.
- Extra Large:Accommodates oversized PCB panels and display substrates in Shenzhen electronics manufacturing clusters.
Medium formats generate the shipment volume while large formats capture expanding share through foundry consolidation trends.
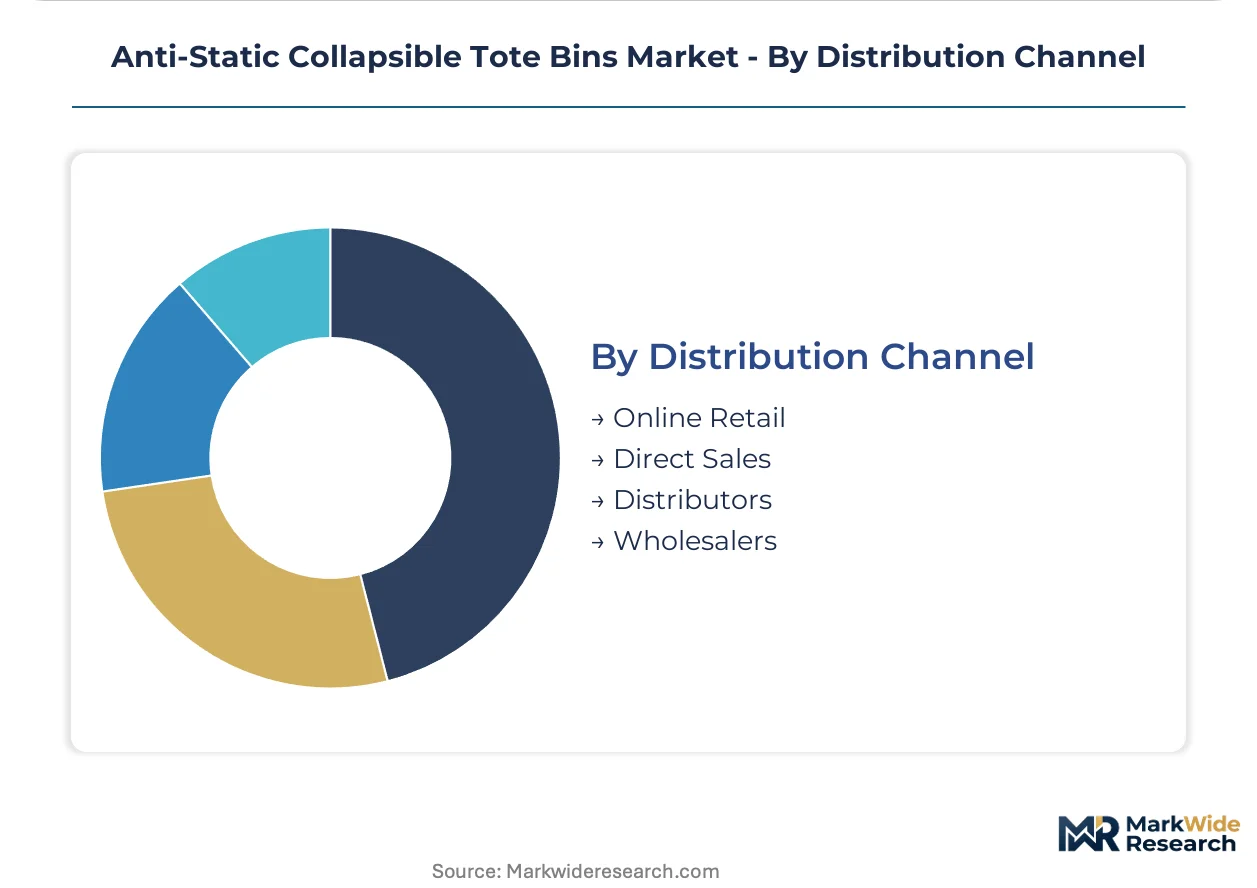
Distribution Channel:
Customer type bifurcation separates contract electronics manufacturers seeking direct technical partnership from smaller operators purchasing through intermediaries.
- Direct Sales:Taiwan-based foundries and South Korean semiconductor manufacturers negotiate master service agreements with compounders possessing in-house dispersion capabilities and cleanroom extrusion infrastructure.
- Distributors:European pharmaceutical distributors rely on this channel for ESD-compliant container procurement under EU F-Gas Regulation thermal management constraints.
- Online Retail:Serves maintenance-repair-operations procurement for smaller electronics assemblers in India PLI scheme facilities.
- Wholesalers:Aggregates demand from automotive tier suppliers in Guangdong province where injection molding equipment concentration creates geographic supply proximity.
Direct sales commands the contract value concentration while distributor relationships expand most quickly among mid-tier pharmaceutical manufacturers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Government incentive programs and cleanroom construction timelines are redrawing procurement maps for electrostatic discharge-compliant material handling systems across major electronics manufacturing jurisdictions.
Taiwan
Semiconductor foundry expansion in Hsinchu Science Park and Tainan Science Park is compressing vendor qualification timelines for ANSI/ESD S20.20-certified containers. The National Development Council's chip industry support framework subsidizes domestic supply chain localization. Kaohsiung corridor facilities now negotiate consolidated master service agreements covering multiple fabrication sites.
South Korea
Samsung and SK Hynix fab construction in Pyeongtaek and Yongin is synchronizing with container supplier certification investments. The Ministry of Trade, Industry and Energy classifies ESD materials as strategic components under its semiconductor independence initiative. Seoul Capital Area plants specify medium-format totes for automated material handling system compatibility.
China
Shenzhen electronics clusters and Yangtze River Delta semiconductor packaging facilities are absorbing volume for intra-fab component movement. MIIT domestic substitution mandates favor local compounders with carbon nanotube dispersion capabilities. Guangdong province injection molding equipment concentration creates geographic supply proximity for regional demand.
Germany
Automotive battery assembly lines in Bavaria and Baden-Württemberg require flame-retardant formulations where thermal runaway protection intersects with static control. REACH substance restrictions redirect procurement toward halogen-free polypropylene compounds. ECHA compliance timelines are accelerating supplier qualification cycles for cross-border logistics operators.
United States
Biologics cleanroom expansion under USP <797> compliance requirements is generating ESD container demand outside traditional electronics channels. FDA cGMP guidelines shape product design specifications for pharmaceutical manufacturers. Greater Boston and Research Triangle Park facilities anchor the Atlantic seaboard concentration.
Anti-Static Collapsible Tote Bins Market Competitive Environment
Player mix skews toward diversified material handling conglomerates with adjacent warehouse automation portfolios. Market structure exhibits moderate consolidation around compounders possessing in-house dispersion capabilities and cleanroom extrusion infrastructure. Two strategic archetypes dominate: vertically integrated polymer processors and specialized ESD certification laboratories. Competitive moves concentrate on geographic expansion through distributor partnerships and technology licensing for RFID-integrated tracking formulations.
Among North American distributors, ULINE occupies a position exemplifying bulk contract fulfillment scale for electronics OEMs. SSI Schaefer Ltd anchors the European archetype through automated warehouse integration capabilities. Akro-Mils represents the specialized conductive formulation segment for pharmaceutical cleanroom protocols. These three companies illustrate how certification depth and regional logistics infrastructure determine competitive positioning in procurement channels.
| Leading Market Players |
|---|
| ULINE |
| Elcom Ltd. |
| GWP Group Limited |
| Protektive Pak |
| CYG TEFA CO.,LTD |
| SSI Schaefer Ltd |
| Rubbermaid Commercial Products |
| AUER Packaging U.K. |
| Akro-Mils |
| Others |
Value Chain & Pricing Dynamics
High-tonnage injection molding capacity utilization in Guangdong and Zhejiang provinces creates scale economies that compress unit economics for carbon-filled polypropylene formulations, simultaneously anchoring price floors and concentrating supply leverage among compounders with captive carbon black sourcing.
Pricing Analysis
Certification level (ANSI/ESD S20.20 versus unvalidated commodity grade) creates the primary spread across pricing tiers, with validated electrostatic discharge control programs commanding three-to-five multiples over standard industrial containers. Volume scale and geographic delivery cost provide secondary differentiation, with Taiwan-based foundries negotiating master service agreements that bundle multi-site procurement. Cost compression in the commodity tier is intensifying because carbon black feedstock volatility exposes margin structures to crude price swings. Smaller electronics assemblers in India PLI scheme facilities exhibit the highest price sensitivity, while semiconductor cleanroom operators in Hsinchu Science Park prioritize specification compliance over unit cost.
Supply Chain Analysis
Taiwan and South Korea anchor wafer fabrication demand, while Guangdong province concentrates injection molding equipment for container production. Conductive polypropylene formulations draw from petroleum-derived carbon fillers and specialized compounding additives, with cleanroom extrusion infrastructure serving as a bottleneck input. Single-source vulnerability concentrates in carbon nanotube dispersion capabilities, where qualified compounders with in-house expertise remain limited. Distribution runs through direct sales channels for contract electronics manufacturers and distributor networks for mid-tier pharmaceutical operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Validated electrostatic discharge control programs and cleanroom extrusion infrastructure represent scarce capabilities that filter competitive access, with the supplier base compressing toward compounders possessing both ANSI/ESD S20.20 certification and carbon nanotube dispersion expertise.
For Market Incumbents: Fortify certification depth by accelerating ANSI/ESD S20.20 validation timelines for carbon nanotube-doped formulations, defending against emerging compounders from China's MIIT-favored domestic substitution pipeline. Prioritize backward integration into carbon black sourcing to buffer margin structures from petroleum price volatility, while expanding cleanroom extrusion capacity in Taiwan and South Korea to synchronize with foundry construction cycles.
For New Entrants and Emerging Players: Lead with RFID-integrated tracking formulations as a differentiated wedge into automated warehouse integration opportunities, targeting mid-tier pharmaceutical manufacturers in Germany and France where extended producer responsibility mandates are accelerating reusable packaging adoption. Focus initial penetration on the US biologics cleanroom expansion segment, where USP <797> compliance requirements have outpaced established supplier qualification capacity.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors compounders with demonstrated carbon nanotube dispersion capabilities and existing cleanroom infrastructure, as wafer manufacturers tighten particulate contamination thresholds for sub-10 nanometer process nodes. Long-term viability hinges on supply chain localization trends in India PLI scheme jurisdictions and semiconductor independence initiatives in South Korea. Monitor carbon black feedstock contract renegotiation patterns as an inflection indicator for margin compression timing.
| Strategic Initiative | Industry Significance |
|---|---|
| ANSI/ESD S20.20 Certification Investment | Validates electrostatic discharge control programs for Taiwan foundry master service agreements. |
| Carbon Nanotube Dispersion Capability Buildout | Enables qualification for Hsinchu Science Park sub-10 nanometer wafer transport protocols. |
| RFID-Integrated Tracking Formulation Launch | Captures automated warehouse integration demand from Seoul Capital Area semiconductor plants. |
| Halogen-Free Polypropylene Compound Development | Secures REACH compliance access for European pharmaceutical distributor procurement channels. |
| India PLI Scheme Localization Partnership | Positions supply proximity for Gujarat and Karnataka semiconductor assembly facilities. |
Study Parameters
A standing panel of cleanroom operations managers, semiconductor procurement directors, pharmaceutical supply chain leads, and conductive materials compounders provided ongoing calibration across the study period. Primary fieldwork combined structured interviews with secondary validation from SEC filings of listed material handling conglomerates, ECHA REACH substance restriction databases, and Taiwan National Development Council chip industry support framework documentation. Customs records from Guangdong and Zhejiang provinces, FDA cGMP guidance documents, and IEC 61340 testing protocol publications anchored bottom-up volume estimation. Top-down triangulation cross-checked against foundry construction cycle announcements from Samsung, SK Hynix, and Taiwan Semiconductor Manufacturing.
Model outputs were validated against external benchmarks including semiconductor capital expenditure disclosures, cleanroom construction permit filings in Hsinchu and Tainan Science Parks, and extended producer responsibility framework implementation timelines in Germany and France. Segmentation modeling spanned material formulation, application end-use, dimensional format, and distribution channel across the projection horizon. CAGRs were derived from fitted growth curves calibrated to historical procurement patterns and forward-looking fab capacity expansion schedules. Carbon black feedstock price indices, injection molding equipment utilization surveys, and ANSI/ESD S20.20 certification completion timelines served as industry-specific forecast inputs.
The analysis sits within stated boundaries; outcomes outside sustained semiconductor fab construction momentum, stable carbon black supply conditions, or continued REACH regulatory stringency would require recalibration. Forecasts reflect documented assumptions regarding cleanroom expansion timelines, compounder qualification rates, and regional substitution policy implementation. Recalibration cycles align with material shifts in semiconductor process node transitions, ECHA substance restriction amendment schedules, and PLI scheme incentive disbursement patterns.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bags and Containers
Garbage Bag Market
Bags and Containers
Mylar Bags Market
Bags and Containers
Isothermal Bags and Containers Market
Bags and Containers
Shrink Bags Market
Bags and Containers
Hermetic Storage Bags Market
Bags and Containers
Liner Bags Market
Bags and Containers
Laser Scored Bags Market
Bags and Containers
Bulk Bag Divider Market
Bags and Containers
Crates Market
Bags and Containers
Low Melt Point Bags Market
Bags and Containers
Frosted Bag Market
Bags and Containers
Self-Sealed Bubble Bags Market
Bags and Containers
Scented Trash Bags Market
Bags and Containers
Tote and Ingredient Bags Packaging Market
Bags and Containers
Global PP Jumbo Bags Market
Bags and Containers
Net Bags Market