
 Heavy Duty Paper Tags Market | 2026-2036
Heavy Duty Paper Tags Market Size, Share, and Industry Trends Forecast 2026-2036
Heavy Duty Paper Tags Market Foresight
Subscription-based tag replenishment services is expanding as a recurring revenue layer that shifts buyer relationships from transactional orders to contracted inventory programs. Avery Dennison Corporation leverages its global adhesive science footprint to anchor premium coated-paper tag lines for industrial clients. Brady Corporation specializes in harsh-environment specifications that differentiate its offerings from commodity alternatives. SATO Holdings Corporation dominates RFID-integrated paper tag architectures in Asian manufacturing corridors.
Heavy duty paper tags are reinforced fiber-based identification substrates, typically constructed from 10–18 point cardstock or laminated kraft paper, designed to withstand abrasion, moisture exposure, and repeated handling in logistics and manufacturing environments. Their primary purpose is to carry barcode, human-readable, or RFID-encoded data through supply chain touchpoints without substrate failure. Printed tags command the largest volume share due to pre-encoded shipping and compliance requirements, while adhesive tags represent the fastest-growing configuration as warehouse automation demands peel-and-stick application speed. Kraft paper tags carry expanding margin pools as sustainability procurement policies favor unbleached, FSC-certified fiber sources over virgin coated alternatives.
FDA food-contact regulations and OSHA hazard-communication standards shape material selection and print durability requirements for tags entering pharmaceutical and chemical handling workflows. The EU Green Deal and REACH frameworks restrict certain coating chemistries, redirecting R&D toward bio-based barrier treatments. Stakeholders must monitor how EPR legislation and packaging-waste directives in multiple jurisdictions redefine recyclability certifications as competitive gatekeepers rather than optional premiums.
Market Dynamics
E-commerce fulfillment networks are compressing order cycles and demanding tear-resistant paper tags that survive automated sortation, while REACH and EU Green Deal compliance is redirecting substrate R&D toward bio-based barrier coatings.
Growth Catalysts
- Warehouse robotics integration:Automated picking systems require adhesive-backed heavy duty tags that withstand repeated mechanical handling without edge fraying or barcode degradation.
- REACH chemical restrictions:European coating chemistries face substitution mandates, accelerating development of plant-derived moisture barriers for kraft paper substrates.
- Germany automotive parts tagging:Tier-1 suppliers specify 18-point laminated tags for engine component traceability through heat-treatment and machining workflows.
Market Restraints
- Pulp fiber cost volatility:Unbleached kraft pulp prices fluctuate with Nordic supply disruptions, squeezing margin on FSC-certified product lines.
- Concentrated adhesive supply:Acrylic pressure-sensitive adhesive production clusters in Belgium and the Netherlands, creating single-source vulnerability for tag converters.
- Plastic tag substitution:Polypropylene synthetic tags offer superior moisture resistance in cold-chain logistics, threatening paper share in pharmaceutical distribution.
Strategic Opportunities
- India manufacturing corridors:PLI scheme incentives for electronics assembly are creating demand for ESD-safe paper tags with conductive coatings.
- RFID inlay convergence:UHF chip antenna integration with fiber substrates enables item-level tracking without separate plastic enclosures.
- Subscription replenishment models:Contracted inventory programs lock in multi-year tag supply agreements with 3PL operators.
Industry Challenges
- Print durability certification:ISO 12947 abrasion testing extends qualification timelines for new substrate-coating combinations.
- Legacy WMS integration:Warehouse management systems require middleware development to parse RFID-encoded paper tag data streams.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Heavy Duty Paper Tags Market |
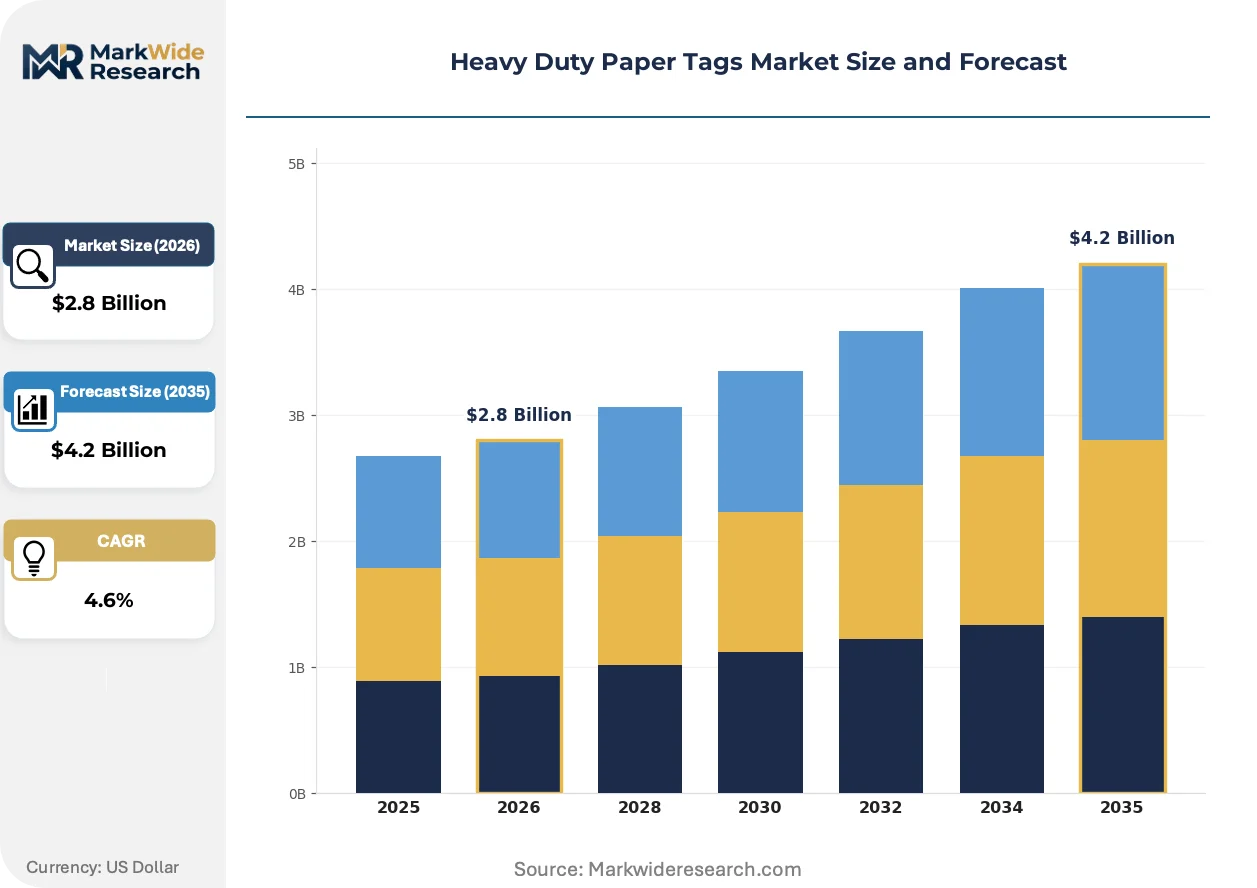
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.2 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Tags, Adhesive Tags, Plain Tags, Printed Tags Material: Cardstock, Recycled Paper, Coated Paper, Kraft Paper Application: Gift Tagging, Inventory Control, Labeling, Industrial Use Size: Small, Medium, Large, Custom |
| Companies Covered | Avery Dennison Corporation, 3M Company, Brady Corporation, Zebra Technologies Corporation, SATO Holdings Corporation, Uline, Metalcraft, Inc., Dutch Label Shop, The Nilorn Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Heavy Duty Paper Tags Market Shifts & Advancements
Digital print technologies and bio-based material science are converging to redefine tag performance specifications, while procurement models evolve toward integrated supply contracts.
Laser die-cutting systems paired with digital inkjet presses are automating short-run custom tag production for seasonal retail workflows. Third-party logistics providers in the Netherlands adopt these systems to compress turnaround from two weeks to 48 hours. Variable-data printing is automating the elimination of pre-printed inventory buffers and reducing obsolescence write-offs.
EU Green Deal packaging-waste directives are mandating recyclability certifications as competitive gatekeepers for public-sector procurement. Bio-based barrier treatments derived from cellulose nanofibrils substitute petroleum-based polyethylene coatings. German automotive suppliers now specify cradle-to-cradle certified tags for component traceability programs.
Buyer consolidation among mega-3PL operators concentrates purchasing power and compresses supplier margins. DHL Supply Chain and similar operators unbundle tag procurement from broader packaging contracts to negotiate direct substrate supply agreements. This concentration is most visible in Benelux distribution corridors where automated fulfillment density exceeds European averages.
Heavy Duty Paper Tags Market Segmentation
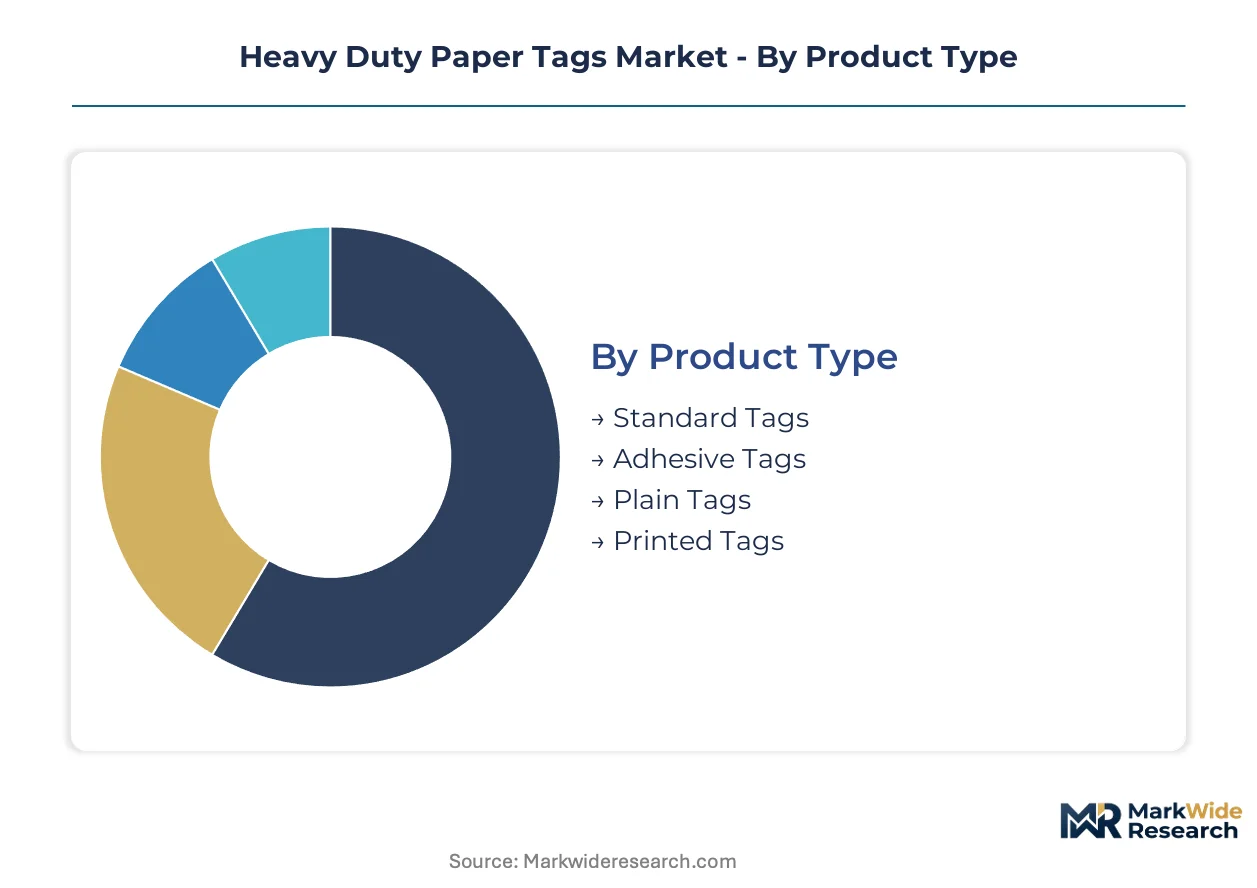
Segmentation in heavy duty paper tags reveals how capital allocation, substrate specifications, and application durability requirements fragment manufacturing strategies. Converters must balance equipment specialization against volume flexibility across divergent end-use specifications.
Product Type:
Capital intensity peaks with adhesive tag production, where precision coating lines and die-cutting automation demand seven-figure equipment investments before commercial viability.
- Standard Tags:These 10–14 point cardstock substrates with pre-punched holes serve general logistics and retail applications. German automotive suppliers specify laminated standard tags for heat-treatment traceability, though REACH coating restrictions are forcing substrate reformulation toward bio-based barriers.
- Adhesive Tags:Pressure-sensitive constructions combine fiber substrates with acrylic adhesive layers for peel-and-stick deployment in automated warehouses. E-commerce fulfillment centers in the Netherlands and Belgium are driving specifications for edge-fray resistance under robotic handling systems.
- Plain Tags:Unprinted fiber substrates allow end-user customization through thermal transfer or handwriting. These carry lower equipment barriers and attract regional converters serving seasonal agricultural and construction workflows.
- Printed Tags:Pre-encoded variable data including barcodes, serial numbers, and compliance markings. FDA food-contact and OSHA hazard-communication standards govern ink durability and substrate safety for pharmaceutical and chemical handling environments.
Printed tags absorb the bulk of installed capacity; adhesive tags are expanding most quickly.
Material:
Raw material sourcing strategies diverge sharply between virgin fiber dependence and circular supply chain integration, with certification premiums reshaping procurement economics.
- Cardstock:Multi-ply constructions from 10–18 point thickness provide tear resistance for industrial workflows. Nordic pulp supply disruptions are squeezing margin on bleached virgin grades, redirecting investment toward integrated recycling capabilities.
- Kraft Paper:Unbleached long-fiber substrates deliver superior wet strength and sustainability credentials. EU Green Deal packaging-waste directives are elevating FSC-certified kraft to competitive gatekeeper status for public-sector procurement in Germany and France.
- Recycled Paper:Post-consumer fiber content reduces virgin pulp exposure and aligns with EPR legislation compliance. Quality inconsistency limits deployment in barcode-critical applications where substrate uniformity affects scan reliability.
- Coated Paper:Clay or polymer surface treatments enhance print resolution and moisture resistance. REACH chemical restrictions are accelerating substitution of petroleum-based polyethylene coatings with cellulose nanofibril barriers.
Kraft paper commands the steepest expansion trajectory; cardstock retains dominant volume share.
Application:
End-use durability specifications create tiered performance requirements that stratify converter capabilities and customer relationships.
- Industrial Use:Engine component tagging, chemical drum labeling, and harsh-environment asset tracking demand 18-point laminated constructions with ISO 12947 abrasion certification. German tier-1 automotive suppliers specify cradle-to-cradle certified tags through machining and heat-treatment workflows.
- Inventory Control:Warehouse management systems require scannable durability through automated sortation cycles. RFID-integrated architectures are converging with fiber substrates to enable item-level tracking without separate plastic enclosures.
- Labeling:General identification applications across logistics and retail carry moderate durability requirements and attract commodity competition from plastic tag alternatives.
- Gift Tagging:Seasonal retail and promotional applications prioritize aesthetic customization over mechanical performance, serving as entry point for digital print specialists.
Industrial use concentrates the highest value contracts; inventory control is gaining share fastest.
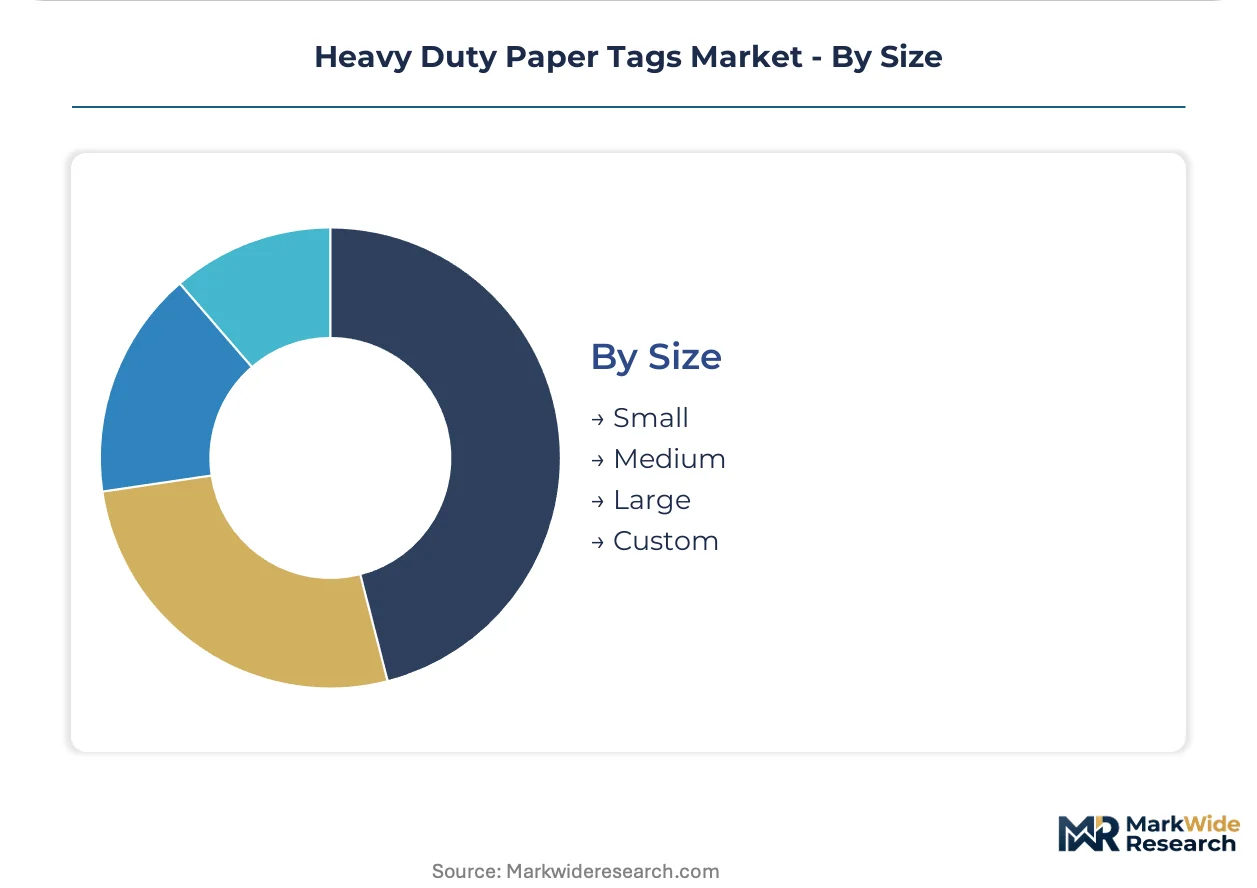
Size:
Format flexibility requirements determine die-cutting automation investment and inventory risk exposure across short-run versus long-run production economics.
- Custom:Variable dimensions tailored to specific equipment or branding requirements. Laser die-cutting paired with digital inkjet is compressing turnaround from weeks to 48 hours for seasonal retail workflows in the Netherlands.
- Large:Oversized formats for pallet-level identification and bulk chemical drum labeling. Standardization reduces tooling costs but limits differentiation.
- Medium:Conventional dimensions for carton and package-level tagging balance equipment utilization across customer portfolios.
- Small:Compact formats for individual item marking in electronics and pharmaceutical distribution. ESD-safe specifications with conductive coatings are emerging for India electronics assembly corridors under PLI scheme incentives.
Custom formats capture premium pricing; medium sizes dominate unit volume.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production of heavy duty paper tags concentrates in German and Benelux manufacturing corridors, while consumption spreads across automotive supply chains in Germany, e-commerce fulfillment networks in the Netherlands, and electronics assembly corridors in India. This geographic split creates trade flows of finished tags and substrate materials that expose converters to pulp fiber cost volatility and REACH compliance costs.
Germany
Tier-1 automotive suppliers specify 18-point laminated tags for engine component traceability through heat-treatment and machining workflows. The EU Green Deal packaging-waste directives elevate cradle-to-cradle certification to competitive gatekeeper status for public-sector procurement. Stuttgart and Munich industrial clusters drive specifications for tear-resistant substrates that survive automated sortation cycles.
Netherlands
E-commerce fulfillment centers in Rotterdam and Eindhoven demand adhesive-backed tags with edge-fray resistance under robotic handling systems. REACH chemical restrictions accelerate substitution of petroleum-based polyethylene coatings with cellulose nanofibril barriers. Third-party logistics operators unbundle tag procurement from broader packaging contracts to negotiate direct substrate supply agreements.
India
PLI scheme incentives for electronics assembly create demand for ESD-safe paper tags with conductive coatings in Karnataka and Tamil Nadu manufacturing corridors. The country's national industrial standards body governs substrate safety for pharmaceutical handling workflows. Pune and Chennai clusters specify variable-data printed tags for component traceability through assembly and testing stages.
United States
FDA food-contact regulations and OSHA hazard-communication standards govern ink durability and substrate safety for pharmaceutical and chemical handling workflows. Warehouse robotics integration in Chicago and Dallas fulfillment networks requires adhesive tags that withstand repeated mechanical handling without barcode degradation. Midwest distribution corridors concentrate automated fulfillment density above national averages.
Belgium
Acrylic pressure-sensitive adhesive production clusters around Antwerp, creating single-source vulnerability for tag converters across European supply chains. EPR legislation and packaging-waste directives redefine recyclability certifications as mandatory procurement criteria rather than optional premiums. Brussels-based regulatory compliance services support substrate reformulation toward bio-based barrier treatments.
Heavy Duty Paper Tags Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across substrate coating, die-cutting automation, and digital print integration. The vendor base stratifies between integrated converters controlling pulp-to-finished-tag supply chains and specialized shops laser-focused on variable-data short runs. Three archetypes dominate: multinational adhesive science platforms, harsh-environment specification specialists, and RFID-integrated architecture leaders. Capacity expansion and strategic partnerships constitute the dominant competitive moves as players secure substrate supply agreements and warehouse automation qualifications.
Within the multinational platform tier, Avery Dennison Corporation and 3M Company exemplify adhesive science capabilities that anchor premium coated-paper tag lines for industrial clients. Brady Corporation occupies a position among harsh-environment specialists, while SATO Holdings Corporation anchors RFID-integrated paper tag architectures in Asian manufacturing corridors. These named entities represent strategic archetypes rather than exhaustive market coverage, with each converter's geographic origin and corporate structure signaling distinct capability bundles.
| Leading Market Players |
|---|
| Avery Dennison Corporation |
| 3M Company |
| Brady Corporation |
| Zebra Technologies Corporation |
| SATO Holdings Corporation |
| Uline |
| Metalcraft, Inc. |
| Dutch Label Shop |
| The Nilorn Group |
| Others |
Supply & Pricing Matrix
Unbleached kraft pulp costs cascade through heavy duty paper tag pricing tiers, with Nordic supply disruptions compressing margins on FSC-certified grades while REACH-compliant bio-based barrier coatings command premium positioning against petroleum-based alternatives.
Pricing Analysis
Margin tightening in standard cardstock tiers reflects Nordic pulp fiber volatility and buyer consolidation among mega-3PL operators. Three-tier pricing structure across premium laminated, standard kraft, and economy recycled grades differentiates by certification level and wet-strength performance. Cost-down pressure on commodity alternatives accelerates because polypropylene synthetic tags threaten paper share in cold-chain pharmaceutical distribution. E-commerce fulfillment centers show lowest price sensitivity due to automated handling failure costs, while seasonal agricultural buyers drive spot-market negotiation.
Supply Chain Analysis
Freight cost exposure concentrates around Belgian and Dutch adhesive production clusters serving European tag converters. Raw material sourcing draws from Nordic kraft pulp mills, German coating chemical facilities, and Asian RFID inlay manufacturers. Single-source vulnerability in acrylic pressure-sensitive adhesive production creates structural risk for just-in-time fulfillment networks. Distribution runs through converter-to-3PL direct agreements that bypass traditional packaging distributors in Benelux corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Capacity constraints in REACH-compliant bio-based coating production prop pricing power for qualified suppliers, with qualified substrate availability acting as the binding bottleneck across German automotive and Netherlands e-commerce demand clusters.
For Market Incumbents: Cement substrate supply agreements with Nordic pulp mills to lock in FSC-certified fiber access before competitor qualification. Expand in-house coating capabilities to capture margin pools shifting from commodity converters to integrated producers as REACH chemical restrictions deepen. Defend against polypropylene substitution by accelerating cellulose nanofibril barrier certification timelines. For New Entrants and Emerging Players: Launch via digital print-enabled custom tag services targeting seasonal retail workflows in Netherlands third-party logistics corridors. Penetrate India electronics assembly markets under PLI scheme incentives with ESD-safe conductive coating specifications. White-space opportunity concentrates in 48-hour turnaround laser die-cutting for variable-data applications where incumbent equipment utilization prioritizes long-run contracts. For Investors and Strategic Acquirers: RFID-integrated paper tag architecture adoption in Asian manufacturing corridors is the leading indicator that substrate-electronics convergence will reshape competitive economics. Five-to-ten-year viability favors converters controlling upstream coating formulation and downstream warehouse automation qualification relationships. Acquisition target archetype: mid-cap specialists with captive bio-based barrier R&D and existing OEM tier-1 automotive certifications.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Coating Formulation | REACH compliance costs favor in-house bio-based barrier development over outsourced petroleum-based alternatives. |
| RFID Inlay Convergence Investment | UHF chip antenna integration with fiber substrates displaces separate plastic enclosure requirements in inventory control. |
| Subscription Replenishment Model Deployment | Multi-year supply agreements with 3PL operators lock in volume visibility and reduce customer acquisition cost exposure. |
| Laser Die-Cutting Automation Scale-Up | Rotterdam and Eindhoven fulfillment density supports 48-hour custom turnaround economics for seasonal retail workflows. |
| Cradle-to-Cradle Certification Program | German automotive supplier procurement mandates elevate circular material credentials to competitive gatekeeper status. |
Research Methodology
Independent corroboration across converter operations executives, 3PL procurement directors, and coating formulation chemists underwrites the qualitative findings. Primary fieldwork engaged plant managers at Benelux distribution facilities, automotive tier-1 supplier logistics leads, and regulatory compliance officers navigating REACH and EU Green Deal frameworks. Secondary validation drew from ECHA substance restriction databases, FSC chain-of-custody certification records, and customs trade flows for kraft pulp and pressure-sensitive adhesive materials. Bottom-up capacity modeling and top-down demand segmentation triangulate volume estimates.
Comparable-period anchoring to historical automotive production cycles and e-commerce fulfillment expansion patterns structured the projection horizon. Segmentation dimensions span product type, material substrate, application durability tier, and regional regulatory cluster. CAGRs derive from installed capacity utilization rates, substitution elasticity between paper and synthetic alternatives, and procurement contract renewal velocities. RFID adoption curves and bio-based coating reformulation timelines feed industry-specific trajectory inputs.
Pulp fiber cost volatility, REACH regulatory scope expansion, and warehouse robotics qualification failure rates are the dominant revision risks to modeled outputs. Forecasts embed assumptions about coating chemistry substitution timelines and buyer consolidation trajectories that may shift with macroeconomic conditions. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Heavy Duty Packaging
High-Stress PCR HDPE Detergent Bottles Market
Heavy Duty Packaging
Heavy Duty Corrugated Packaging Market
Heavy Duty Packaging
Hazardous Goods Packaging Market
Heavy Duty Packaging
Global Heavy Duty Bags and Sacks Market
Heavy Duty Packaging
High-Density Packaging Market
Heavy Duty Packaging
Heavy Duty Bins Market
Heavy Duty Packaging
Europe High Density Polyethylene Jerrycan Market
Heavy Duty Packaging
Hazmat Packaging Market
Heavy Duty Packaging
Heavy-Duty Corrugated Boxes Market
Heavy Duty Packaging
High Impact Corrugated Boxes Market
Heavy Duty Packaging
Large Blow Molded Products Market
Heavy Duty Packaging
Heavy-Duty Paper and Multiwall Shipping Sack Market