
 Hazardous Goods Packaging Market | 2026-2036
Hazardous Goods Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Hazardous Goods Packaging Market Foresight
The EU Green Deal is recalibrating material specifications across European hazardous goods supply chains, compelling shippers to abandon single-use plastic liners in favor of recyclable fiberboard and post-consumer resin formulations. Greif, Inc. leverages its captive steel drum production network across Germany and the Netherlands to preempt compliance deadlines. Mauser Packaging Solutions sustains R&D intensity in reusable IBC designs that reduce per-trip carbon footprints. Schütz GmbH & Co. KGaA anchors its competitive position through closed-loop pooling systems that integrate collection, reconditioning, and reissue logistics.
Hazardous goods packaging encompasses engineered containment systems designed to prevent leakage, rupture, or chemical interaction during the handling of toxic, flammable, corrosive, or reactive substances, with UN certification markings certifying compliance with pressure, drop, and stack testing protocols. These systems employ multi-layer coextruded polyethylene, epoxy-lined carbon steel, or phenolic-impregnated fiberboard to withstand internal pressures exceeding kPa thresholds specified in modal transport regulations. Drum formats dominate volume throughput in chemical and oil & gas end uses where single-trip disposal economics favor steel and tight-head plastic constructions. IBC segments capture expanding share in pharmaceutical and agriculture applications requiring tote-based dispensing precision and reduced manual handling exposure. Fiberboard material grades represent the fastest-growing structural category as brand owners substitute corrugated alternatives for lower-hazard formulations to satisfy extended producer responsibility mandates.
FDA, EPA, and DOT regulations in the United States impose stringent testing and documentation burdens on pharmaceutical and chemical shippers, while REACH and CLP frameworks in Europe restrict substance classifications and mandate hazard communication labeling on all packaging surfaces. These regulatory architectures elevate barriers for uncertified producers and concentrate procurement authority with vendors holding multinational accreditation portfolios. Stakeholders must monitor evolving state-level extended producer responsibility laws and modal-specific amendments to the UN Model Regulations to anticipate redesign cycles and requalification costs.
Market Dynamics
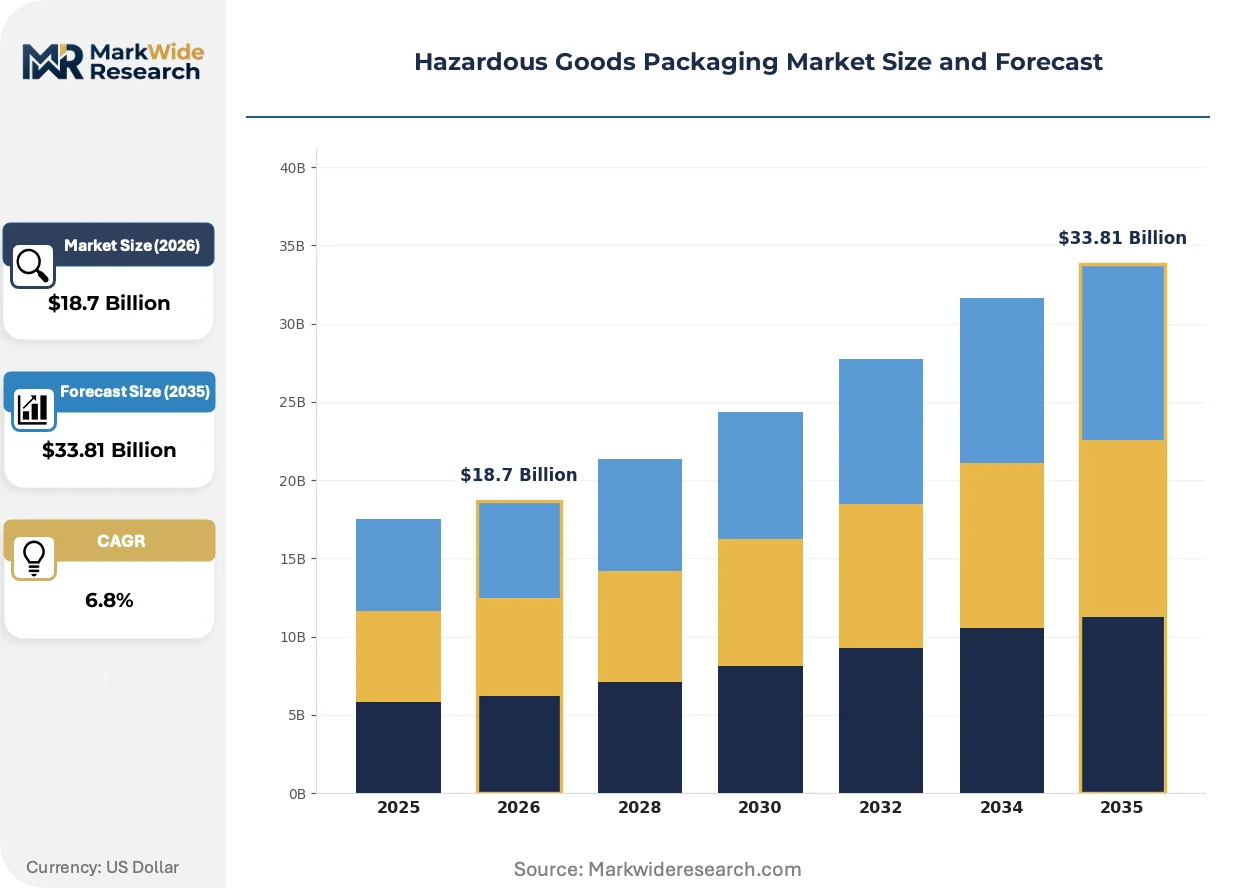
UN Model Regulations revisions and EU Green Deal packaging waste directives are forcing simultaneous material transitions and certification requalification across chemical supply chains. This dual pressure compresses redesign cycles while elevating compliance costs for container producers serving export-intensive industrial clusters.
Growth Catalysts
- REACH substance restrictions:CLP hazard classification expansions in Europe mandate upgraded containment integrity for corrosive and toxic chemical shipments, accelerating drum replacement cycles.
- Agrochemical export logistics:Coastal production zones in Germany, China, and the United States require intermediate bulk containers certified for multimodal sea-rail-road transfers to emerging markets.
- Post-consumer resin formulations:Recycled polymer processing advances enable UN-certified containers meeting drop-test protocols while satisfying extended producer responsibility mandates.
Market Restraints
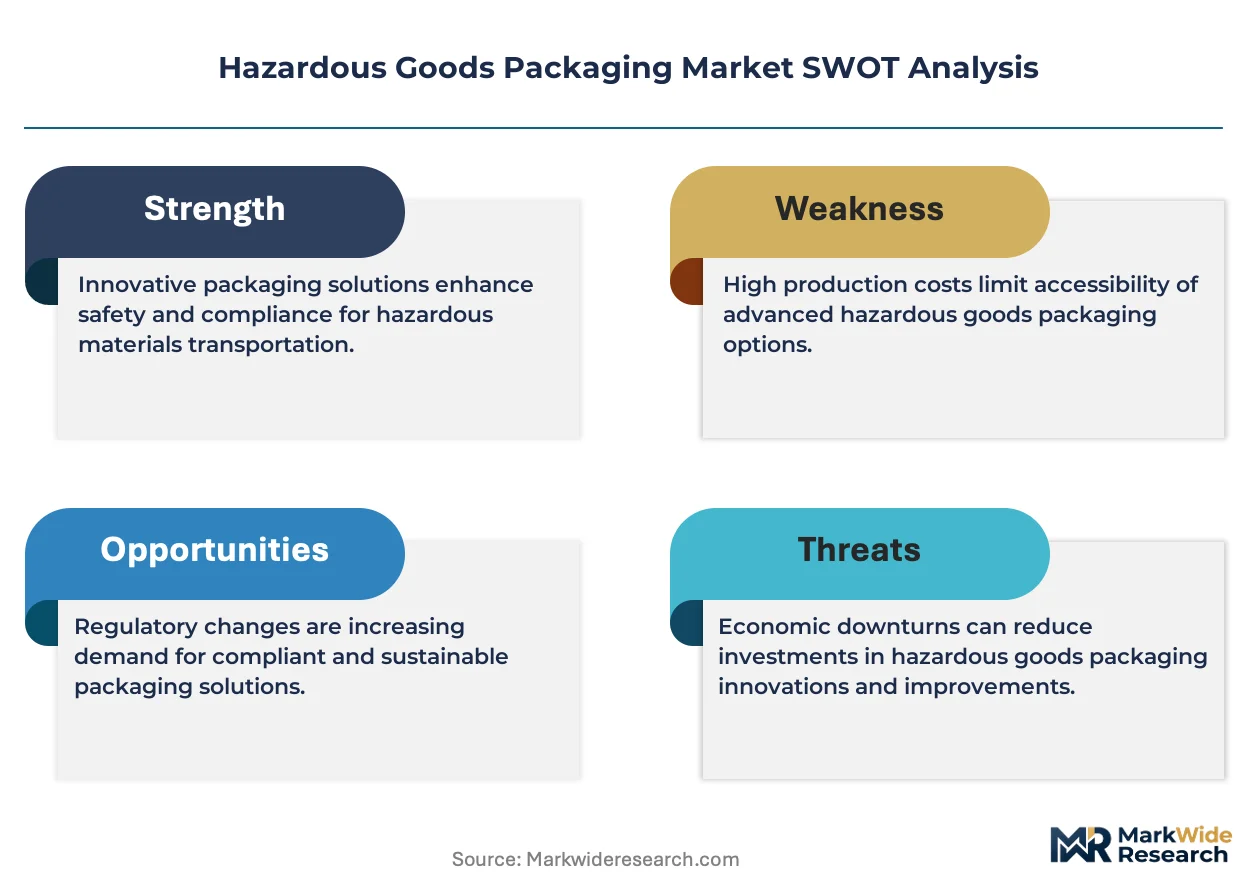
- Steel coil input volatility:Carbon steel drum production faces margin compression from scrap metal price swings and energy-intensive lining operations.
- German reconditioning concentration:Closed-loop pooling infrastructure clusters in the Rhine-Ruhr industrial corridor, creating geographic single-point vulnerabilities for IBC fleet availability.
- Fiberboard moisture limitations:Phenolic-impregnated corrugated alternatives fail UN pressure tests for Class 3 flammable liquids above specific vapor pressure thresholds.
Strategic Opportunities
- India agrochemical formulation:Domestic crop protection chemical production expansion creates demand for UN-certified drums and composite IBCs serving export-oriented Gujarat and Maharashtra manufacturing hubs.
- Reusable IBC telemetry integration:RFID-enabled fleet tracking converges with pressure sensor arrays to enable condition-based reconditioning and reduce per-trip asset loss rates.
- EU AI Act supply chain transparency:Automated documentation systems for hazardous goods tracking open vendor opportunities in digital compliance tooling adjacent to physical packaging.
Industry Challenges
- UN certification requalification timelines:Modal transport regulation amendments require 12-18 month retesting protocols that freeze product portfolios during transition periods.
- Multi-material welding expertise:Steel-plastic composite IBC production demands certified pressure vessel technicians scarce in Eastern European manufacturing zones.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hazardous Goods Packaging Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Drum, IBC, Bag, Bottle Material: Metal, Plastic, Glass, Fiberboard End User: Chemical, Oil & Gas, Pharmaceuticals, Agriculture Application: Storage, Transportation, Waste Disposal, Manufacturing |
| Companies Covered | THIELMANN US LLC, Great Western Containers Inc., Greif, Inc., Balmer Lawrie & Co. Ltd., Myers Container, Mauser Packaging Solutions, Peninsula Drums, Fibrestar Drums Limited, Schütz GmbH & Co. KGaA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hazardous Goods Packaging Market Shifts & Advancements
Material science advances and digital traceability requirements are converging to transform hazardous goods packaging from passive containment into active compliance infrastructure. Container producers now engineer for circularity metrics alongside traditional pressure and drop-test performance.
Multi-layer coextruded polyethylene with embedded barrier polymers is modularizing drum construction, allowing chemical manufacturers to specify tailored permeation resistance without full redesign. Pharmaceutical and specialty chemical buyers in Switzerland and the Netherlands are specifying these configurations for oxygen-sensitive active ingredients. The technology compresses SKU proliferation while extending container service life in closed-loop systems.
CSRD sustainability reporting mandates in Europe now require Scope 3 emissions disclosure from chemical shippers, forcing packaging procurement to document recycled content percentages and end-of-life recovery rates. Container vendors must embed mass-balance certification into supply contracts. Fiberboard drum producers serving French and German agrochemical formulators are restructuring supplier qualification protocols to capture this data.
Third-party reconditioning networks are displacing captive fleet management among mid-size chemical distributors seeking to convert fixed asset burdens into variable per-trip costs. The Rhine-Ruhr and Houston Ship Channel industrial corridors host the densest concentrations of independent IBC wash-and-reissue facilities. This behavior shift concentrates procurement authority with pooling service operators rather than original equipment manufacturers.
Hazardous Goods Packaging Market Segmentation
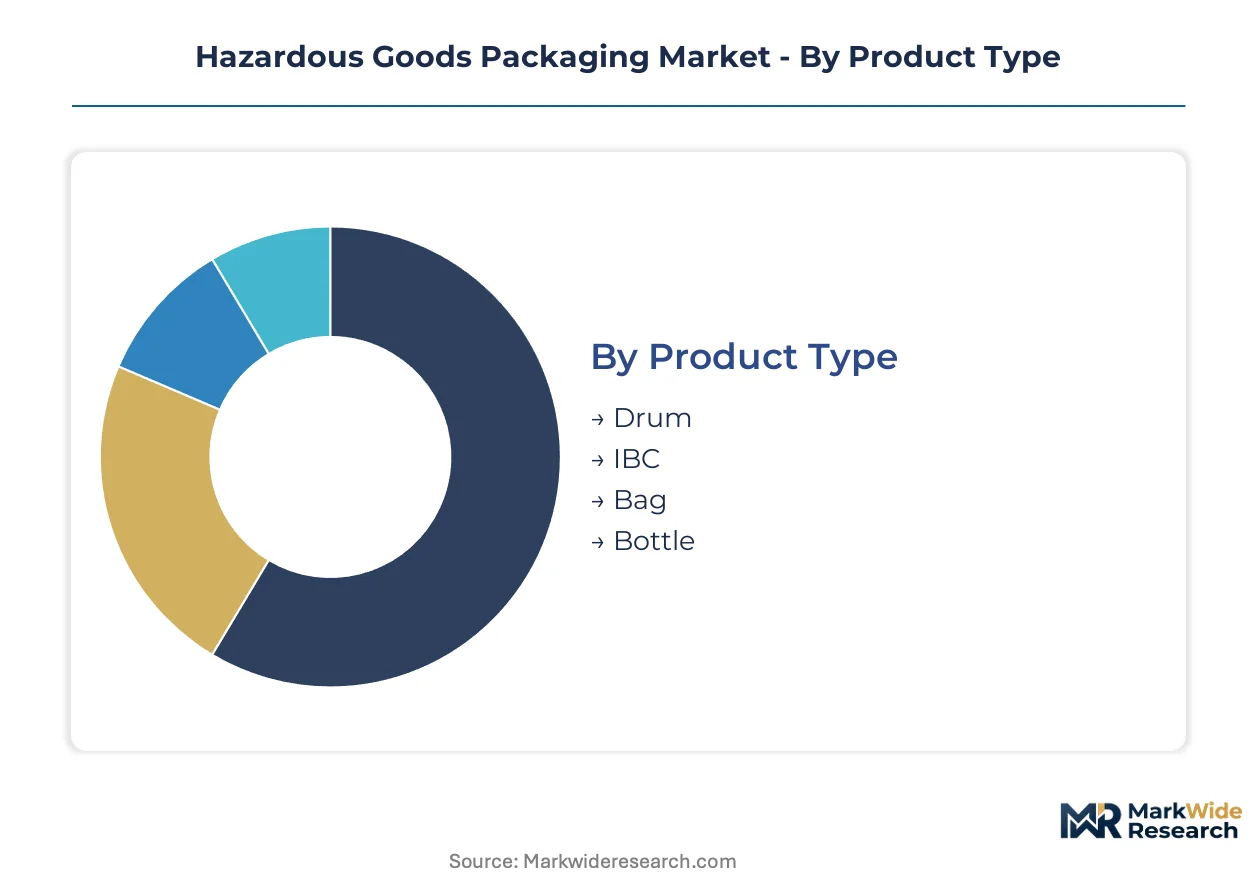
UN certification requirements and modal transport regulations create divergent performance specifications across container formats. Material selection and end-use hazard classifications further stratify procurement criteria, forcing vendors to maintain parallel qualification portfolios.
Product Type:
Structural engineering specifications determine pressure tolerance, stacking strength, and dispensing ergonomics across container architectures.
- Drum:Cylindrical steel or tight-head polyethylene constructions dominate corrosive chemical and petroleum distillate shipments. German and US Gulf Coast petrochemical clusters specify epoxy-lined carbon steel variants for single-trip export logistics to emerging markets.
- IBC:Composite steel-cage polyethylene totes enable tote-based dispensing precision with reduced manual handling exposure. Pharmaceutical formulators in Switzerland and the Netherlands specify multi-layer coextruded configurations for oxygen-sensitive active ingredients.
- Bag:Flexible intermediate bulk containers with woven polypropylene outer layers serve lower-hazard dry chemical and agricultural powder formulations.
- Bottle:Rigid fluorinated HDPE configurations address laboratory-scale reagent distribution and clinical trial material shipments.
Drum leads on scale; IBC leads on momentum.
Material:
Cost structures and circularity mandates are recalibrating raw material procurement across container supply chains.
- Metal:Carbon steel drum production with phenolic or epoxy interior linings withstands Class 3 flammable liquid vapor pressures exceeding fiberboard thresholds. Scrap metal price volatility compresses margins for European producers dependent on electric arc furnace inputs.
- Plastic:Post-consumer resin formulations now achieve UN drop-test certification for non-corrosive chemical segments. REACH substance restrictions and EU Green Deal packaging waste directives accelerate substitution timelines.
- Glass:Borosilicate and soda-lime configurations retain niche positions in pharmaceutical parenteral and analytical reagent applications requiring inert contact surfaces.
- Fiberboard:Phenolic-impregnated corrugated alternatives satisfy extended producer responsibility mandates for lower-hazard agrochemical formulations. Moisture limitations constrain deployment against Class 3 flammables above specific vapor pressure thresholds.
Metal dominates current throughput; fiberboard is expanding most quickly.
End User:
Hazard classification severity and shipment frequency determine container specification intensity across industrial verticals.
- Chemical:Corrosive, toxic, and reactive substance handlers require UN-certified drums and IBCs with pressure relief and containment sum specifications. Coastal manufacturing clusters in Germany, China, and the United States drive multimodal sea-rail-road certification demand.
- Oil & Gas:Lubricant and drilling fluid producers favor tight-head steel drums for single-trip disposal economics in remote extraction sites.
- Pharmaceuticals:FDA and EMA serialization mandates converge with oxygen barrier requirements for active ingredient bulk shipments.
- Agriculture:Crop protection chemical formulators in Gujarat and Maharashtra manufacturing hubs generate demand for UN-certified composite IBCs serving export-oriented production.
Chemical leads on scale; Agriculture leads on momentum.
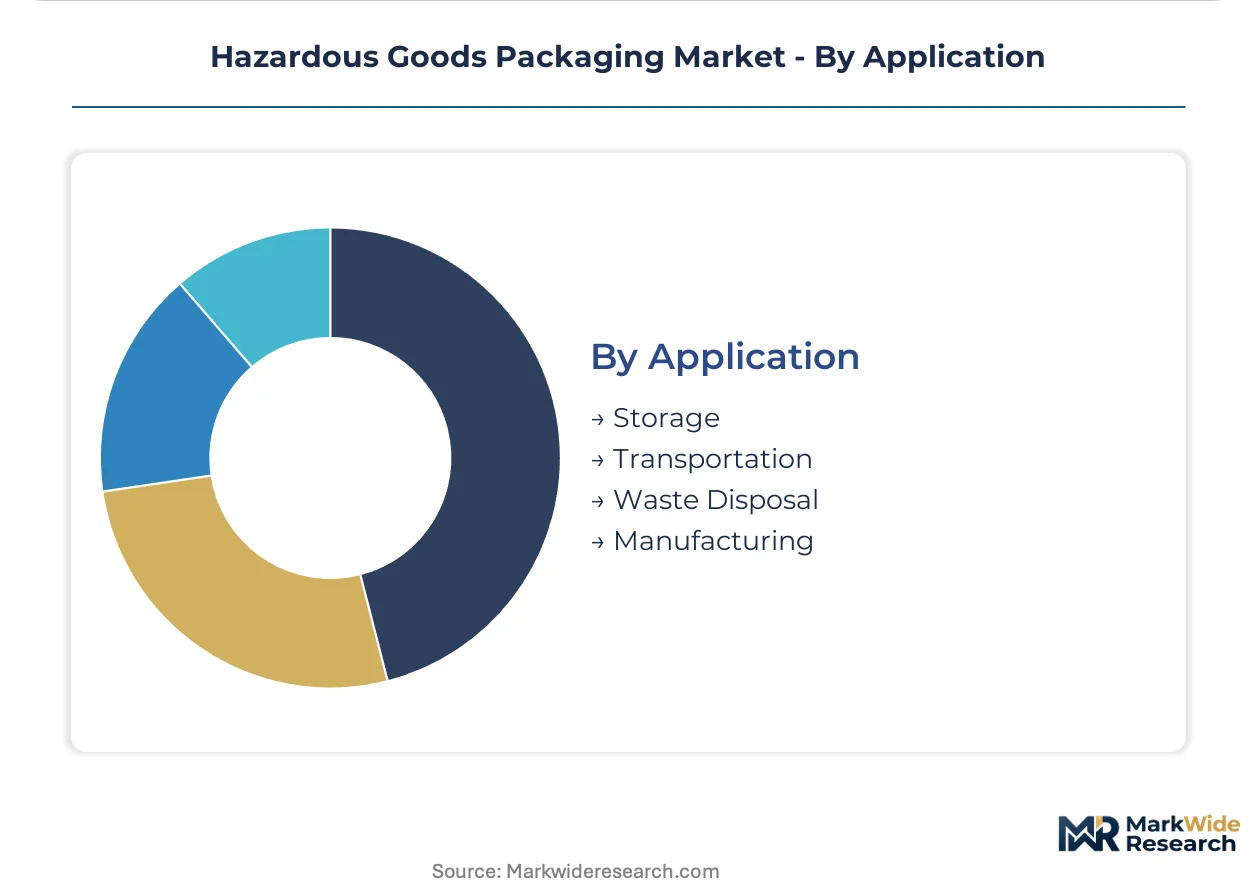
Application:
Lifecycle phase determines durability specifications, reconditioning potential, and regulatory documentation burdens.
- Storage:Long-duration containment demands UV-stabilized exteriors and vapor-tight closures for warehouse-staged inventory. CSRD sustainability reporting mandates now require Scope 3 emissions disclosure covering storage-phase container assets.
- Transportation:Modal transfer certification under UN Model Regulations governs sea, rail, and road shipment integrity. RFID-enabled telemetry integration is converging with pressure sensor arrays for condition-based fleet management.
- Waste Disposal:Single-use fiberboard and polyethylene configurations address contaminated material consolidation with minimized decontamination liability.
- Manufacturing:In-process tote systems enable just-in-time chemical feeding with reduced drum handling labor.
Transportation leads on scale; Storage leads on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized drum fabrication technicians cluster in Germany's Rhine-Ruhr corridor and along the US Gulf Coast, anchoring regional production capacity for UN-certified steel containers. These workforce concentrations attract reconditioning infrastructure and captive fleet operators seeking proximity to chemical manufacturing demand.
United States
Petrochemical expansion along the Houston Ship Channel drives drum procurement for lubricant and drilling fluid exports. EPA and DOT regulations enforce UN Model Regulations compliance for multimodal shipments. Texas and Louisiana host the densest concentrations of tight-head steel drum fabrication serving single-trip disposal economics in remote extraction sites.
Germany
Agrochemical formulators in North Rhine-Westphalia require composite IBCs for crop protection chemical exports to emerging markets. EU Green Deal packaging waste directives and REACH substance restrictions mandate recyclable fiberboard transitions. The Rhine-Ruhr industrial corridor concentrates closed-loop pooling infrastructure and reconditioning fleet capacity.
China
Coastal manufacturing zones in Jiangsu and Zhejiang provinces scale intermediate bulk container production for petrochemical exports. GB standards and MIIT regulations align with UN certification protocols for sea-rail-road transfers. Yangtze River Delta chemical clusters procure UN-certified drums for domestic distribution and Southeast Asian export logistics.
India
Domestic crop protection chemical production in Gujarat and Maharashtra generates demand for UN-certified composite IBCs. DGFT export regulations and BIS standards govern hazardous goods packaging compliance. Ahmedabad and Mumbai manufacturing hubs serve export-oriented agrochemical formulation to African and Southeast Asian markets.
Switzerland
Pharmaceutical active ingredient bulk shipments require multi-layer coextruded IBC configurations with oxygen barrier specifications. Swissmedic and EMA serialization mandates converge with CSRD sustainability reporting requirements. Basel and Zurich chemical formulators specify tailored permeation resistance for oxygen-sensitive compounds without full container redesign.
Hazardous Goods Packaging Market Competitive Landscape
Capital-heavy drum fabricators compete with asset-light pooling service operators across divergent margin structures. The market exhibits tiered concentration with multinational container producers commanding certification authority alongside regional reconditioning specialists. Three archetypes dominate: integrated steel drum manufacturers with captive lining operations, composite IBC designers emphasizing modular barrier configurations, and third-party fleet managers converting fixed asset burdens into per-trip service contracts. Capacity expansion and strategic partnerships represent the primary competitive vectors as players secure reconditioning network density.
Among US-based container producers, THIELMANN US LLC and Myers Container exemplify the integrated fabrication archetype with in-house steel processing capabilities. Greif, Inc. occupies a position spanning both manufacturing and pooling services across North American and European chemical corridors. Schütz GmbH & Co. KGaA represents the German-engineered composite IBC segment with emphasis on closed-loop logistics integration. These three anchors illustrate how geographic origin and corporate structure map onto divergent strategic postures within UN-certified packaging supply chains.
| Leading Market Players |
|---|
| THIELMANN US LLC |
| Great Western Containers Inc. |
| Greif, Inc. |
| Balmer Lawrie & Co. Ltd. |
| Myers Container |
| Mauser Packaging Solutions |
| Peninsula Drums |
| Fibrestar Drums Limited |
| Schütz GmbH & Co. KGaA |
| Others |
Supply & Pricing Matrix
Scrap steel coil volatility transmits directly through carbon steel drum fabrication costs, compressing margins for European producers tethered to electric arc furnace inputs while amplifying price spreads between epoxy-lined premium containers and standard tight-head constructions across German and US Gulf Coast chemical corridors.
Pricing Analysis
Bundled pooling services command per-trip premiums over unbundled container sales, with closed-loop reconditioning contracts capturing recurring revenue streams that transactional drum purchases cannot match. Three-tier pricing structure across premium, standard, and economy levels separates UN-certified composite IBCs with RFID telemetry from basic steel drums and single-use fiberboard alternatives. Pricing pressure stems from post-consumer resin formulation R&D costs as vendors race to meet EU Green Deal compliance deadlines. Mid-size chemical distributors exhibit highest price sensitivity, converting fixed fleet ownership to variable per-trip costs through third-party pooling arrangements.
Supply Chain Analysis
Dual-sourcing requirements from multinational chemical shippers mandate parallel qualification of German, Chinese, and US drum fabricators to mitigate geographic concentration risk. Raw material procurement draws from carbon steel coil suppliers, phenolic resin compounders, and multi-layer polyethylene extruders across three continents. Single-source vulnerability concentrates in the Rhine-Ruhr reconditioning corridor where closed-loop pooling infrastructure clusters. Distribution runs through coastal industrial zones with multimodal sea-rail-road transfer certification.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds returns through regulatory layering, with EU Green Deal packaging waste directives and UN Model Regulations revisions forcing simultaneous material transitions and certification requalification across chemical supply chains.
For Market Incumbents: Cement market position through captive reconditioning network density in the Houston Ship Channel and Rhine-Ruhr corridors, preempting margin erosion from asset-light pooling operators. Deepen backward integration into post-consumer resin compounding to secure supply continuity for fiberboard transitions mandated by extended producer responsibility laws.
For New Entrants and Emerging Players: Launch via independent IBC wash-and-reissue facilities in Gujarat and Maharashtra manufacturing hubs, converting fixed asset burdens into per-trip service contracts for domestic agrochemical formulators. Target India's crop protection chemical export expansion with UN-certified composite IBCs certified for multimodal transfers to African and Southeast Asian markets.
For Investors and Strategic Acquirers: Consolidation pressure builds where mid-size reconditioning specialists lack capital to integrate RFID-enabled telemetry for condition-based fleet management. Five-to-ten year viability favors operators with multinational accreditation portfolios spanning FDA, EPA, DOT, REACH, and CLP frameworks. Watch for EU AI Act supply chain transparency mandates triggering automated documentation system acquisitions.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Post-Consumer Resin Compounding | Secures feedstock supply for EU Green Deal compliance deadlines while capturing circularity premiums from German chemical shippers. |
| RFID-Enabled Fleet Telemetry Integration | Enables condition-based reconditioning for Mauser Packaging Solutions and Schütz GmbH closed-loop systems. |
| Capacity Expansion in Gujarat Manufacturing Corridor | Serves India's agrochemical export growth to African and Southeast Asian markets under DGFT regulations. |
| Long-Term Supply Agreement with Coastal Petrochemical Clusters | Locks in drum procurement volumes from Houston Ship Channel and Yangtze River Delta producers. |
| Joint Venture for Multi-Material Welding Expertise | Addresses certified pressure vessel technician scarcity in Eastern European steel-plastic composite IBC production. |
Research Methodology
Multiple input streams — primary interviews with drum fabrication plant managers, chemical procurement leads, and reconditioning facility operators, alongside secondary validation through UN Model Regulations documentation, customs trade data, and SEC filings from container producers — were reconciled through bottom-up and top-down triangulation to construct market estimates.
Historical volume trajectories were cross-referenced against panel input from industry stakeholders to derive expansion rates across the analysis window, with segmentation modeling across container format, material grade, end-use industry, and regional production hub dimensions. Forecast inputs incorporated REACH substance restriction timelines, coastal manufacturing cluster capacity announcements, and post-consumer resin processing yield improvements.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt UN certification requalification timeline compressions or scrap metal price spikes. Deviation in EU Green Deal implementation pacing would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Heavy Duty Packaging
Heavy-Duty Corrugated Boxes Market
Heavy Duty Packaging
Heavy-Duty Paper and Multiwall Shipping Sack Market
Heavy Duty Packaging
Europe High Density Polyethylene Jerrycan Market
Heavy Duty Packaging
Heavy Duty Corrugated Packaging Market
Heavy Duty Packaging
Heavy Duty Paper Tags Market
Heavy Duty Packaging
Large Blow Molded Products Market
Heavy Duty Packaging
High-Density Packaging Market
Heavy Duty Packaging
Global Heavy Duty Bags and Sacks Market
Heavy Duty Packaging
Hazmat Packaging Market
Heavy Duty Packaging
High Impact Corrugated Boxes Market
Heavy Duty Packaging
High-Stress PCR HDPE Detergent Bottles Market
Heavy Duty Packaging
Heavy Duty Bins Market