
 Heavy Duty Bins Market | 2026-2036
Heavy Duty Bins Market Size, Share, and Industry Trends Forecast 2026-2036
Heavy Duty Bins Market Foresight
Recycled high-density polyethylene formulation is reshaping how heavy duty bins achieve structural integrity without virgin resin dependence. ORBIS Corporation leverages closed-loop recycling infrastructure to supply automotive assembly plants across North America. SSI Schaefer anchors its position through automated warehouse integration, embedding bins within robotics-compatible dimensioning systems. Schoeller Allibert competes on folding-ratio engineering, compressing return-trip volume for beverage and agriculture pooling networks.
Heavy duty bins are rigid, load-bearing containers engineered from injection-molded plastics, welded steel, or laminated wood composites, typically rated above 50 kg static load and designed for multi-trip industrial circulation. Their primary purpose centers on protecting bulk goods through mechanized handling cycles while minimizing unit-cost per trip across closed or open pooling systems. Plastic bins lead unit volume due to corrosion immunity and washdown compatibility in food and pharmaceutical logistics, while metal bins retain margin concentration in molten-metal-adjacent foundry and forging operations where thermal tolerance exceeds polymer limits. Extra-large capacity formats represent the fastest-growing structural segment as e-commerce fulfillment centers consolidate inbound SKUs into fewer, larger tote movements to reduce handling touches.
FDA food-contact regulations and OSHA ergonomic lifting guidelines in the United States shape material selection and maximum allowable loaded weights, while REACH substance restrictions in Europe limit certain plasticizers and flame retardants in bin compositions destined for cross-border pooling. Stakeholders must monitor how extended producer responsibility frameworks in multiple jurisdictions shift cost accountability from end-users back to container manufacturers and pool operators.
Market Dynamics
Construction site logistics teams are scaling reusable container fleets to replace single-use packaging, tightening specifications for load-bearing capacity and chemical resistance across industrial corridors.
Growth Catalysts
- EPA landfill diversion rules:United States waste regulations mandate reduced disposal volumes, pushing manufacturers toward closed-loop pooling systems for heavy duty bins in automotive and food processing plants.
- Recycled HDPE formulation advances:Structural integrity without virgin resin dependence enables automotive assembly plants to meet sustainability targets while maintaining mechanized handling compatibility.
- Chicago-Detroit-Cleveland industrial corridor concentration:Dense manufacturing clustering creates economies of scale for bin pooling operators serving Tier 1 automotive suppliers and metal forging operations.
Market Restraints
- Petrochemical feedstock volatility:Virgin and recycled polyethylene prices fluctuate with crude oil markets, compressing margin predictability for injection-molded plastic bin manufacturers.
- Steel tariff exposure:Welded metal bin producers face input cost instability from trade policy shifts affecting hot-rolled coil availability for foundry-adjacent container specifications.
- REACH substance restrictions:European chemical regulations limit certain plasticizers and flame retardants in cross-border pooling networks, fragmenting formulation standardization.
Strategic Opportunities
- E-commerce fulfillment consolidation:Extra-large capacity formats for SKU aggregation into fewer tote movements reduce handling touches in automated distribution centers.
- Extended producer responsibility frameworks:Emerging regulations in multiple jurisdictions shift cost accountability from end-users back to manufacturers and pool operators, creating service revenue streams.
- Robotics-compatible dimensioning:Automated warehouse integration demands bins engineered for precise gantry and AMR gripping surfaces, opening specification premiums.
Industry Challenges
- Weld certification timelines:Metal bin fabricators face extended qualification periods for OSHA-compliant load-rating documentation in molten-metal environments.
- Legacy ERP integration:Pool operators struggle to embed RFID-tracked container fleets into customer warehouse management systems without custom middleware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Heavy Duty Bins Market |
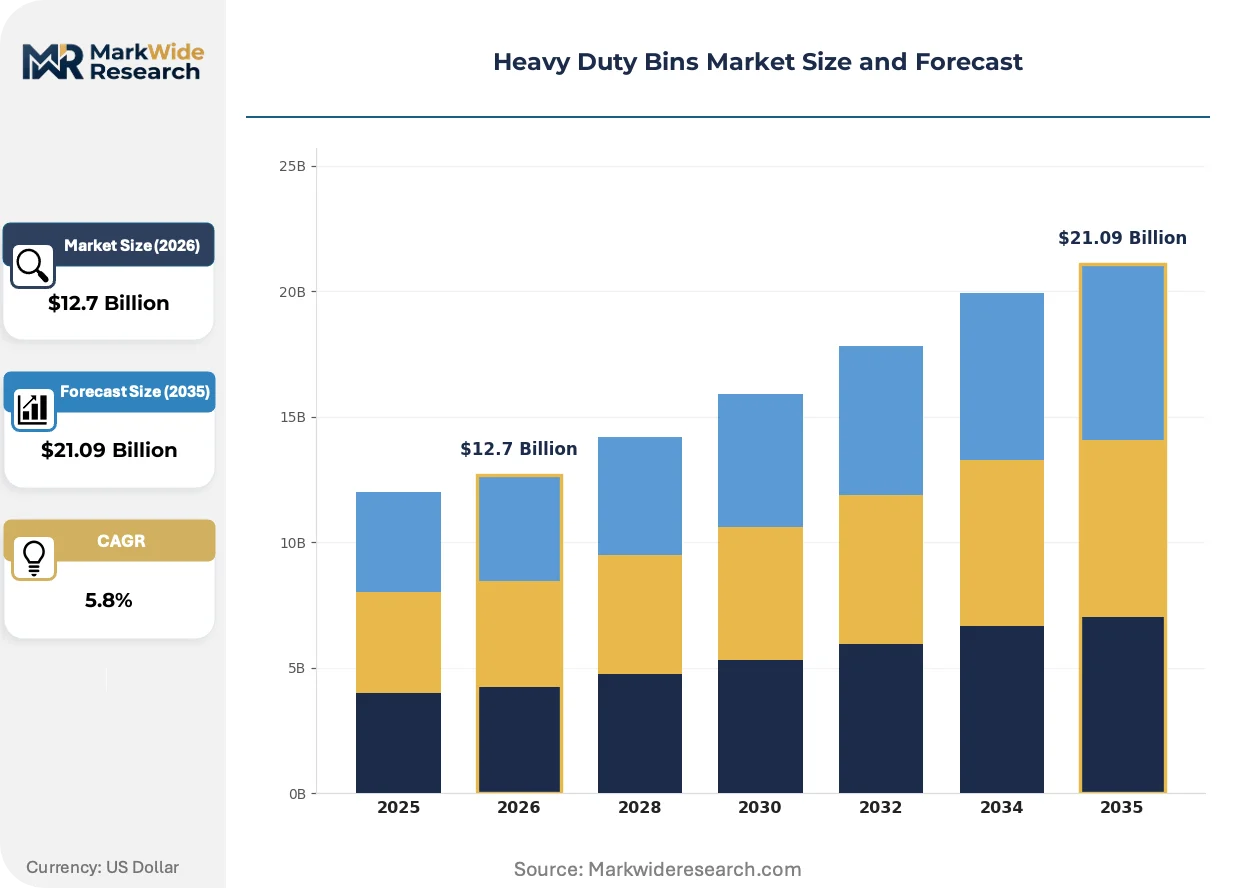
| Market Size in 2026 | $12.7 Billion |
| Market Size in 2035 | $21.09 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plastic Bins, Metal Bins, Wood Bins, Wire Bins Use Case: Construction, Agriculture, Waste Management, Industrial Storage End User: Manufacturers, Retailers, Contractors, Distributors Capacity: Small, Medium, Large, Extra Large |
| Companies Covered | ORBIS Corporation, Akro-Mils, SSI Schaefer, Schoeller Allibert, Rubbermaid, RPC Group Plc, Snyder Industries, Greif, Mauser Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Heavy Duty Bins Market Shifts & Advancements
Active material science breakthroughs and regulatory tightening are compressing design cycles while expanding performance envelopes for multi-trip industrial containers.
Collapsible folding-ratio engineering is rendering obsolete fixed-wall containers in beverage and agriculture pooling networks. Pallet pooling operators are adopting compression-optimized designs that reduce return-trip volume by over seventy percent. This technology is rendering obsolete traditional rigid bin configurations for seasonal harvest logistics and reverse distribution loops.
OSHA ergonomic lifting guidelines in the United States now mandate maximum allowable loaded weights for manual handling scenarios. These rules force redesign of bin lip geometry and caster placement to reduce musculoskeletal injury risk. Food and pharmaceutical logistics segments are responding with washdown-compatible plastic formulations that maintain structural ratings at reduced tare weights.
Automotive Tier 1 suppliers are consolidating vendor bases around container-as-a-service contracts rather than capital purchase models. This procurement evolution transfers fleet management risk to pool operators while embedding performance guarantees for damage rates and turnaround velocity. The shift is most visible in Michigan and Ohio assembly plant supply chains where just-in-sequence delivery tolerances have tightened.
Heavy Duty Bins Market Segmentation
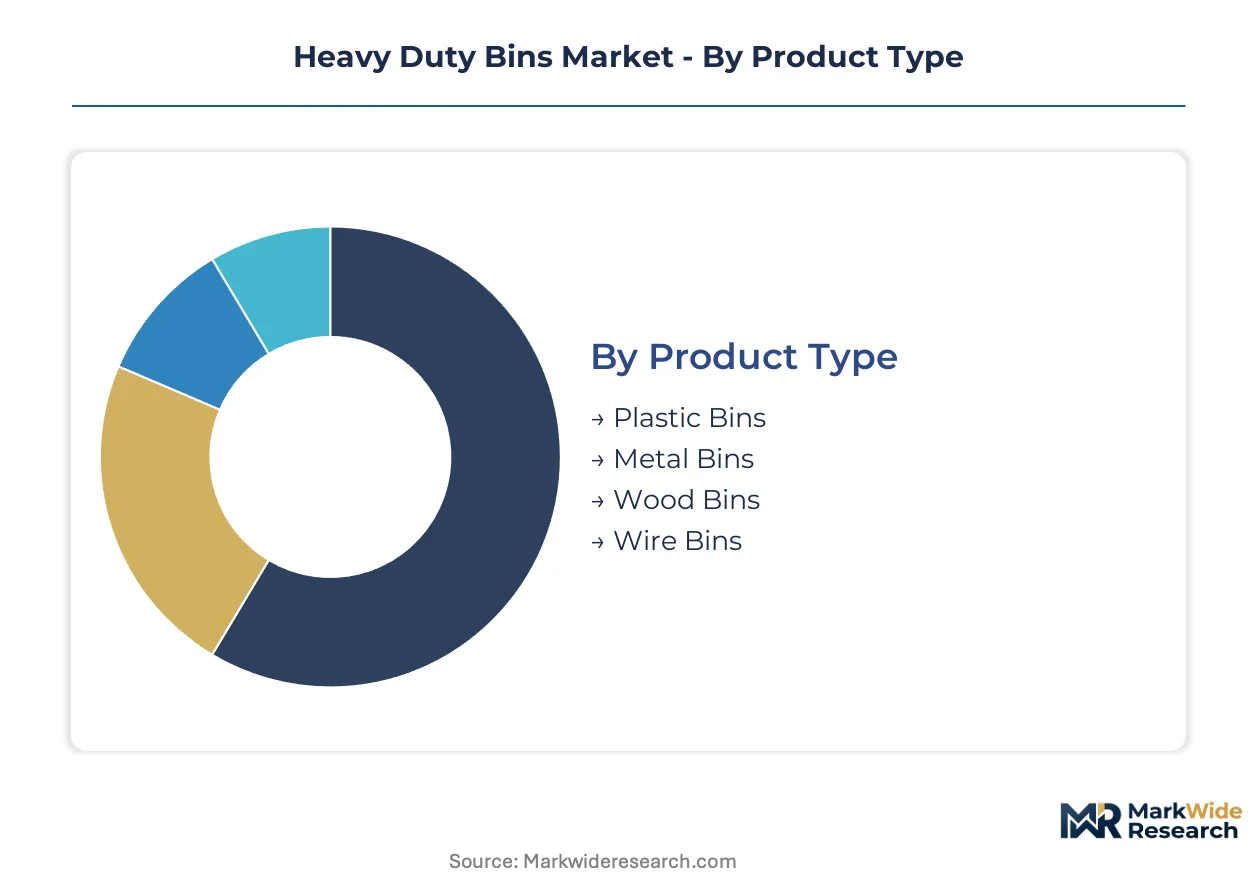
Heavy duty bin procurement varies sharply by asset turnover velocity. Plastic pooling fleets rotate every 45-60 days in automotive supply chains while metal foundry containers depreciate over 8-12 year cycles. Segment-specific durability requirements dictate formulation chemistry, wall thickness engineering, and residual value recovery models across closed-loop systems.
Product Type:
Cycle times diverge dramatically: plastic bins turn fastest in high-velocity pooling networks while metal assets amortize slowly in thermal-stress environments.
- Plastic Bins:Injection-molded high-density polyethylene structures dominate unit volume through corrosion immunity and FDA food-contact compliance. Demand concentrates in Michigan and Ohio automotive assembly corridors where ORBIS Corporation operates closed-loop recycling infrastructure for Tier 1 supplier fleets. Recycled resin formulation advances enable structural parity with virgin material at reduced carbon intensity.
- Metal Bins:Welded steel constructions rated for molten-metal adjacency retain margin concentration in forging and foundry operations. Chicago-Detroit industrial clusters specify OSHA-compliant load ratings for thermal tolerance exceeding polymer limits. Extended weld certification timelines constrain supplier qualification velocity.
- Wood Bins:Laminated composite formats serve niche agriculture harvest logistics with biodegradable end-of-life pathways. Lower capital cost suits seasonal deployment patterns with limited return-trip economics.
- Wire Bins:Mesh steel configurations optimize visibility and drainage for produce handling and construction debris sorting. Reduced tare weight improves transport efficiency in open pooling networks.
Plastic bins anchor the volume base while extra-large capacity formats gain share at the steepest rate in e-commerce fulfillment consolidation.
Use Case:
Application-driven specification tiers separate capital-intensive infrastructure deployments from operational consumables models.
- Construction:Reusable container fleets replace single-use packaging across site logistics teams scaling circular procurement. EPA landfill diversion rules tighten chemical resistance specifications for concrete-adjacent deployments.
- Agriculture:Seasonal harvest logistics demand collapsible folding-ratio engineering to compress return-trip volume by over seventy percent. Pallet pooling operators prioritize compression-optimized designs for reverse distribution loops.
- Waste Management:Roll-out cart compatibility and automated lift-arm interfaces dominate municipal procurement specifications. Load-bearing capacity ratings must survive mechanized collection cycles exceeding 10,000 actuations.
- Industrial Storage:Automated warehouse integration requires robotics-compatible dimensioning for gantry and AMR gripping surfaces. SSI Schaefer anchors positioning through embedded sensor mounting points.
Construction use cases absorb the highest capital deployment while agriculture applications expand most quickly through pooling network densification.
End User:
Procurement authority concentration determines contract structure complexity and performance guarantee requirements.
- Manufacturers:Automotive Tier 1 suppliers consolidate vendor bases around container-as-a-service contracts transferring fleet management risk to pool operators. Just-in-sequence delivery tolerances in Ohio and Michigan assembly plants embed damage rate and turnaround velocity guarantees.
- Retailers:E-commerce fulfillment centers drive extra-large capacity adoption to consolidate inbound SKUs into fewer tote movements. Distribution automation demands precise bin dimensioning for robotic handling compatibility.
- Contractors:Project-based procurement favors rental and short-term lease structures over capital ownership. Site logistics teams prioritize rapid deployment flexibility over long-term asset optimization.
- Distributors:Intermediate inventory positioning requires cross-compatible bin formats serving heterogeneous downstream customer bases. Standardization pressure intensifies under extended producer responsibility frameworks.
Manufacturers anchor the volume base through automotive supply chain concentration while retailers climb the fastest on fulfillment automation investment cycles.
Capacity:
Handling touch reduction economics favor consolidation into larger unit loads across mechanized distribution environments.
- Small:Manual handling scenarios under OSHA ergonomic lifting guidelines mandate maximum allowable loaded weights. Redesigned lip geometry and caster placement reduce musculoskeletal injury risk in food and pharmaceutical logistics.
- Medium:General-purpose industrial circulation balances cube utilization with forklift maneuverability in standard rack configurations.
- Large:Bulk ingredient handling in processing plants combines washdown compatibility with structural ratings at reduced tare weights.
- Extra Large:SKU aggregation formats reduce handling touches in automated distribution centers. Schoeller Allibert competes on folding-ratio engineering for beverage and agriculture pooling networks compressing return-trip volume.
Medium capacity segments anchor installed base volume while extra-large formats gain share fastest on e-commerce consolidation economics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German heavy duty bin exports flow primarily into automotive assembly corridors across the United States and Central European manufacturing belts. This trade pattern reflects the concentration of injection-molding capacity near industrial demand centers.
United States
Automotive Tier 1 suppliers in Michigan and Ohio drive fleet renewal cycles for container-as-a-service contracts. EPA landfill diversion rules mandate reduced disposal volumes, pushing closed-loop pooling adoption. The Chicago-Detroit-Cleveland industrial corridor concentrates demand for load-bearing containers in metal forging and assembly plant logistics.
Germany
REACH substance restrictions limit certain plasticizers in cross-border pooling networks, fragmenting formulation standardization. ECHA compliance costs pressure mid-sized fabricators toward consolidated resin sourcing. The Baden-Württemberg automotive cluster anchors demand for robotics-compatible bin dimensioning in Stuttgart-area assembly plants.
China
E-commerce fulfillment centers drive extra-large capacity adoption for SKU consolidation into fewer tote movements. MIIT industrial standards govern load-rating documentation for mechanized handling equipment. The Yangtze River Delta manufacturing belt concentrates injection-molding capacity serving domestic automotive and electronics logistics.
Japan
Food and pharmaceutical logistics segments demand washdown-compatible plastic formulations with reduced tare weights. METI circular economy guidelines incentivize recycled resin integration in multi-trip container fleets. The Kanto region around Tokyo anchors precision manufacturing demand for automated warehouse integration.
India
Construction site logistics teams scale reusable container fleets to replace single-use packaging across infrastructure projects. BIS certification requirements extend qualification timelines for load-bearing capacity documentation. The Maharashtra-Gujarat industrial corridor concentrates demand from automotive and chemical processing plants.
Heavy Duty Bins Market Competitive Landscape
Channel-controlling players compete with product-specialist players across tiered market strata. Consolidation pressures favor operators with captive recycling infrastructure and automated warehouse integration capabilities. Three archetypes dominate: closed-loop pool operators, injection-molding scale producers, and robotics-compatible engineering specialists. M&A activity concentrates around recycling asset acquisition, while capacity expansion targets automotive corridor proximity.
Within the pool-operator archetype, ORBIS Corporation and Schoeller Allibert exemplify channel-controlling positioning through fleet management scale. SSI Schaefer occupies a distinct tier among warehouse integration specialists, embedding containers within automated material handling architectures. These three entities anchor competitive dynamics through differentiated control points—recycling infrastructure, folding-ratio engineering, and robotics compatibility—rather than undifferentiated product manufacturing.
| Leading Market Players |
|---|
| ORBIS Corporation |
| Akro-Mils |
| SSI Schaefer |
| Schoeller Allibert |
| Rubbermaid |
| RPC Group Plc |
| Snyder Industries |
| Greif |
| Mauser Group |
| Others |
Supply & Pricing Matrix
The Chicago-Detroit-Cleveland industrial corridor concentrates injection-molding capacity for automotive-grade heavy duty bins, creating localized pricing power for pool operators serving Tier 1 suppliers. EPA landfill diversion rules and OSHA load-rating standards embed compliance costs that manufacturers pass through to buyers seeking closed-loop fleet contracts.
Pricing Analysis
Next-generation robotics-compatible bin formats command 15-25% premiums over legacy fixed-wall designs due to precision dimensioning requirements. Three-tier pricing structure across premium, standard, and economy levels separates FDA food-contact certified formulations from general industrial grades and uncertified commodity bins. Cost compression in standard-grade plastic bins is intensifying because recycled HDPE feedstock volatility compresses margin buffers for injection molders. Contractors and project-based buyers exhibit highest price sensitivity, while automotive manufacturers prioritize performance guarantees over unit cost.
Supply Chain Analysis
Export-control regimes on advanced polymer compounding technology limit cross-border transfer of high-performance recycled resin formulations. Supply concentrates in the United States, Germany, and China, with the Yangtze River Delta anchoring injection-molding capacity for domestic automotive and electronics logistics. Raw material dependencies center on virgin and recycled polyethylene pellets, steel coil for welded metal variants, and chemical additives for FDA compliance. Single-source vulnerability in automotive-grade recycled resin supply creates exposure for North American pool operators. Distribution runs through captive fleet management networks rather than traditional wholesale channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story where switching costs lock automotive OEMs into established pool operator relationships through just-in-sequence delivery integration.
For Market Incumbents: Build captive recycling infrastructure moats by acquiring post-industrial HDPE collection assets in Michigan and Ohio. ORBIS Corporation's closed-loop model demonstrates how backward integration into resin recovery insulates against petrochemical feedstock volatility. Defend against folding-ratio engineering specialists by embedding RFID tracking layers that increase customer switching costs. For New Entrants and Emerging Players: Establish a beachhead in construction site logistics where project-based procurement favors rental flexibility over long-term pooling contracts. The agriculture segment presents penetrable white space through seasonal harvest logistics demanding collapsible compression-optimized designs. Pursue container-as-a-service go-to-market positioning to transfer fleet management risk from capital-constrained contractors. For Investors and Strategic Acquirers: Long-term, this sits as a circular-economy infrastructure play because extended producer responsibility frameworks shift cost accountability upstream to manufacturers and pool operators. Acquisition targets should display captive recycling assets or robotics-compatible engineering capabilities. Monitor EPA enforcement intensity on landfill diversion rules as the critical inflection signal for pooling network expansion velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Recycling Infrastructure Acquisition | Backward integration into post-industrial HDPE collection secures resin supply for automotive Tier 1 contracts. |
| Robotics-Compatible Dimensioning Investment | Precision-engineered gripping surfaces unlock specification premiums in automated warehouse integration projects. |
| Container-as-a-Service Platform Launch | Revenue model shift from capital sales to performance-guaranteed fleet management transfers utilization risk. |
| Folding-Ratio Engineering Partnership | Compression-optimized designs reduce return-trip volume by seventy percent in agriculture pooling networks. |
| Extended Producer Responsibility Compliance Program | Proactive regulatory positioning captures service revenue streams emerging from accountability framework shifts. |
Research Methodology
Two parallel data streams informed the analysis: primary field engagement with industry stakeholders and secondary validation across regulatory and trade databases. Interviews covered pool operator fleet managers, automotive Tier 1 procurement directors, injection-molding plant engineers, and construction site logistics coordinators. Secondary sources included EPA enforcement records, OSHA material handling standard updates, customs trade data on plastic container imports, and SEC filings from publicly traded packaging companies. Bottom-up unit economics modeling triangulated against top-down market sizing from production capacity assessments.
Forecast inputs considered product type evolution, capacity format preferences, end-user procurement model shifts, and regional regulatory enforcement trajectories across the analysis window. Segmentation dimensions modeled include material formulation, use case application, end-user procurement authority, and capacity tier. CAGRs derived from elasticity-adjusted demand projections and supply-side capacity expansion schedules. Industry-specific inputs incorporated automotive production cycle timing and e-commerce fulfillment center buildout pipelines.
Stress conditions across petrochemical feedstock volatility, steel tariff exposure, and REACH substance restriction expansion were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions on regulatory enforcement intensity and pooling network densification rates. Material shifts in extended producer responsibility framework adoption timelines or automotive electrification-driven supply chain reconfigurations would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Heavy Duty Packaging
Hazardous Goods Packaging Market
Heavy Duty Packaging
Global Heavy Duty Bags and Sacks Market
Heavy Duty Packaging
High-Stress PCR HDPE Detergent Bottles Market
Heavy Duty Packaging
Heavy-Duty Paper and Multiwall Shipping Sack Market
Heavy Duty Packaging
Large Blow Molded Products Market
Heavy Duty Packaging
Hazmat Packaging Market
Heavy Duty Packaging
Europe High Density Polyethylene Jerrycan Market
Heavy Duty Packaging
Heavy Duty Paper Tags Market
Heavy Duty Packaging
Heavy Duty Corrugated Packaging Market
Heavy Duty Packaging
High-Density Packaging Market
Heavy Duty Packaging
High Impact Corrugated Boxes Market
Heavy Duty Packaging
Heavy-Duty Corrugated Boxes Market