
 Water Resistant Packing Cubes Market | 2026-2036
Water Resistant Packing Cubes Market Size, Share, and Industry Trends Forecast 2026-2036
Water Resistant Packing Cubes Market Analytics
Premium-grade water resistance certification is collapsing the gap between specialty outdoor gear and mainstream luggage accessories. Eagle Creek leverages decades of expedition-grade manufacturing heritage to sustain credibility among technical users. Away competes through direct-to-consumer channel control and minimalist design language that resonates with urban travelers. Peak Design anchors its position in the creator-economy segment with modular compatibility across its ecosystem.
Water resistant packing cubes are organizational containers engineered from coated synthetic fabrics—typically ripstop nylon or thermoplastic polyurethane laminates—with sealed seams and water-repellent zippers designed to shield contents from moisture intrusion during transit or exposure. Their primary commercial purpose centers on compartmentalized luggage organization for travelers operating in variable climates or humidity conditions. Compression cubes dominate volume throughput as the default utility format, while tech pouches command disproportionate margin contribution due to specialized protective foams and precision-fit dimensions for electronics. TPU-based material variants represent the fastest-growing structural segment as consumers prioritize fully waterproof barriers over conventional water-repellent coatings in adventure-travel contexts.
EPA oversight of per- and polyfluoroalkyl substances directly constrains durable water repellent chemistry options available to manufacturers serving North American distribution channels. REACH registration requirements in Europe impose parallel compliance burdens on imported textile coatings and adhesive formulations. ISO 811 hydrostatic head testing standards increasingly shape procurement specifications for retail buyers and corporate travel program managers. Stakeholders must monitor regulatory phase-outs of legacy fluorocarbon treatments while evaluating bio-based water-repellent alternatives that maintain performance parity.
Market Dynamics
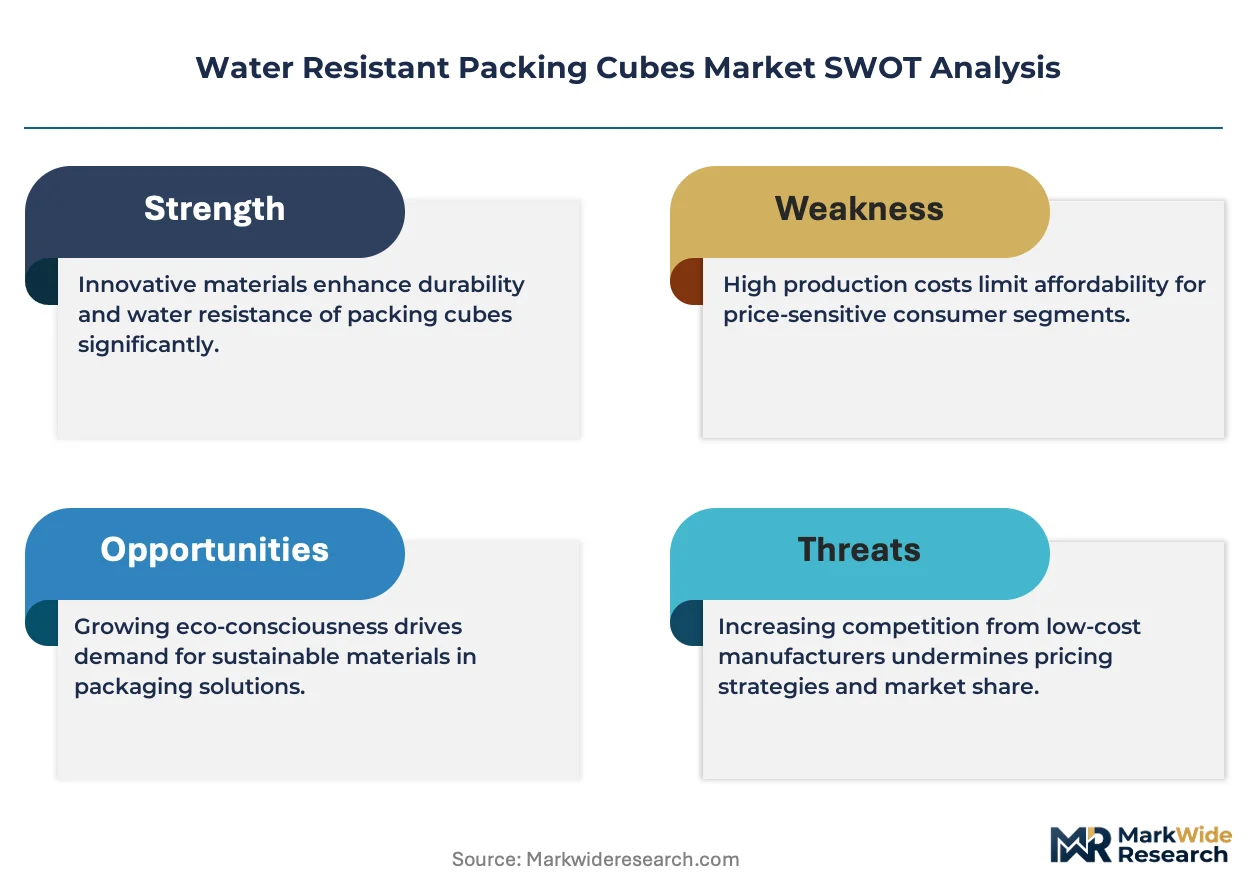
EPA phase-outs of per- and polyfluoroalkyl substances are forcing manufacturers to abandon legacy durable water repellent chemistries and reformulate with bio-based alternatives that meet ISO 811 hydrostatic head benchmarks.
Growth Catalysts
- REACH registration requirements:European ECHA mandates on textile coatings accelerate certified supplier consolidation, creating procurement preference for compliant manufacturers serving EU distribution channels.
- Adventure travel segment expansion:Outdoor enthusiasts operating in variable humidity conditions drive TPU laminate adoption for fully waterproof barriers over conventional water-repellent nylon.
- Creator economy mobility:Content producers requiring modular, precision-fit electronics protection generate disproportionate margin contribution from tech pouch subcategories.
Market Restraints
- Fluorocarbon chemistry obsolescence:Legacy C6 and C8 DWR treatments face regulatory prohibition, stranding formulation R&D investments and compressing available coating options.
- Ripstop nylon supply concentration:Synthetic fabric production clusters in East Asian textile hubs expose brands to freight cost volatility and tariff exposure.
- Biodegradable alternative performance gap:Plant-based water-repellent treatments currently fail to match the wash durability of synthetic predecessors, limiting premium positioning.
Strategic Opportunities
- Underpenetrated corporate travel procurement:Fortune 500 travel program managers in Germany and Japan increasingly specify ISO-certified organizational accessories for employee mobility kits.
- Direct-to-consumer channel control:Vertically integrated brands bypass wholesale margin compression through owned e-commerce and flagship retail in urban centers.
- EU Green Deal alignment:Circular economy action plan incentives reward take-back programs and recycled content verification for textile accessories.
Industry Challenges
- Specialized polymer engineering talent scarcity:TPU lamination expertise and seam-sealing automation programming skills concentrate among legacy outdoor gear manufacturers.
- Multi-jurisdiction certification timelines:Simultaneous EPA, REACH, and state-level chemical disclosure compliance extends product launch cycles by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Water Resistant Packing Cubes Market |
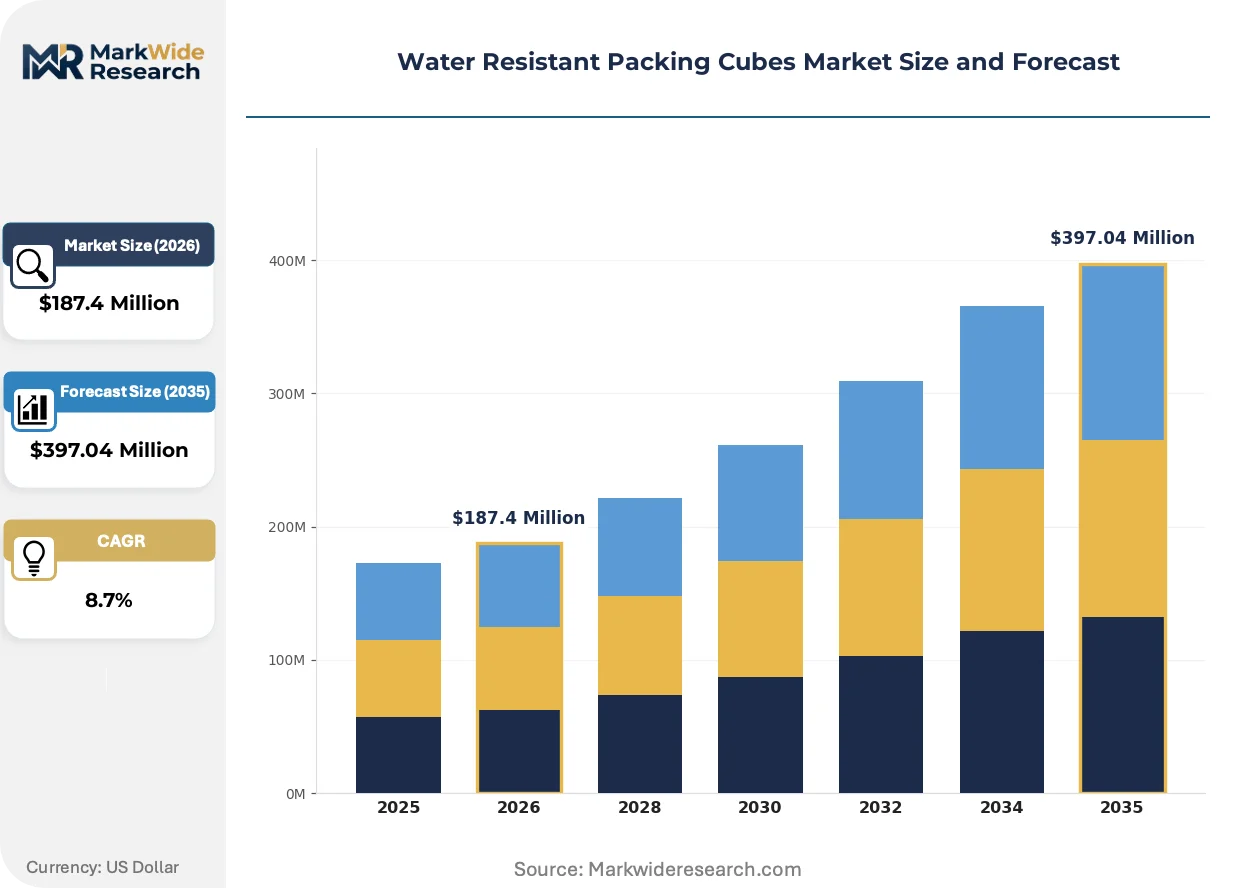
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Compression Cubes, Shelved Cubes, Laundry Cubes, Tech Pouches Material: Nylon, Polyester, Canvas, TPU Size: Small, Medium, Large, Extra Large End User: Travelers, Outdoor Enthusiasts, Business Professionals, Students |
| Companies Covered | Eagle Creek, Away, Tumi, eBags, Vasco Bags, Red Oxx Mfg, Anatomie Store, Peak Design, Thule, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Water Resistant Packing Cubes Market Evolving Landscape
Material science breakthroughs and regulatory chemistry mandates are collapsing the functional boundary between expedition-grade equipment and urban luggage accessories, compressing traditional category distinctions.
Thermoplastic polyurethane laminate construction is decomposing the historical separation between water-repellent and fully waterproof packing accessories. Adventure travelers and backcountry operators now specify TPU as baseline equipment for humidity-critical itineraries. This material migration is decomposing the premium tier into a standard-performance floor, forcing legacy nylon specialists to defend positioning through certification depth rather than barrier claims alone.
REACH authorization restrictions on perfluorinated compounds impose parallel compliance burdens across EU and UK distribution channels. Manufacturers serving European retail must now validate alternative water-repellent chemistries through ECHA-recognized testing protocols. The outdoor specialty segment bears disproportionate adaptation costs, with smaller brands lacking in-house toxicology resources outsourcing formulation development to certified chemical suppliers.
Corporate procurement departments now mandate sustainability credentials alongside performance specifications for employee travel accessories. Travel managers at technology and professional services firms in the United States and Japan increasingly require recycled content verification and repairability documentation. This specification elevation disadvantages wholesale-dependent brands lacking direct customer data infrastructure to demonstrate compliance transparency.
Water Resistant Packing Cubes Market Segmentation
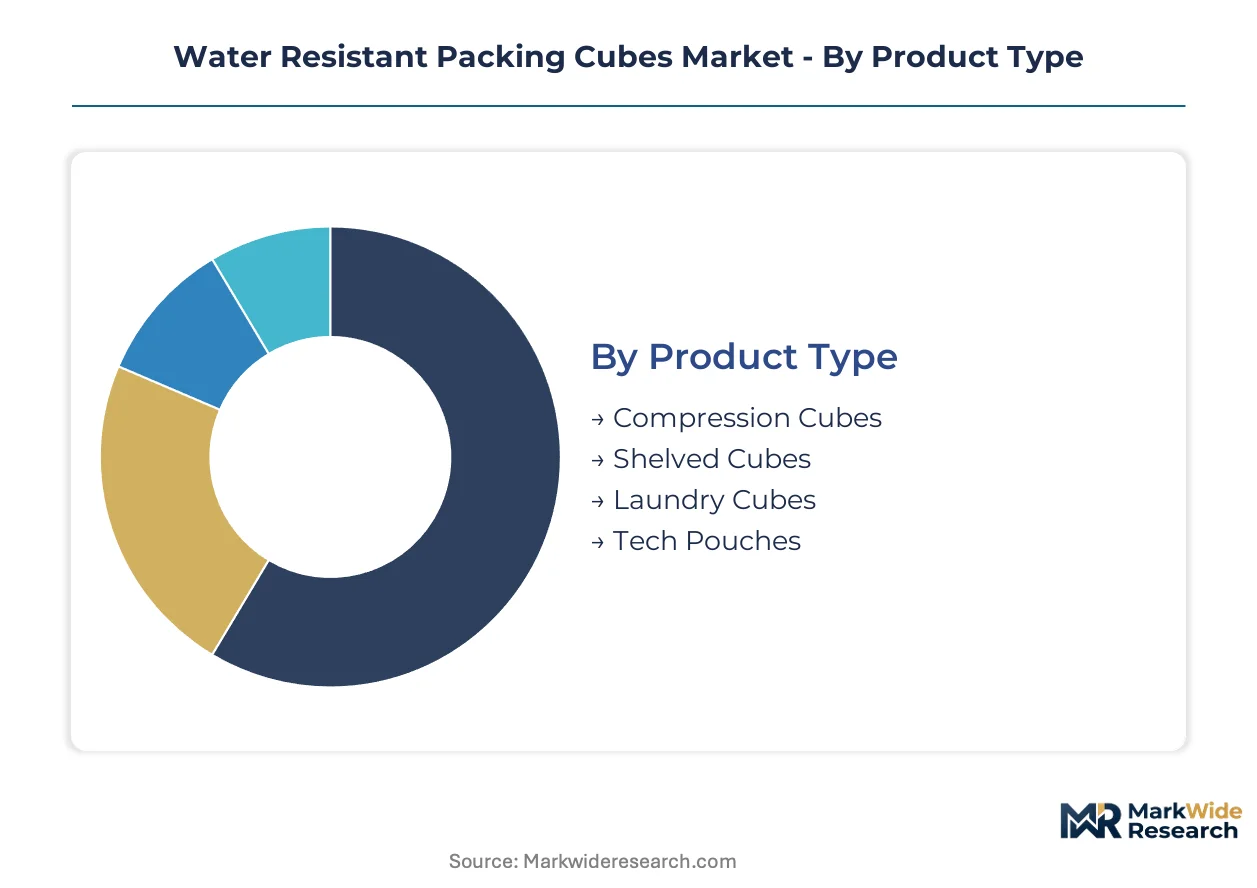
Product configuration and material selection in water resistant packing cubes determine distribution economics and margin structure. Compression formats dominate volume throughput while specialized electronics protection commands premium positioning. Material chemistry choices increasingly hinge on REACH and EPA compliance timelines rather than performance specifications alone.
Product Type:
Domestic retail channels in the United States and Germany favor compression and shelved formats for urban travelers, while export-led demand from Japanese and Australian distributors concentrates on tech pouches and laundry cubes for adventure itineraries.
- Compression Cubes:Engineered with dual-zipper expansion systems and laminated nylon shells rated to ISO 811 hydrostatic head standards. Demand concentrates among frequent flyers operating through variable-climate hubs like Singapore and Dubai, driven by luggage weight optimization mandates from low-cost carriers. Compression Cubes command the established base.
- Tech Pouches:Precision-molded EVA foam inserts with TPU-laminated exteriors and welded seam construction for electronics protection. Creator-economy professionals in Los Angeles and Tokyo generate disproportionate procurement volume, prioritizing modular compatibility across accessory ecosystems. The steepest expansion runs through Tech Pouches.
- Shelved Cubes:Internal compartment dividers with rigid polymer frames for garment organization.
- Laundry Cubes:Antimicrobial-lined compartments with odor-barrier films for soiled item separation.
Compression formats anchor mass-market retail placement. Tech pouch specialization delivers the fastest margin expansion trajectory.
Material:
Cost tier stratification separates commodity synthetic supply from certified sustainable alternatives, with premium positioning requiring ECHA-recognized bio-based water-repellent validation.
- TPU:Fully welded thermoplastic polyurethane laminate construction delivering hydrostatic resistance exceeding 10,000mm. Expedition operators in New Zealand and Norway specify TPU as baseline equipment for humidity-critical itineraries, displacing conventional coated nylons in adventure-travel procurement. TPU represents the fastest-climbing material category.
- Nylon:Ripstop weave constructions with C0 durable water repellent treatments compliant with EPA PFAS phase-out timelines. Corporate travel programs in Germany and Japan continue specifying nylon for employee mobility kits due to established supplier certification and repairability documentation. Nylon retains the volume foundation.
- Polyester:Recycled-content PET variants gaining traction through EU Green Deal circular economy incentives.
- Canvas:Waxed cotton and hemp blends targeting heritage positioning in boutique retail channels.
Nylon maintains procurement preference among Fortune 500 travel managers. TPU laminate adoption accelerates most quickly in outdoor specialty distribution.
Size:
Application context dictates dimensional specification, with business travel and student segments driving divergent format requirements across regional markets.
- Medium:Standard carry-on compatibility dimensions optimized for 20-22 inch roller luggage. Business professionals in London and Frankfurt generate consistent procurement volume for 2-3 day itineraries, prioritizing single-bag mobility compliance with airline cabin restrictions. Medium sizes dominate transaction frequency.
- Small:Compact formats for accessory organization and under-seat personal item compliance.
- Large:Checked luggage scale for extended-duration travel and family packing configurations.
- Extra Large:Expedition-scale capacity for gear-intensive outdoor activities.
Medium formats anchor standard retail assortment. Small sizes gain share fastest through direct-to-consumer subscription bundling.
End User:
Customer type determines channel configuration and certification depth, with corporate procurement elevating compliance requirements above consumer retail.
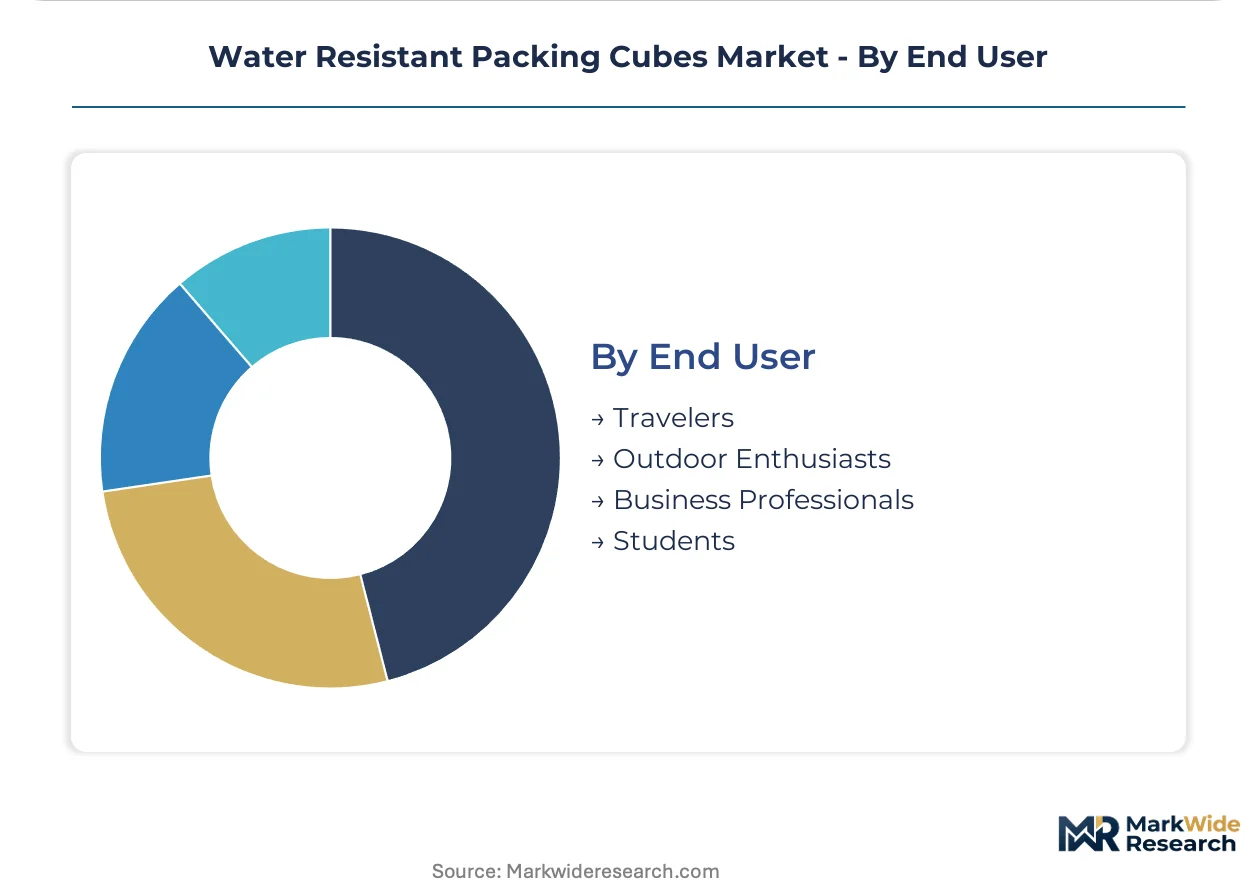
- Travelers:General leisure and business segments prioritizing organizational efficiency and weather protection. Urban professionals in New York and Chicago drive e-commerce volume through direct-to-consumer brands, responding to minimalist design language and lifetime warranty positioning. Travelers constitute the core revenue base.
- Outdoor Enthusiasts:Backcountry operators and adventure travelers requiring fully waterproof barrier performance. Technical users in Colorado and the Pacific Northwest specify ISO-certified TPU construction for moisture-critical environments, driving premium tier expansion through specialty retail. Outdoor Enthusiasts deliver the steepest growth trajectory.
- Business Professionals:Corporate travel program procurement with sustainability credential mandates.
- Students:Price-sensitive segment concentrated in back-to-school retail windows and campus bookstore channels.
General travelers maintain volume concentration. Outdoor specialist demand expands most rapidly through technical certification requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Synthetic fabric production clusters in East Asian textile hubs expose brands to freight cost volatility and tariff exposure, while regulatory compliance timelines in North America and Europe reshape procurement specifications across distribution channels.
United States
Urban professionals in New York and Chicago drive direct-to-consumer volume through minimalist design preferences, while corporate travel managers at technology firms mandate sustainability credentials for employee mobility kits. EPA phase-outs of per- and polyfluoroalkyl substances constrain durable water repellent chemistry options for manufacturers serving North American distribution. Los Angeles anchors creator-economy demand for modular tech pouch configurations.
Germany
Fortune 500 travel program procurement in Frankfurt and Munich elevates ISO-certified organizational accessories with recycled content verification requirements. REACH registration mandates through ECHA accelerate certified supplier consolidation, creating procurement preference for compliant manufacturers. Bavaria hosts specialty outdoor retailers driving TPU laminate adoption for humidity-critical itineraries.
Japan
Business professionals in Tokyo and Osaka generate consistent demand for medium-format compression cubes optimized for single-bag mobility compliance. METI industrial standards influence textile coating specifications for imported accessories. The Kansai region concentrates premium retail infrastructure serving adventure travel segments.
Australia
Backcountry operators in Queensland and Western Australia specify fully waterproof TPU construction for moisture-critical expedition environments. The country's national environmental regulator maintains strict chemical disclosure requirements on imported textile coatings. Sydney anchors urban professional demand through direct-to-consumer brand penetration.
United Kingdom
Corporate travel procurement in London specifies repairability documentation alongside performance benchmarks for employee accessories. Post-Brexit regulatory alignment with REACH authorization restrictions imposes parallel compliance burdens on textile coating formulations. The Midlands region concentrates logistics infrastructure for EU-UK distribution reconciliation.
Water Resistant Packing Cubes Market Competitive Landscape
Concentration sits with expedition-heritage manufacturers and direct-to-consumer specialists, while wholesale-dependent brands face margin compression from channel disintermediation. The vendor base spans three strategic tiers: legacy outdoor gear fabricators with certification depth, vertically integrated urban luggage brands controlling owned e-commerce, and private-label suppliers serving mass retail. Dominant competitive moves include backward integration into TPU lamination capacity and geographic expansion through flagship retail in metropolitan centers.
Within the expedition-heritage tier, Eagle Creek and Peak Design exemplify positioning through decades of technical manufacturing credibility and creator-economy ecosystem integration respectively. Among direct-to-consumer specialists, Away occupies a position through channel control and minimalist design language resonance with urban travelers. Thule anchors the premium mobility accessories segment through cross-category brand extension from automotive cargo systems.
| Leading Market Players |
|---|
| Eagle Creek |
| Away |
| Tumi |
| eBags |
| Vasco Bags |
| Red Oxx Mfg |
| Anatomie Store |
| Peak Design |
| Thule |
| Others |
Value Network & Pricing Analysis
Capacity utilization rates above 85% at Vietnamese and Bangladeshi textile mills compress margin flexibility for brands sourcing coated nylons, while EPA compliance investments in alternative water-repellent chemistries establish price floors that favor scaled manufacturers with captive formulation R&D.
Pricing Analysis
REACH authorization restrictions dictate the pricing tier structure across European distribution channels, with ECHA-recognized bio-based DWR validation separating premium positioning from commodity tiers. Three-tier pricing structure across premium, standard, and economy levels reflects ISO 811 hydrostatic head certification grade and volume scale. Cost compression in the standard tier intensifies because legacy C6 chemistry obsolescence strands mid-tier suppliers lacking reformulation partnerships. Corporate travel programs exhibit lowest price sensitivity due to sustainability credential mandates, while student segments concentrate demand in economy tiers through campus bookstore channels.
Supply Chain Analysis
Strategic stockpile preferences dominate procurement behavior among expedition-gear specialists, who maintain 90-120 day TPU laminate inventories to buffer against East Asian textile hub disruptions. Synthetic fabric production draws from China, Vietnam, and Taiwan, with ripstop nylon weaving and coating concentration exposing brands to tariff volatility. Raw material dependencies center on thermoplastic polyurethane pellets, C0 DWR treatment chemicals, and YKK water-repellent zipper assemblies. Single-source vulnerability in seam-sealing automation equipment constrains rapid capacity expansion. Distribution runs through direct-to-consumer flagship retail in urban centers, wholesale outdoor specialty networks, and corporate procurement portals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
After-sales repair and recoat services expand faster than hardware unit sales, creating attach-rate opportunities that recalibrate lifetime customer value calculations away from transactional margins.
For Market Incumbents: Fortify certification depth through backward integration into TPU lamination capacity and ECHA-recognized toxicology partnerships, defending against direct-to-consumer entrants lacking compliance infrastructure. Prioritize ISO 811 testing laboratory accreditation as a procurement gatekeeper for Fortune 500 travel programs. Channel control through owned e-commerce insulates against wholesale margin compression from Amazon and REI marketplace fees. For New Entrants and Emerging Players: Repair-service networks represent the most penetrable white-space, as legacy manufacturers under-invest in recoat infrastructure and warranty fulfillment speed. Target creator-economy professionals in Los Angeles and Tokyo through modular tech pouch compatibility with existing Peak Design and Away ecosystems. Launch through Kickstarter validation to demonstrate demand density before retail distribution commitments. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors vertically integrated specialists with captive TPU lamination and ECHA registration capabilities over wholesale-dependent brands. Long-term viability hinges on regulatory chemistry adaptation speed rather than brand heritage alone. Acquisition targets should demonstrate repair-service attach rates above 15% and direct-to-consumer revenue mix exceeding 40%. Watch EPA state-level chemical disclosure expansion as the inflection signal for compliance cost acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| TPU Lamination Capacity Expansion | Captive supply of fully waterproof barriers reduces dependency on East Asian coating specialists and accelerates REACH-compliant product launches. |
| Direct-to-Consumer Channel Launch | Owned e-commerce in New York and Berlin captures margin compression from wholesale intermediaries and enables subscription bundling. |
| Repair-Service Network Buildout | After-sales recoat infrastructure extends product lifecycles and satisfies EU Green Deal circular economy incentive requirements. |
| ECHA-Recognized Formulation Partnership | Certified bio-based DWR chemistry access insulates against EPA fluorocarbon phase-out stranding risk. |
| Corporate Procurement Portal Integration | ISO 811 documentation and sustainability credential transparency unlock Fortune 500 travel program specification. |
Research Methodology
A standing panel of product development directors at expedition-gear manufacturers, ECHA compliance consultants, corporate travel procurement managers, and specialty retail buyers provided ongoing calibration throughout the study period. Primary interview data combined with secondary validation from customs trade records, EPA chemical disclosure filings, and ISO certification databases. Bottom-up unit economics triangulated against top-down market sizing from retail audit data and distributor shipment reports.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework modeled product type, material chemistry, end-user segment, and regional regulatory cluster dimensions. CAGRs derived from segment-level growth rate reconciliation with macroeconomic travel demand indicators and corporate mobility program expansion patterns. Forecast inputs incorporated low-cost carrier luggage restriction tightening and adventure travel participation trends.
Forecasts assume regulatory continuity in EPA, REACH, and METI regimes; material policy shifts would require re-modeling of chemistry transition timelines and certification cost burdens. Specific risks include accelerated PFAS prohibition schedules, East Asian textile hub labor disruptions, and corporate travel budget contractions. Revision becomes warranted when TPU laminate price volatility exceeds 25% annual amplitude or when EU Green Deal circular economy mandates expand to mandatory take-back quotas.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Containers
Concentrate Containers Market
Containers
EPS Container Market
Containers
Disposable Cups and Lids Market
Containers
Old Corrugated Containers (OCC) Market
Containers
Multi Cavity Tray Market
Containers
Americas Container Technology Market
Containers
PUR Containers Packaging Market
Containers
Disposable Lids Market
Containers
Foldable Large Containers Market
Containers
PP Container Liner Market
Containers
Stackable Plastic Trays Market
Containers
Thin Wall Plastic Containers Market
Containers
USA and Canada Packer Bottle Market
Containers
Global Food Storage Container Market
Containers
Wooden Crates Market
Containers
Global Cardboard Box and Container Market