
 High Impact Corrugated Boxes Market | 2026-2036
High Impact Corrugated Boxes Market Size, Share, and Industry Trends Forecast 2026-2036
High Impact Corrugated Boxes Market Foresight
Recycled fiber integration with virgin pulp is narrowing performance gaps between sustainable and conventional high-impact grades. International Paper Company leverages its North American containerboard network to control raw material flows from mill to box plant. WestRock Company anchors its position through backward integration into pulp production and automated converting assets. Smurfit Kappa Group specializes in heavy-duty triple-wall configurations for industrial machinery exports.
High impact corrugated boxes are engineered paperboard containers built with multi-layer flute structures—typically double or triple wall—to withstand compressive loads exceeding standard shipping demands, with burst strengths commonly rated above test standards for fragile or dense cargo. Their primary commercial purpose centers on protective transit packaging for weight-intensive, shock-sensitive, or high-value products across manufacturing and retail supply chains. Double wall box types capture the dominant volume share as they balance cost and load-bearing capacity for mainstream industrial applications, while triple wall configurations command premium positioning in aerospace components and heavy equipment logistics. Recycled paper material grades are gaining structural share as mills advance fiber recovery technologies that preserve strength properties through multiple re-pulping cycles.
The EPA guides containerboard recycling standards and emissions benchmarks for US mill operations, while REACH and the EU Packaging and Packaging Waste Regulation impose material traceability and extended producer responsibility obligations across European supply chains. These frameworks compel converters to certify recycled content thresholds and document end-of-life recovery pathways to maintain market access. Stakeholders must monitor evolving state-level packaging EPR laws in the US and pending EU recycled content mandates to calibrate capacity investments and supplier qualification protocols.
Market Dynamics
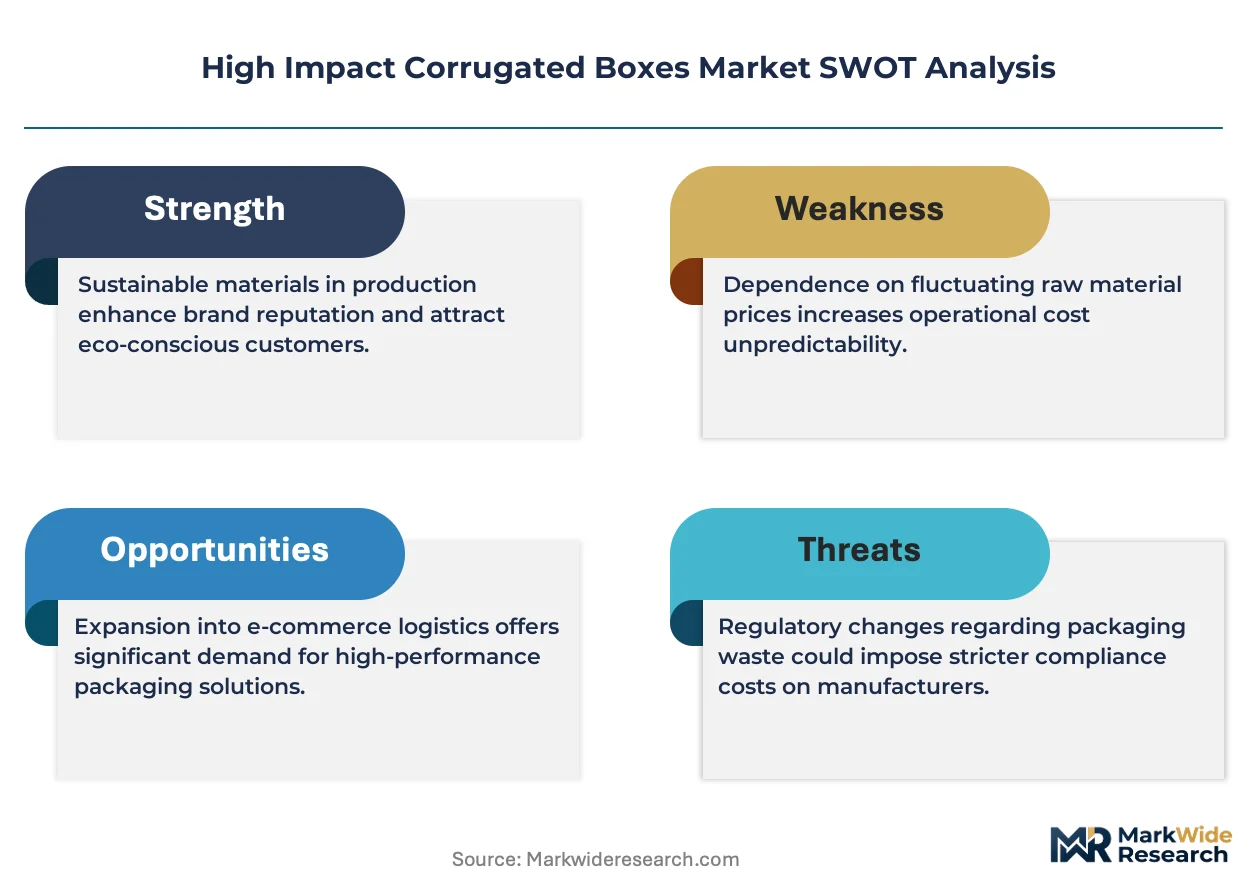
E-commerce fulfillment networks are compressing order-to-delivery cycles, forcing corrugated converters to engineer lighter-weight triple-wall configurations that maintain crush resistance while reducing dimensional weight charges for parcel carriers.
Growth Catalysts
- EU Packaging and Packaging Waste Regulation:Recycled content mandates are accelerating mill investments in fiber recovery technologies that preserve burst strength through multiple re-pulping cycles.
- Automotive export logistics:Germany's machinery and vehicle component manufacturers are specifying certified triple-wall boxes for ocean freight consolidation to Asia-Pacific markets.
- Digital printing integration:Direct-to-board inkjet systems are enabling batch-size-one production for customized protective packaging without plate changeover delays.
Market Restraints
- Old corrugated container (OCC) supply volatility:Export demand from Asian packaging mills is creating periodic fiber shortages in North American collection networks.
- Energy cost concentration:Natural gas price spikes in European integrated mills are compressing margins for kraft linerboard production.
- Plastic crate substitution:Returnable transit packaging systems are capturing closed-loop automotive component logistics from single-use corrugated.
Strategic Opportunities
- India's PLI scheme for manufacturing:Electronics and appliance production incentives are creating demand for export-grade protective packaging from domestic converters.
- CE marking alignment:Harmonized structural testing protocols are enabling European box producers to qualify for Middle East infrastructure project shipments without duplicate certification.
- Automated box-on-demand systems:Warehouse robotics integration is opening fleet retrofit opportunities for right-sized packaging generation at point of fulfillment.
Industry Challenges
- Structural engineer talent pipeline:Finite element modeling expertise for predictive crush simulation remains concentrated among legacy packaging science programs.
- ISPM-15 heat treatment compliance:Wooden pallet substitution with corrugated slip sheets requires documented phytosanitary equivalence that customs authorities dispute.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | High Impact Corrugated Boxes Market |
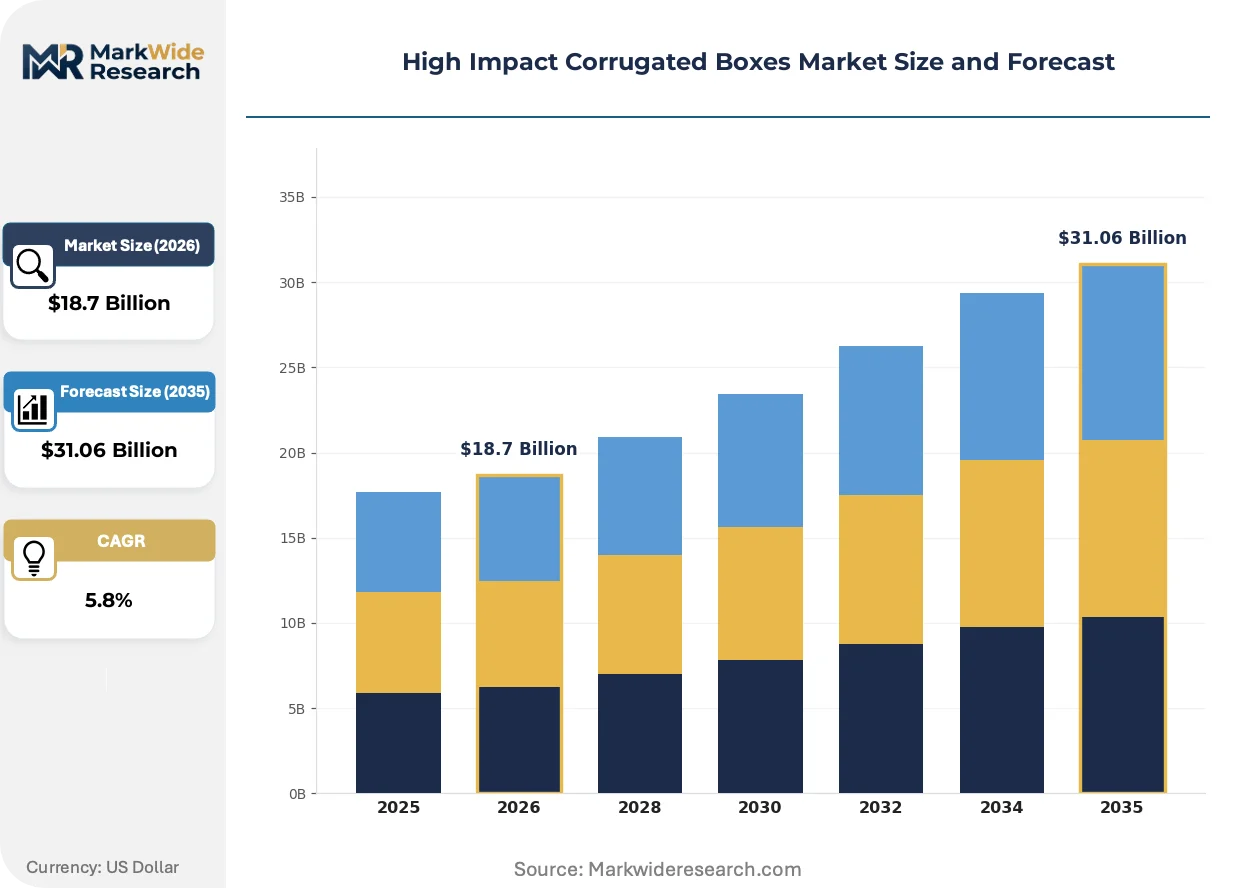
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $31.06 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Box Type: Single Wall, Double Wall, Triple Wall, Heavy Duty Material Type: Recycled Paper, Virgin Fiber, Coated Paper, Specialty Paper End User: Food & Beverage, Electronics, Consumer Goods, Pharmaceuticals Distribution Channel: Online Retail, Wholesale, Direct Sales, Packaging Distributors |
| Companies Covered | International Paper Company, WestRock Company, Smurfit Kappa Group, Mondi Group, DS Smith, Packaging Corporation of America, Georgia-Pacific LLC, Oji Holdings Corporation, Rengo Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
High Impact Corrugated Boxes Market Shifts & Advancements
Material science advances and regulatory stringency are converging to redefine performance benchmarks for protective shipping containers across industrial supply chains.
Flute profile miniaturization combined with high-performance adhesives is rendering obsolete traditional double-wall constructions for mid-weight electronics shipments. Medical device manufacturers in Switzerland and the Netherlands are specifying these engineered micro-flute grades for temperature-controlled pharmaceutical distribution. The structural efficiency gains are compressing fiber consumption per unit of protective capacity by approximately one-third versus legacy configurations.
REACH substance restrictions on formaldehyde-based resins are compelling adhesive reformulation across European converting assets. Water-based polymer alternatives are penetrating at scale in German and French box plants serving food-contact and toy applications. The transition is extending curing times and requiring recalibration of corrugator speed settings that had been optimized for thermosetting chemistries.
Consolidated buying by third-party logistics providers is compressing supplier rosters for protective packaging specifications. Amazon's Packaging Support and Supplier Network certification is displacing legacy vendor qualification processes for consumer electronics brands in North America. The concentration is visible most acutely in California and Washington state distribution clusters where sustainability scorecarding has become a gatekeeping criterion for contract renewal.
High Impact Corrugated Boxes Market Segmentation
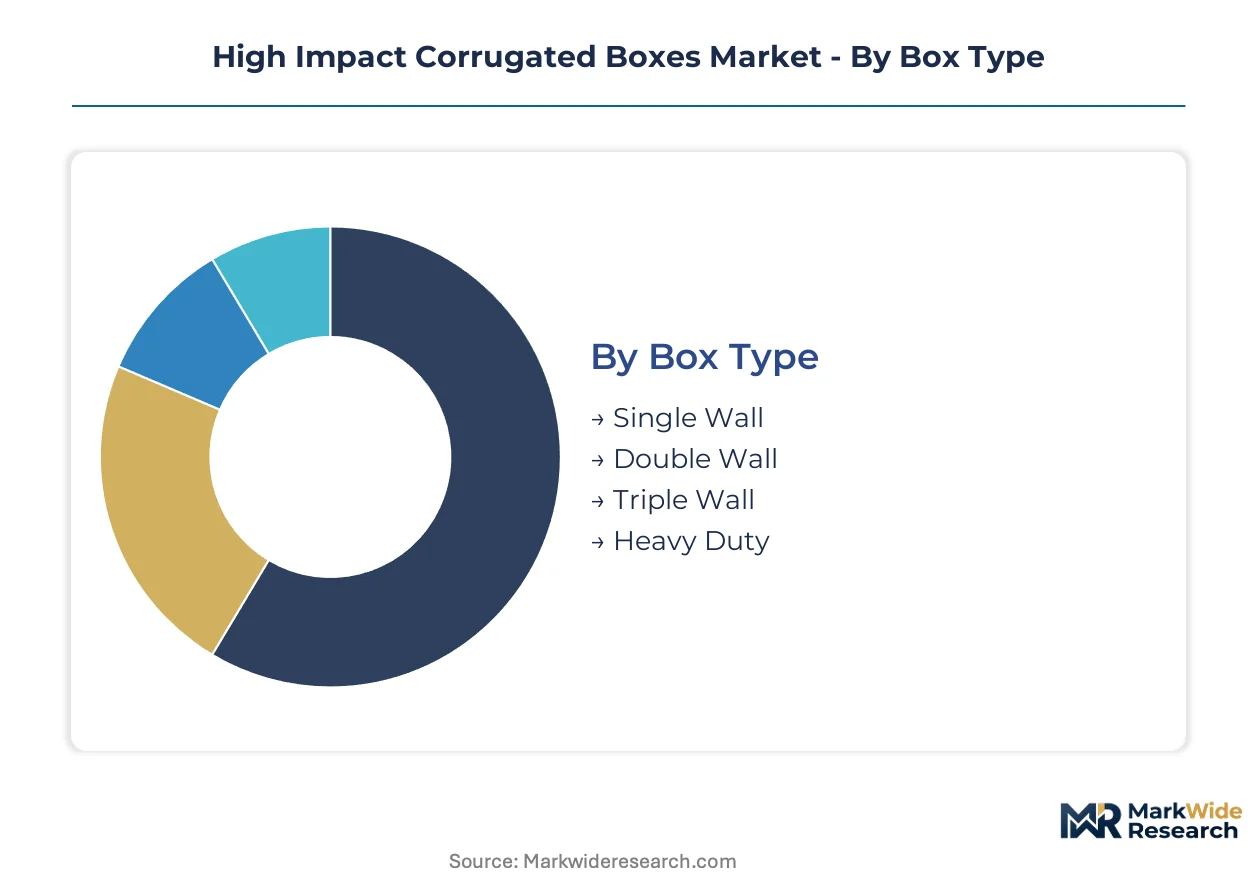
High impact corrugated boxes serve divergent protective requirements across industrial logistics and consumer fulfillment, making granular segmentation essential for capacity planning and specification alignment. Engineers and procurement teams navigate trade-offs between structural performance, fiber sourcing, and end-use compliance that reshape competitive positioning across each dimension.
Box Type:
Structural configurations span lightweight parcel protection through heavy machinery crating, with flute geometry and wall count determining load-bearing thresholds and freight economics.
- Double Wall:Two fluted mediums bonded between three linerboards deliver burst ratings sufficient for most industrial components and mid-weight electronics. Automotive parts suppliers in Germany specify this grade for intra-European consolidated freight, balancing protective capacity against dimensional weight penalties in parcel networks.
- Triple Wall:Three fluted layers with four linerboards achieve compressive strength exceeding 1,100 lbs per square foot for aerospace components and heavy equipment exports. Machinery manufacturers specify certified configurations for ocean freight consolidation to Asia-Pacific markets, where humidity exposure and stacking loads demand redundant structural margins.
- Single Wall:Standard A, B, or C-flute constructions serve lightweight consumer goods where crush resistance requirements remain modest.
- Heavy Duty:Custom-engineered board combinations with enhanced adhesives address irregular cargo profiles and extreme handling conditions.
The dominant share belongs to Double Wall, while Triple Wall is closing the gap fastest as export logistics specifications tighten.
Material Type:
Raw material sourcing strategies reflect regulatory pressure on recycled content thresholds and performance requirements for moisture resistance or printability.
- Recycled Paper:Post-consumer fiber recovery now preserves tensile properties through multiple re-pulping cycles, narrowing performance gaps with virgin grades. EU Packaging and Packaging Waste Regulation mandates are accelerating mill investments in de-inking and fiber conditioning systems across German and French integrated sites.
- Virgin Fiber:Unbleached kraft linerboard from northern softwood delivers maximum tear strength and moisture resistance for cold-chain pharmaceuticals and frozen food exports. Premium positioning reflects energy-intensive pulping processes and European natural gas cost volatility.
- Coated Paper:Clay or polymer surface treatments enable high-fidelity brand graphics for retail-ready packaging.
- Specialty Paper:Flame-retardant, anti-static, or grease-resistant formulations address niche hazardous material and electronics applications.
Recycled Paper commands volume leadership, though Specialty Paper is expanding most quickly as regulatory compliance complexity multiplies.
End User:
Demand concentration varies sharply by sector sensitivity to transit damage, regulatory traceability, and packaging cost as percentage of goods value.
- Electronics:Shock-sensitive semiconductors, displays, and finished devices require engineered cushioning integration with corrugated shells. E-commerce fulfillment networks in California and Washington state are compressing order-to-delivery cycles, forcing converters to certify vibration-dampening configurations for parcel carrier handling intensity.
- Pharmaceuticals:Temperature-controlled distribution mandates in Switzerland and the Netherlands are driving micro-flute adoption with insulated liner systems for biologics and vaccines.
- Food & Beverage:Moisture-resistant barriers and food-contact compliance dominate specification priorities for chilled and frozen supply chains.
- Consumer Goods:Brand differentiation through retail-ready graphics and right-size optimization shapes procurement for omnichannel fulfillment.
Electronics retains the largest share, while Pharmaceuticals is gaining share fastest on cold-chain infrastructure expansion.
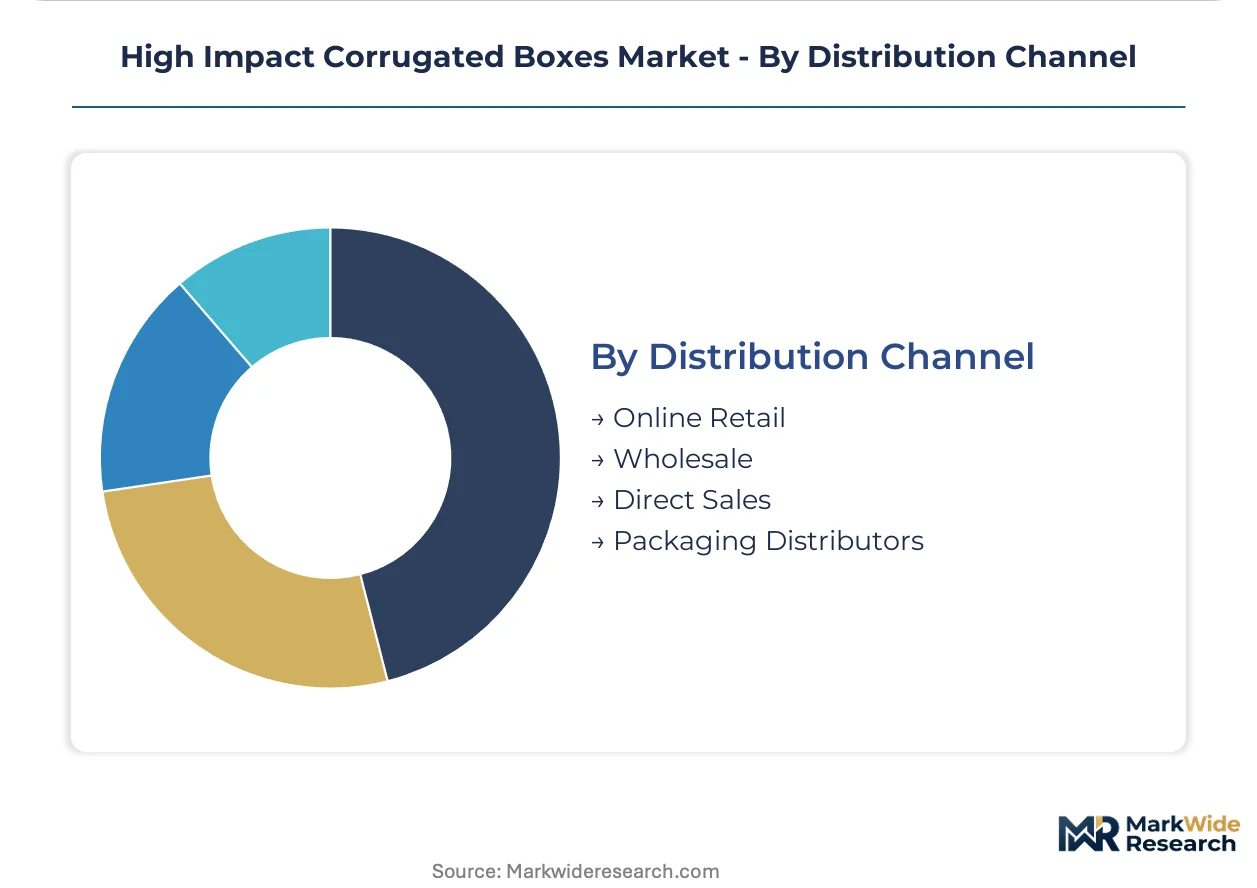
Distribution Channel:
Channel structure reflects customer scale, technical service requirements, and geographic concentration of protective packaging demand.
- Packaging Distributors:Independent and national distributors maintain regional inventory positions and structural engineering support for mid-market manufacturers. Consolidated buying by third-party logistics providers is compressing supplier rosters, with sustainability scorecarding becoming a gatekeeping criterion in California distribution clusters.
- Direct Sales:National account teams serve high-volume automotive and machinery OEMs with customized specification development and just-in-time delivery coordination.
- Online Retail:Digital procurement platforms are penetrating small-to-mid volume buyers with standardized grade catalogs and rapid quoting.
- Wholesale:Bulk volume transactions for commodity grades serve downstream converters and regional box plants.
Packaging Distributors holds the leading position, though Direct Sales is climbing the fastest as OEM consolidation concentrates procurement authority.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's automotive and machinery export corridors to Asia-Pacific markets are driving specification-grade demand for certified triple-wall configurations. Ocean freight consolidation routes from Hamburg and Bremerhaven ports require humidity-resistant protective packaging that maintains structural integrity across extended transit cycles.
United States
E-commerce fulfillment networks in California and Washington state are compressing order-to-delivery cycles, forcing converters to engineer lighter-weight triple-wall boxes. EPA containerboard recycling standards govern mill emissions benchmarks. The Pacific Northwest distribution cluster is certifying vibration-dampening configurations for parcel carrier handling intensity.
Germany
Automotive parts suppliers specify double-wall grades for intra-European consolidated freight, balancing protective capacity against dimensional weight penalties. EU Packaging and Packaging Waste Regulation mandates accelerate mill investments in fiber recovery technologies. Stuttgart and Munich industrial corridors are expanding certified triple-wall specifications for machinery exports to Asia-Pacific markets.
China
Electronics manufacturing clusters demand engineered cushioning integration with corrugated shells for shock-sensitive semiconductors and displays. GB standards and MIIT regulations shape packaging material traceability requirements. The Yangtze River Delta manufacturing belt is scaling domestic converter capacity for export-grade protective packaging.
India
Electronics and appliance production incentives under the PLI scheme are creating demand for export-grade protective packaging from domestic converters. BIS certification requirements govern structural performance standards. Maharashtra and Gujarat industrial corridors are attracting mill investments to serve contract manufacturing growth.
Japan
Precision machinery and automotive component exporters specify high burst-strength configurations for ocean freight consolidation. METI guidelines influence sustainable packaging material selection. The Nagoya industrial corridor maintains stringent quality protocols for aerospace and heavy equipment logistics.
High Impact Corrugated Boxes Market Competitive Landscape
Channel-controlling players compete with product-specialist players across a market structure that shows moderate consolidation at the integrated mill level and fragmentation among regional converting assets. Integrated containerboard producers with captive pulp supply dominate upstream supply security, while independent converters compete on specification flexibility and regional service density. Three archetypes define competitive positioning: North American integrated mills with backward fiber control, European specialists in heavy-duty industrial configurations, and Asia-Pacific scale players serving export manufacturing clusters. M&A activity concentrates on converting asset consolidation, while capacity expansion focuses on automated corrugator lines with digital printing integration.
Among the named entities, International Paper Company and WestRock Company represent the North American integrated mill archetype with upstream pulp production control, while Smurfit Kappa Group occupies a position exemplifying European specialization in heavy-duty triple-wall configurations for industrial machinery exports. These three entities anchor the competitive landscape by demonstrating divergent strategic postures: fiber security through captive supply, specification leadership through engineered structural solutions, and geographic footprint optimization across Atlantic trade corridors.
| Leading Market Players |
|---|
| International Paper Company |
| WestRock Company |
| Smurfit Kappa Group |
| Mondi Group |
| DS Smith |
| Packaging Corporation of America |
| Georgia-Pacific LLC |
| Oji Holdings Corporation |
| Rengo Co., Ltd. |
| Others |
Supply & Pricing Matrix
Mill undercapacity in Germany is compressing supplier pricing power while accelerating backward integration investments among converters seeking fiber security. This utilization squeeze feeds directly into contract renegotiation postures across European containerboard networks.
Pricing Analysis
Flute-generation pricing gaps separate legacy double-wall grades from micro-flute innovations and emerging nano-flute prototypes. Three-tier pricing structure across premium certified, standard industrial, and economy commodity levels dominates transactional flows. Price differentiation hinges on burst-strength certification tiers and volume-scale commitments in long-term offtake agreements. Cost compression in standard grades is intensifying because OCC supply volatility from Asian export demand is forcing spot-market fiber premiums. Automotive OEMs exhibit lowest price sensitivity due to damage-cost exposure, while e-commerce fulfillment houses face acute margin pressure from dimensional weight charges.
Supply Chain Analysis
Old corrugated container feedstock draws from North American collection networks, German integrated mill complexes, and emerging Indian de-inking facilities. Kraft linerboard, starch adhesives, and high-performance polymer alternatives constitute critical input dependencies. Single-source vulnerability concentrates in European natural gas supply for integrated kraft pulping operations. Distribution runs through packaging distributors maintaining regional inventory positions and direct sales channels serving national automotive accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story anchored in regulatory entrenchment: EU Packaging and Packaging Waste Regulation compliance creates certification barriers that entrench qualified incumbents against unqualified challengers.
For Market Incumbents: Insulate margin position through captive pulp supply expansion in the US Southeast and automated converting asset deployment in Germany's Stuttgart corridor. Plastic crate substitution in closed-loop automotive logistics represents the most acute substitution threat demanding counter-investment in returnable corrugated hybrid systems. Fiber recovery technology R&D serves as the critical defensive lever against recycled content mandate acceleration. For New Entrants and Emerging Players: India's Maharashtra and Gujarat industrial corridors under PLI scheme manufacturing incentives represent the most penetrable entry point for export-grade protective packaging qualification. Mid-volume electronics contract manufacturers in the Yangtze River Delta seeking secondary supplier diversification offer secondary white-space access. CE marking alignment for Middle East infrastructure project qualification provides the most efficient go-to-market angle versus duplicative certification burdens. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across automated corrugator lines with digital printing integration, favoring scaled players over fragmented regional converters. Long-term viability over the coming decade rests on fiber security positioning and regulatory compliance infrastructure depth. Acquisition target archetype: European mid-cap specialists with certified triple-wall capabilities and established automotive OEM relationships. The signal to watch as inflection indicator is mill consolidation activity in German and French integrated sites.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Pulp Production | Captive fiber supply secures margin stability against OCC export demand volatility from Asian mills. |
| Automated Corrugator Line Deployment | Digital printing integration enables batch-size-one production for e-commerce fulfillment customization requirements. |
| CE Marking Alignment Investment | Harmonized structural testing protocols unlock Middle East infrastructure project shipments without duplicate certification. |
| Fiber Recovery Technology Scale-Up | Advanced de-inking systems preserve burst strength through multiple re-pulping cycles for EU recycled content mandates. |
| Triple-Wall Certification Expansion | Certified configurations for ocean freight consolidation capture machinery export growth to Asia-Pacific markets. |
Research Methodology
Cross-validation between mill operations data and converter procurement patterns anchors the qualitative findings in this study. Primary interviews with corrugator plant managers, automotive packaging engineers, e-commerce fulfillment operations directors, and pulp procurement leads combined with secondary validation from EPA emissions filings, EU Packaging and Packaging Waste Regulation compliance databases, and containerboard trade flow records. Bottom-up capacity modeling and top-down demand segmentation triangulation ensure dimensional consistency across volume estimates.
Calibration against historical capacity utilization rates and announced mill investment pipelines shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include box type, material grade, end-use sector, and distribution channel, with additional weighting for regulatory compliance tier. CAGRs were derived from trend extrapolation adjusted for identified inflection triggers. Industry-specific forecast inputs encompass e-commerce parcel volume growth trajectories and automotive export logistics specification evolution.
Practitioners should monitor OCC export demand shifts, natural gas price volatility in European integrated mills, and state-level packaging EPR law progression for early signals requiring forecast revision. Cross-checking against customs trade data for containerboard and corrugated box movements is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Heavy Duty Packaging
Heavy Duty Bins Market
Heavy Duty Packaging
Heavy Duty Corrugated Packaging Market
Heavy Duty Packaging
Large Blow Molded Products Market
Heavy Duty Packaging
Hazardous Goods Packaging Market
Heavy Duty Packaging
Hazmat Packaging Market
Heavy Duty Packaging
High-Density Packaging Market
Heavy Duty Packaging
Europe High Density Polyethylene Jerrycan Market
Heavy Duty Packaging
Heavy-Duty Corrugated Boxes Market
Heavy Duty Packaging
Heavy Duty Paper Tags Market
Heavy Duty Packaging
High-Stress PCR HDPE Detergent Bottles Market
Heavy Duty Packaging
Heavy-Duty Paper and Multiwall Shipping Sack Market
Heavy Duty Packaging
Global Heavy Duty Bags and Sacks Market