
 Hazmat Packaging Market | 2026-2036
Hazmat Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Hazmat Packaging Market Intelligence
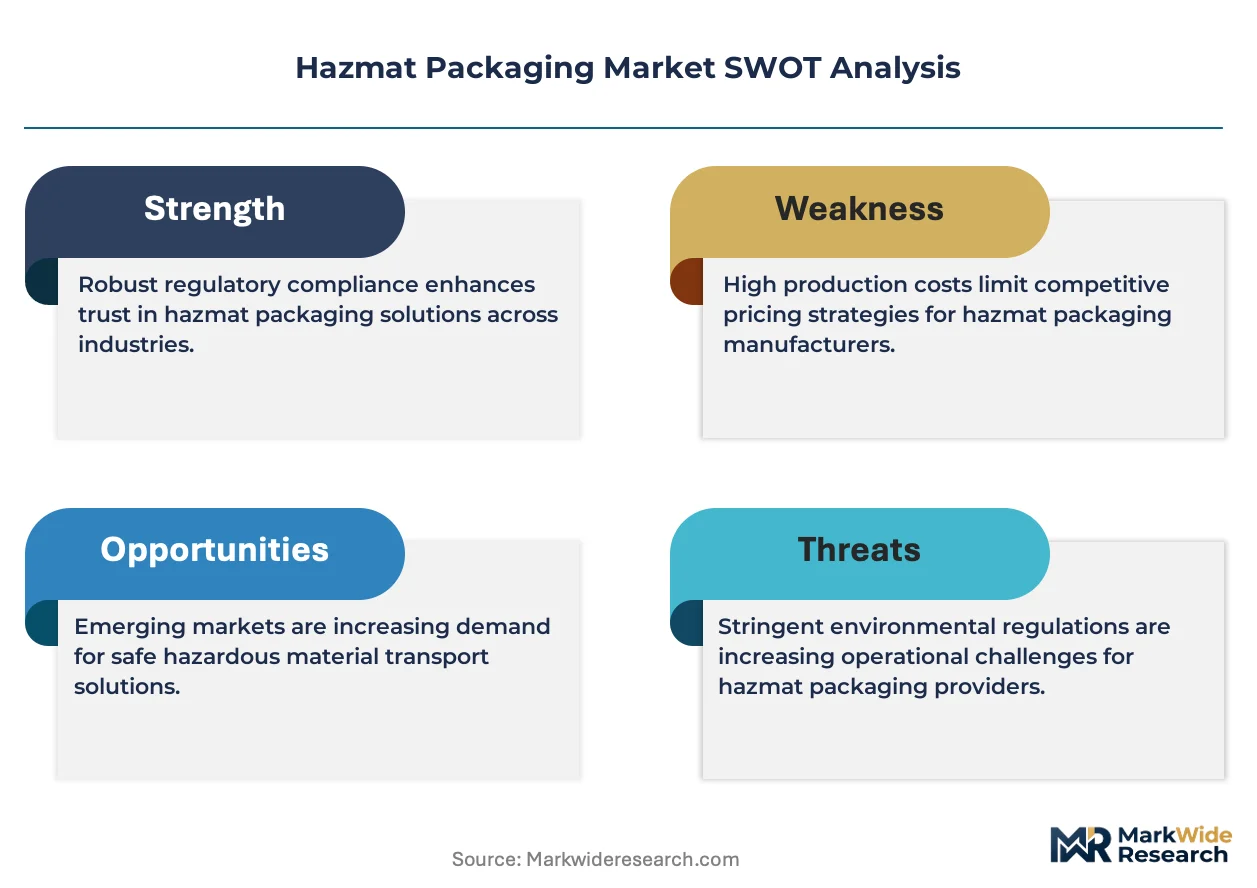
The European Union's REACH regulation is shifting the material science and testing requirements for hazmat packaging, increasing compliance costs for manufacturers. Greif, Inc. leverages its extensive global manufacturing footprint to meet diverse regional compliance standards. Schütz GmbH & Co. KGaA specializes in composite intermediate bulk containers, focusing on reusability and closed-loop systems. Mauser Group competes on the breadth of its product portfolio, from steel drums to plastic containers.
Hazmat packaging comprises containers specifically engineered and certified to transport hazardous materials safely. These products must pass rigorous testing, including drop, stack, and pressure tests, to receive specific UN certification markings that dictate their approved contents. Steel and plastic drums continue to dominate the market by volume for bulk chemical transport. However, composite totes and specialized bottles for laboratory samples represent the fastest-growing product categories, driven by pharmaceutical and electronics applications.
Regulatory frameworks from bodies like the U.S. Department of Transportation (DOT) and Europe's ECHA dictate performance standards and labeling protocols. Furthermore, ISO 16106 provides a global benchmark for the performance testing of dangerous goods packaging, influencing market access and product design. Supplier selection will increasingly hinge on a manufacturer's ability to provide packaging that is not only compliant but also optimized for sustainable material use and end-of-life recycling.
Market Dynamics
The hazmat packaging market is shaped by the persistent tension between the need for globally harmonized standards, such as GHS, and the proliferation of stringent, region-specific regulations like the EU's REACH. This dynamic is forcing manufacturers to engineer products that meet a complex matrix of overlapping compliance requirements.
Growth Catalysts
- GHS Harmonization:The ongoing global adoption of the Globally Harmonized System of Classification and Labelling of Chemicals mandates standardized hazard communication, compelling chemical producers to procure compliant packaging solutions for international trade.
- Pharmaceutical Sector Demand:Expansion in biologics and active pharmaceutical ingredients (APIs) requires specialized, temperature-controlled, and impact-resistant packaging to ensure product integrity and safety during transit, stimulating demand for high-performance containers.
- Industrial Activity in China:The scale of China's chemical and battery manufacturing sectors concentrates procurement for bulk containers, particularly steel drums and intermediate bulk containers (IBCs), to support domestic production and export volumes.
Market Restraints
- Raw Material Price Volatility:Fluctuations in the price of steel and high-density polyethylene (HDPE) resins, primary inputs for drums and plastic containers, directly impact manufacturer cost structures and create pricing instability for end-users.
- Substitution from Reconditioned Packaging:The growing market for reconditioned and refurbished drums and IBCs presents a lower-cost alternative to new packaging, potentially capping demand and compressing margins for manufacturers of new units.
- Complex Certification Processes:Securing UN certifications for new packaging designs is a costly and time-consuming process involving rigorous testing, which can act as a significant barrier to entry for smaller firms and slow innovation.
Strategic Opportunities
- Sustainable Materials:There is a significant opportunity in developing and marketing packaging made from recycled content or bio-based polymers that still meets the rigorous performance and safety standards of hazmat transport regulations.
- Smart Packaging Integration:Incorporating sensors for temperature, shock, and location tracking into high-value packaging for pharmaceuticals and electronics chemicals offers a new value proposition centered on supply chain visibility and security.
- Emerging Geographic Markets:Manufacturing growth in Southeast Asia and India presents an opportunity for suppliers to establish local production or distribution to serve burgeoning chemical and pharmaceutical industries in those regions.
Industry Challenges
- End-of-Life Management:Managing the collection, cleaning, and disposal or recycling of used hazmat containers, particularly those that held highly toxic substances, poses a significant logistical and environmental challenge for the industry.
- Regulatory Divergence:Despite harmonization efforts, divergence in specific national regulations, such as those from the U.S. DOT and Europe's ECHA, requires manufacturers to maintain multiple product variants and complex compliance knowledge bases.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hazmat Packaging Market |
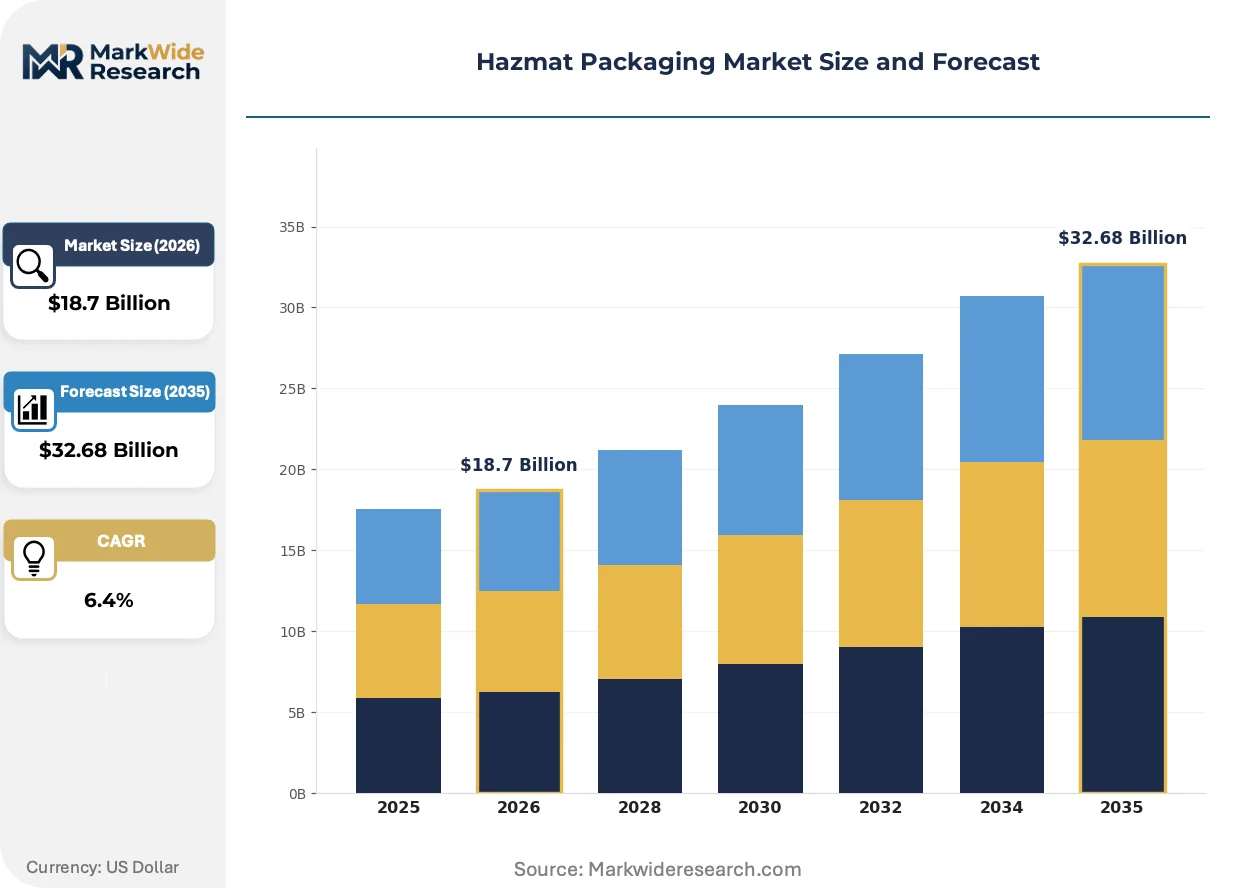
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $32.68 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Drums, Boxes, Bags, Bottles, Totes, Cylinders Material: Plastic, Steel, Fiberboard, Aluminum, Composite, Glass Application: Chemicals, Pharmaceuticals, Electronics Components, Aerospace, Laboratory Samples, Agriculture Ingredients End User: Manufacturers, Distributors, Laboratories, E-commerce Firms, Research Institutes, Wholesale Traders |
| Companies Covered | Greif, Inc., Mauser Group, Balmer Lawrie & Co. Ltd., Great Western Containers Inc., Peninsula Drums, Sicagen India Limited, Schütz GmbH & Co. KGaA, THIELMANN US LLC, Fibrestar Drums Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hazmat Packaging Market Strategic Shifts & Innovations
Material science advancements are intersecting with digital technologies to address dual pressures for enhanced safety and improved sustainability. This evolution is driven by regulatory mandates and a demand-side pull for greater transparency in the transport of hazardous goods, reshaping product design and service models.
Smart packaging technology integrates sensors and data loggers directly into containers and closures. The pharmaceutical and specialty chemical sectors are adopting these solutions for high-value, sensitive shipments to ensure chain of custody and monitor for excursions in temperature or pressure. This embedded sensing capability is converging with logistics software, enabling real-time alerts and creating a more transparent and secure supply chain for dangerous goods.
Europe's Circular Economy Action Plan, part of the EU Green Deal, is influencing packaging design far beyond its borders. The policy promotes waste reduction and reusability, compelling packaging manufacturers to innovate in closed-loop systems, reconditioning services, and materials that facilitate easier recycling. The composite IBC and steel drum segments are most affected, with leading suppliers investing heavily in networks to retrieve, refurbish, and redeploy used containers.
A significant shift in buyer behavior is the prioritization of a supplier's end-of-life service capabilities. Large-volume purchasers in the chemical industry are moving away from a purely transactional procurement model for containers. They now favor partnerships with suppliers who can provide a comprehensive "cradle-to-cradle" service, including container retrieval, reconditioning, and certified disposal, a trend most visible in North America and Europe.
Hazmat Packaging Market Segmentation
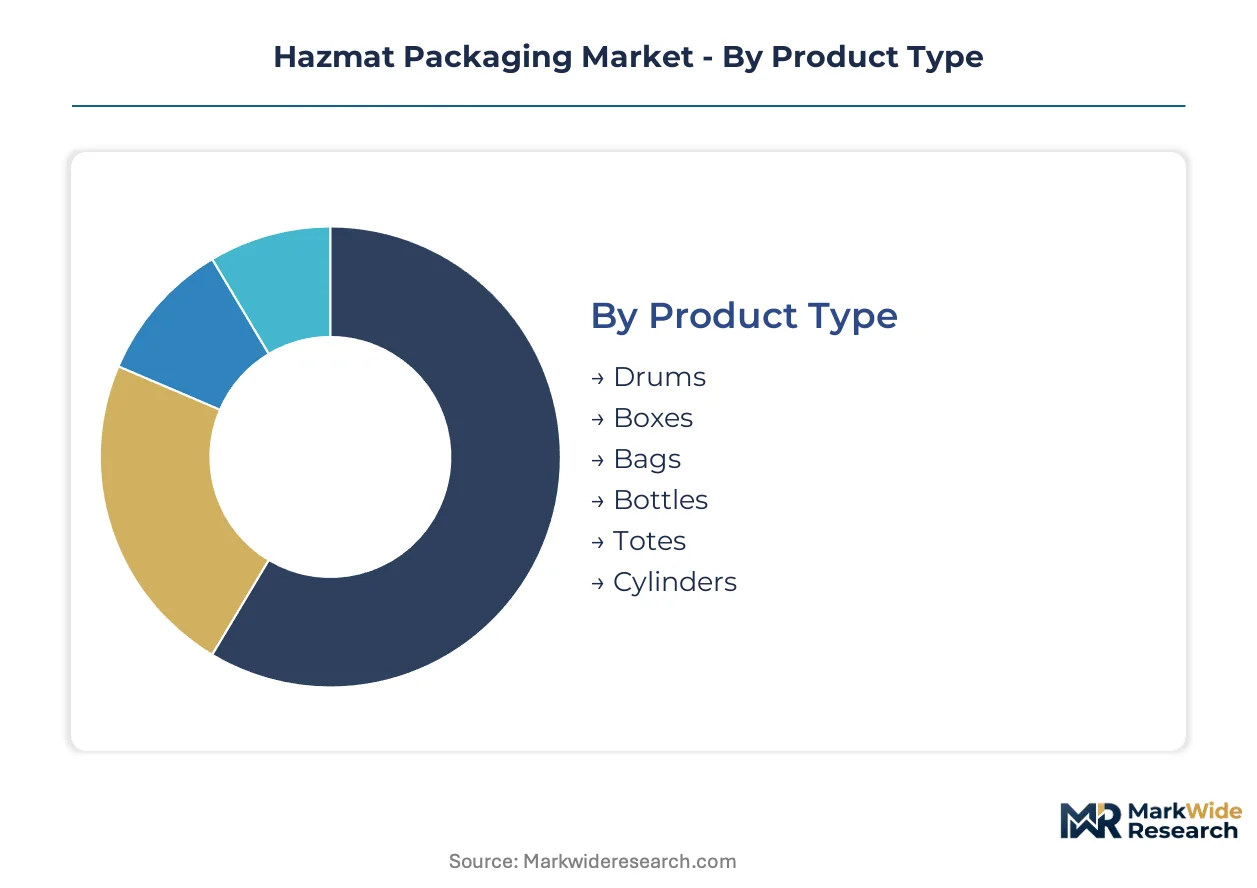
The hazmat packaging market segments by fundamental product characteristics, material composition, end-use application, and the customer type procuring these specialized containers. Understanding these distinctions helps manufacturers align product development with specific regulatory requirements and demand patterns across different hazardous goods categories.
Product Type:
Supply concentration in hazmat packaging often dictates the dominant product types, reflecting established supply chains for bulk hazardous materials.
- Drums:These cylindrical containers, typically made of steel or plastic, are engineered for the bulk transport of liquids, powders, and solids. Demand for drums is concentrated in industrial chemical manufacturing in China, supporting both domestic use and export volumes.
- Totes:Intermediate Bulk Containers (IBCs) are larger, often composite, containers designed for efficient handling and storage of bulk liquids or semi-solids. The pharmaceutical sector in Europe concentrates demand for reusable composite totes to transport active pharmaceutical ingredients safely.
- Boxes:These are typically fiberboard or wooden containers, often used as outer packaging for smaller inner receptacles containing hazardous substances.
- Bags:Flexible packaging solutions, usually woven polypropylene or multi-layer plastic, are used for bulk transport of dry hazardous goods like certain chemicals or fertilizers.
- Bottles:Smaller, rigid containers, often plastic or glass, are used for precise volumes of hazardous liquids, particularly in laboratory and pharmaceutical settings.
- Cylinders:High-pressure containers, usually steel or aluminum, are specifically designed for the transport of compressed, liquefied, or dissolved gases.
Drums absorb the bulk of installed capacity; composite totes are expanding most quickly.
Material:
Cost tiering significantly influences material selection in hazmat packaging, balancing performance requirements with economic considerations for manufacturers.
- Plastic:High-density polyethylene (HDPE) is a common material for drums, bottles, and IBCs, offering chemical resistance and lighter weight. The chemical industry in North America drives demand for plastic containers due to their versatility and lower cost.
- Steel:Robust and durable, steel is used for drums and cylinders, providing high strength for corrosive or flammable liquids and solids. Industrial manufacturing in Germany concentrates demand for steel drums for heavy-duty chemical transport.
- Fiberboard:Often used for outer packaging, fiberboard provides a cost-effective and lightweight solution for certain hazardous goods.
- Aluminum:Lighter than steel, aluminum is used for smaller containers and some gas cylinders where weight reduction is critical.
- Composite:These materials combine different layers or components, such as plastic liners with metal or fiberboard outer layers, for enhanced protection.
- Glass:Primarily used for laboratory samples and certain pharmaceutical products, glass offers excellent chemical inertness and barrier properties.
Steel containers anchor significant market volume; composite materials are climbing the fastest.
Application:
Application-specific demands shape hazmat packaging design, requiring tailored solutions for diverse hazardous material characteristics.
- Pharmaceuticals:This segment requires specialized, often temperature-controlled and tamper-evident packaging for active pharmaceutical ingredients and biologics. The biopharmaceutical sector in Switzerland concentrates demand for high-performance, validated packaging.
- Chemicals:Covering a broad range of industrial chemicals, this application demands robust containers resistant to corrosion, flammability, and reactivity. Bulk chemical producers in the United States drive demand for large-volume drums and IBCs.
- Electronics Components:Packaging for electronics components often involves electrostatic discharge protection and precise handling requirements for sensitive materials.
- Aerospace:This sector requires packaging for specialized fuels, lubricants, and hydraulic fluids, often with stringent temperature and pressure controls.
- Laboratory Samples:Small-volume, highly secure, and often temperature-controlled packaging is essential for biological and chemical laboratory samples.
- Agriculture Ingredients:Packaging for pesticides, herbicides, and fertilizers requires durability and chemical resistance for safe transport and storage.
Chemicals applications consume the largest share of packaging; pharmaceuticals are gaining share fastest.
End User:
Customer type influences procurement patterns and service requirements, with large-volume users often seeking comprehensive packaging solutions.
- Manufacturers:Chemical, pharmaceutical, and industrial manufacturers are primary end-users, requiring bulk packaging for their production processes and finished goods. Large chemical manufacturers in Japan frequently partner with suppliers for comprehensive packaging and recycling services.
- Laboratories:Research and testing laboratories require specialized small-volume packaging for samples, reagents, and hazardous waste. Academic and commercial laboratories in the United Kingdom concentrate demand for secure, certified laboratory sample containers.
- Distributors:These entities handle the logistics and storage of hazardous materials, necessitating compliant and efficient packaging for onward shipment.
- E-commerce Firms:Online retailers shipping hazardous consumer goods require packaging that meets regulations for parcel delivery.
- Research Institutes:Similar to laboratories, these organizations need specialized packaging for experimental materials and scientific samples.
- Wholesale Traders:These firms buy and sell hazardous materials in bulk, requiring standard industrial packaging for transport and storage.
Manufacturers represent the largest end-user segment; e-commerce firms are on the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand-side concentration for hazmat packaging is highly localized, driven by specific industrial activities and regulatory landscapes. This creates distinct regional requirements for container design and material science. Manufacturers must navigate a complex web of compliance across diverse markets.
China
Industrial activity in China's chemical and battery manufacturing sectors generates significant procurement for bulk containers. The GB standards for dangerous goods transport dictate specific packaging requirements for domestic and export markets. Production hubs in the Yangtze River Delta concentrate demand for steel drums and intermediate bulk containers.
United States
Bulk chemical producers in the United States drive substantial demand for large-volume drums and IBCs, particularly plastic containers. U.S. Department of Transportation (DOT) regulations mandate performance standards and labeling protocols for hazardous materials. Chemical manufacturing clusters in the Gulf Coast region require robust and compliant packaging solutions.
Germany
Industrial manufacturing in Germany concentrates demand for robust steel drums for heavy-duty chemical transport and specialized industrial fluids. Europe's ECHA and REACH regulations impose stringent material science and testing requirements on hazmat packaging. The Rhine-Ruhr area, a major industrial heartland, sees high demand for durable and certified containers.
Switzerland
The biopharmaceutical sector in Switzerland concentrates demand for high-performance, validated packaging for active pharmaceutical ingredients and biologics. Swissmedic guidelines for pharmaceutical transport necessitate specialized, temperature-controlled, and tamper-evident solutions. Research and development clusters around Basel and Zurich require small-volume, secure laboratory sample containers.
India
Emerging chemical and pharmaceutical industries in India are increasing demand for diverse hazmat packaging solutions, including composite totes and drums. The Bureau of Indian Standards (BIS) sets national standards for the safe transport of dangerous goods. Manufacturing zones in Gujarat and Maharashtra are expanding their procurement of compliant industrial packaging.
Hazmat Packaging Market Key Industry Players
European producers anchor one tier, emphasizing advanced material science and circular economy principles; North American specialists hold another, focusing on bulk volume and cost efficiency. The market exhibits a tiered structure with global conglomerates competing against regional specialists. Strategic archetypes include integrated packaging solutions providers and niche players focusing on specific hazardous goods categories. Portfolio diversification and geographic expansion are common competitive moves.
Within the integrated solutions tier, Greif, Inc. and Mauser Group exemplify global reach and broad product portfolios, spanning steel drums, plastic containers, and IBCs. These multinational corporations often leverage extensive manufacturing footprints to meet diverse regional compliance standards. Schütz GmbH & Co. KGaA, a German-based company, anchors the specialization in composite intermediate bulk containers, focusing on reusability and closed-loop systems. This segment of players represents the industry's drive towards comprehensive service offerings alongside product manufacturing, addressing both bulk and specialized transport needs.
| Leading Market Players |
|---|
| Greif, Inc. |
| Mauser Group |
| Balmer Lawrie & Co. Ltd. |
| Great Western Containers Inc. |
| Peninsula Drums |
| Sicagen India Limited |
| Schütz GmbH & Co. KGaA |
| THIELMANN US LLC |
| Fibrestar Drums Limited |
| Others |
Cost & Logistics Intelligence
Steel futures contracts directly influence the cost structure for hazmat packaging, cascading through the supply chain into tiered pricing for bulk industrial users and specialized applications. This dynamic creates persistent pressure on manufacturers to optimize material procurement and production efficiencies.
Pricing Analysis
Volume-based contracts dominate hazmat packaging procurement, impacting margins for manufacturers of standard containers. Price differentiation stems from UN certification levels and the provision of comprehensive after-sales services like reconditioning. Pricing softness runs through the market, driven by the availability of lower-cost reconditioned packaging alternatives. Bulk chemical manufacturers exhibit high price sensitivity for standard drums, while pharmaceutical and laboratory sectors prioritize performance and certification over cost for specialized containers.
Supply Chain Analysis
Reverse logistics for hazmat containers, including retrieval, cleaning, and reconditioning, form a critical part of the supply chain, particularly for steel drums and composite IBCs. Geographic supply concentration for raw materials relies heavily on China for chemical manufacturing inputs and global markets for HDPE resins. Raw material price volatility represents a structural supply chain risk for packaging producers. Distribution runs through a network of direct sales from manufacturers and specialized industrial distributors serving regional markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The hazmat packaging market is witnessing a vertical-integration race, with suppliers increasingly pursuing end-of-life service capabilities to offer comprehensive cradle-to-cradle solutions.
For Market Incumbents: Acquire specialized reconditioning networks to expand comprehensive cradle-to-cradle service offerings, mitigating the threat from reconditioned packaging. Invest in advanced material science R&D for bio-based polymers, aligning with evolving European circular economy regulations. Expand global compliance expertise for diverse regional standards like GB in China, strengthening market access. Focus on strategic partnerships with large chemical and pharmaceutical manufacturers to secure long-term supply agreements.
For New Entrants and Emerging Players: Begin with smart packaging solutions for high-value pharmaceuticals, addressing the need for enhanced supply chain visibility and security. Target specialized laboratory sample containers, a segment with high growth and less price sensitivity. Focus initial market entry on emerging geographic markets like India, leveraging burgeoning chemical and pharmaceutical industries. Develop niche expertise in specific hazardous goods categories to gain initial market traction.
For Investors and Strategic Acquirers: Distressed-cycle entries favor specialized material science firms in Europe, particularly those focused on bio-based polymers and circular economy principles. The persistent demand for safe hazardous material transport ensures long-term viability for well-positioned packaging providers. Acquisition targets should include companies with robust UN certification portfolios or established reconditioning infrastructure. Monitor the adoption rates of smart packaging technologies as an inflection indicator for future growth opportunities.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion in Southeast Asia | Supports burgeoning chemical and pharmaceutical industries in the region. |
| Green Manufacturing Transition | Addresses EU Green Deal mandates and buyer demand for sustainable solutions. |
| Long-term Supply Agreement with Pharma | Secures stable demand for high-performance, validated packaging solutions. |
| Product Launch: Smart IBCs | Enhances supply chain visibility and security for sensitive, high-value shipments. |
| Strategic Partnership for Reconditioning | Establishes closed-loop systems, meeting end-of-life management challenges. |
Research Approach
Document review covered U.S. Department of Transportation regulations, Europe's ECHA guidelines, and ISO 16106 standards, complemented by interviews with hazmat packaging manufacturers, chemical industry procurement leads, pharmaceutical logistics managers, and regulatory compliance officers. This primary research was triangulated with secondary data from customs/trade data and industry association reports. A robust bottom-up and top-down approach ensured comprehensive market sizing and validation.
Cross-referencing historical market data with expert panel input informs the hazmat packaging market forecast across the analysis window. The analytical framework modeled segmentation dimensions including product type, material composition, end-use application, and customer type, alongside regional regulatory frameworks. Compound annual growth rates were derived through statistical modeling and expert consensus, using key inputs like global chemical production volumes and pharmaceutical R&D pipelines.
Underlying measurement precision varies by segment; bulk chemical drums carry tighter precision than specialized laboratory samples. Forecasts reflect assumptions regarding raw material price stability and regulatory evolution. Practitioners should monitor geopolitical shifts impacting trade and rapid regulatory changes for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Heavy Duty Packaging
Heavy-Duty Corrugated Boxes Market
Heavy Duty Packaging
High-Stress PCR HDPE Detergent Bottles Market
Heavy Duty Packaging
High Impact Corrugated Boxes Market
Heavy Duty Packaging
High-Density Packaging Market
Heavy Duty Packaging
Global Heavy Duty Bags and Sacks Market
Heavy Duty Packaging
Hazardous Goods Packaging Market
Heavy Duty Packaging
Europe High Density Polyethylene Jerrycan Market
Heavy Duty Packaging
Heavy Duty Paper Tags Market
Heavy Duty Packaging
Heavy-Duty Paper and Multiwall Shipping Sack Market
Heavy Duty Packaging
Large Blow Molded Products Market
Heavy Duty Packaging
Heavy Duty Bins Market
Heavy Duty Packaging
Heavy Duty Corrugated Packaging Market