
 Heavy-Duty Corrugated Boxes Market | 2026-2036
Heavy-Duty Corrugated Boxes Market Size, Share, and Industry Trends Forecast 2026-2036
Heavy-Duty Corrugated Boxes Market Foresight
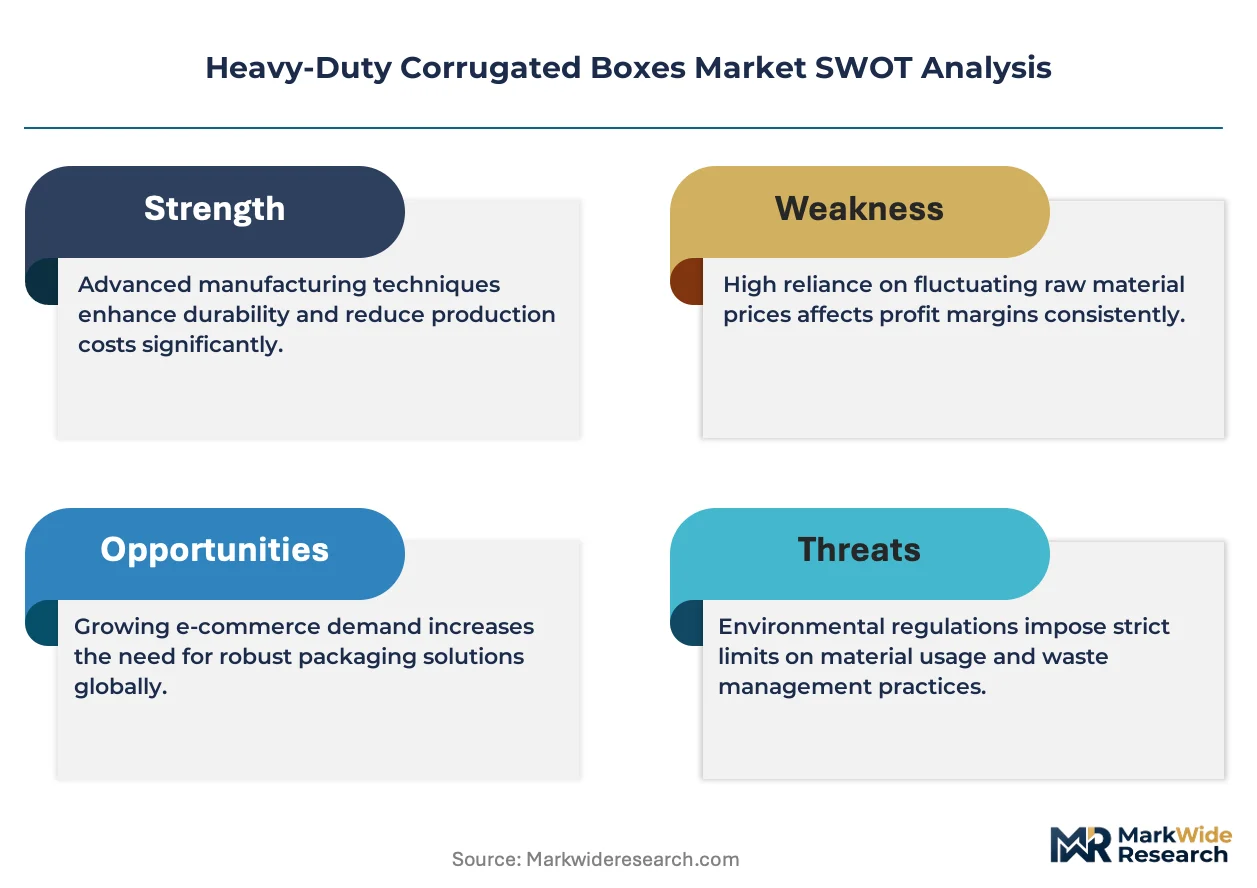
India's containerboard capacity build-out is fragmenting the Asia-Pacific supplier base. International Paper Company leverages its integrated pulp-to-box infrastructure across North American mills. Smurfit WestRock anchors European production through recycled fiber networks. Mondi Group specializes in high-performance kraftliner grades for heavy-load applications.
Heavy-duty corrugated boxes are multi-layered fiberboard containers engineered with burst strengths exceeding 200 psi and edge crush tests above 50 lb/in, manufactured through steam-fluted corrugation and adhesive-bonded lamination to protect dense or fragile goods during extended supply chain transit. Double wall constructions dominate industrial packaging for machinery and automotive parts due to superior stacking strength and puncture resistance. E-commerce end use represents the fastest-expanding segment as fulfillment centers require damage-resistant shipping solutions for bulky consumer durables. Custom sizing commands premium positioning among electronics manufacturers seeking exact-fit protective geometries.
EPA guidelines govern recycled content thresholds in US corrugated production, while the EU Packaging and Packaging Waste Regulation mandates extended producer responsibility for end-of-life recovery. India's BIS certification requirements for packaging materials are tightening quality benchmarks for export-bound containerboard. Stakeholders must monitor how regulatory shifts toward mono-material recyclability reshape adhesive and coating specifications across major manufacturing jurisdictions.
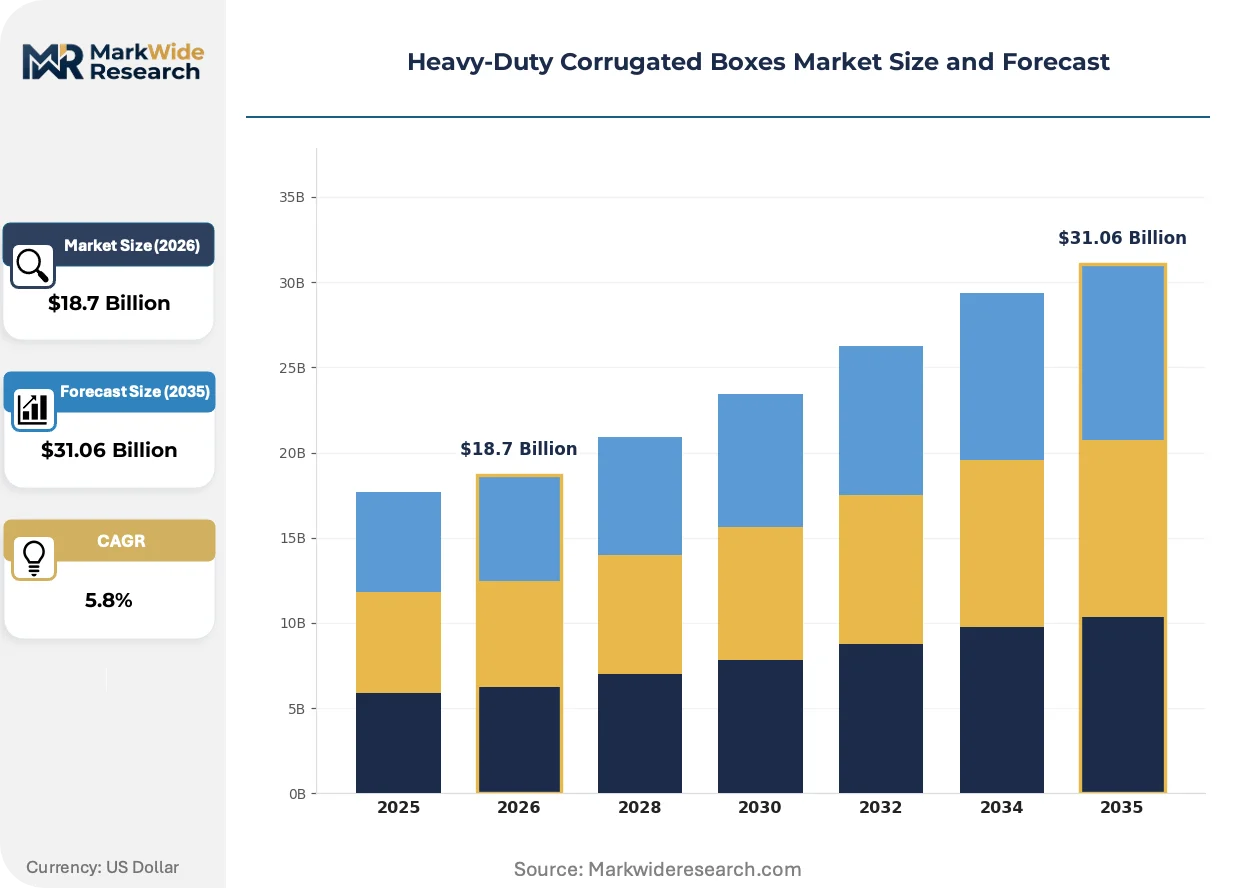
Market Dynamics
E-commerce fulfillment networks are compressing damage-tolerance specifications while the EU Packaging and Packaging Waste Regulation tightens recyclability mandates, forcing simultaneous performance upgrades and material redesign across the corrugated supply base.
Growth Catalysts
- E-commerce logistics expansion:Fulfillment centers handling bulky consumer durables now mandate burst strengths above 200 psi, pulling double-wall constructions into standard specifications for electronics and furniture shipments.
- REACH chemical restrictions:EU adhesive formulations are pivoting toward starch-based bonding agents that maintain lamination integrity without compromising mono-material recyclability targets.
- Germany's industrial corridor:Automotive and machinery OEMs in Baden-Württemberg and Bavaria are consolidating packaging procurement around heavy-duty grades for export-bound component kits.
Market Restraints
- Recycled fiber cost volatility:Old corrugated containerboard pricing swings in North American spot markets compress margin predictability for independent converters lacking integrated pulp supply.
- Kraftliner supply concentration:High-performance virgin liner production clusters in Scandinavian pulp mills, exposing downstream box plants to freight cost spikes and currency exposure.
- Plastic crate substitution:Returnable plastic packaging systems are capturing closed-loop automotive logistics routes, displacing single-trip corrugated for high-frequency parts movements.
Strategic Opportunities
- India's export packaging gap:BIS certification requirements for containerboard quality are creating tiered supplier accreditation that rewards integrated pulp-to-box investments serving pharmaceutical and textile exporters.
- Digital print integration:Direct-to-board inkjet systems are converging with variable-data cutting tables, enabling lot-size-one production for seasonal promotional packaging without plate changeover costs.
- Extended producer responsibility tailwinds:EU member state implementation of the Packaging and Packaging Waste Regulation is mandating producer-funded collection infrastructure that favors established corrugated recyclers with scale.
Industry Challenges
- Fluting technician scarcity:Steam-corrugation line operators with precision calibration skills are retiring faster than vocational programs in Poland and the Czech Republic can replenish qualified labor pools.
- Legacy ERP integration friction:Real-time moisture sensors and automated stacker controls require middleware bridges to decade-old manufacturing execution systems common in mid-tier European box plants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Heavy-Duty Corrugated Boxes Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $31.06 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single Wall, Double Wall, Triple Wall, Die-Cut End Use: Industrial Packaging, E-Commerce, Food & Beverage, Electronics Size: Small, Medium, Large, Custom Distribution Channel: Direct Sales, Online Retail, Distributors, wholesalers |
| Companies Covered | International Paper Company, Smurfit WestRock, Mondi Group, WestRock Company, DS Smith Packaging Limited, Packaging Corporation of America, Georgia Pacific LLC, Smurfit Kappa Group Plc, Pratt Industries Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Heavy-Duty Corrugated Boxes Market Shifts & Advancements
Material science advances and regulatory chemistry constraints are rewriting specification sheets faster than procurement cycles can absorb, compressing the window between pilot validation and scaled deployment.
High-modulus fluting mediums derived from agricultural residues are collapsing the virgin-recycled performance gap in edge crush tests. German appliance manufacturers are qualifying these grades for washing machine packaging within eighteen-month validation windows. The technology is collapsing premium pricing tiers that historically separated kraftliner-reinforced boxes from recycled-content alternatives.
REACH Annex XVII restrictions on formaldehyde-releasing adhesives are forcing reformulation of starch-based bonding systems used in triple-wall constructions. Industrial packaging converters serving French automotive suppliers are accelerating water-resistant additive testing to maintain wet-strength specifications. Heavy-duty grades for outdoor machinery storage face the steepest compliance timelines as ECHA enforcement intensifies.
Consolidated procurement desks at multinational electronics retailers are unbundling protective packaging from freight contracts, shifting vendor selection toward ISO 9001-certified converters with direct-to-DC fulfillment capability. Tier-one suppliers in China's Pearl River Delta are absorbing design-for-shipping responsibilities previously held by brand logistics teams. This concentration is most visible in television and white-goods categories where damage claims now route directly to box manufacturers rather than freight carriers.
Heavy-Duty Corrugated Boxes Market Segmentation
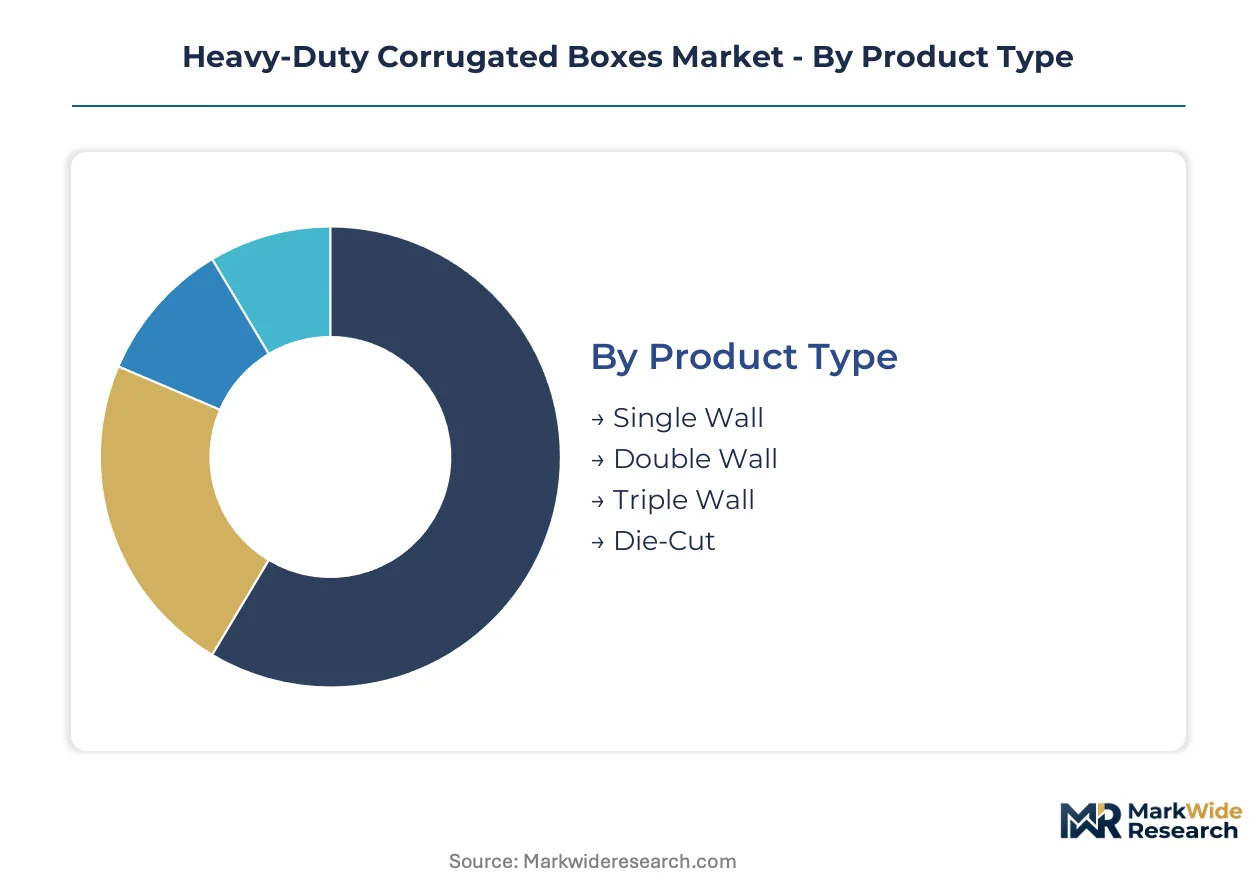
Heavy-duty corrugated boxes segment across structural specifications, end-use performance requirements, and procurement pathways. Each dimension carries distinct margin profiles and technical certification thresholds that shape vendor selection.
Product Type:
Mature double-wall constructions dominate industrial procurement while emerging fluting technologies reshape single-wall performance benchmarks.
- Double Wall:Two corrugated mediums laminated between three linerboards deliver burst strengths exceeding 200 psi and edge crush resistance above 50 lb/in. German automotive OEMs in Baden-Württemberg specify these grades for export-bound powertrain components where stacking loads exceed 500 kg.
- Triple Wall:Three fluted layers bonded with starch-based adhesives create the highest load-bearing capacity in fiberboard packaging. REACH Annex XVII restrictions on formaldehyde-releasing bonding agents are forcing reformulation timelines for French industrial converters serving outdoor machinery storage applications.
- Single Wall:Standard A-flute or C-flute constructions serve lightweight protective applications with cost advantages in high-volume consumer goods.
- Die-Cut:Precision-cut formats with integrated handles and display features address retail-ready packaging requirements for electronics and promotional shipments.
Double Wall retains volume leadership; Die-Cut holds the steepest expansion curve.
End Use:
Application-driven specifications diverge sharply between damage-tolerance mandates in e-commerce fulfillment and chemical-resistance requirements in food-contact packaging.
- E-Commerce:Fulfillment centers handling bulky consumer durables now mandate burst strengths above 200 psi as standard specifications. Electronics retailers with consolidated procurement desks are unbundling protective packaging from freight contracts, routing damage claims directly to ISO 9001-certified converters.
- Industrial Packaging:Machinery and automotive parts shipments require superior puncture resistance and moisture-barrier properties for extended supply chain transit. India's BIS certification requirements for containerboard quality are creating tiered supplier accreditation for pharmaceutical and textile exporters.
- Food & Beverage:Direct-contact grades must satisfy FDA thresholds for recycled content and EU food-grade migration limits on coatings and adhesives.
- Electronics:Exact-fit protective geometries with anti-static liners command premium positioning among semiconductor and display manufacturers.
Industrial Packaging retains volume leadership; E-Commerce is climbing the fastest.
Size:
Customer procurement patterns split between standardized volume tiers and engineered custom formats with extended design validation cycles.
- Custom:Variable-dimension cutting tables integrated with direct-to-board inkjet systems enable lot-size-one production without plate changeover costs. Seasonal promotional packaging for white-goods manufacturers in China's Pearl River Delta absorbs design-for-shipping responsibilities previously held by brand logistics teams.
- Large:Refrigerator and washing machine packaging requires reinforced corner posts and pallet-compatible footprints for automated warehouse handling.
- Medium:Standardized footprints for consumer electronics and mid-sized appliances optimize truckload cube utilization.
- Small:Compact formats for component kits and spare parts leverage high-volume throughput with minimal material waste.
Large retains volume leadership; Custom is gaining share fastest.
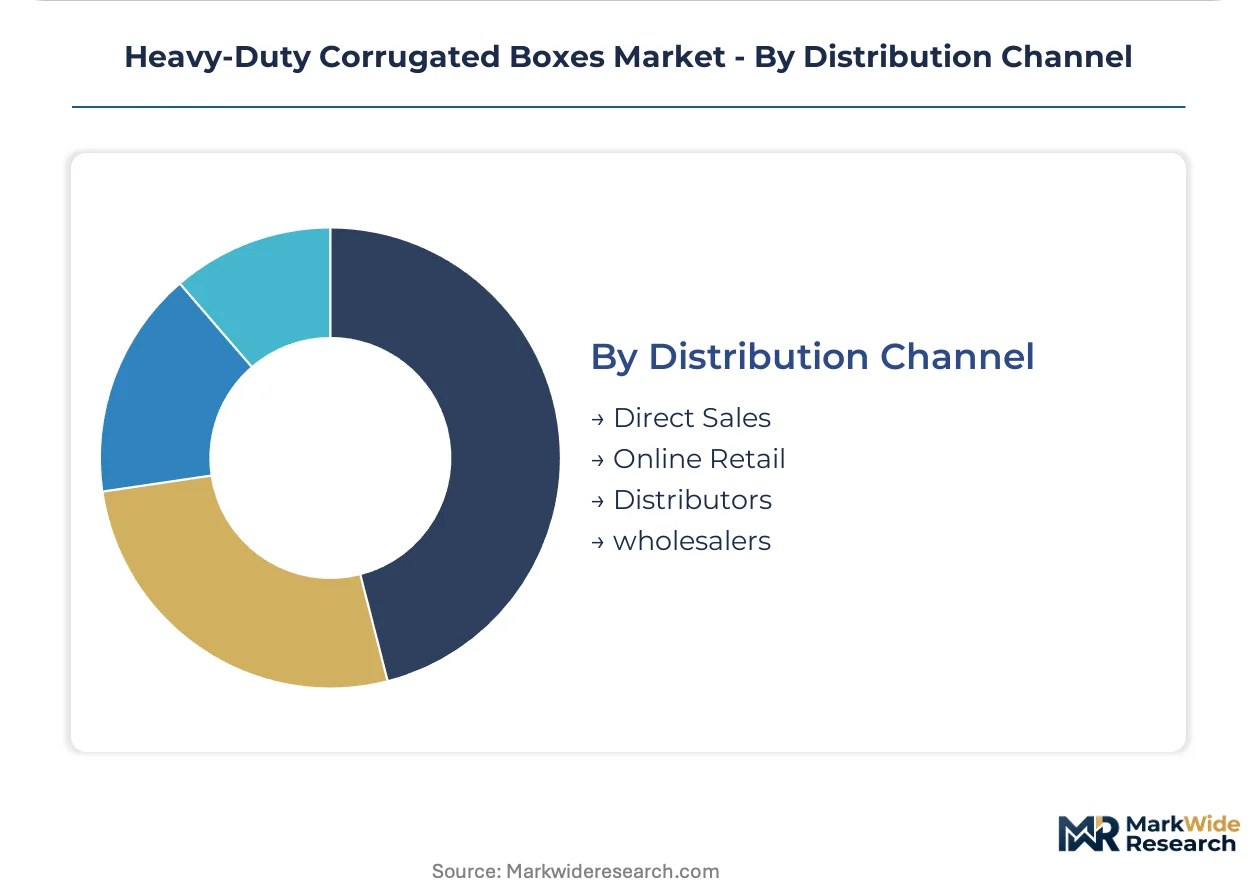
Distribution Channel:
Channel selection reflects order scale, technical service requirements, and geographic proximity to converting capacity.
- Direct Sales:National account relationships with multinational electronics retailers and automotive OEMs provide design engineering support and direct-to-DC fulfillment capability. Consolidated procurement desks favor ISO 9001-certified converters with integrated moisture sensors and automated stacker controls.
- Distributors:Regional inventory positioning serves mid-tier box plants and independent converters lacking integrated pulp supply.
- Online Retail:Digital platforms aggregate spot purchases for standardized grades with transparent pricing and rapid turnaround.
- Wholesalers:Volume aggregation for commodity single-wall and double-wall constructions serves packaging resellers and smaller fulfillment operations.
Direct Sales retains volume leadership; Online Retail holds the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EPA guidelines govern recycled content thresholds in US corrugated production while the EU Packaging and Packaging Waste Regulation mandates extended producer responsibility for end-of-life recovery. Demand concentrates in Germany's industrial manufacturing corridor and India's export packaging build-out.
United States
Fulfillment centers handling bulky consumer durables now mandate burst strengths above 200 psi as standard specifications. EPA guidelines govern recycled content thresholds in corrugated production, compressing margin predictability for independent converters lacking integrated pulp supply. The Southeast manufacturing belt anchors containerboard capacity expansion serving e-commerce logistics networks.
Germany
Automotive and machinery OEMs in Baden-Württemberg and Bavaria consolidate packaging procurement around heavy-duty grades for export-bound component kits. REACH Annex XVII restrictions on formaldehyde-releasing adhesives force reformulation timelines for starch-based bonding systems. The industrial corridor around Stuttgart and Munich drives premium-grade demand for powertrain packaging with stacking loads exceeding 500 kg.
India
BIS certification requirements for containerboard quality create tiered supplier accreditation rewarding integrated pulp-to-box investments. The country's national packaging regulator tightens quality benchmarks for export-bound containerboard serving pharmaceutical and textile exporters. Maharashtra and Gujarat host capacity build-outs fragmenting the Asia-Pacific supplier base for heavy-load applications.
China
Tier-one suppliers in the Pearl River Delta absorb design-for-shipping responsibilities previously held by brand logistics teams. The country's national standards body governs quality benchmarks for containerboard used in electronics and white-goods export packaging. Guangdong Province anchors television and appliance packaging demand where damage claims route directly to box manufacturers.
Heavy-Duty Corrugated Boxes Market Competitive Landscape
Integrated pulp-to-box operators and recycled fiber specialists split the market between captive supply chains and circular material networks. The structure favors scale players with backward integration into kraftliner production alongside regional converters serving niche custom specifications. Two dominant competitive moves define positioning: capacity consolidation through mill acquisitions and geographic expansion into India's export packaging corridor.
Among North American integrated producers, International Paper Company and Packaging Corporation of America exemplify the captive-supply archetype with mill networks spanning pulp through finished box production. Smurfit WestRock and Mondi Group represent the European recycled-fiber model, anchoring circular production systems across continental converting footprints. These four operators occupy positions that determine pricing benchmarks for burst-strength specifications above 200 psi.
| Leading Market Players |
|---|
| International Paper Company |
| Smurfit WestRock |
| Mondi Group |
| WestRock Company |
| DS Smith Packaging Limited |
| Packaging Corporation of America |
| Georgia Pacific LLC |
| Smurfit Kappa Group Plc |
| Pratt Industries Inc. |
| Others |
Supply & Pricing Matrix
Overcapacity in India's containerboard build-out compresses pricing power for export-grade kraftliner while tightening quality spreads between integrated and non-integrated suppliers across the Asia-Pacific corridor.
Pricing Analysis
Scandinavian virgin linerboard commands a 15-20% premium over recycled-content alternatives in German automotive procurement, though high-modulus agricultural-fluting grades are collapsing this spread. Three-tier pricing structure across premium kraftliner-reinforced, standard double-wall recycled, and economy single-wall grades stratifies by burst-strength certification and ISO 9001 compliance. Price erosion runs through the standard tier as Indian capacity floods spot markets with BIS-accredited containerboard. Small fulfillment operators show highest price sensitivity; German OEMs with consolidated procurement desks prioritize damage-tolerance specifications over unit cost.
Supply Chain Analysis
Tariff exposure between the United States and Canadian pulp suppliers dominates raw material cost volatility for North American converters lacking backward integration. Kraftliner production clusters in Sweden, Finland, and the United States; recycled fiber networks anchor European and Indian supply. The supply chain draws from old corrugated containerboard spot markets, virgin pulp from Scandinavian mills, and starch-based adhesives subject to REACH Annex XVII restrictions. Single-source vulnerability concentrates in high-performance virgin liner supply. Distribution runs through direct national accounts for automotive and electronics OEMs, regional distributors for mid-tier converters, and digital platforms for standardized spot purchases.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Heavy-duty corrugated boxes sit in early-cycle expansion as e-commerce fulfillment networks re-specify damage-tolerance standards and EU recyclability mandates force simultaneous performance upgrades and material redesign.
For Market Incumbents: Harden quality-certification moats around BIS and ISO 9001 accreditations to lock in pharmaceutical and automotive export contracts. Deepen backward integration into kraftliner production or captive pulp supply to insulate margins from Old Corrugated Containerboard price swings. Add moisture-sensor and automated-stacker capacity in Germany's industrial corridor to meet consolidated procurement desk requirements for direct-to-DC fulfillment. For New Entrants and Emerging Players: India's Maharashtra and Gujarat export packaging corridor offers the most penetrable white-space as BIS tiered accreditation fragments incumbent supplier relationships. Target pharmaceutical and textile exporters with integrated pulp-to-box investments that shortcut legacy quality validation cycles. Lead with digital print integration and variable-data cutting tables to capture seasonal promotional packaging demand from China's Pearl River Delta white-goods manufacturers. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among integrated pulp-to-box operators with captive kraftliner supply and long-term automotive OEM contracts. Five-to-ten-year viability favors scale players with backward integration into virgin liner production and established EU extended producer responsibility collection infrastructure. Watch for REACH adhesive reformulation compliance failures as an inflection signal for distressed acquisition opportunities among French and German industrial converters.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Kraftliner Production | Captive virgin liner supply insulates margin from OCC spot volatility and Scandinavian freight cost spikes. |
| Digital Print and Variable-Data Cutting Integration | Direct-to-board inkjet systems enable lot-size-one production without plate changeover costs for seasonal promotional packaging. |
| BIS and ISO 9001 Certification Investment | Tiered accreditation unlocks pharmaceutical and automotive export contracts in India's fragmented supplier base. |
| REACH-Compliant Adhesive Reformulation | Starch-based bonding systems without formaldehyde-releasing agents maintain wet-strength specifications under ECHA enforcement. |
| Direct-to-DC Fulfillment Capability | Automated stacker controls and real-time moisture sensors satisfy consolidated procurement desk requirements at multinational electronics retailers. |
Research Methodology
Cross-validation between primary interviews with corrugated plant managers, automotive procurement leads, e-commerce fulfillment directors, and adhesive R&D specialists and secondary validation through SEC filings of integrated paper companies, EPA recycled content guidelines, and EU Packaging and Packaging Waste Regulation implementation documents anchors the qualitative findings. Customs data on containerboard trade flows, BIS certification registries, and REACH Annex XVII restriction timelines provided supply-side calibration. Bottom-up shipment data from converting capacity and top-down demand modeling from end-use industries were triangulated.
Calibration against historical capacity utilization rates, OCC price volatility patterns, and automotive OEM packaging procurement cycles shaped the analytical framework across the analysis window. Segmentation dimensions modeled include product type (double wall, triple wall, single wall, die-cut), end use (e-commerce, industrial packaging, food and beverage, electronics), size tier (custom, large, medium, small), and distribution channel (direct sales, distributors, online retail, wholesalers). CAGRs were derived from regression analysis against e-commerce logistics expansion rates and REACH regulatory compliance timelines. Forecast inputs incorporated fluting technician labor availability in Poland and the Czech Republic and kraftliner freight cost sensitivity to Scandinavian pulp mill capacity.
The forecast holds incumbent behavior within observed patterns; aggressive capacity additions by Indian integrated producers or accelerated REACH enforcement timelines would shift outcomes. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Heavy Duty Packaging
Heavy Duty Corrugated Packaging Market
Heavy Duty Packaging
Large Blow Molded Products Market
Heavy Duty Packaging
High-Density Packaging Market
Heavy Duty Packaging
Heavy-Duty Paper and Multiwall Shipping Sack Market
Heavy Duty Packaging
High-Stress PCR HDPE Detergent Bottles Market
Heavy Duty Packaging
Heavy Duty Bins Market
Heavy Duty Packaging
High Impact Corrugated Boxes Market
Heavy Duty Packaging
Heavy Duty Paper Tags Market
Heavy Duty Packaging
Europe High Density Polyethylene Jerrycan Market
Heavy Duty Packaging
Hazardous Goods Packaging Market
Heavy Duty Packaging
Global Heavy Duty Bags and Sacks Market
Heavy Duty Packaging
Hazmat Packaging Market