
 High-Density Packaging Market | 2026-2036
High-Density Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
High-Density Packaging Market Analysis
Modularization of chiplet-based system architectures is decoupling memory from logic in high-performance computing designs. TSMC sustains process leadership through its CoWoS and InFO packaging platforms, while ASE Technology Holding Co., Ltd. anchors backend assembly capacity across multiple fabs in Taiwan and China. Samsung Group differentiates by integrating advanced memory packaging with its own logic foundry services, creating captive demand for HBM stacks.
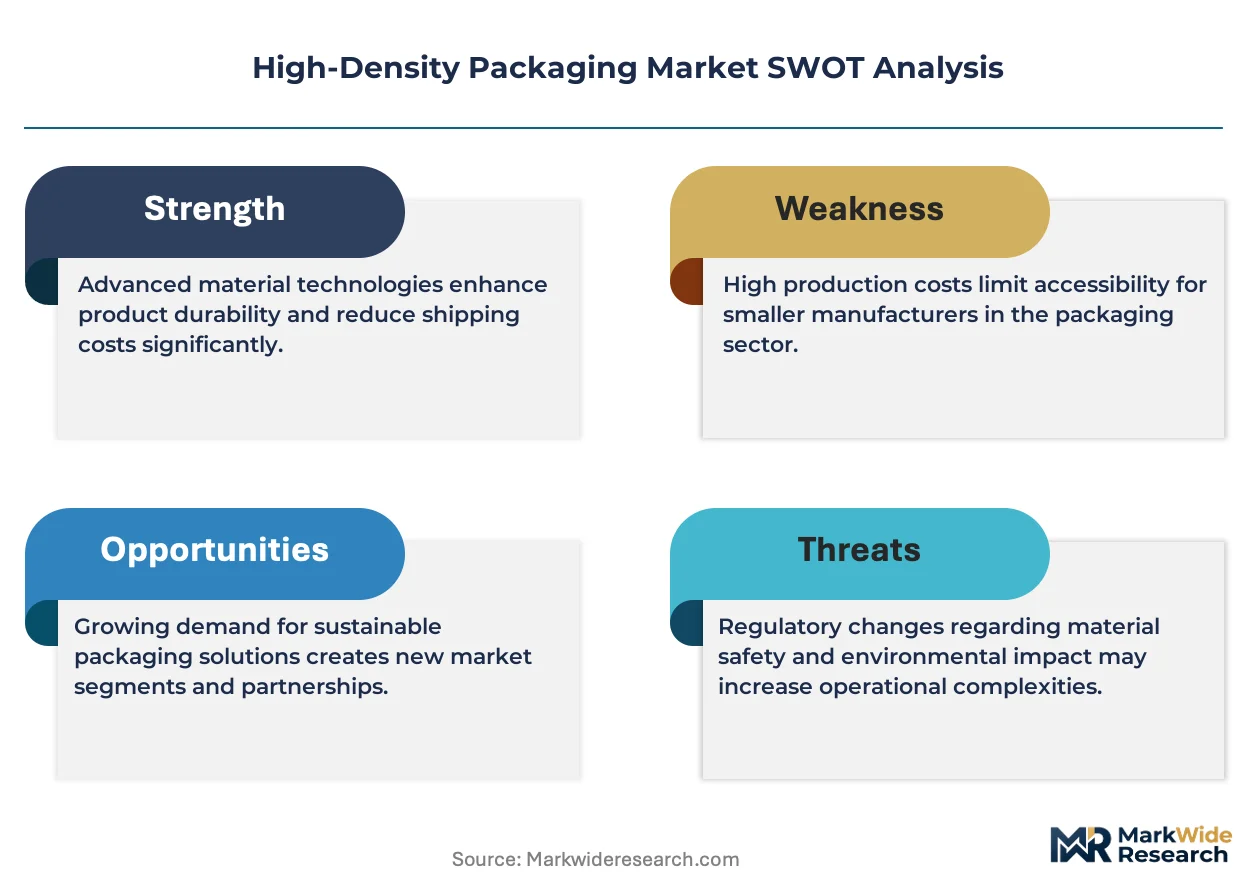
High-density packaging refers to semiconductor and electronic component configurations that maximize interconnect density per unit area, typically achieving line widths below 10 micrometers and via densities exceeding 10,000 per square centimeter for fan-out and 2.5D/3D integration schemes. These configurations enable higher I/O counts, reduced signal path lengths, and improved thermal management for processors, memory modules, and RF devices in space-constrained applications. Protective packaging for bare die and interposers commands premium margins due to cleanliness requirements and low-k dielectric fragility, while flexible packaging formats for wearable sensors represent the fastest-expanding demand pool as substrate thinning techniques mature. Rigid packaging for automotive ADAS modules maintains stable volume but faces margin compression from qualification-intensive reliability testing.
The EPA regulates per- and polyfluoroalkyl substance emissions in US semiconductor fabrication, pushing packagers toward fluorine-free mold compounds, while REACH restrictions in Europe constrain halogenated flame retardant use in substrate laminates. Japan's METI coordinates domestic supply chain resilience programs that subsidize advanced packaging equipment procurement, indirectly shaping competitive access for foreign substrate vendors. Stakeholders must monitor how divergent chemical safety regimes fragment material qualification requirements across major demand centers.
Market Dynamics
Chiplet disaggregation is fragmenting monolithic silicon into specialized tiles, forcing substrate vendors to rearchitect interposer designs around heterogeneous integration requirements rather than homogeneous scaling. This structural shift concentrates procurement leverage with advanced packaging foundries capable of hybrid bonding and through-silicon via fabrication.
Growth Catalysts
- 5G Modem Specifications:Consumer electronics brands now mandate fan-out wafer-level packaging for 5G chipsets, concentrating orders in East Asian packaging foundries with proven high-volume yield.
- EU REACH Restrictions:Halogenated flame retardant bans in substrate laminates are accelerating bio-based epoxy resin qualification cycles among material suppliers.
- HBM Stack Demand:High-bandwidth memory integration with logic dies is pulling advanced substrate capacity expansion in Taiwan and South Korea.
Market Restraints
- Low-K Dielectric Fragility:Protective packaging for bare die and interposers commands premium margins due to cleanliness requirements and mechanical sensitivity during assembly.
- East Asian Supply Concentration:Backend assembly capacity clusters in Taiwan and China create geographic risk exposure for fabless semiconductor designers.
- Fluorine Compound Transition Costs:EPA regulations on per- and polyfluoroalkyl substances push mold compound reformulation, extending material qualification timelines.
Strategic Opportunities
- Wearable Sensor Formats:Flexible packaging for health-monitoring devices represents expanding demand as substrate thinning techniques mature.
- Automotive ADAS Modules:Rigid packaging for driver-assistance systems maintains stable volume despite margin compression from reliability testing requirements.
- Japan METI Subsidies:Domestic supply chain resilience programs subsidize advanced packaging equipment procurement, indirectly shaping competitive access for foreign substrate vendors.
Industry Challenges
- Hybrid Bonding Expertise Scarcity:Chiplet-based architectures require specialized process engineers capable of sub-micron alignment and thermal compression bonding.
- Divergent Chemical Safety Regimes:Fragmented material qualification requirements across EPA, REACH, and METI jurisdictions multiply compliance documentation burdens.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | High-Density Packaging Market |
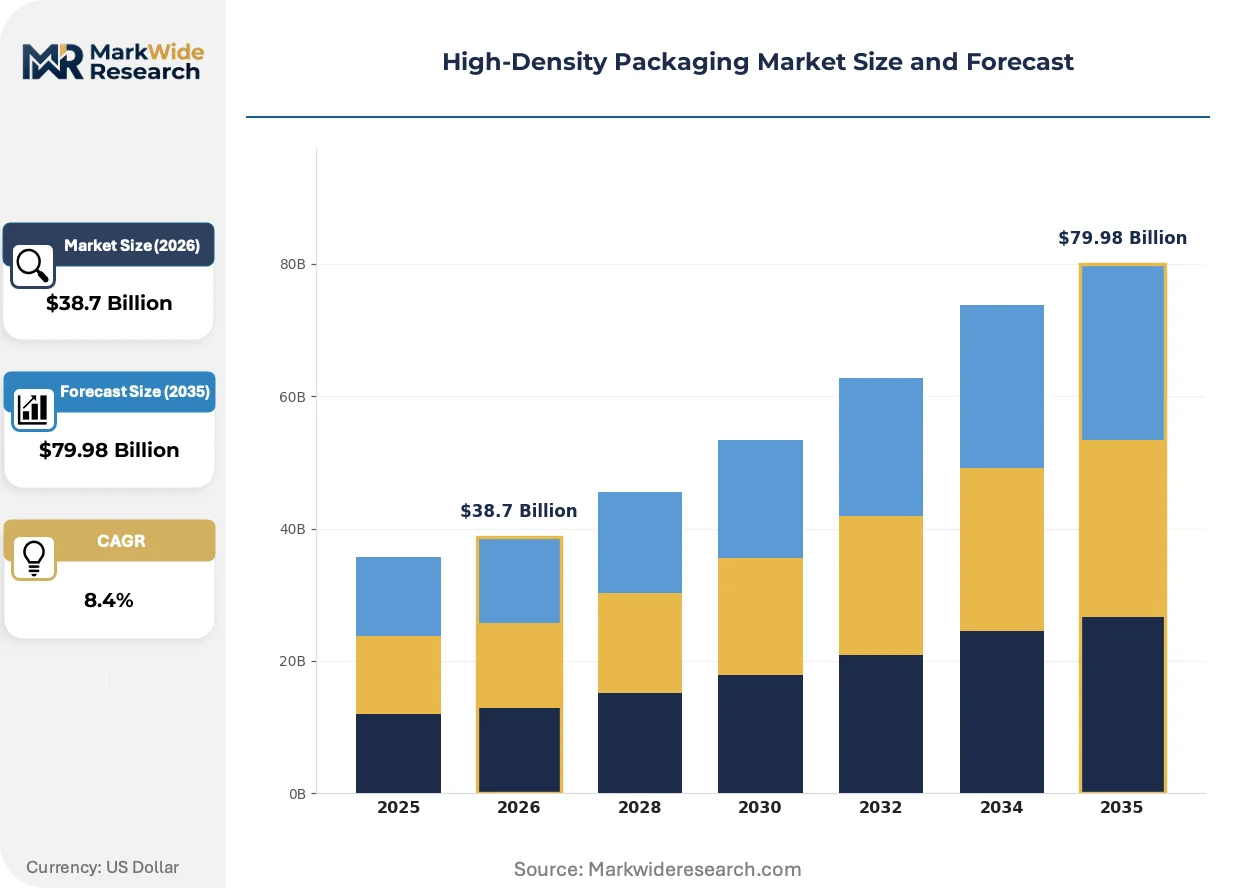
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $79.98 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Protective Packaging, Flexible Packaging, Rigid Packaging, Bulk Packaging Material: Plastic, Metal, Glass, Composite End User: Food & Beverage, Consumer Electronics, Pharmaceuticals, Cosmetics Distribution Channel: Online, Retail, Wholesale, Distributor |
| Companies Covered | ASE Technology Holding Co., Ltd., Amkor Technology, Inc., TSMC, Toshiba Corporation, Fujitsu Ltd., Hitachi, Ltd., IBM Corporation, Samsung Group, Micron Technology, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
High-Density Packaging Market Emerging Trajectories
Integration complexity is compressing traditional packaging hierarchies into unified process flows, collapsing distinctions between front-end fabrication and back-end assembly. Material science advances and regulatory chemistry constraints are simultaneously reshaping substrate composition roadmaps.
Hybrid bonding technology is unifying memory and logic die attachment through direct copper-to-copper interconnects at sub-10-micron pitch. High-performance computing designers are adopting this approach for AI accelerators and data center processors. The technology is unifying previously separate thermal management and electrical routing functions into single process steps, compressing capital intensity for advanced packaging lines.
EU REACH restrictions on halogenated flame retardants are forcing substrate laminate suppliers to reformulate resin systems around phosphorus-nitrogen chemistries. This regulatory pressure extends qualification cycles for new material stacks by 12-18 months. European automotive electronics suppliers face the most acute compliance burden as they simultaneously satisfy AEC-Q100 reliability standards.
Direct foundry engagement is displacing traditional OSAT intermediaries for advanced packaging procurement. Fabless semiconductor designers now contract packaging as part of wafer supply agreements rather than separate backend transactions. This pattern concentrates most visibly in 5G modem and AI chipset procurement flows targeting Taiwan-based packaging foundries.
High-Density Packaging Market Segmentation
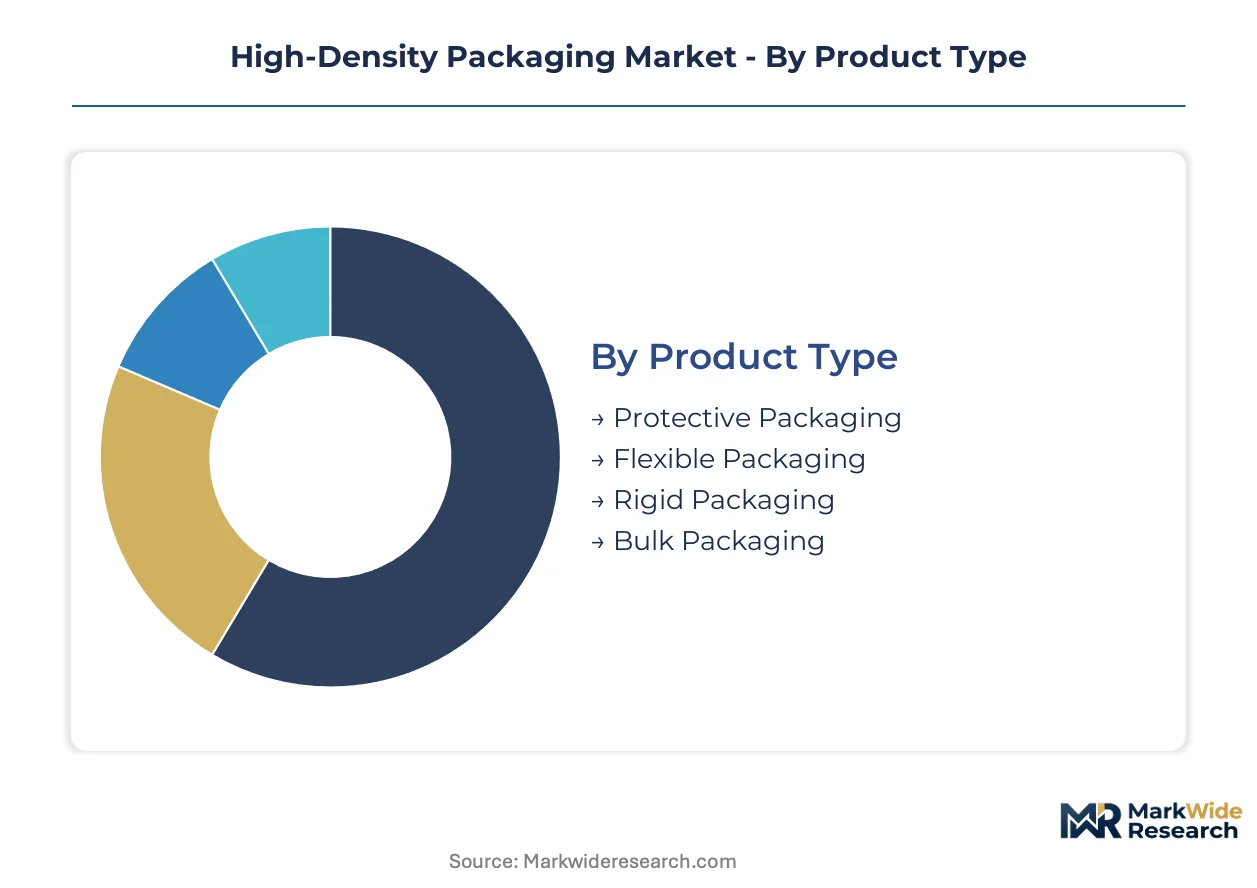
Segmentation in high-density packaging reveals how certification intensity, material compatibility, and channel economics partition commercial opportunity. Each dimension carries distinct margin profiles and regulatory exposure that shape supplier strategy.
Product Type:
Protective packaging for semiconductor bare die carries the heaviest qualification burden, requiring ISO 14644 cleanroom certification and AEC-Q100 automotive reliability testing. Flexible formats face lighter regulatory entry but demand biocompatibility validation for wearable health applications.
- Protective Packaging:Encompasses bare die carriers, interposer shields, and thermal spreaders engineered for low-k dielectric fragility. Demand concentrates in Taiwan and South Korea packaging foundries serving AI accelerator and HBM stack integration, where cleanliness specifications command premium positioning.
- Flexible Packaging:Thin-film substrates and stretchable interconnects for wearable sensors and curved display modules. Procurement is accelerating most quickly in health-monitoring device supply chains as substrate thinning below 50 micrometers matures.
- Rigid Packaging:Laminated substrates and molded enclosures for automotive ADAS modules. EPA fluorine-free mold compound mandates extend qualification timelines for US-bound shipments.
- Bulk Packaging:Standardized wafer-level shipping containers and tray systems for high-volume commodity die. Cost pressure dominates purchasing decisions with minimal differentiation.
Protective packaging sits at the top of the volume ranking, with flexible packaging climbing the fastest.
Material:
Material selection determines REACH compliance pathways and thermal performance ceilings, with bio-based alternatives gaining traction under EU chemical safety mandates.
- Plastic:Mold compounds, epoxy laminates, and polyimide films constitute the dominant substrate base. EU REACH halogenated flame retardant restrictions are accelerating phosphorus-nitrogen resin system qualification cycles among European automotive electronics suppliers.
- Metal:Copper leadframes, thermal spreaders, and EMI shielding layers. Demand clusters in high-bandwidth memory stack integration where thermal conductivity requirements exceed 200 W/mK.
- Glass:Interposer cores and through-glass vias for RF transparency and dimensional stability. Emerging adoption in 5G mmWave antenna-in-package modules.
- Composite:Hybrid organic-inorganic laminates combining CTE matching with mechanical flexibility. Niche positioning in aerospace-qualified die packaging.
Plastic substrates anchor procurement volume, though metal components are gaining share fastest in thermal-intensive applications.
End User:
End-use verticals impose divergent reliability standards, with automotive and medical segments requiring the most extensive documentation trails.
- Food & Beverage:Sensor packaging for smart packaging and supply chain tracking applications. FDA food contact material compliance adds qualification layer distinct from semiconductor standards.
- Consumer Electronics:5G modem chipsets, smartphone processors, and wearable devices. Fan-out wafer-level packaging specifications now dominate procurement contracts for flagship mobile platforms.
- Pharmaceuticals:Drug delivery device electronics and cold chain monitoring sensors. FDA 21 CFR Part 11 and EU MDR traceability requirements extend validation timelines.
- Cosmetics:Premium packaging with embedded NFC authentication and dispensing sensors. Lower certification burden permits faster design cycles.
Consumer electronics commands the largest procurement volume, with pharmaceuticals expanding most quickly as connected drug delivery platforms proliferate.
Distribution Channel:
Channel structure reflects order scale and technical support intensity, with direct foundry engagement displacing traditional intermediaries for advanced formats.
- Online:E-procurement platforms for standardized tray and shipping container replenishment. Limited to catalog items with established specifications.
- Retail:Specialized electronics distributors serving prototype and low-volume production runs. Technical field application support differentiates positioning.
- Wholesale:Volume contracting for commodity packaging materials with predictable consumption profiles. Price transparency compresses margins.
- Distributor:Authorized channel partners managing inventory and logistics for just-in-time fab delivery. Concentrated in Taiwan and China backend clusters.
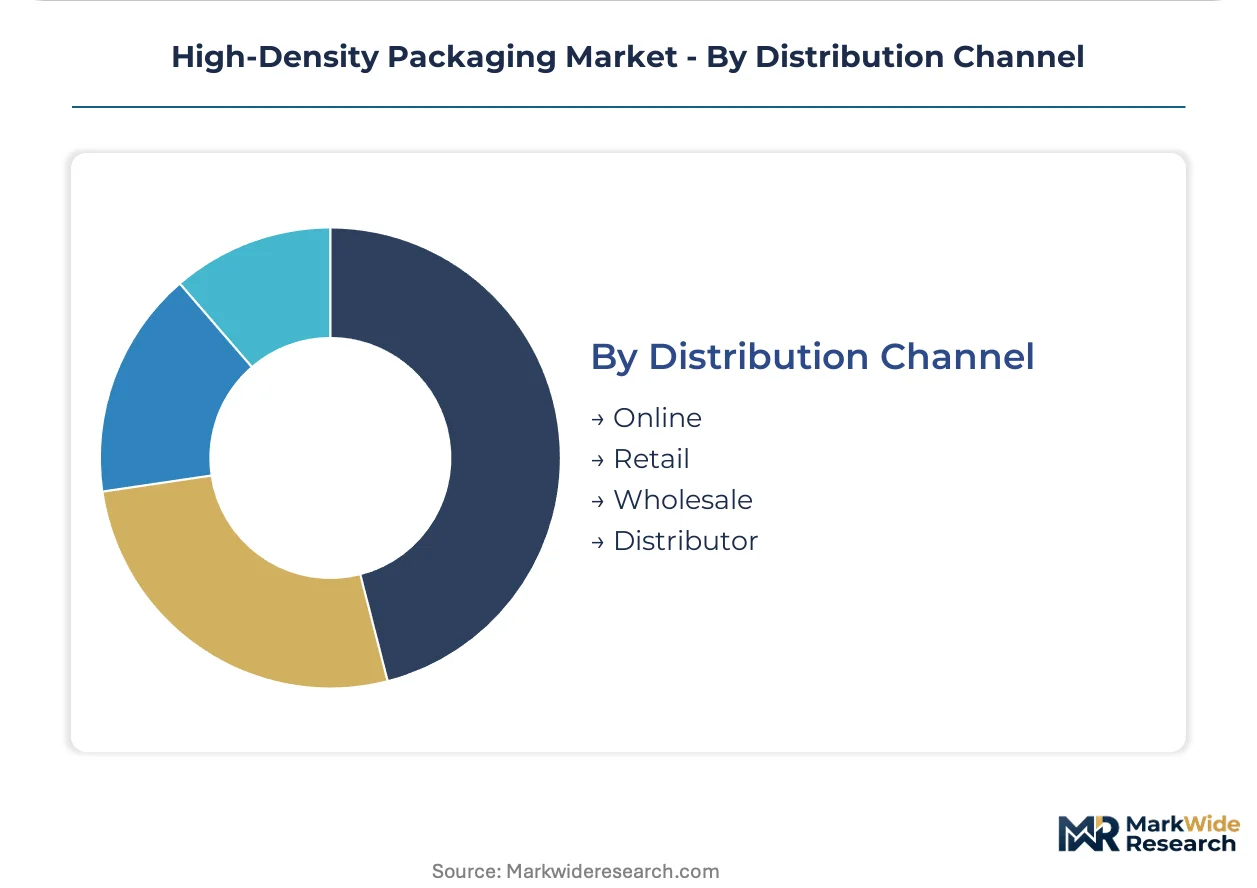
Distributor channels handle the highest transaction volume, with online procurement climbing fastest for standardized consumables.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
High-density packaging originated in US semiconductor research corridors during the 1960s, migrated to Japanese precision manufacturing in the 1980s, and consolidated in Taiwan and South Korea during the 2000s as foundry-scale packaging became economically dominant.
Taiwan
TSMC's CoWoS and InFO platforms drive advanced substrate demand for AI accelerators and 5G modems. METI-style industrial policy through the National Development Council subsidizes packaging equipment procurement. The Hsinchu Science Park anchors backend capacity expansion as ASE Technology scales hybrid bonding lines.
South Korea
Samsung Group integrates HBM stack production with logic foundry services, creating captive demand for interposer substrates. The Ministry of Trade, Industry and Energy coordinates domestic supply chain resilience programs. Pyeongtaek and Hwaseong clusters concentrate memory-logic packaging integration capacity.
United States
EPA regulations on per- and polyfluoroalkyl substances push mold compound reformulation for domestic packaging operations. The CHIPS and Science Act directs federal funding toward advanced packaging research corridors. Arizona and Texas fabs are expanding substrate qualification facilities for military-aerospace specifications.
Japan
Hitachi and Fujitsu heritage positions Tokyo and Osaka metros for precision equipment and materials supply. METI subsidizes advanced packaging equipment procurement under supply chain resilience frameworks. The Tohoku region maintains specialty substrate laminate production for automotive reliability grades.
Germany
ECHA REACH restrictions on halogenated flame retardants accelerate bio-based epoxy resin qualification among laminate suppliers. The KBA and automotive OEMs impose AEC-Q100 reliability standards on ADAS module packaging. Bavaria and Baden-Württemberg host substrate testing facilities serving European electronics supply chains.
High-Density Packaging Market Vendor Landscape
Premium-margin players sit above commodity-margin players across qualification intensity and thermal performance tiers. The vendor base stratifies between captive foundry packaging divisions, merchant OSATs, and specialized substrate material suppliers. Three archetypes dominate: integrated device manufacturers with captive packaging, pure-play packaging foundries, and equipment-intensive material vendors. Capacity expansion and strategic partnerships constitute the dominant competitive moves as firms secure hybrid bonding expertise and fluorine-free material qualifications.
Within the foundry-integrated tier, TSMC and Samsung Group exemplify captive packaging scale, while ASE Technology Holding Co., Ltd. anchors merchant backend assembly capacity across Taiwan and China. These three entities represent divergent strategic positions: TSMC occupies the premium process-technology vector, Samsung integrates memory-logic packaging vertically, and ASE Technology exemplifies multi-fab geographic diversification serving fabless semiconductor procurement flows.
| Leading Market Players |
|---|
| ASE Technology Holding Co., Ltd. |
| Amkor Technology, Inc. |
| TSMC |
| Toshiba Corporation |
| Fujitsu Ltd. |
| Hitachi, Ltd. |
| IBM Corporation |
| Samsung Group |
| Micron Technology |
| Others |
Supply Flow & Price Mechanics
Hybrid bonding adoption for AI accelerators is compressing capital intensity per packaging line while concentrating procurement leverage with foundries capable of sub-10-micron pitch interconnects. This process unification simultaneously elevates equipment amortization costs and reduces supplier fragmentation, reshaping margin distribution across substrate tiers.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels segments the market by certification grade and thermal performance. AEC-Q100 automotive reliability testing and ISO 14644 cleanroom specifications command premium positioning for protective packaging, while bulk wafer-level shipping containers face commodity spot pricing with minimal differentiation. Cost compression in rigid automotive formats is intensifying because EPA fluorine-free mold compound mandates extend qualification timelines. Fabless semiconductor designers show lowest price sensitivity for CoWoS and InFO platforms, whereas consumer electronics procurement teams negotiate aggressively on fan-out wafer-level packaging volumes.
Supply Chain Analysis
Regional distribution centers in Hsinchu Science Park and Pyeongtaek cluster coordinate just-in-time substrate delivery through hub-and-spoke patterns radiating from Taiwan and South Korea. Raw material flows draw from Japanese precision equipment suppliers, German epoxy resin formulators adapting to REACH phosphorus-nitrogen chemistries, and Chinese specialty chemical providers. Single-source vulnerability concentrates in hybrid bonding equipment where Tokyo and Osaka metros anchor lithography and thermal compression tool production. Distribution runs through authorized channel partners managing inventory for packaging foundries rather than traditional wholesale intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in high-density packaging rests on substrate thinning cost-down curves and the premium-tier shift toward HBM stack integration. Foundry-scale procurement consolidation rewards players with captive hybrid bonding expertise and fluorine-free material qualifications.
For Market Incumbents: Extend AEC-Q100 certification coverage into automotive ADAS module supply chains before European laminate suppliers complete REACH-compliant resin transitions. Add hybrid bonding capacity in Taiwan science park clusters to defend against Samsung Group's memory-logic vertical integration. Lock in long-term fluorine-free mold compound supply agreements with Japanese specialty chemical providers to preempt EPA regulatory bottlenecks.
For New Entrants and Emerging Players: Capture flexible packaging demand for wearable health sensors where substrate thinning below 50 micrometers creates technical entry barriers lower than protective packaging tiers. Target pharmaceutical drug delivery device electronics where FDA 21 CFR Part 11 traceability requirements slow incumbent response times. Lead with biocompatibility validation capabilities rather than competing on semiconductor cleanliness specifications.
For Investors and Strategic Acquirers: Valuations sit cheapest among merchant OSATs lacking foundry integration but holding multi-fab geographic diversification across Taiwan and China. The five-to-ten-year viability window favors substrate material suppliers with qualified phosphorus-nitrogen resin systems over equipment-dependent packaging houses. Watch Japan METI subsidy disbursement rates as an inflection indicator for competitive access reshuffling.
| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid Bonding Capacity Expansion | TSMC's CoWoS platform pulls substrate demand toward sub-10-micron pitch interconnect capabilities. |
| Fluorine-Free Material Qualification | EPA per- and polyfluoroalkyl substance regulations force mold compound reformulation for US-bound shipments. |
| Backward Integration into Epoxy Resins | EU REACH halogenated flame retardant bans accelerate captive supply of phosphorus-nitrogen chemistries. |
| Flexible Packaging Process Development | Substrate thinning below 50 micrometers unlocks wearable health sensor procurement from medical device OEMs. |
| Automotive Reliability Certification Investment | AEC-Q100 testing infrastructure separates premium protective packaging from commodity tray suppliers. |
Methodological Framework
Multiple input streams — packaging foundry operations executives, substrate material procurement leads, semiconductor fabless design firms, EPA regulatory affairs specialists, and ECHA compliance officers — were reconciled against SEC 10-K filings, customs and trade data, FDA medical device registration databases, and METI subsidy disclosure records. Bottom-up wafer-level packaging volume estimates and top-down semiconductor capital expenditure triangulation anchored market sizing.
Historical capacity expansion patterns cross-referenced against foundry equipment procurement panel input shaped the projection framework across the analysis window. Segmentation modeling incorporated product type hierarchy, material chemistry compliance pathways, end-use vertical reliability standards, and distribution channel technical support intensity. CAGRs derived from equipment utilization rates and substrate yield improvement curves rather than simple historical extrapolation.
Underlying measurement precision varies by segment; protective packaging for bare die carries tighter precision than flexible formats where substrate thinning techniques remain emergent. Forecasts reflect documented assumptions around hybrid bonding adoption timelines and REACH regulatory enforcement consistency. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Heavy Duty Packaging
Heavy Duty Paper Tags Market
Heavy Duty Packaging
Europe High Density Polyethylene Jerrycan Market
Heavy Duty Packaging
Heavy-Duty Paper and Multiwall Shipping Sack Market
Heavy Duty Packaging
Global Heavy Duty Bags and Sacks Market
Heavy Duty Packaging
High-Stress PCR HDPE Detergent Bottles Market
Heavy Duty Packaging
Heavy-Duty Corrugated Boxes Market
Heavy Duty Packaging
Hazardous Goods Packaging Market
Heavy Duty Packaging
Heavy Duty Bins Market
Heavy Duty Packaging
Hazmat Packaging Market
Heavy Duty Packaging
High Impact Corrugated Boxes Market
Heavy Duty Packaging
Heavy Duty Corrugated Packaging Market
Heavy Duty Packaging
Large Blow Molded Products Market