

High-Stress PCR HDPE Detergent Bottles Market Size, Share, and Industry Trends Forecast 2026-2036
High-Stress PCR HDPE Detergent Bottles Market Insights
Buyer concentration among commercial laundries and hospitality chains is expanding as institutional procurement shifts toward consolidated supplier contracts. Berry Global Group leverages its North American manufacturing footprint to serve these volume buyers. ALPLA Group anchors European supply through its network of dedicated PCR compounding facilities. Graham Packaging Company competes on technical service depth for custom bottle designs.
High-stress PCR HDPE detergent bottles combine post-consumer recycled high-density polyethylene with virgin resin ratios engineered to withstand internal pressure, chemical compatibility with alkaline surfactants, and drop-impact resistance through multi-layer extrusion blow molding. Extrusion-blow molded bottles dominate unit volume due to equipment ubiquity and cost efficiency, while injection-molded variants command premium positioning for precision neck finishes and closure compatibility. Compression-molded bottles represent the fastest-growing product type as machinery suppliers improve cycle times for PCR-heavy formulations.
The EU Green Deal and REACH frameworks mandate minimum recycled content thresholds for plastic packaging, directly shaping resin procurement strategies and bottle design specifications. FDA food-contact equivalency standards for PCR HDPE in the United States create parallel compliance pathways that influence cross-border production decisions. Stakeholders must monitor evolving Extended Producer Responsibility fee structures and mechanical recycling yield rates to calibrate long-term capacity investments.
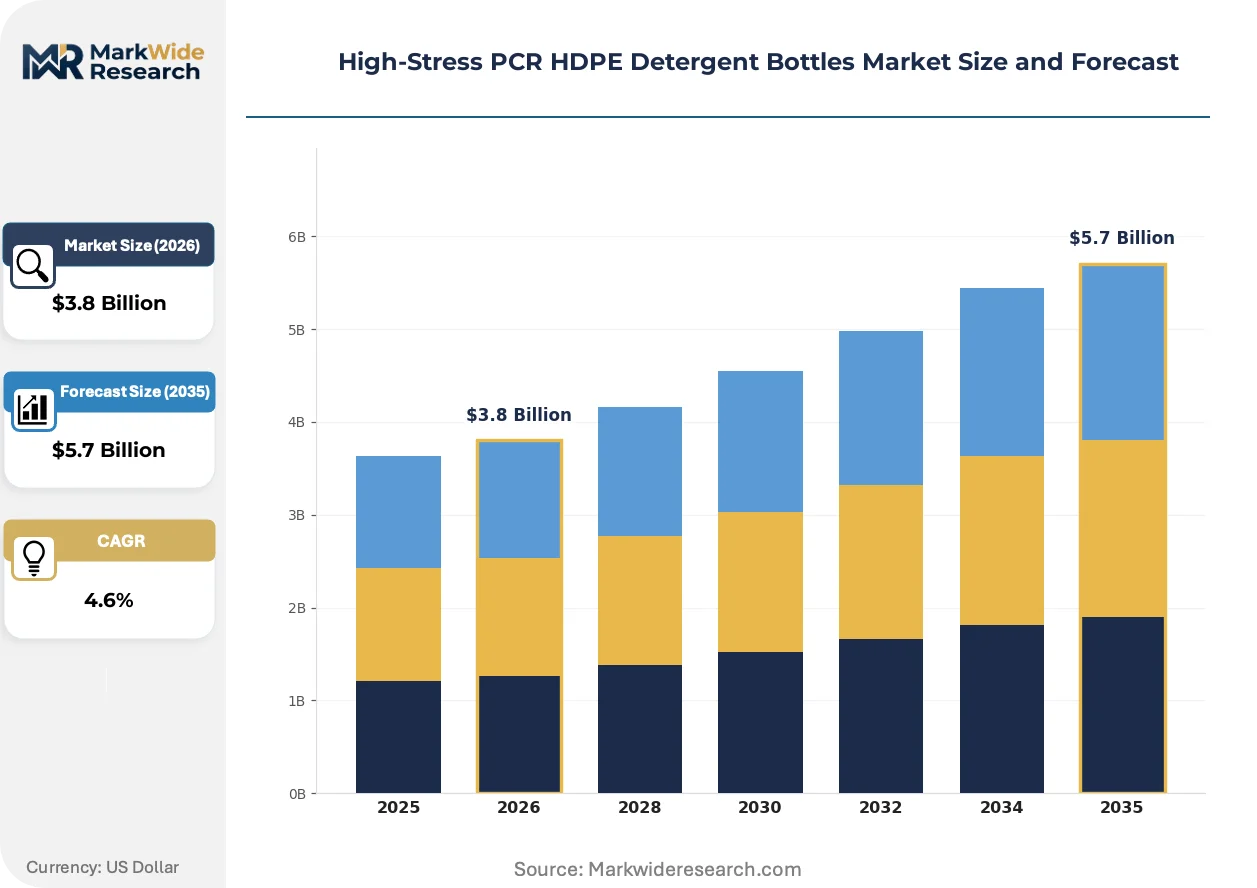
Market Dynamics
Post-consumer recycled content mandates under the EU Green Deal are compressing virgin resin demand curves while forcing rapid retooling of extrusion blow molding lines across European manufacturing bases.
Growth Catalysts
- EU Green Deal packaging thresholds:Mandatory recycled content floors for plastic containers are pulling forward capital deployment into PCR compounding infrastructure across Germany, France, and Italy.
- Commercial laundry consolidation:Institutional buyers in hospitality and healthcare are centralizing detergent procurement through multi-year supply agreements that specify PCR-heavy packaging.
- Multi-layer extrusion advances:Improved barrier layer bonding techniques are extending PCR HDPE loadings beyond previous mechanical performance limits without sacrificing drop-impact resistance.
Market Restraints
- PCR feedstock cost volatility:Mechanical recycling yield rates fluctuate with municipal collection quality, creating input cost instability that compresses margin predictability for converters.
- German regulatory concentration risk:Packaging sustainability regulations most advanced in Germany create asymmetric compliance burdens that disadvantage smaller producers lacking dedicated regulatory affairs functions.
- Alkaline surfactant compatibility limits:High-pH detergent chemistries degrade PCR HDPE polymer chains faster than virgin resin, constraining formulation flexibility for concentrated products.
Strategic Opportunities
- North American EPR acceleration:Extended Producer Responsibility fee structures emerging in California, Oregon, and Maine will create premium pricing corridors for PCR-verified containers.
- Compression molding technology convergence:Faster cycle times for PCR-heavy formulations are opening white space in single-serve and travel-size detergent segments previously dominated by injection molding.
- Chemical recycling integration:Pyrolysis-based HDPE recovery is approaching commercial scale, offering feedstock quality parity with virgin resin for high-stress applications.
Industry Challenges
- PCR compounding technical talent scarcity:Formulation chemists capable of balancing recycled content ratios with burst-pressure specifications command premium compensation in tight labor markets.
- FDA food-contact equivalency timeline compression:Cross-border production decisions face extended certification cycles as PCR HDPE migrates into adjacent cleaning product categories with stricter contact standards.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
High-Stress PCR HDPE Detergent Bottles Market Trends and Innovations
Equipment suppliers and resin compounders are co-developing processing technologies that expand PCR loading thresholds while maintaining the pressure ratings required for concentrated detergent formulations.
Multi-layer extrusion blow molding is modularizing around standardized barrier layer configurations that separate functional performance from recycled content ratios. Commercial laundries in Germany and the Netherlands are specifying these modular designs in tender documents to lock in future PCR percentage upgrades without bottle geometry changes. This architecture is compressing product development cycles from eighteen months to under eight months for format extensions.
REACH framework amendments are tightening migration limit testing for recycled content in alkaline chemical contact applications. The European Chemicals Agency is requiring enhanced substance identification protocols that extend compliance documentation burdens to compounders previously exempt under virgin resin equivalency assumptions. German converters are responding by integrating in-house analytical laboratories to reduce third-party certification delays.
Institutional procurement teams are consolidating supplier panels around lifecycle assessment disclosure requirements that privilege PCR transparency over unit cost. Hospitality chains operating across Germany, France, and Spain are disintermediating regional distributors to contract directly with bottle manufacturers capable of verified mass-balance accounting. This pattern is most visible in the contract laundry segment, where sustainability scorecarding now determines allocation of multi-year volume commitments previously awarded on price alone.
High-Stress PCR HDPE Detergent Bottles Market Segmentation
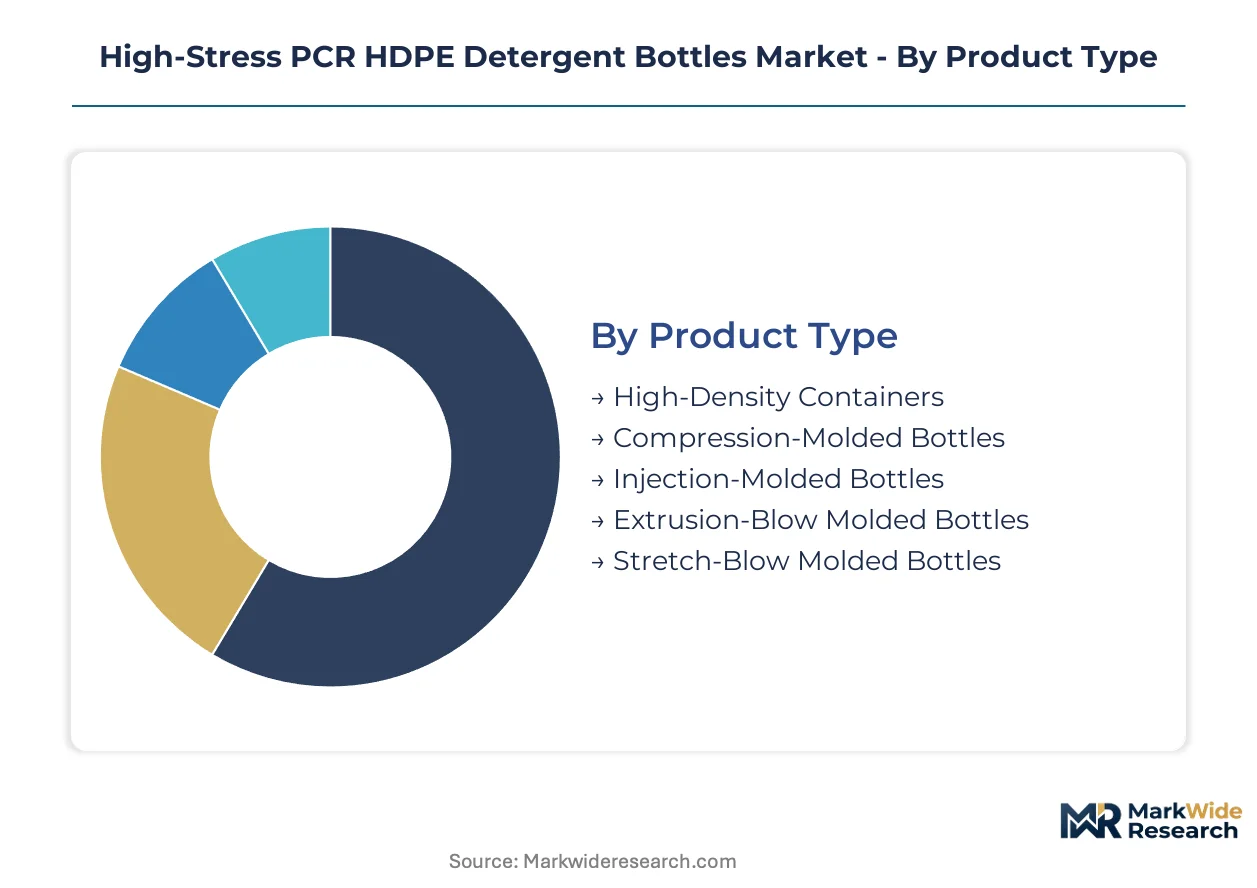
Segmentation in high-stress PCR HDPE detergent bottles reveals how capital deployment, regulatory pressure, and end-use performance requirements intersect. Each dimension exposes distinct margin structures and capacity allocation patterns across converter networks.
Product Type:
Capital intensity varies sharply across molding technologies, with multi-layer extrusion lines requiring the heaviest upfront investment for PCR-heavy formulations.
- Extrusion-Blow Molded Bottles:Equipment ubiquity and established processing protocols make this the default choice for volume production of standard detergent formats. Commercial laundries in Germany and the Netherlands specify these containers in consolidated procurement contracts that lock in PCR percentage commitments across multi-year horizons.
- Compression-Molded Bottles:Machinery cycle times for PCR-heavy formulations have improved sufficiently to open single-serve and travel-size segments previously ceded to injection molding. European compounders are prioritizing this technology for concentrated alkaline surfactant applications where drop-impact resistance cannot be compromised.
- Injection-Molded Bottles:Precision neck finishes command premium positioning for closure compatibility in precision-dosing applications.
- Stretch-Blow Molded Bottles:Orientation stretching enhances barrier properties for oxygen-sensitive concentrated formulations.
- High-Density Containers:Thick-wall designs serve bulk institutional formats where stacking strength overrides material efficiency considerations.
Most installed capacity flows through extrusion-blow molded formats. Expansion is steepest in compression-molded systems as machinery suppliers resolve cycle time limitations.
Application:
Formulation chemistry dictates resin selection and layer architecture, with alkaline surfactants imposing the most severe constraints on PCR loading thresholds.
- Fabric Wash Liquids:The largest volume application, where multi-layer barrier designs separate aggressive surfactant contact from external PCR-rich layers. REACH migration limit testing under ECHA protocols has intensified compounder documentation burdens for these high-pH formulations.
- Surface Cleaners:Diverse pH ranges allow flexible PCR content ratios, with EU Green Deal thresholds driving rapid format standardization across German retail channels.
- Dishwashing Liquids:Viscosity requirements favor specific neck finish geometries that constrain molding technology choices.
- Floor Cleaners:Large-format containers prioritize stacking strength over barrier sophistication.
- Vehicle Cleaning Solutions:Solvent compatibility demands virgin-rich barrier layers that limit PCR economics.
Procurement volume concentrates in fabric wash applications. Regulatory pressure is most acute in surface cleaners where EU Green Deal compliance deadlines approach fastest.
End User:
Customer scale determines specification complexity, with institutional buyers imposing the most demanding lifecycle assessment and mass-balance verification requirements.
- Commercial Laundries:Centralized procurement through hospitality and healthcare networks now mandates PCR transparency over unit cost. German operators are disintermediating distributors to contract directly with manufacturers capable of verified sustainability scorecarding.
- Hospitality Sector:Brand-level sustainability commitments translate into rigid packaging specifications that cascade through contract laundry supply chains. Chains operating across Germany, France, and Spain have standardized PCR-heavy bottle requirements in pan-European tender documents.
- Household Consumers:Price sensitivity constrains PCR premiums in mass retail channels where private label competition dominates.
- Institutional Facilities:Healthcare and education procurement offices are consolidating supplier panels around consolidated contract structures.
- Automotive Care Centers:Solvent exposure limits PCR loading for professional-grade concentrates.
Contract value aggregates most heavily with commercial laundries. Sustainability specification intensity is climbing fastest in hospitality procurement.
Packaging Type:
Dispensing mechanism selection reflects usage context and formulation viscosity, with precision dosing systems commanding specialized neck finish tolerances.
- Screw Caps:Universal compatibility and lowest unit cost sustain dominance in bulk institutional formats where controlled pouring suffices.
- Trigger Sprayers:Mechanical complexity and chemical compatibility requirements create specification barriers that favor established converter relationships.
- Pump Dispensers:Viscous formulations in concentrated fabric wash segments require precision dosing mechanisms.
- Flip Tops:One-handed operation suits kitchen and bathroom countertop storage contexts.
- Snap Lids:Tamper-evident features serve refill and bulk transfer applications in commercial settings.
Volume throughput peaks with screw cap configurations. Technical service intensity concentrates around trigger sprayer integrations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany commands tighter packaging sustainability regulations than the United States, yet both markets drive divergent innovation pathways for PCR-heavy detergent containers. France and the Netherlands intermediate between these poles with procurement-led compliance models. Italy and Spain concentrate manufacturing capacity serving southern European hospitality supply chains.
United States
Commercial laundry consolidation across hospitality chains accelerates PCR specification adoption in bulk detergent procurement. FDA food-contact equivalency standards for PCR HDPE create parallel compliance pathways that influence cross-border production decisions. Chicago and Atlanta industrial corridors host converter networks retooling extrusion lines for EPR-driven demand from California and Oregon.
Germany
EU Green Deal packaging thresholds pull capital deployment into PCR compounding infrastructure across North Rhine-Westphalia and Bavaria. REACH framework amendments tighten migration limit testing for recycled content in alkaline chemical contact applications. Hamburg and Berlin converters integrate in-house analytical laboratories to reduce third-party certification delays.
France
Hospitality sector procurement offices centralize supplier panels around lifecycle assessment disclosure requirements that privilege PCR transparency. ECHA protocols extend compliance documentation burdens to compounders under virgin resin equivalency assumptions. Lyon and Paris packaging clusters specialize in multi-layer barrier designs for concentrated fabric wash segments.
Netherlands
Institutional buyers specify modular multi-layer designs in tender documents to lock in future PCR percentage upgrades without bottle geometry changes. Rotterdam port logistics anchor feedstock import flows for mechanical recycling operations. Eindhoven equipment suppliers co-develop processing technologies that expand PCR loading thresholds for commercial laundry applications.
Italy
Surface cleaner format standardization accelerates across retail channels approaching EU Green Deal compliance deadlines. Lombardy and Emilia-Romagna manufacturing bases serve pan-European hospitality chains with PCR-heavy bottle requirements. Milan converters compress product development cycles from eighteen months to under eight months for format extensions.
High-Stress PCR HDPE Detergent Bottles Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across three distinct tiers. Large-scale converters with integrated resin compounding capabilities anchor supply relationships with institutional procurement offices. Mid-tier regional fabricators serve fragmented retail channels through distributor networks. Specialized technology providers license barrier layer bonding innovations to multiple converter tiers. Capacity expansion and strategic partnerships dominate competitive moves as EPR frameworks mature.
Within the diversified packaging tier, Berry Global Group and ALPLA Group exemplify scale-driven positioning across North American and European manufacturing footprints. Graham Packaging Company occupies a specialist position emphasizing technical service depth for custom bottle designs. These three entities represent contrasting archetypes: continental manufacturing scale, dedicated PCR compounding infrastructure, and precision engineering capabilities respectively.
| Leading Market Players |
|---|
| Berry Global Group |
| ALPLA Group |
| Graham Packaging Company |
| Silgan Plastics |
| Plastipak Packaging |
| Logoplaste |
| CKS Packaging |
| Amcor |
| Berlin Packaging |
| Others |
Pricing and Supply Chain Analysis
Commercial laundry procurement consolidation across Germany, France, and the Netherlands is forcing converters to absorb PCR certification costs while maintaining contract pricing, compressing margin structures for mid-tier suppliers lacking dedicated compounding infrastructure.
Pricing Analysis
Capacity additions in Germany and North Rhine-Westphalia are reshaping price floors for PCR-heavy formulations as Berry Global Group and ALPLA Group deploy integrated compounding assets. Three-tier pricing structure across premium certified, standard compliance, and economy virgin-rich tiers separates buyers by sustainability verification requirements. Cost compression in standard tiers is intensifying because REACH migration testing burdens compounders with documentation overhead. Household consumers through mass retail channels exhibit highest price sensitivity, while hospitality chains with pan-European sustainability scorecards accept PCR premiums.
Supply Chain Analysis
PCR compounding technical talent scarcity across Germany, Italy, and the United States is constraining production expansion timelines for high-stress formulations. Supply draws from post-consumer bale collection networks in Germany, mechanical recycling operations in the Netherlands, and resin compounding facilities in North America. Single-source vulnerability concentrates in specialized barrier layer bonding equipment sourced from Eindhoven equipment suppliers. Distribution runs through institutional procurement offices in hospitality and healthcare that disintermediate traditional distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a stable compounder where regulatory ratchets under the EU Green Deal create predictable demand expansion for PCR-verified packaging.
For Market Incumbents: Extend analytical laboratory capabilities in-house to compress REACH certification cycles that currently delay product launches. Build backward integration into mechanical recycling feedstock streams to secure bale quality consistency against municipal collection volatility. These moves defend against specialty compounders capturing hospitality procurement direct contracts.
For New Entrants and Emerging Players: Direct-to-institutional digital procurement platforms offer bypass routes around entrenched distributor relationships controlling German commercial laundry supply. Target compression-molded single-serve formats where machinery cycle time improvements have opened white space previously dominated by injection molding incumbents. Lead with modular multi-layer designs that enable PCR percentage upgrades without bottle geometry changes.
For Investors and Strategic Acquirers: Asymmetric upside sits with mid-scale converters possessing in-house PCR compounding and existing hospitality supply relationships. Five-to-ten year viability rests on EPR framework maturation creating premium pricing corridors for verified mass-balance accounting. Watch California and Oregon EPR fee implementation as inflection signal for North American capacity deployment timing.
| Strategic Initiative | Industry Significance |
|---|---|
| In-House PCR Compounding Investment | REACH certification speed separates German converters from competitors facing third-party delays. |
| Modular Multi-Layer Design Platform | Rotterdam institutional buyers specify upgradeable PCR percentages without geometry changes. |
| Direct Hospitality Procurement Channel | Pan-European sustainability scorecards disintermediate distributors for verified mass-balance suppliers. |
| Compression Molding Capacity Addition | Eindhoven equipment advances open single-serve segments previously ceded to injection molding. |
| Chemical Recycling Feedstock Partnership | Pyrolysis-based HDPE recovery approaches quality parity with virgin resin for high-stress applications. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with extrusion blow molding plant managers, procurement leads at commercial laundry networks, technical R&D directors at resin compounders, and sustainability officers at hospitality chains with secondary validation. Sources included EU Green Deal implementation documents, ECHA migration limit protocols, SEC filings from diversified packaging conglomerates, and customs data on PCR resin trade flows. Bottom-up capacity modeling and top-down demand segmentation triangulated volume estimates.
Historical reference periods anchored the projection horizon across product type, application chemistry, end-user scale, and regional regulatory cluster dimensions. CAGR derivation weighted EPR framework implementation timelines against mechanical recycling yield rate trajectories. Modeled inputs included PCR loading thresholds achievable through multi-layer extrusion advances and compression molding cycle time improvements.
The model assumes a particular technology adoption path; alternative pathways for chemical recycling scale-up would alter the outlook. Forecasts reflect assumptions on EU Green Deal threshold enforcement consistency and REACH amendment implementation speed. Material deviation in EPR fee structures or mechanical recycling feedstock availability warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.