
 Plastic Waste Sorting Equipment Market | 2026-2036
Plastic Waste Sorting Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Plastic Waste Sorting Equipment Market Analytics
Buyer concentration among recycling facilities is realigning as large waste management companies consolidate municipal contracts while smaller regional recyclers fragment into specialized streams. TOMRA Systems ASA leverages its sensor-based sorting leadership to dominate high-purity polymer recovery. Sesotec GmbH differentiates through multi-spectral detection systems for complex mixed-plastic feeds. Vecoplan AG anchors its position with integrated shredding and sorting lines for post-industrial plastic processors.
Plastic waste sorting equipment encompasses machinery designed to separate mixed polymer streams by resin type, color, and contamination level using automated detection and ejection mechanisms, typically processing 1–10 tons per hour with purity thresholds exceeding 95 percent for bottle-to-bottle recycling. Optical sorters lead installed capacity due to proven near-infrared detection economics, while robotics represents the fastest-growing technology segment as AI-guided pickers reduce labor dependence in dirty or mixed-waste environments. Air classifiers occupy a mature niche in film and flake density separation where capital constraints favor simpler mechanical solutions over sensor-based alternatives.
The EPA enforces landfill diversion targets that push U.S. municipalities toward automated sorting investments, while the EU Green Deal's recycling rate mandates and REACH compliance requirements for recycled content traceability shape equipment specifications across Europe. China's MEE enforces import purity standards that compel domestic recyclers to upgrade from manual to automated sorting lines. Stakeholders must monitor how regulatory tightening on recycled content quotas alters the acceptable cost threshold for advanced detection technologies versus conventional mechanical separation.
Market Dynamics
Extended producer responsibility mandates are forcing mechanical recyclers to upgrade from batch-fed manual lines to continuous automated sorting systems capable of meeting 95 percent purity thresholds for food-grade polymer recovery.
Growth Catalysts
- EU Green Deal recycling rate mandates:The framework requires member states to achieve 55 percent plastic packaging recycling by 2030, compelling municipal MRFs to replace legacy density-based separators with near-infrared optical sorters.
- China's MEE import purity standards:Domestic recyclers must process post-consumer streams to sub-1 percent contamination levels previously achieved only through manual labor, accelerating capital deployment in automated detection systems.
- Bottle-to-bottle recycling expansion:Food and beverage brands are securing offtake agreements for rPET flake that exceeds FDA and EFSA food-contact specifications, creating pull-through demand for high-resolution polymer identification equipment.
Market Restraints
- Capital intensity of sensor-based systems:Near-infrared and X-ray fluorescence units require USD 800,000–2.5 million per installed line, excluding integration and civil works, freezing out independent recyclers operating on thin commodity margins.
- Optical component supply concentration:Indium gallium arsenide detector arrays and specialized short-wave infrared cameras concentrate among German and Japanese component suppliers, exposing equipment OEMs to 16–24 week lead time volatility.
- Technical limitation in black plastic detection:Carbon-black pigmentation absorbs near-infrared wavelengths, forcing recyclers to either landfill these streams or invest in costly alternative detection methods such as laser-induced breakdown spectroscopy.
Strategic Opportunities
- Underpenetrated Southeast Asian markets:Vietnam, Indonesia, and Thailand are drafting extended producer responsibility frameworks modeled on EU structures, creating first-mover advantage for equipment suppliers establishing regional service networks.
- AI-guided robotic picking convergence:Integration of computer vision with delta robots enables sorting of dirty mixed-waste streams previously uneconomical to process, opening municipal solid waste and construction demolition applications.
- California's SB 54 recycled content mandates:The legislation requires 30 percent recycled plastic in packaging by 2030, generating equipment demand among West Coast processors seeking to capture premium pricing for state-compliant flake.
Industry Challenges
- Electro-optical technician scarcity:Maintenance of multi-spectral detection systems requires expertise in hyperspectral imaging calibration and pneumatic ejector alignment, skills concentrated among German and Austrian engineering workforces.
- Legacy mechanical integration friction:Retrofitting optical sorters into existing shredding and washing lines demands custom conveyor routing and dust management, extending commissioning timelines and disrupting continuous operations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Plastic Waste Sorting Equipment Market |
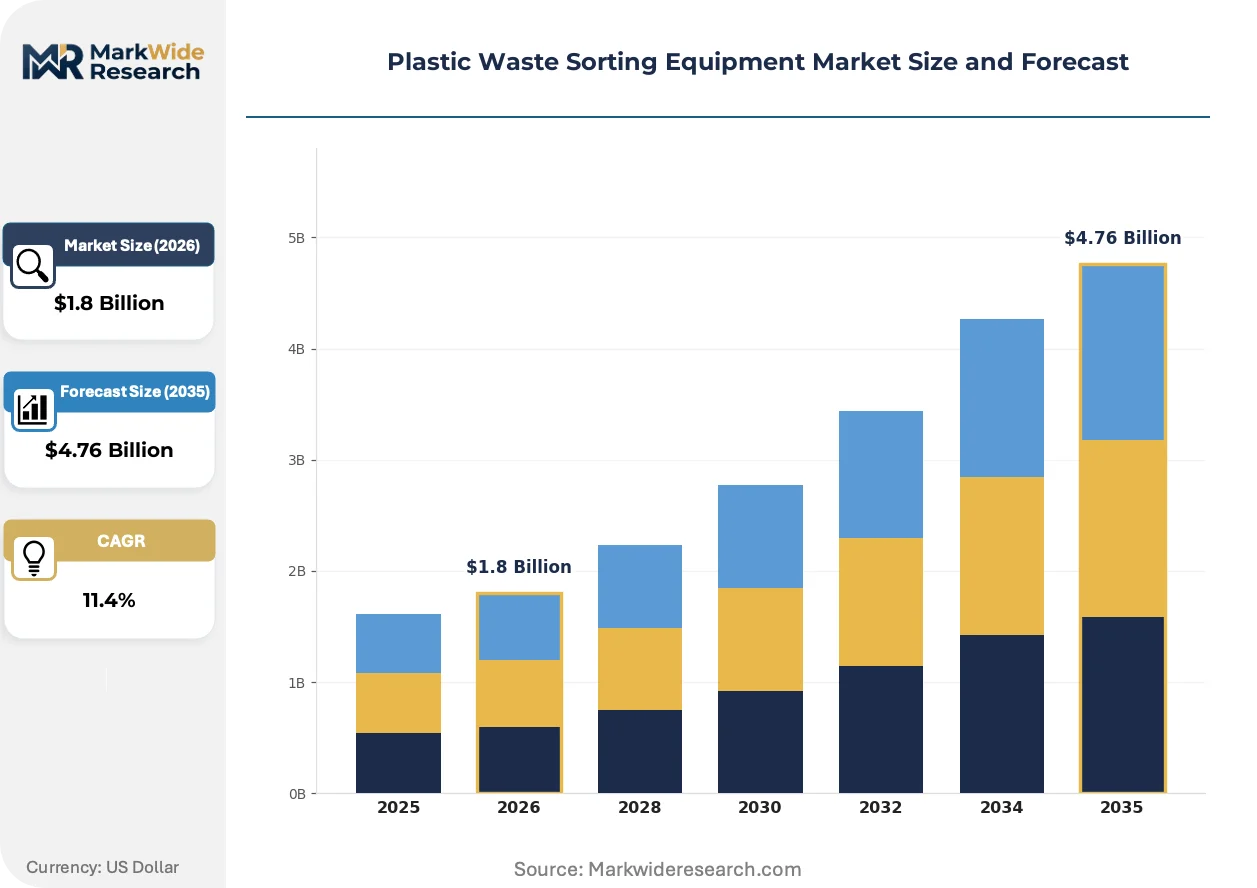
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual Sorters, Optical Sorters, Air Classifiers, Separator Machines Technology: X-ray Technology, Infrared Sensors, Robotics, Laser Sorting End User: Municipalities, Recycling Facilities, Industrial Plants, Waste Management Companies Capacity: Small Scale, Medium Scale, Large Scale, Custom Solutions |
| Companies Covered | Wastequip, Sesotec GmbH, TOMRA Systems ASA, SSI Shredding Systems Inc, Eldan Recycling A/S, EREMA, Vecoplan AG, Geording Machinery, Terex Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Plastic Waste Sorting Equipment Market Evolving Landscape
Deep learning architectures are displacing rule-based classification algorithms across detection systems, compressing the accuracy gap between laboratory-grade spectroscopy and production-line sorting economics.
Hyperspectral imaging is rewriting the technical frontier for polymer identification. The technology captures contiguous spectral bands across 400–2500 nanometers, enabling discrimination of chemically similar resins such as PET and PLA that near-infrared systems conflate. European post-industrial plastic processors are piloting these units for automotive shredder residue applications. The capability is compressing the viable feedstock envelope to include multi-layer packaging and degraded ocean plastics previously rejected as non-recyclable.
REACH compliance requirements for recycled content traceability are reshaping equipment specifications across European installations. The regulation mandates chain-of-custody documentation from collection through reprocessing, forcing sorter OEMs to integrate data logging and material fingerprinting directly into machine control systems. German recycling facilities are responding by specifying equipment with embedded spectroscopic audit trails rather than retrofitted compliance modules.
Performance-based service contracts are displacing traditional capex procurement among North American waste management companies. Under these arrangements, equipment suppliers guarantee throughput tonnage and purity thresholds, absorbing operational risk in exchange for per-ton processing fees. The model is concentrating most visibly in California and New York municipal contracts where budget constraints favor opex flexibility over upfront capital deployment.
Plastic Waste Sorting Equipment Market Segmentation
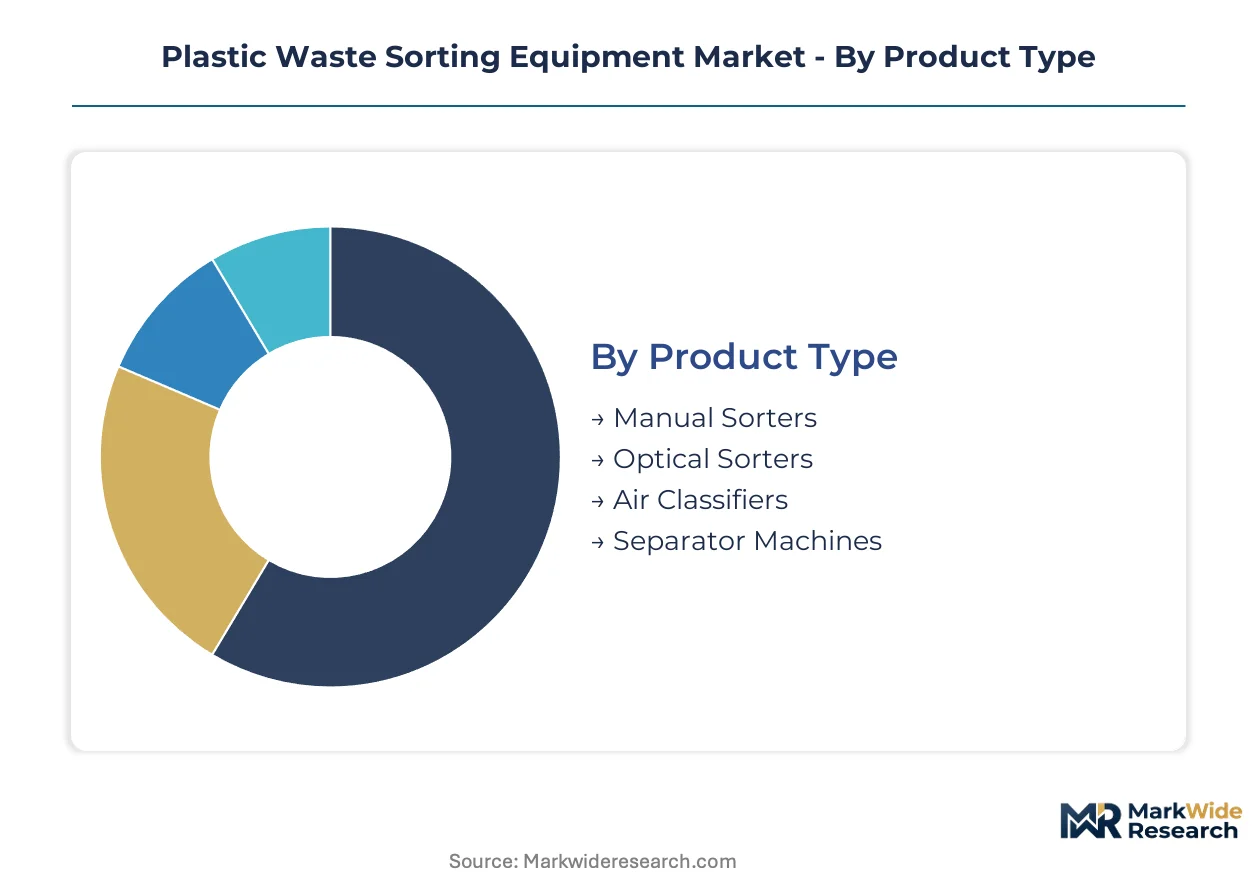
Segmentation in plastic waste sorting equipment reveals how capital constraints, feedstock complexity, and purity mandates reshape procurement patterns across recycler tiers. Buyers optimize technology choices against contamination levels, throughput requirements, and regulatory deadlines rather than pursuing uniform solutions.
Product Type:
Equipment selection hinges on whether processors prioritize capital efficiency or purity thresholds for food-grade polymer recovery.
- Optical Sorters:Near-infrared detection systems dominate high-volume municipal MRFs, achieving polymer-specific separation at 1–10 tons per hour with purity exceeding 95 percent. Germany's recycling facilities lead European deployment as EU Green Deal mandates force upgrades from density-based separators. Capital intensity of USD 800,000–2.5 million per line restricts adoption to consolidated waste management operators with secured municipal contracts.
- Air Classifiers:Density separation units occupy a mature niche for film and flake applications where simpler mechanical solutions outperform sensor economics. Chinese domestic recyclers favor these systems for post-industrial plastic streams with homogeneous composition and lower contamination loads. The technology avoids optical component supply bottlenecks that plague near-infrared deployments.
- Manual Sorters:Labor-intensive batch-fed lines persist in emerging markets with wage arbitrage and irregular feedstock quality.
- Separator Machines:Electromagnetic and eddy-current units recover metals from mixed plastic streams in automotive shredder residue applications.
Optical sorters lead volumes today; robotics-integrated sorting lines are gaining share fastest.
Technology:
Detection sophistication determines which polymer streams become economically recoverable versus landfill-bound.
- Infrared Sensors:Near-infrared and short-wave infrared systems anchor installed capacity with proven economics for PET, HDPE, and PP identification. TOMRA and Sesotec concentrate supply among German and Austrian engineering bases, creating 16–24 week lead time exposure for detector arrays. The technology fails on carbon-black pigmented plastics, forcing parallel investment in alternative detection for complete stream coverage.
- Robotics:AI-guided delta robots with computer vision enable sorting of dirty mixed-waste streams previously uneconomical to process. California's SB 54 recycled content mandates generate demand among West Coast processors seeking to capture premium pricing for state-compliant flake. Labor scarcity in North American recycling labor markets accelerates payback calculations against manual alternatives.
- X-ray Technology:X-ray fluorescence and transmission systems identify chlorine-containing polymers in mixed construction demolition waste.
- Laser Sorting:Laser-induced breakdown spectroscopy penetrates black plastic detection barriers that defeat near-infrared wavelengths.
Infrared sensors dominate installed base; robotics represents the steepest expansion trajectory among detection modalities.
End User:
Procurement scale and risk tolerance separate institutional buyers from specialized operators.
- Recycling Facilities:Dedicated mechanical recyclers deploy continuous automated lines capable of 95 percent purity thresholds for food-grade polymer recovery. Extended producer responsibility mandates in the EU and emerging Asian frameworks compel capital deployment toward sensor-based systems. Performance-based service contracts with guaranteed throughput and purity terms are displacing traditional capex procurement.
- Municipalities:Public-sector MRFs face EPA landfill diversion targets that push toward automated sorting investments despite budget constraints. California and New York municipal contracts concentrate opex-flexible procurement models where suppliers absorb operational risk for per-ton fees. Political procurement cycles create irregular upgrade timelines compared to private-sector continuous improvement.
- Waste Management Companies:Vertically integrated operators leverage consolidated contract portfolios to standardize equipment specifications across regional footprints.
- Industrial Plants:Post-industrial plastic processors prioritize integrated shredding and sorting lines with lower contamination tolerance than post-consumer streams.
Recycling facilities lead equipment absorption; waste management companies are consolidating procurement fastest.
Capacity:
Throughput specification reflects feedstock security and offtake contract duration.
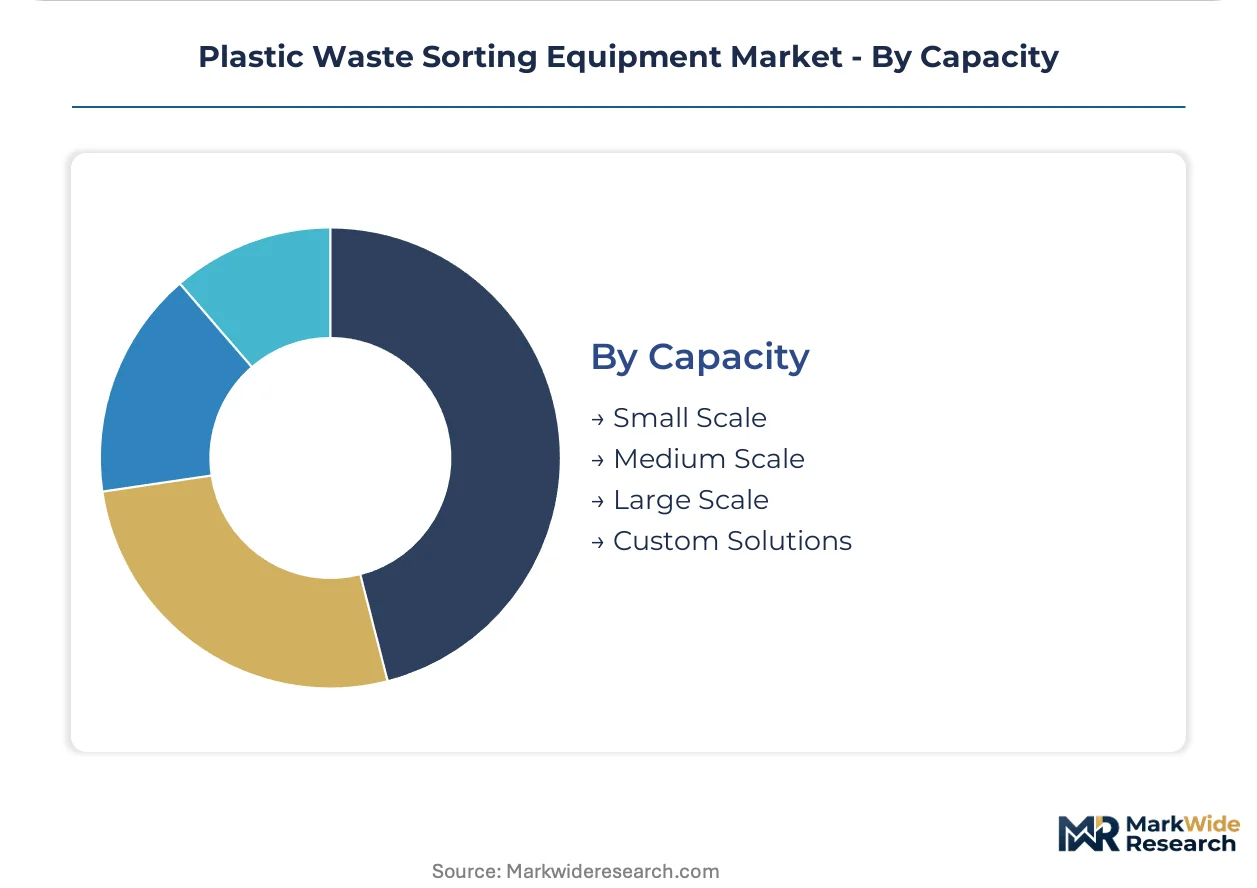
- Large Scale:Continuous-duty lines processing 5–10 tons per hour serve consolidated operators with secured municipal contracts or long-term brand offtake agreements. China's MEE import purity standards compel domestic recyclers to upgrade from manual to automated lines at this scale. Commissioning timelines extend due to custom conveyor routing and dust management requirements for legacy mechanical integration.
- Custom Solutions:Engineered configurations address automotive shredder residue and ocean plastic degradation challenges that defeat standard detection algorithms. European post-industrial processors pilot hyperspectral imaging units for multi-layer packaging identification. REACH compliance requirements for recycled content traceability force embedded spectroscopic audit trails rather than retrofitted modules.
- Medium Scale:Modular 2–5 ton per hour systems target regional recyclers with fragmented feedstock supply.
- Small Scale:Batch-fed units below 2 tons per hour serve specialized stream processors and pilot demonstration facilities.
Large scale systems anchor revenue concentration; custom solutions are expanding most quickly as feedstock complexity intensifies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German and Austrian engineering workforces anchor optical component supply chains, concentrating detector array expertise that feeds equipment deployment across multiple continents.
United States
EPA landfill diversion targets and California's SB 54 recycled content mandates drive municipal MRF upgrades. The EPA enforces diversion thresholds that push automated sorting investments. West Coast processors in California deploy high-resolution polymer identification equipment to capture premium pricing for state-compliant flake.
Germany
EU Green Deal recycling rate mandates and REACH compliance requirements reshape equipment specifications. The EU Green Deal requires member states to achieve 55 percent plastic packaging recycling by 2030. Bavarian recycling facilities specify equipment with embedded spectroscopic audit trails rather than retrofitted compliance modules.
China
Domestic recyclers upgrade from manual to automated sorting lines to meet MEE import purity standards. The MEE enforces sub-1 percent contamination levels previously achieved only through manual labor. Yangtze River Delta processors deploy capital in automated detection systems at large scale to satisfy these thresholds.
Japan
Specialized short-wave infrared camera supply concentrates among Japanese component suppliers, creating lead time exposure for equipment OEMs. METI industrial policy supports domestic recycling infrastructure development. Osaka-area engineering clusters contribute detector array manufacturing capacity serving regional equipment demand.
Vietnam
Drafting extended producer responsibility frameworks modeled on EU structures creates first-mover opportunity for equipment suppliers. The country's national environmental regulator develops recycling rate mandates for packaging waste. Ho Chi Minh City industrial zones attract regional service network establishment by international equipment vendors.
Plastic Waste Sorting Equipment Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered market positions. The vendor base organizes around three strategic archetypes: sensor technology leaders, integrated line providers, and regional fabrication specialists. Consolidated waste management operators with secured municipal contracts favor premium-tier suppliers, while independent recyclers on thin commodity margins seek modular configurations. Dominant competitive moves include performance-based service contracts displacing traditional capex procurement and geographic expansion into underpenetrated Southeast Asian markets.
Among European engineering specialists, TOMRA Systems ASA and Sesotec GmbH represent the sensor-technology archetype, while Vecoplan AG exemplifies integrated line provision. These three anchors demonstrate how German and Austrian engineering bases concentrate expertise in hyperspectral imaging calibration and pneumatic ejector alignment. Wastequip occupies a position within the North American fabrication tier. SSI Shredding Systems Inc and Eldan Recycling A/S sit within the specialized shredding and recycling equipment segment. EREMA exemplifies the Austrian engineering tradition in plastics processing systems.
| Leading Market Players |
|---|
| Wastequip |
| Sesotec GmbH |
| TOMRA Systems ASA |
| SSI Shredding Systems Inc |
| Eldan Recycling A/S |
| EREMA |
| Vecoplan AG |
| Geording Machinery |
| Terex Corporation |
| Others |
Value Network & Pricing Analysis
German and Austrian electro-optical technician workforces concentrate the specialized skills for hyperspectral imaging calibration and pneumatic ejector alignment, creating labor-cost differentials that widen pricing spreads between premium sensor-integrated systems and economy-tier mechanical alternatives. This workforce geography forces equipment OEMs to absorb 16–24 week lead time volatility for indium gallium arsenide detector arrays, compressing margins on mid-tier offerings while consolidated waste management operators capture scale economies in procurement.
Pricing Analysis
Performance-based service contracts versus traditional capex procurement splits the market into bundled and unbundled service structures. Three-tier pricing structure across premium, standard, and economy levels differentiates by purity threshold certification and after-sales service intensity. Cost compression in the standard tier is intensifying because optical component supply concentration exposes OEMs to detector array shortages. Independent recyclers operating on thin commodity margins exhibit highest price sensitivity, while municipal MRFs under California's SB 54 mandates demonstrate lowest sensitivity due to compliance-driven procurement timelines.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand from consolidated waste management operators, while regional fabrication specialists serve mid-scale recyclers through distributor networks. Component supply draws from Germany, Japan, and Austria for indium gallium arsenide detector arrays and specialized short-wave infrared cameras. Raw material dependencies include optical-grade glass, precision-machined aluminum framing, and industrial pneumatic systems. Single-source vulnerability in Japanese short-wave infrared camera supply creates exposure for equipment OEMs serving North American municipal contracts. Distribution runs through authorized service networks with embedded technical support for hyperspectral system maintenance.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in plastic waste sorting equipment hinges on automation-driven labor cost reduction and the shift toward premium-tier food-grade polymer recovery systems. This dynamic rewards suppliers who can guarantee 95 percent purity thresholds through embedded spectroscopic audit trails.
For Market Incumbents: Hedge against robotics-integrated sorting disruption by acquiring computer vision capabilities or forming technology partnerships with AI-guided picking specialists. Defensive consolidation of regional service networks in Vietnam and Indonesia protects first-mover positioning as extended producer responsibility frameworks emerge. Capacity addition in Southeast Asian manufacturing clusters reduces exposure to German-Austrian workforce bottlenecks.
For New Entrants and Emerging Players: The 40–60 percent price-point gap between premium sensor-based systems and economy-tier air classifiers opens white-space opportunity in modular 2–5 ton per hour optical sorters for regional recyclers. Vietnam's drafting EPR framework and Indonesia's packaging waste mandates represent the most penetrable geographies. A go-to-market angle anchored on performance-based service contracts with guaranteed purity terms differentiates against incumbent capex-heavy sales cycles.
For Investors and Strategic Acquirers: Waste management companies with consolidated municipal contract portfolios are the most active acquirer in this space, seeking vertical integration into sorting technology to secure operational control. Long-term viability over a 5–10 year window favors targets with embedded spectroscopic data logging for REACH compliance traceability. The signal to watch is regulatory tightening on recycled content quotas in additional U.S. states beyond California, which would accelerate equipment replacement cycles.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Detector Array Supply | Reduces 16–24 week lead time exposure from German and Japanese optical component suppliers. |
| Performance-Based Service Contract Expansion | Captures municipal MRF demand in California and New York under opex-favorable procurement models. |
| Southeast Asian Regional Service Network Buildout | Establishes first-mover positioning in Vietnam, Indonesia, and Thailand as EPR frameworks finalize. |
| AI-Guided Robotic Picking Integration | Opens municipal solid waste applications previously uneconomical for sensor-based detection systems. |
| Embedded Spectroscopic Audit Trail Development | Meets REACH compliance requirements for recycled content traceability in European installations. |
Research Methodology
Bottom-up recycling facility and waste management company modeling reconciled against top-down equipment OEM production tracking forms the analytical core of this study. Primary interviews with plant engineers at mechanical recyclers, procurement leads at municipal MRFs, aftermarket service heads at equipment distributors, and technical R&D directors at sensor technology suppliers combined with secondary validation from SEC filings, customs and trade data, EPA landfill diversion reports, and EU Green Deal implementation tracking. This triangulation ensures installed capacity estimates align with purity threshold achievement rates across regulatory jurisdictions.
Input-output matrices map polymer feedstock volumes through detection technology deployment rates, with segmentation across product type, technology modality, end-user category, and capacity tier. CAGRs derive from regression analysis of historical equipment shipments against regulatory deadline schedules and purity standard escalations. Forecast inputs include MEE import purity standard enforcement intensity in China, SB 54 recycled content mandate compliance trajectories in California, and EU Green Deal recycling rate milestone achievement patterns across member states.
The model assumes a particular technology adoption path; alternative pathways for laser-induced breakdown spectroscopy penetration in black plastic detection would alter the outlook. Forecasts reflect base-case assumptions regarding optical component supply normalization and electro-optical technician training pipeline expansion. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Equipment
Stretch Wrappers Market
Packaging Equipment
Strapping Devices Market
Packaging Equipment
Nitrogen Filling Systems Market
Packaging Equipment
Tissue Roll Unwinders Market
Packaging Equipment
Diaper Packaging Machines Market
Packaging Equipment
Thermal Impulse Sealers Market
Packaging Equipment
Hydrapulper Market
Packaging Equipment
Global Reverse Vending Machine Market
Packaging Equipment
Shrink Wrapper Market
Packaging Equipment
Ancillary Packaging Equipment Market
Packaging Equipment
Global Cap Applicators Market
Packaging Equipment
Global End-Of-Line Packaging Market
Packaging Equipment
Global 2-Shot Injection Molding Market
Packaging Equipment
Aerosol Dispensing Systems Market
Packaging Equipment
Semi-Automatic and Manual Filling Equipment Market
Packaging Equipment
Hang Tag Applicators Market