
 Warming Cabinet Market | 2026-2036
Warming Cabinet Market Size, Share, and Industry Trends Forecast 2026-2036
Warming Cabinet Market Intelligence
Hospital procurement channels for warming cabinets is fragmenting as group purchasing organizations lose leverage to direct manufacturer contracts and specialty surgical distributors. STERIS leverages its integrated infection control portfolio to bundle warming systems with sterilization workflows. MAC Medical competes through stainless-steel fabrication specialization and custom sizing for orthopedic suites. Getinge AB anchors its position via R&D intensity in patient temperature management across its broader critical care portfolio.
A warming cabinet is an enclosed heated storage unit designed to maintain blankets, intravenous fluids, or surgical irrigation solutions at controlled temperatures typically between 90°F and 200°F depending on content type; construction centers on insulated steel chambers with forced-air or radiant heating elements, digital thermostats, and overtemperature safety cutoffs. Floor-standing units dominate hospital central supply departments due to capacity requirements, while countertop configurations capture outpatient surgical center demand where space constraints dictate form factor. Electric technology leads the installed base for precision and regulatory compliance, though combination heating systems are gaining traction in high-throughput catering environments where load flexibility matters.
FDA 510(k) premarket notification governs medical warming cabinets in the United States, requiring substantial equivalence demonstrations that extend development timelines and favor incumbents with regulatory dossier libraries. The EU Medical Device Regulation imposes post-market surveillance and unique device identification mandates that reshape documentation burdens for CE-marked products sold across member states. Stakeholders must monitor evolving energy efficiency standards from the Department of Energy and state-level hospital sustainability mandates that threaten to disqualify older heating element designs from new construction specifications.
Market Dynamics
Hospital surgical units are consolidating temperature management equipment procurement under infection control capital budgets rather than standalone medical device purchases, reshaping vendor relationships and specification priorities across the installed base.
Growth Catalysts
- Ambulatory Surgical Center Expansion:United States Medicare reimbursement changes favor outpatient procedures, driving countertop warming cabinet demand in facility buildouts across Texas, Florida, and Arizona markets.
- FDA 510(k) Pathway Refinement:Streamlined substantial equivalence reviews for fluid warming devices reduce time-to-market for manufacturers with established predicate device libraries.
- Perioperative Hypothermia Protocol Mandates:Joint Commission accreditation standards now require active patient warming documentation, compelling surgical departments to upgrade blanket warming infrastructure.
Market Restraints
- Stainless Steel Input Volatility:Medical-grade 304 and 316 stainless steel price swings compress fabrication margins for cabinet chamber manufacturers dependent on Asian mill supply.
- Heating Element Supply Concentration:Forced-air and radiant element production clusters in German and Japanese component houses create single-source vulnerability for North American cabinet assemblers.
- EU MDR Documentation Burden:Post-market surveillance and unique device identification requirements extend CE marking timelines and strain regulatory affairs staffing at mid-tier manufacturers.
Strategic Opportunities
- India Operating Room Modernization:Government hospital infrastructure programs under Ayushman Bharat create first-time specification opportunities for fluid warming systems in tier-2 and tier-3 cities.
- Combination Heating Platforms:Dual-mode radiant and convection systems enable single-cabinet flexibility for alternating blanket and irrigation solution loads, appealing to mixed-use surgical suites.
- Direct Manufacturer Contracting:Bypassing group purchasing organization fee structures allows vendors to capture margin and offer extended service agreements to IDN procurement departments.
Industry Challenges
- Biomedical Engineering Talent Scarcity:Hospital in-house service departments lack technicians trained on digital thermostat calibration and overtemperature cutoff validation, forcing reliance on manufacturer field service.
- Legacy HVAC Integration:Older hospital central supply departments require electrical and ventilation retrofits to accommodate high-capacity floor-standing units, extending installation timelines and capital planning cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Warming Cabinet Market |
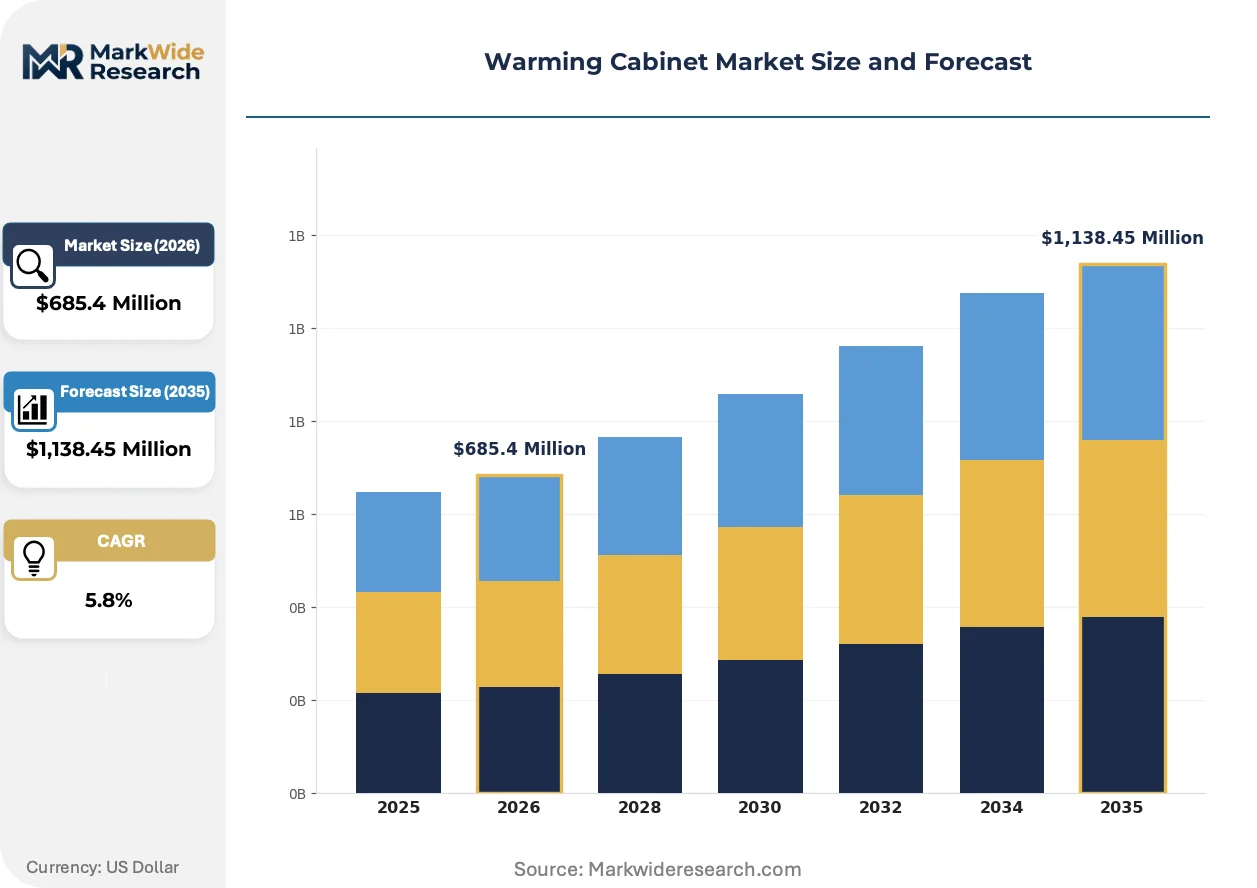
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,138.45 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Countertop, Floor-standing, Wall-mounted, Modular Technology: Electric, Gas, Combination, Induction Application: Restaurants, Catering, Healthcare, Retail End User: Hospitality, Food Service, Clinical, Household |
| Companies Covered | STERIS, MAC Medical, Blickman, Continental Metal Products, Skytron, Pedigo Products, Getinge AB, Enthermics, Barkey, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Warming Cabinet Market Strategic Shifts & Innovations
Forced-air precision control systems are displacing conventional bimetallic thermostats in next-generation warming cabinets, enabling tighter temperature bands and automated logging that satisfies evolving accreditation documentation requirements.
Silicon-controlled rectifier heating modules with PID feedback loops maintain set points within tighter tolerances than electromechanical thermostats. Academic medical centers in Massachusetts and California specify these modules for research protocol compliance. Conventional bimetallic control systems are rendering obsolete in new construction specifications.
EU Medical Device Regulation post-market surveillance mandates require warming cabinet manufacturers to maintain clinical follow-up databases and periodic safety update reports. This documentation burden favors incumbent firms with established quality management systems. Small and mid-tier manufacturers are consolidating or exiting the CE-marked product segment rather than absorbing compliance costs.
Integrated service contracting now bundles warming cabinet maintenance with sterilizer and washer-disinfector coverage under single-source infection control equipment agreements. Hospital procurement departments in the United States Midwest and Southeast are consolidating vendor relationships. Specialty surgical distributors lose attach rates as manufacturers disintermediate through direct field service organizations.
Warming Cabinet Market Segmentation
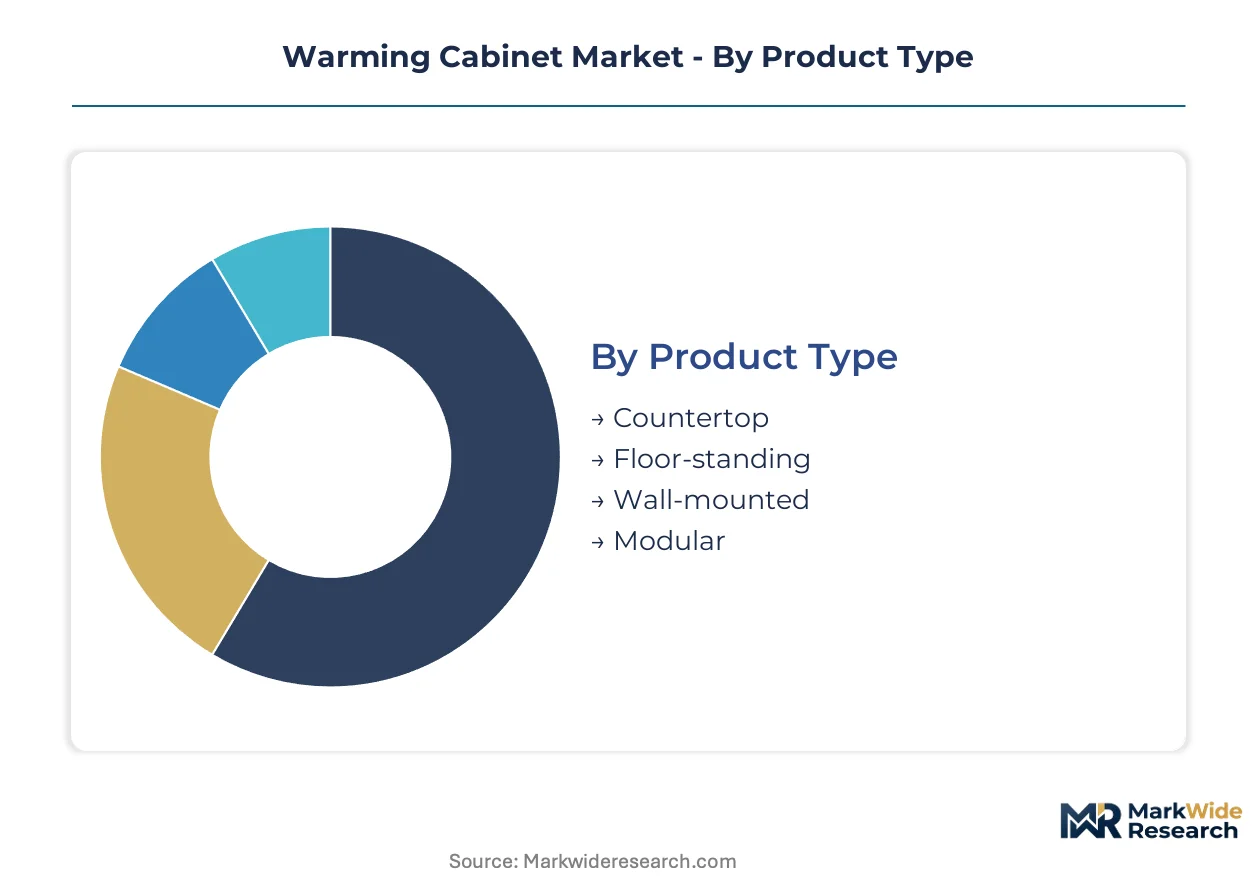
Warming cabinet procurement patterns diverge sharply across product configurations and end-use environments. Surgical departments prioritize regulatory compliance and temperature precision, while food service operators emphasize throughput capacity and energy efficiency.
Product Type:
Mature floor-standing designs dominate hospital central supply installations, while emerging countertop formats capture ambulatory surgical center buildouts.
- Countertop:Compact units with 2-6 cubic foot capacity utilize forced-air circulation and digital thermostats for space-constrained environments. Demand concentrates in United States ASCs across Texas and Florida markets driven by Medicare outpatient reimbursement expansion.
- Floor-standing:High-capacity insulated steel chambers with 15-30 cubic foot storage accommodate bulk blanket and fluid warming in hospital surgical suites. These units require 220V electrical infrastructure and HVAC integration that extends installation timelines in aging United States facilities.
- Wall-mounted:Space-saving configurations with swing-door access suit corridor installations in European hospital ward renovations.
- Modular:Stackable component systems enable capacity scaling for multi-procedure days in German and Japanese academic medical centers.
Floor-standing retains volume leadership; countertop holds the steepest expansion curve.
Technology:
Cost tiers separate precision-controlled electric systems from emerging combination platforms offering load flexibility.
- Electric:Silicon-controlled rectifier modules with PID feedback loops maintain temperature bands within tighter tolerances than electromechanical alternatives. Massachusetts and California academic medical centers specify these for research protocol compliance.
- Combination:Dual-mode radiant and convection heating enables single-cabinet flexibility for alternating blanket and irrigation solution loads. Mixed-use surgical suites in India and Brazil adopt these to reduce capital equipment counts.
- Gas:Propane and natural gas systems persist in mobile catering applications where electrical infrastructure is unavailable.
- Induction:Electromagnetic heating elements offer rapid warm-up cycles for high-turnover food service environments in Middle Eastern hospitality sectors.
Electric commands the premium tier; combination platforms are climbing fastest in mid-market penetration.
Application:
Volume concentration splits between clinical compliance requirements and food service throughput demands.
- Healthcare:Perioperative hypothermia prevention protocols mandate active patient warming documentation under Joint Commission standards. United States hospital surgical units upgrade blanket warming infrastructure to maintain accreditation.
- Catering:High-volume banquet operations require rapid thermal recovery and humidity control for plated meal holding. Indian wedding catering markets and Middle Eastern hospitality events drive specification.
- Restaurants:Fine-dining establishments in France and Italy utilize compact warming cabinets for sauce and protein staging during service rushes.
- Retail:Prepared food sections in United States grocery chains deploy countertop units for rotisserie chicken and hot bar maintenance.
Healthcare anchors value concentration; catering delivers the steepest volume expansion.
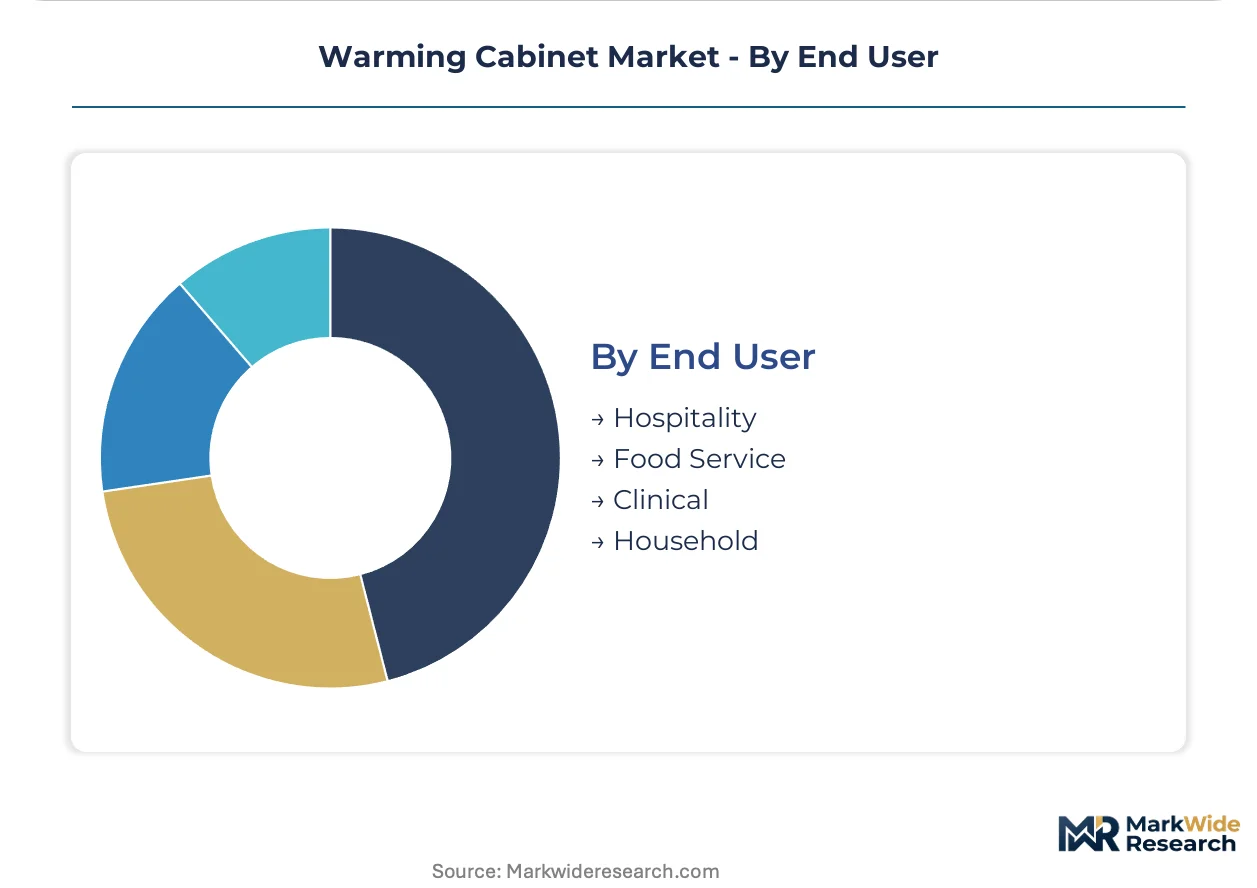
End User:
Customer type determines specification priority, from clinical temperature precision to hospitality operational efficiency.
- Clinical:Hospital biomedical engineering departments demand FDA 510(k) cleared devices with overtemperature safety cutoffs and calibration documentation. United States integrated delivery networks consolidate procurement under infection control capital budgets.
- Food Service:Contract catering operators prioritize energy efficiency certifications and rapid service response. European Union energy efficiency standards from the Department of Energy threaten to disqualify older heating element designs from new construction specifications.
- Hospitality:Hotel banquet departments in Dubai and Singapore specify aesthetic finishes matching kitchen design schemes.
- Household:Consumer-grade countertop units with simplified controls serve home healthcare and residential care settings in Japan and South Korea.
Clinical commands specification intensity; food service generates the broadest installed base expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Hamburg's medical device logistics corridor underwrites Germany's distribution dominance for European warming cabinet supply chains. Rail links from Rotterdam to Milan enable rapid component transit for stainless steel chassis fabrication. The Suez Canal route connects Indian surgical equipment manufacturers to Middle Eastern hospital procurement channels.
United States
Ambulatory surgical center buildouts across Texas and Florida drive countertop warming cabinet specifications. FDA 510(k) premarket notification requirements tighten validation protocols for electric heating module designs. The Boston-Cambridge medical device cluster anchors R&D activity for PID-controlled temperature management systems.
Germany
Academic medical centers in Bavaria and Baden-Württemberg specify precision-controlled warming systems for research protocol compliance. EU Medical Device Regulation post-market surveillance mandates reshape documentation burdens for CE-marked manufacturers. The Stuttgart industrial basin concentrates forced-air heating element production for cabinet assembly.
India
Government hospital infrastructure programs under Ayushman Bharat create first-time specification opportunities in tier-2 and tier-3 cities. Central Drugs Standard Control Organization medical device regulations establish import substitution incentives for domestic manufacturers. The Pune-Nashik manufacturing corridor attracts stainless steel fabrication investment for orthopedic suite equipment.
Japan
Aging hospital infrastructure replacement cycles drive demand for modular warming systems in Tokyo and Osaka metropolitan areas. Ministry of Economy, Trade and Industry energy efficiency standards disqualify older heating element designs from new construction specifications. The Nagoya medical device cluster specializes in compact countertop configurations for space-constrained surgical suites.
United Arab Emirates
Dubai and Abu Dhabi hospital construction booms specify aesthetic-finish warming cabinets matching premium kitchen design schemes. Ministry of Health and Prevention medical device registration requirements streamline Gulf Cooperation Council market access for approved manufacturers. The Jebel Ali Free Zone anchors regional distribution for European and Asian equipment suppliers.
Warming Cabinet Market Key Industry Players
On the supply side, the industry is consolidating around integrated infection control portfolios and specialized stainless steel fabrication capabilities. Tiered competitive positioning separates premium precision-control vendors from mid-market capacity providers. Strategic archetypes include bundled sterilization workflow suppliers, custom orthopedic suite fabricators, and critical care portfolio anchors. Dominant competitive moves encompass direct manufacturer contracting to bypass group purchasing organizations and R&D intensity in patient temperature management systems.
Within the integrated portfolio tier, STERIS exemplifies bundled infection control equipment positioning. Among specialized fabricators, MAC Medical occupies a position emphasizing stainless steel construction customization. At the critical care systems end, Getinge AB anchors a broader patient temperature management portfolio spanning warming cabinets through critical care monitors.
| Leading Market Players |
|---|
| STERIS |
| MAC Medical |
| Blickman |
| Continental Metal Products |
| Skytron |
| Pedigo Products |
| Getinge AB |
| Enthermics |
| Barkey |
| Others |
Cost & Logistics Intelligence
Undercapacity in forced-air heating element fabrication across German and Japanese component houses is tightening supplier pricing power and extending lead times for North American cabinet assemblers. This utilization squeeze feeds into tiered procurement contracts where integrated delivery networks absorb cost pass-throughs more readily than independent ambulatory surgical centers.
Pricing Analysis
Volume-discount tiering structures separate enterprise procurement agreements from spot purchases by standalone surgical facilities. Pricing stratifies across FDA 510(k) cleared premium systems, CE-marked standard configurations, and uncertified economy units for non-clinical applications. Cost compression in the mid-tier is intensifying because stainless steel input volatility from Asian mills compresses fabrication margins. Independent ambulatory surgical centers exhibit the highest price sensitivity, while United States integrated delivery networks prioritize total cost of ownership over unit pricing.
Supply Chain Analysis
Tariff exposure between United States and Chinese stainless steel suppliers dominates supply chain risk planning for cabinet chamber manufacturers. Component sourcing draws from Germany for precision heating elements, Japan for PID control modules, and China for medical-grade 304 stainless steel mill products. Single-source vulnerability concentrates in forced-air element production clustered around Stuttgart and Nagoya industrial basins. Distribution runs through specialty surgical distributors losing share to direct manufacturer field service organizations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The warming cabinet market is undergoing high-growth disruption as EU MDR post-market surveillance mandates and FDA 510(k) pathway refinements simultaneously elevate compliance burdens and accelerate incumbent consolidation.
For Market Incumbents: Pre-empt regulatory dossier gaps by investing in clinical follow-up database infrastructure before EU MDR periodic safety update report deadlines. Capture margin recovery through direct contracting with United States integrated delivery networks, bypassing group purchasing organization fee structures that erode pricing power. Vertical integration into stainless steel fabrication insulates against Asian mill price volatility threatening mid-tier profitability.
For New Entrants and Emerging Players: Establish a beachhead in India's tier-2 and tier-3 city hospital infrastructure programs under Ayushman Bharat, where first-time specification opportunities outpace mature market replacement cycles. Target combination heating platform segments in mixed-use surgical suites across Brazil and India, where capital equipment count reduction drives purchasing decisions. Pursue private-label partnerships with European distributors seeking CE-marked alternatives as small manufacturers exit compliance-heavy segments.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across EU MDR compliance infrastructure as quality management system investments become table stakes for market access. Long-term viability favors targets with established FDA 510(k) predicate device libraries and integrated infection control equipment bundling capabilities. Watch for CDSCO import substitution policy acceleration in India as the signal indicating domestic manufacturing joint venture attractiveness.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Clearance Expansion | Substantial equivalence demonstrations accelerate time-to-market for manufacturers with predicate libraries. |
| Direct Manufacturer Contracting | Bypassing group purchasing organizations captures margin and enables extended service agreement bundling. |
| Combination Heating Platform Development | Dual-mode radiant and convection systems reduce capital equipment counts in mixed-use surgical suites. |
| EU MDR Quality System Investment | Post-market surveillance infrastructure separates viable CE-marked competitors from exiting mid-tier firms. |
| India Domestic Manufacturing Partnership | CDSCO import substitution incentives under Ayushman Bharat create localization advantages for joint ventures. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted across hospital biomedical engineering departments, ambulatory surgical center procurement managers, group purchasing organization contract specialists, and stainless steel fabrication plant engineers. Secondary validation drew from FDA 510(k) premarket notification databases, EU MDR technical documentation filings, hospital capital equipment procurement records, and stainless steel trade flow customs data. Bottom-up unit shipment estimates triangulated against top-down infection control capital spending analysis.
Calibration against historical regulatory approval timelines and replacement cycle patterns anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include product configuration, heating technology type, application environment, and end-user procurement channel. CAGRs derived from installed base growth rates and average selling price trajectory assumptions. Industry-specific inputs encompassed Joint Commission accreditation standard evolution and Medicare outpatient reimbursement policy shifts.
Stress conditions across stainless steel price volatility, heating element supply disruption, and regulatory timeline extension were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding ambulatory surgical center buildout rates and EU MDR enforcement consistency. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
HVAC Equipment
Ventilation Equipment Market
HVAC Equipment
Blowers Market
HVAC Equipment
Equipment Fan Filter Unit (EFU) Market
HVAC Equipment
Strip Warmer Market
HVAC Equipment
Europe Residential Fan Coil Convectors Market
HVAC Equipment
Linear Slot Diffuser Market
HVAC Equipment
Industrial Ventilation Equipment Market
HVAC Equipment
Industrial Heating Equipment Market
HVAC Equipment
Global Split Systems Market
HVAC Equipment
Europe Dehumidifier Market
HVAC Equipment
US Residential HVAC Systems Market
HVAC Equipment
United Kingdom Heating Equipment Market
HVAC Equipment
Steam Boiler Systems Market
HVAC Equipment
Canada HVAC Equipment Market
HVAC Equipment
United States Residential Heating Equipment Market
HVAC Equipment
Compressor Controllers Market