
 Europe Heat Shrink Tubing for Automotive Market | 2026-2036
Europe Heat Shrink Tubing for Automotive Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Heat Shrink Tubing for Automotive Market Foresight
Tier-1 supplier consolidation is recalibrating procurement leverage across the European automotive supply base. TE Connectivity leverages extensive cross-border manufacturing footprints to sustain volume commitments to consolidated harness makers. HellermannTyton anchors its position through specialized adhesive-lined formulations that dominate connector insulation specifications. RADPOL S.A. competes on proximity, operating captive production facilities within Poland that feed Central European vehicle assembly corridors.
Heat shrink tubing for automotive applications comprises cross-linked polymeric sleeves that contract radially when exposed to controlled thermal energy, typically achieving shrink ratios between two-to-one and four-to-one depending on base polymer and wall architecture. The material permanently conforms to substrate contours, delivering dielectric insulation, mechanical strain relief, and environmental sealing against moisture, chemicals, and abrasion in underhood and chassis environments. Dual-wall constructions command margin premiums because adhesive inner layers resolve permeation failures in high-voltage electric vehicle architectures where single-wall alternatives prove inadequate. Polyolefin formulations lead volume shipments across wiring harness and cable protection applications, while fluoropolymer grades capture niche value pools in thermal extremes near power electronics and battery thermal management circuits.
REACH restrictions on halogenated flame retardants and the EU Green Deal's embedded carbon thresholds are forcing reformulation timelines across European compounders. ECHA substance evaluations now directly influence automotive OEM material approval lists, with non-compliant tubing variants losing platform qualification. The F-Gas Regulation indirectly shapes demand by accelerating heat pump integration into electric vehicle thermal systems, expanding the temperature range specifications that tubing must satisfy. Stakeholders must monitor pending MDR-aligned durability testing standards that threaten to obsolete current thin-wall product lines if adopted into automotive supplier quality agreements.
Market Dynamics
REACH chemical restrictions and the EU Green Deal's embedded carbon thresholds are forcing compounders to reformulate halogenated flame retardants out of automotive polymer grades, with ECHA substance evaluations now directly determining OEM material approval lists.
Growth Catalysts
- 800V Electric Vehicle Architectures:High-voltage wiring harness specifications now mandate dual-wall adhesive-lined tubing to prevent ionic permeation failures in battery electric vehicle powertrains.
- F-Gas Regulation:Heat pump integration into electric vehicle thermal management systems expands operating temperature ranges, requiring fluoropolymer grades near power electronics.
- Poland:Central European vehicle assembly corridors draw captive tubing production facilities that shorten lead times for harness makers supplying Volkswagen Group and Stellantis plants.
Market Restraints
- Raw Material Volatility:Cross-linking agent prices fluctuate with European natural gas benchmarks, compressing compounder margins during energy price spikes.
- Supplier Concentration:Three German chemical groups control the majority of radiation cross-linking capacity for automotive-grade polyolefin, creating single-source risk for Tier-2 processors.
- Thin-Wall Technical Limits:Current single-wall constructions fail emerging durability testing standards aligned with EU Medical Device Regulation methodologies.
Strategic Opportunities
- Italy:Premium sports car and supercar manufacturers in Emilia-Romagna represent underserved demand for high-temperature silicone tubing in exhaust-adjacent harness routing.
- CSRD Reporting Mandates:Corporate Sustainability Reporting Directive disclosure requirements create pull for bio-based polyolefin formulations with verified carbon footprint data.
- Recycling Convergence:Mechanical and chemical recycling technology maturation enables closed-loop tubing recovery from end-of-life vehicle wiring harnesses.
Industry Challenges
- Polymer Science Talent Gap:European compounders struggle to recruit formulation chemists with expertise in non-halogenated flame retardant systems.
- MDR-Aligned Certification Timelines:Pending automotive supplier quality agreements incorporating medical-grade durability testing threaten eighteen-month platform requalification cycles.
- Legacy Harness Integration:Dual-wall tubing's thicker wall profile conflicts with space-constrained internal combustion engine bay architectures still serving hybrid transition volumes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Heat Shrink Tubing for Automotive Market |
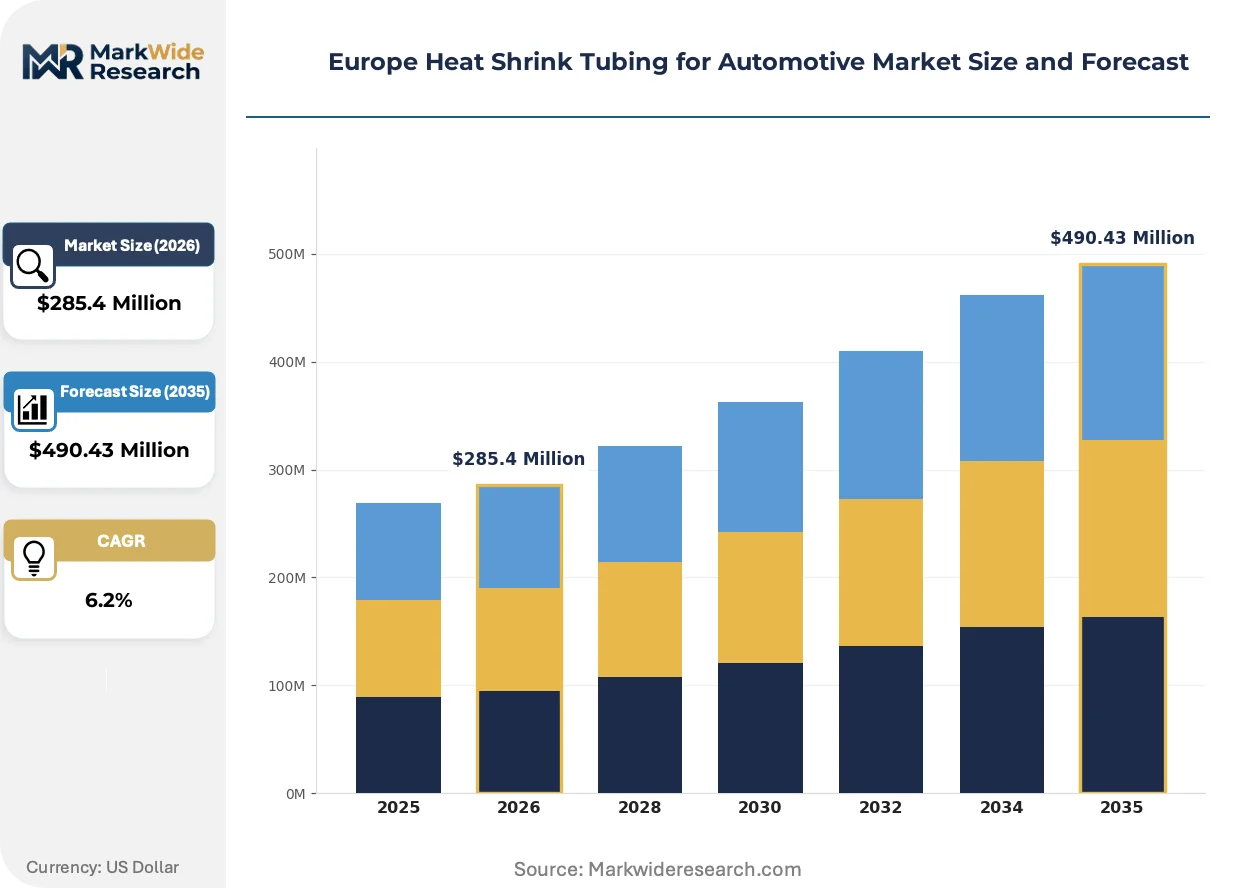
| Market Size in 2026 | $285.4 Million |
| Market Size in 2035 | $490.43 Million |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-Wall, Dual-Wall, Adhesive-Lined, Thin-Wall Material: Polyolefin, PVC, Fluoropolymer, Nylon Application: Wiring Harness, Cable Protection, Connector Insulation, Environmental Sealing End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Vehicle Assemblers |
| Companies Covered | TE Connectivity, 3M, Molex, ABB, HellermannTyton, Sumitomo Electric Industries, SHAWCOR, RADPOL S.A., GREMCO GmbH, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Heat Shrink Tubing for Automotive Market Shifts & Advancements
Material science advancement and regulatory chemistry restrictions are converging to reshape European automotive tubing specifications. Three developments dominate the current transformation.
Dual-wall adhesive-lined constructions are absorbing the bulk of innovation investment as electric vehicle OEMs confront high-voltage isolation failures. Battery pack manufacturers specify these formulations for 800V busbar protection, accepting the 40% material cost premium over single-wall alternatives. The technology is absorbing market share from basic polyolefin grades in powertrain applications while compressing adoption timelines for next-generation thermal management circuits.
REACH Annex XIV authorization requirements are systematically removing brominated flame retardants from automotive polymer supply chains. ECHA's 2023-2024 substance evaluations added three halogenated compounds to the candidate list, triggering immediate reformulation mandates from German OEM material engineering departments. Tier-1 harness suppliers in France and Italy now require compounders to submit full substance declarations before platform qualification, with non-compliant variants removed from approved vendor lists within six-month windows.
Direct contracting between OEM material engineering teams and specialized tubing compounders is displacing traditional distributor-mediated procurement in high-voltage segments. Harness makers serving Stellantis and BMW Group now source critical dual-wall grades through approved compounder relationships rather than broadline electrical distributors. This pattern concentrates most visibly in Germany and the Czech Republic, where vehicle assembly plants operate within 300-kilometer radii of cross-linking facilities.
Europe Heat Shrink Tubing for Automotive Market Segmentation
Segmentation in the European automotive heat shrink tubing market reveals how regulatory chemistry restrictions and electrification architectures split demand across incompatible technical specifications. Material approval requirements from ECHA and OEM engineering departments create divergent compliance burdens that reshape procurement patterns across each category.
Product Type:
REACH substance restrictions and platform qualification timelines impose distinct certification loads across wall architectures, with high-voltage applications demanding the most rigorous documentation.
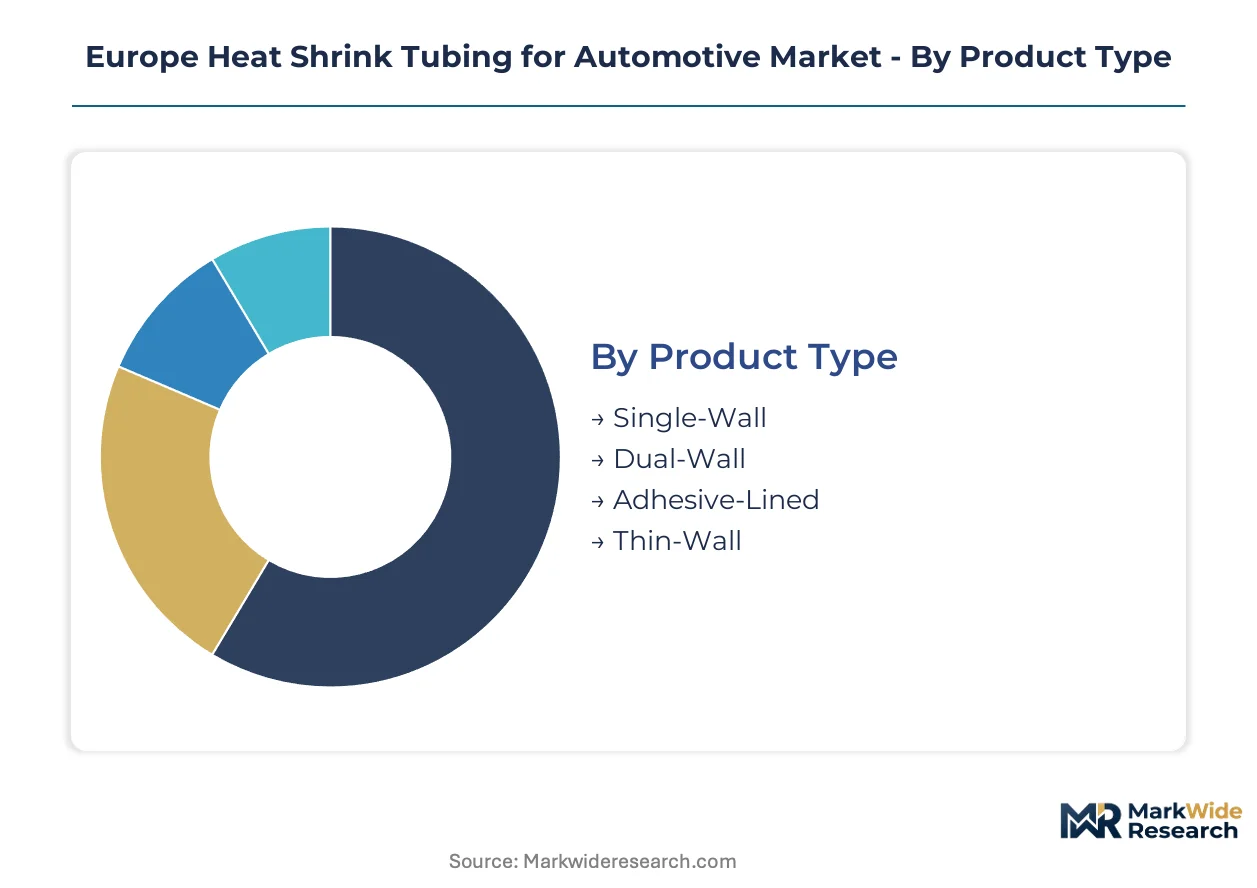
- Single-Wall:Basic polyolefin constructions dominate legacy internal combustion engine harness volumes across German and French vehicle plants. Cost-sensitive procurement from Stellantis and Renault Group assembly corridors sustains this segment despite thinning margins.
- Dual-Wall:Adhesive-lined constructions incorporate meltable inner layers that activate during heat application to form permanent environmental seals. Battery electric vehicle powertrain specifications in the Czech Republic and Slovakia now mandate these formulations for 800V busbar protection against ionic permeation failures.
- Adhesive-Lined:Specialized formulations command qualification premiums from BMW Group and Mercedes-Benz material engineering teams for connector insulation in thermal management circuits. ECHA substance declarations now required before platform approval.
- Thin-Wall:Space-constrained architectures in hybrid transition vehicles favor reduced wall profiles, though pending MDR-aligned durability testing threatens segment viability.
Leading the category by volume: Single-Wall. Growing fastest: Dual-Wall.
Material:
Raw material sourcing geography and cross-linking infrastructure concentration in Germany and Poland determine which polymer families capture platform share.
- Polyolefin:Radiation cross-linked grades anchor volume shipments across standard wiring harness applications. Three German chemical groups control the majority of European cross-linking capacity, concentrating supply risk for Tier-2 processors serving Volkswagen Group plants.
- Fluoropolymer:PTFE and FEP grades withstand thermal extremes near power electronics and battery thermal management circuits. Heat pump integration under the F-Gas Regulation expands addressable demand in premium electric vehicle segments assembled in Germany and the Netherlands.
- PVC:Cost-driven formulations retain position in aftermarket cable protection despite REACH pressure on plasticizer chemistries.
- Nylon:Abrasion-resistant grades serve chassis routing applications in commercial vehicle assembly corridors across Poland and Turkey.
Volume concentration: Polyolefin. Steepest expansion trajectory: Fluoropolymer.
Application:
Functional performance requirements and failure-mode consequences determine which tubing constructions qualify for each use case.
- Wiring Harness:Bundle protection across powertrain, body, and chassis domains consumes the majority of regional tubing volume. Dual-wall specifications now mandatory for high-voltage segments in battery electric vehicles produced in Germany and Hungary.
- Cable Protection:Abrasion and chemical resistance specifications vary by vehicle zone, with underhood applications demanding fluoropolymer grades near exhaust components in Italian premium sports car manufacturing.
- Connector Insulation:Dielectric isolation requirements tighten as operating voltages climb, favoring adhesive-lined constructions with documented ECHA compliance.
- Environmental Sealing:Moisture ingress prevention specifications now incorporate medical-grade durability testing methodologies under pending supplier quality agreements.
Dominant application: Wiring Harness. Gaining share fastest: Environmental Sealing.
End User:
Procurement leverage and technical specification authority vary sharply across the automotive supply chain hierarchy.
- OEMs:Volkswagen Group, BMW Group, and Mercedes-Benz material engineering teams now direct-contract specialized compounders for high-voltage grades, bypassing traditional distribution channels.
- Tier-1 Suppliers:Harness makers serving Stellantis and Renault Group consolidate procurement volumes to extract pricing concessions from cross-linking facilities within 300-kilometer radii of assembly plants.
- Aftermarket Providers:Independent distributors stock standard polyolefin grades for repair and maintenance demand across European vehicle parc.
- Vehicle Assemblers:Contract manufacturers in Central European corridors operate captive tubing inventories to synchronize with just-in-sequence harness delivery.
Procurement volume leader: Tier-1 Suppliers. Expanding most quickly: OEMs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
European automotive heat shrink tubing procurement concentrates in vehicle assembly corridors spanning Germany, France, and Italy, with Central European manufacturing zones emerging as demand growth poles. Tier-1 harness suppliers locate captive inventory within 300-kilometer radii of major plants to synchronize just-in-sequence delivery.
Germany
Volkswagen Group, BMW Group, and Mercedes-Benz material engineering teams drive dual-wall tubing specifications for 800V electric vehicle architectures. REACH Annex XIV authorization requirements trigger immediate reformulation mandates from domestic OEMs. Cross-linking facilities in Bavaria and Baden-Württemberg anchor regional polyolefin supply.
France
Stellantis and Renault Group assembly plants sustain volume demand for standard polyolefin grades across hybrid transition vehicles. ECHA substance evaluations now determine approved vendor list status for compounders serving French harness makers. Industrial clusters around Paris-Saclay and Lyon house specialized connector insulation suppliers.
Italy
Premium sports car manufacturers in Emilia-Romagna generate underserved demand for high-temperature silicone tubing in exhaust-adjacent harness routing. EU Green Deal embedded carbon thresholds pressure compounders serving Ferrari and Lamborghini supply chains. Turin-based engineering centers influence thermal management circuit specifications.
Poland
Central European vehicle assembly corridors draw captive tubing production facilities that shorten lead times for Volkswagen Group and Stellantis plants. RADPOL S.A. operates radiation cross-linking capacity feeding regional harness demand. Lower Silesia and Greater Poland voivodeships concentrate Tier-2 processor activity.
Czech Republic
Battery electric vehicle powertrain specifications now mandate dual-wall adhesive-lined tubing for 800V busbar protection at Hyundai and Škoda Auto plants. F-Gas Regulation compliance accelerates heat pump integration into thermal management systems. Industrial zones around Mladá Boleslav and Nošovice anchor high-voltage harness assembly.
Europe Heat Shrink Tubing for Automotive Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue specialized high-voltage formulations and bio-based material platforms. Market structure reflects moderate consolidation around radiation cross-linking capacity controlled by German chemical groups. Three strategic archetypes dominate: diversified electrical component conglomerates, specialized polymer compounders with captive cross-linking assets, and regional processors serving single OEM ecosystems. Competitive moves concentrate on direct contracting relationships bypassing distribution channels and backward integration into cross-linking capacity.
Among diversified electrical component suppliers, TE Connectivity exemplifies scale-driven positioning across European harness supply chains. Specialized polymer compounders with captive manufacturing footprints include HellermannTyton, which anchors connector insulation specifications through adhesive-lined formulation expertise. RADPOL S.A. occupies a position as a proximity-focused regional processor serving Central European vehicle assembly corridors. These three represent distinct competitive archetypes: global scale, technical specialization, and geographic adjacency.
| Leading Market Players |
|---|
| TE Connectivity |
| 3M |
| Molex |
| ABB |
| HellermannTyton |
| Sumitomo Electric Industries |
| SHAWCOR |
| RADPOL S.A. |
| GREMCO GmbH |
| Others |
Supply & Pricing Matrix
European natural gas benchmarks governing cross-linking agent costs cascade through polyolefin compounder margins into three distinct pricing tiers across automotive heat shrink tubing procurement. REACH compliance documentation requirements and ECHA substance declaration burdens concentrate premium capture among German chemical groups with captive radiation capacity, while price-sensitive harness makers serving Stellantis and Renault Group plants in France negotiate standard-grade contracts on volume commitments.
Pricing Analysis
Volume shipments of basic single-wall polyolefin constructions generate thin margins for compounders serving cost-driven hybrid vehicle programs, while dual-wall adhesive-lined formulations for 800V electric vehicle architectures sustain forty-percent material cost premiums at BMW Group and Mercedes-Benz. Price differentiation hinges on ECHA substance compliance certification and radiation cross-linking quality grade. Cost compression in standard polyolefin tiers is intensifying because Tier-1 harness suppliers consolidate procurement volumes within 300-kilometer radii of assembly plants. Aftermarket distributors exhibit highest price sensitivity; OEM direct-contracting segments show lowest.
Supply Chain Analysis
Direct-to-OEM channels handle high-voltage grade demand from Volkswagen Group and BMW Group material engineering teams, while broadline electrical distributors serve aftermarket and legacy harness replacement. Geographic supply concentrates in Germany, Poland, and the Czech Republic, with three German chemical groups controlling majority European radiation cross-linking capacity. Raw material sourcing draws from ethylene feedstock, peroxide cross-linking agents, and adhesive polymer resins. Single-source vulnerability pervades the Tier-2 processor tier dependent on German cross-linking facilities. Distribution runs through approved compounder relationships displacing traditional distributor mediation in high-voltage segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
REACH Annex XIV authorization requirements and ECHA substance evaluation timelines construct a formidable cost-of-compliance barrier that protects qualified compounders while excluding undercapitalized entrants from OEM approved vendor lists. The EU Green Deal's embedded carbon thresholds further deepen this moat through mandatory reformulation investments.
For Market Incumbents: Cement backward integration into radiation cross-linking capacity within Poland and the Czech Republic to defend against supply disruption risks from German chemical group concentration. Prioritize bio-based polyolefin formulation R&D to capture CSRD reporting mandate premiums from sustainability-driven OEM procurement teams.
For New Entrants and Emerging Players: Specialized adhesive compounders serving Italian premium sports car manufacturers in Emilia-Romagna represent the most penetrable white-space target for high-temperature silicone tubing formulations. Target direct contracting relationships with Stellantis harness makers seeking dual-wall alternatives to incumbent supply chains.
For Investors and Strategic Acquirers: The window for entry favors compounders with captive cross-linking assets and established ECHA compliance documentation. Long-term viability centers on consolidation plays in Central European corridors feeding Volkswagen Group and Stellantis assembly plants. Monitor pending MDR-aligned durability testing standard adoption as inflection indicator for thin-wall product line obsolescence risk.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cross-Linking Capacity | Captive radiation facilities in Poland and Czech Republic reduce dependency on German chemical group supply. |
| Bio-Based Polyolefin Formulation Development | CSRD reporting mandates from BMW Group and Mercedes-Benz create verified carbon footprint premiums. |
| Direct OEM Contracting Relationships | Bypassing electrical distributors concentrates margin capture in high-voltage 800V architecture segments. |
| REACH Compliance Certification Investment | ECHA substance declaration capabilities determine approved vendor list status across European OEMs. |
| Central European Manufacturing Footprint Expansion | Proximity to Volkswagen Group and Stellantis plants in Poland and Slovakia shortens just-in-sequence lead times. |
Research Methodology
Document review covered ECHA substance evaluation databases, EU Green Deal policy frameworks, and automotive OEM material engineering specifications, complemented by interviews with Tier-1 harness supplier procurement directors, radiation cross-linking facility plant managers, and polymer compounder technical R&D leads. Secondary validation drew from customs trade data, SEC filings of diversified electrical component suppliers, and vehicle production databases. Bottom-up volume modeling across product type, material, application, and end-user segments triangulated with top-down market sizing from regional production cluster analysis.
Segment-level outputs across the analysis window reflect discrete modeling of single-wall, dual-wall, adhesive-lined, and thin-wall constructions by polyolefin, fluoropolymer, PVC, and nylon material families. CAGRs were derived from electric vehicle penetration trajectories, REACH regulatory phase-in schedules, and F-Gas Regulation heat pump adoption curves. Industry-specific inputs included 800V architecture deployment timelines at Hyundai and Škoda Auto plants and ECHA candidate list substance evaluation calendars.
Several conditions sit outside the modeled scope, including potential MDR-aligned durability testing standard adoption into automotive supplier quality agreements and mechanical recycling technology maturation enabling closed-loop tubing recovery. Forecasts reflect assumptions about regulatory enforcement consistency and OEM platform qualification timelines. Periodic stress-testing of base assumptions against ECHA substance evaluation announcements and OEM electrification capex disclosures is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Components
Automotive Brake Tube Market
Automotive Components
Argentina Automotive Composites Market
Automotive Components
Automated Lubrication Systems Market
Automotive Components
Automotive Skid Plate Market
Automotive Components
Russia Automotive Pneumatic Actuators Market
Automotive Components
Automotive Active Bonnet Market
Automotive Components
Automotive Carbon Fiber Composites Parts Market
Automotive Components
Japan Automotive Sunroof Market
Automotive Components
Automotive Distributor O Ring Market
Automotive Components
Japan Automotive Composites Market
Automotive Components
Automotive Key Market
Automotive Components
North America Automotive Glass Market
Automotive Components
North America Automotive Heat Shield Market
Automotive Components
Automotive Solenoid Market
Automotive Components
Automotive Door Module Market
Automotive Components
China Automotive Actuators Market