
 North America Heat Shrink Tubing for Automotive Market | 2026-2036
North America Heat Shrink Tubing for Automotive Market Size, Share, and Industry Trends Forecast 2026-2036
North America Heat Shrink Tubing for Automotive Market Analytics
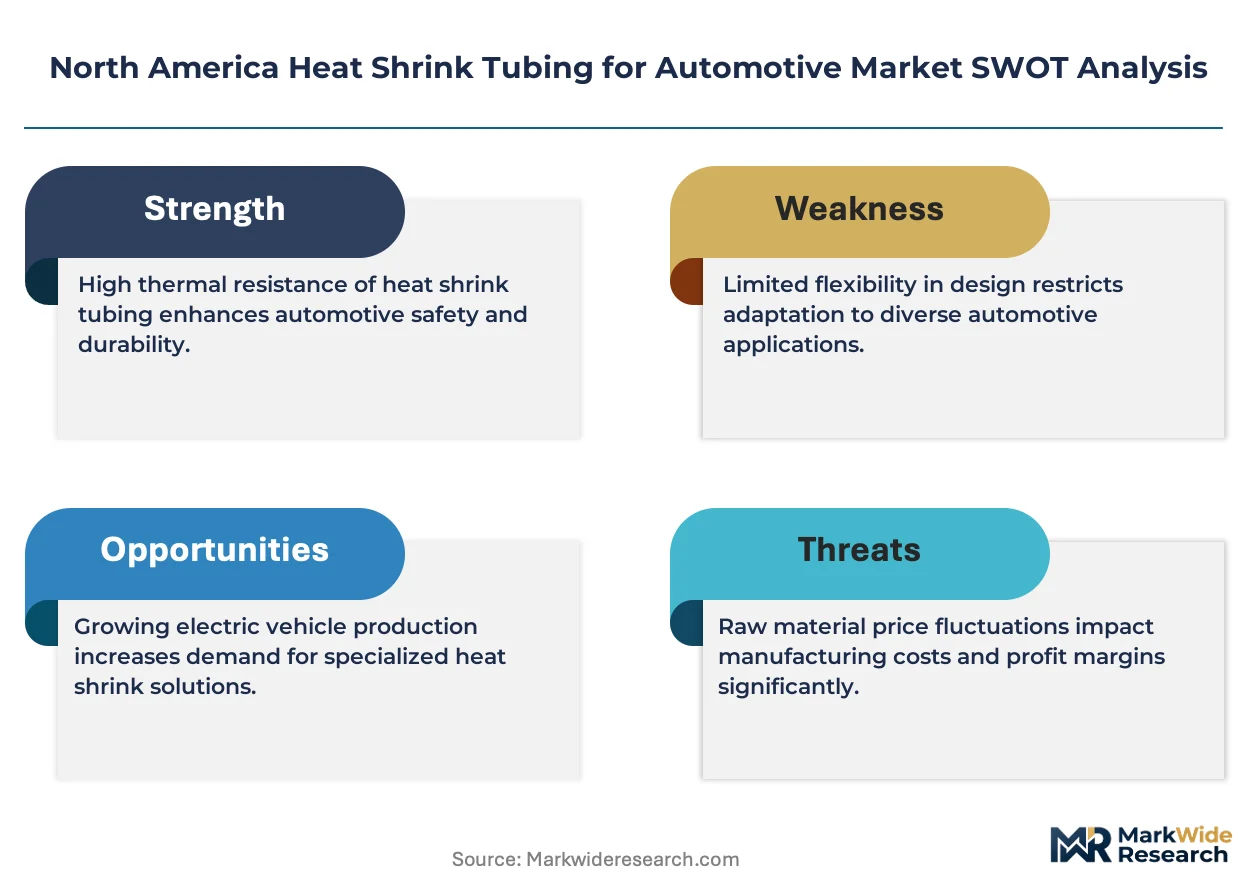
Polymer compounding expertise is redrawing competitive boundaries across the North American supply base. TE Connectivity leverages captive resin formulation capabilities to secure OEM qualification timelines. 3M sustains brand preference among Tier-1 harness suppliers through adhesive-lined product architectures. HellermannTyton anchors its position with application tooling bundled alongside tubing specifications.
Heat shrink tubing comprises cross-linked polymeric sleeves that contract radially when heated, typically to one-half or one-third of supplied diameter, creating strain-relieved environmental seals over electrical conductors. Automotive grades incorporate flame-retardant additives and fluid-resistant jackets to survive engine-bay temperatures exceeding 125°C while protecting against gasoline, brake fluid, and road salt intrusion. Polyolefin formulations dominate volume shipments due to cost-performance balance across wiring insulation and splice protection duties, though PTFE variants command premium positioning for high-temperature zones near exhaust manifolds and battery thermal management circuits. Application segmentation reveals environmental sealing as the fastest-expanding category, driven by ingress-protection ratings rising to IP6K9K for underbody and wheel-well electronics.
NHTSA Federal Motor Vehicle Safety Standards govern electrical system integrity in crash scenarios, compelling tubing rated for abrasion resistance and short-circuit containment. EPA REACH-aligned chemical restrictions and California Proposition 65 labeling requirements are filtering halogenated compound selections across supplier portfolios. Stakeholders must monitor evolving battery-electric platform voltage architectures, as 800V systems will redefine insulation thickness and dielectric strength specifications before decade's end.
Market Dynamics
Platform electrification is compressing product qualification timelines across the North American automotive supply base. OEMs now demand tubing portfolios validated for 800V architectures simultaneously with 400V legacy systems, forcing compounders to maintain parallel resin development tracks.
Growth Catalysts
- NHTSA crashworthiness mandates:Federal Motor Vehicle Safety Standards for electrical system integrity in collision scenarios require flame-retardant tubing rated for abrasion resistance. Harness suppliers must source certified materials to maintain OEM qualification status.
- EV thermal management circuits:Battery pack cooling lines and power electronics enclosures need high-temperature sleeves surviving sustained 150°C exposure. PTFE and fluoropolymer formulations capture design wins in underhood zones.
- Mexico's northern border assembly belt:Kia, BMW, and Tesla production facilities in Nuevo León and Baja California generate concentrated demand for just-in-time tubing deliveries. Suppliers locate compounding operations within 200 kilometers of these plants.
Market Restraints
- Polyolefin resin cost volatility:Ethylene and propylene feedstock prices track crude oil benchmarks, compressing tubing margins when petrochemical spreads tighten. Compounders lack pricing power to pass through input spikes.
- Single-source fluoropolymer dependence:PTFE and FEP resin supply concentrates with Chemours and Daikin facilities in the southeastern United States. Any force majeure event disrupts high-performance tubing production.
- REACH-aligned substance restrictions:EPA enforcement of halogenated compound limitations filters brominated flame retardant selections. Reformulation cycles extend 18-24 months.
Strategic Opportunities
- Canada's EV battery corridor:Stellantis-LG and Volkswagen-PowerCo cell factories in Ontario and Quebec need thermal runaway protection sleeves. Tubing suppliers can anchor regional compounding capacity.
- Adhesive-lined splice sealing:Dual-wall constructions with hot-melt inner layers enable IP6K9K ratings for wheel-well electronics. Tier-1 harness manufacturers specify these for premium vehicle programs.
- Inflation Reduction Act domestic content credits:Battery assembly incentives reward North American-sourced components. Tubing producers qualifying under IRA rules gain procurement preference.
Industry Challenges
- Polymer chemist talent scarcity:Cross-linking expertise and radiation processing knowledge concentrates with aging workforces at legacy compounders. Universities produce few graduates with relevant specialty training.
- UL and SAE certification timelines:New material qualifications require 12-18 months of thermal aging and fluid immersion testing. Product development cycles misalign with 24-month vehicle platform schedules.
- Legacy harness integration complexity:400V architectures persist in hybrid variants alongside 800V full-electric systems. Tubing suppliers must maintain dual inventory and tooling configurations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Heat Shrink Tubing for Automotive Market |
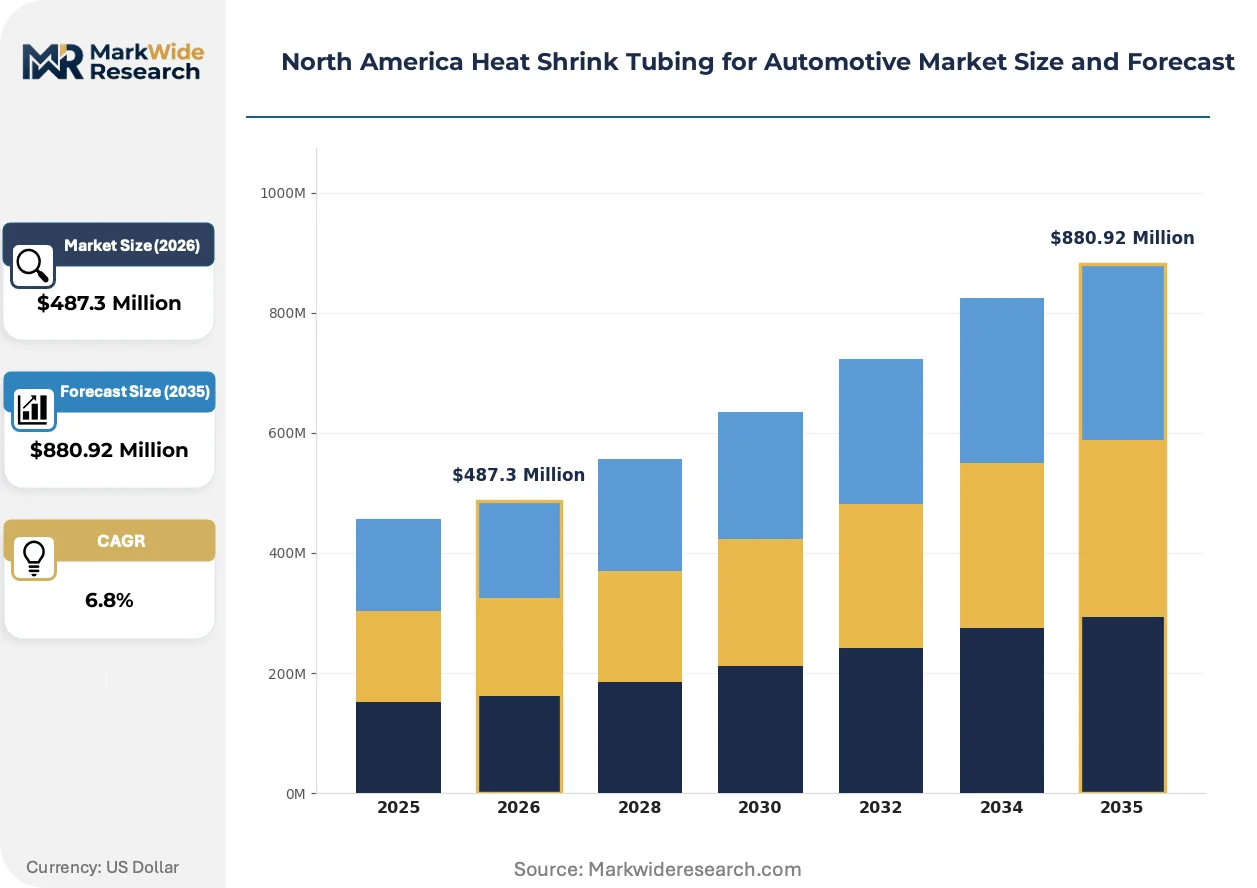
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $880.92 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyolefin, PVC, PTFE, Nylon Application: Wiring Insulation, Splice Protection, Environmental Sealing, Component Identification End User: OEMs, Aftermarket Providers, Vehicle Assemblers, Tier-1 Suppliers Size: Small, Medium, Large, Extra Large |
| Companies Covered | TE Connectivity, 3M, Molex, Panduit, ABB, Sumitomo Electric Industries, HellermannTyton, Alpha Wire, Qualtek Electronics Corp., Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Heat Shrink Tubing for Automotive Market Evolving Landscape
Material science advances and voltage architecture shifts are redrawing performance specifications across the North American automotive tubing value chain. Suppliers now compete on thermal endurance and dielectric strength rather than commodity cost alone.
High-temperature fluoropolymer blends are fragmenting the traditional polyolefin-dominated product hierarchy. Battery pack engineers specify PTFE and PFA variants for cell-to-cell busbar insulation and coolant line protection. These materials command 4-5x unit pricing but eliminate thermal derating risks in 800V systems. The technology is fragmenting procurement patterns as OEMs bifurcate specifications between cost-driven legacy platforms and performance-critical electric architectures.
EPA enforcement of California Proposition 65 labeling requirements is filtering halogenated compound portfolios. Suppliers must reformulate brominated flame retardant systems or absorb litigation exposure costs. Environmental sealing grades for underbody applications face the most acute substitution pressure, driving migration to phosphorus-nitrogen intumescent chemistries.
Harness manufacturers are consolidating supplier relationships around vertically integrated compounders offering captive resin formulation. TE Connectivity and 3M leverage in-house polymer expertise to compress qualification timelines. Tier-1 buyers in Michigan's automotive corridor now favor single-source tubing-to-adhesive systems over multi-vendor assemblies.
North America Heat Shrink Tubing for Automotive Market Segmentation
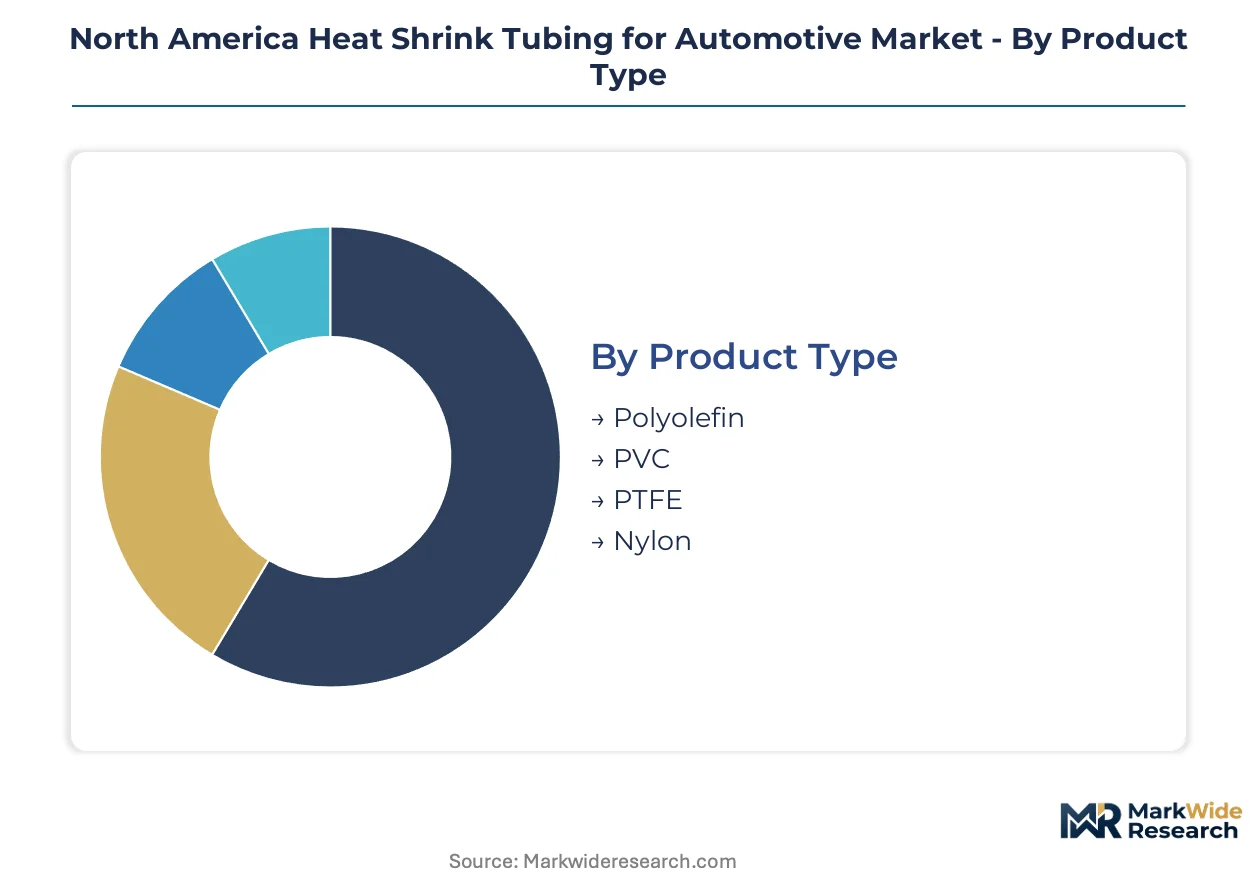
Segmentation in the North American automotive tubing market reveals how material chemistry, application environment, and supply chain position determine procurement patterns. Each dimension channels distinct margin structures and technical qualification requirements.
Product Type:
Channel flow splits between high-volume polyolefin grades distributed through Tier-1 harness suppliers and specialty fluoropolymers sold direct to OEM engineering teams.
- Polyolefin:Cross-linked polyethylene and polypropylene formulations deliver cost-performance balance for general wiring insulation. Michigan's automotive corridor consumes the majority of volume as Detroit Three OEMs specify these grades for 12V and 48V auxiliary circuits. Feedstock volatility compresses compounder margins when ethylene spreads tighten.
- PTFE:Fluoropolymer chemistry survives sustained 260°C exposure with near-zero moisture absorption. Battery pack engineers in Ontario's EV corridor specify PTFE for cell-to-cell busbar insulation and coolant line protection in 800V architectures. Chemours and Daikin resin supply concentrates in the southeastern United States.
- PVC:Plasticized vinyl formulations serve cost-sensitive interior applications where temperature exposure remains below 105°C. Mexico's northern border assembly belt sources these grades for entry-level vehicle programs.
- Nylon:Polyamide heat shrink offers abrasion resistance and chemical compatibility for fuel system proximity. Aftermarket distributors stock these for repair scenarios involving engine-bay fluid exposure.
Polyolefin dominates installed base. PTFE is where expansion concentrates.
Application:
Cost tiering separates commodity insulation duties from premium sealing specifications requiring dual-wall constructions.
- Environmental Sealing:Dual-wall adhesive-lined constructions create IP6K9K-rated barriers against pressure washing and submersion. Wheel-well electronics and underbody control modules in Nuevo León assembly plants drive specification. NHTSA crashworthiness mandates compel harness suppliers to source certified materials.
- Splice Protection:Heat-activated inner sealants encapsulate crimped connections against galvanic corrosion. Tier-1 manufacturers in Michigan bundle these with terminal specifications for premium vehicle programs.
- Wiring Insulation:Single-wall polyolefin sleeves provide dielectric isolation across 12V to 48V architectures. Volume concentration sits with high-run powertrain harnesses.
- Component Identification:Color-coded and printed tubing enables circuit tracing during assembly and service. Print durability requirements filter supplier qualifications.
Environmental sealing commands premium pricing. Splice protection delivers the steepest expansion trajectory as EV thermal management complexity multiplies connection counts.
End User:
Customer type determines contract structure, with OEM direct procurement favoring long-term compound development partnerships over spot purchasing.
- Tier-1 Suppliers:Delphi, Aptiv, and Lear Corporation consolidate tubing procurement across multiple OEM platforms. These buyers demand 18-month qualification timelines and dual-source redundancy.
- OEMs:Tesla, Rivian, and Lucid Motors source specialty fluoropolymers directly for battery pack integration. In-house polymer expertise compresses specification cycles.
- Vehicle Assemblers:Contract manufacturers in Mexico's northern border belt purchase through distributor channels for just-in-line replenishment.
- Aftermarket Providers:Repair specialists and fleet maintenance operations stock standard sizes through industrial distributors. Price sensitivity dominates procurement criteria.
Tier-1 suppliers anchor volume throughput. OEM direct relationships concentrate where 800V thermal specifications require co-development.
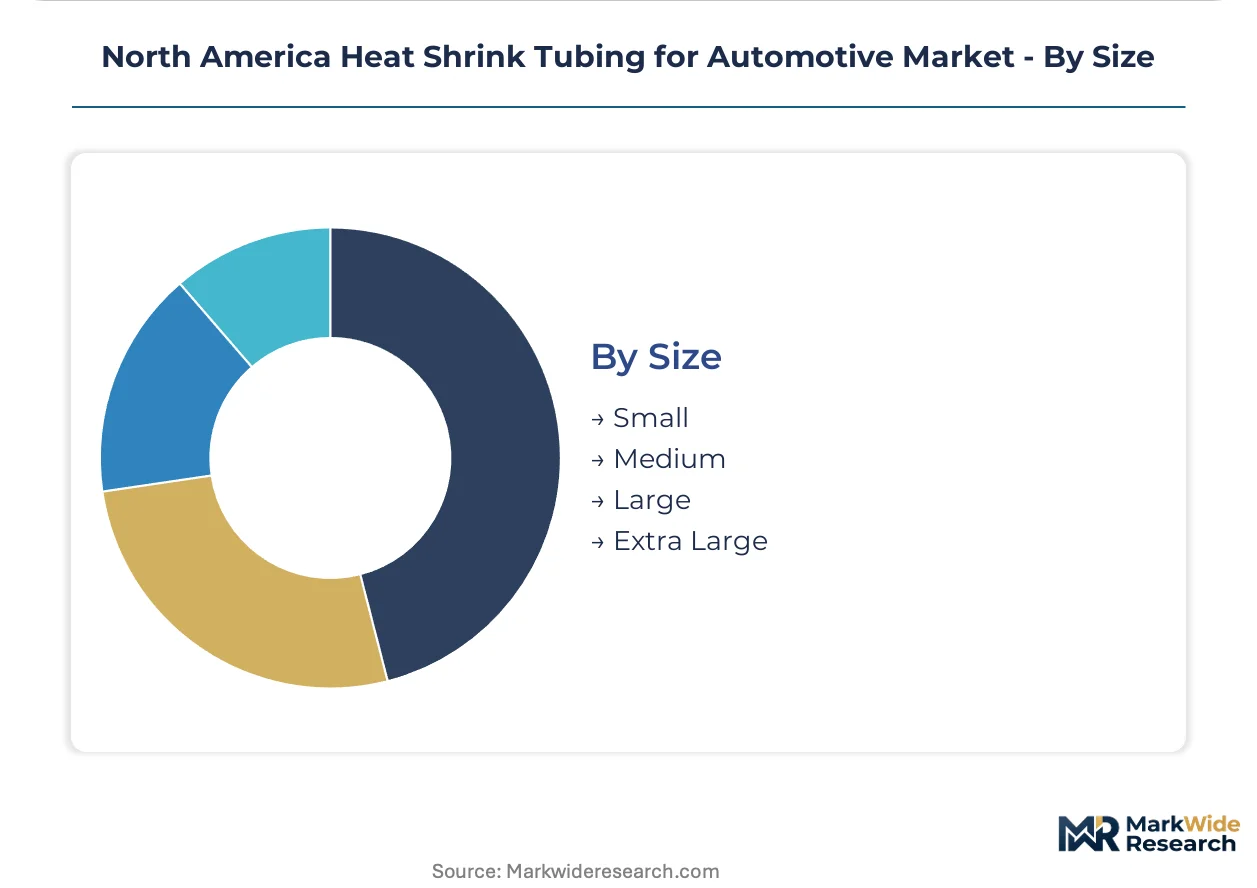
Size:
Volume distribution tracks conductor gauge proliferation across electrified architectures, with medium sizes capturing legacy internal combustion harness density.
- Medium:3mm to 12mm recovered diameters encapsulate 14AWG to 4AWG conductors in power distribution and lighting circuits. Michigan harness suppliers consume this tier at highest velocity.
- Small:Sub-3mm sleeves protect sensor wiring and CAN bus lines with minimal bundle diameter addition. ADAS camera and radar installations multiply connection counts.
- Large:12mm to 25mm recovered diameters accommodate battery cable assemblies and motor phase conductors. Ontario battery corridor demand is climbing fastest.
- Extra Large:Above 25mm specifications serve high-current busbar and charging inlet cable management. Limited application count constrains SKU proliferation.
Medium sizes dominate current installed base. Large diameters are where electrification-driven expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States consumes heat shrink tubing primarily for high-voltage battery protection and ADAS harness sealing, while Canada and Mexico concentrate demand in EV battery manufacturing and contract assembly respectively. This three-country consumption mix reflects divergent industrial specializations across the North American automotive belt.
United States
Michigan's automotive corridor and Tesla's Texas Gigafactory drive specifications for 800V-rated fluoropolymer tubing. NHTSA Federal Motor Vehicle Safety Standards mandate flame-retardant materials for crashworthiness compliance. Southeast resin compounding facilities in Virginia and North Carolina supply PTFE formulations to battery engineers in California's Silicon Valley.
Canada
Ontario's Windsor-to-Toronto EV battery corridor demands thermal runaway protection sleeves for Stellantis-LG and Volkswagen-PowerCo cell factories. Canada's federal Investment Tax Credits for clean technology manufacturing subsidize domestic component sourcing. Quebec's Bécancour lithium processing hub anchors upstream material flows for regional tubing compounders.
Mexico
Nuevo León's Monterrey metro and Baja California's Tijuana-Mexicali axis host Kia, BMW, and Tesla assembly plants requiring just-in-time tubing deliveries. Mexico's IMMEX maquiladora program enables duty-free import of raw resins for local conversion. Suppliers locate compounding operations within 200 kilometers of these northern border facilities to meet OEM replenishment cycles.
North America Heat Shrink Tubing for Automotive Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in North American automotive heat shrink tubing supply. TE Connectivity and 3M maintain captive resin formulation capabilities that compress OEM qualification timelines, while mid-scale compounders compete on application-specific tooling bundles and regional logistics proximity. Three archetypes dominate: vertically integrated material-science conglomerates, harness-system integrators with captive tubing production, and focused polymer specialists serving aftermarket channels. Consolidation pressure intensifies through strategic partnerships between resin producers and tubing fabricators, plus capacity expansion announcements targeting Ontario's battery corridor.
Within the integrated-materials tier, TE Connectivity and 3M exemplify compounders leveraging in-house polymer expertise to secure multi-platform OEM qualifications. HellermannTyton occupies a position among European-originated specialists emphasizing application tooling alongside tubing specifications. These three anchors represent distinct competitive vectors: resin chemistry control, adhesive-system integration, and installation-equipment bundling respectively.
| Leading Market Players |
|---|
| TE Connectivity |
| 3M |
| Molex |
| Panduit |
| ABB |
| Sumitomo Electric Industries |
| HellermannTyton |
| Alpha Wire |
| Qualtek Electronics Corp. |
| Others |
Value Network & Pricing Analysis
PTFE resin substitution for polyolefin in 800V battery architectures is redrawing supply geography toward southeastern United States compounding facilities while compressing per-unit economics across legacy 400V platforms. This material migration concentrates pricing power with fluoropolymer resin producers as OEMs absorb premium differentials for thermal runaway protection.
Pricing Analysis
Long-term offtake agreements anchor procurement between Tier-1 harness suppliers and compounders with captive resin formulation, insulating qualified vendors from spot ethylene volatility. Price differentiation rests on UL certification tier and volume scale, with adhesive-lined dual-wall constructions commanding substantial premiums over single-wall commodity grades. Cost compression in polyolefin tiers is intensifying because feedstock spreads track crude benchmarks without pass-through mechanisms. Aftermarket distributors exhibit highest price sensitivity, while OEM engineering teams prioritize thermal performance over unit economics in 800V specifications.
Supply Chain Analysis
Strait of Hormuz transit risk for petrochemical feedstocks underwrites margin volatility across polyolefin-dependent compounders despite minimal direct exposure. Raw material flows concentrate on United States Gulf Coast ethylene crackers, Canadian Alberta petrochemical complexes, and southeastern fluoropolymer resin facilities. Supply chain vulnerability centers on single-source PTFE resin dependence with Chemours and Daikin. Distribution runs through Tier-1 harness manufacturer consolidation centers in Michigan's automotive corridor and just-in-line replenishment networks serving Mexico's northern border assembly belt.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat arena where regulatory entrenchment creates formidable barriers. NHTSA crashworthiness mandates and EPA REACH-aligned substance restrictions embed switching costs that protect qualified supplier relationships across vehicle platform generations.
For Market Incumbents: Compound qualification advantages by anchoring regional compounding capacity within 200 kilometers of Ontario's EV battery corridor and Nuevo León assembly plants. Threats from emerging fluoropolymer specialists with Chinese resin partnerships demand accelerated captive formulation investment. Prioritize backward integration into radiation cross-linking equipment to compress development cycles.
For New Entrants and Emerging Players: Lead with application-specific tooling bundles targeting aftermarket distributors underserved by integrated conglomerates. Canada's Windsor-to-Toronto battery corridor offers the most penetrable geography given federal Investment Tax Credit subsidies and nascent local supply base. Go-to-market execution should emphasize rapid UL certification turnaround for thermal runaway protection sleeves.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed mid-scale compounders possessing regional logistics advantages but lacking fluoropolymer expertise. Long-term viability hinges on 800V platform penetration sustaining premium pricing architecture. Watch NHTSA rulemaking on battery enclosure integrity as the decisive inflection signal for thermal protection demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Regional Compounding Capacity Expansion | Proximity to Ontario's Stellantis-LG and Volkswagen-PowerCo cell factories captures IRA domestic content preference. |
| Fluoropolymer Formulation Partnership | Resin supply agreements with Chemours or Daikin secure PTFE allocation for 800V thermal management specifications. |
| Adhesive-Lined Product Architecture Development | Dual-wall IP6K9K-rated constructions command premium positioning in wheel-well and underbody electronics sealing. |
| Radiation Cross-Linking Equipment Investment | In-house electron beam processing compresses qualification timelines and insulates margins from toll-processing dependencies. |
| Application Tooling Bundling | Heat gun and installation equipment integration with tubing specifications locks in Tier-1 harness supplier relationships. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across primary interview programs and secondary validation protocols. Stakeholder engagement encompassed Tier-1 harness procurement directors, OEM platform engineers, aftermarket distribution channel managers, and radiation processing equipment specialists. Secondary sources included vehicle production databases, NHTSA Federal Motor Vehicle Safety Standards filings, EPA chemical restriction notices, SEC 10-K disclosures from resin producers, and customs trade flow records. Bottom-up volume modeling triangulated against top-down market sizing across product type, application, and end-user segmentation dimensions.
Across the analysis window, the forecasting framework integrated propulsion architecture migration curves, content-per-vehicle coefficients for high-voltage harness protection, and regional production cluster capacity buildouts. Segmentation modeling captured material chemistry tiers, voltage architecture specifications, and OEM direct versus Tier-1 indirect procurement patterns. CAGRs derived from regression analysis against historical platform electrification rates and thermal management circuit proliferation trajectories. Specific inputs included battery pack cooling line counts, ADAS sensor harness density, and NHTSA regulatory compliance timeline assumptions.
Forecasts assume regulatory continuity in NHTSA crashworthiness standards and EPA REACH-aligned enforcement; material policy shifts would require re-modeling qualification timeline assumptions and compound substitution trajectories. Practitioners should keep alternative scenarios live as 800V platform adoption rates and fluoropolymer resin supply availability evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Components
Automotive Catalyst Market
Automotive Components
United States Automotive Pneumatic Actuators Market
Automotive Components
Global Automotive Gearbox Market
Automotive Components
Europe and North Africa Automotive Window Regulator Market
Automotive Components
Automotive Camshaft Phase Variator Market
Automotive Components
Europe Automotive Bearing Market
Automotive Components
Global Automotive Noise Filter Market
Automotive Components
Automotive Rear End Module Market
Automotive Components
Global Automotive Cigarette Lighters Market
Automotive Components
India Passenger Vehicles Lubricants Market
Automotive Components
Automotive Emblem Market
Automotive Components
Automotive Brake Tube Market
Automotive Components
Automotive Glass Fiber Composites Market
Automotive Components
Automotive Brake Rotor Market
Automotive Components
India Automotive Glass Fiber Composites Market
Automotive Components
Global Automotive Components Forging Market