
 North America Automotive Glass Market | 2026-2036
North America Automotive Glass Market Size, Share, and Industry Trends Forecast 2026-2036
North America Automotive Glass Market Outlook
NHTSA's updated windshield retention standards is consolidating supplier compliance costs around laminated glass architectures. AGC Inc. leverages its integrated float glass operations across North American manufacturing corridors. Saint-Gobain Sekurit anchors premium OEM supply relationships through specialized acoustic and solar-control laminates. Fuyao Glass Industry Group Co., Ltd. competes on cost-optimized tempered and laminated capacity serving both Detroit and southern US assembly expansion.
North America Automotive Glass comprises silica-based transparent or translucent panels engineered to specified optical clarity, impact resistance, and dimensional tolerances through float forming, tempering, or polyvinyl butyral interlayer lamination processes, serving structural, aerodynamic, and occupant protection functions in vehicle cabins. Laminated glass dominates windshield applications due to occupant retention requirements, while smart glass represents the fastest-expanding technology segment as electrochromic and suspended particle devices penetrate luxury and electric vehicle programs. Tempered glass sustains mature demand in side and backlite positions where fragmentation safety protocols govern specification.
NHTSA, Transport Canada, and EPA frameworks collectively govern glazing safety performance, emissions-linked lightweighting credits, and manufacturing environmental compliance across the US and Canadian production base. These regulators enforce differential compliance burdens that favor suppliers with cross-border certification capabilities and integrated testing infrastructure. Stakeholders must monitor evolving autonomous vehicle sensor integration requirements that will redefine optical clarity specifications and glazing interface standards.
Market Dynamics
NHTSA's updated windshield retention standards are compressing specification cycles across Detroit's assembly corridor, forcing laminated glass architectures into platforms previously designed for tempered alternatives. This regulatory compression is redrawing supplier qualification timelines and capital deployment patterns.
Growth Catalysts
- Lightweighting mandates:EPA emissions credits reward gram-per-kilometer reductions, pulling thin-glass and acoustic interlayer configurations into electric vehicle programs across Michigan and Ohio assembly plants.
- Autonomous sensor integration:LiDAR-transparent windshields and camera-optimized optical clarity specifications are creating new glazing performance tiers for premium OEM platforms.
- Transport Canada harmonization:Cross-border safety standard alignment reduces dual-certification burdens for suppliers serving the Great Lakes manufacturing cluster.
Market Restraints
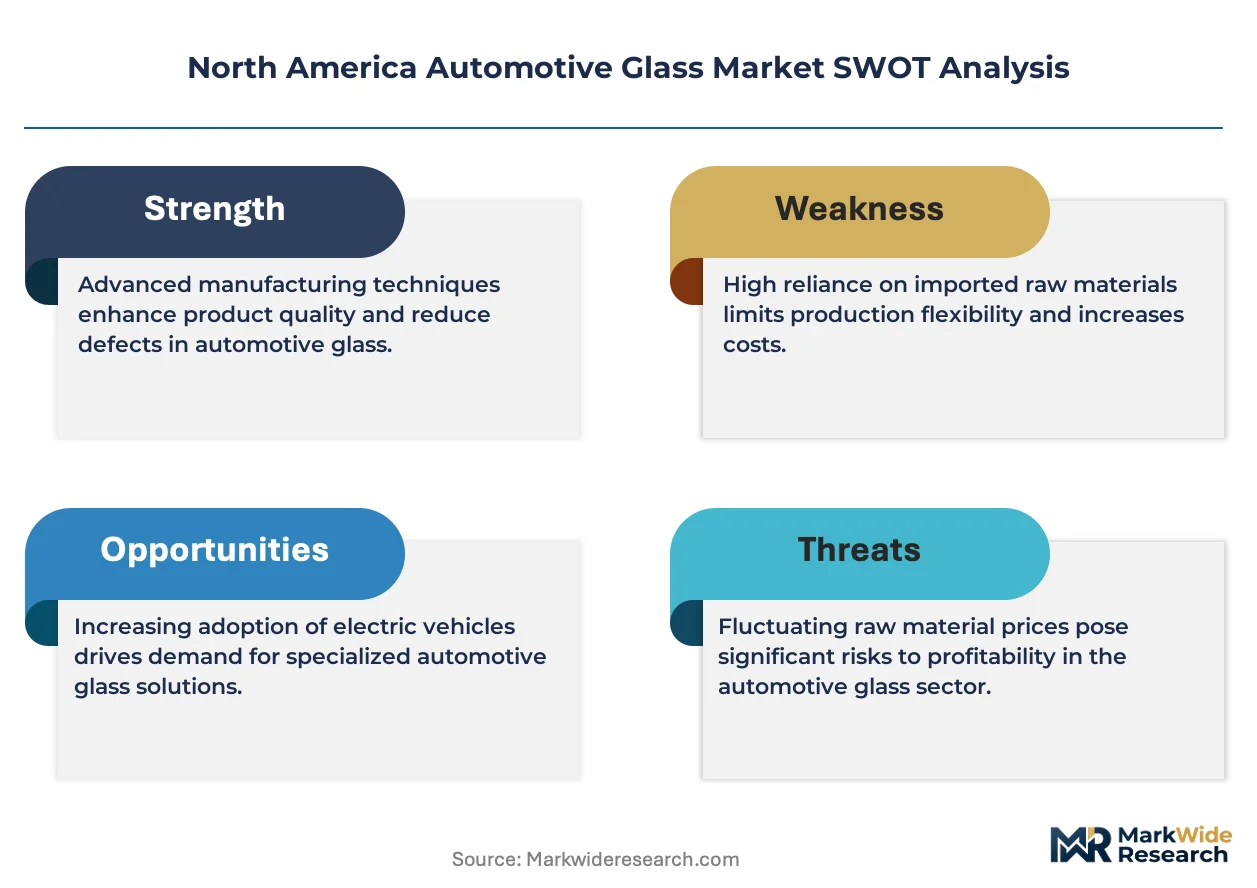
- Float glass energy intensity:Natural gas price volatility at AGC and Saint-Gobain Sekurit melting operations compresses margin buffers during winter demand spikes.
- PVB interlayer supply concentration:Three chemical conglomerates control North American polyvinyl butyral resin supply, creating input bottleneck risk for laminated capacity expansions.
- Tempered fragmentation protocols:Side and backlite safety standards lock in mature glass types, limiting premium technology penetration in volume segments.
Strategic Opportunities
- Southern US assembly migration:Tennessee, South Carolina, and Texas greenfield plants lack established glazing supplier footprints, opening qualification windows for integrated manufacturers.
- Smart glass convergence:Electrochromic and SPD technologies intersect with electric vehicle battery thermal management needs, creating specification pull from luxury BEV platforms.
- IRA clean manufacturing credits:Domestic content incentives favor float glass produced with renewable energy at Ohio and Tennessee furnace operations.
Industry Challenges
- Optical engineer scarcity:Autonomous vehicle clarity specifications demand specialized metrology talent that concentrates at legacy camera lens and semiconductor firms.
- Sensor-glazing integration timelines:OEM development cycles for LiDAR-compatible windshields compress supplier R&D windows while safety certification protocols remain unsettled.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Automotive Glass Market |
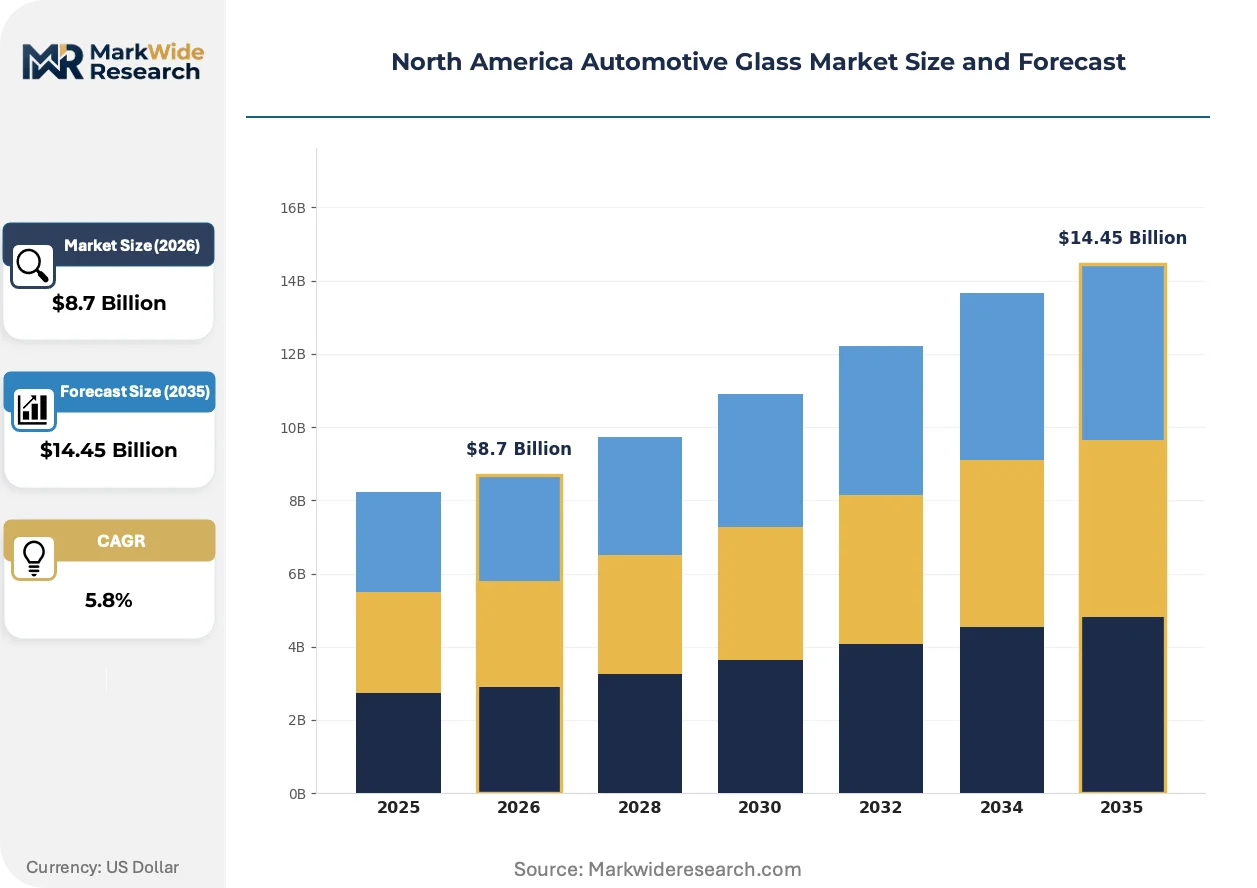
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $14.45 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Windshields, Side Windows, Back Windows, Sunroofs Technology: Tempered Glass, Laminated Glass, Coated Glass, Smart Glass End User: OEMs, Aftermarket, Vehicle Assemblers, Service Centers Vehicle Type: Passenger Cars, Commercial Vehicles, Electric Vehicles, Luxury Vehicles |
| Companies Covered | AGC Inc., Saint-Gobain Sekurit, Fuyao Glass Industry Group Co., Ltd., Vitro S.A.B. de C.V., Gentex Corporation, Pilkington Automotive (NSG Group), Guardian Industries Corp., Central Glass Co., Ltd., Magna International Inc., Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Automotive Glass Market Strategic Shifts
Electrochromic and suspended particle device technologies are penetrating vehicle cabins at accelerating rates, displacing mechanical sunshades and creating new electrical interface requirements between glazing suppliers and tier-one electronics integrators.
Smart glass is absorbing interior climate control functions previously handled by HVAC subsystems. General Motors and Ford Motor Company specification teams are embedding electrochromic layers in panoramic roof modules for electric SUV platforms. This absorption is compressing the traditional boundary between glazing and thermal management supplier tiers.
NHTSA's updated windshield retention standards are tightening adhesive and laminate performance thresholds. The regulation forces recertification of existing bonded mounting systems and accelerates migration toward thicker interlayer configurations. Detroit Three engineering groups are responding by consolidating supplier pools around integrated laminate-acoustic-testing capabilities.
Fleet procurement teams at rental and commercial operators are unbundling aftermarket glazing from dealer service networks. Independent glass installation chains in Texas and Florida are capturing volume replacement demand through mobile service models and direct insurer billing relationships. This channel shift is most visible in high-hail-frequency corridors where comprehensive coverage drives rapid replacement cycles.
North America Automotive Glass Market Segmentation
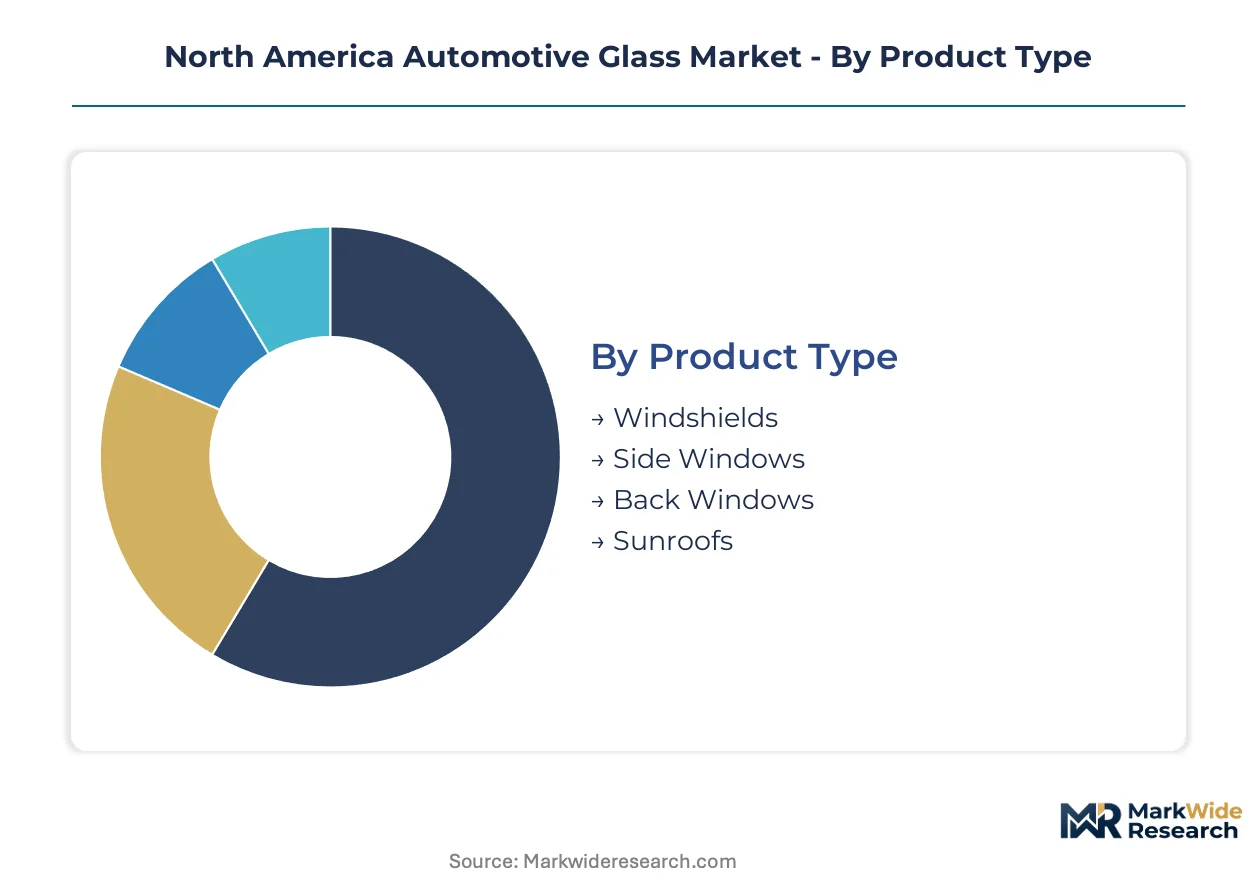
Automotive glass segmentation in North America reflects divergent capital deployment patterns across float furnace operations, tempering lines, and lamination equipment. Supplier investment decisions hinge on which segments command premium pricing and which face commoditization pressure from Mexican and Asian import competition.
Product Type:
Capital intensity escalates sharply from tempered side and back windows to laminated windshields and complex sunroof assemblies requiring precision forming and sealing systems.
- Windshields:Laminated silica-PVB constructions meeting NHTSA retention standards require integrated float-temper-laminate lines with acoustic interlayer testing capabilities. Michigan and Ohio assembly corridors concentrate demand as Detroit Three platforms convert to thicker interlayer specifications under updated federal safety protocols.
- Sunroofs:Large-format tempered or laminated panels with integrated drainage channels and frame sealing systems demand specialized bending furnaces and robotic handling equipment. Tennessee and South Carolina greenfield plants are pulling capacity expansion for panoramic roof modules in electric SUV programs.
- Side Windows:Tempered glass fragmentation safety compliance governs specification with lower capital barriers than laminated alternatives.
- Back Windows:Heated defogger-integrated tempered panels serve mature replacement cycles with standardized forming requirements.
Windshields absorb the bulk of installed capacity; sunroofs are expanding most quickly.
Technology:
Process complexity and intellectual property protection separate commodity tempered production from premium laminated and smart glass tiers.
- Laminated Glass:Silica-PVB interlayer constructions engineered to NHTSA windshield retention and acoustic damping specifications require captive resin supply relationships or tolling arrangements with chemical conglomerates. Transport Canada harmonization with US standards reduces dual-certification burdens for cross-border Great Lakes supply.
- Smart Glass:Electrochromic and suspended particle device architectures integrate electrical control systems with glazing substrates, creating new interface requirements with tier-one electronics suppliers. General Motors and Ford specification teams are embedding these layers in panoramic roof modules for battery thermal management.
- Tempered Glass:Rapid thermal quench processes produce fragmentation-safe side and backlite panels at scale with mature equipment depreciation profiles.
- Coated Glass:Solar-control and infrared-reflective thin-film depositions add marginal cost for premium OEM acoustic laminate configurations.
Laminated glass commands the dominant share of technology-specific capital deployment; smart glass is gaining share fastest.
End User:
Contract structure and inventory risk allocation distinguish OEM supply relationships from aftermarket service channels.
- OEMs:Long-term platform supply agreements with Detroit Three and transplant assemblers require co-located sequencing facilities and just-in-time delivery commitments. Michigan, Ohio, and Ontario assembly plant clustering favors suppliers with cross-border logistics infrastructure.
- Aftermarket:Independent glass installation chains in Texas and Florida are capturing volume replacement demand through mobile service models and direct insurer billing relationships, particularly in high-hail-frequency corridors.
- Vehicle Assemblers:Contract manufacturing arrangements for emerging electric vehicle startups create qualification windows without legacy supplier lock-in.
- Service Centers:Dealer network-affiliated facilities face margin compression from unbundled fleet procurement at rental and commercial operators.
OEM supply relationships anchor supplier revenue stability; aftermarket channels are climbing the fastest.
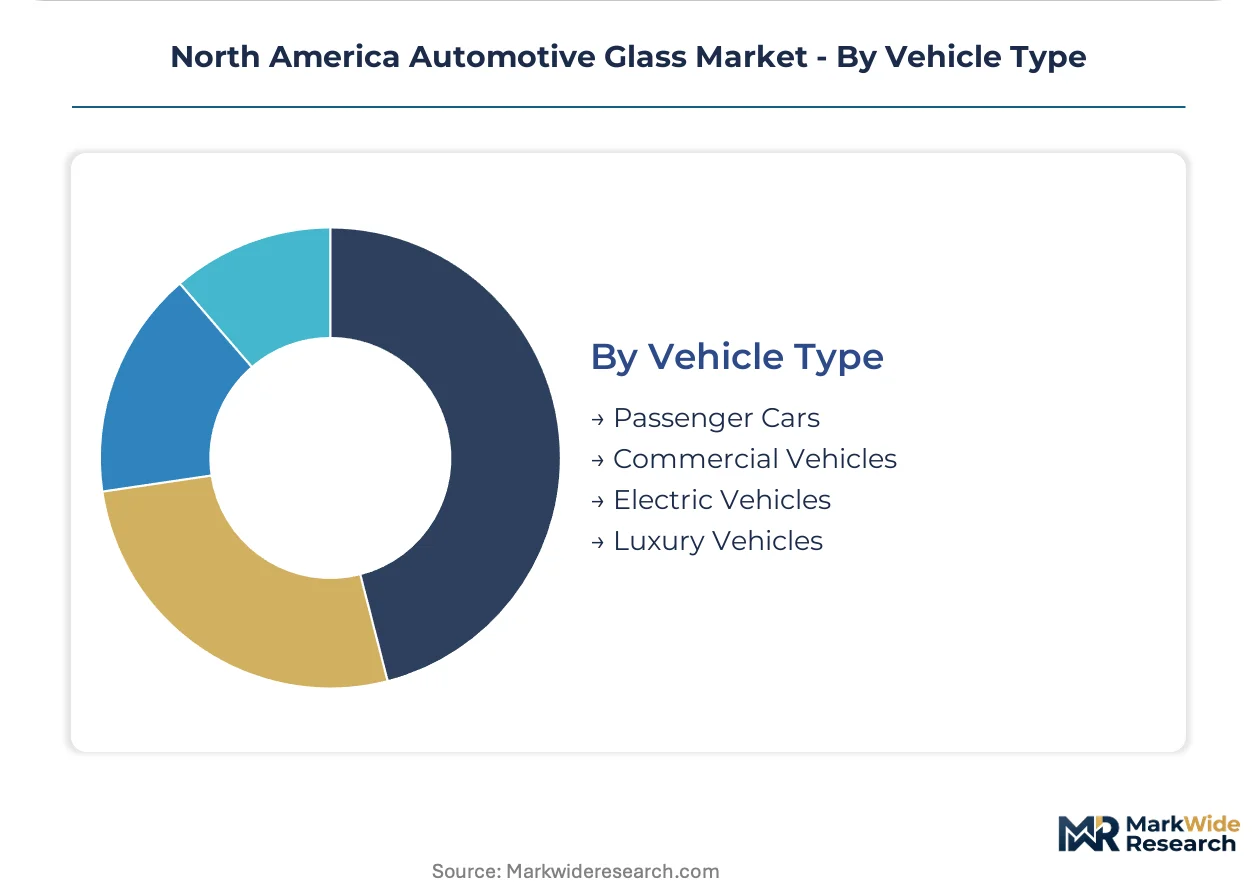
Vehicle Type:
Platform architecture and lightweighting intensity drive differential glass specification across passenger, commercial, and electrified segments.
- Electric Vehicles:Thin-glass and acoustic interlayer configurations serve gram-per-kilometer reduction targets tied to EPA emissions credits. Battery thermal management needs are pulling electrochromic smart glass specifications into luxury BEV platforms from General Motors and Ford.
- Luxury Vehicles:LiDAR-transparent windshields and camera-optimized optical clarity specifications create performance tiers demanding specialized metrology talent concentrated at legacy camera lens and semiconductor firms.
- Passenger Cars:High-volume compact and mid-size segments sustain tempered side and backlite demand with standardized safety protocols.
- Commercial Vehicles:Fleet procurement unbundling and durability-focused specifications govern replacement cycle economics.
Passenger cars retain the largest installed base; electric vehicles are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The US-Mexico-Canada Agreement's automotive rules of origin are concentrating glass supplier investments along cross-border manufacturing corridors. Tax-advantaged zones in Tennessee and South Carolina are pulling new assembly capacity away from legacy Midwest clusters.
United States
Michigan and Ohio assembly corridors anchor laminated windshield demand as Detroit Three platforms convert to thicker interlayer specifications. NHTSA's updated windshield retention standards are compressing supplier qualification timelines across these states. Tennessee and South Carolina greenfield plants are opening qualification windows for panoramic roof capacity in electric SUV programs.
Canada
Ontario's Windsor-Toronto manufacturing belt sustains cross-border just-in-time supply relationships with Michigan assembly plants. Transport Canada's harmonization with US safety standards reduces dual-certification burdens for suppliers serving the Great Lakes cluster. Oakville and Oshawa facilities are integrating acoustic interlayer testing capabilities for premium OEM platforms.
Mexico
Bajío Region and Nuevo León assembly expansion is pulling tempered and laminated capacity southward from US border states. Mexico's IMMEX program enables duty-free import of float glass for vehicle export production. Silao and Aguascalientes plants are capturing specification share from transplant assemblers seeking cost-optimized supply.
North America Automotive Glass Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across distinct technology tiers. The market structure consolidates around integrated float-laminate operations and specialized smart-glass developers. Three archetypes dominate: Japanese-Korean integrated materials groups, European premium-systems specialists, and Chinese cost-optimized volume players. Competitive moves center on captive PVB resin supply arrangements and acoustic-interlayer certification capabilities.
Among Japanese-Korean integrated manufacturers, AGC Inc. and Central Glass Co., Ltd. represent the materials-conglomerate archetype with captive float operations. Saint-Gobain Sekurit exemplifies the European premium-systems specialist focused on acoustic and solar-control laminates. Fuyao Glass Industry Group Co., Ltd. occupies the cost-optimized volume position serving both legacy and southern US assembly expansion.
| Leading Market Players |
|---|
| AGC Inc. |
| Saint-Gobain Sekurit |
| Fuyao Glass Industry Group Co., Ltd. |
| Vitro S.A.B. de C.V. |
| Gentex Corporation |
| Pilkington Automotive (NSG Group) |
| Guardian Industries Corp. |
| Central Glass Co., Ltd. |
| Magna International Inc. |
| Others |
Value Chain & Pricing Dynamics
Detroit Three procurement concentration anchors contract-based long-term offtake structures for laminated windshields, compressing spot market liquidity and amplifying premium capture for acoustic-interlayer-certified suppliers. NHTSA's updated retention standards tighten specification windows, forcing tiered pricing stratification across premium laminate, standard tempered, and economy aftermarket tiers.
Pricing Analysis
Short lead-time premiums dominate OEM supply relationships, with just-in-time sequencing commands from Michigan and Ohio assembly plants commanding price premiums over spot inventory positions. Pricing stratifies across premium acoustic-laminate, standard PVB-laminate, and economy tempered tiers, with certification grade and volume scale as primary differentiation drivers. Cost compression in the tempered segment intensifies due to Mexican import competition, while aftermarket channels exhibit highest price sensitivity amid fleet procurement unbundling.
Supply Chain Analysis
Cross-border freight costs from Ontario float operations to Michigan assembly plants anchor logistics expenditure structures, with winter heating season spikes amplifying margin pressure. Supply concentrates in the United States, Canada, and Mexico, with raw material dependencies spanning soda ash, silica sand, and PVB resin from three chemical conglomerates. Single-source vulnerability in interlayer resin creates bottleneck risk for laminated capacity expansions. Distribution runs through co-located sequencing facilities serving Detroit Three just-in-time programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
PVB interlayer supply concentration creates a structural capacity bottleneck, propping pricing power for integrated laminate suppliers while compressing margins at tolling-dependent competitors.
For Market Incumbents: Lock in captive resin supply arrangements or long-term tolling contracts with chemical conglomerates before qualification windows close for NHTSA-compliant interlayer specifications. Prioritize acoustic-testing certification investments at Ohio and Tennessee furnace operations to defend against emerging Chinese volume players exploiting southern US assembly migration. For New Entrants and Emerging Players: Independent glass installation chains in Texas and Florida represent the most penetrable channel target, with mobile service models and direct insurer billing relationships offering a go-to-market angle unburdened by dealer network legacy costs. Target fleet procurement unbundling at rental and commercial operators seeking aftermarket alternatives to OEM-captive service networks. For Investors and Strategic Acquirers: The window for entry favors integrated float-laminate operators with cross-border certification capabilities and established Detroit Three platform relationships. Watch autonomous vehicle sensor-glazing integration timelines as the inflection signal for premium optical clarity specification demand.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into PVB Resin | Captive interlayer supply secures NHTSA compliance capacity against chemical conglomerate bottleneck risk. |
| Acoustic-Interlayer Certification Investment | Detroit Three consolidation of supplier pools around integrated testing capabilities favors early movers. |
| Southern US Manufacturing Footprint | Tennessee and South Carolina greenfield proximity opens qualification windows for panoramic roof modules. |
| Smart Glass Platform Partnership | Electrochromic layer integration with General Motors and Ford thermal management programs creates specification pull. |
| Aftermarket Channel Control | Mobile service models in Texas and Florida capture fleet procurement unbundling from dealer networks. |
Study Parameters
Multi-period observation of vehicle production volumes, platform specification cycles, and interlayer pricing indices anchored the trend analysis, supplemented by interviews with OEM platform engineers, Tier 1 supplier procurement leads, aftermarket distributors, float furnace operations managers, and acoustic testing laboratory directors. Secondary validation drew from vehicle registration databases, NHTSA safety standard filings, customs trade records, and SEC disclosures from integrated materials conglomerates. Bottom-up capacity modeling and top-down demand aggregation were triangulated to reconcile segment-level outputs.
Segment-weighting approaches distributed value across product type, technology tier, end-user channel, and vehicle propulsion architecture dimensions. CAGRs were derived from regression analysis of historical production correlations with macroeconomic indicators, applied across the projection horizon. Industry-specific inputs included battery electric vehicle penetration assumptions and EPA lightweighting credit valuation models.
Caveats apply where NHTSA autonomous vehicle glazing standards, PVB resin supply disruptions, or southern US assembly migration pace could materially shift the outlook. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Components
Automotive Filters Market
Automotive Components
Automotive Solenoid Market
Automotive Components
Australia Automotive Composites Market
Automotive Components
Global Automotive HUD Market
Automotive Components
Automotive Straps Market
Automotive Components
Automotive License Plate Light Market
Automotive Components
Automotive Headliners Market
Automotive Components
Africa and Middle East Automotive Pneumatic Actuators Market
Automotive Components
Europe Automotive Bearing Market
Automotive Components
Global Automotive Gears Market
Automotive Components
Automotive Stabilizer Bar Link Market
Automotive Components
Global Automotive Radiator Market
Automotive Components
Global Automotive Acoustic Materials Market
Automotive Components
Global Automotive Cigarette Lighters Market
Automotive Components
Automotive V-Belts Market
Automotive Components
Europe Torque Vectoring Market