
 Europe Government and Security Biometrics Market | 2026-2036
Europe Government and Security Biometrics Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Government and Security Biometrics Market Insights
Platform licensing revenue is tilting toward multimodal and contactless biometric suites as European governments phase out single-factor systems. Innovatrics leverages its algorithm development capabilities to compete for large-scale national ID contracts across Central Europe. Veridos GmbH anchors its position through manufacturing scale and direct relationships with interior ministries in Germany and neighboring states.
Europe government and security biometrics encompasses fingerprint, facial, iris, and voice recognition systems deployed for citizen identification, border control, and secure facility access, typically operating with matching thresholds above 99.5% accuracy and liveness detection to prevent spoofing. Face recognition and contactless biometrics are capturing disproportionate investment as pandemic-era hygiene requirements persist in public infrastructure procurement. Fingerprint recognition retains dominance in law enforcement applications where legacy database interoperability creates switching costs for agencies.
The EU AI Act, GDPR, and ETSI standards collectively mandate algorithmic transparency, data minimization, and human oversight in biometric deployments, filtering out vendors lacking certified fairness audits. National regulators in France, Germany, and Italy enforce divergent implementation timelines, fragmenting procurement schedules. Stakeholders must track evolving conformity assessment pathways as the European Commission expands prohibited use cases for real-time remote biometric identification.
Market Dynamics
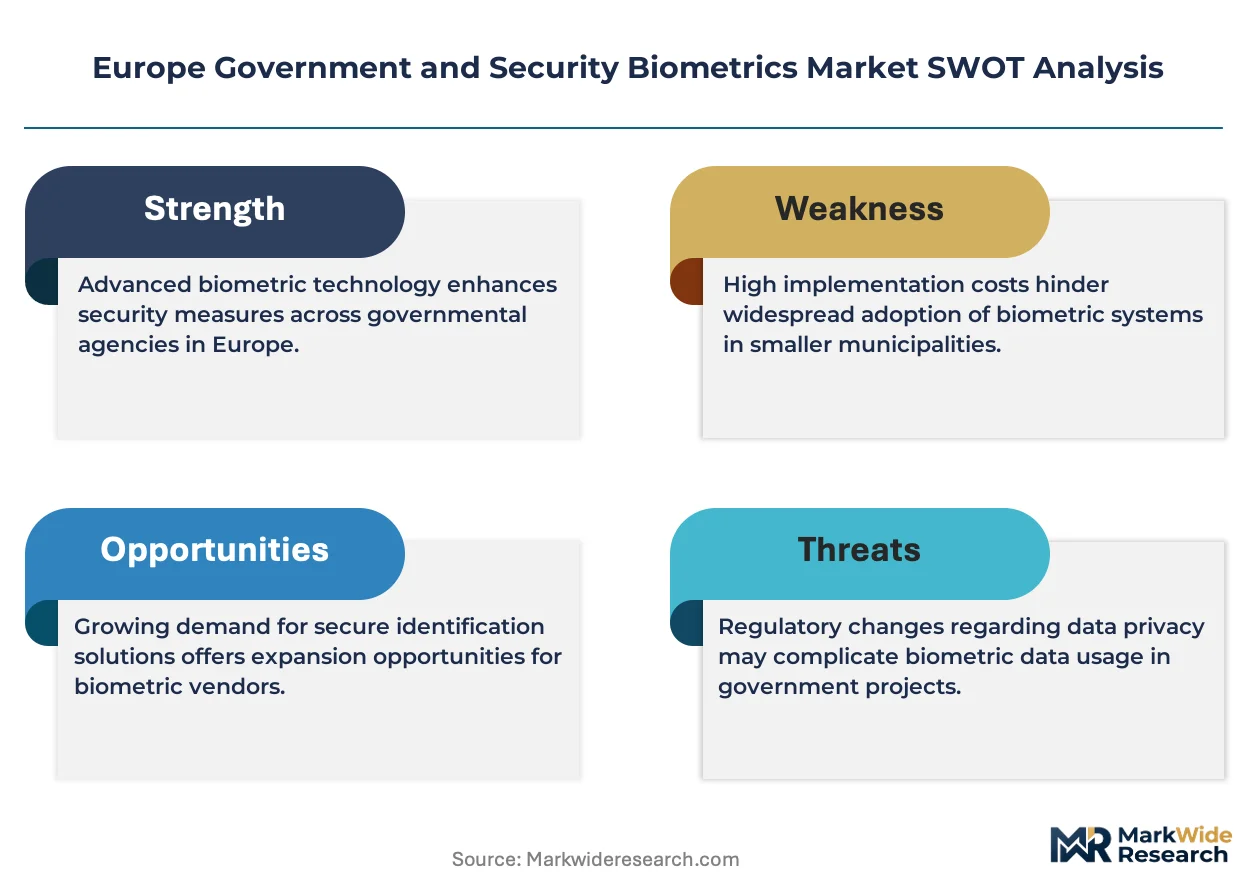
The EU AI Act's risk-based classification system is forcing vendors to re-engineer algorithmic pipelines before certification deadlines, compressing product development cycles and elevating compliance costs as the dominant market-shaping force.
Growth Catalysts
- Border Modernization Mandates:Schengen Area agencies are replacing single-factor fingerprint scanners with multimodal contactless corridors at major airports and land crossings.
- GDPR-Driven Upgrade Cycles:Data protection impact assessments are compelling interior ministries to retire legacy biometric databases that lack purpose limitation and storage minimization controls.
- France:The National Identity Card modernization program is deploying facial recognition for online authentication, creating template demand for liveness detection and anti-spoofing modules.
Market Restraints
- Algorithm Training Costs:High-quality facial datasets compliant with GDPR anonymization requirements command premium licensing fees from specialized data brokers.
- Vendor Concentration:Three firms control the majority of certified fingerprint sensor manufacturing for law enforcement-grade devices, creating single-source vulnerability.
- Interoperability Limitations:Legacy AFIS (Automated Fingerprint Identification System) architectures in Germany and Italy resist API integration with modern cloud-native platforms.
Strategic Opportunities
- Poland and Czechia:National digital identity programs in these Central European states remain in early procurement phases, offering first-mover positioning for multimodal suite vendors.
- EU Digital Identity Wallet:This framework mandate creates embedded biometric authentication demand across mobile government service applications.
- Edge-AI Convergence:On-device neural processing units combined with thermal imaging enable offline biometric verification for remote border checkpoints lacking reliable connectivity.
Industry Challenges
- Forensic Examiner Shortage:Latent fingerprint analysis requires specialized training pipelines that European police academies have scaled back, creating verification bottlenecks.
- Conformity Assessment Timelines:ETSI certification for facial recognition fairness metrics involves 14-18 month evaluation windows that delay contract eligibility.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Government and Security Biometrics Market |
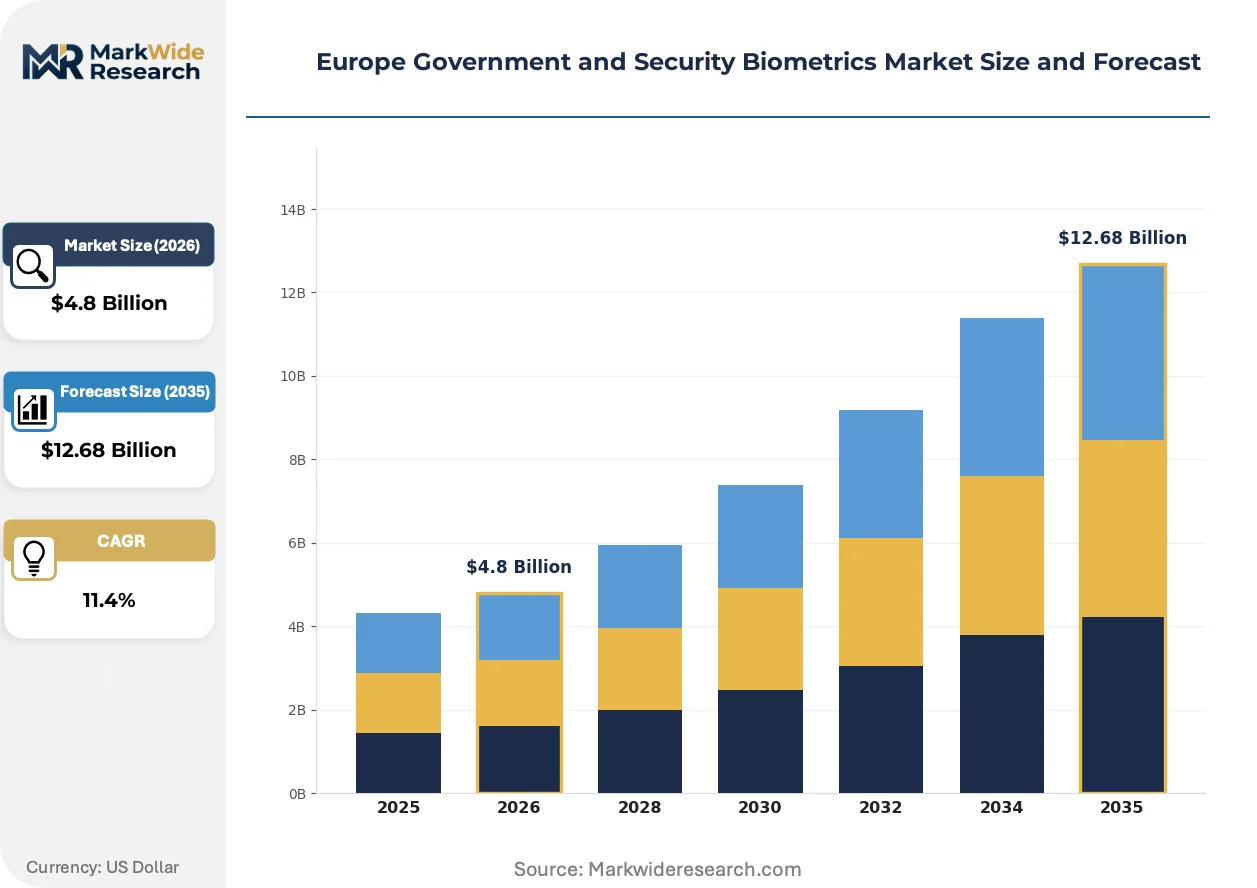
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $12.68 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fingerprint Recognition, Face Recognition, Iris Recognition, Voice Recognition End User: Government Agencies, Law Enforcement, Financial Institutions, Defense Technology: Multimodal Biometrics, Contactless Biometrics, Biometric Analysis Software, Wearable Biometrics Application: Identity Verification, Access Control, Time & Attendance, Border Security |
| Companies Covered | Innovatrics, BioID, Veridos GmbH, Fulcrum Biometrics, BIO-key International, IrisGuard Ltd, DERMALOG Identification Systems GmbH, id3 Technologies, Corsight AI, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Government and Security Biometrics Market Trends and Innovations
Contactless biometric modalities are overtaking touch-based systems as hygiene protocols harden into permanent procurement specifications, while algorithmic transparency requirements are rewriting vendor qualification criteria across member states.
Multimodal fusion engines that combine facial geometry with iris pattern recognition are rendering obsolete single-factor fingerprint terminals at high-throughput border checkpoints. Dutch and Belgian port authorities have accelerated deployment timelines for these contactless corridors. The structural consequence is collapsing hardware refresh cycles from seven years toward four-year replacement schedules.
The EU AI Act's prohibition of real-time remote biometric identification in publicly accessible spaces is forcing vendors to pivot toward consent-based authentication architectures. Interior ministries in Germany and Spain are rewriting technical specifications to exclude non-compliant algorithm versions from tender eligibility. Law enforcement segments are responding by concentrating investment on forensic post-event analysis tools rather than live surveillance systems.
Centralized procurement consortia are displacing individual ministry tendering across Nordic states, with Sweden, Denmark, and Norway coordinating biometric framework agreements through shared negotiation platforms. This buyer consolidation is compressing vendor margins while privileging suppliers with cross-border deployment experience. The shift is most visible in national ID card production contracts, where scale economies now dominate selection criteria over technical differentiation alone.
Europe Government and Security Biometrics Market Segmentation
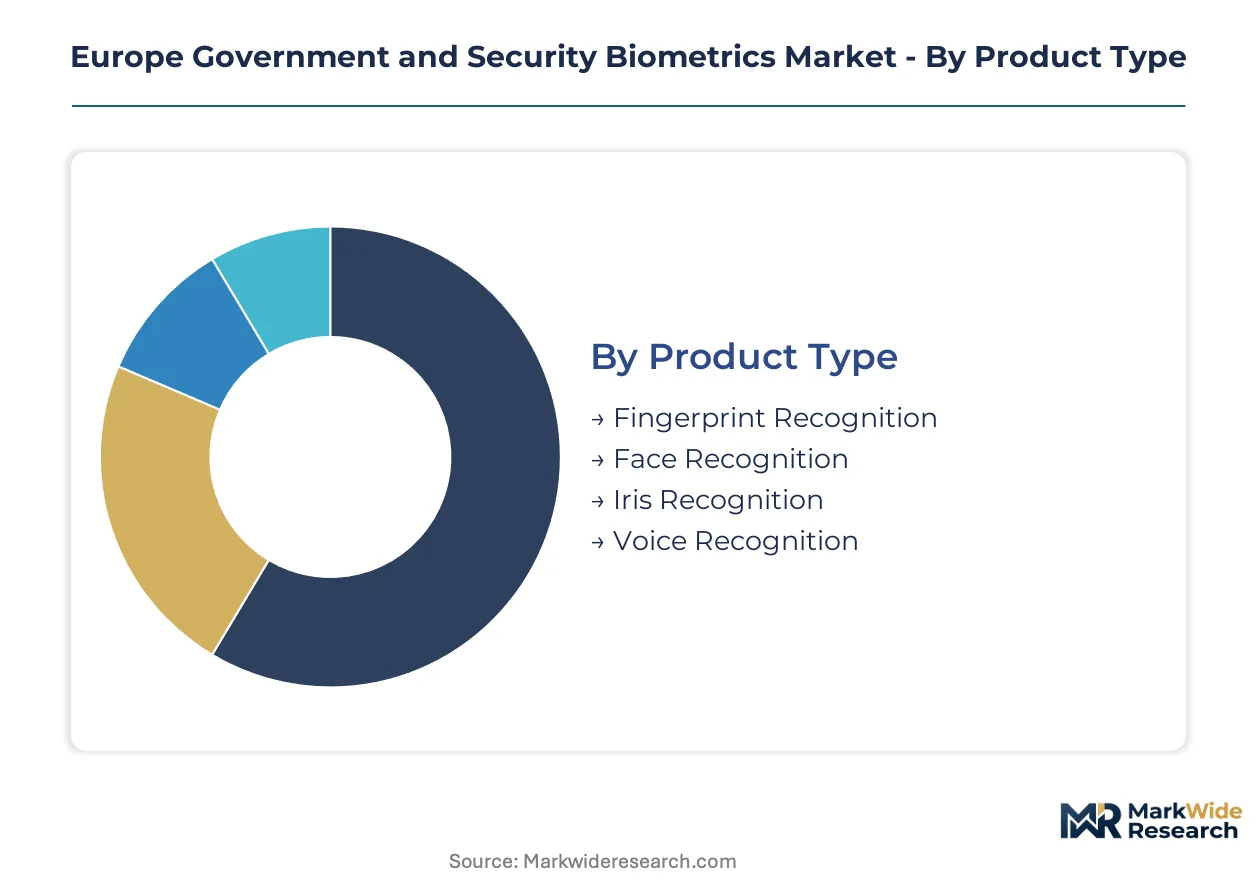
Biometric procurement patterns diverge sharply across European public sector verticals. National ID programs favor contactless modalities, while law enforcement clings to fingerprint architectures for database continuity. Understanding these segment fault lines reveals where vendor R&D investments will concentrate.
Product Type:
Technology selection hinges on accuracy thresholds, environmental conditions, and legacy system compatibility across deployment scenarios.
- Face Recognition:Algorithms now operate above 99.5% verification accuracy under variable lighting conditions. Schengen border agencies in Germany and France are installing contactless facial corridors at major airports to replace fingerprint queues. GDPR Article 9 special category processing rules are forcing vendors to re-engineer liveness detection pipelines for explicit consent architectures.
- Fingerprint Recognition:Ten-print and latent matching systems retain dominance in criminal identification due to INTERPOL and national AFIS database interoperability. German federal police maintain proprietary template formats that lock agencies into specific hardware vendors. The modality faces procurement headwinds as hygiene protocols accelerate touch-system phaseouts in civilian applications.
- Iris Recognition:Pattern-matching accuracy exceeds face recognition in one-to-many identification scenarios. Deployments concentrate at high-security defense facilities and data center access points.
- Voice Recognition:Speaker verification serves remote authentication for telephone-based government services. Adoption remains constrained by environmental noise sensitivity and deepfake spoofing vulnerabilities.
Fingerprint recognition commands the established base. The steepest expansion runs through face recognition.
End User:
Customer procurement authority determines compliance burden, contract scale, and technology specification rigor.
- Government Agencies:National interior ministries issue framework agreements covering passport issuance, voter registration, and social benefit authentication. French ANTS specifications for online ID card renewal mandate ISO 30107-3 Presentation Attack Detection certification.
- Law Enforcement:Forensic laboratories and criminal intelligence units require ten-print and latent fingerprint systems with 50,000+ DPI resolution. INTERPOL's biometric data exchange standards create cross-border interoperability mandates that constrain vendor selection.
- Financial Institutions:Customer onboarding and transaction authentication under PSD2 Strong Customer Authentication rules are driving biometric adoption. Compliance with EBA guidelines on remote identification creates demand for certified liveness detection modules.
- Defense:Classified facility access and deployed personnel identification require TEMPEST shielding and offline operation capability. NATO standardization agreements are harmonizing biometric data formats across member armed forces.
Law enforcement represents the most entrenched installed base. Financial institutions are gaining share fastest as digital banking penetration accelerates.
Technology:
Architecture choices separate vendors positioned for EU AI Act compliance from those facing obsolescence.
- Multimodal Biometrics:Fusion engines combining face and iris patterns reduce false acceptance rates below single-factor alternatives. Dutch port authorities and Belgian federal police have accelerated procurement timelines for multimodal corridors at high-throughput checkpoints.
- Contactless Biometrics:Thermal imaging and 3D structured light systems enable hygienic authentication without physical surface contact. Pandemic-era procurement specifications have hardened into permanent technical requirements across Nordic and German federal tenders.
- Biometric Analysis Software:Algorithm licensing and matching engine deployments allow hardware-agnostic system integration. Cloud-native architectures are displacing on-premise installations in smaller member state agencies.
- Wearable Biometrics:Continuous authentication bracelets and smart badges serve high-security facility perimeter control. Military pilot programs in Estonia and Latvia are testing soldier-worn identification for battlefield casualty management.
Contactless systems are displacing legacy touch-based architectures. Multimodal suites are climbing the fastest as border agencies consolidate procurement.
Application:
Use case requirements dictate hardware durability, throughput capacity, and integration complexity.
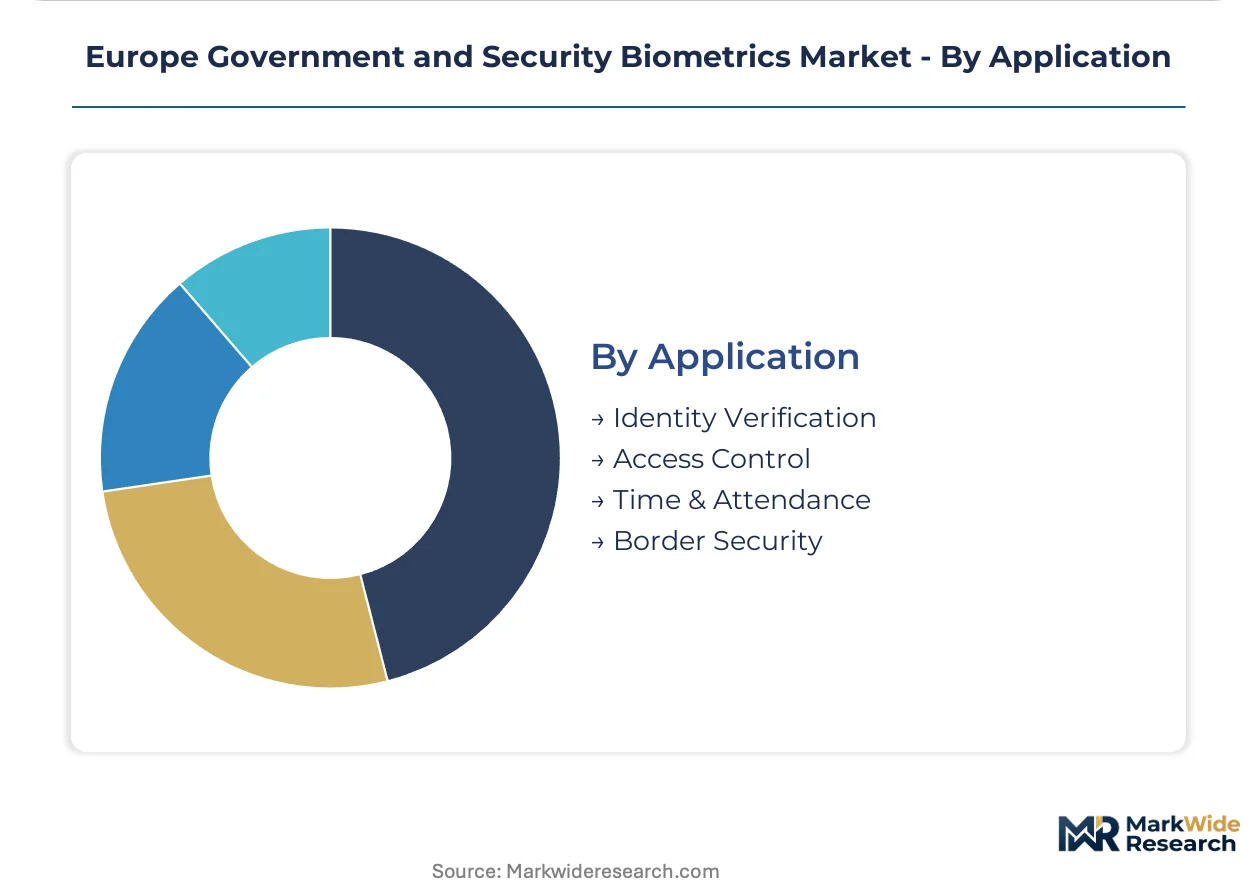
- Border Security:Automated border control gates process 15-20 travelers per minute with simultaneous passport chip and biometric verification. Eurostar terminals at London St. Pancras and Paris Gare du Nord represent reference deployments for multimodal contactless corridors.
- Identity Verification:Remote onboarding for digital government services requires smartphone-compatible face matching with anti-spoofing. France's National Identity Card modernization program is the largest European deployment of online biometric authentication.
- Access Control:Physical perimeter security for ministries, courts, and critical infrastructure combines biometric templates with smart card credentials. German BSI technical guidelines mandate local template storage to minimize data breach exposure.
- Time & Attendance:Civil servant workforce management systems track presence without personal data retention beyond payroll periods. GDPR storage limitation principles are forcing replacement of legacy systems with privacy-by-design alternatives.
Identity verification anchors current procurement volume. Border security is expanding most quickly as Schengen Area agencies modernize entry infrastructure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany deploys multimodal biometric corridors for border throughput, while France concentrates investment in online national ID authentication. Poland and Czechia lag in procurement maturity, creating divergent technology absorption patterns across the continent.
Germany
Federal police modernization drives demand for contactless border control systems at Frankfurt and Munich airports. The BSI technical guidelines mandate local template storage and GDPR-compliant data architecture. Berlin-Brandenburg hosts the largest concentration of biometric systems integrators serving interior ministry contracts.
France
The ANTS national identity card program generates sustained procurement for facial recognition with liveness detection. GDPR Article 9 special category processing rules shape vendor certification requirements. Paris anchors the market with reference deployments at Gare du Nord Eurostar terminals and government digital service portals.
United Kingdom
Post-Brexit border infrastructure investment accelerates replacement of legacy fingerprint systems. The UK GDPR retains Brussels-equivalent data protection standards for biometric processing. London concentrates demand through Heathrow e-gate expansion and Home Office framework agreements.
Poland
National digital identity programs remain in early procurement phases with multimodal suite specifications under development. The country's data protection authority enforces GDPR alignment with national administrative procedure codes. Warsaw serves as the procurement hub for Central European interior ministry coordination.
Netherlands
Port authorities at Rotterdam accelerate deployment of multimodal fusion engines for high-throughput cargo and passenger corridors. The Autoriteit Persoonsgegegens enforces strict purpose limitation for biometric data retention. Amsterdam Schiphol represents the reference installation for Schengen Area contactless border architecture.
Europe Government and Security Biometrics Market Competitive Landscape
Capability concentration sits with algorithm developers; scale advantage sits with manufacturing-integrated systems houses. The vendor base separates into three tiers: multinational defense contractors with government security clearances, specialized biometric algorithm developers, and document security manufacturers with embedded biometric modules. Competitive dynamics center on ETSI certification timelines and framework agreement positioning through centralized Nordic procurement consortia.
Within the algorithm development tier, Innovatrics and Corsight AI exemplify vendors competing for large-scale national ID contracts through algorithmic performance differentiation. Veridos GmbH anchors the document-integrated segment through direct relationships with German and neighboring interior ministries. DERMALOG Identification Systems GmbH occupies a position bridging hardware manufacturing and software licensing for law enforcement-grade deployments.
| Leading Market Players |
|---|
| Innovatrics |
| BioID |
| Veridos GmbH |
| Fulcrum Biometrics |
| BIO-key International |
| IrisGuard Ltd |
| DERMALOG Identification Systems GmbH |
| id3 Technologies |
| Corsight AI |
| Others |
Pricing and Supply Chain Analysis
German sensor foundries and Dutch semiconductor packaging houses command disproportionate influence over biometric hardware margins, concentrating value capture upstream while systems integrators downstream face compressed bidding windows on framework agreements.
Pricing Analysis
Long-term framework agreements with interior ministries dominate procurement, locking in volume commitments that span four-to-seven year replacement cycles. Three-tier pricing structure across premium, standard, and economy levels separates ETSI-certified multimodal suites from single-factor legacy hardware and uncertified commodity alternatives. Cost compression in the standard tier is intensifying because Nordic procurement consortia are consolidating buyer power through shared negotiation platforms. Law enforcement agencies exhibit lowest price sensitivity due to AFIS database lock-in, while municipal time-and-attendance systems face acute budget constraints.
Supply Chain Analysis
Contract manufacturing for biometric sensors concentrates in Germany, the Netherlands, and Taiwan, with EMS providers in these jurisdictions holding certified capacity for law enforcement-grade device assembly. Production draws from specialized CMOS image sensors, thermal imaging arrays, and neural processing units. Single-source vulnerability runs through certified fingerprint sensor manufacturing where three firms control law enforcement-grade supply. Distribution runs through systems integrators with interior ministry security clearances rather than open channel partners.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Biometric procurement cycles are recovering from pandemic-era delays as border modernization mandates and national ID program restarts release pent-up demand across member states.
For Market Incumbents: Harden algorithmic pipeline certification against EU AI Act deadlines to exclude non-compliant rivals from tender eligibility. Deepen backward integration into liveness detection module production to defend margins against commoditization of facial recognition engines. The threat of cloud-native platform entrants with API-first architectures demands proprietary template format retention. For New Entrants and Emerging Players: Establish a beachhead in Poland and Czechia national digital identity programs before specifications crystallize around incumbent technologies. White-space opportunity sits with edge-AI biometric verification for remote border checkpoints lacking connectivity infrastructure. Go-to-market leverage rests on partnerships with Nordic procurement consortia seeking fresh vendor alternatives. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed algorithm developers holding ETSI certification but lacking manufacturing scale for large-scale national ID contracts. Long-term viability favors vendors with cross-border deployment experience and direct interior ministry relationships. Monitor ETSI certification queue lengths as an inflection signal for competitive positioning shifts.| Strategic Initiative | Industry Significance |
|---|---|
| ETSI Certification Acceleration | Fast-tracks eligibility for French ANTS and German BSI framework agreements ahead of compliance deadlines. |
| Multimodal Fusion Engine Development | Captures Schengen border agency procurement as single-factor fingerprint systems face replacement mandates. |
| Nordic Procurement Consortium Positioning | Secures volume commitments through Sweden-Denmark-Norway shared negotiation platforms. |
| Edge-AI Biometric Module Launch | Addresses offline verification demand at remote Polish and Czechia border checkpoints. |
| GDPR-Compliant Cloud Architecture Deployment | Displaces on-premise legacy installations in smaller member state agencies seeking data minimization controls. |
Research Methodology
Desk research of ETSI technical specifications, EU AI Act regulatory filings, and national procurement databases preceded structured interviews with interior ministry procurement officers, biometric systems integrators, and algorithm development executives. Primary fieldwork with border agency technical directors and data protection authority officials was cross-referenced against INTERPOL biometric data exchange standards and GDPR Article 9 implementation guidance. Bottom-up project pipeline analysis was triangulated with top-down framework agreement value aggregation.
Assumptions held fixed include EU AI Act enforcement timelines, Schengen Area border modernization funding allocations, and ETSI certification throughput capacity; variables tested included national digital identity program acceleration scenarios and procurement consortium expansion patterns. Segmentation modeling covered biometric modality, end-user vertical, deployment architecture, and member state regulatory cluster. CAGRs were derived from contract award velocity analysis and replacement cycle compression trends, with inputs from liveness detection certification queue data and multimodal corridor deployment announcements.
Macroeconomic conditions sit as an overlay; deviation in interior ministry IT capital expenditure budgets or EU cohesion fund allocations would shift the trajectory. Forecasts reflect assumptions regarding certification timeline stability and procurement consortium consolidation pace. Quarterly review of ETSI certification approval rates and national tender publication volumes is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biometrics & Identity Management
Italy Mobile Biometrics Market
Biometrics & Identity Management
Global Authentication Services Market
Biometrics & Identity Management
Mobile Biometric Security and Services Market
Biometrics & Identity Management
Palm Vein Biometrics Market
Biometrics & Identity Management
Airport Biometrics Market
Biometrics & Identity Management
Biometric Services Platform (Biosp) Market
Biometrics & Identity Management
Global Multifactor Authentication Market
Biometrics & Identity Management
Physical Identity and Access Management (PIAM) Software Market
Biometrics & Identity Management
Global Biometric Systems Market
Biometrics & Identity Management
Middle East and Africa Biometrics in Government Market
Biometrics & Identity Management
Identity Theft Protection Services Market
Biometrics & Identity Management
Biometric Data Encryption Device Market
Biometrics & Identity Management
Global Behavioral Biometrics Market
Biometrics & Identity Management
Biometric Passport Market
Biometrics & Identity Management
Mobile Devices User Authentication Services Market
Biometrics & Identity Management
Biometric Bike Locks Market