
 Global Biometric Systems Market | 2026-2036
Global Biometric Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Global Biometric Systems Market Foresight
The capability gap between full-stack hardware-software integrators and component-only vendors is collapsing as cloud-based biometric platforms commoditize sensor middleware. Thales Group leverages its defense-electronics heritage to anchor high-assurance government contracts across NATO member states. NEC Corporation dominates large-scale facial recognition infrastructure in Asia-Pacific smart city deployments. IDEMIA sustains market presence through its civil identity portfolio and chip-based credential manufacturing scale.
Biometric systems encompass automated methods for recognizing individuals based on physiological or behavioral characteristics, typically operating through fingerprint minutiae extraction, iris pattern encoding, or facial geometry mapping against templates stored in encrypted databases. These systems serve critical functions in identity verification, access authorization, and fraud prevention across physical and digital environments. Fingerprint recognition retains the largest installed base among biometric technologies due to mature sensor economics and embedded mobile integration, while facial recognition captures the fastest expansion as contactless protocols gain preference in public transit and retail banking authentication. Among deployment modes, cloud-based architectures are displacing on-premises installations in mid-market financial institutions seeking elastic capacity without capital-intensive server farms.
The U.S. National Institute of Standards and Technology publishes biometric performance testing protocols that shape procurement specifications for federal agencies, while the EU AI Act imposes strict conformity requirements on real-time remote biometric identification systems in publicly accessible spaces. India's UIDAI mandates interoperability standards for Aadhaar authentication devices, creating a regulated hardware ecosystem that limits unapproved vendor participation. Stakeholders must monitor divergence between permissive and restrictive regulatory regimes to anticipate where multimodal biometric investments will face accelerated approval or outright prohibition.
Market Dynamics
Cloud-native biometric platforms are collapsing the traditional hardware-software integration moat, forcing established vendors to rearchitect around API-first delivery models or cede mid-market financial services contracts to software-native entrants.
Growth Catalysts
- EU AI Act Conformity Mandates:Risk classification frameworks for remote biometric identification in publicly accessible spaces are compelling European system integrators to accelerate multimodal system upgrades, expanding addressable hardware and compliance services demand.
- Contactless Authentication Protocols:Public transit authorities and retail banking networks across India and the United States are prioritizing facial and iris recognition over fingerprint sensors, driving sensor replacement cycles and new enrollment infrastructure.
- Aadhaar-Linked Ecosystem Expansion:India's UIDAI interoperability mandates for state-level digital identity programs are creating regulated device procurement pipelines that lock in certified hardware vendors across healthcare, ration distribution, and financial inclusion schemes.
Market Restraints
- Specialized Image Sensor Supply Concentration:High-resolution infrared and time-of-flight sensor modules for facial recognition depend on concentrated East Asian foundry capacity, exposing biometric OEMs to allocation volatility during semiconductor demand surges.
- Template Storage Encryption Overhead:FIPS 140-2 Level 3 and Common Criteria EAL4+ certification requirements for government biometric databases impose 18-24 month validation timelines that compress vendor margins and delay revenue recognition.
- Behavioral Biometric Substitution:Keystroke dynamics and gait analysis software solutions are capturing low-assurance authentication use cases in fintech and remote work access, eroding price positioning for physiological biometric hardware in tier-two banking segments.
Strategic Opportunities
- Edge AI Inference Convergence:On-device neural processing unit integration with biometric sensor modules is enabling offline authentication for critical infrastructure sites in bandwidth-constrained environments across Brazil and Indonesia.
- Health-Biometric Fusion Applications:Contactless vital sign extraction through facial thermography and pulse detection is opening hospital patient identification and remote monitoring adjacencies that extend hardware lifecycle value beyond pure identity verification.
- India's PLI Scheme for Electronics:Production-linked incentive disbursements for semiconductor assembly and testing are attracting biometric device manufacturers to establish captive manufacturing in Gujarat and Tamil Nadu, reducing import duty exposure and qualifying for government contract eligibility.
Industry Challenges
- Multimodal Algorithm Integration Complexity:Fingerprint, facial, and iris fusion systems require specialized machine learning engineering talent that remains concentrated at Thales, NEC, and IDEMIA, constraining mid-tier vendors from delivering competitive accuracy benchmarks.
- Legacy Civil Registry System Interoperability:National ID databases built on proprietary template formats in France, Germany, and Japan force biometric vendors to maintain costly format conversion middleware, fragmenting engineering resources across incompatible national standards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Biometric Systems Market |
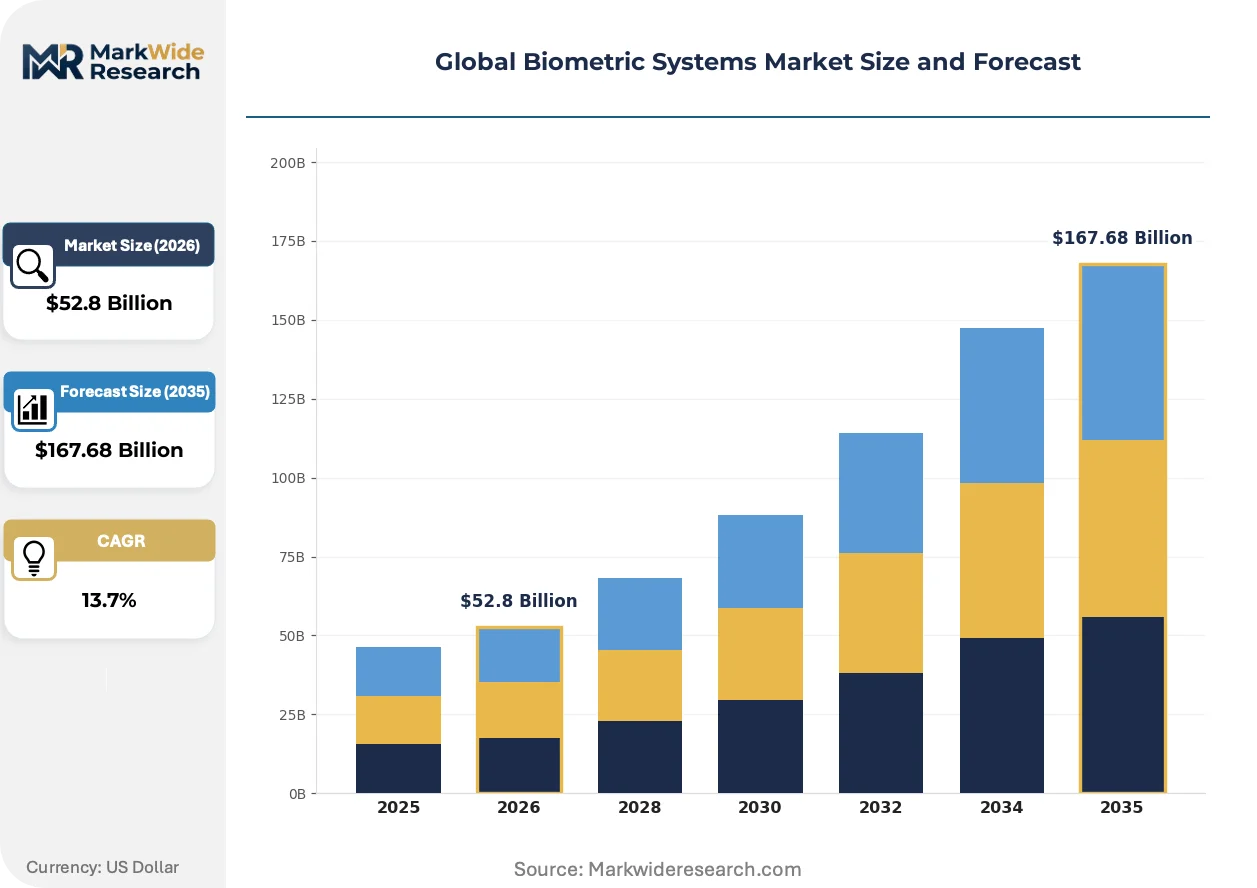
| Market Size in 2026 | $52.8 Billion |
| Market Size in 2035 | $167.68 Billion |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Biometric Technology: Fingerprint Recognition, Facial Recognition, Iris Recognition, Voice Recognition, Palm Vein Recognition, Signature Verification Application: Access Control, Time & Attendance, Border Security, Banking Authentication, E-Governance, Law Enforcement End User: Government Agencies, Financial Institutions, Healthcare Providers, Education Sector, Transportation Operators, Telecommunication Companies Deployment Mode: On-Premises, Cloud-Based, Hybrid Systems, Mobile Platforms, Embedded Systems |
| Companies Covered | Thales Group, IDEMIA, NEC Corporation, HID Global Corporation, Fujitsu Limited, ASSA ABLOY, Suprema Inc., Aware Inc., Precise Biometrics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Biometric Systems Market Shifts & Advancements
Biometric authentication is fragmenting across hardware form factors and deployment topologies, with edge inference, regulatory segmentation, and buyer procurement rationalization each pulling the vendor base in divergent technical directions.
Silicon photonics-based iris scanning modules are miniaturizing from dedicated kiosk enclosures to smartphone-embeddable form factors without sacrificing NIST-compliant matching accuracy. Automotive OEMs and luxury device manufacturers are sampling these sub-5mm modules for driver monitoring and secure device unlock. This compression is collapsing the historical separation between consumer mobile and high-assurance government biometric supply chains.
France's CNIL and Germany's federal data protection authorities are interpreting the EU AI Act's real-time remote biometric identification prohibitions more restrictively than southern member states, creating a compliance patchwork that forces multinational deployments to default to the strictest national standard. Banking and critical infrastructure operators in Paris and Frankfurt are pre-emptively disabling live facial recognition in favor of opt-in, on-device template matching. This divergence is fragmenting product roadmaps and inflating pan-European certification costs.
Subscription-based biometric-as-a-service contracts are displacing perpetual license sales in mid-market North American healthcare and education sectors, compressing upfront revenue recognition and shifting vendor cash flow profiles toward annual recurring metrics. Value-added resellers and systems integrators are capturing recurring authentication transaction fees that hardware OEMs previously monopolized. This reconfiguration is most visible in United States hospital network expansions, where IT departments prioritize OpEx-aligned procurement over capital-intensive on-premises biometric infrastructure.
Global Biometric Systems Market Segmentation
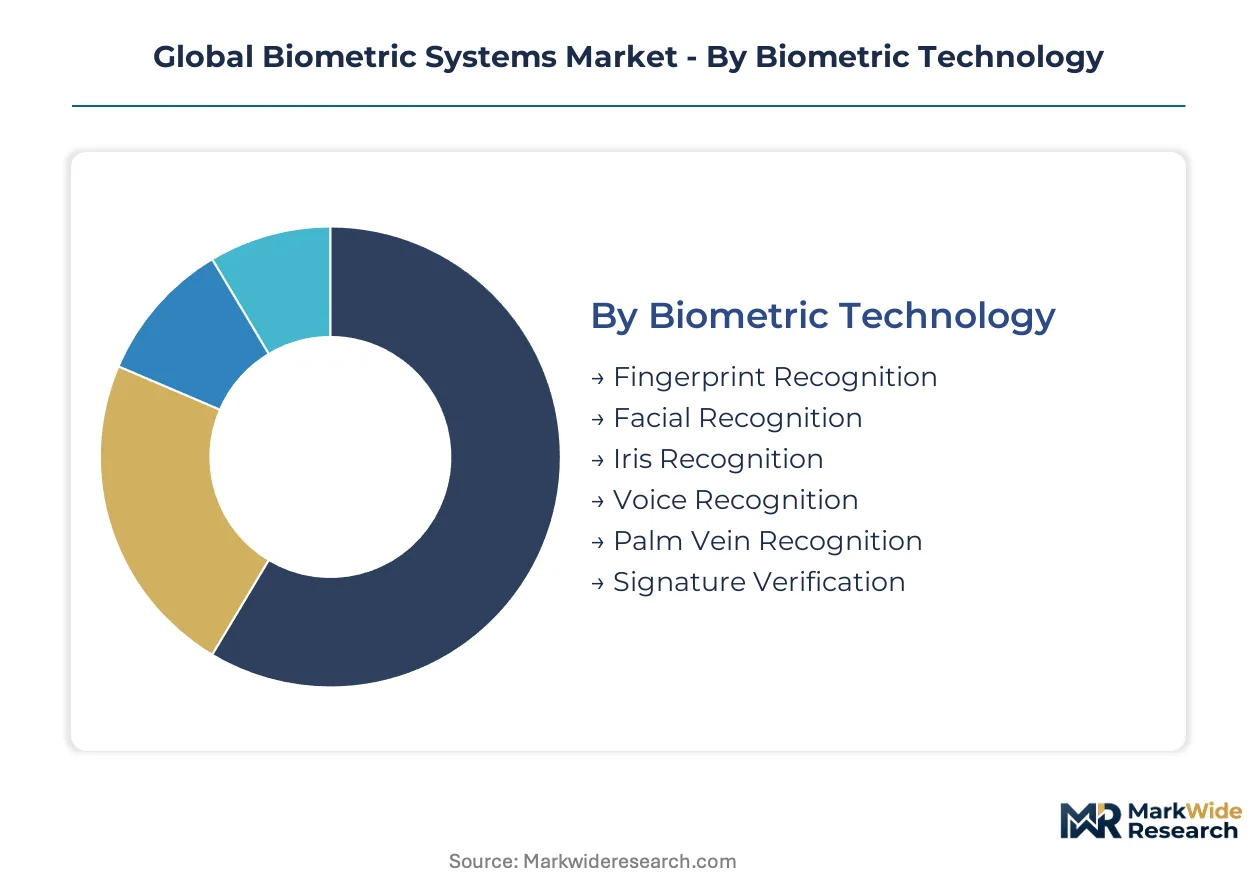
Biometric systems fragment across four intersecting dimensions that determine procurement patterns, margin structures, and regulatory exposure. Technology selection drives hardware economics. Application context dictates certification requirements. End-user type shapes contract duration and integration complexity. Deployment mode determines whether vendors capture recurring service revenue or one-time equipment sales.
Biometric Technology:
Domestic demand concentration varies sharply by modality, with fingerprint and facial recognition systems serving primarily internal national ID programs while iris and palm vein technologies depend more heavily on export markets in the Gulf and Southeast Asia.
- Facial Recognition:Contactless geometry mapping against encrypted template databases now dominates public transit and retail banking authentication. Indian metro authorities and U.S. airport security agencies are replacing fingerprint sensors with thermal-compatible facial systems to eliminate physical contact points.
- Fingerprint Recognition:Minutiae extraction from capacitive or optical sensors retains the largest installed base through embedded mobile integration and Aadhaar-linked device certification. UIDAI interoperability mandates in India lock in certified hardware vendors across healthcare and financial inclusion schemes.
- Iris Recognition:Pattern encoding from near-infrared imaging serves high-assurance border control and national ID applications, with demand concentrating in UAE immigration systems and India's rural authentication expansion.
- Voice Recognition:Spectral analysis of vocal characteristics captures call center authentication and remote banking verification, though accuracy degradation in noisy environments limits physical access control deployment.
- Palm Vein Recognition:Subcutaneous vascular pattern scanning offers liveness detection superior to surface biometrics, finding niche adoption in Japanese banking ATM networks and Brazilian healthcare patient identification.
- Signature Verification:Dynamic stroke analysis of pressure, velocity, and acceleration persists in document fraud prevention for European insurance underwriting and South Korean financial contract validation.
Fingerprint recognition commands the established base. The steepest expansion runs through facial recognition.
Application:
Cost tier stratification separates capital-intensive border infrastructure from lightweight SaaS deployments, with law enforcement and e-governance occupying opposite ends of the integration expense spectrum.
- Border Security:Multimodal enrollment and verification systems at immigration checkpoints require NIST-tested algorithms and FIPS 140-2 Level 3 encryption. U.S. Customs and Border Protection and India's Bureau of Immigration drive specification-setting for this segment.
- Banking Authentication:Regulatory pressure from RBI in India and the EU's PSD2 strong customer authentication mandate is accelerating biometric card and mobile app deployment. Contactless protocols are displacing PIN entry at ATM networks.
- Access Control:Physical entry systems for critical infrastructure and corporate facilities span biometric readers, turnstile integration, and identity management middleware. Demand concentrates in Saudi Aramco facilities and German automotive manufacturing plants.
- E-Governance:Citizen-facing service delivery platforms in India's state-level digital identity programs and Brazil's Cadastro de Pessoas Físicas integration require interoperability-certified devices.
- Time & Attendance:Workforce management systems in Indonesian manufacturing and Mexican maquiladora operations prioritize low-cost fingerprint terminals over multimodal alternatives.
- Law Enforcement:Forensic identification and real-time surveillance applications face the strictest EU AI Act restrictions, fragmenting product roadmaps between permissive and restrictive jurisdictions.
Access control captures the volume base. The most rapid climb occurs in banking authentication.
End User:
Customer type determines contract structure, with government agencies demanding source code escrow and financial institutions prioritizing API-first integration over hardware ownership.
- Government Agencies:National ID, border control, and law enforcement procurement drives multimodal system specifications. UIDAI in India and DHS in the United States mandate interoperability standards that limit vendor participation to certified integrators.
- Financial Institutions:Retail banks and payment networks prioritize cloud-native authentication platforms with elastic transaction scaling. RBI guidelines and EU PSD2 compliance frameworks shape procurement priorities.
- Healthcare Providers:Patient identification and electronic health record access systems in U.S. hospital networks and India's Ayushman Bharat scheme require HIPAA or equivalent data protection compliance.
- Transportation Operators:Public transit authorities in Singapore, London, and Delhi Metro are deploying contactless facial recognition for fare collection and passenger flow management.
- Education Sector:Campus access and examination proctoring applications in Chinese universities and Nigerian secondary schools drive mid-tier hardware demand.
- Telecommunication Companies:Subscriber identity verification for SIM registration in Pakistan, Bangladesh, and African markets employs low-cost fingerprint tablets.
Government agencies anchor procurement volume. Financial institutions are gaining share fastest.
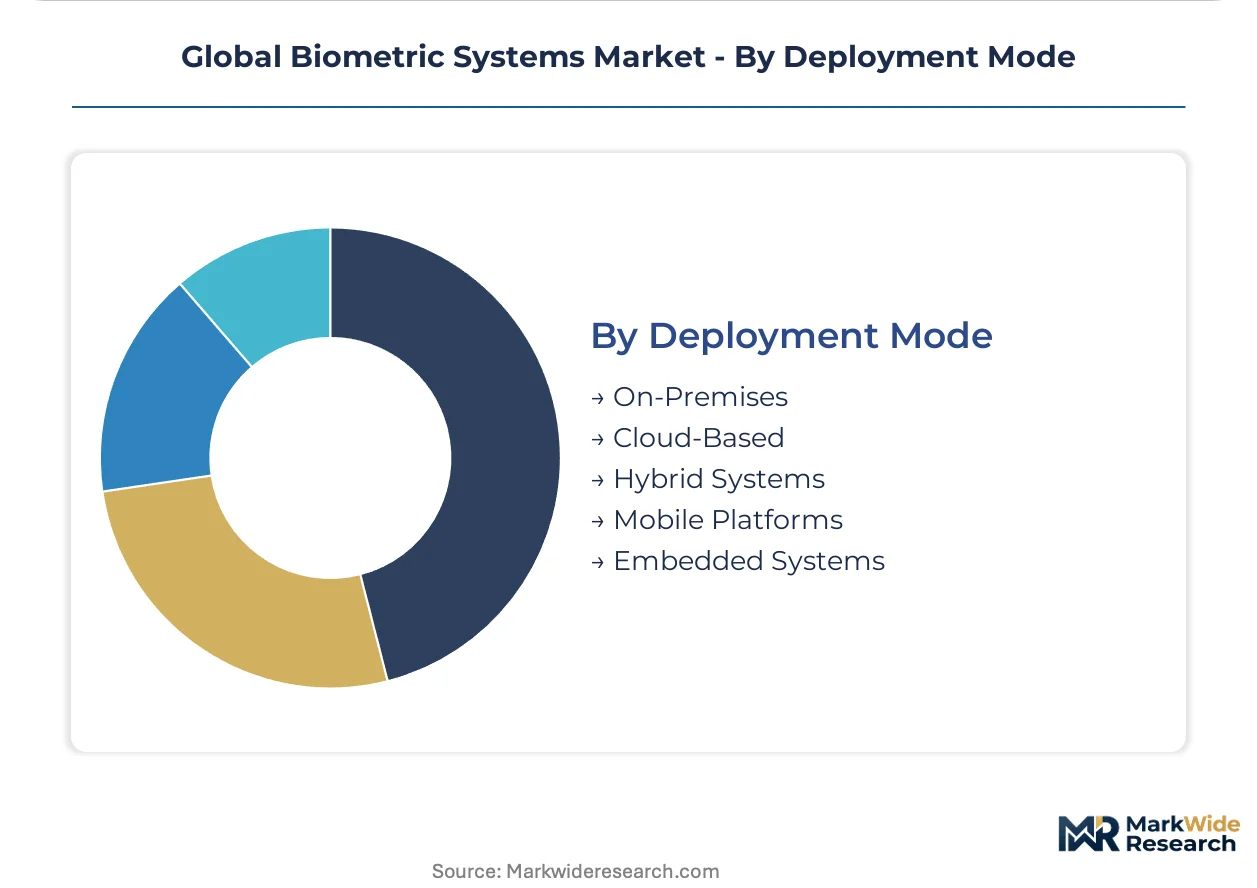
Deployment Mode:
Supply concentration in cloud infrastructure services is shifting margin capture from hardware OEMs toward platform operators and systems integrators.
- Cloud-Based:API-delivered biometric matching services eliminate on-premises server requirements. Mid-market North American healthcare and education sectors are displacing perpetual licenses with subscription contracts.
- On-Premises:Dedicated biometric data centers remain mandatory for government and critical infrastructure operators in France, Germany, and India with data localization requirements.
- Hybrid Systems:Template storage on-premises with cloud-based analytics processing splits compliance and scalability requirements. Japanese financial institutions favor this architecture.
- Mobile Platforms:Smartphone-embedded biometric sensors and SDK-based authentication apps capture consumer-facing fintech and remote workforce access use cases.
- Embedded Systems:Edge AI inference on dedicated neural processing units enables offline authentication for Brazilian mining operations and Indonesian plantation security with limited connectivity.
On-premises systems retain the established base. Cloud-based deployment is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power in the United States exceeds that in India by a factor of three, reflecting divergent procurement sophistication and certification stringency. European integrators command intermediate premiums contingent on EU AI Act compliance investments. East Asian sensor manufacturers capture value through concentrated foundry capacity.
United States
Department of Homeland Security procurement drives multimodal border infrastructure upgrades at land ports and international airports. NIST biometric performance testing protocols shape federal agency specifications and vendor qualification. Thales Group leverages its defense-electronics heritage to anchor high-assurance contracts across NATO member states from its operational presence in Maryland and Virginia corridors.
India
UIDAI interoperability mandates for Aadhaar-linked devices create regulated procurement pipelines across healthcare and financial inclusion schemes. RBI guidelines on strong customer authentication accelerate biometric card deployment at ATM networks. Production-linked incentive disbursements for semiconductor assembly attract device manufacturers to establish captive operations in Gujarat and Tamil Nadu manufacturing clusters.
Germany
Federal data protection authorities interpret EU AI Act prohibitions on real-time remote biometric identification more restrictively than southern member states. Critical infrastructure operators in Frankfurt and Munich pre-emptively disable live facial recognition in favor of opt-in on-device template matching. Automotive OEMs in Baden-Württemberg sample silicon photonics-based iris modules for driver monitoring systems.
China
Smart city deployments in Beijing-Tianjin-Hebei and Yangtze River Delta corridors sustain large-scale facial recognition infrastructure demand. MIIT standards for biometric data security shape domestic vendor qualification and foreign market access. Concentrated East Asian foundry capacity for high-resolution infrared and time-of-flight sensor modules exposes OEMs to allocation volatility during semiconductor demand surges.
United Arab Emirates
UAE immigration systems drive high-assurance iris recognition demand for border control and national ID applications. MOHAP health-biometric fusion specifications open hospital patient identification adjacencies extending hardware lifecycle value. Dubai and Abu Dhabi smart city authorities prioritize contactless authentication protocols for public transit fare collection and passenger flow management.
Global Biometric Systems Market Competitive Landscape
Concentration sits with full-stack hardware-software integrators possessing defense-electronics heritage and civil identity manufacturing scale. The vendor base separates into three tiers: multinational conglomerates with government security credentials, specialized biometric technology developers with algorithmic intellectual property, and regional systems integrators with localized certification relationships. Two competitive moves dominate: cloud-native platform rearchitecture to capture mid-market financial services contracts, and production-linked incentive-driven manufacturing relocation to India for government contract eligibility.
Within the multinational integrator tier, Thales Group and NEC Corporation exemplify divergent geographic anchoring strategies. Thales occupies a position shaped by NATO-aligned defense-electronics procurement relationships across European and North American government agencies. NEC Corporation sits within Asia-Pacific smart city infrastructure deployment patterns, particularly in facial recognition systems for large-scale public transit and urban surveillance networks. IDEMIA represents the civil identity specialization archetype, with chip-based credential manufacturing scale sustaining market presence across regulated government authentication ecosystems.
| Leading Market Players |
|---|
| Thales Group |
| IDEMIA |
| NEC Corporation |
| HID Global Corporation |
| Fujitsu Limited |
| ASSA ABLOY |
| Suprema Inc. |
| Aware Inc. |
| Precise Biometrics |
| Others |
Supply & Pricing Matrix
Take-or-pay capacity reservation contracts with East Asian foundries lock in biometric OEMs to 18-24 month pricing visibility for infrared sensor modules while exposing them to allocation rationing during semiconductor demand cycles. This structure concentrates procurement leverage with sensor suppliers and compresses margin flexibility for system integrators serving price-sensitive Indian government tenders.
Pricing Analysis
Configured-to-order pricing for multimodal border security systems commands substantial premiums over standard fingerprint terminal SKUs. Three-tier pricing structure across premium, standard, and economy levels separates FIPS 140-2 Level 3 certified government installations from mid-market healthcare SaaS subscriptions and low-cost Aadhaar-authentication tablets. Pricing pressure stems from cloud-native platform entrants undercutting perpetual license models in North American financial services. Government agencies exhibit lowest price sensitivity due to certification mandates, while Indonesian manufacturing buyers drive aggressive procurement terms for time-and-attendance hardware.
Supply Chain Analysis
Inventory lead times for high-resolution time-of-flight sensor modules stretch to six quarters during foundry allocation cycles, forcing biometric OEMs into speculative component commitments. Manufacturing concentrates in China, Taiwan, and South Korea for infrared imaging sensors, with assembly increasingly shifting to Gujarat and Tamil Nadu under India's PLI scheme. Raw material dependencies span silicon wafers, near-infrared optical coatings, and neural processing unit chipsets. Single-source vulnerability runs through concentrated East Asian foundry capacity for specialized image sensors. Distribution runs through certified systems integrators for government contracts and direct OEM relationships for cloud platform deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The biometric systems market sits at an inflection where EU AI Act risk classifications are fragmenting product roadmaps and accelerating compliance investments ahead of enforcement deadlines.
For Market Incumbents: Consolidate algorithmic IP through targeted acquisition of specialized machine learning engineering teams concentrated at mid-tier vendors. Deepen captive manufacturing presence in India via PLI-qualified assembly operations to secure government contract eligibility against emerging local competitors. Cloud-native platform entrants threaten perpetual license revenue in North American healthcare; counter through API-first rearchitecture and subscription pricing migration. For New Entrants and Emerging Players: Anchor in edge AI inference for bandwidth-constrained critical infrastructure sites across Brazil and Indonesia where offline authentication creates hardware pull-through. Health-biometric fusion applications in hospital patient identification represent the most penetrable white space, extending device lifecycle value beyond pure identity verification. Pursue go-to-market partnerships with established medical device distributors to bypass lengthy hospital procurement cycles. For Investors and Strategic Acquirers: The market sits at a platform-transition phase that favors software-native authentication platforms with recurring revenue profiles over hardware-dependent legacy vendors. Long-term viability favors vendors possessing both government security credentials and cloud-native delivery capability. Monitor EU AI Act enforcement divergence between restrictive northern member states and permissive southern jurisdictions as the critical signal for where multimodal biometric investments face accelerated approval or outright prohibition.| Strategic Initiative | Industry Significance |
|---|---|
| API-First Platform Rearchitecture | Captures mid-market financial services contracts from legacy hardware vendors migrating to cloud-native delivery. |
| PLI-Driven Manufacturing Relocation | Establishes India-based assembly eligibility for UIDAI-certified device procurement in Aadhaar-linked programs. |
| Multimodal Algorithm Acquisition | Consolidates scarce machine learning engineering talent for fingerprint-facial-iris fusion system development. |
| Health-Biometric Fusion Development | Opens hospital patient identification adjacencies through contactless vital sign extraction from facial thermography. |
| EU AI Act Compliance Certification | Enables continued real-time biometric deployment in publicly accessible spaces under strict conformity assessment. |
Research Methodology
A spread of perspectives from biometric systems engineers, government procurement officers at DHS and UIDAI, cloud platform architects at financial institutions, and semiconductor supply chain managers converged on the working assumptions underlying this analysis. Primary fieldwork combined structured interviews with secondary validation against NIST biometric performance testing protocols, EU AI Act regulatory filings, RBI authentication guidelines, SEC 10-K disclosures from listed vendors, and customs data on biometric device trade flows. Bottom-up unit economics for sensor modules and top-down addressable market sizing were triangulated against reported contract values.
Segmentation dimensions modeled span biometric technology modality, application context from border security to banking authentication, end-user type across government and commercial sectors, and deployment mode from on-premises to cloud-native. CAGRs were derived from regression analysis of historical procurement volumes against regulatory mandate timelines and technology substitution curves. Forecast inputs incorporated UIDAI device certification pipelines, EU AI Act implementation schedules, and cloud infrastructure capex trajectories from hyperscaler disclosures.
Material uncertainties — foundry allocation volatility, regulatory enforcement divergence across EU member states, and behavioral biometric substitution rates — sit outside the modeled envelope. Forecasts reflect assumptions about interoperability mandate adherence and cloud migration velocity that could revise materially. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biometrics & Identity Management
Global Biometric-As-A-Service Market
Biometrics & Identity Management
Mobile Devices User Authentication Services Market
Biometrics & Identity Management
Europe Biometrics Market
Biometrics & Identity Management
Latin America Government & Security Biometrics Market
Biometrics & Identity Management
Asia-Pacific Government and Security Biometrics Market
Biometrics & Identity Management
Germany Identity Verification and Authentication Market
Biometrics & Identity Management
Middle East and Africa Biometrics in Government Market
Biometrics & Identity Management
Biometric Services Platform (Biosp) Market
Biometrics & Identity Management
Biometric Passport Market
Biometrics & Identity Management
Global Voice Biometrics Market
Biometrics & Identity Management
Fingerprint Biometrics Market
Biometrics & Identity Management
Voice Biometric Solutions Market
Biometrics & Identity Management
Mobile Biometric Security and Services Market
Biometrics & Identity Management
Global Authentication Services Market
Biometrics & Identity Management
Multi-Factor Authentication (MFA) Market
Biometrics & Identity Management
Global Human Identification Market