
 Italy Mobile Biometrics Market | 2026-2036
Italy Mobile Biometrics Market Size, Share, and Industry Trends Forecast 2026-2036
Italy Mobile Biometrics Market Insights
Silicon-based capacitive fingerprint sensors are recalibrating hardware economics as polymer substrates displace legacy ceramic modules in mid-tier devices. NEC Corporation leverages its algorithm portfolio to anchor high-assurance government contracts. IDEMIA competes through manufacturing scale across European credentialing programs. Thales Group differentiates via dual-use defense-to-civilian technology transfer.
Italy Mobile Biometrics encompasses portable authentication systems that capture, process, and match physiological or behavioral traits through onboard sensors with template storage capacities typically below 500KB per enrolled identity, serving to bind digital transactions to verified individuals. Fingerprint scanners retain the largest installed base among product types, though facial recognition captures the fastest expansion as liveness detection standards harden. Cloud-based solutions within the technology dimension concentrate margin pools through subscription architectures, while on-premises systems dominate in defense and critical infrastructure applications where data sovereignty constraints apply.
Italy's national data protection authority enforces GDPR biometrics provisions alongside the EU AI Act's risk-classification framework for remote identification systems, compressing deployment timelines for non-compliant vendors. The European Banking Authority's strong customer authentication mandates under PSD2 sustain institutional procurement of multi-modal mobile platforms. Stakeholders must monitor divergence between Italian supervisory interpretations and EU-level implementing acts as enforcement crystallizes.
Market Dynamics
The convergence of EU AI Act risk classifications with GDPR biometric provisions is compressing vendor compliance timelines while simultaneously creating procurement preference for privacy-preserving algorithm architectures in Italian mobile deployments.
Growth Catalysts
- PSD2 Strong Customer Authentication:The European Banking Authority's mandates sustain institutional procurement of multi-modal mobile platforms across Lombardy's fintech corridor.
- Liveness Detection Standards:Hardening technical requirements for presentation attack detection are accelerating facial recognition deployment in high-assurance government credentialing applications.
- Polymer Substrate Economics:Silicon-based capacitive fingerprint sensors utilizing polymer substrates are recalibrating hardware cost structures for mid-tier device manufacturers.
Market Restraints
- GDPR Biometric Data Friction:Italy's national data protection authority enforces strict consent and storage limitations that lengthen enterprise sales cycles and increase legal review costs.
- Defense Contractor Supply Concentration:Dual-use technology transfer dependencies on Thales Group and limited qualified system integrators in the Milan-Genoa corridor create bottleneck risks.
- Template Storage Limitations:Onboard capacities below 500KB per enrolled identity constrain multi-modal enrollment in resource-constrained edge deployments.
Strategic Opportunities
- Sicily and Southern Italy Underpenetration:Financial inclusion initiatives and public digital identity programs present whitespace for mobile biometric service expansion outside the dominant northern industrial triangle.
- Cloud-Based Subscription Architectures:Margin pool concentration through SaaS delivery models offers recurring revenue capture as banks migrate from on-premises authentication stacks.
- Behavioral Biometrics Convergence:Integration of keystroke dynamics and gait analysis with physiological modalities creates differentiated product positioning for fraud prevention vendors.
Industry Challenges
- Algorithm Audit and Certification Talent Scarcity:Shortage of professionals capable of conducting conformity assessments under EU AI Act high-risk system requirements delays product launches.
- Legacy Banking Core Integration Complexity:Mainframe authentication protocols in Italy's established financial institutions require costly middleware development for biometric API connectivity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Italy Mobile Biometrics Market |
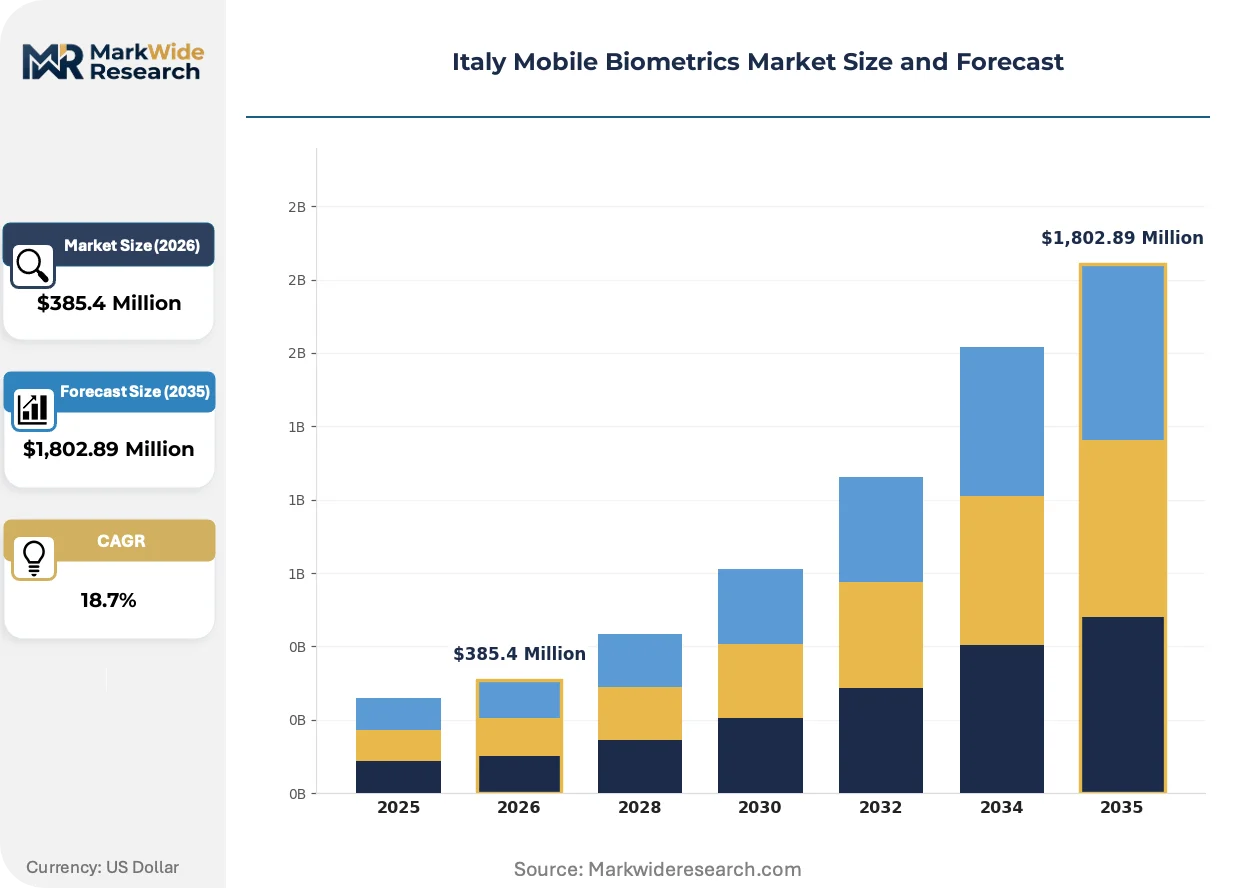
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $1,802.89 Million |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fingerprint Scanners, Iris Scanners, Facial Recognition, Voice Recognition Technology: Biometric Sensors, Cloud-Based Solutions, On-Premises Systems, Mobile Applications End User: Government Agencies, Financial Institutions, Retailers, Healthcare Providers Application: Identity Verification, Access Control, Time Tracking, Payment Authentication |
| Companies Covered | NEC Corporation, IDEMIA, Thales Group, HID Global, Aware, Gemalto, Zebra Technologies, Innovatrics, Precise Biometrics, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Italy Mobile Biometrics Market Trends and Innovations
Privacy-preserving computation techniques and edge AI inference are rewriting the technical foundations of mobile biometric authentication, while regulatory enforcement crystallizes competitive differentiation around compliance architecture rather than raw accuracy metrics.
Homomorphic encryption and secure enclave processing is rewriting how template matching executes on-device, eliminating plaintext biometric exposure during authentication sessions. Italian fintech clusters in Milan are piloting these architectures for PSD2-compliant strong customer authentication. The shift is compressing liability exposure for data controllers while raising hardware performance requirements.
The EU AI Act's risk-classification framework for remote identification systems is mandating algorithmic impact assessments and human-in-the-loop protocols for high-risk deployments. Financial institutions must document conformity with both this framework and GDPR biometric provisions before procurement approval. The Lombardy fintech corridor is experiencing the most concentrated compliance investment as institutions pre-empt supervisory enforcement.
Consumption patterns among Italian banking customers are favoring seamless authentication experiences that eliminate explicit app launches. Demand for passive behavioral verification layered behind device unlock flows is displacing active fingerprint or facial capture prompts in retail banking applications. This preference shift is most visible in Genoa's merchant acquirer ecosystem, where checkout friction reduction drives vendor selection criteria.
Italy Mobile Biometrics Market Segmentation
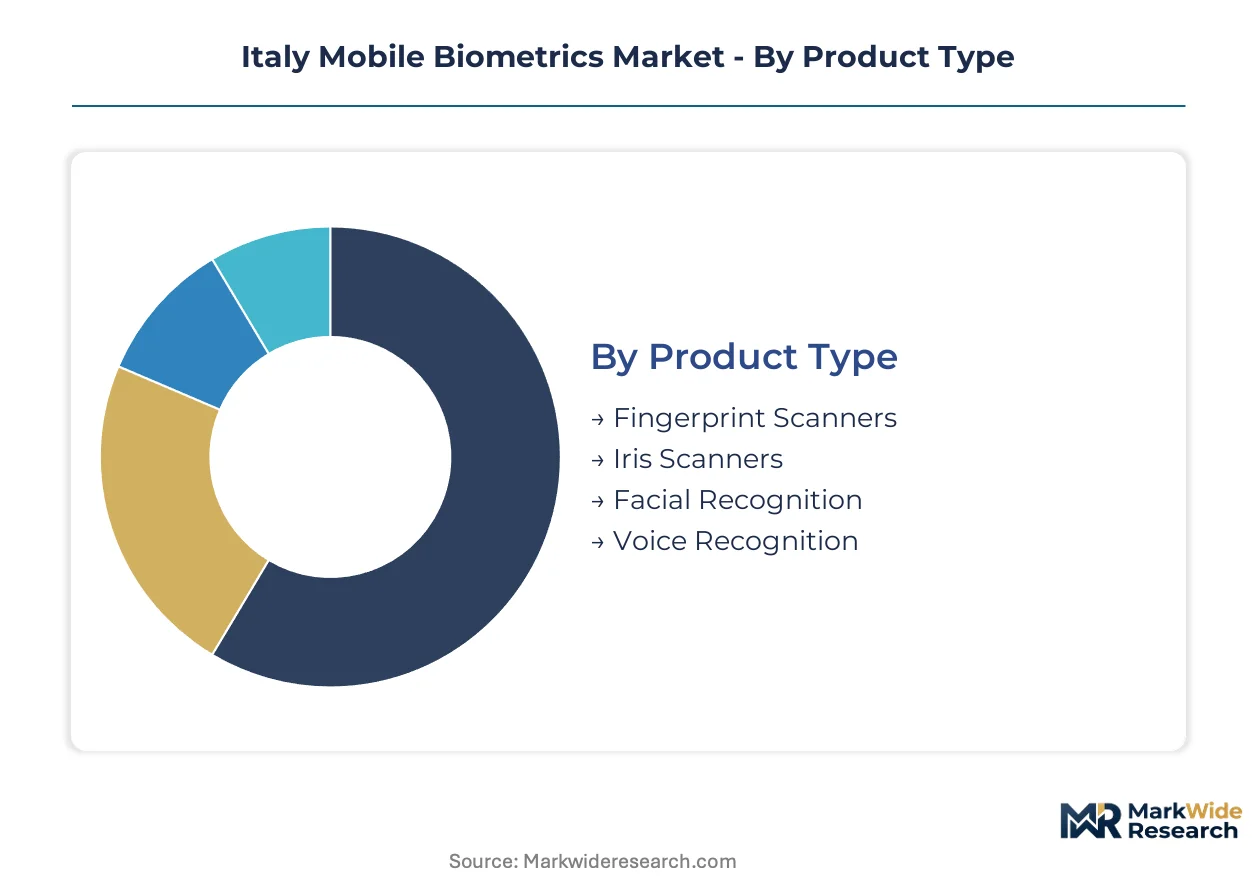
Mobile biometric architectures in Italy fragment across hardware form factors, deployment models, institutional buyers, and transactional use cases. Each segmentation dimension carries distinct compliance obligations under GDPR and the EU AI Act, reshaping vendor product strategies and procurement specifications across Lombardy's fintech corridor and southern expansion zones.
Product Type:
Hardware refresh cycles in Italian mobile deployments are compressing as polymer substrate economics displace legacy ceramic modules, forcing recalibration of sensor procurement specifications across device tiers.
- Fingerprint Scanners:Silicon-based capacitive sensors utilizing polymer substrates now dominate mid-tier hardware economics. Demand concentrates in Milan's merchant acquirer ecosystem where checkout friction reduction drives specifications.
- Facial Recognition:Liveness detection standards hardening under EU AI Act mandates accelerate deployment for high-assurance government credentialing. Lombardy fintech clusters pilot privacy-preserving architectures for PSD2 compliance.
- Iris Scanners:Niche positioning in defense and critical infrastructure applications where template security requirements exceed fingerprint capabilities.
- Voice Recognition:Emerging traction in call center authentication and telebanking channels, constrained by ambient noise performance limitations in mobile environments.
Fingerprint scanners sit at the top of the volume ranking, with facial recognition climbing the fastest as liveness detection standards harden.
Technology:
Deployment architecture choices in Italian mobile biometrics hinge on data sovereignty constraints and recurring revenue model preferences, splitting procurement between cloud-native banks and on-premises defense contractors.
- Biometric Sensors:Edge hardware capturing physiological traits with template storage below 500KB per enrolled identity. Defense contractors in the Milan-Genoa corridor specify secure enclave processing for data sovereignty compliance.
- Cloud-Based Solutions:Subscription architectures concentrate margin pools as Lombardy fintechs migrate from legacy on-premises authentication stacks. GDPR data residency requirements constrain cross-border template storage.
- On-Premises Systems:Dominant in government and critical infrastructure where data sovereignty constraints override cost considerations. Thales Group and NEC Corporation anchor high-assurance contract portfolios.
- Mobile Applications:Software-only delivery leveraging device-native sensors, gaining traction among retail banks seeking rapid deployment without hardware procurement cycles.
Cloud-based solutions are gaining share fastest among financial institutions, though on-premises systems retain volume leadership in government and defense segments.
End User:
Institutional buyer sophistication varies sharply across Italian mobile biometrics, with financial institutions driving multi-modal specifications while healthcare providers lag in authentication infrastructure investment.
- Financial Institutions:Lombardy's banking sector sustains procurement of multi-modal mobile platforms under PSD2 strong customer authentication mandates. Genoa's merchant acquirers prioritize passive behavioral verification to eliminate checkout friction.
- Government Agencies:High-assurance credentialing applications drive facial recognition deployment with human-in-the-loop protocols mandated by EU AI Act risk classifications.
- Healthcare Providers:Lagging adoption constrained by legacy electronic health record integration complexity and fragmented procurement authority across regional health systems.
- Retailers:Emerging demand from merchant acquirers seeking payment authentication differentiation, concentrated in northern Italy's dense point-of-sale networks.
Financial institutions command the highest specification tiers, with government agencies representing the steepest expansion trajectory as EU AI Act enforcement crystallizes.
Application:
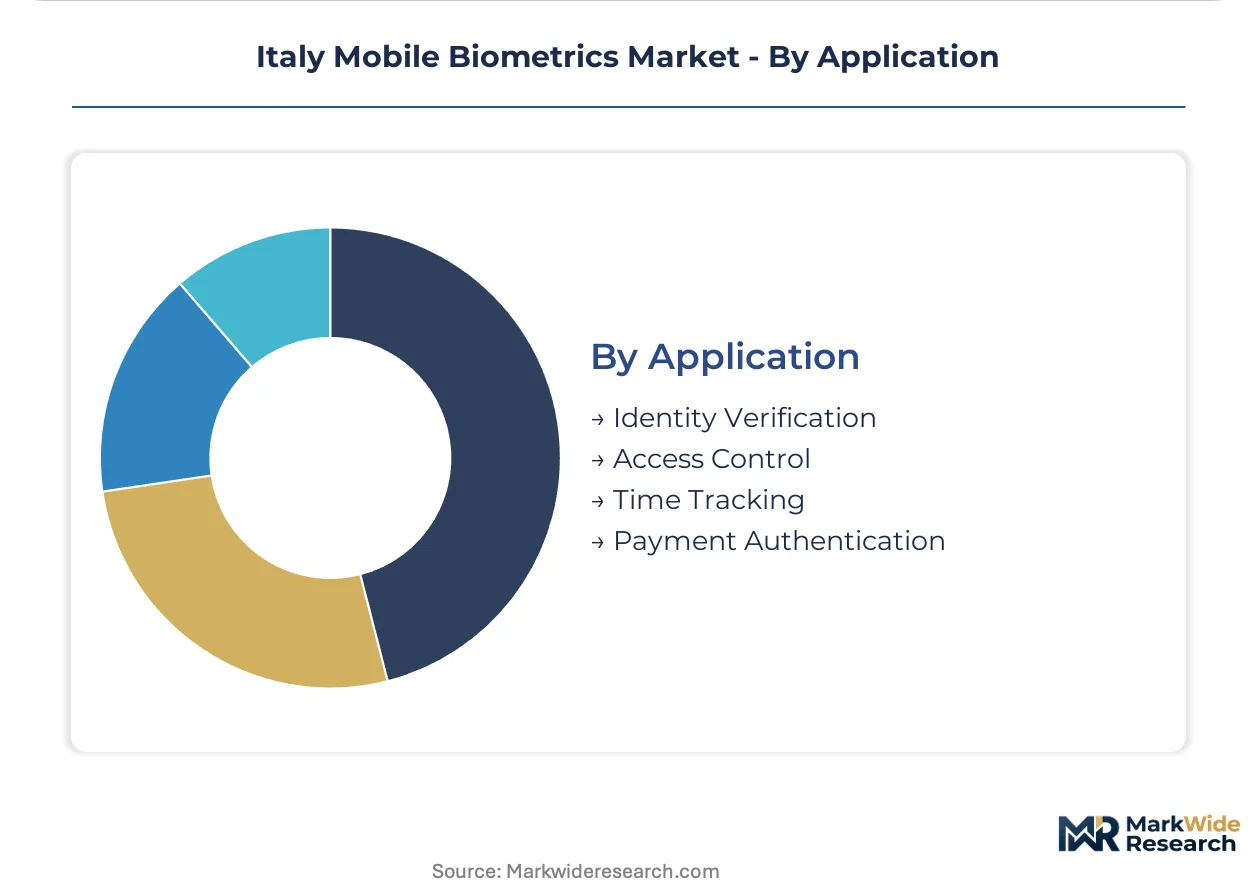
Functional use case segmentation in Italian mobile biometrics maps directly to regulatory trigger points, with payment authentication falling under PSD2 and remote identity verification activating EU AI Act high-risk system requirements.
- Identity Verification:Remote identification systems face EU AI Act high-risk classification mandating algorithmic impact assessments. Italian fintechs in Milan pilot homomorphic encryption to compress liability exposure.
- Payment Authentication:PSD2 strong customer authentication mandates sustain institutional procurement of multi-modal platforms. Behavioral biometrics convergence creates differentiation for fraud prevention vendors.
- Access Control:Physical and logical access applications in defense and critical infrastructure where on-premises deployment dominates.
- Time Tracking:Workforce management applications with lighter compliance burdens, attracting mid-tier vendors seeking volume outside regulated financial services.
Identity verification anchors premium pricing, while payment authentication exhibits the fastest volume growth as PSD2 enforcement tightens across European banking.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Milan-Genoa corridor anchors Italy's mobile biometrics demand, with Lombardy's fintech clusters and defense contractors driving procurement specifications that radiate southward toward underpenetrated markets.
Lombardy
Financial institutions in Milan sustain multi-modal platform procurement under PSD2 strong customer authentication mandates. The Garante per la Protezione dei Dati Personali enforces strict GDPR biometric consent protocols that lengthen enterprise sales cycles. Thales Group and NEC Corporation anchor high-assurance government contracts concentrated in the Brescia-Milan industrial axis.
Piedmont
Turin's automotive and aerospace supply chains generate demand for workforce access control applications with lighter compliance burdens than financial services. The EU AI Act's risk-classification framework for remote identification systems shapes vendor selection criteria among defense contractors. Polymer substrate fingerprint sensors from IDEMIA penetrate mid-tier device specifications through supplier relationships with Fiat Chrysler heritage networks.
Veneto
Padua and Verona host emerging merchant acquirer ecosystems seeking checkout friction reduction through passive behavioral verification. The European Banking Authority's technical standards under PSD2 sustain institutional investment in cloud-based authentication architectures. Regional banks migrate from on-premises stacks toward subscription delivery models, compressing deployment timelines for compliant vendors.
Lazio
Rome's government agencies drive facial recognition deployment for high-assurance credentialing with human-in-the-loop protocols mandated by EU AI Act enforcement. The national data protection authority's supervisory interpretations crystallize procurement specifications that preempt cross-border template storage. Defense contractors cluster in the Tivoli-Frascati corridor where data sovereignty constraints dominate technology selection.
Sicily
Financial inclusion initiatives and public digital identity programs present whitespace for mobile biometric service expansion outside the dominant northern industrial triangle. Regional development funds from the Italian Ministry of Economy and Finance subsidize authentication infrastructure for unbanked populations. Catania and Palermo emerge as pilot locations for behavioral biometrics convergence in telebanking channels.
Italy Mobile Biometrics Market Competitive Landscape
Global majors compete with regional champions across compliance architecture and algorithm certification dimensions, producing a tiered structure where scale-driven credentialing specialists face off against privacy-preserving technology boutiques. NEC Corporation and IDEMIA anchor the premium tier through government contract portfolios and manufacturing scale. Thales Group occupies a dual-use defense-to-civilian transfer position. Strategic moves concentrate on M&A for algorithm portfolios and strategic partnerships for GDPR-compliant cloud delivery.
Within the scale-driven tier, NEC Corporation exemplifies high-assurance government positioning, while IDEMIA represents manufacturing breadth across European credentialing programs. Thales Group sits within the dual-use technology transfer archetype, leveraging defense sector relationships for civilian market access. These three anchors illustrate how compliance architecture rather than raw accuracy metrics now determines competitive differentiation under EU AI Act enforcement.
| Leading Market Players |
|---|
| NEC Corporation |
| IDEMIA |
| Thales Group |
| HID Global |
| Aware |
| Gemalto |
| Zebra Technologies |
| Innovatrics |
| Precise Biometrics |
| Others |
Pricing and Supply Chain Analysis
EU AI Act certification tiers bifurcate vendor economics between high-assurance government contractors and commodity sensor suppliers, compressing margins in the mid-market while concentrating premium pricing power among algorithm-certified specialists serving Lombardy's defense clusters.
Pricing Analysis
Silicon wafer and polymer substrate costs pass through directly to mid-tier device manufacturers, forcing recalibration of sensor procurement specifications. Three-tier pricing structure across premium, standard, and economy levels separates Thales Group's defense-grade secure enclave modules from IDEMIA's scaled credentialing hardware and generic Asian sensor imports. Price erosion runs through the standard tier as polymer substrate economics displace legacy ceramic modules. Government agencies exhibit least price sensitivity due to data sovereignty mandates, while retail banks in Veneto drive hardest bargain negotiations for cloud-based subscription migration.
Supply Chain Analysis
Regional distribution centers in Rotterdam and Hamburg feed hub-and-spoke patterns radiating toward Milan-Genoa corridor demand clusters. Taiwan and South Korea anchor semiconductor wafer supply for capacitive fingerprint sensors, while German precision optics manufacturers feed liveness detection camera modules. German automotive-grade polymer substrate suppliers and Chinese commodity sensor fabs constitute dual-source dependencies. Single-source vulnerability concentrates in EU AI Act algorithm audit certification capacity, where qualified assessor scarcity creates procurement bottlenecks. Distribution runs through Thales Group and NEC Corporation's direct government contracting channels alongside IDEMIA's European credentialing program integration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Arbitrage opportunities emerge between Sicily's subsidized authentication infrastructure deployment and Lombardy's saturated premium-tier procurement, exploiting the Italian Ministry of Economy and Finance regional development cost differential.
For Market Incumbents: Anchor compliance architecture investments against EU AI Act enforcement crystallization in Rome's government procurement specifications. Thales Group and NEC Corporation should deepen secure enclave processing capabilities for data sovereignty-constrained defense contracts. IDEMIA must defend manufacturing scale advantages through backward integration into polymer substrate supply partnerships, preempting margin compression from Asian sensor imports. For New Entrants and Emerging Players: The premium-to-economy price gap in cloud-based authentication platforms creates entry space for SaaS-native vendors targeting Veneto and Sicily regional banks. Sicily's financial inclusion whitespace offers lowest competitive density for behavioral biometrics convergence pilots. Genoa's merchant acquirer ecosystem presents fastest route to revenue through passive verification API integration, bypassing hardware procurement cycles that entrench incumbents. For Investors and Strategic Acquirers: Consolidation pressure builds where algorithm audit certification talent scarcity constrains product launch velocity for mid-tier vendors. Long-term viability favors platforms combining privacy-preserving computation with PSD2 compliance architecture. Target acquisition archetype: SaaS-delivered biometric authentication with existing Italian banking API integrations. The signal to watch is Garante per la Protezione dei Dati Personali enforcement patterns against non-compliant facial recognition deployments.| Strategic Initiative | Industry Significance |
|---|---|
| Privacy-Preserving Algorithm Certification | EU AI Act high-risk system compliance unlocks Lombardy government contract access. |
| Cloud-Based Subscription Migration | Recurring revenue capture accelerates as Veneto regional banks abandon on-premises stacks. |
| Polymer Substrate Supply Partnership | Backward integration into German automotive-grade materials insulates mid-tier sensor margins. |
| Sicily Financial Inclusion Pilot | Ministry-subsidized deployment builds reference architecture for Southern European expansion. |
| Behavioral Biometrics API Integration | Passive verification layers reduce Genoa merchant acquirer checkout friction without hardware cycles. |
Research Methodology
Direct dialogue with biometric platform engineering directors, bank authentication procurement officers, Garante enforcement case officers, and defense contractor security architects grounded qualitative findings. Secondary validation drew from EU AI Act implementing act drafts, European Banking Authority PSD2 technical standards, Garante per la Protezione dei Dati Personali enforcement decisions, and SEC filings of listed biometric technology suppliers. Bottom-up sensor shipment estimates and top-down banking IT spend allocations were triangulated against Lombardy fintech cluster investment tracking.
Bottom-up modeling of fingerprint sensor, facial recognition module, and cloud authentication subscription volumes across product type and technology segments fed into top-down European banking authentication spend allocation analysis. Segmentation dimensions spanned hardware form factor, deployment architecture, institutional buyer sophistication, and application regulatory trigger point. CAGRs were derived from installed base replacement cycles and compliance-driven procurement acceleration. Algorithm certification timelines and polymer substrate cost curves constituted industry-specific forecast inputs.
Caveats apply where Garante supervisory interpretation divergence from EU-level implementing acts, or Taiwan semiconductor supply disruption, could materially shift the outlook. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biometrics & Identity Management
Biometric Passport Market
Biometrics & Identity Management
Global Mobile User Authentication Market
Biometrics & Identity Management
Mobile Devices User Authentication Services Market
Biometrics & Identity Management
Global Behavioral Biometrics Market
Biometrics & Identity Management
North America Enterprise Biometrics Market
Biometrics & Identity Management
Signature Verification Market
Biometrics & Identity Management
Voice Biometric Solutions Market
Biometrics & Identity Management
Biometric Point-Of-Sale Terminals Market
Biometrics & Identity Management
Airport Biometrics Market
Biometrics & Identity Management
Global Biometric Systems Market
Biometrics & Identity Management
Biometric Scan Software Market
Biometrics & Identity Management
Global Biometric Technology Market
Biometrics & Identity Management
Physical Identity and Access Management (PIAM) Market
Biometrics & Identity Management
North America Government and Security Biometrics Market
Biometrics & Identity Management
Biometrics As a Service in Healthcare Market
Biometrics & Identity Management
Global Phone Based Authentication Solution Market