
 Europe Biometrics in Government Market | 2026-2036
Europe Biometrics in Government Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Biometrics in Government Market Foresight
Project finance through public-private partnership structures is narrowing the field of vendors capable of delivering large-scale national biometric infrastructure. NEC Corporation leverages its long-term government contracting relationships to sustain recurring revenue across European border management programs. IDEMIA anchors its position through specialized manufacturing of secure credential documents integrated with biometric enrollment systems. Thales Group competes by extending its defense electronics expertise into civilian government identity markets.
Biometrics in government encompasses the automated measurement and statistical analysis of people's unique physical and behavioral characteristics—fingerprint minutiae, iris patterns, facial geometry, voiceprints, and palm vein structures—for identity verification and access control in public sector applications. These systems typically operate with false acceptance rates below 0.001% and integrate with centralized civil registry databases to prevent duplicate identities and fraudulent document issuance. Fingerprint recognition dominates current installed bases due to mature sensor costs and established forensic interoperability, while facial recognition captures expanding share through contactless deployment advantages at airports and transit hubs. Cloud-based and hybrid deployment models are gaining traction among civil registries seeking to reduce capital expenditure on data center infrastructure.
EMA data protection guidelines, GDPR biometric data processing restrictions, and the EU AI Act's prohibited-practices framework collectively constrain how government agencies deploy real-time biometric identification in publicly accessible spaces. The F-Gas Regulation indirectly affects thermal camera maintenance for certain biometric capture systems. Stakeholders must monitor evolving conformity assessment procedures under the EU AI Act's risk-based classification system to anticipate procurement delays and technical specification changes.
Market Dynamics
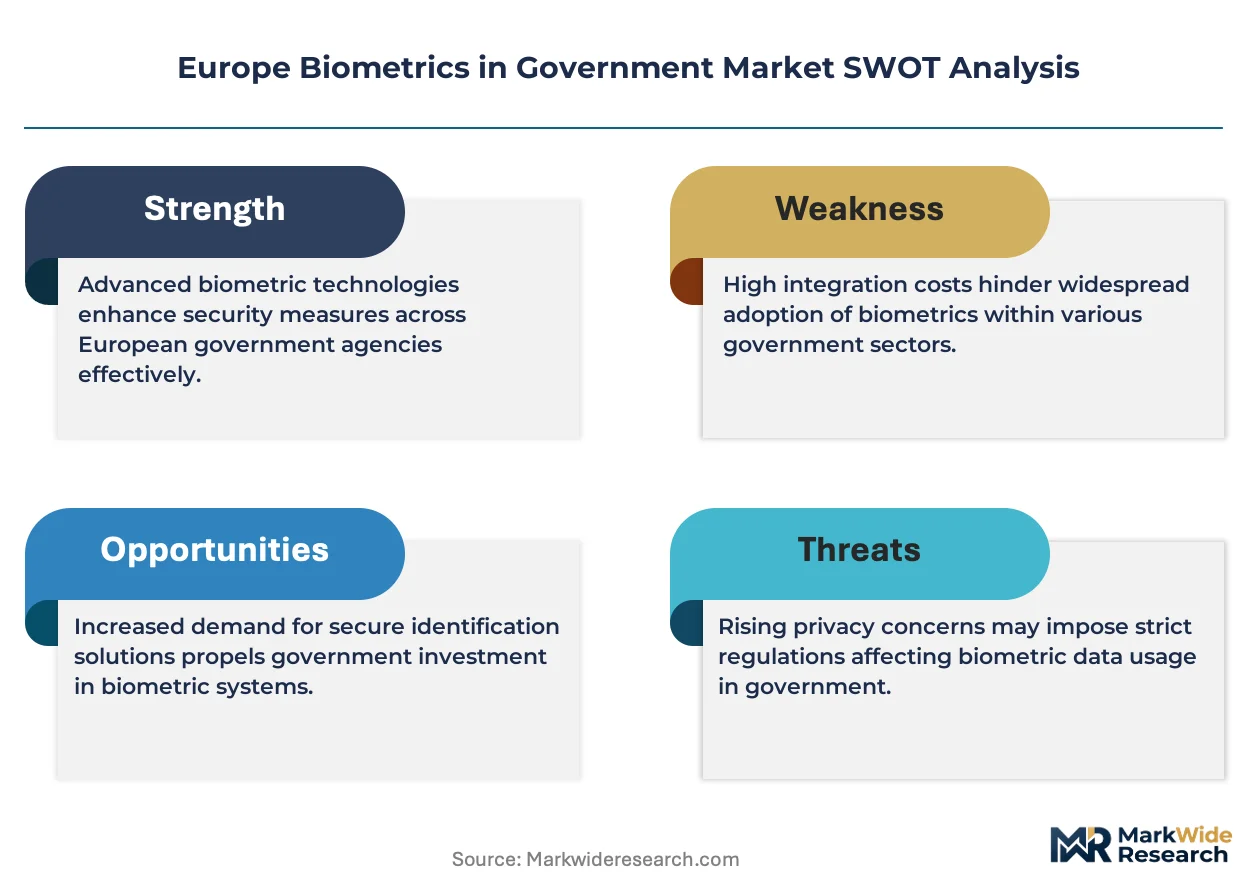
The EU AI Act's risk-based classification system is forcing civil registries and border agencies to reengineer procurement specifications for biometric systems, creating compliance-driven demand for explainable algorithms and human-in-the-loop verification architectures.
Growth Catalysts
- EU AI Act Implementation:The prohibited-practices framework and conformity assessment procedures are mandating upgrades to existing automated biometric identification systems across member states.
- Border Modernization Programs:Germany's federal police are deploying multimodal biometric platforms at international transit hubs to accelerate traveler processing throughput.
- GDPR-Compliant Cloud Migration:Civil registries in France and Italy are adopting hybrid deployment models to reduce capital expenditure while maintaining data sovereignty controls.
Market Restraints
- Specialized Sensor Cost Concentration:Thermal camera components for certain biometric capture modalities face maintenance cost inflation under the F-Gas Regulation.
- Vendor Consolidation Risk:Project finance through public-private partnership structures is narrowing the field of qualified infrastructure integrators capable of delivering at national scale.
- Algorithmic Audit Requirements:The EU AI Act's technical documentation and record-keeping obligations are extending procurement timelines by 12-18 months for high-risk biometric applications.
Strategic Opportunities
- Eastern European Civil Registry Digitization:Poland and Romania are modernizing national identity infrastructure with biometric enrollment systems to prevent duplicate identities and fraudulent document issuance.
- Contactless Airport Deployments:Facial recognition captures expanding share through deployment advantages at transit hubs where fingerprint sensor hygiene concerns persist.
- EMA Data Protection Alignment:Healthcare-government data sharing frameworks are creating new application vectors for biometric patient identification in public health systems.
Industry Challenges
- Forensic Interoperability Standards:National police forces require biometric template formats compatible with existing AFIS databases, complicating multimodal system integration.
- Explainable AI Engineering Talent:Vendors face scarcity of specialists capable of building interpretable deep learning models that satisfy regulator audit requirements under GDPR and the EU AI Act.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Biometrics in Government Market |
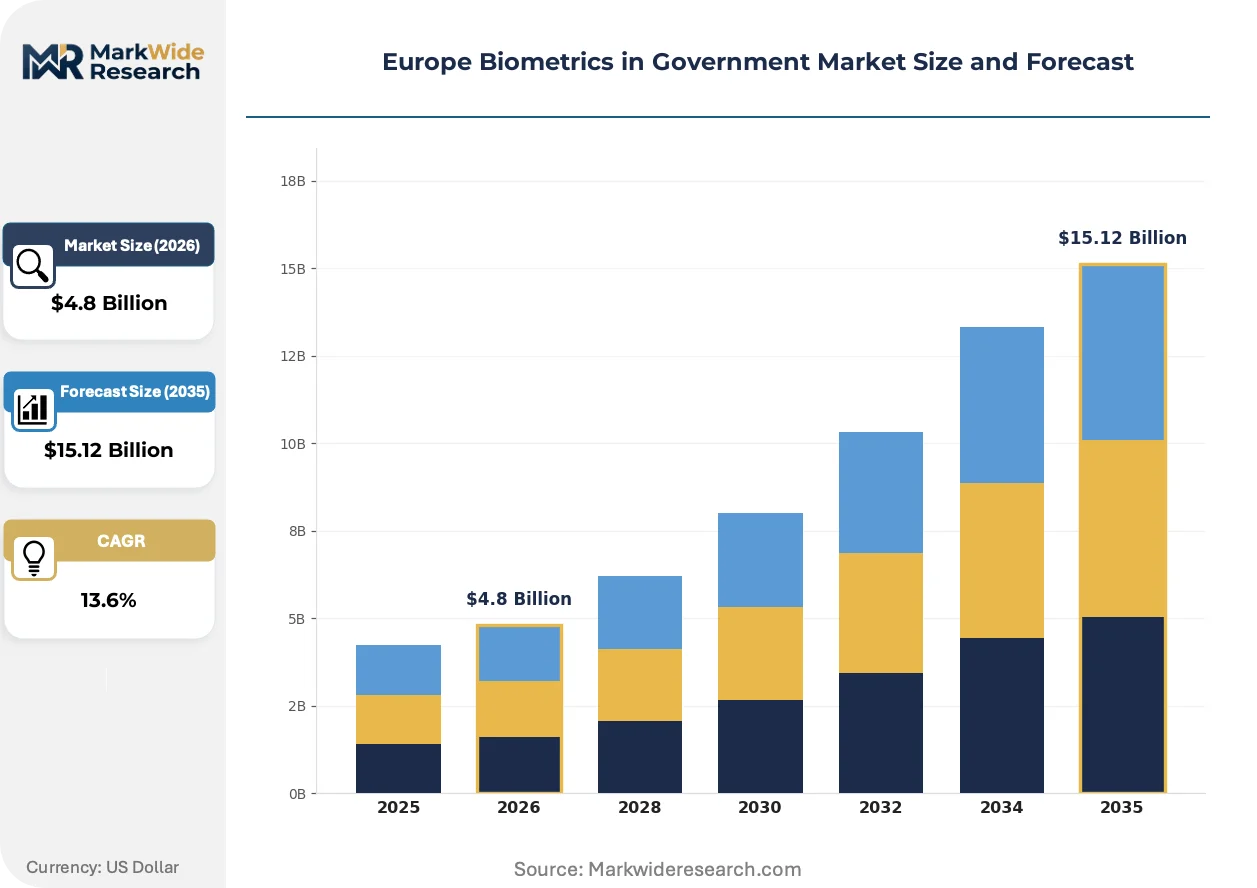
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $15.12 Billion |
| CAGR (2026 – 2036) | 13.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Biometric Technology: Fingerprint Recognition, Facial Recognition, Iris Scanning, Voice Recognition, Palm Vein Recognition Government Application: Identity Verification, Border Control, Law Enforcement, Public Safety, Social Security Management End User: Public Authorities, Security Agencies, Civil Registries, Immigration Offices, Defense Departments Deployment Model: On-Premises, Cloud-Based, Hybrid, Mobile, Edge Computing |
| Companies Covered | NEC Corporation, Innovatrics, Veridos GmbH, DERMALOG Identification Systems GmbH, HID Global Corporation, IDEMIA, Fujitsu, IrisGuard Ltd, Thales Group, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Biometrics in Government Market Shifts & Advancements
Biometric authentication architectures are pivoting from single-modality dependency toward layered verification stacks that balance security assurance with user friction reduction across government service delivery contexts.
Multimodal biometric platforms combining fingerprint minutiae, iris patterns, and facial geometry are hybridizing into unified enrollment systems. Germany's federal police and immigration authorities are deploying these architectures at national scale to reduce false acceptance rates below 0.001%. The technology is hybridizing vendor competitive positions, compressing pure-play sensor manufacturers into component suppliers while systems integrators capture value from orchestration software.
The EU AI Act's prohibited-practices framework is reshaping procurement specifications for real-time biometric identification in publicly accessible spaces. Government agencies must now document fundamental rights impact assessments and maintain human oversight capabilities for automated decision systems. Border control deployments across France and Italy are most affected, with authorities re-specifying contracts to include algorithmic audit trails and bias testing protocols.
Service delivery models for biometric infrastructure are fragmenting between capital-intensive ownership and operational expenditure frameworks. Civil registries in Spain and the Netherlands are unbundling hardware procurement from biometric-as-a-service management contracts. This shift is most visible in national identity card programs where agencies prefer subscription-based credential lifecycle management over perpetual license acquisitions.
Europe Biometrics in Government Market Segmentation
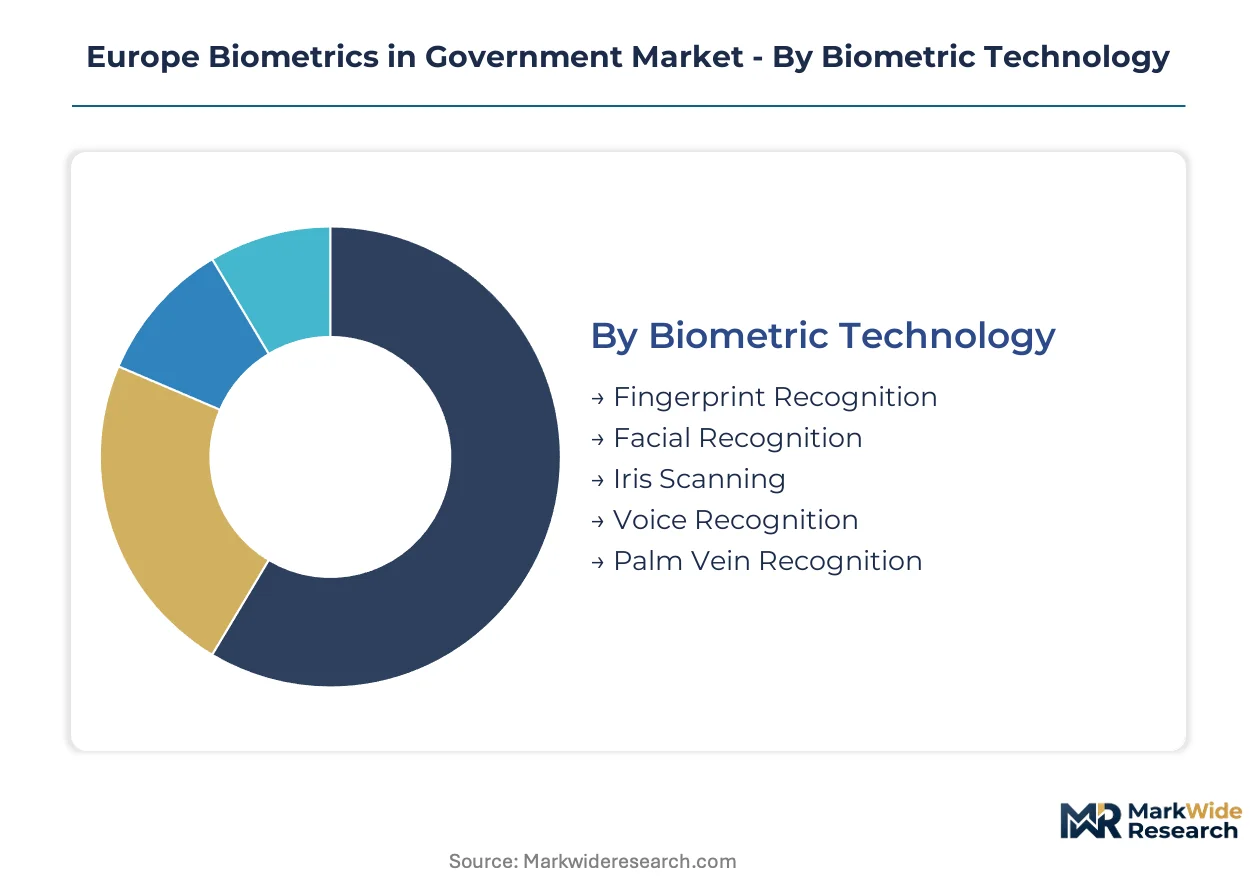
Biometric infrastructure procurement across European government agencies fragments along technology maturity curves, compliance architectures, and operational sovereignty requirements. Each segmentation dimension carries distinct vendor qualification thresholds and lifecycle service obligations that reshape competitive positioning.
Biometric Technology:
After-sales service intensity varies sharply across biometric modalities, with contactless systems demanding remote algorithm updates and multimodal platforms requiring integrated field engineering networks.
- Facial Recognition:Contactless capture systems process geometric facial landmarks through deep learning architectures optimized for transit hub throughput. German federal police and French border agencies are deploying these systems at international airports to accelerate traveler processing while maintaining GDPR-compliant data handling protocols.
- Fingerprint Recognition:Minutiae-based matching algorithms leverage mature sensor costs and established forensic interoperability with existing AFIS databases. Italian immigration authorities and Spanish civil registries continue expanding enrollment stations for national identity documents despite hygiene concerns at high-touch public interfaces.
- Iris Scanning:Pattern recognition systems deliver higher accuracy thresholds for high-security access control applications in defense and intelligence facilities.
- Voice Recognition:Behavioral biometrics enable remote identity verification for telephone-based government services and social security authentication.
- Palm Vein Recognition:Vascular pattern matching offers contactless advantages with lower environmental sensitivity than facial systems for indoor government facilities.
Fingerprint recognition holds the largest share; momentum sits with facial recognition.
Government Application:
Application-specific procurement cycles diverge based on regulatory compliance burdens, with border control and law enforcement facing the most stringent EU AI Act conformity assessment timelines.
- Border Control:Multimodal biometric platforms integrate fingerprint, facial, and iris capture at immigration checkpoints to prevent duplicate identities and fraudulent document usage. German and Italian authorities are modernizing transit hub infrastructure with explainable AI architectures that satisfy fundamental rights impact assessment requirements.
- Identity Verification:Civil registry systems enroll biometric templates during national identity card issuance to establish unique citizen records and eliminate duplicate registrations. Poland and Romania are deploying these systems to modernize legacy paper-based population databases.
- Law Enforcement:AFIS-compatible forensic systems support criminal investigation workflows with biometric evidence matching against centralized databases.
- Public Safety:Real-time biometric identification in publicly accessible spaces faces prohibited-practices constraints under the EU AI Act's risk-based classification framework.
- Social Security Management:Biometric authentication reduces benefit fraud through unique beneficiary verification at distribution points.
Identity verification holds the largest share; border control is expanding most quickly.
End User:
End-user technical sophistication determines deployment complexity, with defense departments and security agencies demanding air-gapped systems while civil registries prioritize interoperability.
- Civil Registries:Population-scale enrollment systems require high-throughput biometric capture with civil database integration to prevent duplicate identity records. French and Dutch agencies are adopting hybrid cloud architectures to reduce capital expenditure while maintaining data sovereignty controls.
- Security Agencies:Counter-terrorism and intelligence applications demand multimodal biometric platforms with hardened security architectures and strict chain-of-custody protocols.
- Public Authorities:Municipal and regional governments deploy biometric access control for facility security and employee authentication.
- Immigration Offices:Visa processing and asylum systems require AFIS-compatible fingerprint matching with international data sharing protocols.
- Defense Departments:Military installations utilize biometric physical access control with PKI-credential integration for classified facility entry.
Civil registries hold the largest share; security agencies are gaining share fastest.
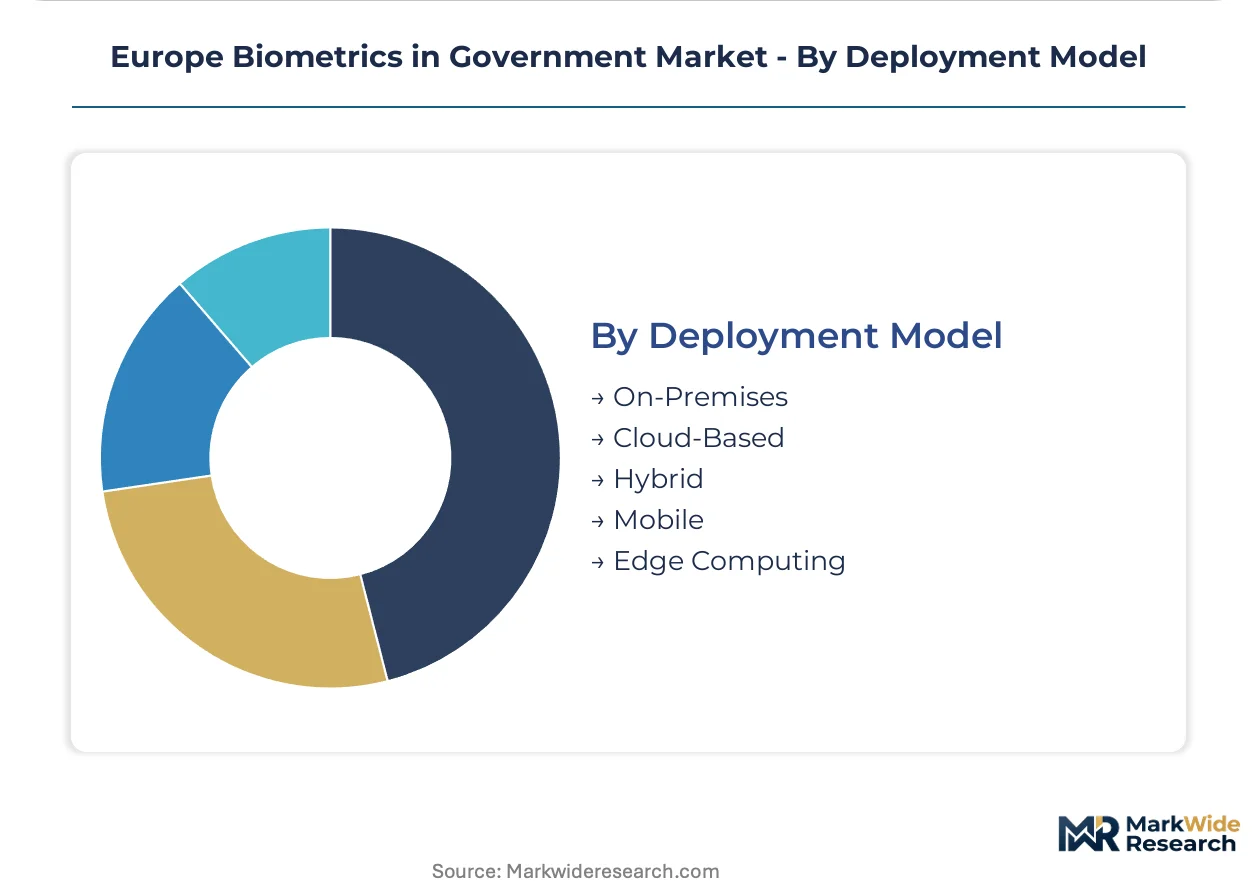
Deployment Model:
Deployment architecture selection reflects data residency requirements and capital availability, with hybrid models capturing expanding share among agencies balancing sovereignty and cost optimization.
- Hybrid:Split architectures process biometric enrollment at local edge nodes while centralizing template storage in sovereign cloud facilities. Spanish and Netherlands civil registries prefer this model for national identity programs requiring both low-latency service delivery and compliance with GDPR data localization mandates.
- On-Premises:Air-gapped data center deployments satisfy defense and intelligence agency requirements for complete operational control over sensitive biometric databases.
- Cloud-Based:Fully managed biometric-as-a-service offerings reduce infrastructure ownership burdens for smaller agencies with limited IT capabilities.
- Mobile:Portable enrollment kits support field-based identity registration for remote populations and emergency response scenarios.
- Edge Computing:Distributed processing architectures enable real-time biometric matching at capture points without centralized data transmission.
On-premises holds the largest share; hybrid deployment is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Border control agencies and civil registries concentrate procurement authority across Germany, France, Italy, Poland, and the Netherlands, with each market shaped by distinct regulatory implementation timelines and infrastructure modernization priorities.
Germany
Federal police and immigration authorities drive multimodal biometric platform deployments at Frankfurt and Munich airports. The EU AI Act's conformity assessment requirements are extending procurement timelines for automated identification systems. Bavaria's security technology cluster around Munich hosts systems integrators delivering national-scale identity infrastructure.
France
French border agencies at Charles de Gaulle and Lyon-Saint Exupéry are re-specifying facial recognition contracts to include algorithmic audit trails. CNIL guidance on GDPR biometric data processing is constraining real-time identification deployments in publicly accessible spaces. The Paris-Saclay research corridor is generating explainable AI engineering talent for compliance-ready system architectures.
Italy
Italian immigration authorities expand fingerprint enrollment stations for national identity documents despite persistent hygiene concerns at high-touch interfaces. EMA data protection guidelines affect healthcare-government biometric data sharing frameworks. Rome's civil registry modernization program is preventing duplicate identities through centralized biometric template storage.
Poland
Polish civil registries are digitizing legacy paper-based population databases with biometric enrollment systems to establish unique citizen records. The EU AI Act's prohibited-practices framework is shaping procurement specifications for real-time identification. Warsaw's emerging technology sector is developing hybrid cloud architectures for sovereign data residency compliance.
Netherlands
Dutch civil registries prefer subscription-based credential lifecycle management over perpetual license acquisitions for national identity programs. GDPR data localization mandates are driving hybrid deployment models with edge processing at enrollment points. The Randstad metropolitan cluster is unbundling hardware procurement from biometric-as-a-service management contracts.
Europe Biometrics in Government Market Competitive Landscape
Channel-controlling players compete with product-specialist players across fragmented procurement channels serving national government agencies. Long-term government contracting relationships sustain recurring revenue for established infrastructure integrators. Three archetypes dominate: defense electronics extenders, specialized secure credential manufacturers, and multimodal platform orchestrators. Competitive moves center on public-private partnership qualification and algorithmic explainability certification.
Within the systems integration tier, NEC Corporation and Thales Group exemplify defense-to-civilian extenders leveraging electronics expertise into government identity markets. IDEMIA anchors the secure credential specialist position through integrated biometric enrollment and document manufacturing capabilities. These three entities represent the qualified vendor pool capable of delivering national-scale infrastructure under EU AI Act compliance frameworks.
| Leading Market Players |
|---|
| NEC Corporation |
| Innovatrics |
| Veridos GmbH |
| DERMALOG Identification Systems GmbH |
| HID Global Corporation |
| IDEMIA |
| Fujitsu |
| IrisGuard Ltd |
| Thales Group |
| Others |
Supply & Pricing Matrix
EU AI Act conformity assessment bottlenecks determine both pricing tier spreads and supply chain configuration for biometric infrastructure procurement. Vendors capable of delivering certified high-risk AI systems command substantial premiums over uncertified competitors, while procurement delays compress margins for systems integrators locked into fixed-price public-private partnership structures.
Pricing Analysis
Cost-plus contracts with EU AI Act compliance indexation dominate large-scale government biometric deployments. Three-tier pricing structure across premium, standard, and economy levels separates NEC Corporation and Thales Group's certified multimodal platforms from regional sensor suppliers and uncertified software vendors. Price differentiation hinges on algorithmic explainability certification and sovereign cloud integration capabilities. Cost compression in mid-tier facial recognition modules is intensifying because Polish and Romanian civil registries are consolidating procurement volumes. Municipal governments and smaller immigration offices exhibit highest price sensitivity, while German federal police and French border agencies prioritize compliance assurance over unit economics.
Supply Chain Analysis
Upstream feedstock for biometric capture hardware draws from Taiwan and South Korea for CMOS image sensors, Germany for precision optics, and Japan for infrared thermal detector arrays. Specialized sensor assembly rests on rare earth element supply from China, fluorinated gas chemistries regulated under the F-Gas Regulation, and silicon wafer feedstock. Single-source vulnerability concentrates in thermal camera modules for iris scanning systems, where European maintenance networks face spare part availability constraints. Distribution runs through systems integrators with pre-qualified public sector vendor status rather than direct OEM-to-agency sales channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story anchored in regulatory entrenchment. The EU AI Act's conformity assessment procedures create switching costs that cement incumbent positions for vendors with established certification track records.
For Market Incumbents: Entrench market position by acquiring explainable AI engineering specialists in the Paris-Saclay research corridor before talent scarcity worsens under GDPR and EU AI Act audit requirements. Extend backward integration into sovereign cloud infrastructure to capture recurring revenue streams from hybrid deployment models preferred by Dutch and Spanish civil registries. Counter emerging competition from defense electronics extenders by deepening algorithmic bias testing protocols that satisfy fundamental rights impact assessments.
For New Entrants and Emerging Players: Eastern European civil registry digitization in Poland and Romania offers the most penetrable entry vector for biometric enrollment systems replacing legacy paper-based population databases. Target healthcare-government data sharing frameworks under EMA guidelines as an alternative application vector with lighter conformity assessment burdens than border control deployments. Pursue biometric-as-a-service subscription models to bypass capital-intensive infrastructure ownership requirements that favor established systems integrators.
For Investors and Strategic Acquirers: The market sits at a compliance-driven consolidation phase that favors vendors with pre-existing government contracting relationships and algorithmic certification assets. Long-term viability across the projection horizon hinges on sustained EU AI Act enforcement and member state infrastructure modernization commitments. Acquisition targets should display hybrid cloud deployment capabilities and explainable AI engineering benches. Monitor conformity assessment backlog lengths at notified bodies as the critical inflection indicator for procurement timeline normalization.
| Strategic Initiative | Industry Significance |
|---|---|
| Algorithmic Explainability Certification | EU AI Act compliance unlocks high-risk biometric procurement opportunities at German federal police and French border agencies. |
| Sovereign Cloud Infrastructure Investment | Hybrid deployment capabilities satisfy GDPR data localization mandates for Dutch and Spanish civil registry modernization programs. |
| Multimodal Platform Integration | Unified fingerprint, facial, and iris systems reduce false acceptance rates below thresholds required for national identity infrastructure. |
| Public-Private Partnership Qualification | Pre-qualified vendor status enables participation in Poland and Romania's national-scale civil registry digitization tenders. |
| Explainable AI Engineering Acquisition | Talent scarcity in interpretable deep learning constrains competitor compliance timelines and defensible moat construction. |
Research Methodology
The analysis maps biometric technology modalities, government application segments, and deployment model architectures, each validated through procurement officers at civil registries, border agency technology directors, and systems integration program managers. Primary interviews with EU AI Act compliance consultants, EMA data protection specialists, and biometric sensor procurement leads combined with secondary validation against EU official journal procurement notices, GDPR enforcement tracker databases, and F-Gas Regulation implementation reports. Bottom-up enrollment volume estimates triangulated against top-down government IT budget appropriations across the analysis window.
Assumption sets held EU AI Act enforcement timelines and member state infrastructure appropriations fixed while varying algorithmic certification success rates and hybrid cloud adoption curves across national civil registries. Segmentation dimensions modeled include biometric technology type, government application function, end-user agency category, and deployment architecture sovereignty level. CAGRs derived from enrollment station deployment trajectories and subscription service revenue scaling patterns, with biometric-as-a-service contract values and multimodal platform unit economics as industry-specific forecast inputs.
Practitioners should monitor notified body conformity assessment capacity expansion and member state fundamental rights impact assessment completion rates for early signals of procurement timeline compression or extension. Forecasts reflect documented assumptions regarding EU AI Act implementation consistency and civil registry modernization funding continuity. Cross-checking against European Court of Human Rights biometric surveillance rulings and CNIL enforcement precedent is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biometrics & Identity Management
Military Biometrics Market
Biometrics & Identity Management
Global Voice Biometrics Market
Biometrics & Identity Management
Global Behavioral Biometrics Market
Biometrics & Identity Management
Europe Government and Security Biometrics Market
Biometrics & Identity Management
Global Authentication and Brand Protection Market
Biometrics & Identity Management
Fingerprint Biometrics Market
Biometrics & Identity Management
Password Management Market
Biometrics & Identity Management
Gait Biometrics Market
Biometrics & Identity Management
Physical Identity and Access Management (PIAM) Market
Biometrics & Identity Management
Global Biometric Identification Market
Biometrics & Identity Management
Latin America Biometrics Market
Biometrics & Identity Management
Italy Mobile Biometrics Market
Biometrics & Identity Management
Flash Calling Authentication Market
Biometrics & Identity Management
Biometric Services Platform (Biosp) Market
Biometrics & Identity Management
Next Generation Biometric Market
Biometrics & Identity Management
Biometric Data Encryption Device Market