
 Biometric Data Encryption Device Market | 2026-2036
Biometric Data Encryption Device Market Size, Share, and Industry Trends Forecast 2026-2036
Biometric Data Encryption Device Market Analytics
Aftermarket service revenue from firmware updates and key rotation management is reshaping margin pools away from one-time hardware sales. Suprema leverages its integrated biometric-encryption platform to sustain recurring licensing income. NEC Corporation anchors its position through deep R&D investment in iris-template protection algorithms. IDEMIA competes on government certification breadth across multiple national security frameworks.
Biometric data encryption devices combine physiological capture sensors with cryptographic engines to transform raw biometric templates into non-reversible, encrypted identifiers that resist replay and spoofing attacks. These systems typically embed AES-256 or ECC hardware modules with tamper-resistant secure elements to protect template data at rest and in transit. Fingerprint scanner hardware occupies the largest installed base, though facial recognition devices are gaining share in contactless access control deployments. Asymmetric encryption technology leads in financial applications where public-key infrastructure supports cross-institutional identity verification. Secure key management represents the fastest-growing technology segment as organizations confront rising template breach liabilities.
FDA guidance on biometric device cybersecurity, EU GDPR Article 9 restrictions on special category data processing, and NIST FIPS 140-3 cryptographic module standards collectively determine product design requirements and market access conditions. The EU AI Act's risk-classification framework for biometric identification systems will force manufacturers to restructure compliance documentation and conformity assessment pathways. Stakeholders must monitor evolving template protection mandates across jurisdictions to anticipate redesign cycles and certification delays.
Market Dynamics
Template protection mandates across multiple jurisdictions are compressing product development cycles and forcing manufacturers to restructure hardware-software architectures around certified secure elements rather than modular add-on encryption.
Growth Catalysts
- Fingerprint-integrated encryption modules:Financial institutions deploy these for transaction authentication, pulling hardware refresh cycles forward across retail banking networks.
- GDPR Article 9:Special category data processing rules mandate biometric template encryption at capture, creating compliance-driven replacement demand for legacy access control systems.
- Federal agency infrastructure:United States government facilities prioritize hardware-backed biometric authentication for classified facility access, concentrating procurement volume in defense and intelligence verticals.
Market Restraints
- Secure element supply concentration:Tamper-resistant chip fabrication concentrates in a limited number of foundries, exposing lead times to geopolitical friction.
- NIST FIPS 140-3 validation costs:Cryptographic module certification requires substantial capital outlay and 12-18 month timelines, filtering smaller vendors from federal procurement pools.
- Behavioral biometrics substitution:Keystroke dynamics and gait analysis software solutions compete for lower-assurance authentication use cases without hardware dependencies.
Strategic Opportunities
- Contactless facial recognition:Healthcare and transportation sectors in Germany and France accelerate deployment of touchless biometric access post-pandemic.
- Key rotation management services:Recurring firmware update subscriptions transform one-time hardware margins into predictable revenue streams.
- EU AI Act risk classification:Conformity assessment pathways for biometric identification systems create first-mover advantage for documentation-ready manufacturers.
Industry Challenges
- Legacy system integration:Enterprise customers demand backward compatibility with decades-old physical access control infrastructure, complicating firmware architecture.
- Cross-border template interoperability:Divergent national standards for biometric data formats fragment R&D investment across incompatible certification regimes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Biometric Data Encryption Device Market |
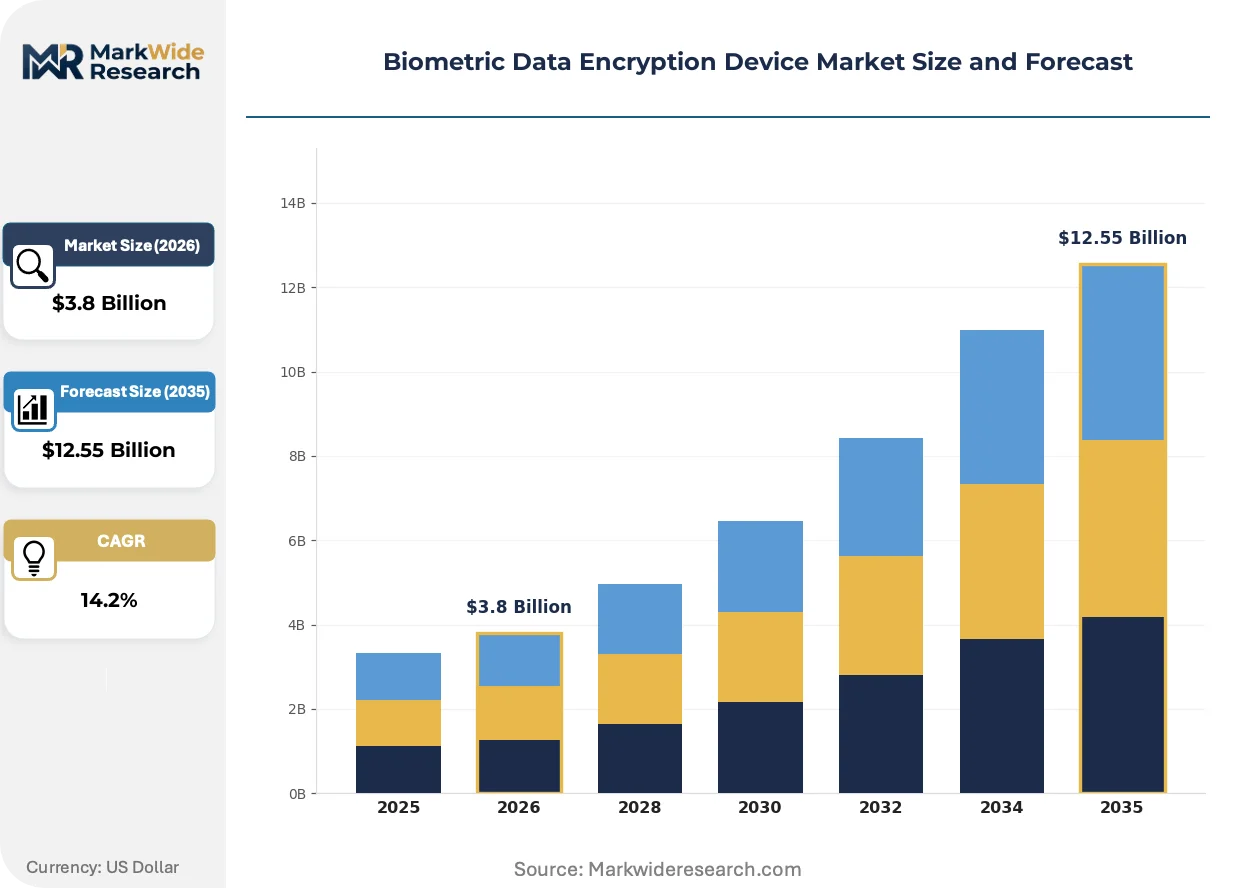
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $12.55 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fingerprint Scanner, Iris Recognition System, Facial Recognition Device, Voice Recognition Module Technology: Symmetric Encryption, Asymmetric Encryption, Hash Functions, Secure Key Management End User: Government Agencies, Financial Institutions, Healthcare Providers, Educational Institutions Application: Access Control, Data Protection, Identity Verification, Secure Transactions |
| Companies Covered | Suprema, Crossmatch (HID Global), IDEMIA, NEC Corporation, Fujitsu, Samsung Electronics, SecuGen, NEXT Biometrics, Nitgen, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Biometric Data Encryption Device Market Evolving Landscape
Encryption architectures are converging with sensor hardware at the silicon level, eliminating attack surfaces that previously separated biometric capture from cryptographic processing. This integration is redrawing competitive boundaries between component suppliers and finished device manufacturers.
Template protection is migrating from server-side storage to edge-embedded secure elements. Financial institutions and government agencies now mandate on-device encryption before any biometric data leaves the sensor. This shift is compressing the addressable market for cloud-based biometric middleware providers while expanding margins for integrated hardware-encryption platform vendors.
The EU AI Act's risk-classification framework for biometric identification systems entered force in 2024. Manufacturers must now document conformity assessment pathways and maintain technical files for high-risk system deployments. European national security frameworks and critical infrastructure operators represent the most affected buyer segments, with procurement specifications increasingly requiring AI Act compliance attestations alongside traditional cybersecurity certifications.
Enterprise buyers now unbundle hardware procurement from multi-year managed service agreements. Large banking networks and federal agencies prefer subscription-based key rotation, firmware lifecycle management, and breach response retainers over traditional capital expenditure models. This pattern is most pronounced in the United States, where GSA schedule contracts increasingly structure biometric access control as operational rather than capital spending.
Biometric Data Encryption Device Market Segmentation
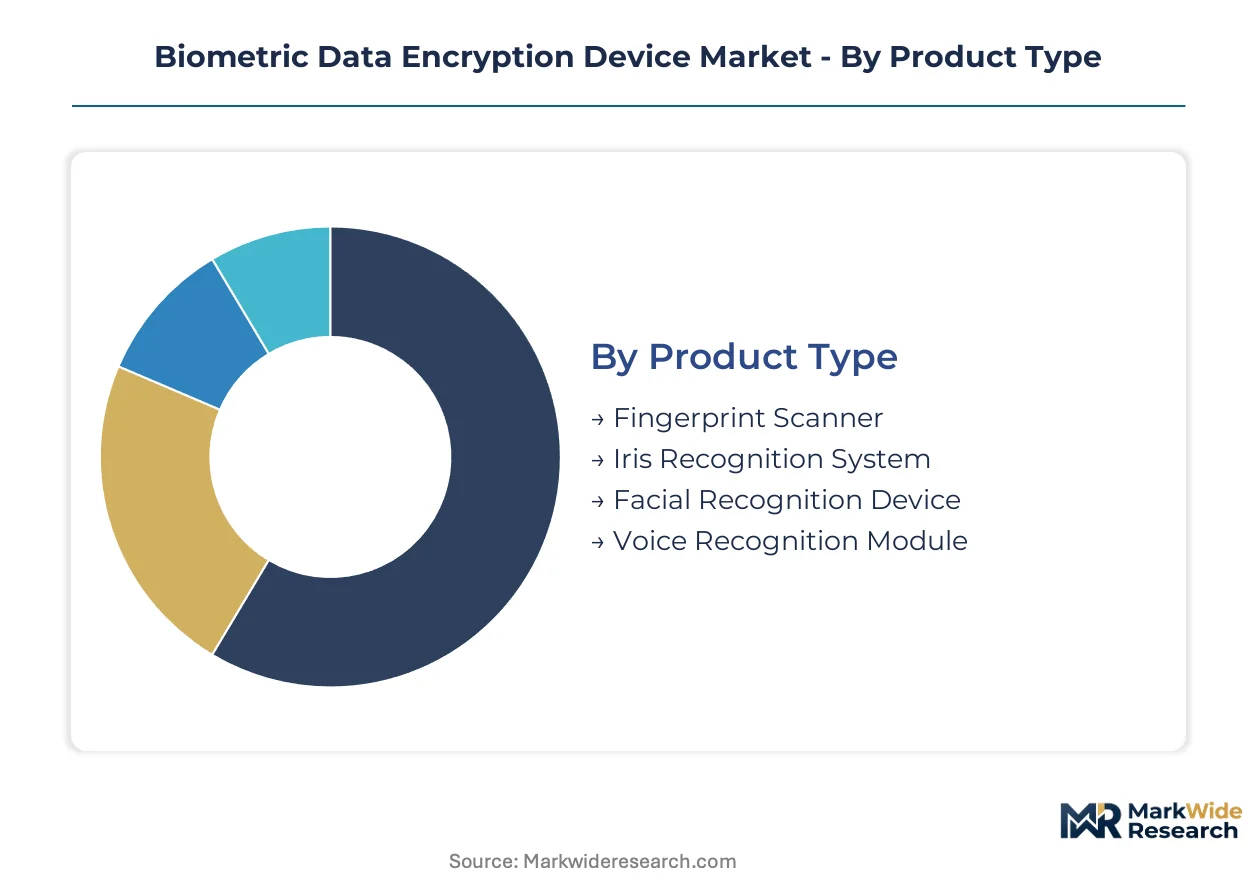
Biometric data encryption devices fragment across four intersecting dimensions that determine procurement specifications, compliance burdens, and margin structures. Product type governs sensor hardware costs and integration complexity. Technology choice dictates certification pathways and cryptographic assurance levels. End user verticals impose divergent security frameworks and budget cycles. Application use case determines whether devices operate in standalone or networked configurations.
Product Type:
Fingerprint scanners anchor high-volume deployments across banking and government facilities, while facial recognition devices gain traction in contactless healthcare and transportation environments.
- Fingerprint Scanner:Capacitive and ultrasonic sensor modules embed AES-256 hardware encryption engines with tamper-resistant secure elements. United States federal agencies and retail banking networks drive replacement demand as NIST FIPS 140-3 compliance deadlines approach for legacy access control infrastructure.
- Facial Recognition Device:Infrared depth-sensing arrays combined with liveness detection algorithms resist spoofing through 3D structure analysis. German and French healthcare facilities accelerate procurement for touchless patient and staff authentication following pandemic-era hygiene protocols.
- Iris Recognition System:Near-infrared cameras capture unique patterns in the trabecular meshwork with false acceptance rates below one in ten million.
- Voice Recognition Module:Spectral analysis engines process vocal biometrics for remote authentication in call center and telemedicine workflows.
Established volume favors fingerprint scanners; emerging adoption favors facial recognition devices.
Technology:
Encryption methodology selection hinges on key management architecture, computational latency requirements, and cross-institutional interoperability mandates.
- Asymmetric Encryption:Public-key infrastructure with ECC hardware modules enables secure template exchange between organizations without shared secrets. Financial institutions across the United States deploy RSA and elliptic curve cryptography for interbank identity verification and federated access management.
- Secure Key Management:Hardware security modules generate, store, and rotate cryptographic keys within tamper-responsive enclosures. Enterprise buyers in defense and intelligence verticals prioritize subscription-based key lifecycle services over perpetual licensing.
- Symmetric Encryption:AES-256 block ciphers deliver low-latency template protection for high-throughput access control points.
- Hash Functions:One-way biometric template transformation prevents reconstruction of raw physiological data from stored identifiers.
Asymmetric encryption dominates financial interoperability; secure key management expands most quickly as breach liability concentrates on template storage.
End User:
Vertical-specific security frameworks and procurement regulations reshape device specifications and vendor qualification requirements.
- Government Agencies:Classified facility access mandates hardware-backed biometric authentication with NIST FIPS 140-3 Level 3 or higher certification. United States defense and intelligence verticals concentrate procurement volume through GSA schedule contracts structured as operational expenditure.
- Financial Institutions:PCI-DSS and GDPR Article 9 compliance drives replacement of legacy access control with encrypted biometric modules. Retail banking networks across the United States refresh hardware cycles to support transaction authentication and branch staff verification.
- Healthcare Providers:HIPAA security rules and infection control protocols accelerate contactless biometric deployment in patient-facing environments.
- Educational Institutions:Campus access control and examination proctoring applications generate mid-volume demand for cost-optimized encryption devices.
Government procurement favors certified secure elements; financial services demand fastest refresh cycles.
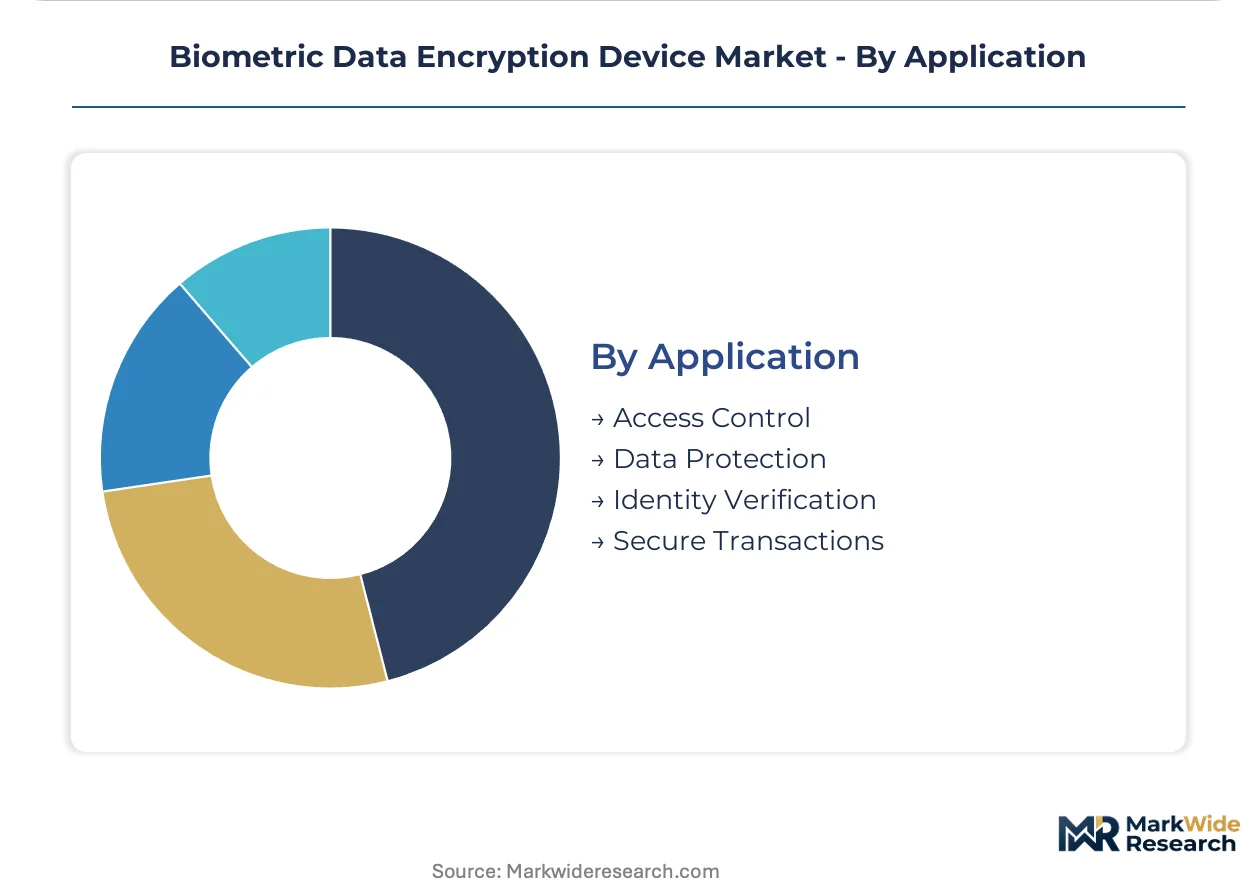
Application:
Use case architecture determines whether biometric encryption operates at the network edge, in centralized data centers, or across hybrid configurations.
- Access Control:Physical and logical entry systems integrate biometric capture with encrypted credential transmission to policy enforcement points. Federal facilities and corporate campuses prioritize on-device template encryption before network transmission.
- Secure Transactions:Payment authentication and high-value wire transfer verification deploy fingerprint-integrated encryption modules at point-of-sale and banking terminals.
- Data Protection:File and database encryption systems use biometric factors for key release and decryption authorization.
- Identity Verification:Remote onboarding and account recovery workflows combine biometric capture with document validation and liveness detection.
Access control generates largest installed base; secure transactions command highest unit margins.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Germany and France demonstrate lowest price elasticity due to stringent EU AI Act compliance mandates, while procurement teams in India and Southeast Asia prioritize cost-optimized configurations over certified secure elements.
United States
Defense and intelligence verticals drive concentrated procurement through GSA schedule contracts structured as operational expenditure. NIST FIPS 140-3 Level 3 certification requirements filter vendor pools for classified facility access systems. Washington DC metro and Northern Virginia corridor host the densest concentration of federal biometric infrastructure deployments.
Germany
Healthcare and transportation sectors accelerate contactless facial recognition adoption following pandemic-era hygiene protocols. GDPR Article 9 template encryption mandates create compliance-driven replacement cycles for legacy access control. Munich and Frankfurt banking clusters specify hardware-backed biometric authentication for transaction terminals.
France
CNIL enforcement actions against biometric data breaches intensify enterprise investment in edge-embedded secure elements. EU AI Act conformity assessment pathways for high-risk biometric systems entered force in 2024. Paris financial district and Lyon healthcare networks prioritize on-device encryption before network transmission.
Japan
Financial institutions deploy fingerprint-integrated encryption modules for interbank identity verification and federated access management. METI guidelines on critical infrastructure cybersecurity shape procurement specifications for biometric access control. Tokyo and Osaka metropolitan areas concentrate demand from retail banking networks and corporate headquarters.
India
Cost-sensitive enterprise buyers favor modular biometric hardware without integrated encryption, driving aftermarket service opportunities for key rotation management. RBI guidelines on digital payment authentication influence specifications for banking terminal deployments. Mumbai and Bangalore technology corridors exhibit fastest adoption of subscription-based firmware lifecycle services.
Biometric Data Encryption Device Market Competitive Landscape
Capability concentration sits with integrated platform vendors possessing certified secure element architectures; scale advantage sits with diversified electronics conglomerates leveraging semiconductor fabrication assets. The vendor base separates into three strategic archetypes: biometric-specialist platform vendors, diversified technology conglomerates with captive encryption capabilities, and component suppliers seeking upstream integration. Dominant competitive moves include strategic partnerships between sensor manufacturers and cryptographic module vendors, plus portfolio diversification into managed key rotation services.
Within the integrated platform tier, Suprema exemplifies recurring revenue architecture through firmware subscription models, while IDEMIA occupies a position anchored by government certification breadth across multiple national security frameworks. NEC Corporation represents deep R&D investment concentration in template protection algorithms. These three vendors collectively illustrate how compliance documentation capabilities and secure element integration determine competitive positioning under tightening EU AI Act and GDPR regulatory frameworks.
| Leading Market Players |
|---|
| Suprema |
| Crossmatch (HID Global) |
| IDEMIA |
| NEC Corporation |
| Fujitsu |
| Samsung Electronics |
| SecuGen |
| NEXT Biometrics |
| Nitgen |
| Others |
Value Network & Pricing Analysis
Undercapacity at Taiwan-based secure element foundries is compressing lead times and emboldening suppliers to enforce stricter payment terms, which in turn hardens pricing postures for NIST FIPS 140-3 certified modules. United States federal procurement pools absorb these premiums more readily than cost-optimized Indian banking networks, fragmenting pricing power across buyer archetypes.
Pricing Analysis
Firmware subscription and key rotation services now capture the majority of lifetime value in enterprise deployments. Three-tier pricing structure across premium, standard, and economy levels separates FIPS 140-3 Level 4 certified hardware from Level 3 configurations and uncertified modular alternatives. Cost compression in economy tiers is intensifying because Indian and Southeast Asian buyers prioritize hardware-only procurement without embedded encryption. Government agencies in the United States exhibit the lowest price sensitivity, while educational institutions and mid-market healthcare providers in India demonstrate the highest.
Supply Chain Analysis
Extended payment terms from Taiwanese and South Korean foundry partners now stretch to 90-120 days for biometric-secure element co-packaging orders. Tamper-resistant chip fabrication concentrates in Taiwan, South Korea, and select United States facilities, while sensor module assembly draws from China, Vietnam, and Malaysia. Single-source vulnerability around EUV lithography capacity for advanced secure elements threatens production continuity for high-assurance devices. Distribution runs through authorized security integrators and GSA schedule holders for federal contracts, with direct OEM relationships dominating financial services procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Key rotation management and firmware lifecycle services are expanding faster than hardware shipments, converting one-time equipment margins into recurring revenue streams that improve cash flow predictability.
For Market Incumbents: Entrench certification breadth as a competitive moat by accelerating NIST FIPS 140-3 Level 4 submissions before smaller vendors exhaust capital reserves. Secure element supply concentration threatens production continuity; backward integration into captive packaging capabilities or exclusive foundry partnerships reduces exposure to Taiwanese capacity constraints. Government procurement pools reward documentation-ready vendors under EU AI Act conformity assessment pathways. For New Entrants and Emerging Players: Establish a beachhead in India's cost-optimized banking terminal segment where modular hardware without integrated encryption dominates procurement specifications. Contactless facial recognition in German and French healthcare facilities offers white-space expansion with lower certification barriers than federal access control. A subscription-first go-to-market positioning around key rotation services bypasses capital-intensive secure element R&D. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among integrated platform vendors with firmware subscription architectures, suggesting superior long-term viability across a 5-10 year holding period. Acquisition targets should display government certification breadth across multiple national security frameworks paired with documented EU AI Act technical files. The signal to watch is NIST FIPS 140-3 validation backlog duration, which indicates pricing power inflection when lead times extend beyond 18 months.| Strategic Initiative | Industry Significance |
|---|---|
| Secure Element Integration | Co-packaging biometric sensors with tamper-resistant chips eliminates attack surfaces between capture and encryption. |
| EU AI Act Documentation | Conformity assessment pathways for high-risk biometric systems create procurement advantage in European national security frameworks. |
| Firmware Subscription Launch | Key rotation management services transform one-time hardware margins into predictable recurring revenue streams. |
| FIPS 140-3 Level 4 Certification | Federal procurement pools filter vendor participation based on cryptographic module assurance tiers. |
| Contactless Facial Recognition Platform | Healthcare and transportation sectors in Germany and France accelerate touchless biometric deployment post-pandemic. |
Research Methodology
A standing panel of biometric device engineering directors, federal procurement officers, banking security architects, and healthcare IT compliance leads provided ongoing calibration across primary interview cycles. Secondary validation drew from NIST FIPS 140-3 validation databases, EU AI Act implementing guidance, GSA schedule contract awards, and SEC filings of publicly traded security technology vendors. Bottom-up unit shipment estimates triangulated against top-down addressable market sizing across the analysis window.
Scenario-bracketing around regulatory implementation timelines and secure element supply constraints bounded high and low growth paths. Segmentation dimensions modeled include product type, encryption technology, end-user vertical, and application use case, with additional cross-cutting analysis by certification tier and regional procurement framework. CAGRs were derived from fitted growth curves anchored to disclosed federal contract values and banking network refresh cycles, with sensitivity testing against NIST validation backlog durations and foundry capacity utilization rates.
Sensitivities concentrate around EU AI Act enforcement intensity, NIST FIPS 140-3 validation timeline extensions, and geopolitical disruption to Taiwanese secure element fabrication. Forecasts reflect documented assumptions regarding regulatory implementation schedules and supply chain continuity. Macroeconomic contraction in federal IT spending, regulatory deviation from draft AI Act guidance, or breakthrough advances in behavioral biometrics substitution would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biometrics & Identity Management
Europe Government and Security Biometrics Market
Biometrics & Identity Management
IRIS Biometrics Market
Biometrics & Identity Management
Europe Decentralized Identity Market
Biometrics & Identity Management
Password Management Market
Biometrics & Identity Management
Biometric Passport Market
Biometrics & Identity Management
Global Biometric Technology Market
Biometrics & Identity Management
Face Voice Biometric Market
Biometrics & Identity Management
Germany Identity Verification and Authentication Market
Biometrics & Identity Management
Mobile Biometrics Market
Biometrics & Identity Management
Italy Mobile Biometrics Market
Biometrics & Identity Management
Global Authentication Services Market
Biometrics & Identity Management
Spain Mobile Biometrics Market
Biometrics & Identity Management
Europe Enterprise Biometrics Market
Biometrics & Identity Management
Next Generation Biometric Market
Biometrics & Identity Management
Biometric Services Platform (Biosp) Market
Biometrics & Identity Management
Mobile Devices User Authentication Services Market