
 Mobile Devices User Authentication Services Market | 2026-2036
Mobile Devices User Authentication Services Market Size, Share, and Industry Trends Forecast 2026-2036
Mobile Devices User Authentication Services Market Outlook
Financial services and healthcare is hardening as the dominant end-use vertical mix for mobile authentication services. Microsoft Corporation leverages its Entra ID ecosystem to anchor enterprise-grade biometric deployments across regulated industries. Thales Group competes through hardware-anchored trust modules that sustain high-assurance authentication in government-facing contracts.
Mobile devices user authentication services encompass identity verification systems that bind cryptographic credentials to smartphone secure elements, fingerprint sensors with liveness detection thresholds, or facial geometry templates protected by on-chip enclaves. These systems enforce access control for enterprise applications, mobile banking, and e-government portals by validating possession of a registered device plus an inherence or knowledge factor. Fingerprint recognition occupies the largest installed base among authentication methods, though facial recognition captures the fastest enterprise upgrade cycle as liveness detection standards tighten. Cloud-based deployment models concentrate margin pools among platform vendors, while hybrid architectures dominate in European and Asia-Pacific regulated sectors where data residency requirements fragment infrastructure decisions.
NIST in the United States, EBA guidelines under EU PSD2, and the EU AI Act collectively reshape product roadmaps by mandating presentation attack detection for biometrics and strict algorithmic audit trails. The EU AI Act classifies remote biometric identification as high-risk, forcing vendors to maintain conformity assessment documentation and human oversight protocols. Stakeholders must monitor divergence between NIST FIDO2 certification pathways and emerging EU harmonized standards to avoid fragmented compliance investments.
Market Dynamics
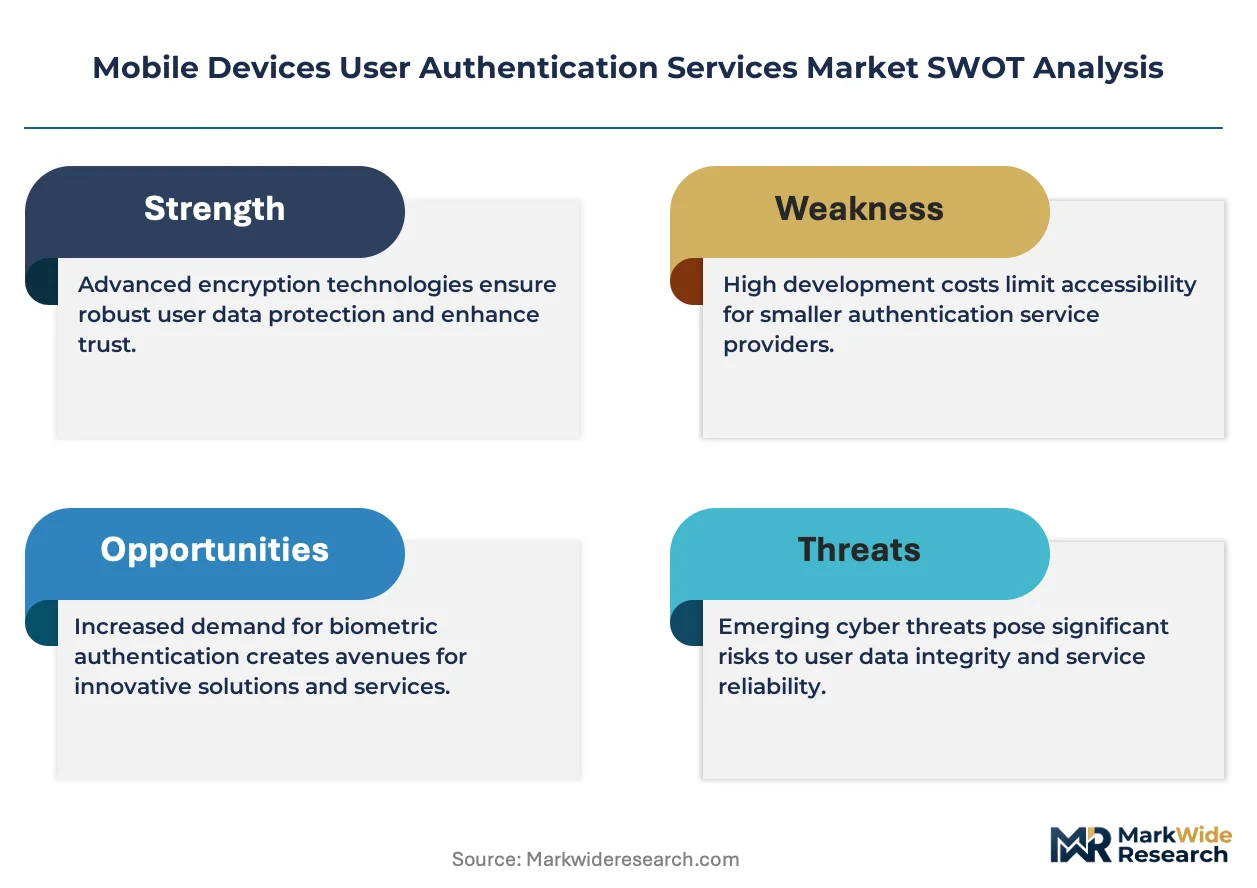
Zero-trust security architectures are compressing procurement cycles across financial services and healthcare, forcing authentication vendors to bundle biometric liveness detection with hardware-backed credential storage.
Growth Catalysts
- NIST FIDO2 frameworks:US federal compliance mandates accelerate enterprise replacement of password-based systems with phishing-resistant authentication protocols.
- Healthcare digitization:HIPAA-covered entities deploy smartphone-based biometric verification to secure electronic health record access across distributed clinical workforces.
- Secure element integration:Smartphone manufacturers embed dedicated cryptographic processors that anchor high-assurance identity verification without external hardware tokens.
Market Restraints
- Biometric sensor cost concentration:Fingerprint and facial recognition module supply clusters in East Asian manufacturing regions, exposing procurement to single-source vulnerability.
- EU AI Act compliance friction:Remote biometric identification classification as high-risk forces vendors to maintain expensive conformity assessment documentation and human oversight protocols.
- Presentation attack detection limitations:Deepfake-enabled spoofing techniques outpace liveness detection algorithm updates in lower-tier device segments.
Strategic Opportunities
- German digital identity mandates:Federal eID infrastructure expansion creates demand for mobile-first authentication integration with government service portals.
- Behavioral biometrics convergence:Keystroke dynamics and gait analysis layer onto existing fingerprint and facial systems for continuous authentication in banking applications.
- PSD2 Strong Customer Authentication:European Banking Authority guidelines drive recurring procurement of certified authentication solutions for payment service providers.
Industry Challenges
- Algorithm audit talent scarcity:Vendors struggle to recruit machine learning engineers capable of documenting bias testing and performance benchmarking for regulatory submissions.
- Legacy IAM integration complexity:Enterprises face extended deployment timelines when bridging modern mobile biometric systems with decades-old on-premises identity management infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mobile Devices User Authentication Services Market |
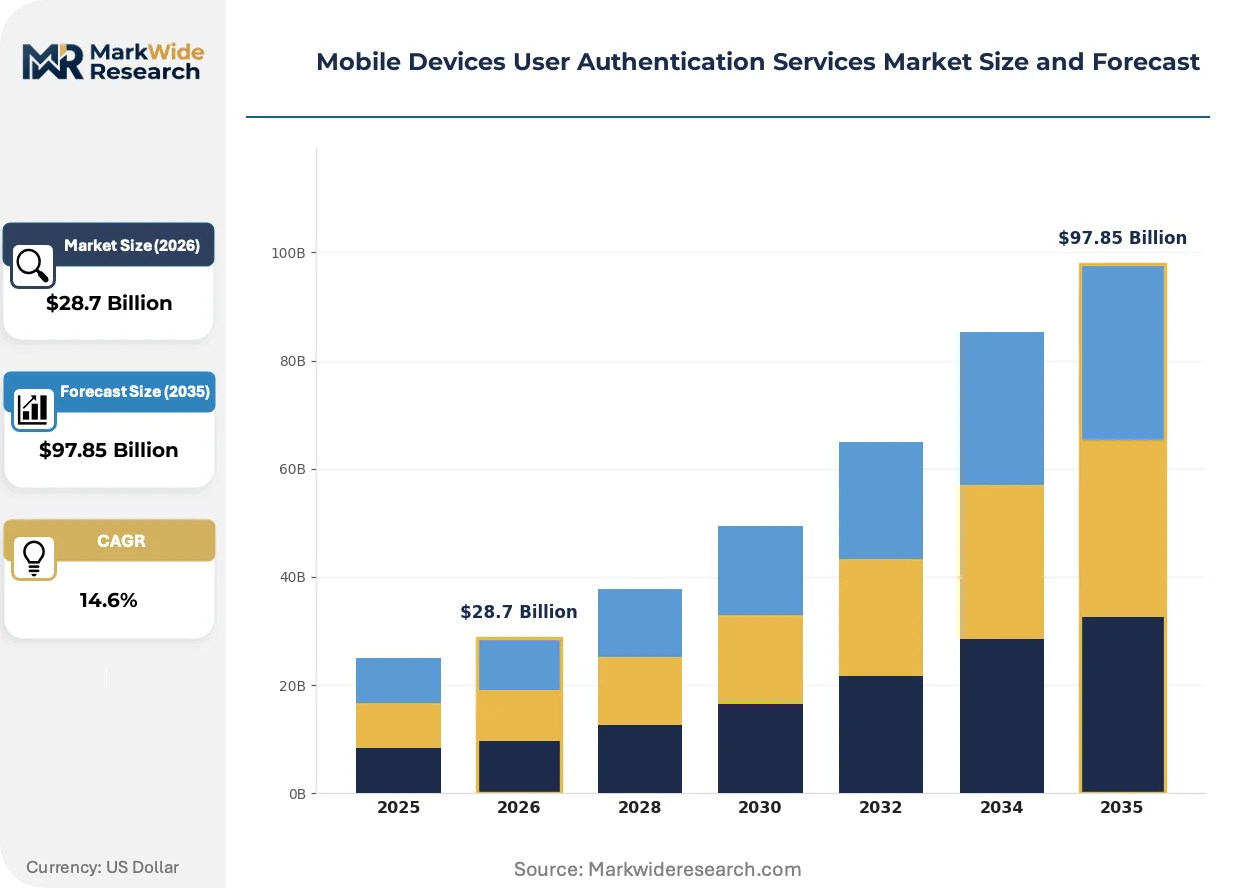
| Market Size in 2026 | $28.7 Billion |
| Market Size in 2035 | $97.85 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Authentication Method: Fingerprint Recognition, Facial Recognition, Password-based, Two-factor Authentication Deployment Model: On-Premises, Cloud-Based, Hybrid, Local Network End User: Consumers, Enterprises, Government Agencies, Educational Institutions Device Type: Smartphones, Tablets, Wearables, Laptops |
| Companies Covered | Microsoft Corporation, RSA Security LLC, Okta, Inc., Google LLC, OneSpan Inc., Duo Security, Thales Group, IBM Security, Ping Identity Holding Corp., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mobile Devices User Authentication Services Market Strategic Shifts
Authentication architectures are fragmenting across cloud-native, hybrid, and on-premises deployments as data residency requirements harden in regulated jurisdictions. Vendors respond with modular platforms that separate biometric processing from credential storage.
Facial recognition with 3D depth sensing and infrared liveness detection is overtaking fingerprint sensors as the primary biometric modality in enterprise smartphone deployments. Financial institutions in the United States and Germany lead this transition, prioritizing presentation attack resistance over familiarity. The shift compresses margins for fingerprint sensor suppliers while expanding addressable market for computer vision specialists.
The EU AI Act mandates algorithmic audit trails and human oversight protocols for remote biometric identification systems deployed in high-risk contexts. Vendors must maintain technical documentation and conformity assessments that extend sales cycles by six to twelve months in European procurement. Healthcare and border control applications face the steepest compliance burden, driving consolidation toward vendors with established regulatory affairs capabilities.
Enterprise buyers increasingly unbundle authentication hardware from platform licensing, sourcing biometric sensors independently from identity orchestration software. This pattern fragments vendor relationships and compresses pricing power for integrated solution providers. German automotive manufacturers and US healthcare systems demonstrate this procurement evolution most visibly, negotiating separate contracts for device firmware, cloud identity services, and on-premise credential vaults.
Mobile Devices User Authentication Services Market Segmentation
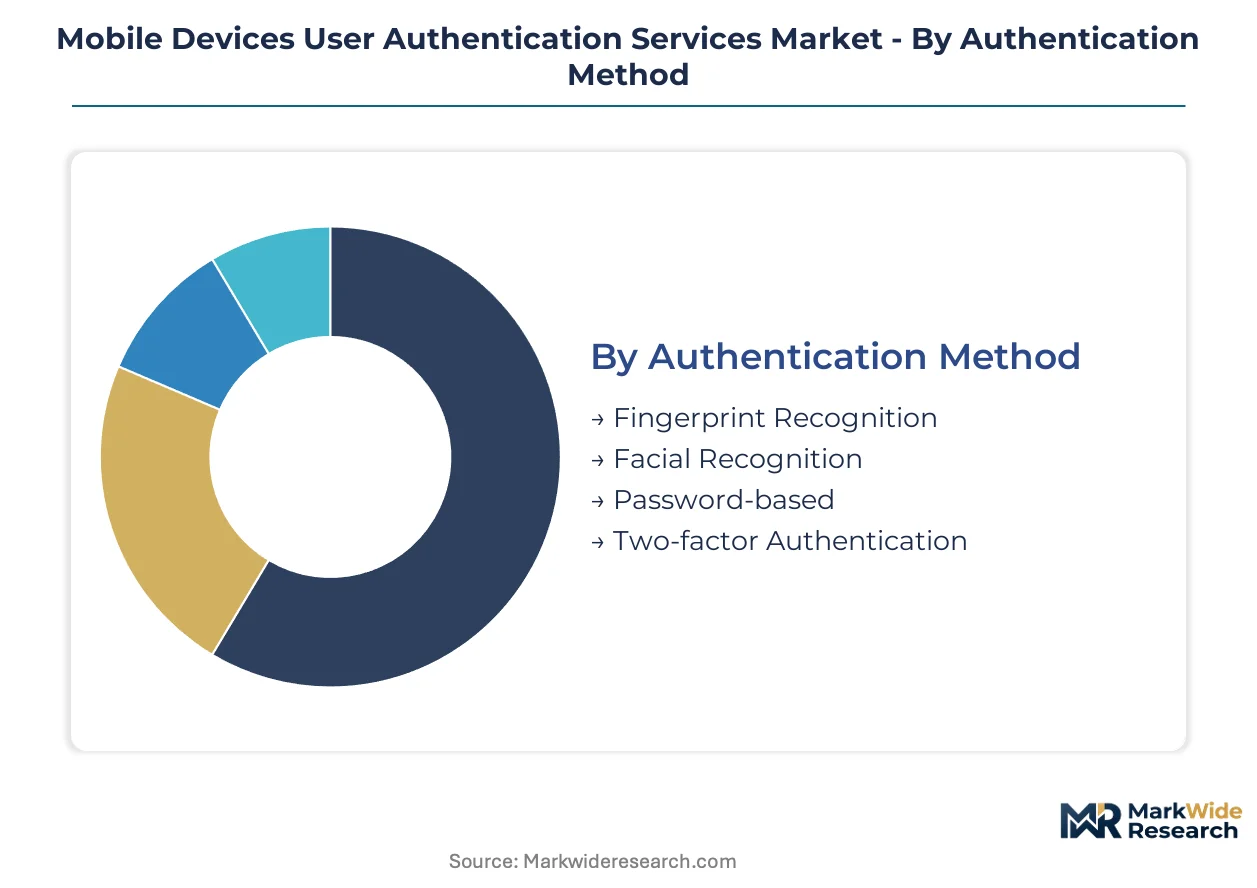
Segmentation in mobile authentication services reveals how capital allocation, regulatory exposure, and hardware integration requirements diverge across customer profiles. Vendors must align R&D spending and compliance infrastructure with the specific deployment constraints of each slice.
Authentication Method:
Capital intensity varies sharply across biometric modalities, with facial recognition systems demanding heavier upfront investment in depth-sensing hardware and liveness detection algorithms than legacy alternatives.
- Fingerprint Recognition:Capacitive and ultrasonic sensors embedded in smartphone home buttons or display undersides provide mature, low-latency verification. Financial services institutions in Germany and the United States continue standardizing on this modality for high-volume retail banking applications where user familiarity reduces training overhead.
- Facial Recognition:Structured light and time-of-flight cameras paired with infrared dot projectors enable 3D facial mapping resistant to presentation attacks. Healthcare systems across HIPAA-covered entities are displacing fingerprint systems with facial authentication to accommodate clinicians wearing gloves, though sensor module costs run three to four times higher than capacitive alternatives.
- Password-based:Knowledge-factor systems require minimal hardware investment but carry escalating compliance costs as NIST FIDO2 frameworks mandate phishing-resistant replacements.
- Two-factor Authentication:SMS and TOTP implementations bridge legacy infrastructure, though carriers and platform vendors face ongoing security audit expenditures.
Fingerprint recognition absorbs the bulk of installed capacity; facial recognition is expanding most quickly.
Deployment Model:
Margin structures compress toward cloud-native delivery in segments with lighter data residency obligations, while hybrid architectures command premium pricing in regulated European and Asia-Pacific jurisdictions.
- Cloud-Based:Multi-tenant identity platforms with biometric processing pipelines hosted in regional data centers enable rapid enterprise onboarding without capital expenditure. United States financial institutions favor this model for workforce authentication, leveraging existing Microsoft Entra ID or Okta integrations.
- Hybrid:Biometric templates stored on-device with policy orchestration delivered from cloud control planes satisfy EU GDPR and emerging AI Act requirements. German automotive manufacturers and French healthcare networks mandate this architecture to retain cryptographic material within national borders.
- On-Premises:Dedicated credential vaults and biometric matching engines deployed in customer data centers serve classified government environments with air-gapped security requirements.
- Local Network:Edge-concentrated authentication without internet dependency supports manufacturing floor and critical infrastructure scenarios where connectivity interruption risks operational continuity.
Cloud-based deployment holds the dominant revenue share; hybrid configurations are climbing the fastest as data localization mandates proliferate.
End User:
Procurement sophistication and contract value scale with organizational IT maturity, fragmenting vendor engagement models across consumer self-service and enterprise solution-selling motions.
- Enterprises:Zero-trust architecture mandates in United States financial services and healthcare drive consolidated platform procurement with biometric liveness detection bundled into workforce identity suites. Contract values span seven figures annually for Fortune 500 deployments.
- Government Agencies:FIPS 140-2 certification and NIST SP 800-63 compliance requirements extend sales cycles but lock in multi-year revenue streams with limited competitive substitution.
- Consumers:Smartphone-native biometric activation through device operating systems generates indirect revenue via app developer licensing and transaction authentication fees.
- Educational Institutions:Campus-wide mobile credentialing for physical access and learning management systems represents emerging demand with elongated budget approval timelines.
Enterprise accounts generate the preponderance of vendor margin; government agencies are gaining share fastest as federal digital identity programs accelerate.
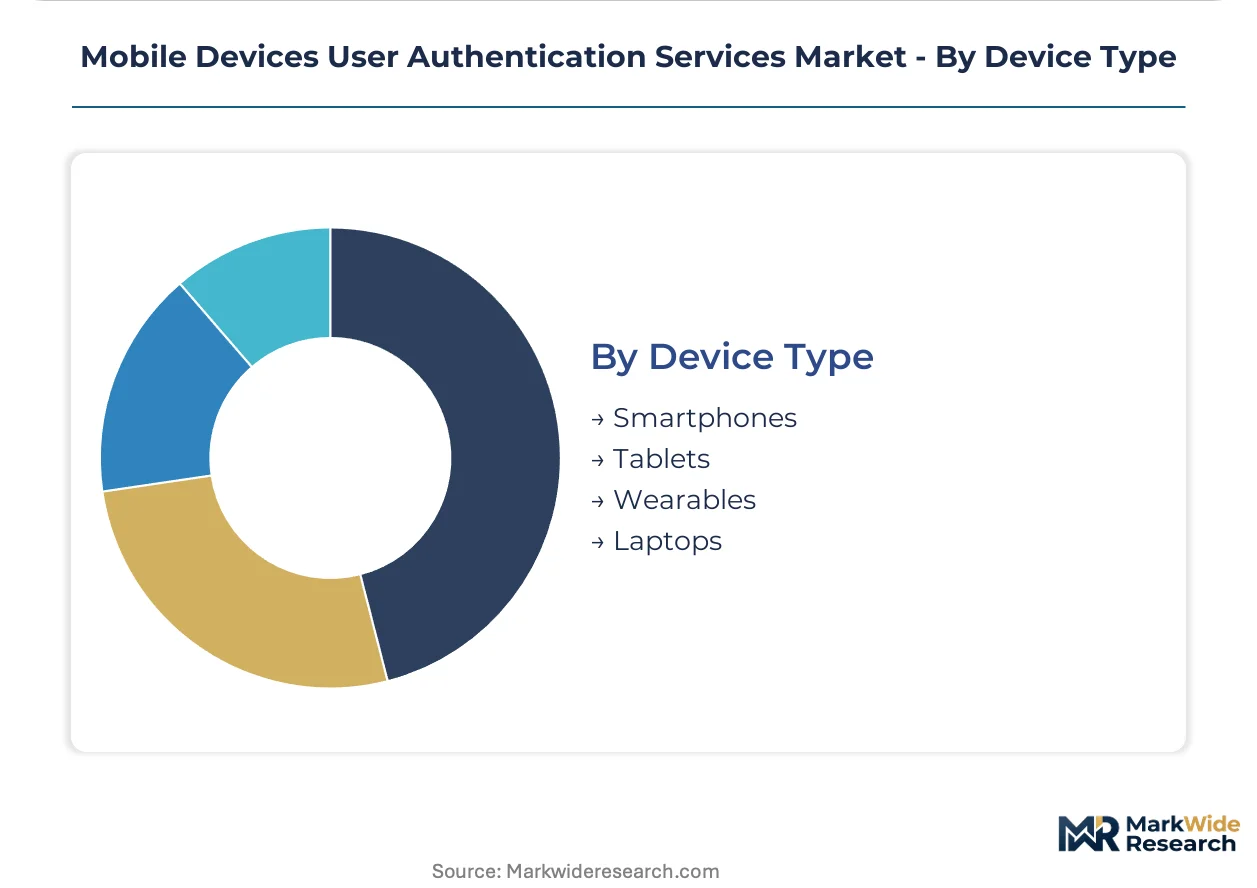
Device Type:
Hardware integration complexity and sensor specification requirements vary across form factors, concentrating biometric innovation investment in smartphone-class devices with sufficient thermal and power budgets.
- Smartphones:Secure element integration and dedicated neural processing units for on-device biometric matching anchor the highest-volume deployment segment. Chinese and South Korean OEMs compete on facial recognition speed and accuracy benchmarks.
- Wearables:Skin conductance sensors and photoplethysmography for continuous authentication impose severe power constraints, limiting biometric sophistication to heart rate variability and gait pattern recognition.
- Tablets:Enterprise field service and clinical documentation use cases in United States healthcare drive demand for large-screen biometric enrollment and verification workflows.
- Laptops:Windows Hello-compatible infrared cameras and fingerprint readers embedded in palm rests satisfy enterprise bring-your-own-device policies with hardware-backed credential isolation.
Smartphones command the dominant installed base; wearables are ascending fastest as continuous authentication use cases mature in financial services fraud prevention.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Authentication services production clusters in East Asian hardware manufacturing zones, while consumption concentrates in North American and European enterprise markets where zero-trust mandates drive procurement.
United States
HIPAA-covered healthcare systems and NIST FIDO2 federal compliance accelerate biometric replacement of legacy password infrastructure. The SEC and FTC enforcement actions against data breaches tighten vendor selection criteria for financial institutions. Seattle and San Francisco Bay Area technology corridors host cloud-native identity platform development that serves Fortune 500 workforce authentication contracts.
Germany
Automotive manufacturers and federal eID infrastructure expansion create demand for hybrid deployment architectures with on-device credential storage. The EU AI Act and GDPR data residency requirements extend procurement cycles by six to twelve months for biometric vendors. Munich and Stuttgart industrial clusters prioritize facial recognition systems with presentation attack detection for manufacturing floor access control.
China
Smartphone OEMs integrate secure element processors and neural processing units for on-device biometric matching at manufacturing scale. MIIT cybersecurity standards and SAMR algorithm governance frameworks shape domestic vendor certification pathways. Shenzhen and Beijing hardware ecosystems concentrate fingerprint and facial recognition sensor module production for global supply.
United Kingdom
Financial services regulators under the FCA mandate strong customer authentication for open banking APIs, driving recurring procurement of certified solutions. The UK GDPR and emerging AI governance frameworks align with EU compliance trajectories post-Brexit. London fintech clusters deploy mobile-first biometric verification for retail banking applications with liveness detection requirements.
India
RBI guidelines for digital payments and the UIDAI Aadhaar ecosystem create foundational identity infrastructure for mobile authentication integration. The BIS and CDSCO regulate biometric device certification for healthcare and financial services deployments. Bangalore and Hyderabad technology hubs develop indigenous authentication platforms for domestic enterprise and government service portal integration.
Mobile Devices User Authentication Services Market Competitive Environment
Top-tier vendors anchor cloud-native identity platforms with biometric liveness detection, while mid-tier specialists compete on hardware-anchored trust modules and sector-specific compliance certifications. The market structure concentrates margin pools among platform vendors with existing enterprise relationships, though hardware-anchored specialists capture high-assurance government contracts. Three archetypes dominate: cloud-native platform orchestrators, hardware-secured credential vault providers, and biometric sensor module integrators. Competitive moves center on modular platform unbundling to accommodate hybrid deployment preferences, and regulatory affairs capability acquisition to compress EU AI Act sales cycles.
Within the cloud-native platform tier, Microsoft Corporation and Google LLC exemplify vendors leveraging existing productivity suite relationships to anchor enterprise biometric deployments. Thales Group occupies a position among hardware-secured specialists, representing the archetype of vendors competing through government-facing certifications and on-premise credential isolation. These three companies illustrate the strategic divergence between software-centric platform expansion and hardware-anchored trust assurance.
| Leading Market Players |
|---|
| Microsoft Corporation |
| RSA Security LLC |
| Okta, Inc. |
| Google LLC |
| OneSpan Inc. |
| Duo Security |
| Thales Group |
| IBM Security |
| Ping Identity Holding Corp. |
| Others |
Value Chain & Pricing Dynamics
Secure element processor fabrication costs in Taiwan and South Korea cascade through three distinct pricing tiers for mobile authentication deployments, with FIDO2-certified biometric modules commanding premium positioning over uncertified alternatives in German and United States federal procurement channels.
Pricing Analysis
Margin tightening in cloud-native authentication tiers reflects hyperscaler platform bundling that compresses standalone biometric software pricing. Three-tier pricing structure across FIDO2-certified, ISO-compliant, and uncertified economy levels separates enterprise buyers by audit documentation requirements. Pricing pressure intensifies in hardware-anchored segments as Chinese OEMs flood mid-market sensor supply. Government agencies demonstrate lowest price sensitivity due to multi-year certification lock-in, while educational institutions face acute budget constraints that delay procurement cycles.
Supply Chain Analysis
Single-source vulnerability sits with East Asian concentrated manufacturing of capacitive fingerprint sensors and structured light facial recognition modules. Taiwan, South Korea, and China anchor global supply for neural processing units, infrared dot projectors, and cryptographic secure elements. Raw material dependencies include rare earth elements for laser diodes, silicon wafers for biometric ASICs, and specialized optical glass for depth-sensing cameras. Tariff exposure on Chinese-manufactured sensor modules threatens margin stability for European and North American integrators. Distribution runs through OEM direct procurement for smartphone-embedded components and value-added resellers for enterprise authentication platform licensing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Facial recognition with 3D liveness detection is displacing fingerprint systems across HIPAA-covered healthcare and NIST-compliant federal environments, compressing deployment timelines for vendors with mature presentation attack resistance capabilities.
For Market Incumbents: Deepen hardware-software integration through captive secure element design partnerships with Taiwanese foundries, defending against modular unbundling trends that fragment vendor relationships in German automotive and United States healthcare procurement. Prioritize EU AI Act conformity assessment pre-certification to compress six-to-twelve-month European sales cycles before regulatory divergence widens compliance cost gaps with NIST FIDO2 pathways. For New Entrants and Emerging Players: Behavioral biometrics convergence with keystroke dynamics and gait analysis offers technology-first wedge positioning in European banking fraud prevention, where PSD2 Strong Customer Authentication mandates create recurring procurement windows. Target underpenetrated educational institution credentialing for campus physical access and learning management integration, leveraging elongated budget cycles through subscription-based pricing that defers upfront capital expenditure. For Investors and Strategic Acquirers: NIST SP 800-63 certification queue acceleration is the leading indicator that hardware-anchored trust module specialists face acquisition premium expansion as federal digital identity programs mature. Long-term viability centers on regulatory affairs capability depth rather than pure technology differentiation, with algorithm audit talent scarcity driving consolidation toward vendors with documented bias testing infrastructure. Watch for EU AI Act harmonized standards publication as the signal for European procurement normalization that rewards early compliance investments.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Microsoft Entra ID ecosystem anchoring accelerates enterprise biometric deployment across HIPAA-covered entities. |
| Regulatory Pre-Certification | EU AI Act conformity assessment documentation compresses sales cycles for German federal eID infrastructure contracts. |
| Acquisition of Specialist Firm | Computer vision liveness detection capabilities address facial recognition upgrade demand in United States financial services. |
| Geographic Expansion | Indian UIDAI Aadhaar ecosystem integration captures RBI-mandated digital payment authentication procurement. |
| Strategic Partnership | Automotive manufacturer alliances in Stuttgart and Munich hybrid deployment architectures satisfy GDPR data residency. |
Study Parameters
SEC 10-K filings, EBA PSD2 implementation reports, and NIST SP 800-63 documentation formed the secondary backbone, cross-referenced with primary interviews across CISOs at Fortune 500 financial institutions, biometric platform engineering leads, federal identity program officers, and healthcare IT procurement committees. Bottom-up triangulation against top-down regulatory mandate sizing validated authentication volume estimates across deployment models.
Historical trendline analysis of federal compliance procurement cycles and healthcare digitization spend patterns informed projection modeling across authentication method, deployment architecture, end-user organization type, and device form factor. CAGRs derived from segment-level demand elasticity to regulatory deadline acceleration, with biometric sensor cost curves and cloud identity platform pricing trajectories as core forecast inputs.
Several conditions sit outside the modeled scope, including sovereign AI Act enforcement variance across EU member states and unforeseen deepfake spoofing breakthroughs that outpace liveness detection algorithm updates. Forecasts reflect documented assumptions regarding NIST FIDO2 adoption velocity and hardware secure element integration timelines. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biometrics & Identity Management
Global Biometric Identification Market
Biometrics & Identity Management
Biometrics Software Market
Biometrics & Identity Management
Mobile Biometric Security and Services Market
Biometrics & Identity Management
Vein Recognition Biometrics Market
Biometrics & Identity Management
Military Biometrics Market
Biometrics & Identity Management
Asia-Pacific Government and Security Biometrics Market
Biometrics & Identity Management
Authentication Solution Market
Biometrics & Identity Management
Signature Verification Market
Biometrics & Identity Management
Mobile Biometrics Market
Biometrics & Identity Management
Global Authentication Services Market
Biometrics & Identity Management
Middle East and Africa Biometrics in Government Market
Biometrics & Identity Management
Biometric Bike Locks Market
Biometrics & Identity Management
Healthcare Biometrics Market
Biometrics & Identity Management
Global Biometrics Middleware Market
Biometrics & Identity Management
North America Government and Security Biometrics Market
Biometrics & Identity Management
Face Voice Biometric Market