
 Palm Vein Biometrics Market | 2026-2036
Palm Vein Biometrics Market Size, Share, and Industry Trends Forecast 2026-2036
Palm Vein Biometrics Market Analysis
Japan is reconfiguring palm vein biometrics capacity through Fujitsu's sustained manufacturing presence and Hitachi's specialized sensor development. NEC Corporation leverages its optical engineering heritage to anchor enterprise security contracts across Asia-Pacific. M2SYS Technology competes in modular integration, while BioSec Group differentiates through access control hardware for European commercial installations.
Palm vein biometrics employs near-infrared illumination to capture subcutaneous hemoglobin patterns, creating a contactless, spoof-resistant identity credential for high-assurance authentication environments. The technology's liveness detection and template encryption satisfy stringent data protection requirements in banking and healthcare infrastructure. Standalone reader deployments dominate current revenue as legacy access control upgrades accelerate, while integrated systems represent the fastest-growing product category as enterprises consolidate physical and logical security stacks. Banking applications command premium pricing due to regulatory compliance burdens, though healthcare is expanding fastest as patient identification errors drive biometric adoption in hospital networks.
Japan's PMDA and METI shape medical device authentication standards, while Europe's GDPR and AI Act impose algorithmic transparency and consent management obligations on biometric vendors. The US FDA and NIST frameworks influence procurement specifications for healthcare and federal security deployments. Stakeholders must monitor evolving cross-border data localization rules and certification reciprocity agreements as palm vein systems proliferate across multinational organizations.
Market Dynamics
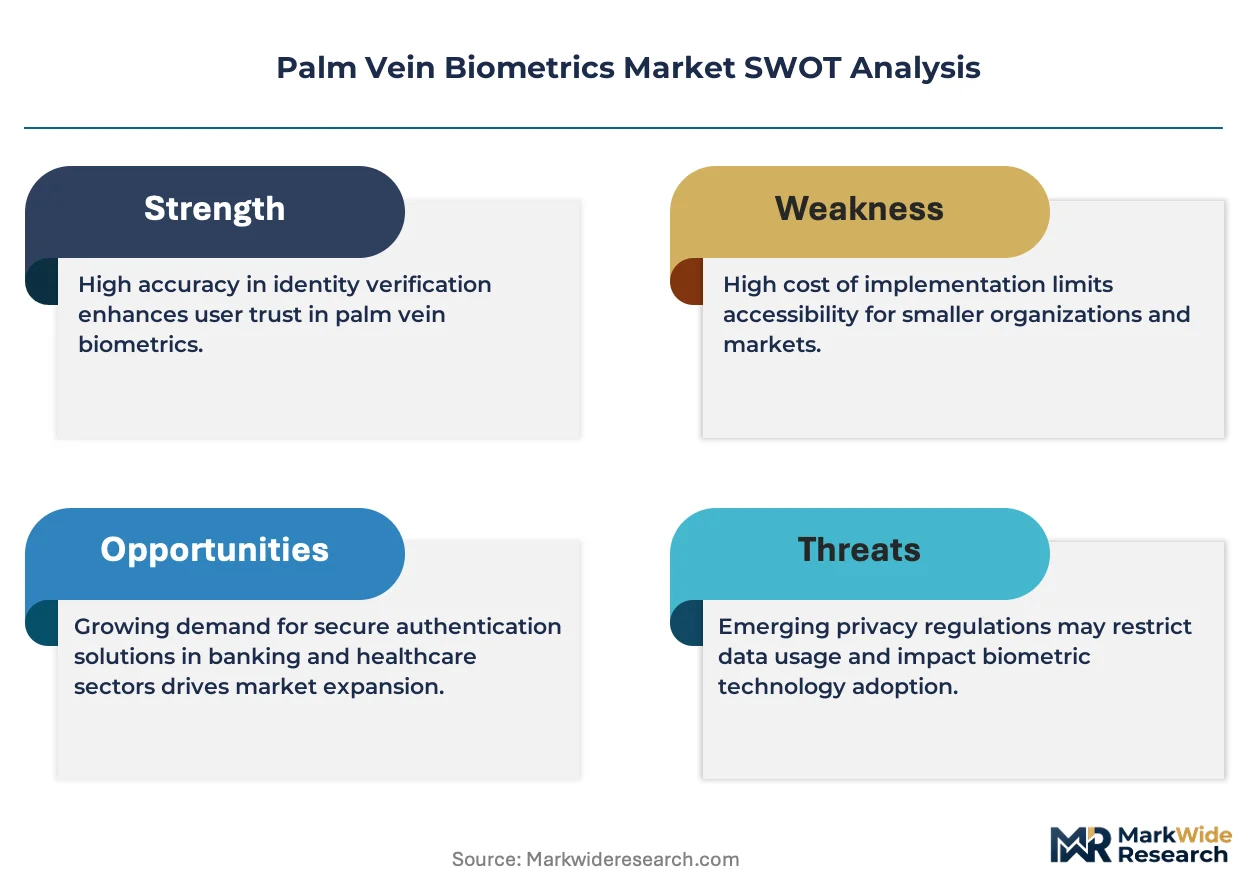
The Palm Vein Biometrics Market is experiencing structural pressure from regulatory fragmentation as GDPR in Europe, Japan's PMDA medical device standards, and South Korea's financial authentication mandates create divergent compliance requirements that reshape vendor R&D allocation and certification roadmaps.
Growth Catalysts
- Healthcare patient identification mandates:Hospital networks in the United States are deploying palm vein systems to eliminate duplicate records and wrong-patient errors, with the Joint Commission accreditation standards accelerating biometric credentialing investments.
- Contactless authentication protocols:Post-pandemic hygiene requirements in Japanese banking branches have institutionalized near-infrared palm scanning as the default high-assurance credential for teller-assisted transactions.
- GDPR Article 9 special category processing:European financial institutions are selecting certified palm vein solutions to satisfy biometric data governance obligations while minimizing consent management friction for recurring authentication.
Market Restraints
- Near-infrared sensor supply concentration:Specialized CMOS and CCD sensor fabrication for subcutaneous imaging remains concentrated among Japanese and Taiwanese semiconductor foundries, creating input cost volatility and procurement lead time exposure.
- Template storage infrastructure capex:Encrypted biometric vault deployments require substantial capital expenditure for on-premise hardware or certified cloud environments, compressing margins for mid-tier enterprise buyers.
- Algorithmic transparency requirements:The EU AI Act's explainability mandates for high-risk biometric systems impose documentation and audit burdens that extend vendor certification timelines by 12-18 months.
Strategic Opportunities
- Indian healthcare digitization:The Ayushman Bharat health infrastructure expansion creates first-mover positioning for palm vein patient identification in tier-2 and tier-3 hospital networks lacking legacy biometric investments.
- Convergence with mobile credentialing:Smartphone-integrated palm vein readers are hybridizing physical access control with remote authentication, opening enterprise zero-trust architecture deployments.
- Brazilian financial inclusion mandates:Central bank regulations requiring biometric verification for digital banking onboarding are creating demand for contactless modalities in underbanked regions with limited fingerprint infrastructure.
Industry Challenges
- Optical engineering talent scarcity:The intersection of near-infrared physics, machine learning, and cryptographic protocol design creates recruitment bottlenecks for specialized firmware and hardware development teams.
- Legacy access control integration complexity:Enterprise security stacks built on Wiegand or OSDP protocols require middleware development for palm vein reader interoperability, extending deployment timelines.
- Cross-border template portability standards:Absence of ISO/IEC 39794-2 implementation consistency across Japanese JIS and European CEN frameworks fragments multinational enterprise rollout strategies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Palm Vein Biometrics Market |
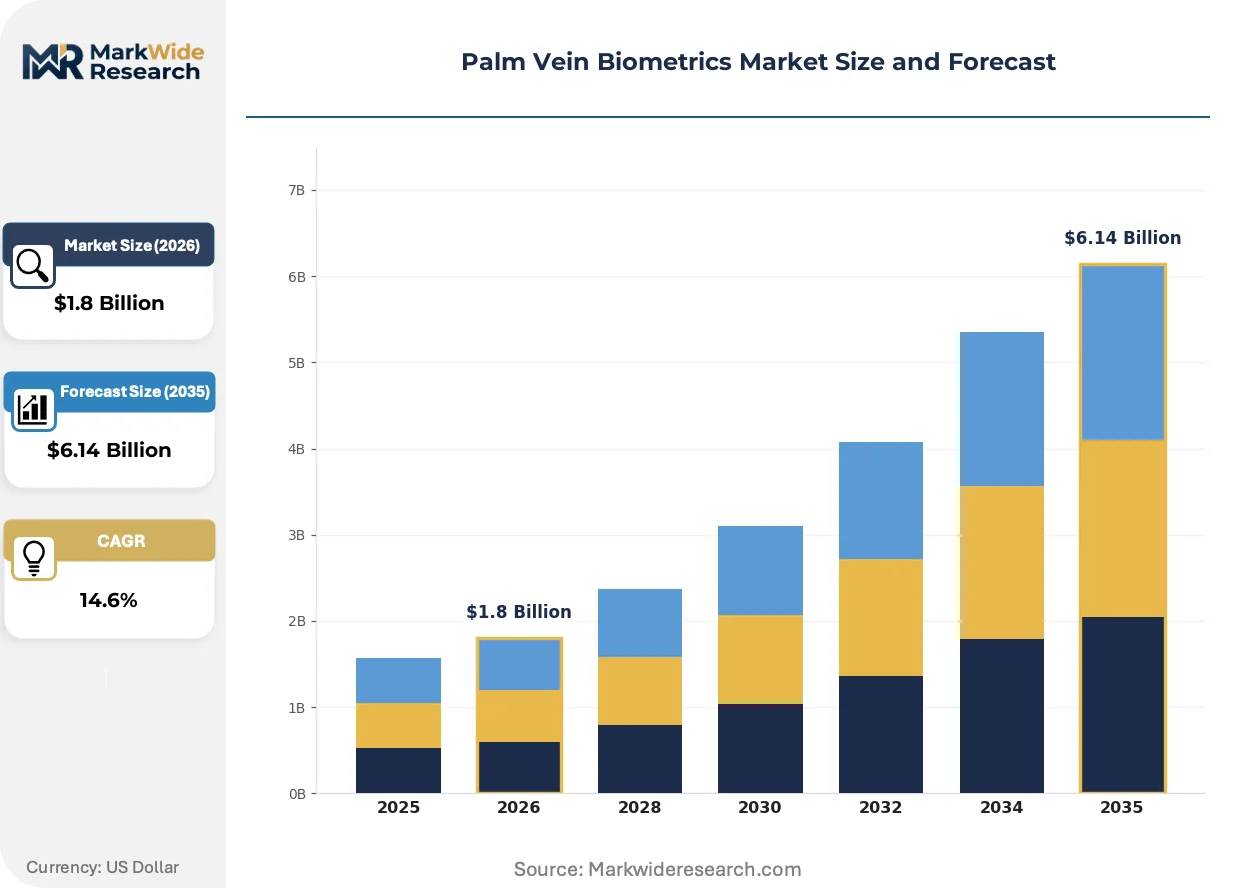
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $6.14 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standalone Reader, Integrated System, Mobile Device, Access Control Application: Security, Time & Attendance, Healthcare, Banking End User: Commercial, Government, Residential, Educational Technology: Near-Infrared, Optical Sensor, Algorithms, Data Encryption |
| Companies Covered | M2SYS Technology, Recogtech, Fujitsu, Hikvision, IDLink Systems, Hitachi, BioSec Group, Mantra Softech, NEC Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Palm Vein Biometrics Market Emerging Trajectories
Near-infrared imaging architectures are converging with edge AI inference to enable on-device template generation, eliminating network transmission of raw biometric data and reshaping vendor competitive positioning around privacy-preserving hardware design.
Multispectral palm vein capture is hybridizing subcutaneous vascular pattern recognition with surface texture analysis to improve performance across skin tone variation and environmental lighting conditions. Medical device manufacturers in Japan are adopting these hybrid sensors for patient identification in emergency departments where rapid enrollment under suboptimal illumination is critical. This convergence is compressing the performance gap between palm vein and iris recognition in high-throughput healthcare settings.
The EU AI Act's high-risk biometric system classification is mandating conformity assessment procedures that extend vendor certification timelines and documentation burdens. European financial institutions are now requiring algorithmic impact assessments and bias testing protocols as standard procurement criteria. Germany's KBA and France's CNIL are interpreting these requirements with additional national specificity, creating a patchwork compliance landscape that favors vendors with established European regulatory affairs capabilities.
Hospital procurement committees are consolidating physical and logical security vendor relationships to reduce contract management overhead and streamline incident response. Integrated platform providers are displacing standalone reader vendors in North American health network tenders, with preference shifting toward vendors offering unified identity credentials across building access, medication dispensing, and EHR authentication. This consolidation is most visible in California and Texas hospital systems pursuing enterprise-wide biometric standardization.
Palm Vein Biometrics Market Segmentation
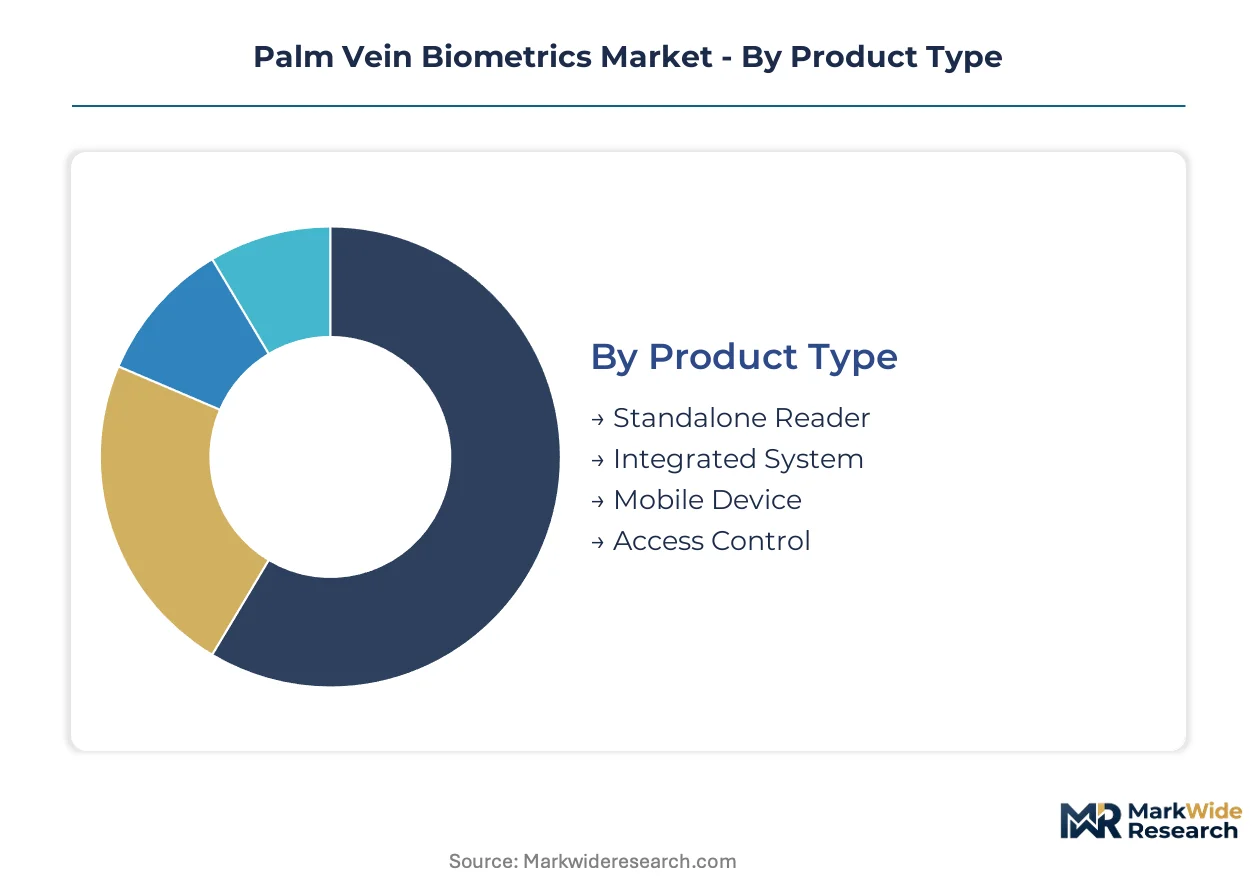
Product architecture determines deployment economics and integration complexity for palm vein biometric systems. Application context shapes regulatory exposure and authentication assurance requirements. Understanding how these dimensions intersect reveals where vendor R&D investments concentrate and where pricing power accumulates.
Product Type:
Cost tier structures procurement decisions across enterprise security budgets, with hardware-software bundling ratios varying sharply by installation scale.
- Standalone Reader:Purpose-built near-infrared capture units with embedded template matching engines. Japanese banking branches deploy these for teller-assisted authentication where legacy infrastructure limits system integration. Regulatory compliance burdens in South Korea's financial sector sustain premium pricing for certified standalone units.
- Integrated System:Multi-modal platforms consolidating palm vein with access control, time tracking, and logical security stacks. North American hospital networks pursue these for unified patient and staff credentialing across physical and digital touchpoints. The steepest expansion runs through this segment as enterprises consolidate vendor relationships.
- Mobile Device:Smartphone-attachable or embedded palm vein modules for remote authentication.
- Access Control:Door-mounted readers with Wiegand or OSDP protocol outputs for building security.
Standalone Reader commands the established base. The steepest expansion runs through Integrated System.
Application:
End-use context dictates performance thresholds, with healthcare and banking imposing the most stringent liveness detection and encryption requirements.
- Banking:High-assurance customer authentication for branch transactions and digital onboarding. Brazil's central bank mandates drive contactless biometric adoption in underbanked regions lacking fingerprint infrastructure. Premium pricing reflects regulatory compliance documentation and audit trail capabilities.
- Healthcare:Patient identification to eliminate duplicate records and wrong-patient medication errors. United States hospital networks accelerate deployments under Joint Commission accreditation pressure. The steepest expansion trajectory appears here as patient safety investments outpace other verticals.
- Security:Physical perimeter protection and logical access management for enterprise facilities.
- Time & Attendance:Workforce tracking with anti-spoofing safeguards against buddy-punching fraud.
Banking commands the established base. The steepest expansion runs through Healthcare.
End User:
Customer type determines procurement sophistication, with government and commercial buyers driving divergent certification and pricing dynamics.
- Commercial:Enterprise campuses, retail chains, and corporate headquarters seeking unified physical-logical security. GDPR Article 9 compliance obligations in European financial services accelerate certified solution procurement. Procurement committees favor vendors with established European regulatory affairs capabilities.
- Government:Federal facilities, defense installations, and critical infrastructure protection. NIST frameworks influence specifications for high-assurance federal security deployments in the United States. Extended certification timelines compress near-term revenue recognition.
- Residential:Smart home and multi-tenant building access applications.
- Educational:Campus security and student meal plan authentication systems.
Commercial commands the established base. The steepest expansion runs through Government.
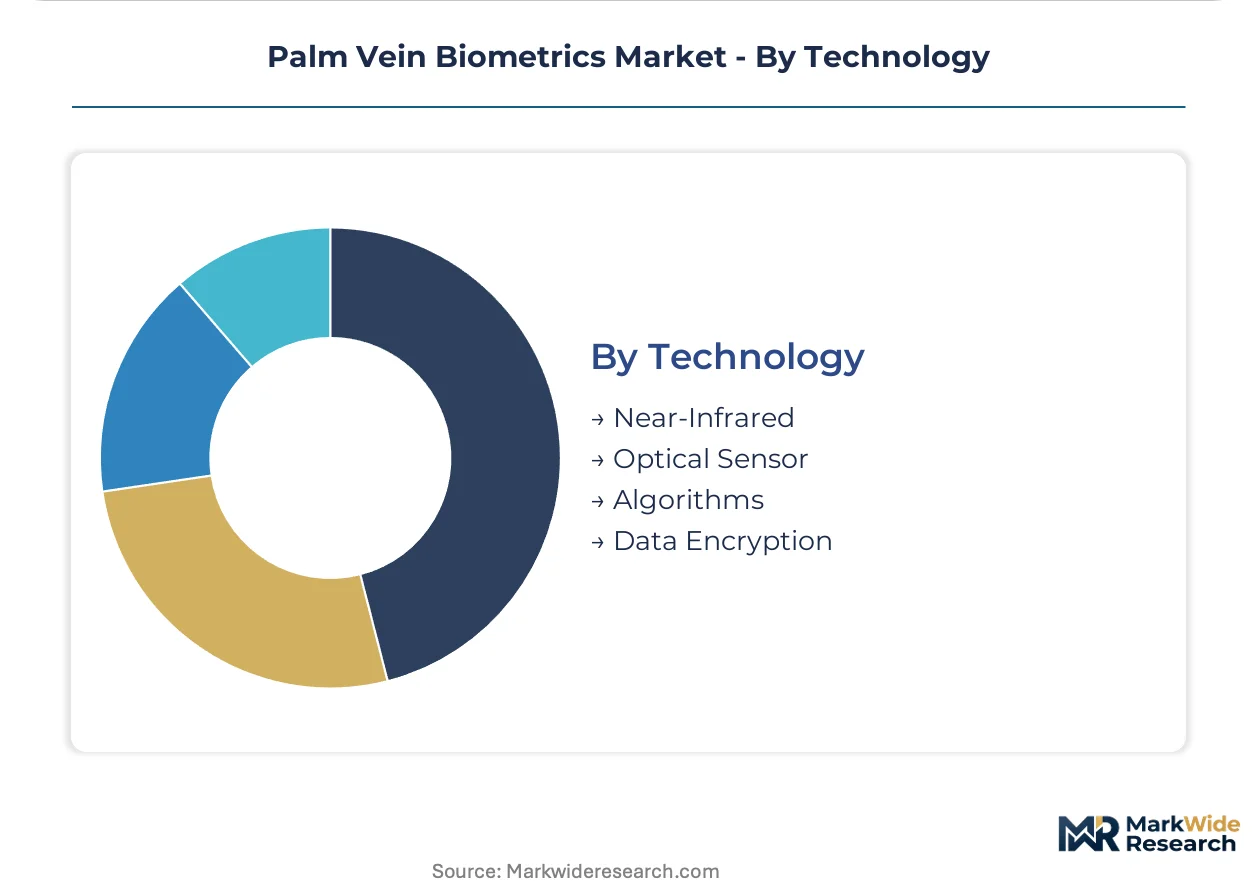
Technology:
Technical maturity varies across the imaging-to-matching stack, with sensor fabrication concentration creating supply-side constraints.
- Near-Infrared:Illumination wavelengths between 700-1000nm penetrating skin to capture hemoglobin absorption patterns. Japanese and Taiwanese semiconductor foundries concentrate specialized CMOS and CCD sensor fabrication, creating input cost volatility. The steepest expansion runs through this foundational layer as multispectral architectures proliferate.
- Algorithms:Template extraction, matching, and liveness detection software. EU AI Act explainability mandates impose documentation burdens extending vendor certification timelines by 12-18 months. Machine learning model development concentrates competitive differentiation.
- Optical Sensor:Lens assemblies and image capture hardware for subcutaneous imaging.
- Data Encryption:Template protection protocols and secure vault architectures for biometric storage.
Near-Infrared commands the established base. The steepest expansion runs through Algorithms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized CMOS and CCD sensor fabrication for near-infrared imaging concentrates among Japanese and Taiwanese foundries, creating regional supply dependencies that reshape procurement strategies across downstream authentication markets.
United States
Hospital networks in California and Texas pursue enterprise-wide biometric standardization for patient identification under Joint Commission accreditation pressure. The FDA and NIST frameworks influence procurement specifications for healthcare and federal security deployments. Greater Boston hosts emerging technology clusters where integrated platform providers consolidate physical and logical security vendor relationships.
Japan
Financial institutions deploy palm vein systems for branch authentication and teller-assisted transactions following post-pandemic contactless protocols. METI and PMDA shape medical device authentication standards and near-infrared imaging requirements. Tokyo anchors Fujitsu's sustained manufacturing presence and Hitachi's specialized sensor development for enterprise security contracts.
Germany
European financial institutions select certified palm vein solutions to satisfy GDPR Article 9 biometric data governance obligations. The KBA interprets EU AI Act explainability mandates with additional national specificity, extending vendor certification timelines. Industrial security clusters in Bavaria drive demand for access control hardware in commercial installations.
South Korea
Financial authentication mandates from the central bank accelerate palm vein deployments across banking branch networks. The MFDS influences medical device standards convergence with biometric authentication systems. Seoul anchors demand concentration for high-assurance credentialing in urban financial centers lacking legacy fingerprint infrastructure.
Brazil
Central bank regulations requiring biometric verification for digital banking onboarding create demand for contactless modalities in underbanked regions. ANVISA frameworks shape healthcare authentication procurement as patient identification systems expand. São Paulo anchors financial inclusion mandates driving palm vein adoption among tier-2 and tier-3 banking networks.
Palm Vein Biometrics Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream controlling sensor fabrication and algorithmic intellectual property. The vendor base stratifies between diversified electronics conglomerates with optical engineering heritage and focused biometric specialists pursuing modular integration partnerships. Three archetypes dominate: diversified technology conglomerates with captive semiconductor capabilities, specialized biometric hardware vendors, and software-centric platform integrators. Competitive dynamics center on strategic partnerships for middleware development and certification reciprocity agreements spanning multiple regulatory jurisdictions.
Among diversified technology conglomerates, Fujitsu and Hitachi anchor the hardware-intensive tier with established sensor manufacturing and optical engineering capabilities. NEC Corporation occupies a position exemplifying enterprise security contract consolidation across Asia-Pacific markets. Within the specialized biometric segment, M2SYS Technology represents modular integration specialists competing on interoperability architecture, while BioSec Group exemplifies European access control hardware differentiation for commercial installations.
| Leading Market Players |
|---|
| M2SYS Technology |
| Recogtech |
| Fujitsu |
| Hikvision |
| IDLink Systems |
| Hitachi |
| BioSec Group |
| Mantra Softech |
| NEC Corporation |
| Others |
Supply Flow & Price Mechanics
Tokyo's semiconductor fabrication clusters concentrate specialized CMOS and CCD sensor capacity for near-infrared imaging, creating asymmetric pricing power for Japanese foundries serving downstream biometric authentication markets. This geographic concentration shapes procurement economics for palm vein system vendors competing on liveness detection performance.
Pricing Analysis
GDPR Article 9 dictates the pricing tier structure for European deployments, with certified solutions commanding premiums over uncertified alternatives. Three-tier pricing structure across certified-premium, standard-compliance, and economy-reader levels separates banking-grade encryption from commercial access control offerings. Pricing pressure stems from algorithmic transparency documentation burdens extending vendor certification timelines. Mid-tier enterprise buyers exhibit highest price sensitivity due to encrypted biometric vault infrastructure capex requirements.
Supply Chain Analysis
Specialized near-infrared sensor fabrication draws from Japanese and Taiwanese foundry capacity, with lens assemblies and edge-AI inference chips completing the hardware stack. Raw material dependencies center on high-purity silicon substrates, near-infrared LED emitters, and cryptographic processor modules. Single-source vulnerability concentrates in subcutaneous imaging sensor supply, exposing procurement timelines to foundry allocation decisions. Distribution runs through systems integrators and direct enterprise contracts for integrated platform deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Palm vein biometrics is recovering from pandemic-delayed enterprise security upgrades, with hospital network standardization and financial branch modernization forming the cyclical demand base.
For Market Incumbents: Build certification moats around EU AI Act conformity assessment procedures and FDA medical device pathways. Extend algorithmic documentation capabilities to compress 12-18 month audit timelines. Anchor enterprise security contracts through middleware development for Wiegand and OSDP protocol interoperability, neutralizing emerging platform integrators. For New Entrants and Emerging Players: Build out modular integration partnerships with access control specialists lacking biometric firmware expertise. Target Indian tier-2 hospital networks under Ayushman Bharat infrastructure expansion, where legacy biometric investments remain absent. Pursue smartphone-attachable palm vein modules for zero-trust architecture deployments as the primary go-to-market angle. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-compliance play because biometric data governance frameworks are tightening across healthcare and financial verticals. Acquisition candidates cluster around algorithm specialists with established European regulatory affairs capabilities. Watch for ISO/IEC 39794-2 template portability standardization as the inflection signal for multinational rollout scalability.| Strategic Initiative | Industry Significance |
|---|---|
| Algorithm Certification Investment | EU AI Act documentation capabilities compress vendor audit timelines by 12-18 months. |
| Middleware Development Partnership | Wiegand and OSDP protocol interoperability extends deployment timelines for enterprise security stacks. |
| Multispectral Sensor Architecture | Hybrid subcutaneous and surface capture improves performance across skin tone variation in emergency departments. |
| Hospital System Consolidation | Unified identity credentials across building access and EHR authentication reduce contract management overhead. |
| Regulatory Affairs Capability Buildout | Established European regulatory expertise navigates KBA and CNIL national specificity patchworks. |
Methodological Framework
Desk research of FDA 510(k) filings, EU MDR conformity assessments, and hospital procurement databases preceded structured interviews with biomedical engineers, GPO contracts managers, and enterprise security architects. Primary fieldwork with palm vein system integrators and near-infrared sensor procurement leads at Japanese foundries validated secondary estimates. Bottom-up unit economics and top-down sector expenditure patterns were triangulated against NIST framework adoption timelines.
Forecast assumptions held regulatory certification timelines and sensor foundry capacity within observed ranges across the analysis window. Segmentation dimensions modeled include product architecture, application vertical, end-user procurement sophistication, and technology layer. CAGRs were derived from installed base growth rates and replacement cycle compression in healthcare settings. Edge-AI inference adoption and multispectral imaging penetration served as industry-specific demand accelerators.
The forecast holds incumbent behavior within observed patterns; aggressive moves by smartphone-integrated biometric platforms would shift outcomes beyond modeled ranges. Cross-checking against Joint Commission accreditation pressure indices and central bank biometric mandate announcements is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biometrics & Identity Management
Global Biometric Card Market
Biometrics & Identity Management
Face Voice Biometric Market
Biometrics & Identity Management
Passive Authentication Market
Biometrics & Identity Management
Global Biometrics Middleware Market
Biometrics & Identity Management
Global Biometric Authentication Identification Market
Biometrics & Identity Management
United States Facial Recognition Market
Biometrics & Identity Management
GCC Biometrics Market
Biometrics & Identity Management
Global Biometric Technology Market
Biometrics & Identity Management
Fingerprint Biometrics Market
Biometrics & Identity Management
Physical Identity and Access Management (PIAM) Software Market
Biometrics & Identity Management
Biometric Smart Cards Market
Biometrics & Identity Management
Flash Calling Authentication Market
Biometrics & Identity Management
Middle East and Africa Biometrics in Government Market
Biometrics & Identity Management
China Mobile Biometrics Market
Biometrics & Identity Management
Spain Mobile Biometrics Market
Biometrics & Identity Management
Biometrics Banking Market