
 Global Behavioral Biometrics Market | 2026-2036
Global Behavioral Biometrics Market Size, Share, and Industry Trends Forecast 2026-2036
Global Behavioral Biometrics Market Foresight
Platform licensing revenue is tilting away from perpetual on-premises contracts toward recurring cloud-based arrangements. BioCatch leverages continuous authentication architectures to sustain its position in financial services fraud prevention. BehavioSec anchors European banking deployments with keystroke and mouse-movement profiling. Nuance Communications competes through voice biometrics integration layered into enterprise contact center stacks.
Behavioral biometrics encompasses the measurement and statistical analysis of human activity patterns—encompassing keystroke dynamics, gait analysis, signature rhythm, and cognitive interaction metrics—to establish identity verification or detect anomalous behavior with false acceptance rates typically engineered below one percent. Its primary commercial purpose centers on invisible, continuous authentication that eliminates friction while flagging session hijacking, account takeover, and synthetic identity fraud in real time. Software components dominate current revenue composition, though services margins are expanding fastest as institutions demand implementation support for hybrid cloud deployments. Fraud detection applications lead transaction volume, while identity verification segments are accelerating as remote onboarding protocols harden against deepfake injection.
The EU AI Act classifies certain biometric inference systems as high-risk, compelling algorithmic transparency documentation and human oversight protocols that reshape vendor R&D priorities. NIST in the United States maintains SP 800-63B digital identity guidelines that directly influence financial sector procurement specifications through FFIEC examination manuals. Stakeholders must monitor how divergent transatlantic compliance architectures affect interoperability investments and customer data residency requirements.
Market Dynamics
Continuous authentication architectures are displacing static password systems across financial services, compressing deployment timelines from multi-year enterprise cycles to quarterly cloud rollouts.
Growth Catalysts
- EU AI Act high-risk classification:Mandatory algorithmic transparency documentation accelerates vendor investment in explainable biometric inference systems that satisfy supervisory scrutiny.
- Keystroke dynamics:Real-time fraud prevention deployments in BFSI institutions generate recurring platform licensing revenue streams replacing perpetual on-premises contracts.
- United States:NIST SP 800-63B guidelines and FFIEC authentication standards shape federal and commercial procurement specifications, concentrating vendor R&D investment.
Market Restraints
- GDPR data residency:Cross-border biometric data flows face structural friction from divergent transatlantic compliance architectures that reshape interoperability investments.
- Deepfake injection:Synthetic identity fraud techniques advance faster than detection model retraining cycles, creating persistent false negative risks in remote onboarding protocols.
- Cloud infrastructure concentration:Hybrid deployment support requirements concentrate vendor dependency on hyperscale compute providers with limited geographic redundancy.
Strategic Opportunities
- Gait analysis:Physical behavioral biometrics for endpoint security remains underpenetrated in enterprise mobility management outside financial services verticals.
- Voice biometrics:Convergence with natural language processing enables contact center stack integration for real-time agent authentication and fraud flagging.
- India:RBI digital payment security guidelines create regulatory tailwind for behavioral authentication deployment in mobile banking and UPI transaction flows.
Industry Challenges
- Explainable AI talent:Scarce machine learning engineering capacity with regulatory documentation expertise constrains vendor scaling for EU AI Act compliance.
- Legacy identity stack integration:Session hijacking detection requires real-time API orchestration with decades-old mainframe authentication architectures in tier-one banks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Behavioral Biometrics Market |
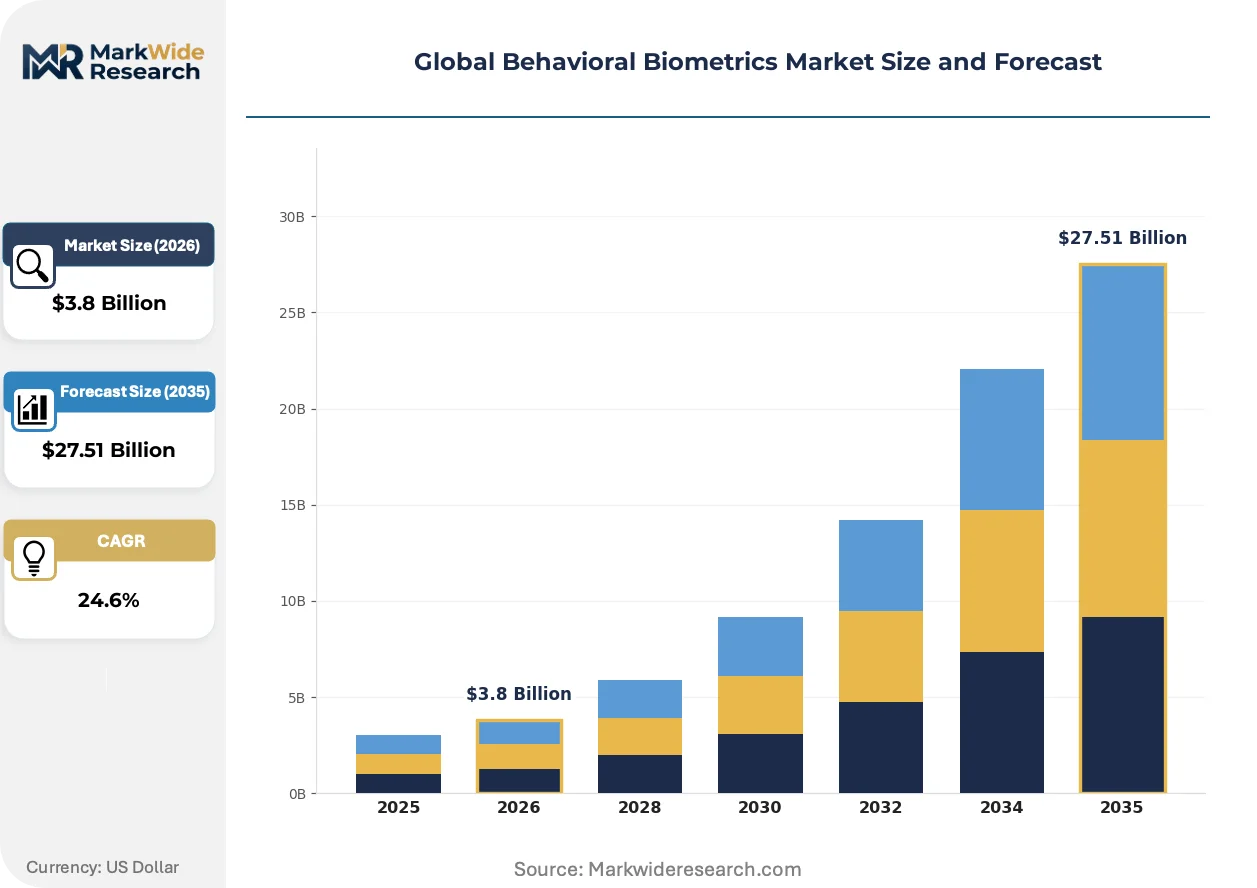
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $27.51 Billion |
| CAGR (2026 – 2036) | 24.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Component: Software, Hardware, Services, Platforms, Middleware Application: Fraud Detection, Identity Verification, Access Management, Risk Management, Transaction Monitoring End User: BFSI, Telecommunications, Government, E-Commerce, Education Deployment: Cloud, On-Premises, Hybrid, Hosted, Managed Services |
| Companies Covered | BioCatch, BehavioSec, FICO, Mastercard, Nuance Communications, SecureAuth Corporation, Plurilock Security, Zighra, SecuredTouch, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Behavioral Biometrics Market Shifts & Advancements
Behavioral biometrics vendors are compressing authentication friction to zero-UI interactions while regulatory pressure forces algorithmic auditability into product roadmaps.
Continuous authentication is collapsing the boundary between login events and session monitoring. Keystroke dynamics and mouse-movement profiling now operate invisibly throughout user sessions rather than at entry points. Financial institutions deploy these architectures to eliminate step-up authentication interruptions while maintaining sub-one-percent false acceptance rates. The technology is collapsing traditional trade-offs between security posture and user experience.
The EU AI Act mandates human oversight protocols and technical documentation for high-risk biometric inference systems. Vendors must maintain algorithmic change logs and impact assessments accessible to supervisory authorities. European banking deployments now require explainability features that expose decision factors behind anomaly flags, accelerating investment in interpretable machine learning architectures.
Enterprise buyers are unbundling authentication from identity proofing workflows. Financial services institutions procure behavioral biometrics as standalone cloud services rather than bundled identity platform modules. This pattern concentrates most acutely in the United States, where FFIEC examination flexibility permits best-of-breed vendor selection over single-stack procurement mandates.
Global Behavioral Biometrics Market Segmentation
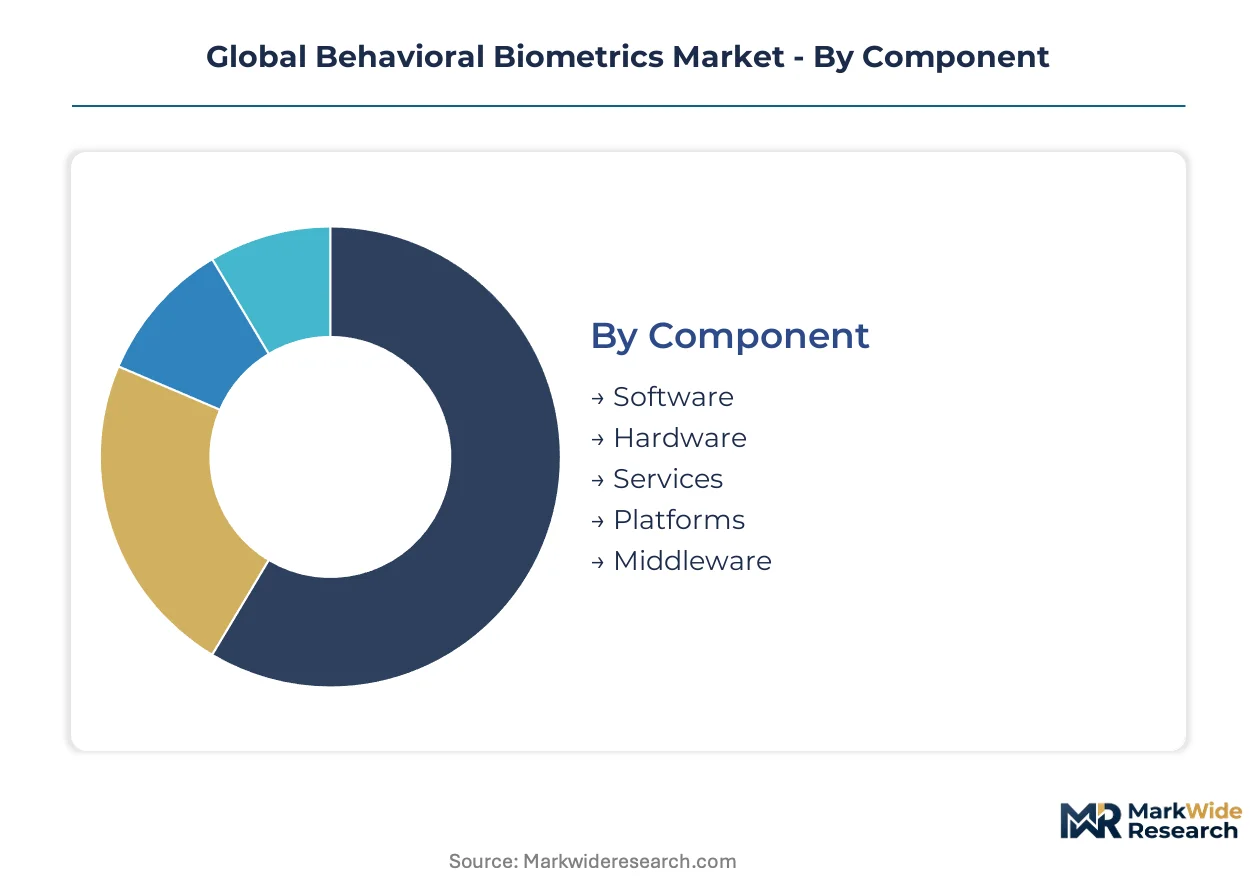
Behavioral biometrics vendors structure offerings across five intersecting dimensions that determine pricing architecture and implementation complexity. Component choices dictate whether buyers procure perpetual licenses or recurring cloud subscriptions. Application focus separates fraud-centric deployments from identity-centric workflows, while end-user verticals impose distinct compliance and latency requirements.
Component:
Mature software licensing models coexist with emerging services revenue streams as deployment patterns shift toward hybrid cloud architectures.
- Software:Algorithm engines processing keystroke dynamics, mouse trajectories, and cognitive interaction patterns in real time. Financial institutions in the United States concentrate procurement here, driven by FFIEC examination flexibility that permits best-of-breed selection over single-stack mandates.
- Services:Implementation consulting, model tuning, and regulatory documentation support for EU AI Act compliance. European banking deployments generate the steepest margin expansion as algorithmic transparency requirements intensify demand for explainable AI expertise.
- Hardware:Specialized sensors for gait analysis and physical behavioral capture at endpoints.
- Platforms:Integrated development environments for continuous authentication orchestration.
- Middleware:API gateways connecting behavioral inference engines to legacy mainframe identity stacks.
Software handles the majority of throughput; Services is the fastest mover on share.
Application:
Volume concentrates in reactive fraud detection while identity verification segments accelerate as remote onboarding hardens against synthetic media injection.
- Fraud Detection:Real-time session hijacking and account takeover flagging using continuous behavioral monitoring. United States financial institutions deploy these architectures most intensively, compressing enterprise cycles from multi-year rollouts to quarterly cloud implementations.
- Identity Verification:Remote onboarding protocols validating legitimate users against deepfake injection attempts. Demand is climbing the fastest in India, where RBI digital payment security guidelines create regulatory tailwind for mobile banking and UPI transaction protection.
- Access Management:Zero-trust perimeter controls replacing static password systems.
- Risk Management:Behavioral scoring for transaction anomaly detection and dynamic friction insertion.
- Transaction Monitoring:Real-time payment flow surveillance for anti-money laundering compliance.
Fraud Detection anchors current revenue composition; Identity Verification is gaining share fastest.
End User:
Customer type determines latency tolerance, regulatory exposure, and integration complexity with existing identity infrastructure.
- BFSI:Tier-one banks and insurance carriers demanding sub-one-percent false acceptance rates with explainable anomaly flags. European deployments face EU AI Act high-risk classification mandates, accelerating vendor investment in interpretable machine learning architectures and human oversight protocols.
- Government:Federal and civilian agencies procuring under NIST SP 800-63B guidelines in the United States. Procurement specifications here directly influence commercial buyer expectations through examination manual alignment.
- Telecommunications:Mobile network operators securing subscriber accounts against SIM-swap fraud.
- E-Commerce:Retail platforms balancing checkout friction reduction with bot detection requirements.
- Education:Universities and testing organizations verifying remote examination integrity.
BFSI commands the dominant share of current deployment value; Government verticals are expanding most quickly on regulatory mandate density.
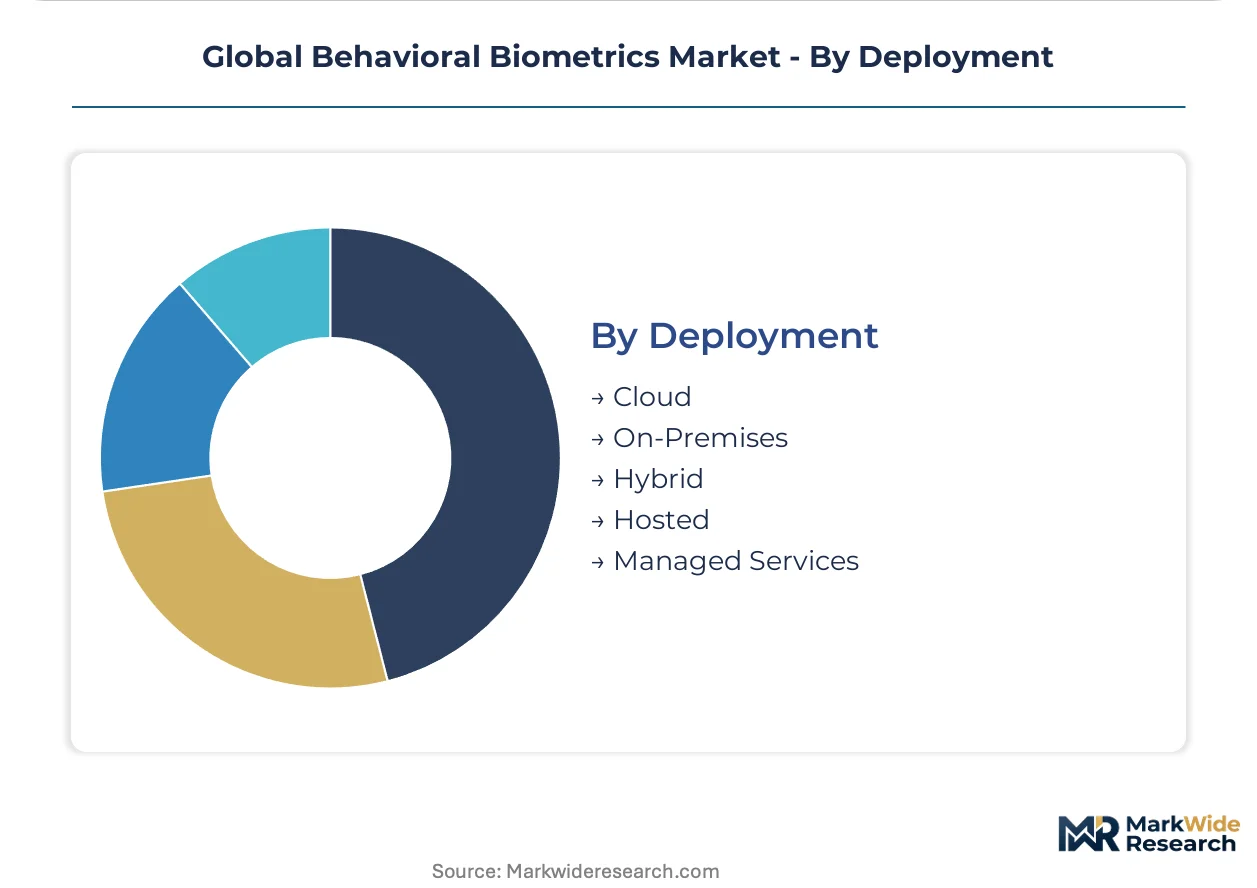
Deployment:
Architecture choices reflect data residency constraints, legacy system entanglement, and operational sovereignty requirements across regulated industries.
- Cloud:Multi-tenant SaaS delivery with elastic compute scaling for seasonal transaction volumes. GDPR data residency requirements in Europe create structural friction for cross-border biometric flows, reshaping vendor interoperability investments and customer data localization strategies.
- Hybrid:Split processing with sensitive inference at edge and model training in centralized cloud. This architecture is climbing fastest as tier-one banks reconcile real-time API orchestration requirements with decades-old mainframe authentication stacks.
- On-Premises:Air-gapped deployments for classified or critical infrastructure environments.
- Hosted:Single-tenant dedicated instances with managed infrastructure outsourcing.
- Managed Services:Fully outsourced biometric operations with SLA-backed performance guarantees.
Cloud carries the heaviest transaction volume; Hybrid is the fastest-expanding architecture as compliance and legacy constraints converge.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in the United States demonstrate the lowest price elasticity, absorbing premium cloud licensing for continuous authentication, while procurement in India and Southeast Asia remains highly sensitive to per-seat costs despite regulatory tailwinds.
United States
Tier-one banks and federal agencies drive concentrated demand for keystroke dynamics and voice biometrics. NIST SP 800-63B guidelines and FFIEC examination manuals shape procurement specifications, creating de facto standards that commercial buyers follow. The Greater Boston and New York financial corridors host dense vendor implementation teams serving BFSI clients.
Germany
Automotive and industrial conglomerates are expanding behavioral authentication for supply chain portal security. The KBA and BSI enforce strict algorithmic documentation requirements that accelerate vendor investment in explainable AI architectures. Frankfurt's fintech cluster anchors continental European deployment expertise for cross-border banking compliance.
India
RBI digital payment security guidelines and UPI transaction volume growth are compressing deployment timelines for mobile banking authentication. The central bank's phased compliance mandates create predictable procurement windows for behavioral bi vendors. Mumbai and Bangalore financial technology corridors concentrate domestic implementation capacity.
United Kingdom
Contact center operators and retail banking networks are layering voice biometrics into customer service stacks. FCA operational resilience requirements and post-Brexit data localization debates reshape vendor cloud architecture decisions. London's insurance and trading technology clusters drive specialized fraud detection procurement.
Japan
Financial institutions and telecommunications operators are deploying gait analysis and cognitive interaction metrics for aging-user accessibility. METI digital identity frameworks and industry-led standards committees slow foreign vendor penetration but validate local partnership strategies. Tokyo-Osaka corridor banks prioritize session hijacking detection for mobile-first customer bases.
Global Behavioral Biometrics Market Competitive Landscape
Capability concentration sits with specialized algorithm vendors holding explainable AI expertise; scale advantage sits with diversified technology platforms with embedded distribution. The market structure reflects a tiered configuration where pure-play behavioral biometrics specialists compete against authentication modules bundled within broader cybersecurity suites. Two strategic archetypes dominate: continuous authentication specialists and voice biometrics integrators. Competitive moves center on strategic partnerships with hyperscale cloud providers and portfolio diversification into adjacent fraud prevention categories.
Within the continuous authentication tier, BioCatch and BehavioSec exemplify capability-focused positioning, while Nuance Communications occupies a position at the voice-centric vector. These three anchors represent divergent geographic and technical specializations: BioCatch exemplifies financial services-centric deployment patterns, BehavioSec anchors European regulatory compliance architectures, and Nuance Communications sits within enterprise contact center integration workflows. Their collective positioning illustrates how vendor concentration follows regulatory geography and end-use vertical rather than pure technology differentiation.
| Leading Market Players |
|---|
| BioCatch |
| BehavioSec |
| FICO |
| Mastercard |
| Nuance Communications |
| SecureAuth Corporation |
| Plurilock Security |
| Zighra |
| SecuredTouch |
| Others |
Supply & Pricing Matrix
Greater Boston's dense concentration of algorithm engineering talent and venture capital flows directly shapes vendor pricing power across the behavioral biometrics landscape. Tier-one banks in New York and federal agencies in Washington absorb premium SaaS licensing rates because proximity to implementation teams compresses deployment risk and accelerates time-to-value realization.
Pricing Analysis
Implementation services and ongoing model tuning contracts drive lifetime value capture beyond initial software licensing. Three-tier pricing structure across premium, standard, and economy levels separates tier-one banks demanding sub-one-percent false acceptance rates from mid-market institutions accepting higher latency trade-offs. Cost compression in the standard tier is intensifying because cloud infrastructure concentration limits vendor differentiation on raw compute costs. Government verticals demonstrate the lowest price elasticity, while Indian mobile banking deployments remain highly sensitive to per-seat costs despite RBI regulatory tailwinds.
Supply Chain Analysis
Contract manufacturing for specialized biometric sensors concentrates with Foxconn, Pegatron, and select EMS providers in Taiwan and mainland China. Algorithm development draws from hyperscale cloud infrastructure anchored in the United States, Ireland, and Singapore. Supply chain risk centers on single-source vulnerability for GPU clusters used in real-time behavioral inference training. Distribution runs through direct enterprise sales teams serving BFSI verticals, supplemented by channel partners for mid-market penetration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The behavioral biometrics market sits in a cyclical recovery phase as financial institutions refresh post-pandemic authentication infrastructure and regulatory mandates harden compliance spending. Enterprise security budget normalization following interest rate stabilization provides the cyclical driver justifying medium-term investment positioning.
For Market Incumbents: Insulate core banking relationships by embedding explainable AI documentation capabilities that satisfy EU AI Act supervisory scrutiny before competitors achieve compliance parity. Deepen vertical integration into edge inference hardware to reduce hyperscale cloud dependency and capture margin from gait analysis sensor deployments. The threat of bundled cybersecurity suite vendors integrating behavioral modules demands preemptive API standardization investments that lock in switching costs.
For New Entrants and Emerging Players: Pursue white-space opportunity in Japanese telecommunications and automotive supply chain portal security, where METI frameworks slow foreign penetration but validate local partnership strategies. Target India's UPI transaction authentication segment, where RBI phased compliance creates predictable procurement windows without incumbent saturation. Lead with voice biometrics-NLP convergence offerings that exploit contact center stack refresh cycles in the United Kingdom and Germany.
For Investors and Strategic Acquirers: Long-term, this sits as a regulatory capture play because divergent transatlantic compliance architectures create durable moats for vendors with documented algorithmic transparency and human oversight protocols. Acquisition targets should display concentrated expertise in interpretable machine learning architectures serving European banking deployments. Monitor FFIEC examination manual updates as the signal indicating when United States procurement flexibility might tighten toward single-stack mandates, compressing specialist vendor margins.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Continuous authentication APIs embedded into legacy mainframe stacks satisfy tier-one bank orchestration requirements. |
| Strategic Partnership | Hyperscaler alliances with AWS, Azure, or GCP accelerate hybrid deployment architectures for GDPR data residency compliance. |
| Acquisition of Specialist Firm | Explainable AI boutiques with EU AI Act documentation expertise fill capability gaps in vendor compliance roadmaps. |
| Geographic Expansion | Mumbai and Bangalore implementation teams capture RBI-mandated mobile banking authentication procurement in India. |
| Product Launch | Zero-UI behavioral inference products eliminate authentication friction while maintaining NIST SP 800-63B compliance standards. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of SEC filings, FFIEC examination manuals, EU AI Act technical documentation, and hyperscaler capex disclosures. Chief information security officers, fraud prevention executives at tier-one banks, regulatory affairs leads specializing in biometric data governance, and channel partners serving mid-market financial institutions provided structured input. Bottom-up deployment estimates triangulated against top-down security software spending analysis derived from procurement database aggregation.
Forecast inputs span component type, application focus, end-user vertical, and deployment architecture across the projection horizon. Segment-level CAGRs emerged from elasticity modeling against security budget growth trajectories and regulatory mandate timing. Voice biometrics adoption curves in contact centers, keystroke dynamics penetration in mobile banking, and gait analysis endpoint security deployment rates served as industry-specific demand drivers.
Macroeconomic conditions sit as an overlay; deviation in enterprise IT spending cycles or central bank digital payment security mandate pacing would shift the trajectory. Forecasts reflect assumptions about sustained FFIEC examination flexibility and EU AI Act enforcement intensity. Quarterly review of vendor algorithmic transparency documentation submissions and NIST guideline revision announcements is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biometrics & Identity Management
GCC Biometrics Market
Biometrics & Identity Management
Europe Biometrics Market
Biometrics & Identity Management
Global Biometric Identification Market
Biometrics & Identity Management
Global Mobile User Authentication Market
Biometrics & Identity Management
Latin America Government & Security Biometrics Market
Biometrics & Identity Management
Healthcare Biometrics Market
Biometrics & Identity Management
Global Authentication Services Market
Biometrics & Identity Management
Next Generation Biometric Market
Biometrics & Identity Management
Fingerprint Biometrics Market
Biometrics & Identity Management
Mobile Biometric Security and Services Market
Biometrics & Identity Management
Asia-Pacific Government and Security Biometrics Market
Biometrics & Identity Management
Authentication Solution Market
Biometrics & Identity Management
Passive Authentication Market
Biometrics & Identity Management
Military Biometrics Market
Biometrics & Identity Management
Global Human Identification Market
Biometrics & Identity Management
AI-Enabled Biometrics Market