
 Biometric Services Platform (Biosp) Market | 2026-2036
Biometric Services Platform (Biosp) Market Size, Share, and Industry Trends Forecast 2026-2036
Biometric Services Platform (Biosp) Market Analytics
India is rewriting the competitive map for biometric service platforms through its national identity infrastructure expansion. IDEMIA leverages its government contracting strength across multiple continents to sustain large-scale deployment pipelines. NEC Corporation anchors its position through deep specialization in multimodal biometric fusion algorithms for high-security environments.
A Biometric Services Platform (Biosp) is a cloud-delivered middleware layer that ingests biometric samples—fingerprint minutiae, iris texture patterns, facial geometry vectors—and returns identity assertions against enrolled templates, typically operating at false acceptance rates below 0.001% for financial-grade deployments. The platform's primary commercial purpose is to eliminate credential-based authentication friction while binding digital transactions to physical identity with non-repudiation guarantees. Face recognition services currently dominate transaction volumes among service types, though iris scanning commands premium pricing in healthcare and defense segments where liveness detection requirements are most stringent. Machine learning and computer vision technologies are absorbing the majority of R&D allocation, while blockchain-based identity anchoring remains nascent but structurally important for decentralized credential ecosystems.
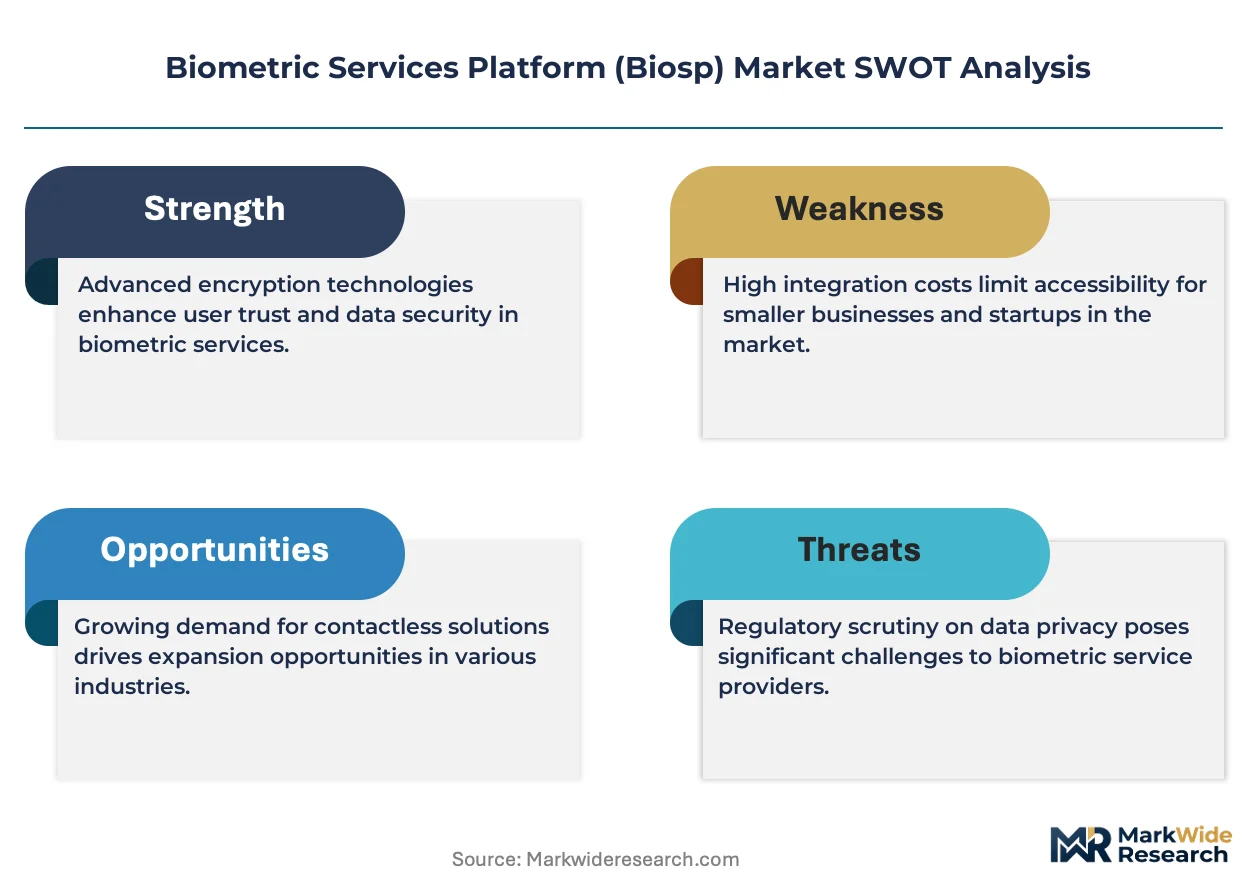
The EU AI Act, India's UIDAI framework, and the US NIST biometric standards collectively shape product roadmaps by mandating algorithmic auditability, demographic parity testing, and template encryption protocols. Regulatory fragmentation between jurisdictions forces platform vendors to maintain multiple certification tracks, elevating compliance costs for entrants while deepening incumbent moats. Stakeholders must monitor evolving liveness detection mandates, as presentation attack resistance is becoming the primary gating criterion for government procurement eligibility.
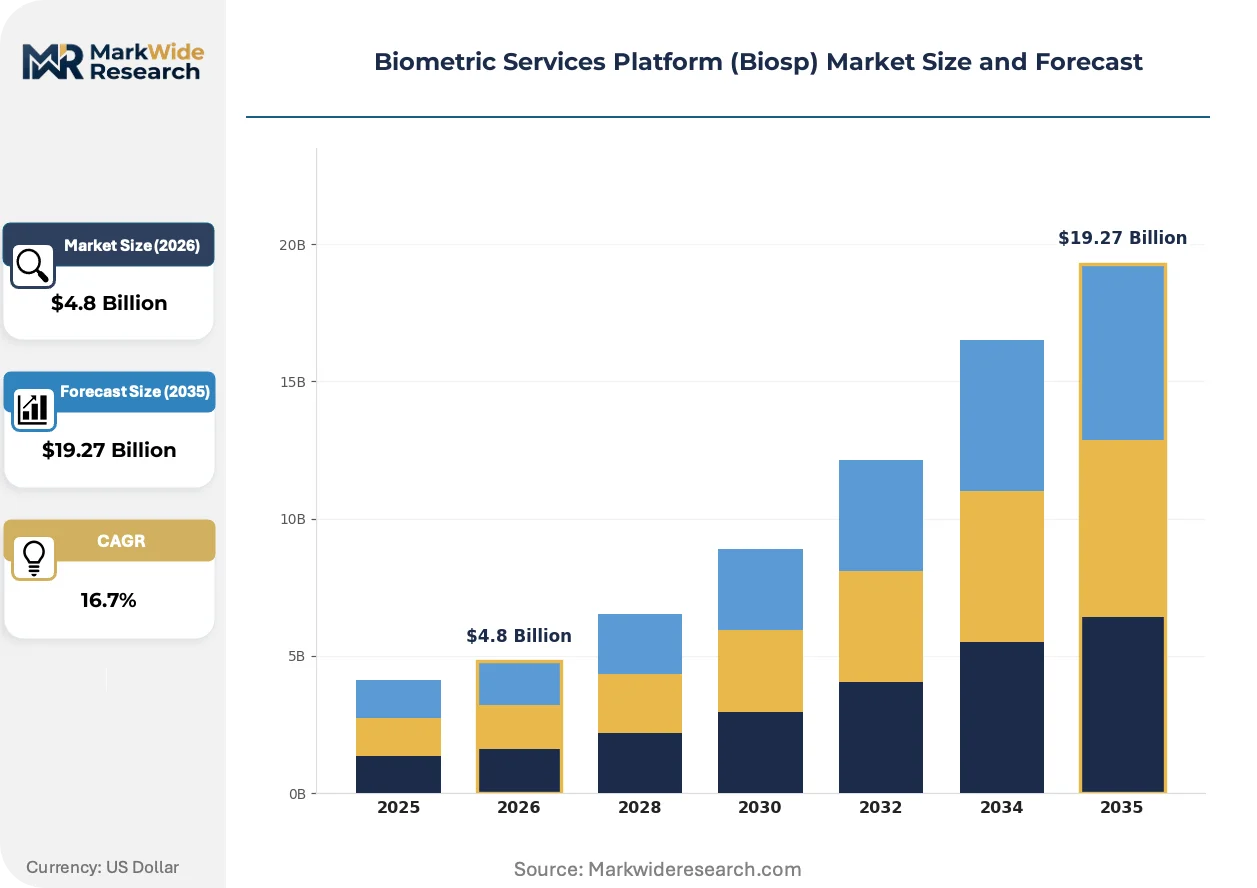
Market Dynamics
The EU AI Act's algorithmic transparency mandates are compressing vendor certification timelines while India's UIDAI framework accelerates large-scale biometric infrastructure rollouts across healthcare and financial networks.
Growth Catalysts
- Aadhaar-linked infrastructure expansion:India's UIDAI framework is extending biometric authentication into rural healthcare clinics and microfinance institutions, creating sustained procurement pipelines for platform vendors.
- Presentation attack resistance standards:ISO/IEC 30107-3 liveness detection certification is becoming a mandatory gating criterion for government biometric tenders across multiple jurisdictions.
- Multimodal fusion adoption:Banking institutions are deploying fingerprint-plus-facial-recognition systems to satisfy non-repudiation requirements for high-value digital transactions.
Market Restraints
- Template encryption hardware costs:FIPS 140-2 Level 3 certified secure elements for biometric template protection impose capital intensity on platform deployments.
- Algorithm training data concentration:High-quality demographic-parity-tested training datasets remain concentrated among incumbent vendors with decade-long government contracting relationships.
- Biometric spoofing sophistication:Deepfake-generated synthetic fingerprints and 3D-printed face masks are forcing continuous R&D expenditure on countermeasure development.
Strategic Opportunities
- Blockchain-anchored decentralized identity:Self-sovereign identity frameworks are creating demand for biometric oracle services that bind physical credentials to distributed ledger records.
- EU AI Act compliance services:Mandatory algorithmic auditability requirements are opening adjacent revenue streams for bias-testing and documentation automation tools.
- Edge biometric processing:On-device inference chips are enabling privacy-preserving authentication for telemedicine and remote banking applications without cloud data transmission.
Industry Challenges
- Cross-jurisdictional certification fragmentation:Platform vendors must maintain parallel compliance tracks for NIST SP 800-76-2, ISO/IEC 19795, and India's UIDAI specifications simultaneously.
- Multimodal system integration complexity:Fingerprint, iris, and facial recognition sensor fusion demands specialized systems engineering talent that remains scarce in commercial markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Biometric Services Platform (Biosp) Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $19.27 Billion |
| CAGR (2026 – 2036) | 16.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Face Recognition, Fingerprint Authentication, Iris Scanning, Voice Recognition Technology: Machine Learning, Computer Vision, Natural Language Processing, Blockchain End User: Government, Healthcare, Banking, Retail Application: Access Control, Identity Verification, Fraud Prevention, Time Tracking |
| Companies Covered | Aware, IDEMIA, Sensory, Nok Nok Labs, Invixium, Fischer International Identity, NEC Corporation, Thales, HID Global, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Biometric Services Platform (Biosp) Market Evolving Landscape
Biometric service platforms are undergoing architectural transformation as edge computing, regulatory auditability mandates, and decentralized identity frameworks simultaneously reshape technical roadmaps and commercial models.
Edge-based biometric inference is virtualizing traditional cloud-dependent authentication architectures. Smartphone manufacturers are integrating dedicated neural processing units capable of on-device template matching at sub-100-millisecond latency. This distributed processing model is compressing data sovereignty compliance costs while enabling offline authentication for air-gapped defense and critical infrastructure environments.
The EU AI Act's risk-based classification system is redefining product development priorities for biometric vendors. High-risk biometric systems deployed in public spaces now require conformity assessments including fundamental rights impact evaluations. European municipalities are responding by demanding algorithmic explainability dashboards and demographic parity documentation as standard procurement deliverables.
Healthcare networks are consolidating vendor relationships around integrated biometric identity platforms. Hospital systems previously purchasing standalone fingerprint readers for patient identification are now procuring enterprise-wide platforms spanning registration, pharmacy dispensing, and electronic health record access. This concentration is most pronounced in India's Ayushman Bharat network, where state-level health authorities are standardizing on Aadhaar-integrated platforms for beneficiary verification.
Biometric Services Platform (Biosp) Market Segmentation
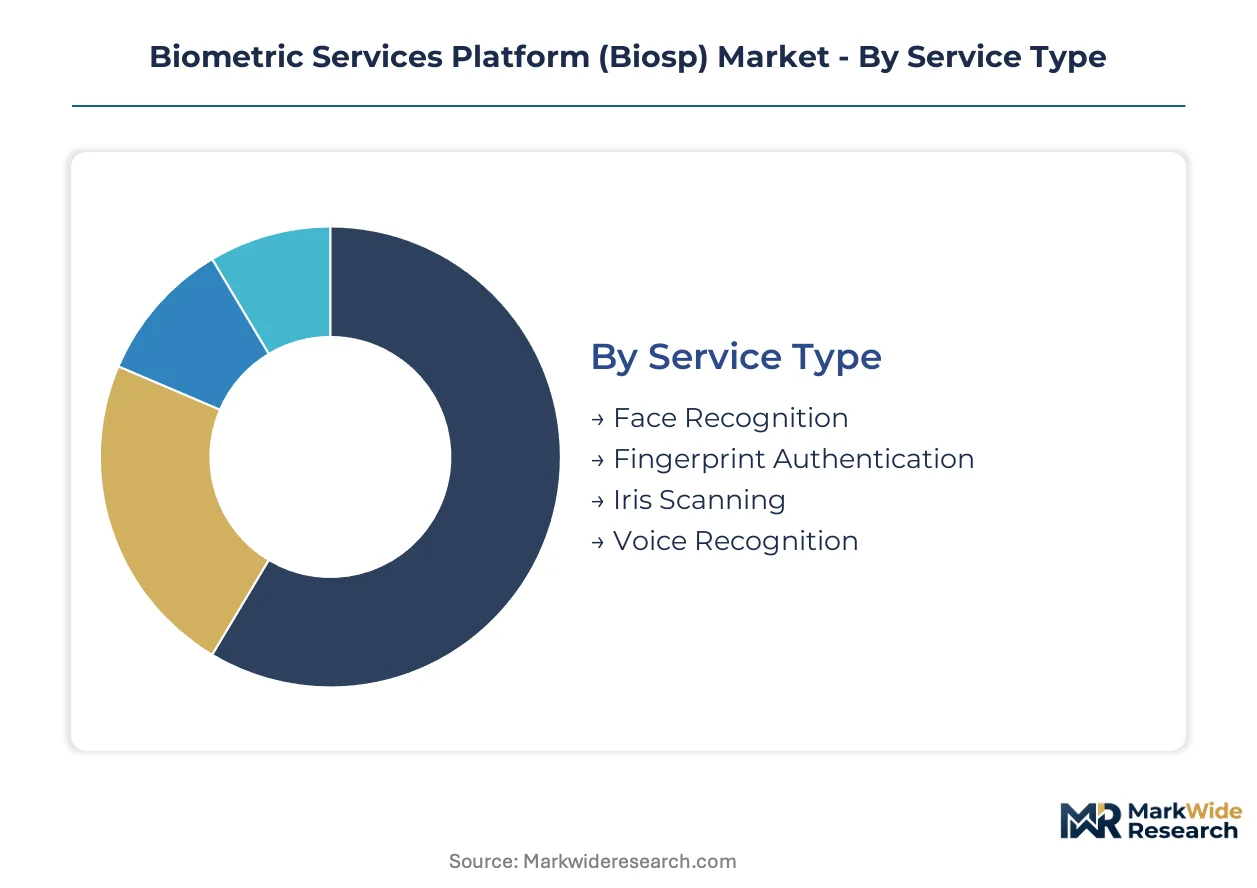
Biometric service platforms fragment across authentication modalities, underlying AI technologies, and sector-specific compliance requirements. Understanding these dimensions reveals where procurement budgets concentrate and where technical differentiation commands premium positioning.
Service Type:
Use-case spectrum spans high-volume consumer authentication to specialized high-security enrollment, with each modality carrying distinct hardware dependencies and liveness detection standards.
- Face Recognition:Cloud-based facial geometry matching dominates transaction volumes across mobile banking and airport e-gates. India's Aadhaar-linked verification networks and EU border control procurements are absorbing the majority of platform deployments, driven by contactless hygiene requirements post-pandemic.
- Fingerprint Authentication:Minutiae-based matching remains the cost benchmark for financial-grade non-repudiation, with capacitive and ultrasonic sensor fusion advancing spoof resistance. UIDAI's rural healthcare expansion and microfinance KYC mandates are sustaining hardware procurement pipelines across South Asian markets.
- Iris Scanning:Texture-pattern recognition commands premium pricing in defense and pharmaceutical dispensing where ISO/IEC 30107-3 Level 3 liveness certification is mandatory.
- Voice Recognition:Speaker verification systems are penetrating call center authentication and voice-command IoT devices, constrained by acoustic environment variability and deepfake synthesis threats.
Established volume favors face recognition; emerging adoption favors iris scanning.
Technology:
Cost tier stratification separates mature inference stacks from experimental trust architectures still seeking product-market fit.
- Machine Learning:Deep neural networks for biometric feature extraction absorb the majority of vendor R&D allocation, with transformer architectures displacing CNNs for facial analysis. NIST FRVT and MINEX III benchmarks dictate competitive survival, forcing continuous retraining on demographically balanced datasets.
- Computer Vision:Edge-optimized inference pipelines enable on-device template matching without cloud transmission, compressing GDPR and UIDAI compliance costs for telemedicine and rural banking applications.
- Natural Language Processing:Voice biometric systems leverage speaker diarization and anti-spoofing models, though deployment remains narrower than vision-based modalities.
- Blockchain:Decentralized identity anchoring remains nascent, with biometric oracle services binding physical credentials to distributed ledger records in pilot self-sovereign identity frameworks.
Commercial maturity concentrates in machine learning; architectural innovation favors blockchain.
End User:
Customer type determines procurement velocity, with government tenders demanding multi-year certification cycles and private sectors prioritizing integration speed.
- Government:National ID programs and border management systems require FIPS 140-2 Level 3 template encryption and ISO/IEC 19795 compliance, creating decade-long vendor relationships that resist disruption.
- Healthcare:Patient identification platforms are consolidating around Aadhaar-integrated systems in India's Ayushman Bharat network, with pharmacy dispensing and EHR access driving enterprise-wide procurement.
- Banking:Financial institutions deploy multimodal fusion for high-value transaction non-repudiation, with RBI and SEBI guidelines shaping authentication architecture requirements.
- Retail:Frictionless checkout and loyalty program verification are absorbing contactless face recognition, though privacy litigation in European and US jurisdictions constrains deployment scale.
Procurement scale favors government; integration flexibility favors retail.
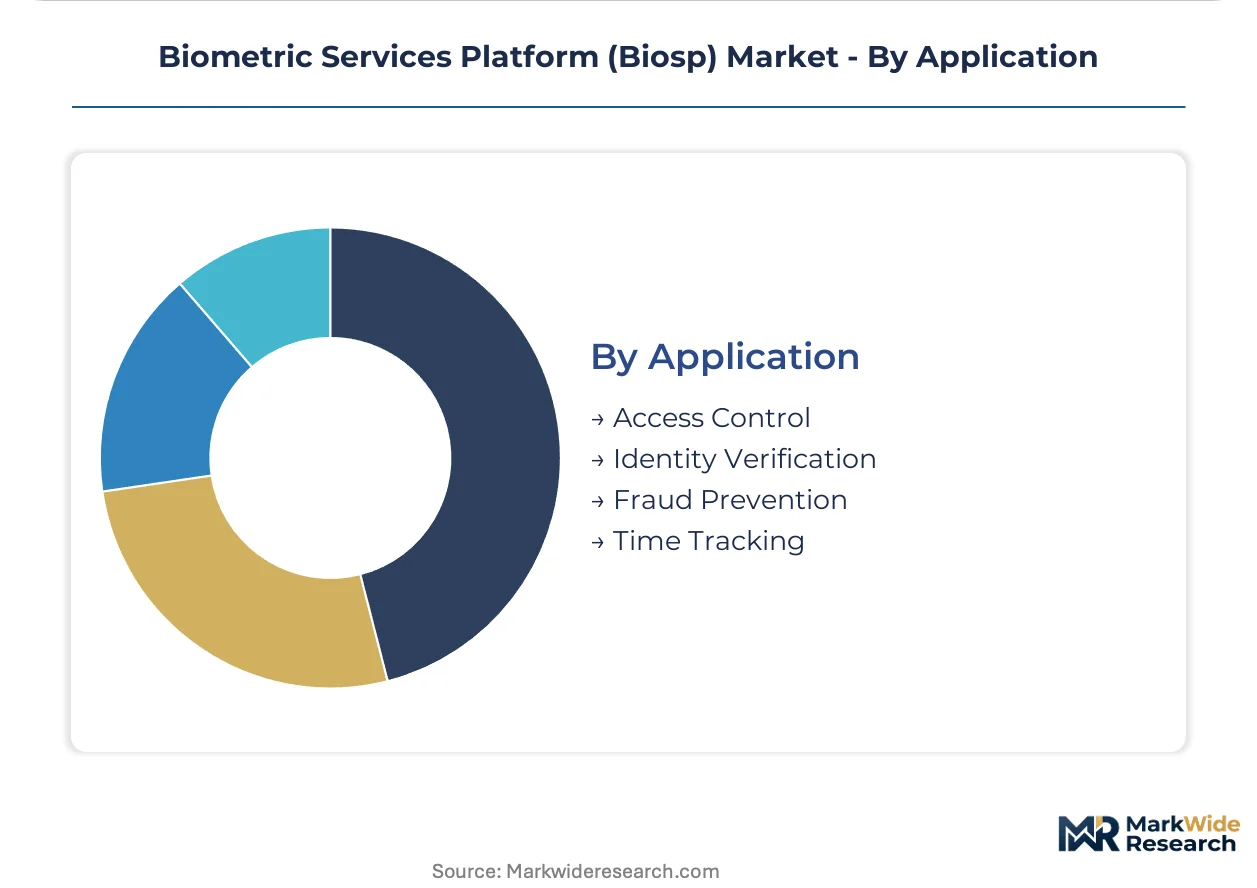
Application:
Margin structure varies by workflow depth, with point solutions compressing pricing and enterprise platforms sustaining service revenue.
- Access Control:Physical and logical entry systems integrate multimodal biometric fusion for critical infrastructure, with defense and data center operators demanding air-gapped edge processing.
- Identity Verification:Remote onboarding for banking and telecommunications represents the fastest-expanding transaction category, driven by regulatory KYC mandates and digital-first customer acquisition strategies.
- Fraud Prevention:Presentation attack detection and synthetic identity countermeasures are absorbing continuous R&D expenditure as deepfake sophistication escalates.
- Time Tracking:Workforce management deployments in manufacturing and healthcare facilities prioritize cost efficiency over security grade, constraining vendor pricing power.
Security premium favors access control; volume scaling favors identity verification.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Vendor concentration clusters around government contracting relationships in India, the United States, and Germany, where national identity infrastructure programs sustain procurement pipelines. Platform providers prioritize certification tracks in jurisdictions with the most stringent algorithmic auditability mandates.
India
UIDAI's Aadhaar-linked authentication networks are extending into rural healthcare clinics and microfinance institutions, creating sustained demand for multimodal biometric platforms. RBI and SEBI guidelines mandate biometric KYC for digital banking onboarding, compressing vendor selection timelines. Karnataka's Bengaluru technology corridor hosts multiple platform engineering centers serving both domestic deployment and export markets.
United States
NIST SP 800-76-2 compliance requirements shape federal procurement for border management and defense applications, with FIPS 140-2 Level 3 encryption standards gating vendor eligibility. DHS biometric exit programs at international airports sustain large-scale facial recognition deployment contracts. California's Silicon Valley and Washington DC metro area concentrate platform R&D and government sales operations respectively.
Germany
The EU AI Act's fundamental rights impact assessment requirements are reshaping municipal procurement for public space biometric systems, elevating algorithmic transparency documentation to mandatory status. BSI technical guidelines for critical infrastructure access control create adjacent compliance service demand. Bavaria's Munich security technology cluster and Berlin's public sector innovation labs represent contrasting deployment environments.
China
MIIT standards for biometric data security and GB/T facial recognition specifications structure domestic platform certification requirements, with SAMR oversight extending to cross-border data transfer restrictions. Smart city initiatives in Yangtze River Delta municipalities are absorbing large-scale multimodal authentication infrastructure. Shenzhen's hardware manufacturing ecosystem supplies sensor components upstream of platform integration layers.
United Arab Emirates
MOHAP healthcare digitization mandates and federal border management modernization programs are driving multimodal biometric procurement for patient identification and airport e-gates. Data localization requirements under UAE cybersecurity regulations influence platform architecture decisions. Dubai's smart city authority and Abu Dhabi's government services digitization programs represent distinct procurement channels with diverging technical specifications.
Biometric Services Platform (Biosp) Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in sensor hardware and algorithm licensing. The vendor structure stratifies across three layers: full-stack platform providers with decade-long government relationships, modular authentication component suppliers, and emerging edge-AI chip vendors enabling on-device inference. Strategic positioning concentrates on multimodal fusion capabilities and cross-jurisdictional certification maintenance. Competitive dynamics favor M&A activity targeting specialized liveness detection startups and strategic partnerships between platform vendors and semiconductor manufacturers.
Within the government-contracting archetype, IDEMIA and NEC Corporation occupy positions defined by sustained large-scale deployment relationships across multiple continents. Thales represents the aerospace-defense crossover segment where air-gapped edge processing requirements intersect with biometric identity verification. These three anchors illustrate how certification depth and geographic diversification separate sustainable platform providers from module-dependent competitors.
| Leading Market Players |
|---|
| Aware |
| IDEMIA |
| Sensory |
| Nok Nok Labs |
| Invixium |
| Fischer International Identity |
| NEC Corporation |
| Thales |
| HID Global |
| Others |
Value Network & Pricing Analysis
The Shanghai-Rotterdam maritime corridor's container rate volatility compresses margins for biometric hardware importers while amplifying pricing power among domestic sensor fabricators in India and China. This logistics cost asymmetry stratifies platform vendors into certification-premium tiers versus commodity hardware assemblers.
Pricing Analysis
The EU AI Act dictates the pricing tier structure across biometric service platforms, mandating fundamental rights impact assessments and algorithmic auditability documentation that separate premium-certified vendors from standard-tier competitors. Pricing stratifies across FIPS 140-2 Level 3 encrypted deployments, ISO/IEC 30107-3 liveness-certified systems, and uncertified economy alternatives. Cost compression in the economy tier is intensifying because Shenzhen-based sensor manufacturers are flooding South Asian markets with unlicensed fingerprint modules. Government procurement offices exhibit the lowest price sensitivity, while rural healthcare clinics in India's Ayushman Bharat network operate under severe budget constraints.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk planning for biometric platform vendors, forcing diversification into Vietnam and Mexico for final assembly operations. Component sourcing draws from Taiwan for neural processing units, South Korea for capacitive fingerprint sensors, and Japan for iris imaging optics. Single-source vulnerability concentrates in EUV lithography-dependent AI accelerators. Distribution runs through systems integrators with decade-long UIDAI and NIST certification relationships rather than direct OEM channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The biometric services platform market represents a high-growth disruption as edge-AI inference chips and EU AI Act compliance mandates simultaneously reshape procurement criteria and technical roadmaps.
For Market Incumbents: Entrench multimodal fusion capabilities through captive R&D investment in presentation attack resistance algorithms, insulating against specialized liveness-detection startups. Deepen UIDAI and NIST certification moats by pre-positioning compliance documentation for anticipated EU AI Act amendments. Control channel access through exclusive partnerships with systems integrators serving India's rural healthcare expansion. For New Entrants and Emerging Players: Southeast Asia's underpenetrated microfinance KYC infrastructure offers white-space entry with lower certification barriers than Indian or EU markets. Target voice biometric authentication for call-center automation, where acoustic-model specialization circumvents incumbent computer-vision dominance. Pursue partnership-first go-to-market positioning with telecom operators seeking rapid digital onboarding solutions. For Investors and Strategic Acquirers: Edge-AI chip vendors with biometric-optimized neural architectures represent the priority acquisition archetype for platform consolidation plays. Long-term viability hinges on regulatory certification durability rather than algorithmic performance benchmarks alone. Monitor ISO/IEC 30107-3 certification backlog queues as the inflection signal for vendor capacity constraints.| Strategic Initiative | Industry Significance |
|---|---|
| ISO/IEC 30107-3 Certification Investment | Presentation attack resistance certification gates government procurement eligibility across EU and Indian tenders. |
| Edge-AI Chip Partnership | On-device inference capability compresses GDPR and UIDAI compliance costs for telemedicine deployments. |
| Blockchain Identity Oracle Development | Self-sovereign identity pilots create demand for biometric credential anchoring to distributed ledgers. |
| Multimodal Fusion R&D Expansion | Fingerprint-plus-facial systems satisfy RBI non-repudiation mandates for high-value digital transactions. |
| EU AI Act Compliance Service Launch | Mandatory algorithmic auditability opens adjacent revenue streams for bias-testing automation tools. |
Research Methodology
Initial hypotheses were tested against primary input from biometric platform engineering directors, government procurement officers at UIDAI and DHS, healthcare IT integration specialists, and financial services KYC compliance leads, then refined against secondary validation from NIST FRVT benchmark disclosures, EU AI Act implementation guidance documents, SEC filings of publicly traded identity technology vendors, UIDAI authentication transaction reports, and ISO/IEC standards committee working drafts. Bottom-up deployment volume estimates across authentication modalities were triangulated with top-down market sizing from vendor revenue aggregation.
Demand-supply balance modeling across the analysis window incorporated service type segmentation by modality, technology tier by AI architecture maturity, end-user procurement velocity by sector, and application workflow depth by integration complexity. CAGRs were derived from fitted growth curves calibrated to observed UIDAI authentication volume trajectories and EU border control procurement cycles. NIST MINEX III and FRVT benchmark progression rates informed technology adoption curve assumptions.
The forecast holds incumbent behavior within observed patterns; aggressive moves by sovereign AI chip manufacturers or sudden EU AI Act enforcement escalation would shift outcomes beyond modeled ranges. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biometrics & Identity Management
Healthcare Biometrics Market
Biometrics & Identity Management
Global Authentication Services Market
Biometrics & Identity Management
Biometric Point-Of-Sale Terminals Market
Biometrics & Identity Management
FIDO Authentication Market
Biometrics & Identity Management
Middle East and Africa Biometrics in Government Market
Biometrics & Identity Management
Europe Biometrics Market
Biometrics & Identity Management
Palm Vein Biometrics Market
Biometrics & Identity Management
Biometrics As a Service in Healthcare Market
Biometrics & Identity Management
Mobile Biometrics Market
Biometrics & Identity Management
ID Verification Market
Biometrics & Identity Management
Biometrics Banking Market
Biometrics & Identity Management
Hand Geometry Biometrics Market
Biometrics & Identity Management
Mobile Devices User Authentication Services Market
Biometrics & Identity Management
Europe Decentralized Identity Market
Biometrics & Identity Management
Global Biometrics Middleware Market
Biometrics & Identity Management
AI-Enabled Biometrics Market