
 Global Multifactor Authentication Market | 2026-2036
Global Multifactor Authentication Market Size, Share, and Industry Trends Forecast 2026-2036
Global Multifactor Authentication Market Outlook
Enterprise software distribution is fragmenting as cloud marketplaces, direct API sales, and managed security service providers compete for authentication procurement budgets. Microsoft Corporation leverages its Entra identity platform to anchor enterprise subscriptions within broader Azure ecosystems. Thales Group competes through specialized hardware security module integration with government-grade token deployments. Okta Inc. differentiates via cloud-native workforce identity orchestration that spans hybrid IT environments.
Multifactor authentication denotes a security mechanism requiring two or more independent verification factors—typically combining knowledge (passwords), possession (tokens or devices), and inherence (biometric templates)—to validate user identity before system access. The technology employs cryptographic protocols, time-synchronized algorithms, or biometric pattern matching to establish trust chains resistant to single-point credential compromise. Biometrics commands premium positioning as facial recognition and fingerprint modalities displace SMS OTP in regulated industries where phishing resistance determines procurement standards. Cloud-based deployment models sustain the fastest expansion trajectory as organizations retire on-premises identity infrastructure. Hardware tokens retain entrenched positions in defense, critical infrastructure, and air-gapped operational technology networks where physical possession proofs remain mandatory.
The US NIST Cybersecurity Framework, the EU AI Act's biometric governance provisions, and India's CERT-In directives collectively shape product certification requirements and cross-border data handling standards for authentication vendors. GDPR and state-level US privacy statutes further constrain how behavioral and biometric factors may be collected, stored, and processed across jurisdictional boundaries. Stakeholders must monitor evolving algorithmic accountability rules and quantum-resistant cryptographic transitions that will determine next-generation protocol investments and compliance architectures.

Market Dynamics
Zero-trust security mandates from US federal agencies and EU financial regulators are forcing wholesale replacement of password-only authentication across enterprise IT estates, compressing deployment timelines from years to quarters.
Growth Catalysts
- US NIST Cybersecurity Framework:Federal contractors must implement phishing-resistant authenticators by 2025, accelerating FIDO2 hardware token procurement across defense industrial base suppliers.
- Biometric template matching:Liveness detection algorithms now defeat presentation attacks, enabling facial recognition deployment in Indian banking apps where RBI mandates MFA for all digital transactions.
- Air-gapped operational technology:Critical infrastructure operators in Germany and Japan deploy hardware tokens where network isolation prevents cloud-based alternatives.
Market Restraints
- Semiconductor supply concentration:Secure element chip fabrication concentrates in Taiwan and South Korea, exposing token manufacturers to geopolitical disruption risk.
- GDPR biometric data classification:Special category status triggers Article 9 processing restrictions, adding legal review costs to European facial recognition deployments.
- SMS OTP persistence:Low-cost messaging infrastructure retains foothold in price-sensitive emerging markets despite known SIM-swap vulnerabilities.
Strategic Opportunities
- Brazilian financial inclusion:Unbanked population accessing digital payments via smartphone biometrics creates first-mover advantage for selfie-authentication vendors.
- Post-quantum cryptography transition:NIST standardization of lattice-based algorithms opens replacement cycle for RSA-dependent hardware tokens in government agencies.
- API-first distribution:Embedded authentication via developer marketplaces bypasses traditional enterprise sales cycles, reaching mid-market SaaS providers directly.
Industry Challenges
- Legacy mainframe integration:Financial institutions running COBOL-based core systems face custom middleware costs to bridge modern FIDO protocols.
- Biometric algorithm auditing:EU AI Act conformity assessments require third-party validation of demographic performance parity, extending product launch timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Multifactor Authentication Market |
| Market Size in 2026 | $23.7 Billion |
| Market Size in 2035 | $92.97 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hardware Tokens, Software Tokens, Biometrics, SMS OTP User Type: Individual Users, Enterprises, Government, Educational Institutions Deployment Model: Cloud-based, On-premises, Hybrid, Managed Service Industry Vertical: BFSI, Healthcare, Retail, IT & Telecom |
| Companies Covered | Microsoft Corporation, Thales Group, Okta Inc., RSA Security LLC, Cisco Systems Inc., HID Global Corporation, Oracle Corporation, Yubico, CyberArk Software Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Multifactor Authentication Market Strategic Shifts
Authentication modalities are fragmenting across hardware, software, and biometric vectors as buyers prioritize phishing resistance over deployment convenience. Vendors race to embed invisible security into user workflows.
Passwordless FIDO2 credentials are migrating from browser-based implementations to platform authenticators built into smartphones and laptops. Large enterprises in US healthcare and German manufacturing now mandate resident key storage on employee devices. This shift is compressing demand for standalone hardware tokens in conventional office environments while preserving their role in high-assurance settings.
EU AI Act biometric governance provisions classify remote identity verification as high-risk, triggering mandatory conformity assessments and human oversight requirements. European digital identity wallet deployments must demonstrate algorithmic fairness across demographic groups. Financial services firms in France and the Netherlands now budget for third-party auditing of facial recognition systems before procurement approval.
Managed detection and response providers bundle authentication telemetry with threat hunting services, unbundling identity from standalone product sales. US mid-market enterprises now purchase workforce identity as a utility through channel partners rather than direct vendor relationships. This pattern is most visible in healthcare and professional services verticals where IT staff scarcity drives outsourcing preference.
Global Multifactor Authentication Market Segmentation
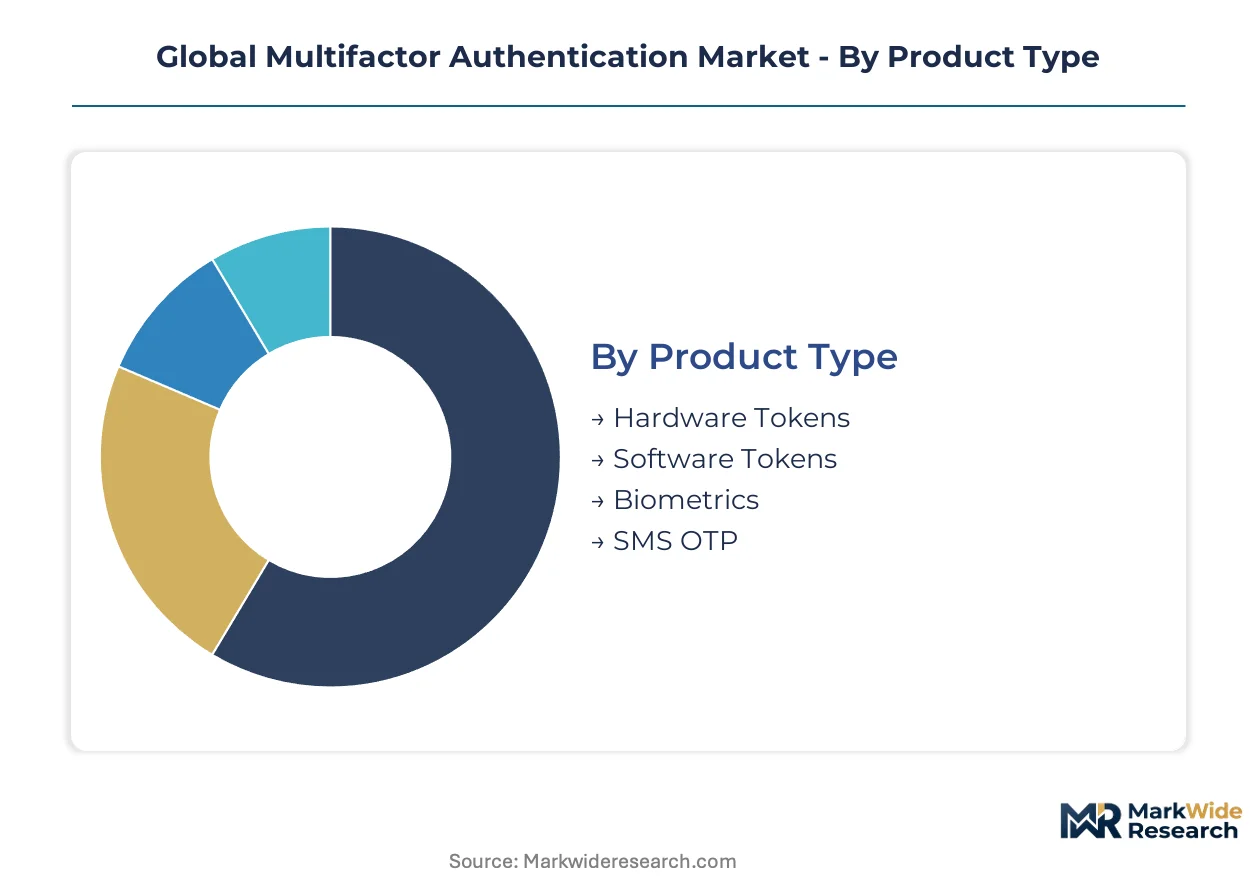
Authentication procurement cycles vary dramatically across product architectures, with hardware tokens requiring multi-year capital planning while cloud-native alternatives compress deployment to quarterly sprints. Understanding these velocity differentials enables vendors to align R&D pipelines with buyer budget calendars and compliance deadlines.
Product Type:
Replacement cycles stretch from months for software credentials to half-decades for government-grade hardware, creating divergent revenue predictability across supplier portfolios.
- Hardware Tokens:Physical devices embedding secure element chips generate cryptographic signatures resistant to remote extraction. Defense contractors in the United States and critical infrastructure operators in Germany favor these for air-gapped environments where network isolation prevents cloud alternatives. NIST mandates for phishing-resistant authenticators accelerate federal procurement despite semiconductor supply concentration risks.
- Biometrics:Facial recognition and fingerprint modalities employ liveness detection algorithms to defeat presentation attacks. Indian banking apps under RBI directives deploy selfie-authentication for digital transactions, while EU AI Act conformity assessments add validation costs to European facial recognition deployments.
- Software Tokens:Mobile applications generate time-synchronized passcodes without dedicated hardware. Enterprise IT departments favor these for remote workforce provisioning.
- SMS OTP:One-time passwords delivered via cellular messaging retain foothold in price-sensitive emerging markets despite documented SIM-swap vulnerabilities.
Hardware tokens anchor the volume base in regulated sectors while biometrics gains share at the steepest rate as liveness detection matures.
User Type:
Budget authority and procurement sophistication create four distinct customer archetypes with varying tolerance for integration complexity and recurring subscription models.
- Enterprises:Workforce identity orchestration spanning hybrid IT environments drives demand for cloud-native platforms with API-first architectures. Zero-trust mandates from US federal agencies compress deployment timelines from years to quarters.
- Government:Sovereign data residency requirements and classified system access dictate hardware token procurement with domestic secure element fabrication where available.
- Individual Users:Consumer-facing financial services and social platforms prioritize frictionless mobile biometric enrollment.
- Educational Institutions:Budget constraints and distributed campus networks favor software-based authentication with federated identity integration.
Enterprises dominate current procurement value while government contracts deliver the longest revenue visibility through multi-year hardware refresh cycles.
Deployment Model:
Capital expenditure preferences and data sovereignty requirements partition buyers between owned infrastructure and utility-style consumption.
- Cloud-based:Scalable identity-as-a-service eliminates data center overhead and accelerates time-to-value for mid-market SaaS providers. This architecture expands most quickly as organizations retire on-premises identity infrastructure.
- Hybrid:Split processing keeps sensitive authentication factors on-premises while leveraging cloud orchestration for policy management.
- On-premises:Air-gapped installations serve defense and intelligence communities with mandatory physical network isolation.
- Managed Service:Outsourced authentication operations address IT staff scarcity in healthcare and professional services verticals.
Cloud-based deployment captures the majority of new logo acquisitions while hybrid configurations retain strategic importance for regulated multinationals.
Industry Vertical:
Regulatory intensity and breach consequence severity determine authentication investment thresholds across sectoral buyers.
- BFSI:Financial institutions face layered compliance from RBI transaction mandates, EU PSD2 strong customer authentication, and US FFIEC guidance. Legacy mainframe integration costs complicate FIDO protocol adoption for COBOL-based core systems.
- Healthcare:HIPAA breach notification rules and ransomware targeting of patient data elevate workforce identity to board-level priority.
- IT & Telecom:Technology sector early adoption of passwordless FIDO2 credentials migrates authentication to platform authenticators in employee devices.
- Retail:Seasonal workforce volatility and franchise network distribution favor low-friction customer authentication over employee-focused deployments.
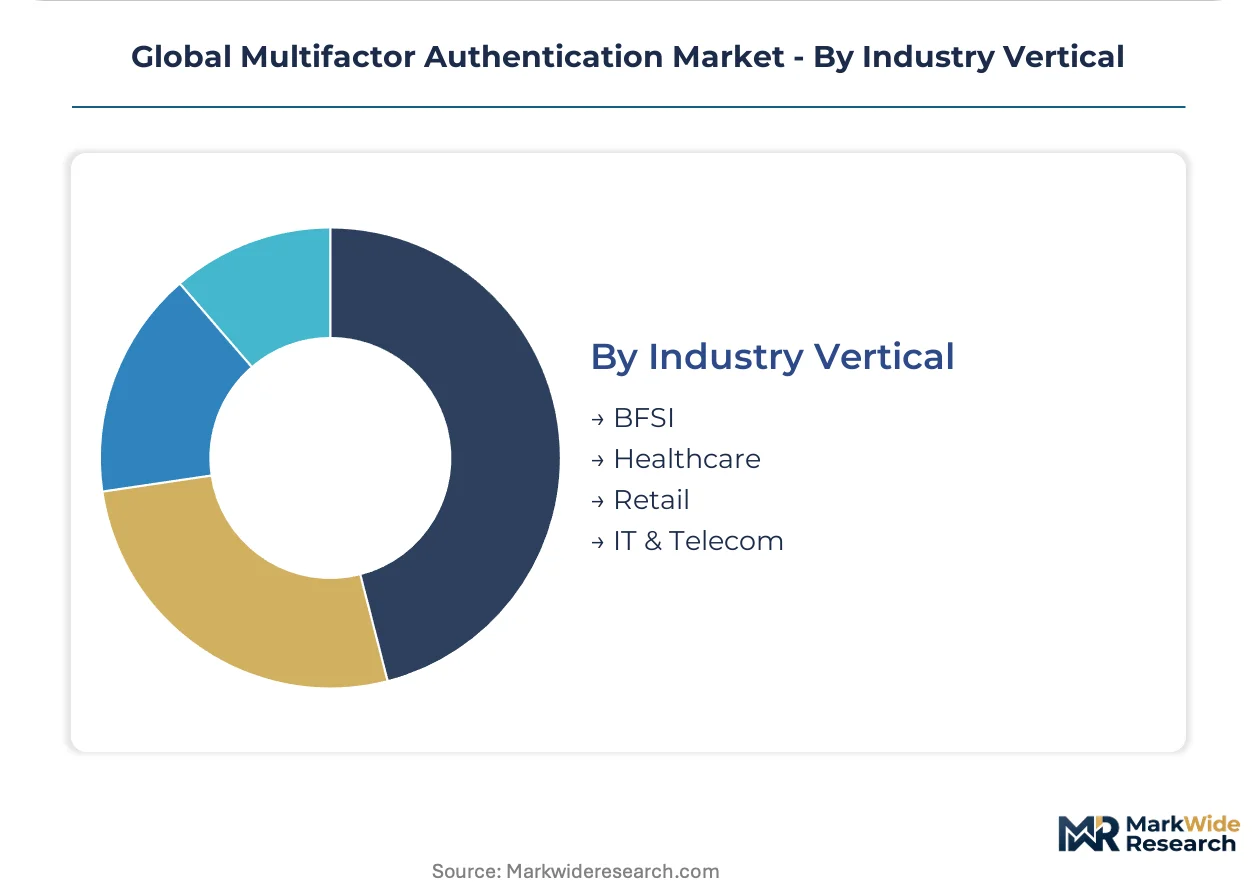
BFSI sustains the highest per-employee authentication spend while healthcare climbs fastest as ransomware incidents multiply.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The transatlantic fiber optic cable corridors linking Frankfurt, London, and New York underpin the data sovereignty architectures shaping authentication procurement across major economies.
United States
Defense contractors and federal agencies drive hardware token demand under NIST phishing-resistant mandates. The Cybersecurity and Infrastructure Security Agency enforces zero-trust timelines for critical infrastructure operators. Seattle and Washington DC metro areas concentrate cloud-native workforce identity deployments for healthcare and government verticals.
Germany
Critical infrastructure operators in energy and manufacturing favor air-gapped hardware tokens where network isolation prevents cloud alternatives. The Bundesamt für Sicherheit in der Informationstechnik certifies sovereign secure element fabrication for government procurement. Munich and Stuttgart industrial clusters anchor demand for FIDO2-compliant manufacturing access systems.
India
RBI transaction mandates for all digital banking push selfie-authentication into mass-market financial apps. The Reserve Bank of India and CERT-In directives compress deployment timelines for domestic fintech providers. Mumbai and Bangalore technology corridors host rapid scaling of biometric liveness detection deployments.
United Kingdom
Financial services firms in the City of London budget for EU AI Act conformity assessments on facial recognition systems despite post-Brexit regulatory divergence. The Financial Conduct Authority maintains PSD2 strong customer authentication alignment with European standards. London's cybersecurity vendor ecosystem supports hybrid identity orchestration for multinational banking headquarters.
Japan
Manufacturing and critical infrastructure operators deploy hardware tokens for operational technology networks where physical possession proofs remain mandatory. The Ministry of Economy, Trade and Industry guides post-quantum cryptographic transition planning for government agencies. Tokyo and Osaka metropolitan areas concentrate enterprise adoption of platform authenticators integrated with employee device fleets.
Global Multifactor Authentication Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream supplying secure elements and biometric sensors. The market structures around three tiers: hyperscale cloud platforms anchoring enterprise subscriptions, hardware security module vendors serving government-grade deployments, and cloud-native identity orchestrators capturing mid-market SaaS providers. Consolidation pressure intensifies as authentication telemetry becomes bundled with managed detection and response services. Strategic moves center on API-first distribution partnerships and embedded authentication via developer marketplaces.
Within the platform integrator tier, Microsoft Corporation exemplifies ecosystem anchoring through identity services bundled with broader cloud infrastructure. Thales Group occupies a position representing specialized hardware security integration with sovereign-grade token deployments. Okta Inc. sits within the cloud-native archetype, exemplifying workforce identity orchestration spanning hybrid IT environments. These three anchors illustrate the competitive vectors—ecosystem lock-in, hardware assurance, and cloud agility—shaping procurement decisions across enterprise, government, and mid-market segments.
| Leading Market Players |
|---|
| Microsoft Corporation |
| Thales Group |
| Okta Inc. |
| RSA Security LLC |
| Cisco Systems Inc. |
| HID Global Corporation |
| Oracle Corporation |
| Yubico |
| CyberArk Software Ltd. |
| Others |
Value Chain & Pricing Dynamics
Taipei-Hsinchu semiconductor corridor capacity utilization directly governs hardware token pricing power, as secure element chip fabrication bottlenecks transmit downstream into authentication vendor margins and procurement lead times.
Pricing Analysis
Volume-discount tiering structures separate enterprise SaaS subscriptions from government hardware token procurements and mid-market API consumption. Certification grade under FIPS 140-2 and Common Criteria EAL4+ creates 30-40% price premiums over commercial-grade alternatives. Cost compression in cloud-native software tiers is intensifying because hyperscaler bundling subsidizes per-seat authentication costs. Mid-market SaaS providers exhibit highest price sensitivity, while defense contractors absorbing NIST-mandated upgrades show lowest elasticity.
Supply Chain Analysis
Contract-manufacturing concentration rests with Taiwan Semiconductor Manufacturing Company and Samsung Foundry for secure element chips, with additional packaging capacity in Malaysia and Vietnam. Raw material dependencies include silicon wafers, rare-earth elements for sensor components, and specialized epoxy resins for tamper-evident housings. Single-source vulnerability in Taiwan Strait geopolitics exposes 18-24 month hardware token lead times. Distribution runs through direct enterprise sales forces, cloud marketplace integrations, and managed security service provider channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating through hyperscaler procurement consolidation, as Microsoft, Amazon, and Google internalize workforce identity into bundled cloud contracts, fragmenting standalone vendor pricing leverage.
For Market Incumbents: Build switching-cost moats through deep API integration into customer ERP and HRIS systems, embedding authentication workflows within operational technology stacks. Thales Group's hardware security module anchoring and Okta's 7,000-plus pre-built integrations exemplify this defensive posture. Prioritize FIDO2 certification maintenance against emerging passkey standard fragmentation. Channel control through managed detection and response provider partnerships defends against hyperscaler bundling.
For New Entrants and Emerging Players: Build out embedded authentication modules for vertical SaaS platforms serving healthcare and professional services, where IT staff scarcity drives outsourcing preference. Brazilian fintech unbanked onboarding and Indian regional bank digital transformation represent most penetrable white-space targets. Developer-first marketplace distribution bypasses traditional enterprise sales cycles entirely.
For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-compliance compounder play because zero-trust mandates and biometric governance provisions create recurring replacement cycles independent of discretionary IT spending. Acquisition target archetype: cloud-native identity orchestrators with API-first architectures and healthcare or government vertical concentration. Watch NIST post-quantum cryptography standardization timing as hardware token replacement inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Post-Quantum Cryptography Transition | NIST lattice-based algorithm adoption forces RSA-dependent token replacement across federal agencies. |
| Platform Authenticator Integration | Resident key storage on employee smartphones compresses standalone hardware demand in conventional environments. |
| API-First Distribution Partnership | Embedded authentication via developer marketplaces reaches mid-market SaaS providers without direct sales overhead. |
| Biometric Liveness Detection Advancement | Presentation attack resistance enables RBI-mandated selfie-authentication for Indian digital banking transactions. |
| Managed Service Provider Bundling | Authentication telemetry integration with threat hunting services unbundles identity from standalone product sales. |
Study Parameters
Cross-validation between primary executive interviews and secondary regulatory filings anchors the qualitative findings on procurement timelines and compliance architecture. Conversations with CISOs, identity platform engineers, federal procurement officers, and managed security service provider executives informed deployment model preferences. Secondary sources include NIST cybersecurity framework updates, EU AI Act biometric governance provisions, RBI transaction directives, and hyperscaler earnings disclosures on identity revenue attribution. Bottom-up segment sizing and top-down macro constraint checks triangulate volume estimates.
Calibration against historical authentication procurement cycles and disclosed federal contract values validates projection trajectories across the analysis window. Segmentation dimensions modeled include product architecture, deployment model, organization size tier, industry vertical, and regional regulatory cluster. CAGRs derive from logistic adoption curve fitting against compliance deadline schedules and technology replacement cycles. Quantum-resistant cryptographic transition timelines and biometric algorithm auditing costs constitute industry-specific forecast inputs.
The forecast holds incumbent behavior within observed patterns; aggressive moves by hyperscalers to subsidize authentication as loss-leader cloud attach would shift outcomes toward faster software token displacement. Regulatory acceleration beyond current NIST and EU AI Act timelines, or Taiwan Strait supply disruption, would compress hardware token availability and elevate pricing. Quarterly review of federal procurement pipeline disclosures and secure element foundry capacity announcements is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biometrics & Identity Management
Biometric Lockers Market
Biometrics & Identity Management
Biometric Smart Cards Market
Biometrics & Identity Management
Palm Vein Biometrics Market
Biometrics & Identity Management
Europe Decentralized Identity Market
Biometrics & Identity Management
Physical Identity and Access Management (PIAM) Market
Biometrics & Identity Management
Biometric Authentication Solution Market
Biometrics & Identity Management
Global Phone Based Authentication Solution Market
Biometrics & Identity Management
Physical Identity and Access Management (PIAM) Software Market
Biometrics & Identity Management
Global Mobile User Authentication Market
Biometrics & Identity Management
Spain Mobile Biometrics Market
Biometrics & Identity Management
IRIS Biometrics Market
Biometrics & Identity Management
Biometric Scan Software Market
Biometrics & Identity Management
Global Biometric Card Market
Biometrics & Identity Management
Biometric Passport Market
Biometrics & Identity Management
Mobile Devices User Authentication Services Market
Biometrics & Identity Management
Voice Biometric Solutions Market