
 Europe Generative AI Market | 2026-2036
Europe Generative AI Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Generative AI Market Analytics
The gap between frontier large language models and narrow task-specific generators is repositioning procurement strategies across European enterprises. Mistral AI leverages open-weight architectures to anchor its presence among regulated institutions seeking auditability. DeepL competes on linguistic precision across twenty-four European languages, sustaining its dominance in professional translation workflows.
Generative AI encompasses neural architectures trained to synthesize novel content — text, imagery, audio, or structured data — through probabilistic pattern completion, typically requiring billions of parameters and terabyte-scale curated datasets. Its primary commercial purpose is automating creative and analytical production at throughput levels unreachable by human-only teams. Natural language processing applications currently occupy the largest deployment share, while image synthesis is recording the fastest uptake in automotive design and pharmaceutical molecular visualization. Cloud-based deployment leads among mid-market adopters, though hybrid configurations are gaining traction where GDPR data residency requirements intersect with latency-sensitive inference workloads.
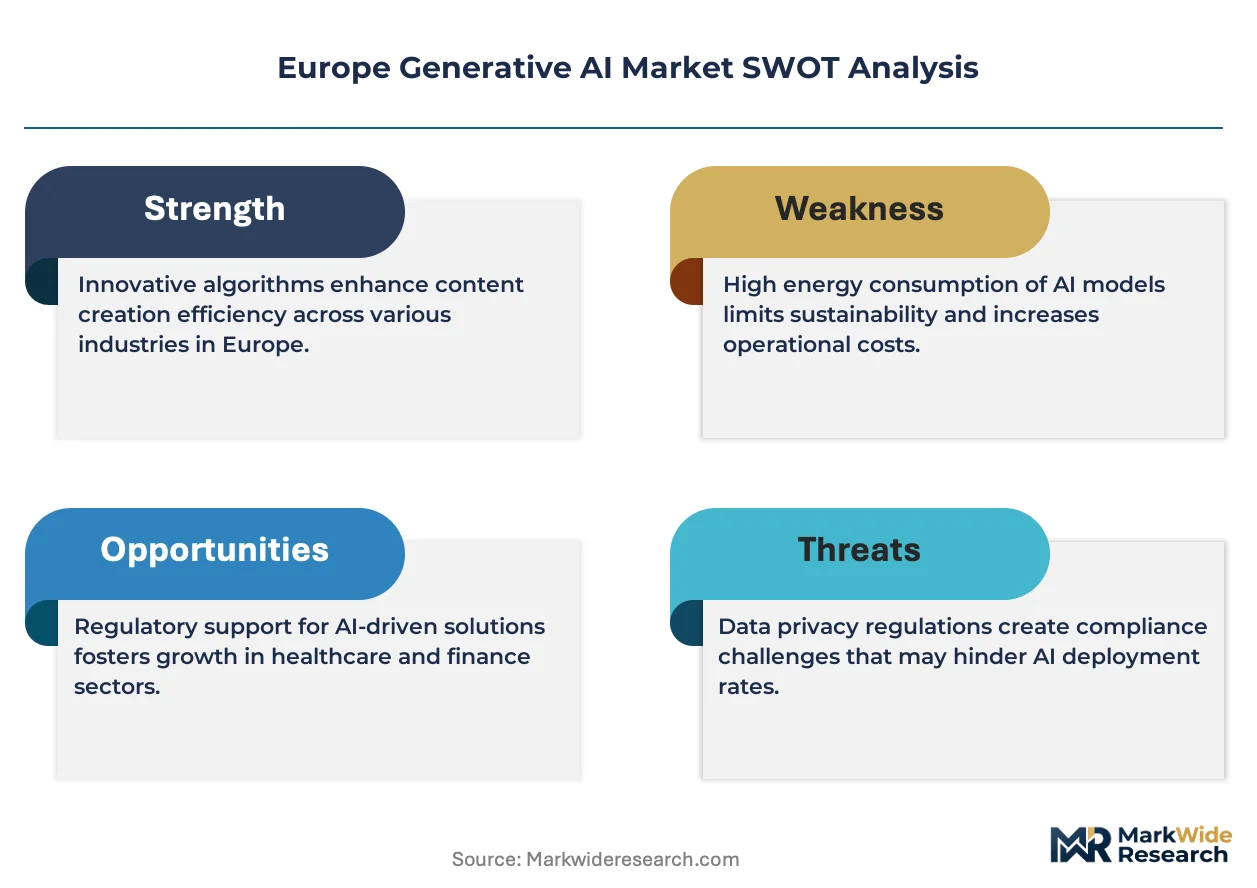
The EU AI Act, alongside GDPR and the proposed Product Liability Directive, is reshaping liability allocation between model developers and enterprise deployers. EMA guidelines for AI-enabled drug discovery and the ECB's framework for algorithmic credit scoring are creating compliance-driven demand for interpretability tools and documentation platforms. Stakeholders must monitor how national supervisory authorities interpret high-risk system classifications, as divergent enforcement across member states will fragment market access conditions.
Market Dynamics
The EU AI Act's risk classification framework is forcing enterprises to restructure model governance before any customer-facing deployment, compressing vendor selection cycles and elevating auditability requirements above raw performance benchmarks.
Growth Catalysts
- High-Risk System Mandates:The EU AI Act's documentation requirements for foundation models are creating compliance-driven procurement of interpretability tools and model cards among Frankfurt and London financial institutions.
- France:National AI sovereignty initiatives are channeling public capital toward domestic large language model development, reducing reliance on non-European cloud inference providers.
- Multimodal Architectures:Automotive design studios in Germany and pharmaceutical molecular visualization teams are adopting image synthesis pipelines trained on proprietary compound libraries.
Market Restraints
- Compute Cost Volatility:NVIDIA GPU supply concentration and energy price spikes in Germany are inflating training costs for mid-market enterprises seeking custom fine-tuning.
- GDPR Data Residency:Cross-border inference routing faces legal friction when model weights and training data must remain within specific member state jurisdictions.
- Technical Limitation:Hallucination rates in regulated document generation remain too high for unsupervised deployment in ECB-supervised credit scoring workflows.
Strategic Opportunities
- Spain and Italy:Lower penetration of enterprise generative AI relative to Germany, France, and the United Kingdom creates first-mover advantage for localized language model providers.
- Regulatory Tailwind:The proposed Product Liability Directive's algorithmic damage provisions will expand insurance-linked demand for model risk assessment platforms.
- Edge Deployment:Hybrid configurations combining cloud training with on-device inference are addressing latency requirements in manufacturing quality control across Bavaria and Baden-Württemberg.
Industry Challenges
- ML Engineering Talent Scarcity:European universities produce insufficient specialists in responsible AI and model evaluation to meet hiring targets at Paris and Berlin AI labs.
- Legacy System Integration:SAP and Oracle ERP environments in industrial enterprises resist API-based generative AI insertion without costly middleware development.
- CE Marking Uncertainty:Ambiguous MDR applicability to AI-generated medical imaging outputs delays commercialization timelines for radiology software vendors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Generative AI Market |
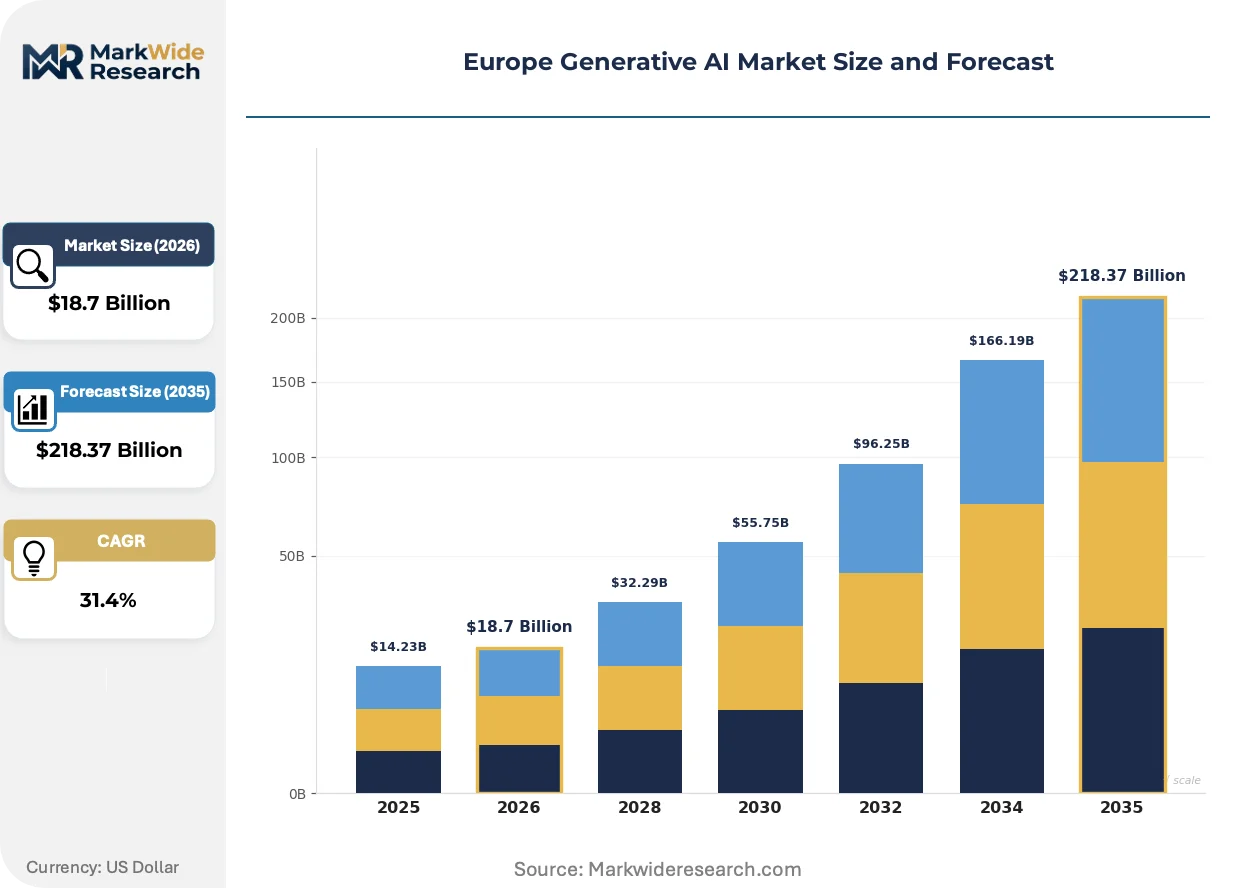
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $218.37 Billion |
| CAGR (2026 – 2036) | 31.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Deep Learning, Reinforcement Learning, Natural Language Processing, Generative Adversarial Networks End User: Healthcare, Automotive, Financial Services, Entertainment Application: Content Creation, Image Synthesis, Data Augmentation, Virtual Assistants Deployment: Cloud-Based, On-Premises, Hybrid, Edge Computing |
| Companies Covered | Mistral AI, Aleph Alpha, Helsing, DeepL, ElevenLabs, Stability AI, Synthesia, Black Forest Labs, PolyAI, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Generative AI Market Evolving Landscape
Foundation model architectures are fragmenting into specialized vertical stacks, with European developers prioritizing linguistic coverage and regulatory auditability over parameter scale.
Retrieval-augmented generation is converging with vector database infrastructure to ground large language model outputs in verifiable enterprise knowledge graphs. German automotive suppliers and French insurance underwriters are deploying these systems for contract analysis and technical documentation. This convergence is compressing the competitive window for pure-play text generation APIs that lack source attribution capabilities.
The EU AI Act's systemic risk tier for general-purpose AI models imposes transparency obligations on training data provenance and compute thresholds. Model providers must now document energy consumption and red-team results before market entry. French and German national regulators are interpreting these provisions more stringently than southern European counterparts, fragmenting compliance costs.
Enterprise buyers are unbundling model procurement from cloud infrastructure commitments, demanding portable weights and on-premise inference options. Mid-market adopters in the Netherlands and Scandinavia are negotiating direct licenses with Mistral AI and Aleph Alpha rather than routing through hyperscale marketplaces. This disintermediation pressures cloud providers to reduce inference markup and accelerate sovereign cloud deployments.
Europe Generative AI Market Segmentation
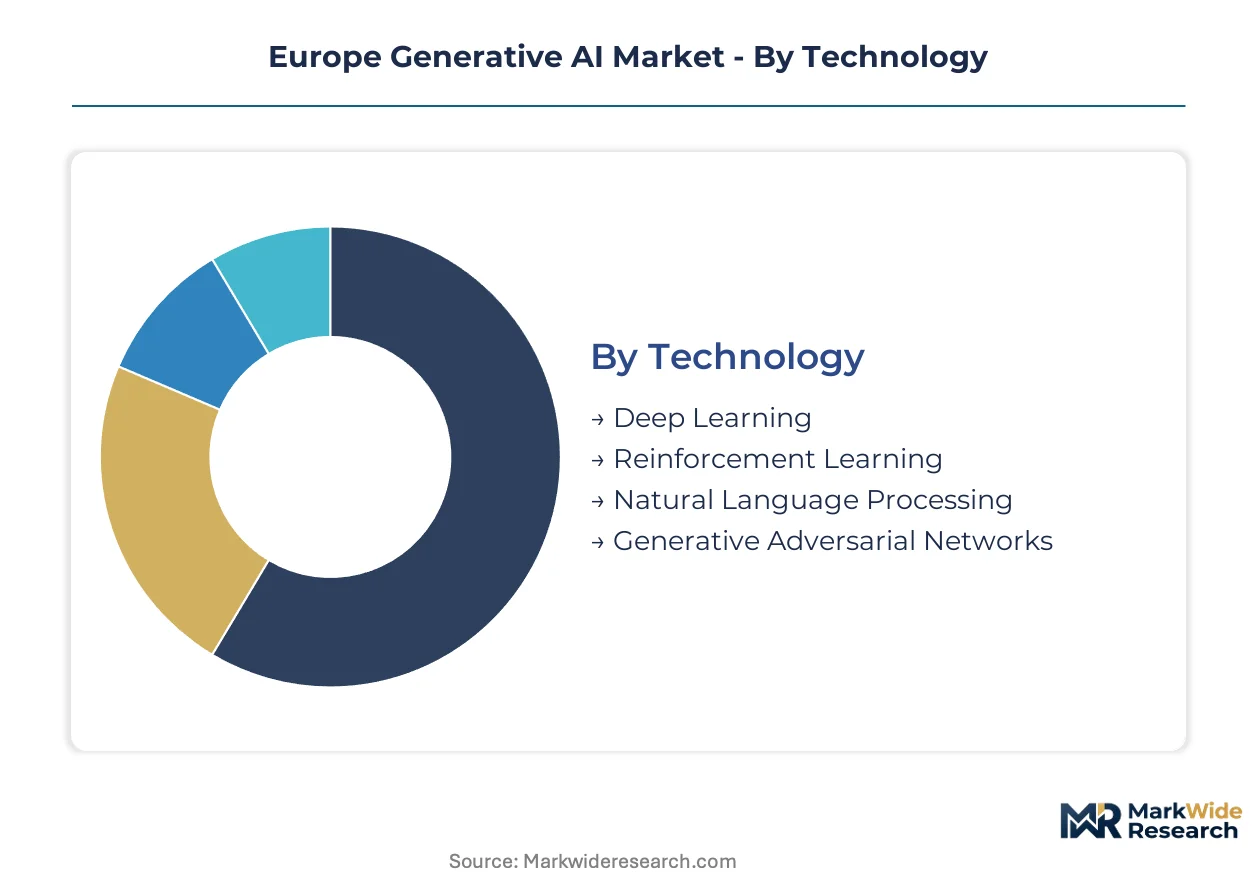
Generative AI procurement in Europe fragments across technical architectures, regulatory exposure levels, and data residency requirements. Buyers prioritize segments offering auditability under EU AI Act risk tiers while balancing inference latency against sovereignty mandates.
Technology:
Standardization dominates foundational layers while customization intensifies at the application frontier.
- Natural Language Processing:Transformer architectures process token sequences for text generation, summarization, and semantic search. Frankfurt and London financial institutions deploy these systems for ECB-supervised credit documentation and MiFID II compliance reporting, constrained by hallucination rates that prevent unsupervised deployment.
- Deep Learning:Multi-layer neural networks with billions of parameters underpin foundation model capabilities. German automotive design studios and French pharmaceutical molecular visualization teams drive demand for proprietary fine-tuning on compound libraries and aerodynamic datasets.
- Reinforcement Learning:Reward-optimized training refines model outputs through human feedback loops.
- Generative Adversarial Networks:Competing generator-discriminator architectures synthesize high-fidelity imagery for industrial quality control.
Leading the category by volume: Natural Language Processing. Growing fastest: Deep Learning.
End User:
Regulatory stringency separates high-compliance verticals from consumer-facing deployments.
- Financial Services:Risk modeling and algorithmic credit scoring under ECB supervision demand interpretability tools and model documentation. Frankfurt and London institutions face compressed vendor cycles as EU AI Act mandates restructure governance frameworks before customer-facing rollout.
- Healthcare:EMA guidelines for AI-enabled drug discovery create compliance-driven procurement of molecular generation platforms. CE marking ambiguity for AI-generated medical imaging delays radiology software commercialization timelines.
- Automotive:Design studios adopt image synthesis for aerodynamic prototyping and synthetic training data generation.
- Entertainment:Content generation workflows prioritize throughput over regulatory auditability.
Dominant by procurement value: Financial Services. Expanding most quickly: Healthcare.
Application:
Attribution requirements differentiate enterprise-grade from consumer-grade use cases.
- Content Creation:Document generation, code synthesis, and marketing copy production. German automotive suppliers and French insurance underwriters deploy retrieval-augmented systems grounded in enterprise knowledge graphs for contract analysis.
- Image Synthesis:Molecular visualization and automotive design pipelines trained on proprietary datasets. Bavaria and Baden-Württemberg manufacturing quality control teams adopt edge-deployed inference for latency-sensitive defect detection.
- Virtual Assistants:Customer service automation with escalating documentation obligations under EU AI Act high-risk system classifications.
- Data Augmentation:Synthetic dataset generation for training data-scarce domains.
Widest deployment footprint: Content Creation. Steepest expansion trajectory: Image Synthesis.
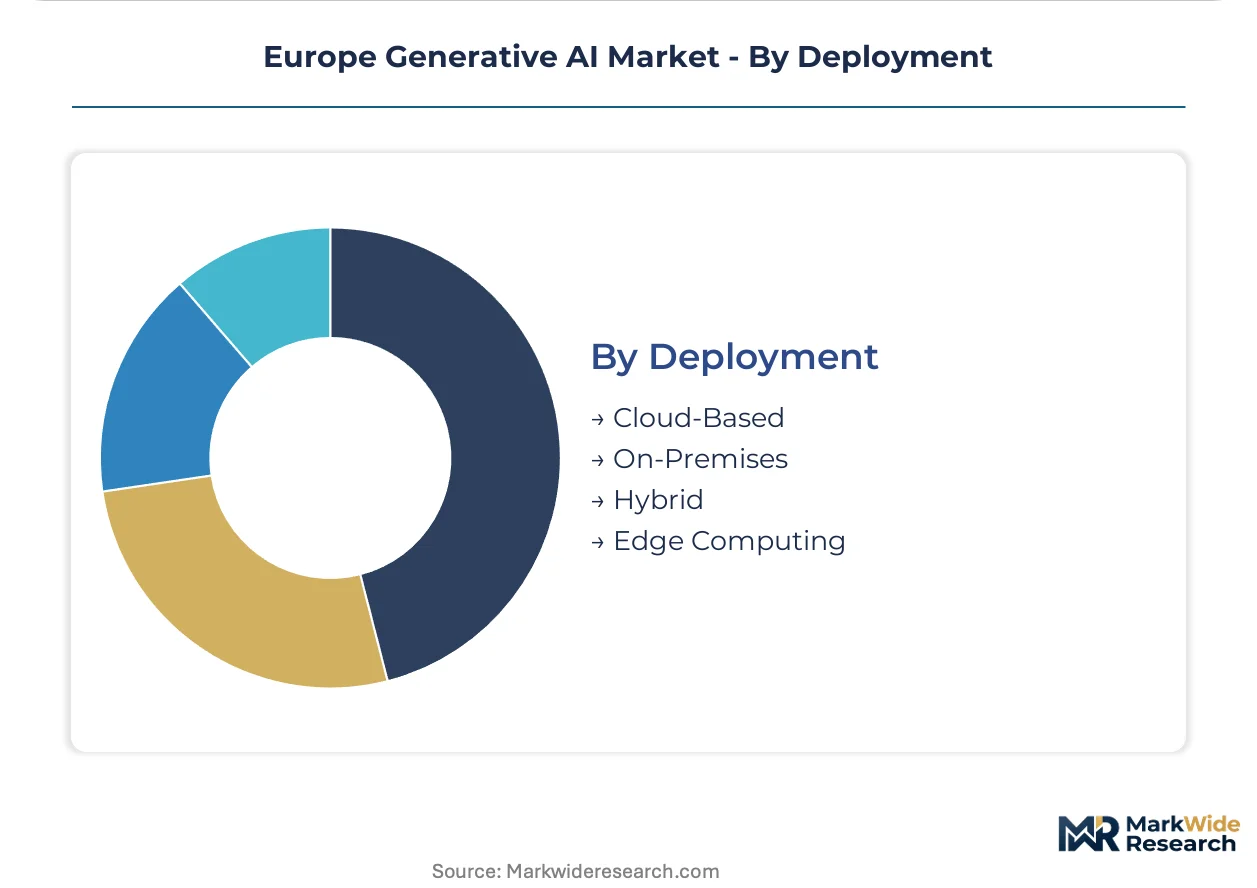
Deployment:
Data residency mandates fragment infrastructure choices across member state jurisdictions.
- Cloud-Based:Centralized training and inference via hyperscale providers. Mid-market adopters in the Netherlands and Scandinavia dominate this segment, though GDPR cross-border routing faces legal friction when model weights must remain within specific jurisdictions.
- Hybrid:Cloud training combined with on-premise or edge inference. Manufacturing quality control across Bavaria and Baden-Württemberg drives adoption where latency requirements intersect with data sovereignty.
- On-Premises:Fully captive infrastructure for maximum auditability and regulatory control.
- Edge Computing:Device-local inference for real-time applications with minimal round-trip latency.
Highest adoption rate: Cloud-Based. Gaining share fastest: Hybrid.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Frankfurt and London anchor Europe's generative AI deployment, with financial institutions in both cities accelerating procurement of large language models for risk modeling and compliance automation under ECB supervision.
Germany
Automotive design studios in Bavaria and Baden-Württemberg drive demand for image synthesis pipelines trained on proprietary aerodynamic datasets. The EU AI Act's high-risk system mandates force Frankfurt financial institutions to restructure model governance frameworks before customer-facing rollout. Manufacturing quality control teams across southern Germany adopt edge-deployed inference for latency-sensitive defect detection.
United Kingdom
London's financial services sector concentrates procurement of interpretability tools and model documentation platforms for MiFID II compliance reporting. The Information Commissioner's Office enforces GDPR data residency requirements that fragment cross-border inference routing. Healthcare AI developers in Cambridge and Oxford face CE marking uncertainty for AI-generated medical imaging outputs.
France
National AI sovereignty initiatives channel public capital toward domestic large language model development in Paris and Île-de-France. The CNIL interprets EU AI Act transparency obligations more stringently than southern European counterparts, elevating compliance costs for foundation model providers. Pharmaceutical molecular visualization teams in Lyon and Strasbourg adopt proprietary compound library training for drug discovery pipelines.
Netherlands
Mid-market enterprises in Amsterdam and Rotterdam negotiate direct licenses with open-weight model providers rather than routing through hyperscale marketplaces. The Dutch Data Protection Authority enforces strict cross-border data transfer limitations that complicate cloud-based deployment architectures. Agritech and logistics clusters in the Randstad region experiment with retrieval-augmented generation for supply chain documentation.
Spain
Lower enterprise generative AI penetration relative to northern Europe creates first-mover advantage for localized language model providers targeting Barcelona and Madrid. The Spanish Data Protection Agency applies EU AI Act enforcement with moderate stringency, reducing compliance friction for mid-market adopters. Fintech and customer service automation clusters in Catalonia drive virtual assistant deployment with escalating documentation obligations.
Europe Generative AI Market Competitive Landscape
Premium-margin players sit above commodity-margin players across auditability and data sovereignty dimensions, with the former commanding pricing power through open-weight architectures and on-premise deployment options. The vendor base concentrates among French and German developers leveraging national AI sovereignty initiatives to anchor presence in regulated institutions. Three archetypes dominate: foundation model providers with transparent training pipelines, vertical specialists optimizing for linguistic precision, and infrastructure-agnostic platforms offering portable weights. Competitive moves center on direct enterprise licensing bypassing hyperscale marketplaces and sovereign cloud partnerships addressing GDPR data residency requirements.
Within the foundation model tier, Mistral AI and Aleph Alpha exemplify the European auditability-focused archetype, occupying positions that emphasize open-weight distribution and regulatory compliance over parameter scale. DeepL anchors the linguistic precision segment, representing specialization across twenty-four European languages that sustains dominance in professional translation workflows. These three companies collectively illustrate how national AI sovereignty initiatives reshape procurement patterns away from non-European cloud inference providers.
| Leading Market Players |
|---|
| Mistral AI |
| Aleph Alpha |
| Helsing |
| DeepL |
| ElevenLabs |
| Stability AI |
| Synthesia |
| Black Forest Labs |
| PolyAI |
| Others |
Value Network & Pricing Analysis
NVIDIA GPU allocation costs cascade through foundation model providers into three-tier pricing structure across premium, standard, and economy levels, with Frankfurt financial institutions absorbing auditability premiums while Dutch mid-market buyers negotiate direct licenses to bypass hyperscale markups.
Pricing Analysis
Outcome-based pricing anchored to inference throughput and compliance documentation dominates procurement contracts for EU AI Act high-risk system deployments. Price differentiation separates open-weight architectures with full audit trails from API-only access, with customization for proprietary compound libraries commanding additional premiums. Pricing pressure stems from energy cost volatility in Germany inflating training economics for mid-market enterprises. Buyer price sensitivity concentrates among Netherlands and Scandinavian mid-market adopters, while ECB-supervised Frankfurt institutions prioritize interpretability over unit cost.
Supply Chain Analysis
Single-source vulnerability sits with NVIDIA's GPU fabrication concentration in Taiwan and advanced packaging in South Korea. European generative AI infrastructure draws from Taiwanese semiconductor foundries, South Korean memory fabrication, and U.S. cloud hyperscaler backbone networks. Supply chain risk centers on export restriction exposure affecting GPU shipment timelines to Frankfurt and Paris AI labs. Distribution runs through sovereign cloud partnerships and direct enterprise licensing channels rather than centralized hyperscale marketplaces.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Foundation model architectures are displacing narrow task-specific generators across European enterprise procurement, with retrieval-augmented generation systems replacing legacy document automation workflows in Frankfurt financial institutions and German automotive suppliers.
For Market Incumbents: Hedge against disintermediation by hyperscale cloud providers through accelerated sovereign cloud partnerships with German and French national infrastructure operators. Fortify position via open-weight distribution models that satisfy CNIL and German regulator documentation requirements under EU AI Act systemic risk tiers. Deepen vertical integration into edge inference hardware for manufacturing quality control deployments across Bavaria. For New Entrants and Emerging Players: Channel partners specializing in SAP and Oracle ERP middleware integration represent the fastest path to legacy system insertion. White-space opportunity concentrates in Spain and Italy, where lower enterprise generative AI penetration reduces competitive density for localized language model providers. Target Barcelona and Madrid fintech clusters with virtual assistant deployments featuring escalating EU AI Act documentation capabilities. For Investors and Strategic Acquirers: Divergent enforcement intensity between French CNIL and Spanish Data Protection Agency interpretations of EU AI Act transparency obligations is the leading indicator that compliance cost fragmentation will reshape competitive positioning. Long-term viability favors acquisition targets with established sovereign cloud deployments and open-weight architectures serving ECB-supervised financial institutions. Watch for inflection when national AI sovereignty initiatives channel public capital toward domestic model development in Paris and Berlin.| Strategic Initiative | Industry Significance |
|---|---|
| Sovereign Cloud Partnership | Addresses GDPR data residency requirements for Frankfurt financial institutions under ECB supervision. |
| Open-Weight Model Distribution | Satisfies EU AI Act auditability mandates for high-risk system classifications in regulated sectors. |
| Edge Inference Deployment | Reduces latency for Bavaria manufacturing quality control teams requiring real-time defect detection. |
| Retrieval-Augmented Generation Integration | Grounds outputs in verifiable enterprise knowledge graphs for French insurance contract analysis. |
| Direct Enterprise Licensing | Bypasses hyperscale marketplace markups for Netherlands and Scandinavian mid-market adopters. |
Research Methodology
Independent corroboration across foundation model providers, financial institution CTOs, and regulatory affairs specialists at ECB-supervised institutions underwrites the qualitative findings presented. Primary interviews with German automotive design studio engineers, French pharmaceutical molecular visualization team leads, and Dutch agritech supply chain managers combined with secondary validation from EMA AI-enabled drug discovery guidelines, ECB algorithmic credit scoring frameworks, and EU AI Act systemic risk tier documentation requirements. Bottom-up deployment estimates across technology segments triangulated with top-down market sizing from cloud hyperscaler capex disclosures and national AI sovereignty initiative budget allocations.
Rate-of-change decomposition across the analysis window separates base-case adoption velocity from regulatory acceleration effects and technology substitution dynamics. Segmentation modeling incorporated natural language processing versus image synthesis deployment patterns, cloud-based versus hybrid infrastructure configurations, and financial services versus healthcare regulatory exposure levels. CAGRs derived from installed base growth curves adjusted for EU AI Act compliance-driven procurement timing shifts and GDPR data residency mandate implementation schedules.
Caveats apply where divergent national supervisory authority interpretations of high-risk system classifications or NVIDIA GPU supply disruption could materially shift the outlook. Forecasts reflect assumptions about EMA guideline finalization timelines and ECB enforcement consistency across member states. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Artificial Intelligence (AI)
Embedded AI Market
Artificial Intelligence (AI)
Human-Computer Interaction (HCI) Market
Artificial Intelligence (AI)
Generative AI in Healthcare Market
Artificial Intelligence (AI)
Voice Assistance Application Market
Artificial Intelligence (AI)
Deep Learning Market
Artificial Intelligence (AI)
Legal AI Market
Artificial Intelligence (AI)
Digital Intelligence Technology Market
Artificial Intelligence (AI)
Global Cognitive Services Market
Artificial Intelligence (AI)
AI in Robotics Market
Artificial Intelligence (AI)
Machine Learning in Pharmaceutical Industry Market
Artificial Intelligence (AI)
Global Conversational Computing Platform Market
Artificial Intelligence (AI)
Global Artificial Intelligence (AI) in Food and Beverages Market
Artificial Intelligence (AI)
Artificial Intelligence (AI) Governance Market
Artificial Intelligence (AI)
United States Artificial Intelligence Market
Artificial Intelligence (AI)
Enterprise LLM Market
Artificial Intelligence (AI)
Europe Synthetic Data Generation Market