
 Embedded AI Market | 2026-2036
Embedded AI Market Size, Share, and Industry Trends Forecast 2026-2036
Embedded AI Market Insights
Foundry capacity expansion in Taiwan is recalibrating supply availability for AI accelerators and system-on-chip designs. NVIDIA Corporation leverages its CUDA software ecosystem to dominate high-performance embedded training workloads. Qualcomm Incorporated anchors smartphone-adjacent edge AI with power-optimized neural processing units. NXP Semiconductors N.V. specializes in automotive-grade inference chips with functional safety certifications.
Embedded AI denotes machine learning and neural network inference executed directly on constrained hardware platforms with sub-10 watt thermal envelopes, typically integrating dedicated tensor cores or DSP arrays alongside general-purpose CPUs. These systems perform real-time pattern recognition, predictive maintenance, and autonomous decision-making without cloud dependency. Hardware segments show AI accelerators capturing the fastest expansion as dedicated silicon displaces general-purpose GPUs in latency-sensitive applications. Application segments reveal automotive systems generating the steepest order growth due to cabin monitoring and autonomous perception requirements. Edge computing technology leads deployment models as manufacturers prioritize data sovereignty and millisecond response times.
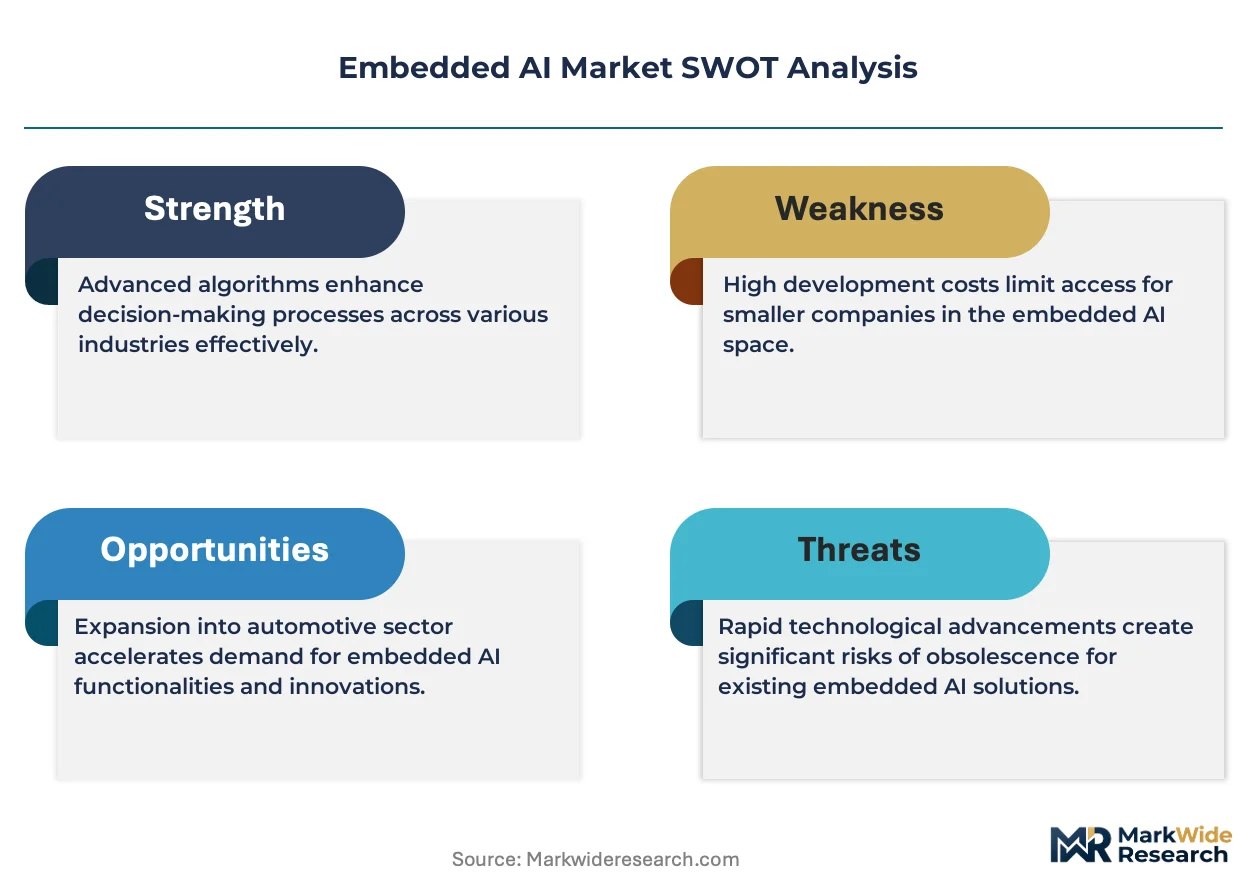
The EU AI Act, FDA software-as-medical-device guidance, and NHTSA autonomous vehicle testing protocols are tightening validation requirements for embedded inference systems in safety-critical applications. Compliance costs favor vendors with pre-certified development pipelines and documented training data provenance. Stakeholders must evaluate whether to build sovereign chip packaging capacity or secure long-term foundry allocations before supply commitments harden.
Market Dynamics
Automotive OEMs are consolidating neural network accelerator procurement around functionally safe inference engines as NHTSA testing protocols and the EU AI Act impose concurrent validation burdens on Tier-1 suppliers.
Growth Catalysts
- EU AI Act certification mandates:Safety-critical embedded inference systems now require documented training data provenance and pre-certified development pipelines, favoring vendors with established automotive-grade track records.
- Edge computing sovereignty requirements:German, Japanese, and US manufacturers are prioritizing on-device pattern recognition to eliminate cloud dependency and achieve millisecond response times in autonomous perception.
- Neural processing unit integration:Dedicated tensor cores and DSP arrays are displacing general-purpose GPUs in sub-10 watt thermal envelopes for real-time predictive maintenance applications.
Market Restraints
- Foundry concentration risk:Taiwan-based capacity expansion remains the primary supply source for AI accelerators and system-on-chip designs, creating single-geography vulnerability.
- Functional safety certification costs:ISO 26262 ASIL-D compliance for automotive inference chips requires 18-24 month validation cycles that bar smaller silicon vendors from safety-critical procurement.
- Legacy DSP substitution:General-purpose digital signal processors in industrial automation retain installed-base inertia against dedicated AI accelerator replacement.
Strategic Opportunities
- India PLI scheme for semiconductor packaging:Sovereign chip assembly capacity construction is attracting embedded AI module manufacturers seeking tariff-advantaged supply routes.
- Cabin monitoring mandate expansion:Driver attention tracking and occupant detection regulations in Germany and Japan are creating dedicated inference hardware demand outside autonomous driving.
- FDA software-as-medical-device pathway:Edge-based diagnostic inference engines for portable medical devices face streamlined premarket review compared to cloud-dependent alternatives.
Industry Challenges
- Embedded systems talent scarcity:Cross-functional engineers combining neural network optimization with thermal-constrained hardware design command premium compensation that strains mid-tier vendor R&D budgets.
- Multi-regulatory concurrency:Simultaneous compliance with NHTSA autonomous vehicle protocols, EU AI Act conformity assessment, and FDA software guidance requires parallel documentation streams.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Embedded AI Market |
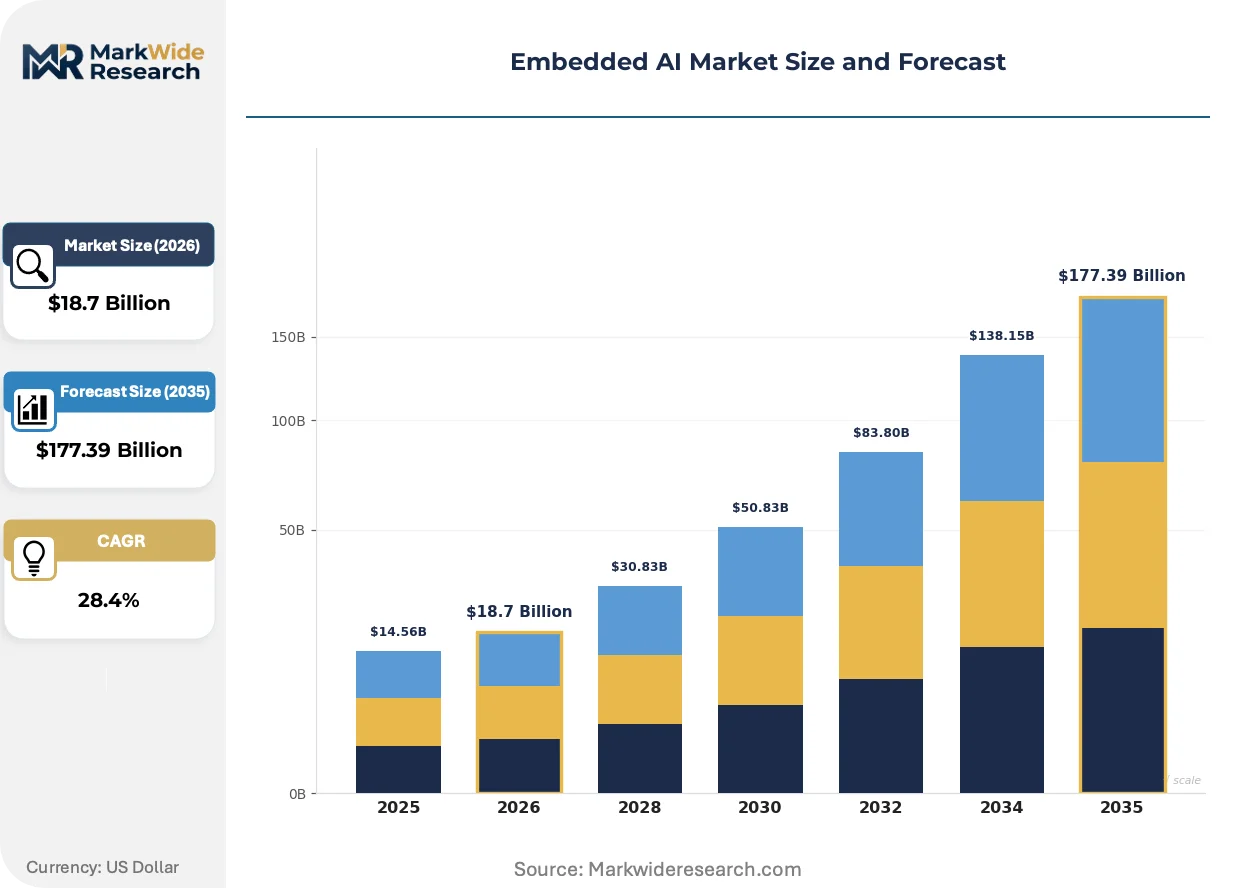
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $177.39 Billion |
| CAGR (2026 – 2036) | 28.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Microcontrollers, System-on-Chip, Embedded Systems, AI Accelerators Application: Consumer Electronics, Automotive Systems, Industrial Automation, Smart Home Devices End User: OEMs, Tier-1 Suppliers, Retailers, Aftermarket Providers Technology: Edge Computing, Machine Learning, Neural Networks, Deep Learning |
| Companies Covered | NVIDIA Corporation, Intel Corporation, Qualcomm Incorporated, Google LLC, Microsoft Corporation, Arm Holdings plc, NXP Semiconductors N.V., Texas Instruments Incorporated, Advanced Micro Devices, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Embedded AI Market Trends and Innovations
Neural network quantization and sparse inference techniques are compressing model footprints to fit microcontroller-class memory constraints without accuracy degradation.
Post-training quantization with INT8 and INT4 precision is automating real-time pattern recognition on automotive-grade inference chips. Tier-1 suppliers in Stuttgart and Nagoya are adopting these compressed models for cabin monitoring systems. The compression is automating the displacement of cloud inference for latency-sensitive autonomous perception functions.
The EU AI Act's risk-based classification system imposes mandatory conformity assessment on safety-critical embedded inference engines. Automotive OEMs must now document training data provenance and algorithmic transparency for driver assistance systems. German regulators are enforcing this through notified body audits that extend certification timelines by 8-12 months.
Buyers are consolidating accelerator procurement around vertically integrated silicon vendors offering pre-certified development pipelines. Tier-1 automotive suppliers are abandoning multi-source GPU strategies in favor of single-vendor neural processing unit contracts with guaranteed functional safety documentation. This concentration is most visible in Michigan and Baden-Württemberg manufacturing clusters.
Embedded AI Market Segmentation
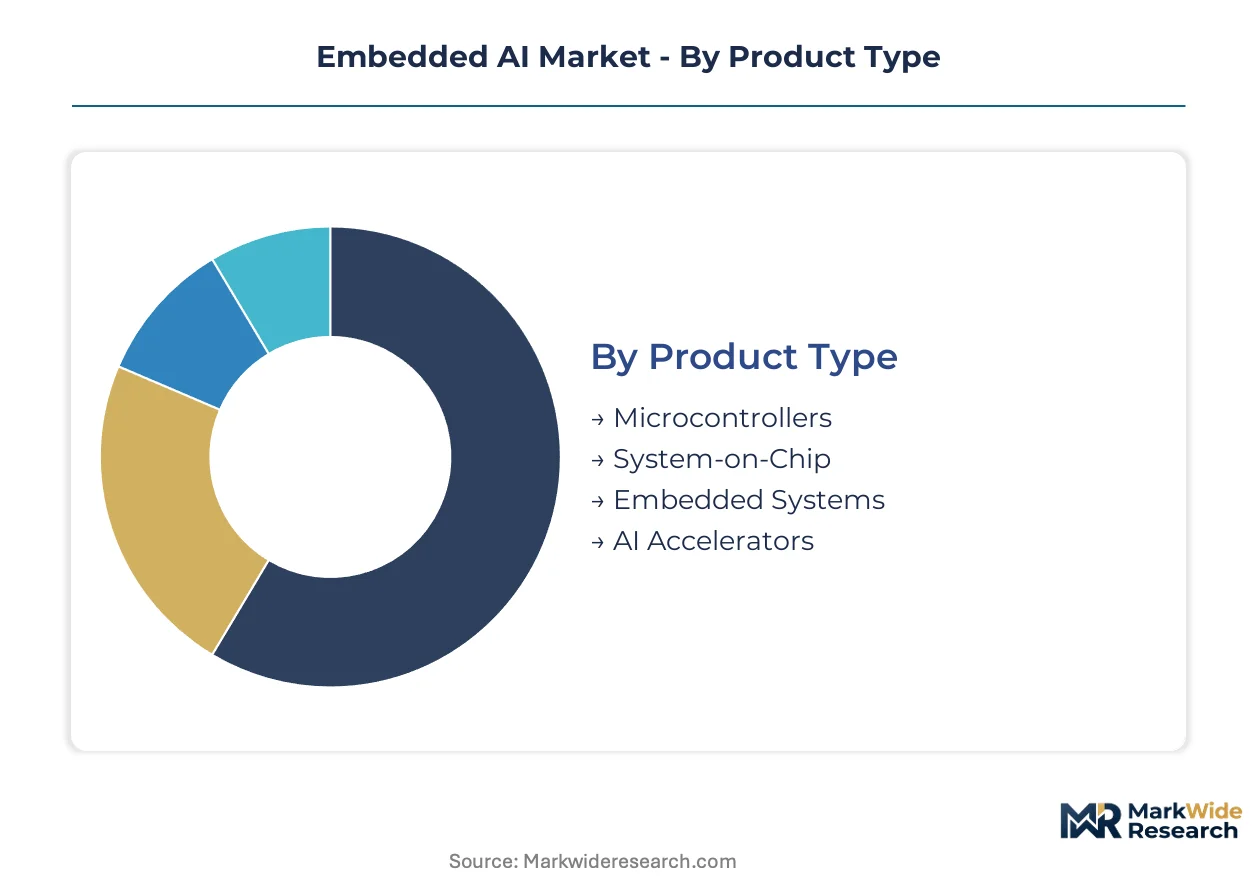
Embedded AI segmentation reflects thermal constraints, functional safety tiers, and sovereignty-driven supply chain reconfigurations. Procurement patterns diverge sharply between latency-critical automotive inference and cost-optimized consumer edge devices.
Product Type:
Silicon packaging capacity in Taiwan, Germany, and the United States is concentrating supply availability for dedicated inference engines versus general-purpose compute platforms.
- AI Accelerators:Dedicated tensor cores and neural processing units deliver sub-10 watt inference with deterministic latency for autonomous perception. Stuttgart and Nagoya automotive clusters are absorbing the bulk of ASIL-D certified accelerator output as cabin monitoring mandates expand.
- System-on-Chip:Integrated CPU-GPU-NPU architectures combine application processors with dedicated inference engines on single die. German and Japanese OEMs are consolidating procurement around pre-certified SoC vendors to compress EU AI Act validation timelines.
- Microcontrollers:ARM Cortex-M class devices with embedded vector extensions enable quantized neural networks on sub-dollar silicon.
- Embedded Systems:Modular compute boards integrating accelerators with industrial I/O for factory automation retrofit applications.
AI Accelerators absorb the bulk of installed capacity; System-on-Chip is expanding most quickly.
Application:
Regulatory mandates in Germany, Japan, and the United States are creating divergent demand profiles across safety-critical and convenience-oriented deployment contexts.
- Automotive Systems:Driver assistance and cabin monitoring functions require ISO 26262 ASIL-D certified inference with documented training data provenance. KBA enforcement of EU AI Act conformity assessments extends German OEM certification cycles.
- Industrial Automation:Predictive maintenance and quality inspection applications prioritize deterministic latency over functional safety certification.
- Consumer Electronics:Smartphone and wearable devices leverage Qualcomm neural processing units for voice recognition and computational photography.
- Smart Home Devices:Local voice processing and security camera inference operate on cost-optimized microcontrollers with INT8 quantization.
Automotive Systems command the highest silicon allocation per unit; Industrial Automation is climbing the fastest as legacy DSP replacement accelerates.
End User:
Procurement authority is shifting from distributed Tier-1 engineering teams to centralized OEM platform divisions with direct foundry allocation agreements.
- OEMs:Automotive and industrial original equipment manufacturers are securing multi-year accelerator supply contracts with guaranteed capacity. Michigan and Baden-Württemberg manufacturing clusters are consolidating procurement around single-vendor neural processing unit strategies.
- Tier-1 Suppliers:Bosch, Continental, and Denso are developing proprietary inference software stacks to differentiate commodity silicon procurement.
- Retailers:Consumer electronics distributors prioritize price-optimized microcontroller bundles with pre-integrated edge AI frameworks.
- Aftermarket Providers:Retrofit driver monitoring and fleet telematics vendors source uncertified accelerators through open-market distribution.
OEMs absorb the bulk of certified silicon capacity; Tier-1 Suppliers are gaining share fastest through vertical software differentiation.
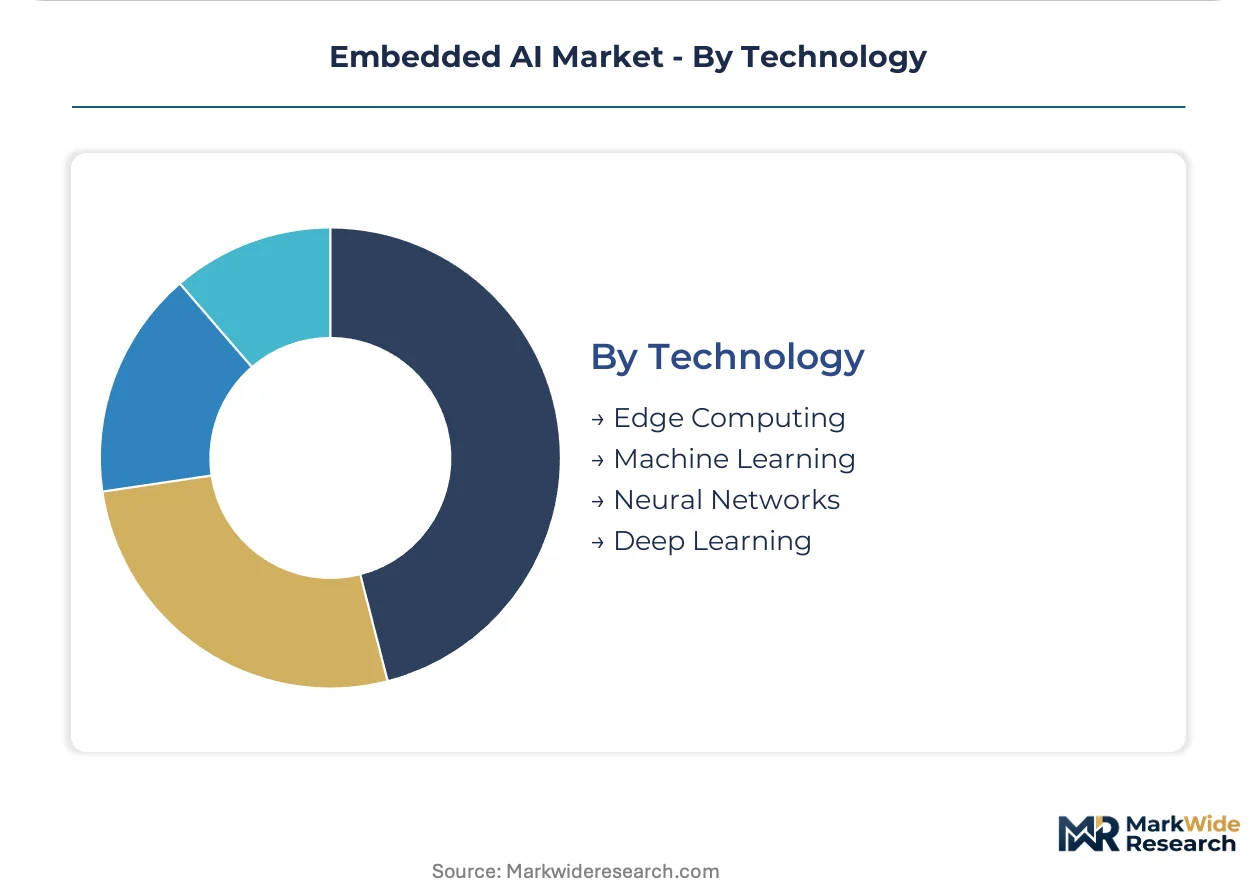
Technology:
Deployment model selection hinges on data sovereignty requirements versus cloud training dependency, with European manufacturers prioritizing on-device pattern recognition.
- Edge Computing:Millisecond-latency inference executed entirely on-device without network dependency. German automotive OEMs are prioritizing edge architectures to satisfy GDPR data localization and EU AI Act transparency requirements.
- Neural Networks:Post-training quantization and sparse inference techniques compress model footprints to microcontroller-class memory constraints.
- Machine Learning:Traditional statistical methods and shallow neural networks on DSP arrays retain installed base in industrial vibration analysis.
- Deep Learning:Transformer and convolutional architectures for autonomous perception require dedicated accelerator silicon with high-bandwidth memory.
Edge Computing dominates deployment volume; Neural Networks is gaining share fastest through quantization-enabled microcontroller penetration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German automotive clusters and Taiwanese foundry infrastructure anchor embedded AI supply chains. Sovereign packaging capacity construction in Japan and the United States is redrawing procurement geography.
Germany
Stuttgart and Munich automotive OEMs drive ASIL-D certified accelerator demand for cabin monitoring systems. KBA enforcement of EU AI Act conformity assessments extends certification cycles by 8-12 months. Baden-Württemberg manufacturing clusters consolidate procurement around single-vendor neural processing unit strategies.
United States
Michigan automotive platform divisions secure multi-year accelerator supply contracts with guaranteed foundry capacity. NHTSA autonomous vehicle testing protocols impose concurrent validation burdens on Tier-1 suppliers. Austin and Phoenix semiconductor packaging investments attract embedded AI module manufacturers.
Japan
Nagoya automotive clusters absorb bulk of pre-certified inference engine output for driver assistance systems. METI semiconductor packaging subsidies support sovereign chip assembly capacity construction. Tokyo-based OEMs prioritize on-device pattern recognition to satisfy data localization requirements.
Taiwan
Taipei-based foundry capacity expansion remains primary supply source for AI accelerators and system-on-chip designs. Concentration risk persists despite diversification efforts. Hsinchu Science Park anchors neural network accelerator wafer fabrication for automotive and industrial segments.
India
Bengaluru and Hyderabad embedded systems engineers command premium compensation for cross-functional neural network optimization skills. PLI scheme for semiconductor packaging attracts tariff-advantaged supply route construction. Domestic OEMs pilot microcontroller-class inference engines for industrial automation retrofit.
Embedded AI Market Competitive Landscape
Global majors compete with regional champions across certification depth and foundry allocation security. The vendor base stratifies between vertically integrated silicon vendors and specialized inference software developers. Three archetypes dominate: CUDA-ecosystem incumbents, automotive-grade functional safety specialists, and smartphone-adjacent edge AI optimizers. Competitive moves center on pre-certified development pipeline construction and multi-year foundry capacity reservation.
Within the automotive-grade functional safety tier, NXP Semiconductors N.V. exemplifies vendors with ISO 26262 ASIL-D track records and documented training data provenance. Qualcomm Incorporated occupies a position in smartphone-adjacent edge AI through power-optimized neural processing unit integration. NVIDIA Corporation represents the CUDA-ecosystem incumbent archetype, leveraging software lock-in to dominate high-performance embedded training workloads.
| Leading Market Players |
|---|
| NVIDIA Corporation |
| Intel Corporation |
| Qualcomm Incorporated |
| Google LLC |
| Microsoft Corporation |
| Arm Holdings plc |
| NXP Semiconductors N.V. |
| Texas Instruments Incorporated |
| Advanced Micro Devices, Inc. |
| Others |
Pricing and Supply Chain Analysis
Automotive OEM consolidation around single-vendor neural processing unit strategies forces foundries to reserve dedicated capacity blocks, compressing spot-market availability and elevating contract premiums for uncertified silicon tiers.
Pricing Analysis
Warranty and functional safety documentation bundling separates ASIL-D certified accelerators from uncertified alternatives. Three-tier pricing structure across automotive-grade, industrial-grade, and consumer-grade certification levels reflects 18-24 month validation cycle investments. Pricing pressure stems from Taiwan foundry concentration as German and Japanese OEMs compete for guaranteed allocation. Tier-1 suppliers exhibit lowest price sensitivity given EU AI Act compliance mandates; aftermarket retrofit vendors face acute cost compression.
Supply Chain Analysis
Advanced packaging substrates draw from Japanese specialty chemical producers, Taiwanese wafer fabrication facilities, and German automotive-grade testing laboratories. EUV photoresist, high-bandwidth memory stacks, and ASIL-D certification services constitute critical input dependencies. Single-source vulnerability concentrates in Hsinchu Science Park wafer output. Distribution runs through direct OEM-foundry contracts with minimal spot-market intermediation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Foundry capacity constraints in Taiwan prop pricing power for vendors with pre-certified development pipelines and multi-year allocation agreements.
For Market Incumbents: Deepen backward integration into sovereign semiconductor packaging capacity in Germany, Japan, and the United States to mitigate Taiwan concentration risk. Secure ISO 26262 ASIL-D certification moats against emerging FPGA-based inference competitors. Expand in-house training data provenance documentation to compress EU AI Act validation timelines for Tier-1 customers. For New Entrants and Emerging Players: Launch via India PLI scheme tariff-advantaged supply routes targeting industrial automation retrofit applications with INT8-quantized microcontroller solutions. Penetrate the cabin monitoring mandate expansion outside autonomous driving where functional safety requirements remain less stringent. Develop proprietary inference software stacks to differentiate commodity silicon procurement for Tier-1 suppliers. For Investors and Strategic Acquirers: The window for entry favors vertically integrated silicon vendors with established automotive-grade track records and documented training data provenance. Long-term viability hinges on securing foundry allocation agreements before supply commitments harden across the projection horizon. Watch NHTSA autonomous vehicle protocol revisions as inflection indicator for safety-critical inference engine demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Foundry Capacity Reservation | Multi-year agreements with TSMC and Samsung secure wafer allocation for automotive NPU output. |
| Functional Safety Certification Investment | ISO 26262 ASIL-D pipelines compress EU AI Act validation timelines for German OEMs. |
| Sovereign Packaging Facility Construction | India PLI scheme and US CHIPS Act funding reduce Taiwan supply chain concentration risk. |
| Neural Network Quantization Platform | INT4 and INT8 compression enables microcontroller-class inference without accuracy degradation. |
| Tier-1 Supplier Software Partnership | Proprietary inference stacks differentiate Bosch, Continental, and Denso silicon procurement. |
Research Methodology
SEC 10-K filings, EU regulatory databases, and automotive production statistics formed the secondary backbone for this analysis. Primary interviews with OEM platform engineers, Tier-1 supplier procurement leads, foundry capacity planners, and semiconductor packaging specialists validated demand-side assumptions. Bottom-up triangulation across accelerator unit shipments and top-down reconciliation with foundry wafer output estimates anchored market sizing.
Historical trendline analysis of neural processing unit deployment across automotive, industrial, and consumer segments informed projection modeling. Segmentation dimensions included product type, application vertical, end-user procurement authority, and deployment technology across the analysis window. CAGRs derived from regression analysis of certified silicon allocation growth and foundry capacity expansion schedules. Forecast inputs incorporated EU AI Act implementation timelines and NHTSA autonomous vehicle protocol evolution.
Taiwan geopolitical disruption, EU AI Act enforcement acceleration, and automotive OEM insourcing decisions are the dominant revision risks for embedded AI market forecasts. Model outputs reflect assumptions about foundry yield improvements and quantization algorithm advancement. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Artificial Intelligence (AI)
Connectivity Constraint Computing Market
Artificial Intelligence (AI)
Global Aiops Platform Market
Artificial Intelligence (AI)
No-Code AI Platform Market
Artificial Intelligence (AI)
Generative AI in Coding Market
Artificial Intelligence (AI)
Artificial Intelligence Chatbots Market
Artificial Intelligence (AI)
Autonomous Agents Market
Artificial Intelligence (AI)
Artificial Intelligence (AI) Market
Artificial Intelligence (AI)
Voice Recognition Market
Artificial Intelligence (AI)
Cognitive Services Platform Market
Artificial Intelligence (AI)
Global Deep Learning Neural Networks (Dnns) Market
Artificial Intelligence (AI)
AI in Retail Market
Artificial Intelligence (AI)
Image Recognition Market
Artificial Intelligence (AI)
Global AI in Social Media Market
Artificial Intelligence (AI)
Global Cognitive Operations Market
Artificial Intelligence (AI)
Artificial Intelligence in Business Market
Artificial Intelligence (AI)
Artificial Intelligence and Machine Learning Market