
 Global Cognitive Services Market | 2026-2036
Global Cognitive Services Market Size, Share, and Industry Trends Forecast 2026-2036
Global Cognitive Services Market Foresight
India is tilting toward cognitive services capacity as Microsoft Corporation and Amazon Web Services expand hyperscale cloud regions in Mumbai and Hyderabad. Microsoft leverages its Azure AI platform to anchor enterprise adoption across speech recognition and natural language processing workloads. Amazon Web Services sustains competitive pressure through Bedrock and SageMaker, dominating the managed machine learning infrastructure layer.
Cognitive services encompass cloud-delivered artificial intelligence capabilities that process unstructured data through pretrained neural models, typically accessed via application programming interfaces with latency thresholds under 200 milliseconds for real-time inference. These systems convert raw text, audio, and visual inputs into structured intelligence for automated decision workflows. Natural language processing and image analysis segments lead current revenue contribution, while anomaly detection commands premium pricing in financial services deployments. Edge computing as a deployment model is accelerating fastest, driven by manufacturing and telecommunications latency requirements that preclude round-trip cloud routing.
FDA scrutiny of machine learning-based software as a medical device shapes product validation requirements for healthcare-facing cognitive services, forcing vendors to document training data provenance and algorithmic drift monitoring. The EU AI Act imposes conformity assessments on high-risk cognitive applications in credit scoring and biometric identification, creating market access friction for non-compliant providers. Stakeholders must weigh regulatory certification costs against the margin expansion available in regulated verticals before committing to geographic expansion or sector specialization.
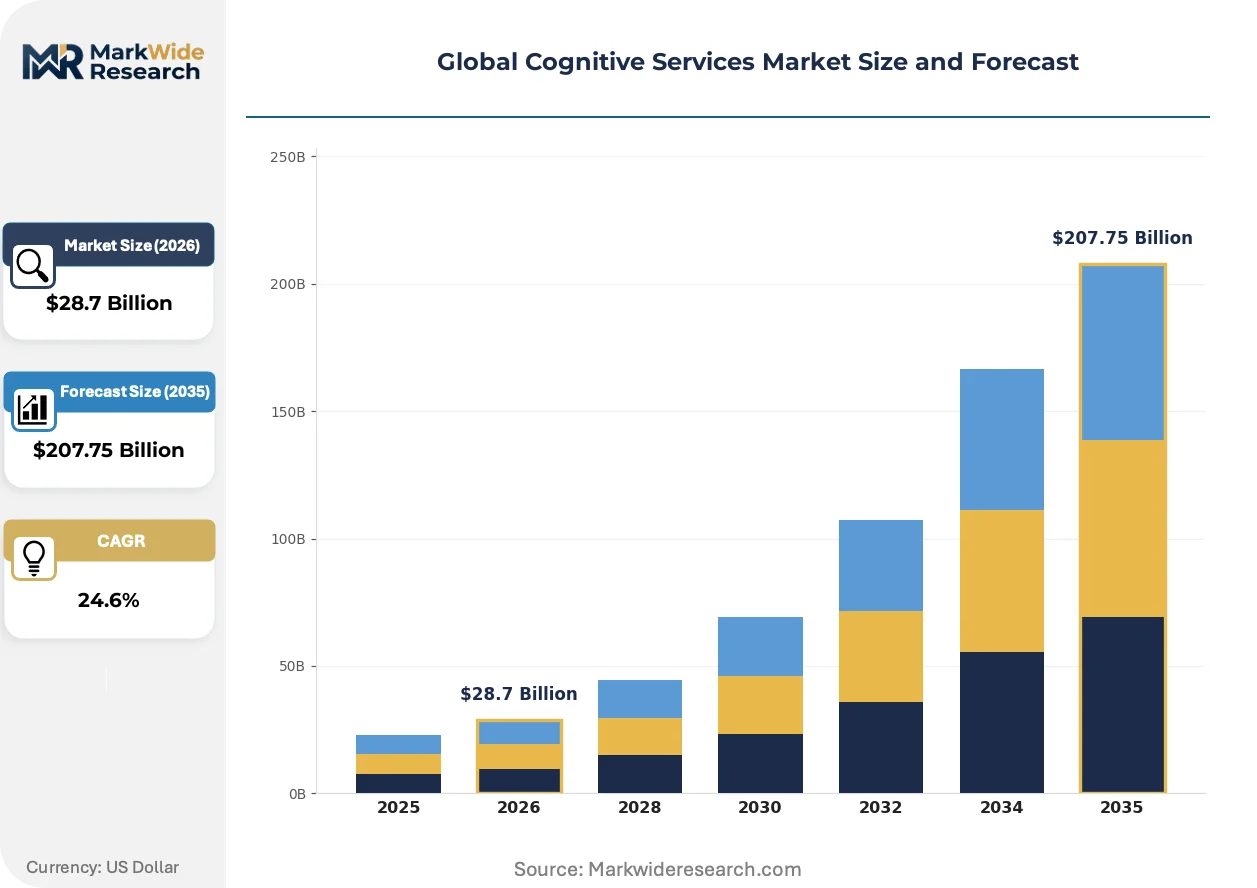
Market Dynamics
Hyperscalers are compressing cognitive services into vertically integrated stacks, forcing independent software vendors to specialize in regulated verticals or risk margin erosion from API commoditization.
Growth Catalysts
- EU AI Act conformity infrastructure:Healthcare and financial services providers are procuring certified cognitive services to preempt market access restrictions, accelerating vendor investment in audit-ready pipelines.
- Edge inference hardware cost curves:Manufacturing and telecommunications operators are deploying on-premise neural accelerators, bypassing cloud latency for quality inspection and predictive maintenance workloads.
- India's data localization mandates:Multinational enterprises are establishing sovereign cognitive processing instances in Mumbai and Hyderabad to satisfy RBI and MeitY requirements for financial and government contracts.
Market Restraints
- Training data provenance documentation:FDA and EMA validation requirements for machine learning-based software as a medical device impose 18-24 month certification timelines, freezing release cycles for diagnostic imaging APIs.
- GPU supply concentration:Foundry capacity constraints in Taiwan and South Korea limit neural training cluster availability, forcing queue-based pricing for compute-intensive model development.
- On-device inference accuracy gaps:Quantized edge models suffer 8-15% precision degradation versus cloud equivalents, restricting deployment in high-stakes biometric and credit scoring applications.
Strategic Opportunities
- Brazil's ANVISA regulatory pathway:Early movers are establishing clinical validation partnerships with São Paulo hospital networks to capture Latin American healthcare cognitive services procurement.
- Synthetic data generation tooling:Privacy-constrained European financial institutions are adopting differentially private training pipelines to circumvent GDPR restrictions on historical customer records.
- 5G network slicing integration:Telecommunications operators in Germany and Japan are embedding guaranteed-latency cognitive API delivery into enterprise service level agreements.
Industry Challenges
- MLOps talent scarcity:Production-grade model monitoring and drift detection functions command 40-60% salary premiums over conventional DevOps roles in the United States and United Kingdom.
- Legacy EMR integration complexity:Hospital systems running Cerner and Epic deployments require 12-18 month customization cycles to embed clinical decision support APIs into existing workflow interfaces.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Cognitive Services Market |
| Market Size in 2026 | $28.7 Billion |
| Market Size in 2035 | $207.75 Billion |
| CAGR (2026 – 2036) | 24.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Speech Recognition, Image Analysis, Natural Language Processing, Sentiment Analysis, Anomaly Detection Deployment Model: Public Cloud, Private Cloud, Hybrid Cloud, On-Premises, Edge Computing Use Case: Customer Support Automation, Fraud Detection, Personalized Marketing, Predictive Maintenance, Risk Management End User Industry: BFSI, Telecommunications, Manufacturing, Media & Entertainment, Education |
| Companies Covered | Microsoft Corporation, Amazon Web Services, Google LLC, IBM Corporation, SAS Institute, Attivio, Apple, Tata Consultancy Services, Nuance Communications, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Cognitive Services Market Shifts & Advancements
Foundation model architectures are commoditizing language and vision capabilities, redirecting competitive differentiation toward domain-specific fine-tuning and regulatory compliance tooling.
Multimodal neural architectures that fuse text, image, and audio processing through unified transformers are migrating from research environments to production customer service and content moderation pipelines. Retail and media enterprises are deploying these systems to consolidate vendor relationships previously split across separate speech, vision, and NLP providers. The consolidation is compressing addressable market space for point-solution specialists while expanding contract values for full-stack platforms.
The EU AI Act's risk-tiered conformity assessment framework is mandating algorithmic impact documentation and human oversight protocols for high-risk cognitive applications in credit scoring and biometric identification. Vendors serving European financial services and border control sectors are restructuring product roadmaps around CE-marking timelines and notified body engagement. German and French procurement authorities are inserting AI Act compliance clauses into public sector tenders, creating first-mover advantages for certified providers.
Enterprise buyers are unbundling cognitive service procurement from cloud infrastructure commitments, negotiating standalone API contracts with specialized providers rather than accepting bundled hyperscaler packages. Manufacturing quality assurance teams in Japan and South Korea are sourcing computer vision inference from niche vendors with sector-specific training data advantages. The disintermediation is fragmenting wallet share and compressing pricing power for generalist platforms in latency-tolerant applications.
Global Cognitive Services Market Segmentation
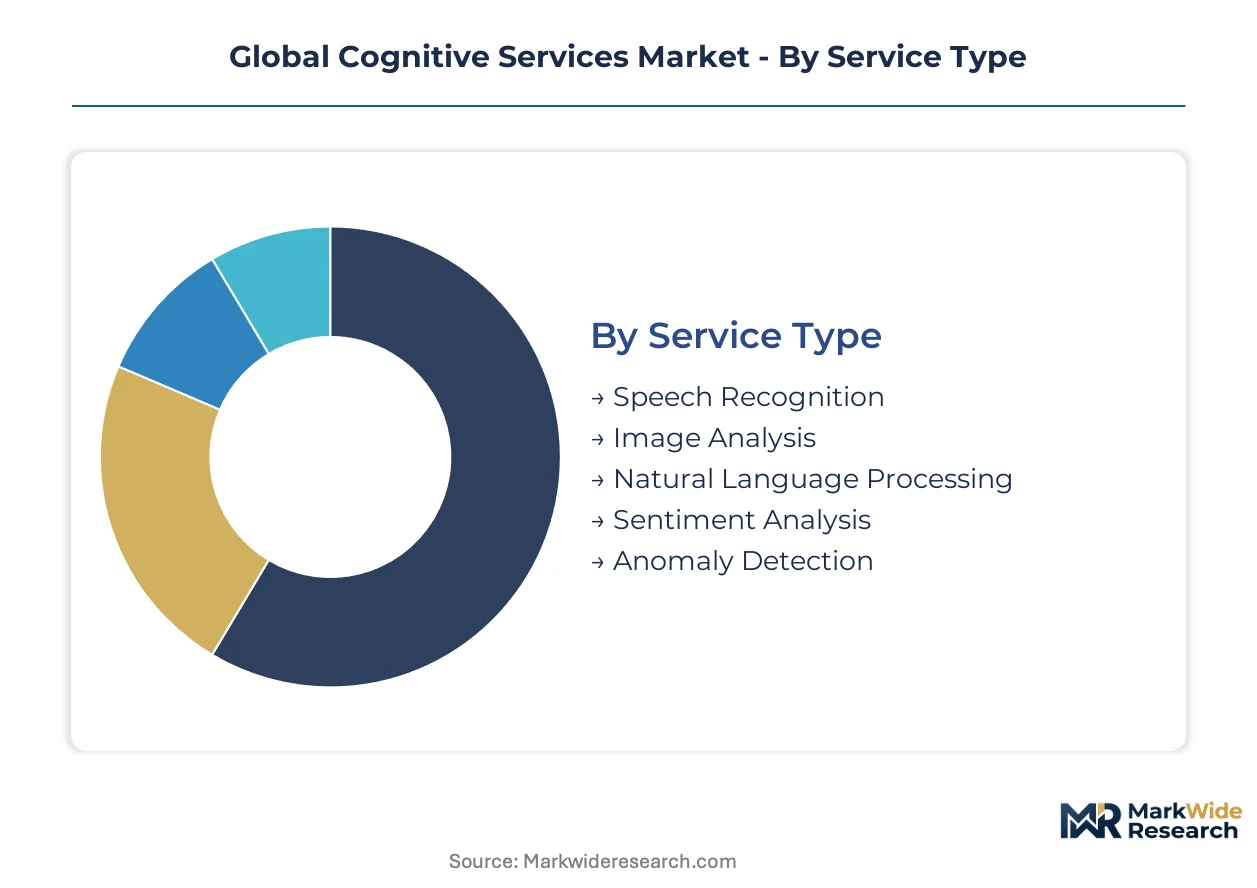
Cognitive services procurement patterns diverge sharply across technical layers and operational contexts. Service type selection dictates API latency requirements and compliance burden, while deployment model choices reflect data sovereignty priorities and edge latency constraints.
Service Type:
Speech recognition and natural language processing APIs refresh model weights quarterly, compressing vendor innovation cycles, while anomaly detection deployments remain static for 18-24 months under FDA and EMA validation lock-in.
- Speech Recognition:Real-time audio transcription pipelines process 160-millisecond latency thresholds for contact center deployments. Demand concentrates in United States telecommunications providers modernizing interactive voice response systems under FCC accessibility mandates.
- Natural Language Processing:Transformer-based text analysis engines extract entities and relationships from unstructured documents. Financial services procurement in Germany and France accelerates under EU AI Act conformity requirements for credit scoring automation.
- Image Analysis:Convolutional neural networks classify visual inputs for quality inspection and diagnostic radiology.
- Sentiment Analysis:Opinion mining APIs score customer feedback polarity across social media and survey channels.
- Anomaly Detection:Statistical deviation models flag transaction fraud and equipment failure precursors.
Natural language processing anchors the volume base while anomaly detection gains share at the steepest rate.
Deployment Model:
Cost tiering separates hyperscaler-managed inference from capital-intensive on-premise installations, with hybrid configurations capturing mid-market buyers seeking workload-specific optimization.
- Public Cloud:Shared-tenant API endpoints deliver pretrained models through metered consumption. United States enterprise buyers dominate procurement, leveraging existing Azure and AWS commitments for speech and vision workloads.
- Edge Computing:On-premise neural accelerators execute inference without round-trip cloud routing. Manufacturing quality inspection in Japan and South Korea drives adoption where 50-millisecond latency thresholds preclude remote processing.
- Private Cloud:Single-tenant cognitive infrastructure isolates data processing within sovereign boundaries.
- Hybrid Cloud:Split architectures route sensitive workloads on-premise while bursting peak demand to public endpoints.
- On-Premises:Fully captive hardware deployments satisfy air-gapped security requirements in defense and critical infrastructure sectors.
Public cloud deployments represent the largest installed base, though edge computing is climbing the fastest as manufacturing and telecommunications operators bypass cloud latency.
Use Case:
Application maturity varies from commoditized chatbot deployments to emerging predictive maintenance implementations requiring custom sensor fusion and domain-specific training data.
- Customer Support Automation:Conversational AI agents resolve tier-one inquiries through integrated speech and text channels. Retail and telecommunications procurement in India accelerates as Microsoft and Amazon expand Mumbai and Hyderabad cloud regions.
- Fraud Detection:Real-time transaction scoring identifies anomalous patterns in payment flows. European banking procurement tightens under EU AI Act high-risk system classification for credit and insurance decisions.
- Personalized Marketing:Recommendation engines match consumer profiles to content and product suggestions.
- Predictive Maintenance:Equipment degradation models forecast failure from vibration, thermal, and acoustic sensor streams.
- Risk Management:Document analysis pipelines extract obligations and exposures from contract and regulatory text corpora.
Customer support automation holds the largest contract volume, while predictive maintenance is expanding most quickly as industrial operators digitize asset monitoring.
End User Industry:
Margin structures diverge between regulated verticals demanding compliance tooling premiums and price-sensitive sectors prioritizing API commoditization.
- BFSI:Banking, financial services, and insurance deploy cognitive services for document processing, fraud surveillance, and algorithmic trading. United States and European procurement dominates, with EU AI Act conformity assessments adding 15-20% implementation overhead.
- Manufacturing:Computer vision and anomaly detection optimize quality assurance and supply chain forecasting. German and Japanese automotive suppliers lead adoption, embedding edge inference directly on production lines.
- Telecommunications:Speech recognition and sentiment analysis modernize customer interaction channels.
- Media & Entertainment:Content moderation and automated subtitling scale video platform operations.
- Education:Personalized tutoring and automated assessment expand in India under MeitY digital learning initiatives.
BFSI contributes the dominant revenue share, though manufacturing is gaining share fastest as industrial IoT sensor deployments multiply training data availability.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hyperscaler cloud infrastructure concentrates cognitive services capacity in jurisdictions with permissive data governance and substantial enterprise IT spending. Regulatory fragmentation across major economies is forcing vendors to establish sovereign processing instances and obtain jurisdiction-specific certifications.
United States
FDA scrutiny of machine learning-based software as a medical device shapes healthcare-facing cognitive services validation requirements. Enterprise AI budgets and Azure and AWS cloud commitments anchor North American demand concentration. Diagnostic imaging API providers in the Boston and San Francisco corridors face 18-24 month certification timelines.
Germany
Automotive suppliers embed edge inference directly on production lines for quality inspection workloads. EU AI Act conformity assessments and CE-marking timelines restructure product roadmaps for credit scoring and biometric identification vendors. Industrial cognitive services procurement clusters in Stuttgart and Munich manufacturing belts.
India
Microsoft and Amazon Web Services expand hyperscale cloud regions in Mumbai and Hyderabad to satisfy RBI and MeitY data localization mandates. Financial services and government contracts require sovereign cognitive processing instances. Tata Consultancy Services anchors domestic enterprise adoption across speech recognition and natural language processing workloads.
Japan
Manufacturing quality assurance teams source computer vision inference from niche vendors with sector-specific training data advantages. METI industrial digitization initiatives accelerate predictive maintenance deployments. Edge computing adoption concentrates in Nagoya automotive production corridors and Osaka electronics manufacturing zones.
Brazil
ANVISA regulatory pathway for clinical validation partnerships shapes Latin American healthcare cognitive services procurement. Early movers establish relationships with São Paulo hospital networks to capture diagnostic imaging and clinical decision support contracts. Multinational vendors localize Portuguese-language natural language processing capabilities.
Global Cognitive Services Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in the value chain. The vendor base organizes around three tiers: hyperscalers offering vertically integrated cognitive stacks, independent software vendors specializing in regulated verticals, and point-solution providers serving latency-sensitive edge deployments. Strategic differentiation concentrates on regulatory certification tooling and domain-specific fine-tuning capabilities. Competitive moves emphasize M&A for training data assets and strategic partnerships for sovereign cloud infrastructure.
Within the hyperscaler tier, Microsoft Corporation and Amazon Web Services occupy positions defined by cloud infrastructure scale and managed machine learning platform breadth. Microsoft leverages its Azure AI platform to anchor enterprise adoption, while Amazon Web Services sustains competitive pressure through Bedrock and SageMaker. Google LLC represents the search-origin archetype with multimodal foundation model integration. IBM Corporation exemplifies the enterprise-consulting hybrid, anchoring cognitive services within professional services engagements. Nuance Communications sits within the healthcare-specialist segment, its clinical documentation focus reflecting vertical depth over horizontal scale.
| Leading Market Players |
|---|
| Microsoft Corporation |
| Amazon Web Services |
| Google LLC |
| IBM Corporation |
| SAS Institute |
| Attivio |
| Apple |
| Tata Consultancy Services |
| Nuance Communications |
| Others |
Supply & Pricing Matrix
GPU supply concentration in Taiwan and South Korea determines both pricing tier spreads and supply chain shape, forcing buyers into queue-based allocation for training clusters while compressing margins for inference-only providers dependent on third-party silicon.
Pricing Analysis
The EU AI Act dictates the pricing tier structure across European deployments, separating certified high-risk systems from uncertified commodity APIs. Three-tier pricing structure across premium, standard, and economy levels reflects validation depth, with FDA-cleared diagnostic imaging commanding substantial premiums over unvalidated alternatives. Pricing pressure stems from hyperscaler API commoditization in speech and vision workloads, squeezing independent vendor margins. Financial services buyers in Germany and France exhibit lowest price sensitivity due to regulatory compliance mandates, while mid-market retail adopters in India drive volume at economy tiers.
Supply Chain Analysis
US export controls on advanced neural accelerators constrain supply chain flows, limiting foundry capacity access for Chinese model developers and fragmenting global training infrastructure. Taiwan Semiconductor Manufacturing and Samsung Electronics anchor wafer production, while NVIDIA and AMD concentrate advanced GPU design. The supply chain draws from South Korean memory fabs and Japanese specialty chemical suppliers for photoresists and substrates. Single-source vulnerability concentrates in advanced node lithography equipment held by ASML in the Netherlands. Distribution runs through direct hyperscaler procurement for cloud deployments and regional systems integrators for sovereign edge installations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Global cognitive services sit in early-cycle expansion, with enterprise AI budget allocation acceleration and regulatory compliance procurement creating durable demand tailwinds across healthcare and financial verticals.
For Market Incumbents: Entrench regulatory certification moats by accelerating FDA 510(k) and EU AI Act conformity timelines ahead of smaller competitors. Deepen backward integration into sovereign cloud infrastructure in India and Brazil to preempt data localization mandates. Hyperscaler API commoditization threatens point-solution margins; vertical specialization in clinical decision support or fraud detection preserves pricing power. For New Entrants and Emerging Players: Mid-market manufacturing quality assurance in Japan and South Korea represents the most penetrable entry point, where sector-specific training data advantages outweigh hyperscaler scale. Synthetic data generation tooling for GDPR-constrained European financial institutions offers second white-space target. Partner with established industrial automation distributors rather than building direct enterprise sales capacity. For Investors and Strategic Acquirers: The EU AI Act's phased enforcement timeline reshapes the acquisition landscape, privileging vendors with existing notified body relationships and documented algorithmic impact assessments. Long-term viability centers on regulatory tooling capabilities rather than raw model performance. Target acquisition archetype: vertical specialists with 2-3 jurisdiction certifications and captive training data libraries in healthcare or credit scoring. Watch FDA enforcement patterns on machine learning-based software as medical device as inflection indicator for healthcare cognitive services valuation multiples.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Certification Investment | EU AI Act conformity assessments create first-mover procurement advantages in German and French public sector tenders. |
| Sovereign Cloud Infrastructure Deployment | Mumbai and Hyderabad regions satisfy RBI data localization mandates for financial services contracts. |
| Synthetic Data Generation Capability | Differentially private training pipelines circumvent GDPR restrictions for European banking model development. |
| Edge Inference Hardware Integration | On-premise neural accelerators capture Japanese automotive quality inspection demand below 50-millisecond latency thresholds. |
| Vertical Acquisition of Training Data Assets | São Paulo hospital network partnerships accelerate ANVISA pathway for Latin American diagnostic imaging market entry. |
Research Methodology
Desk research of hyperscaler capex disclosures, regulatory filing databases, and cloud infrastructure deployment announcements preceded structured interviews with enterprise AI procurement officers, clinical informatics directors, regulatory affairs leads at cognitive services vendors, and MLOps engineering managers. Secondary validation drew from FDA 510(k) clearance databases, EU notified body conformity assessment registries, and national cloud infrastructure investment trackers. Bottom-up deployment estimates triangulated against top-down enterprise IT spending allocations.
Assumptions held fixed include prevailing export control regimes on advanced semiconductors, phased EU AI Act enforcement timelines, and sustained hyperscaler cloud region expansion rates across the analysis window. Segmentation modeling incorporated service type, deployment architecture, end-use industry, and geographic regulatory cluster. CAGRs derived from slope-intercept fitting of disclosed vendor revenue growth and enterprise survey-based adoption curve projections. Forecast inputs included foundry capacity expansion schedules and sovereign data center construction permits.
Stress conditions across GPU supply availability, regulatory enforcement intensity, and enterprise AI budget cyclicality were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding training cluster cost curves and inference latency requirements. Material shifts in US-China semiconductor trade policy or EU AI Act liability interpretations would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Artificial Intelligence (AI)
AI Code Assistant Market
Artificial Intelligence (AI)
Global Voice Assistant Market
Artificial Intelligence (AI)
Artificial Intelligence Based Personalization Market
Artificial Intelligence (AI)
Enterprise Generative AI Market
Artificial Intelligence (AI)
Multimodal AI Market
Artificial Intelligence (AI)
North America Artificial Intelligence Market
Artificial Intelligence (AI)
AI Orchestration Market
Artificial Intelligence (AI)
Decision Intelligence Market
Artificial Intelligence (AI)
Global Artificial Intelligence (AI) Hardware Market
Artificial Intelligence (AI)
AI Text Generator Market
Artificial Intelligence (AI)
Global Ambient Intelligence Market
Artificial Intelligence (AI)
AI Search Engine Market
Artificial Intelligence (AI)
North America Chatbot Market
Artificial Intelligence (AI)
Content Automation AI Tools Market
Artificial Intelligence (AI)
Global Insight Engines Market
Artificial Intelligence (AI)
Edge AI Software Market