
 Europe Synthetic Data Generation Market | 2026-2036
Europe Synthetic Data Generation Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Synthetic Data Generation Market Analytics
Enterprise software procurement channels across Europe are being redrawn as synthetic data vendors bypass traditional IT distributors and sell directly to line-of-business buyers. This channel shift is reshaping how MOSTLY AI Solutions MP GmbH reaches healthcare and banking clients in Vienna and Berlin. NVIDIA Corporation leverages its GPU cloud infrastructure to embed synthetic data tools within broader AI development workflows. Statice GmbH anchors its position through deep specialization in privacy-preserving tabular data for German insurers and pharmaceutical researchers.
Europe Synthetic Data Generation produces artificial datasets through algorithmic models that replicate statistical properties of real information without exposing identifiable records, typically employing differential privacy thresholds and generative adversarial network architectures to preserve utility while eliminating re-identification risk. Its primary commercial purpose enables AI model training, software testing, and analytics in jurisdictions where raw personal data usage faces strict legal constraints. Tabular data generation dominates current revenue as banks and insurers in Frankfurt and Zurich replace sensitive customer records for fraud detection development. Generative Adversarial Networks represent the fastest-expanding technique category, driven by automotive manufacturers in Stuttgart and Munich requiring photorealistic synthetic imagery to train autonomous driving perception systems without costly field data collection.
GDPR enforcement by national data protection authorities across EU member states directly elevates demand for compliant synthetic alternatives that fall outside personal data classification. The EU AI Act's conformity assessment requirements for high-risk AI applications reinforce this regulatory pull, particularly for healthcare and financial services deployers in Paris, Amsterdam, and Milan. BSI and DIN standards development in Germany adds technical credibility layers that influence procurement specifications. Stakeholders must monitor how upcoming delegated acts under the AI Act define data quality benchmarks, as these will determine whether synthetic outputs qualify for regulatory safe harbors in regulated deployment scenarios.
Market Dynamics
The EU AI Act's risk-classification framework is forcing financial institutions and healthcare providers across the continent to abandon raw personal datasets in favor of privacy-preserving synthetic alternatives that satisfy conformity assessment requirements.
Growth Catalysts
- GDPR Enforcement:National data protection authorities in Germany, France, and the Netherlands are classifying synthetic outputs as non-personal data, removing legal barriers to cross-border AI training workflows.
- Automotive Computer Vision:Original equipment manufacturers in Stuttgart and Munich require photorealistic synthetic imagery to train autonomous driving perception systems without costly field data collection campaigns.
- Generative Adversarial Networks:This technique category is displacing simpler statistical methods in pharmaceutical research clusters, enabling replication of complex longitudinal patient records with preserved correlations.
Market Restraints
- Computational Infrastructure Costs:Training large generative models demands sustained access to GPU clusters, creating dependency on cloud providers with limited European sovereign alternatives.
- Technical Validation Gaps:Absence of harmonized benchmarks for synthetic data fidelity forces buyers to conduct expensive in-house utility testing before regulatory submission.
- Substitution from Federated Learning:Some healthcare networks in Switzerland and Austria are deploying federated analytics as an alternative privacy architecture, reducing synthetic data budgets.
Strategic Opportunities
- Underpenetrated Nordic Markets:Sweden and Denmark maintain nascent synthetic data adoption in life sciences despite strong pharmaceutical manufacturing bases, presenting first-mover expansion potential.
- CSRD-Aligned ESG Reporting:The Corporate Sustainability Reporting Directive creates demand for synthetic operational datasets that enable carbon footprint modeling without exposing supplier commercial data.
- Convergence with Digital Twins:Industrial AI developers in Milan and Turin are combining synthetic data generation with physics-based simulation to compress product development cycles.
Industry Challenges
- Differential Privacy Expertise Scarcity:Implementation of mathematically rigorous privacy guarantees requires rare cross-training in cryptography and domain statistics, constraining vendor scaling.
- Legacy System Integration Friction:Banks in Frankfurt and Zurich face complex API reconfiguration to pipe synthetic datasets into established fraud detection pipelines without disrupting production environments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Synthetic Data Generation Market |
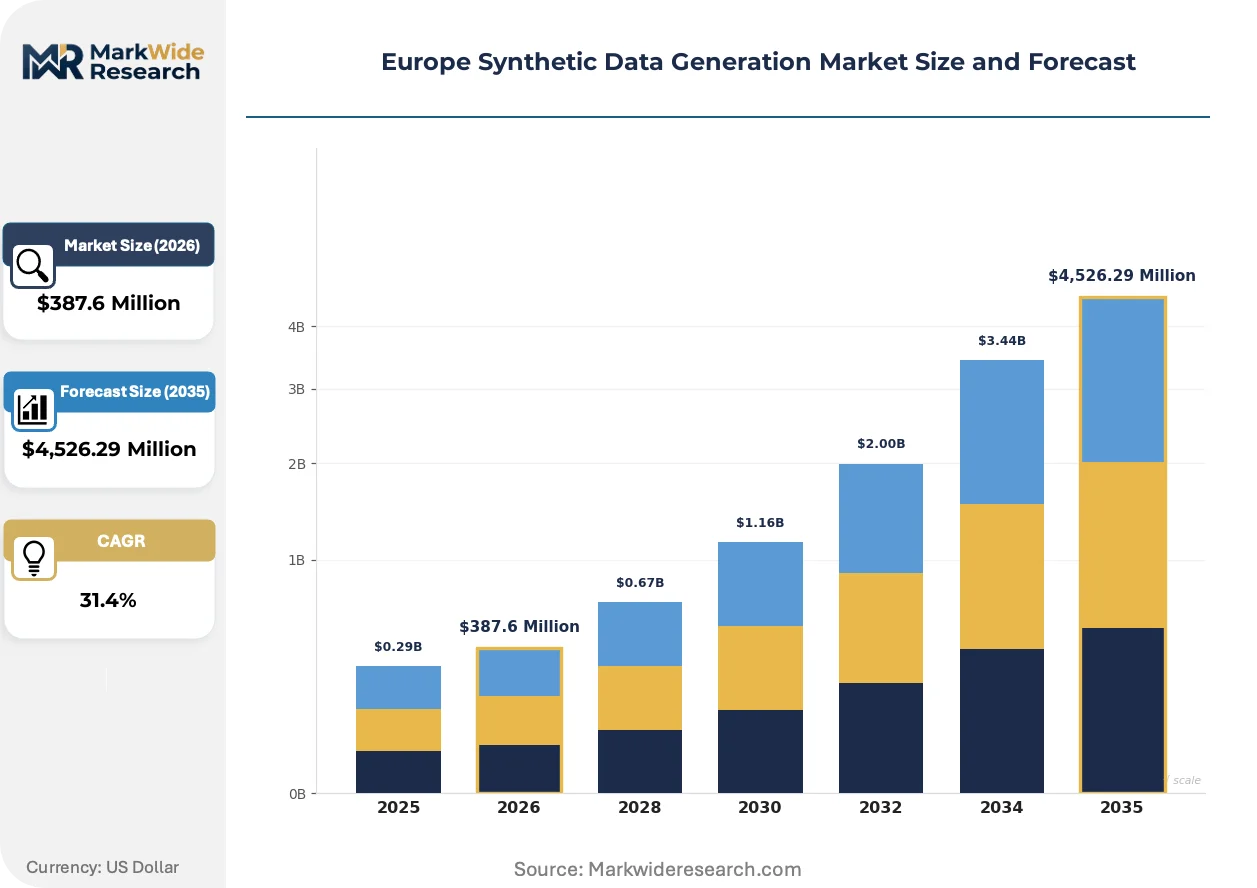
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $4,526.29 Million |
| CAGR (2026 – 2036) | 31.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Text Data, Image Data, Video Data, Tabular Data End User: Healthcare, Finance, Retail, Telecommunications Deployment: Cloud-Based, On-Premises, Hybrid, Edge Computing Generation Technique: Rule-Based, Machine Learning, Simulation, Generative Adversarial Networks |
| Companies Covered | MOSTLY AI Solutions MP GmbH, Statice GmbH, Hazy Limited, Synthesis AI, Inc., YData, MDClone Limited, Gretel.ai, Tonic.ai, NVIDIA Corporation, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Synthetic Data Generation Market Evolving Landscape
Foundation model architectures are compressing the cost structure of synthetic data production while expanding the modalities beyond tabular records into three-dimensional sensor simulations and multimodal clinical documentation.
Diffusion-based generative models are digitizing the production of synthetic medical imaging, with radiology departments in Paris and Berlin adopting these tools to augment limited pathology datasets for rare disease AI training. Academic medical centers are replacing traditional data-sharing agreements with synthetic data exchanges that preserve institutional control over intellectual property. This shift is digitizing collaboration patterns that previously required months of legal negotiation.
The EU AI Act's delegated acts on data quality benchmarks are compelling vendors to document provenance and transformation pipelines for synthetic training sets used in high-risk applications. Financial services deployers in Amsterdam and Milan must now maintain technical documentation demonstrating that synthetic outputs meet statistical equivalence thresholds. This regulatory layering is creating certification-driven vendor selection criteria that favor established providers with audit-ready governance frameworks.
Line-of-business buyers in healthcare and automotive sectors are disintermediating traditional IT procurement channels, purchasing synthetic data tools through direct vendor relationships rather than enterprise software distributors. This pattern concentrates most visibly in Germany's industrial AI clusters, where engineering teams specify synthetic sensor datasets independently of central IT. The resulting channel fragmentation is compressing sales cycles but complicating enterprise-wide standardization efforts.
Europe Synthetic Data Generation Market Segmentation
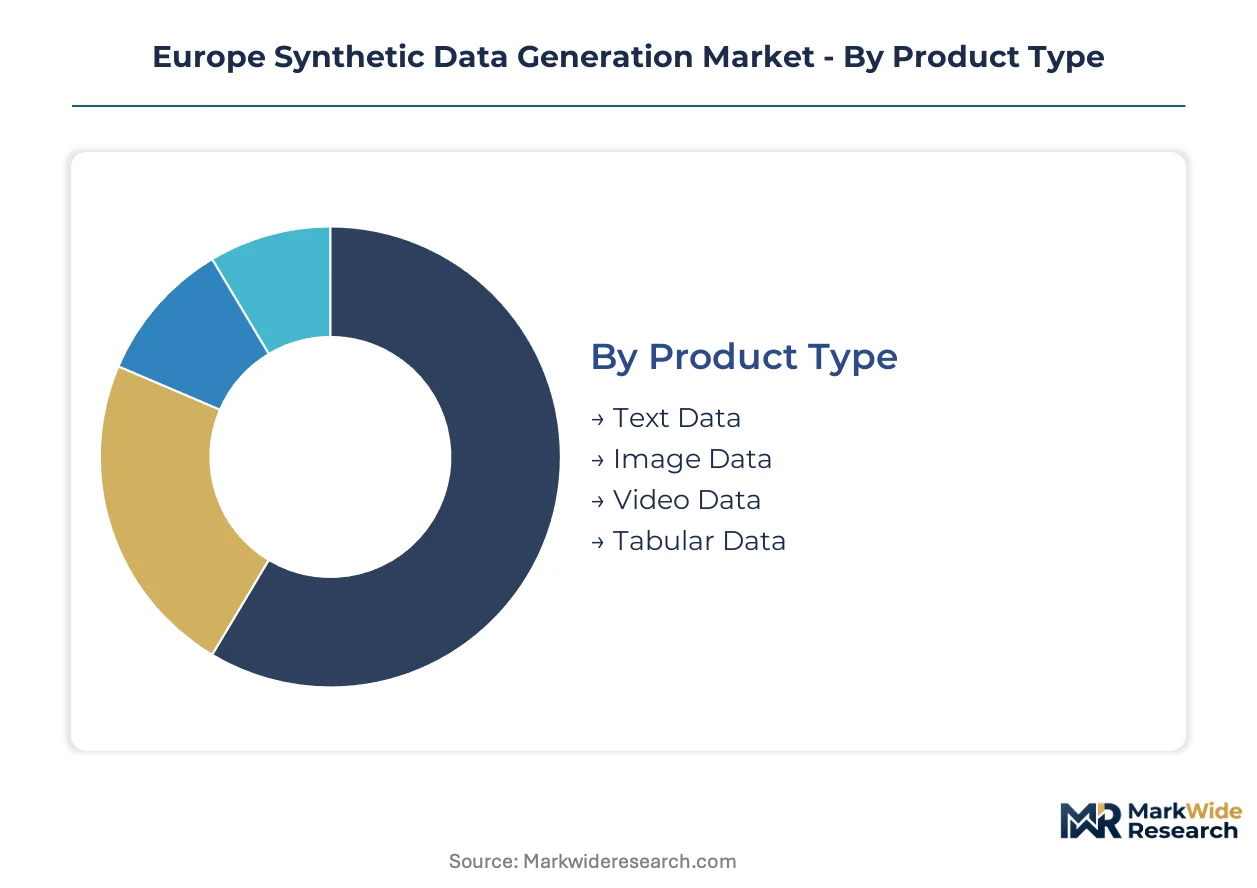
Synthetic data vendors in Europe structure their offerings around distinct technical and commercial boundaries that determine pricing architecture and customer engagement intensity. Each segment carries different service requirements, integration complexity, and regulatory documentation burdens that reshape go-to-market economics across the continent.
Product Type:
After-sales service intensity varies sharply across product categories, with tabular and image data requiring sustained engineering support while text and video segments demand lighter touch maintenance.
- Tabular Data:Structured numerical and categorical records replicate customer transactions, claims histories, and operational metrics with preserved statistical distributions. German insurers in Frankfurt and Munich deploy these datasets for fraud model development under BSI audit requirements. The format demands continuous schema validation and differential privacy calibration that locks vendors into multi-year service relationships.
- Image Data:Photorealistic synthetic imagery trains computer vision systems for defect detection, medical diagnostics, and autonomous perception. Automotive OEMs in Stuttgart source these datasets to simulate rare edge cases without field deployment costs. Technical support concentrates on rendering pipeline optimization and domain-specific augmentation protocols.
- Text Data:Synthetic documents and conversational records enable natural language processing training while scrubbing personally identifiable information. Financial services deployers in Amsterdam use these outputs for sentiment analysis and document classification workflows.
- Video Data:Temporal sequences combining synthetic imagery with motion modeling support action recognition and predictive behavior systems. Demand remains nascent outside defense and advanced manufacturing clusters in France and Sweden.
Tabular data holds the largest share; momentum sits with image data.
End User:
Customer archetypes diverge by procurement maturity, with healthcare and finance operating centralized vendor management while retail and telecommunications favor decentralized experimentation.
- Healthcare:Academic medical centers and pharmaceutical manufacturers in Berlin, Paris, and Basel replace patient records with synthetic equivalents for AI diagnostic training. EMA guidelines and national ethics boards impose documentation standards that extend sales cycles but secure long-term contracts.
- Finance:Banks and insurers in Zurich, Frankfurt, and Amsterdam face EU AI Act conformity assessments that mandate synthetic alternatives for high-risk credit scoring and fraud detection models. Procurement teams require audit trails proving statistical equivalence to source datasets.
- Retail:E-commerce platforms and consumer goods manufacturers apply synthetic customer behavior data to demand forecasting and personalization engines. Adoption concentrates in London and Paris with lighter regulatory overlay.
- Telecommunications:Network operators generate synthetic traffic patterns and user mobility data to optimize infrastructure planning. Nordic operators in Stockholm and Copenhagen lead deployment for 5G network simulation.
Finance commands current revenue concentration; healthcare is climbing the fastest.
Deployment:
Infrastructure configuration determines data sovereignty compliance and latency sensitivity, with hybrid architectures gaining traction among multi-jurisdictional enterprises.
- Cloud-Based:Scalable compute resources hosted by European sovereign cloud providers enable rapid model training without capital expenditure. French healthcare networks favor this model for burst workloads in radiology AI development.
- On-Premises:Dedicated hardware installations satisfy strictest GDPR interpretations and national security requirements. German automotive manufacturers in Munich mandate this configuration for proprietary design data.
- Hybrid:Split architectures process sensitive raw data locally while synthetic generation and model training leverage cloud elasticity. Swiss banks in Zurich deploy this pattern to balance privacy with computational scale.
- Edge Computing:Distributed generation at sensor locations reduces transmission latency for real-time autonomous systems. Industrial IoT deployments in Turin and Milan test this architecture for predictive maintenance.
Cloud-based deployment holds the largest share; hybrid configurations are gaining share fastest.
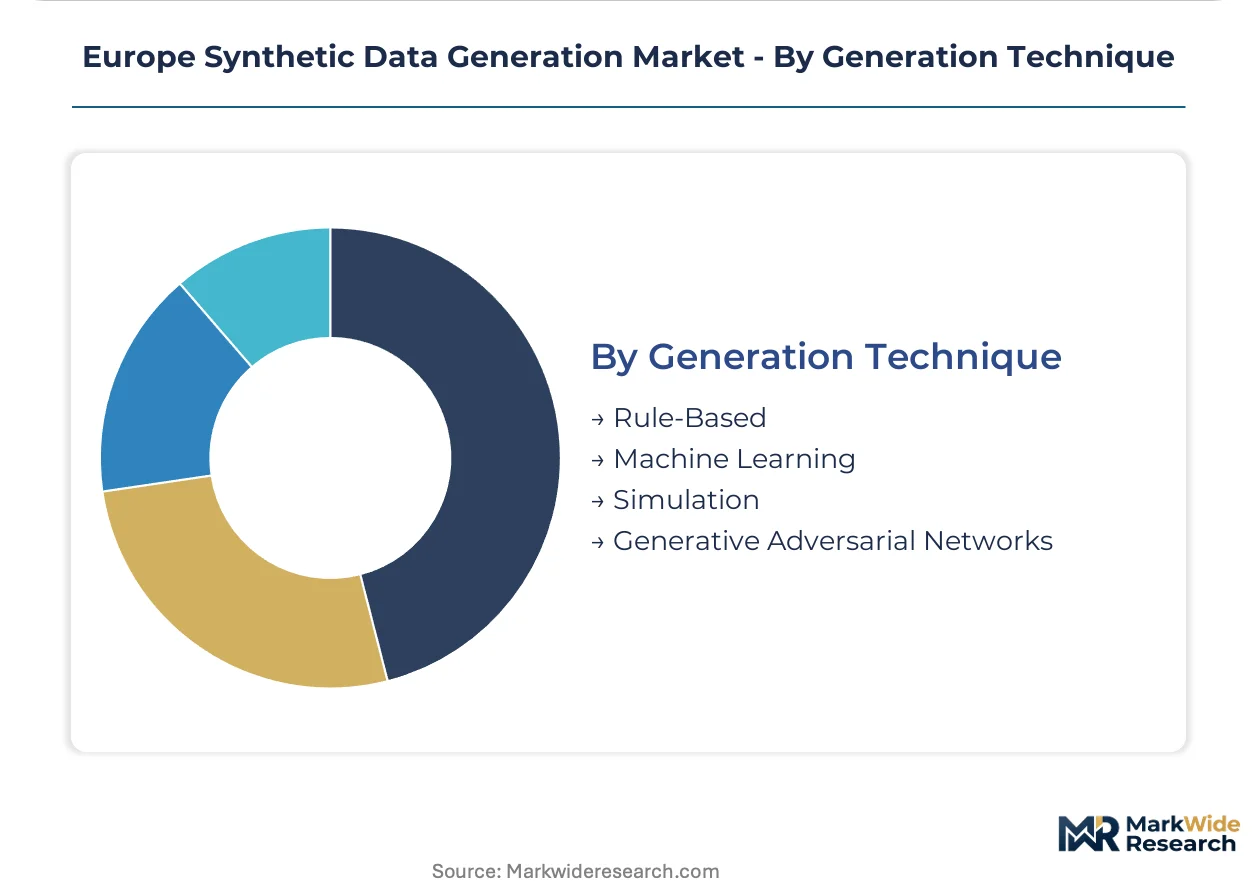
Generation Technique:
Technical sophistication tiers separate established statistical methods from emerging deep learning architectures, with implementation cost and expertise requirements widening the competitive moat.
- Generative Adversarial Networks:Adversarial training architectures produce high-fidelity synthetic records by pitting generator and discriminator networks against each other. Automotive perception teams in Stuttgart rely on GANs for photorealistic driving scene synthesis where statistical methods fail. The technique demands GPU clusters and specialized ML engineering that limits vendor proliferation.
- Machine Learning:Supervised and unsupervised learning approaches beyond GANs, including variational autoencoders and flow-based models, capture complex multivariate relationships in structured data. Pharmaceutical researchers in Basel apply these methods to longitudinal patient record synthesis.
- Simulation:Physics-based and agent-based models generate synthetic data from first principles rather than statistical replication. Aerospace and industrial engineering clusters in Toulouse and Hamburg favor this approach for safety-critical system validation.
- Rule-Based:Deterministic algorithms apply predefined transformation rules to mask or perturb source data. Smaller insurers in Vienna and Prague retain this lower-cost approach for compliance-driven use cases with modest fidelity requirements.
Machine learning techniques hold the largest installed base; generative adversarial networks show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German synthetic data vendors command pricing premiums 20-30% above Spanish and Italian counterparts, reflecting tighter GDPR enforcement and BSI certification requirements that buyers in Düsseldorf and Frankfurt treat as non-negotiable procurement filters.
Germany
Automotive OEMs in Stuttgart and Munich drive demand for photorealistic synthetic imagery to train autonomous perception systems without field deployment costs. BSI and DIN standards development adds technical credibility layers that shape procurement specifications for insurers in Frankfurt. Industrial AI clusters in Bavaria and Baden-Württemberg combine synthetic data with physics-based simulation to compress product development cycles.
France
Academic medical centers in Paris replace traditional data-sharing agreements with synthetic patient record exchanges that preserve institutional IP control. ANSM and CNIL guidance on synthetic data classification removes legal barriers to cross-border AI training workflows. Radiology departments across Île-de-France adopt diffusion-based generative models to augment limited pathology datasets for rare disease AI training.
United Kingdom
Financial services deployers in London face EU AI Act conformity assessment requirements that mandate synthetic alternatives for high-risk credit scoring models. The Information Commissioner's Office enforcement posture elevates demand for compliant synthetic alternatives that fall outside personal data classification. Fintech clusters in London and Edinburgh experiment with synthetic customer behavior data for demand forecasting engines.
Switzerland
Swissmedic guidance and FINMA expectations drive pharmaceutical researchers in Basel toward longitudinal patient record synthesis with preserved correlations. Some healthcare networks deploy federated analytics as an alternative privacy architecture, creating competitive tension with synthetic data budgets. Banks in Zurich mandate hybrid deployment configurations to balance privacy with computational scale for fraud detection pipelines.
Netherlands
Financial services deployers in Amsterdam must maintain technical documentation demonstrating that synthetic outputs meet statistical equivalence thresholds under EU AI Act delegated acts. The Dutch Data Protection Authority classifies synthetic outputs as non-personal data, accelerating cross-border AI training workflows. Eindhoven's semiconductor equipment manufacturers apply synthetic sensor data to optimize predictive maintenance models.
Europe Synthetic Data Generation Market Competitive Landscape
Specialized privacy-preserving vendors and GPU-cloud infrastructure providers split the market along capability lines, with the former commanding service-intensive multi-year contracts and the latter embedding tools within broader AI development workflows. The vendor base clusters around three strategic archetypes: differential privacy specialists anchoring regulated healthcare and finance verticals, generative model platforms serving automotive computer vision teams, and cloud-native suites targeting line-of-business buyers outside central IT procurement. Dominant competitive moves include direct sales channel expansion that bypasses traditional IT distributors, and vertical integration into sovereign cloud infrastructure to address data residency requirements.
Within the specialized privacy-preserving tier, MOSTLY AI Solutions MP GmbH and Statice GmbH exemplify vendors that have built defensible positions through deep domain specialization in GDPR-compliant tabular data. NVIDIA Corporation occupies a scale-driven position leveraging GPU cloud infrastructure to embed synthetic generation within end-to-end AI development pipelines. These three anchors illustrate how competitive positioning in this market depends on choosing between vertical depth in regulated industries and horizontal breadth across AI infrastructure layers.
| Leading Market Players |
|---|
| MOSTLY AI Solutions MP GmbH |
| Statice GmbH |
| Hazy Limited |
| Synthesis AI, Inc. |
| YData |
| MDClone Limited |
| Gretel.ai |
| Tonic.ai |
| NVIDIA Corporation |
| Others |
Value Network & Pricing Analysis
Stuttgart's automotive AI cluster concentrates GPU cloud capacity and differential privacy engineering talent, creating localized pricing power for vendors serving German OEMs while compressing margins for standardized tabular data offerings elsewhere in Europe.
Pricing Analysis
Customization-premium spreads separate configured-to-order synthetic data pipelines from standard SaaS tiers. Subscription models dominate, with pricing stratifying across differential privacy certification grade, schema complexity, and after-sales engineering intensity. Cost compression in standardized tabular generation is intensifying because cloud-native entrants are automating schema validation. Mid-sized insurers in Vienna and Prague exhibit highest price sensitivity, while Stuttgart automotive perception teams accept 40-50% premiums for photorealistic edge-case imagery with guaranteed statistical fidelity.
Supply Chain Analysis
US export controls on advanced GPU architectures constrain compute availability for European synthetic data vendors training large generative models. Supply concentrates in Taiwan's semiconductor foundries, Ireland's hyperscaler regions, and Germany's sovereign cloud initiatives. The value chain draws from NVIDIA's GPU allocations, European sovereign infrastructure investments, and specialized differential privacy engineering pools. Single-source vulnerability around CUDA-dependent training frameworks creates structural risk. Distribution runs through direct vendor relationships with line-of-business buyers, bypassing traditional IT distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
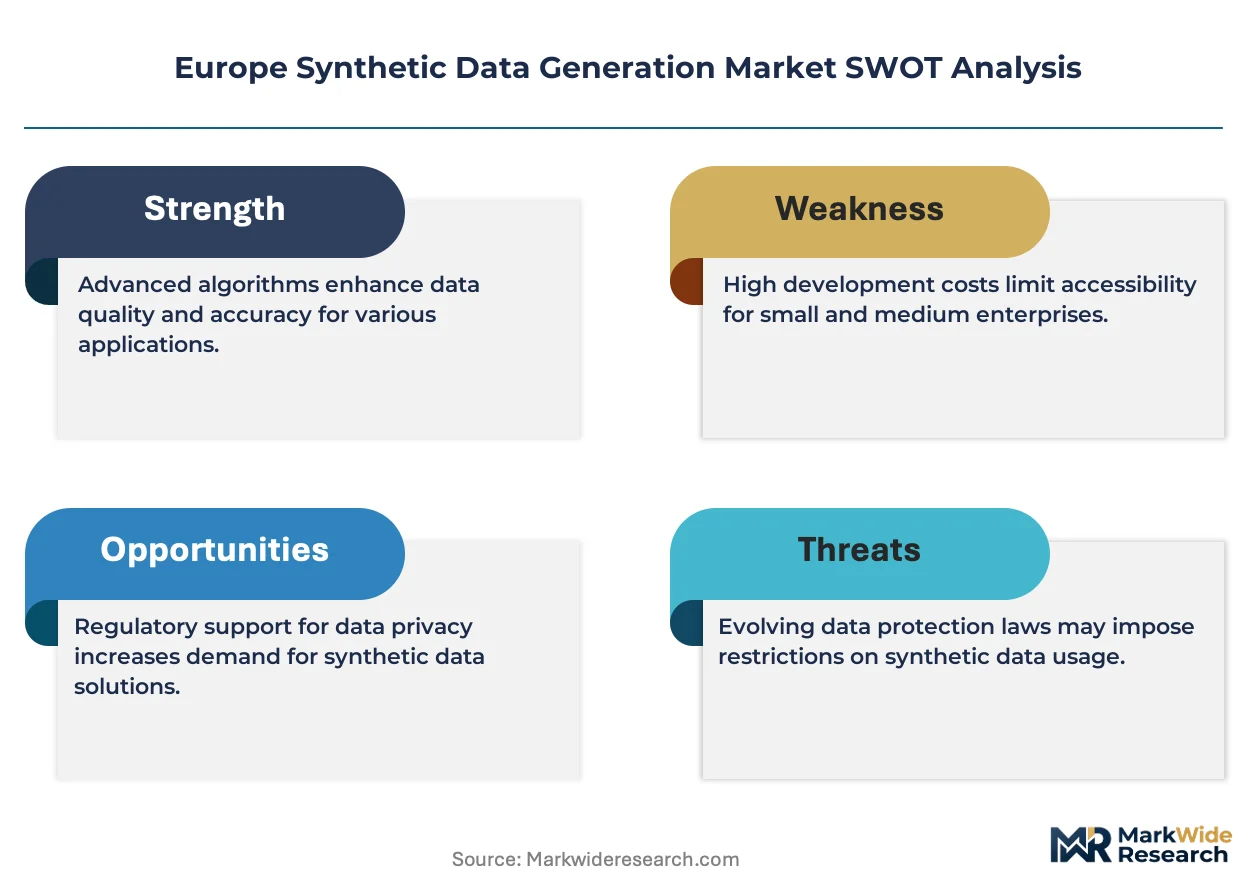
Federated learning architectures threaten synthetic data budgets in healthcare networks, forcing incumbents to demonstrate superior statistical fidelity or risk substitution in high-value pharmaceutical research contracts.
For Market Incumbents: Harden defensible positions through backward integration into sovereign GPU cloud infrastructure, addressing data residency requirements that federated learning cannot satisfy. Deepen vertical capabilities in EMA-aligned documentation standards for high-risk AI applications. Certification investment in BSI and DIN frameworks creates switching costs that alternative privacy architectures cannot replicate.
For New Entrants and Emerging Players: Nordic life sciences clusters present underpenetrated expansion terrain despite strong pharmaceutical manufacturing bases in Stockholm and Copenhagen. Target CSRD-aligned ESG reporting use cases where synthetic operational datasets enable carbon footprint modeling without exposing supplier commercial data. Lead with hybrid deployment architectures that Swiss banks and German manufacturers increasingly specify.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors differential privacy specialists with audit-ready governance frameworks over horizontal AI infrastructure plays. Long-term viability hinges on regulatory safe harbor qualification under EU AI Act delegated acts. Acquisition targets should demonstrate proven statistical equivalence documentation for high-risk deployment scenarios. Monitor ANSM and CNIL guidance evolution on synthetic data classification as the critical inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Sovereign Cloud Infrastructure Investment | Addresses GDPR data residency requirements that federated learning competitors cannot match for German automotive OEMs. |
| EMA-Aligned Documentation Certification | Enables high-risk AI Act conformity assessments for Basel pharmaceutical researchers deploying longitudinal patient synthesis. |
| Direct Line-of-Business Channel Expansion | Bypasses IT procurement bottlenecks in Stuttgart industrial AI clusters where engineering teams specify synthetic sensor datasets. |
| Physics-Based Simulation Convergence | Compresses product development cycles for Milan and Turin industrial AI developers combining synthetic data with digital twins. |
| Diffusion Model Architecture Migration | Captures radiology AI demand in Paris and Berlin departments augmenting limited pathology datasets for rare disease training. |
Research Methodology
Operator-level perspectives from synthetic data platform engineers, GDPR compliance officers at German insurers, automotive perception team leads in Stuttgart, and pharmaceutical biostatisticians in Basel anchored the qualitative base. Primary interviews combined with secondary validation from EMA guideline documents, EU AI Act delegated act drafts, BSI certification standards, and hyperscaler capex disclosures. Bottom-up segment sizing triangulated against top-down regulatory demand modeling.
Scenario-bracketing framed projections across the analysis window, with segmentation dimensions spanning data modality, deployment architecture, generation technique sophistication, and end-user vertical regulatory intensity. CAGRs derived from differential adoption curves across GDPR enforcement tiers and EU AI Act implementation phases. Forecast inputs incorporated GPU cloud capacity expansion timelines and differential privacy engineering labor supply constraints.
Practitioners should monitor delegated act publication on data quality benchmarks and national data protection authority enforcement postures for early signals. Forecasts reflect documented assumptions around regulatory timeline adherence and sovereign infrastructure investment continuity. Material shifts in EU AI Act high-risk classification scope or export control expansion would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Artificial Intelligence (AI)
Mlops Market
Artificial Intelligence (AI)
Artificial Intelligence (AI) Assisted Robots Market
Artificial Intelligence (AI)
Digital Intelligence Technology Market
Artificial Intelligence (AI)
Text-To-Speech (TTS) Market
Artificial Intelligence (AI)
Global Voice Cloning Market
Artificial Intelligence (AI)
Asia-Pacific Generative AI Market
Artificial Intelligence (AI)
Voice Assistance Application Market
Artificial Intelligence (AI)
AI Consulting Services Market
Artificial Intelligence (AI)
Edge AI Hardware Market
Artificial Intelligence (AI)
Artificial Intelligence-Based Security Market
Artificial Intelligence (AI)
Conversation Intelligence Software Market
Artificial Intelligence (AI)
AI Orchestration Market
Artificial Intelligence (AI)
Artificial Intelligence (AI) in Social Media Market
Artificial Intelligence (AI)
MENA Artificial Intelligence Market
Artificial Intelligence (AI)
Latin America Artificial Intelligence Market
Artificial Intelligence (AI)
AI Watermarking Market