
 Human-Computer Interaction (HCI) Market | 2026-2036
Human-Computer Interaction (HCI) Market Size, Share, and Industry Trends Forecast 2026-2036
Human-Computer Interaction (HCI) Market Foresight
Silicon Valley's semiconductor foundry cluster is pivoting toward dedicated neural processing capacity for next-generation interface hardware. Nvidia leverages its CUDA ecosystem to anchor high-performance computing substrates for real-time gesture rendering. Microsoft sustains enterprise-grade voice interface deployments through Azure cognitive services infrastructure. Apple differentiates via proprietary spatial computing silicon and closed-loop sensor fusion architectures.
Human-Computer Interaction encompasses the design, evaluation, and implementation of interactive computing systems, incorporating haptic feedback loops operating at sub-20 millisecond latency thresholds and multimodal input fusion algorithms for commercial and industrial deployment. Voice Recognition technology leads current enterprise procurement cycles due to measurable productivity gains in call center and documentation workflows. Brain-Computer Interface represents the fastest-expanding segment as neural signal decoding accuracy crosses clinical viability thresholds for assistive device control. Gesture Control commands premium pricing in automotive and surgical environments where touchless operation reduces contamination risk.
FDA scrutiny of neurostimulation interfaces intensifies premarket validation requirements for Brain-Computer Interface developers targeting therapeutic applications. The EU AI Act imposes conformity assessment obligations on biometric emotion recognition systems, directly constraining Natural Language Processing deployment architectures across European enterprise software. China's MIIT issues dedicated GB standards for intelligent human-machine interaction terminals, shaping domestic procurement specifications for touchscreen and voice-enabled industrial panels. Stakeholders must monitor regulatory divergence between jurisdictional frameworks when architecting multimodal interface product roadmaps.
Market Dynamics
The convergence of sub-20 millisecond haptic latency requirements with multimodal sensor fusion architectures is compressing vendor differentiation windows and forcing rapid capability consolidation across interface hardware suppliers.
Growth Catalysts
- Germany's industrial automation corridor:Automotive OEMs and precision manufacturers are deploying gesture-controlled assembly lines to minimize contamination in cleanroom environments.
- EU AI Act biometric governance:Conformity assessment obligations for emotion recognition systems are creating compliance-driven procurement specifications that favor certified interface vendors.
- Neural signal decoding accuracy:Clinical viability thresholds for assistive device control are expanding Brain-Computer Interface addressable populations beyond early-adopter disability segments.
Market Restraints
- Neurostimulation validation costs:FDA premarket requirements for therapeutic Brain-Computer Interfaces impose 18-36 month certification timelines that freeze smaller developers' capital deployment.
- Specialized foundry concentration:Dedicated neural processing capacity resides with a narrow Taiwan-South Korea manufacturing base, creating single-source vulnerability for next-generation interface silicon.
- Optical gesture recognition limitations:Ambient light interference and occlusion handling constraints restrict automotive deployment to controlled cabin environments.
Strategic Opportunities
- China's MIIT GB standards:Intelligent human-machine interaction terminal specifications are reshaping domestic procurement for voice-enabled industrial panels, creating compliant vendor preference.
- Touchless surgical interfaces:Contamination risk reduction mandates in US and EU hospital systems are accelerating gesture control adoption in operating theaters.
- Spatial computing convergence:Proprietary sensor fusion architectures combining LiDAR, eye-tracking, and hand gesture inputs are opening enterprise training and remote collaboration verticals.
Industry Challenges
- Multimodal algorithm integration:Fusing voice, gesture, and haptic feedback loops requires scarce expertise in real-time sensor calibration and latency synchronization.
- Legacy system interoperability:Enterprise voice interface deployments face friction integrating with decades-old call center infrastructure and proprietary CRM databases.
- Biometric data liability exposure:Cross-border neural signal storage and emotion recognition data processing trigger divergent GDPR, HIPAA, and China's PIPL compliance architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Human-Computer Interaction (HCI) Market |
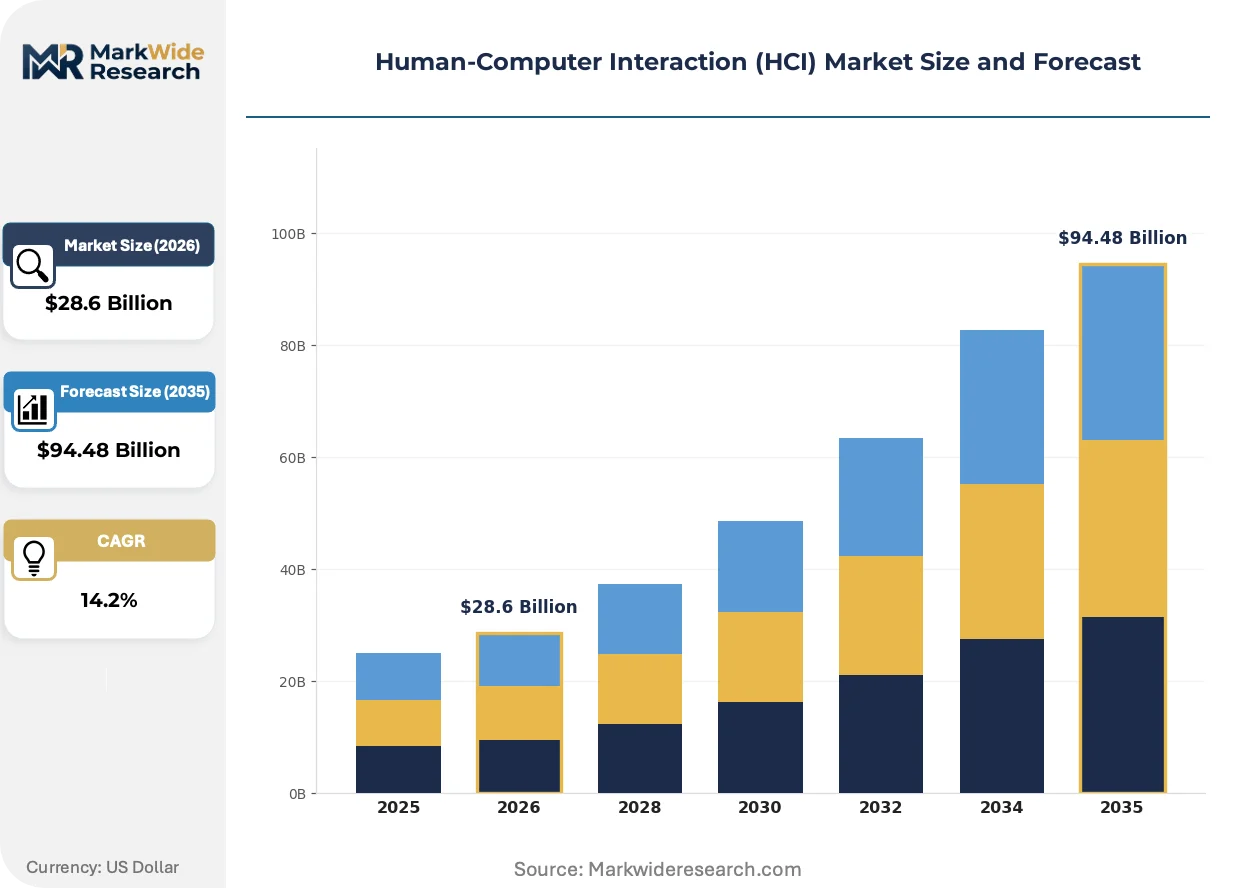
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $94.48 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Touchscreen, Voice Recognition, Gesture Control, Brain-Computer Interface Application: Gaming, Education, Healthcare, Smart Homes User Interface: Graphical User Interface, Voice User Interface, Natural Language Processing, Augmented Reality End User: Consumers, Enterprises, Developers, Researchers |
| Companies Covered | Meta Platforms, Adobe, Microsoft, Nvidia, IBM, Alphabet, Amazon, Oracle, Apple, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Human-Computer Interaction (HCI) Market Shifts & Advancements
Neural processing unit integration at the edge is collapsing the latency-performance tradeoff that previously forced cloud-dependent architectures, while regulatory fragmentation between biometric governance frameworks is fragmenting product roadmaps.
Edge-deployed neural inference engines are consolidating voice and gesture processing onto single-chip substrates that eliminate round-trip cloud latency. Automotive Tier 1 suppliers are qualifying these consolidated architectures for cabin monitoring and infotainment control. The shift is compressing value capture away from cloud API providers toward semiconductor and embedded software vendors.
The EU AI Act's emotion recognition prohibitions in workplace and educational settings are forcing Natural Language Processing vendors to strip affective computing modules from European deployments. Industrial software providers are responding with jurisdiction-specific product variants that disable biometric inference for EU endpoints while retaining full functionality elsewhere.
Hospital procurement committees are mandating touchless interface specifications in infection-sensitive departments, displacing traditional touchscreen panels in surgical suites and intensive care units. US health systems are leading this specification shift, with EU facilities following through MDR-linked hygiene protocols. Vendor sales cycles are elongating as clinical validation requirements expand beyond technical performance to workflow integration studies.
Human-Computer Interaction (HCI) Market Segmentation
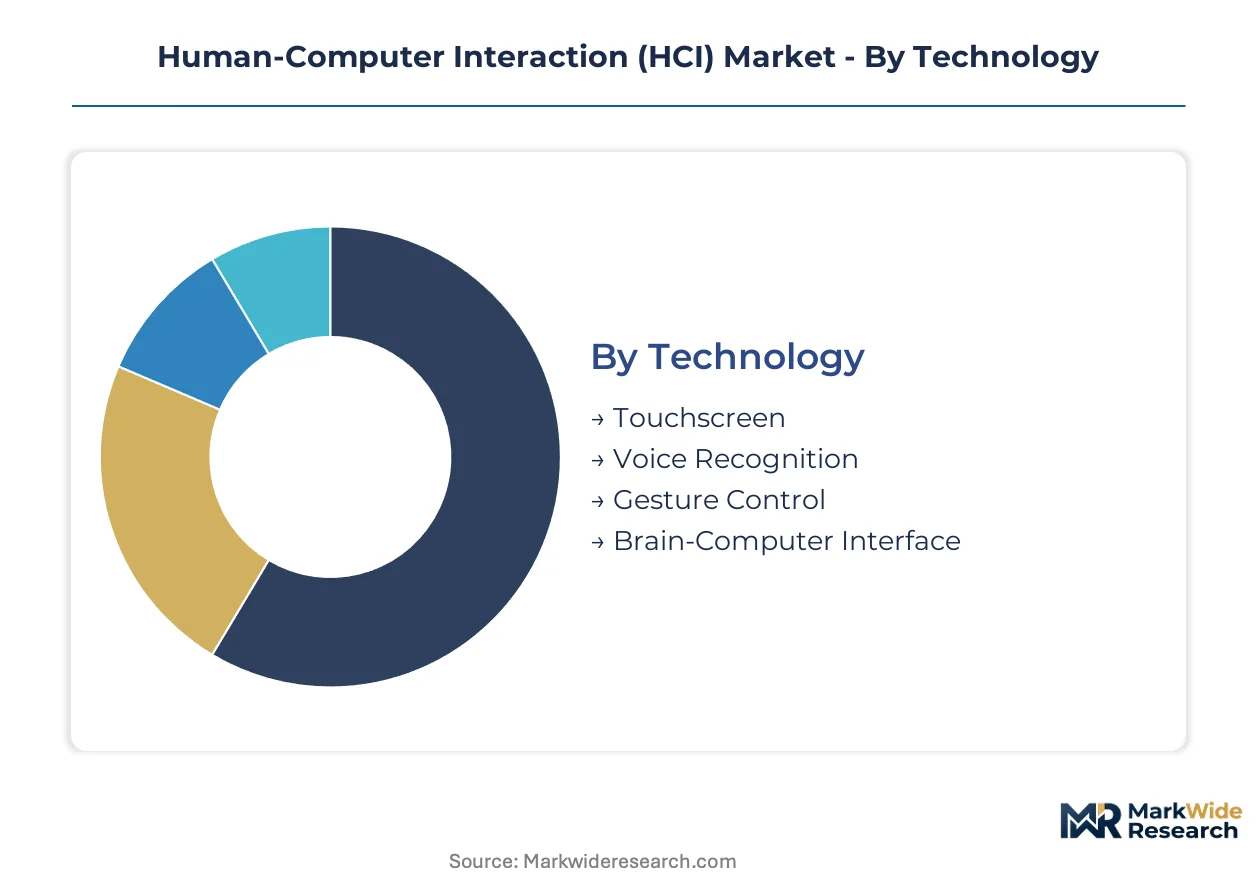
Technology refresh cycles in interface hardware compress replacement windows to 18-36 months, forcing procurement committees to weigh backward compatibility against performance gains. Segmentation reveals where upgrade urgency concentrates across clinical, industrial, and consumer deployment contexts.
Technology:
Replacement urgency varies sharply by latency sensitivity and contamination risk, with surgical and automotive environments demanding shortest upgrade cycles.
- Voice Recognition:Cloud-dependent acoustic models and on-device neural inference engines power enterprise call center automation and clinical documentation workflows. Demand concentrates in US healthcare systems pursuing HIPAA-compliant ambient documentation, constrained by legacy telephony infrastructure integration costs.
- Brain-Computer Interface:Implanted and non-invasive neural signal acquisition systems decode motor intent for assistive device control. Demand concentrates in US and European rehabilitation clinics as FDA and EMA premarket pathways clarify, though 18-36 month validation timelines freeze smaller developers' capital deployment.
- Gesture Control:Optical and radar-based skeletal tracking enables touchless operation in contamination-sensitive environments.
- Touchscreen:Capacitive and resistive panels remain dominant in consumer electronics and industrial control terminals.
Voice Recognition sits at the top of the volume ranking, with Brain-Computer Interface climbing the fastest.
Application:
Cost tier stratification separates premium clinical deployments from mass-market consumer implementations, with middleware and integration services capturing differential margin.
- Healthcare:Surgical gesture control, neural rehabilitation interfaces, and ambient clinical documentation systems demand sub-20 millisecond latency and FDA/EMA validation. German hospital procurement committees now mandate touchless specifications in infection-sensitive departments, displacing traditional touchscreen panels.
- Smart Homes:Voice-controlled environmental management and gesture-activated entertainment systems integrate with existing IoT device ecosystems. Demand concentrates in North American and European residential construction as building codes incorporate accessibility requirements, constrained by fragmented protocol standards.
- Gaming:Haptic feedback peripherals and motion capture systems target enthusiast segments with premium pricing.
- Education:Immersive AR/VR learning environments and voice-enabled accessibility tools serve institutional procurement.
Healthcare commands premium pricing tiers, with Smart Homes expanding most quickly through residential construction integration.
User Interface:
Supply concentration in neural processing silicon favors vendors with captive foundry relationships or long-term capacity agreements.
- Natural Language Processing:Transformer-based language models and intent classification systems power enterprise virtual assistants and clinical decision support. EU AI Act emotion recognition prohibitions force vendors to strip affective computing modules from European deployments, creating jurisdiction-specific product variants.
- Augmented Reality:Spatial computing platforms combining LiDAR, eye-tracking, and hand gesture inputs enable remote collaboration and enterprise training. Demand concentrates in German automotive OEMs and precision manufacturers deploying gesture-controlled assembly lines in cleanroom environments.
- Graphical User Interface:Visual interaction paradigms dominate legacy enterprise software and consumer applications.
- Voice User Interface:Speech-first interaction models serve accessibility requirements and hands-constrained operational contexts.
Graphical User Interface retains installed base dominance, with Augmented Reality gaining share fastest through industrial training verticals.
End User:
Maturity gradients separate established enterprise procurement from emerging researcher-driven demand, with developer ecosystems determining platform stickiness.
- Enterprises:Large-scale voice interface deployments and custom gesture control integrations target productivity and safety outcomes. Microsoft's Azure cognitive services infrastructure anchors enterprise-grade implementations, though legacy CRM and call center integration friction elongates sales cycles.
- Researchers:Academic and clinical neuroscience laboratories drive Brain-Computer Interface innovation, requiring open signal acquisition APIs and raw neural data access. China's MIIT GB standards for intelligent human-machine interaction terminals shape domestic procurement specifications for voice-enabled industrial panels.
- Consumers:Mass-market adoption of voice assistants and gesture-controlled entertainment systems follows platform ecosystem lock-in patterns.
- Developers:Toolchain and SDK accessibility determines platform adoption in application creation workflows.
Enterprises anchor current revenue concentration, with Researchers expanding most quickly through clinical validation partnerships.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory divergence between GDPR-linked EU AI Act constraints and China's MIIT standardization creates compliance-cost arbitrage, pushing interface hardware production toward jurisdictions with clearer certification pathways. Taiwan and South Korea foundries capture neural processing silicon demand as US and European vendors seek supply chain resilience outside mainland China.
United States
FDA premarket validation timelines for therapeutic Brain-Computer Interfaces stretch 18-36 months, freezing capital deployment for smaller neurostimulation developers. HIPAA ambient documentation requirements drive voice interface procurement in hospital systems. Silicon Valley semiconductor clusters pivot toward dedicated neural processing capacity for gesture-controlled surgical hardware.
Germany
Automotive OEMs and precision manufacturers in the industrial automation corridor deploy gesture-controlled assembly lines to minimize cleanroom contamination. EU AI Act conformity assessment obligations for biometric emotion recognition reshape procurement specifications for Natural Language Processing vendors. Baden-Württemberg's automotive engineering clusters integrate touchless interfaces into next-generation manufacturing cells.
China
MIIT GB standards for intelligent human-machine interaction terminals reshape domestic procurement for voice-enabled industrial panels. Neural signal decoding research accelerates through state-funded rehabilitation technology programs. Yangtze River Delta electronics manufacturing bases consolidate touchpanel and gesture sensor production for export markets.
Japan
METI industrial automation incentives support haptic feedback integration in precision manufacturing equipment. Aging demographics drive Brain-Computer Interface demand for assistive device control in rehabilitation clinics. Kansai region robotics clusters develop multimodal sensor fusion for manufacturing and healthcare applications.
South Korea
Foundry capacity for neural processing silicon concentrates in Seoul Capital Area and Busan-Ulsan manufacturing zones, creating single-source vulnerability for next-generation interface hardware. Government semiconductor self-sufficiency programs expand domestic neural inference engine production. Samsung and SK Hynix anchor supply chains for edge-deployed gesture and voice processing chips.
Human-Computer Interaction (HCI) Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue spatial computing and neural interface specialization. The vendor base stratifies across cloud infrastructure anchors, proprietary silicon architects, and open-platform middleware providers. Three archetypes dominate: hyperscale cloud service providers bundling cognitive APIs, semiconductor firms with captive neural processing silicon, and vertical specialists in clinical or industrial deployment contexts. Competitive moves center on foundry capacity reservation agreements and jurisdiction-specific product variant development for regulatory compliance.
Within the hyperscale cloud tier, Microsoft and Amazon anchor enterprise-grade voice interface deployments through Azure and AWS cognitive services infrastructure. Nvidia occupies a distinct position supplying CUDA-optimized neural inference substrates for real-time gesture rendering across automotive and surgical applications. Meta Platforms exemplifies the vertical integration archetype, combining proprietary spatial computing hardware with social platform distribution for consumer and enterprise immersive interfaces.
| Leading Market Players |
|---|
| Meta Platforms |
| Adobe |
| Microsoft |
| Nvidia |
| IBM |
| Alphabet |
| Amazon |
| Oracle |
| Apple |
| Others |
Supply & Pricing Matrix
Hyperscale cloud providers with captive infrastructure investments anchor pricing discipline across voice and gesture interface tiers, compressing margins for middleware vendors while rewarding semiconductor specialists with neural processing silicon. Their balance-sheet scale enables multi-year capacity reservations that lock in foundry output ahead of smaller competitors, translating supply security into pricing power across enterprise deployment contracts.
Pricing Analysis
Distributor margins on embedded gesture sensors run 12-18 points above direct-to-OEM neural inference chip sales, reflecting the technical integration burden shouldered by channel partners. Three-tier pricing structure across premium, standard, and economy levels separates FDA-validated surgical interfaces from industrial automation panels and consumer entertainment peripherals. Cost compression in mid-tier voice hardware is intensifying because Taiwan foundry customers are consolidating purchase volumes to secure allocation. Healthcare systems demonstrate lowest price sensitivity due to infection-control procurement mandates, while smart home builders face acute budget constraints from fragmented IoT protocol costs.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand for Azure and AWS cognitive service bundles, while specialized distributors manage fragmented healthcare and industrial automation procurement. Taiwan, South Korea, and the United States concentrate neural processing silicon fabrication, with Yangtze River Delta facilities consolidating touchscreen and gesture sensor assembly. Supply chains draw from rare earth elements for haptic actuators, photonic components for LiDAR spatial computing, and advanced substrates for edge inference engines. Single-source vulnerability concentrates in Seoul Capital Area foundries, where government semiconductor programs have yet to diversify beyond Samsung and SK Hynix anchor positions. Distribution runs through authorized component distributors for industrial panels and direct enterprise sales teams for cloud-anchored voice platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in this market rests on collapsing latency requirements that force buyers toward premium-tier edge inference hardware, even as cloud API commoditization squeezes middleware vendors. Neural processing unit integration at the device level creates pricing power for semiconductor architects while eroding value capture from pure-play software providers.
For Market Incumbents: Lock in foundry capacity reservations through 2026-2027 allocation windows before smaller competitors secure wafer starts. Defensive consolidation moves center on acquiring haptic feedback specialists with sub-20 millisecond latency IP and securing EU AI Act conformity assessment certifications ahead of competitor filings. The threat of emerging spatial computing entrants with proprietary sensor fusion architectures demands accelerated R&D in LiDAR-eye-tracking-hand gesture integration stacks. Channel control through exclusive distribution agreements with German automotive OEMs represents the critical defensive lever.
For New Entrants and Emerging Players: Mid-tier rehabilitation clinics in Japan and South Korea present an underserved buyer archetype with unmet demand for non-invasive Brain-Computer Interface assistive devices. White-space targets include voice-enabled industrial panels compliant with China's MIIT GB standards and touchless surgical interfaces for US hospital systems pursuing infection-control procurement mandates. The most penetrable segment spans German precision manufacturers deploying gesture-controlled cleanroom assembly lines. A clinical validation partnership go-to-market angle with university rehabilitation centers accelerates FDA premarket pathway navigation.
For Investors and Strategic Acquirers: Valuations sit cheapest among vertical specialists with FDA-validated neurostimulation pipelines but frozen capital deployment due to 18-36 month certification timelines. Long-term viability across the analysis window favors vendors with captive neural processing silicon or exclusive foundry relationships over pure-play software layer competitors. Acquisition target archetypes include haptic feedback hardware specialists and open-signal-acquisition API providers serving academic neuroscience laboratories. The signal to watch is EU AI Act conformity assessment obligation publication timelines, which will trigger compliance-driven procurement specification shifts favoring certified vendors.
| Strategic Initiative | Industry Significance |
|---|---|
| Foundry Capacity Reservation | Secures Taiwan and South Korea neural processing silicon allocation ahead of competitor purchase commitments. |
| EU AI Act Conformity Certification | Unlocks procurement specifications for biometric emotion recognition systems across German and French enterprise deployments. |
| Clinical Validation Partnership | Accelerates FDA premarket pathway navigation for therapeutic Brain-Computer Interface developers targeting US rehabilitation clinics. |
| Spatial Computing Platform Integration | Combines LiDAR, eye-tracking, and hand gesture inputs for German automotive OEM training and remote collaboration verticals. |
| MIIT GB Standard Compliance | Enables domestic procurement participation for voice-enabled industrial panels across China's Yangtze River Delta manufacturing bases. |
Research Methodology
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region's regulatory and manufacturing clusters. The approach combines structured interviews with interface hardware procurement managers, clinical rehabilitation specialists, semiconductor foundry planning officers, and enterprise IT architects with secondary validation against FDA 510(k) filings, EMA premarket submission databases, MIIT GB standard publications, and hyperscaler capital expenditure disclosures. Bottom-up vendor revenue triangulation against top-down end-use demand modeling ensures cross-verification of segment sizing across voice recognition, Brain-Computer Interface, and gesture control technology tiers.
Rate-of-change decomposition separates volume expansion from pricing trajectory and mix-shift effects across the projection horizon. Segmentation dimensions modeled include technology type, application vertical, user interface paradigm, and end-user archetype, with additional granularity on latency sensitivity tiers and contamination-risk deployment environments. CAGRs derive from regression analysis of historical replacement cycles and forward-looking procurement intention surveys. Industry-specific forecast inputs incorporate EU AI Act implementation timelines, FDA neurostimulation validation pathway updates, and China's MIIT standard revision schedules.
Underlying measurement precision varies by segment; Voice Recognition and Touchscreen carry tighter precision than emerging Brain-Computer Interface categories where clinical trial outcomes remain unresolved. Forecasts reflect assumptions regarding regulatory clearance timelines, foundry capacity expansion rates, and enterprise software procurement budget trajectories. Periodic stress-testing of base assumptions is recommended given sensitivity to FDA premarket validation delays and EU AI Act conformity assessment obligation interpretations.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Artificial Intelligence (AI)
Global Cognitive Services Market
Artificial Intelligence (AI)
Artificial Intelligence (AI) Accelerator Market
Artificial Intelligence (AI)
Voice Assistance Application Market
Artificial Intelligence (AI)
Conversational AI Market
Artificial Intelligence (AI)
Europe AI Orchestration Market
Artificial Intelligence (AI)
Latin America Artificial Intelligence Market
Artificial Intelligence (AI)
Artificial Intelligence HPC Cloud Market
Artificial Intelligence (AI)
Generative AI in Coding Market
Artificial Intelligence (AI)
Consumer Facing AI Products Market
Artificial Intelligence (AI)
Edge AI Market
Artificial Intelligence (AI)
AI Datasets Market
Artificial Intelligence (AI)
AI-Ready Enterprise Knowledge Graph Market
Artificial Intelligence (AI)
Global Artificial Intelligence in Law Market
Artificial Intelligence (AI)
Federated Learning Market
Artificial Intelligence (AI)
Artificial Intelligence (AI) in BFSI Market
Artificial Intelligence (AI)
Global Artificial Intelligence in E-Commerce Market