
 Artificial Intelligence (AI) Governance Market | 2026-2036
Artificial Intelligence (AI) Governance Market Size, Share, and Industry Trends Forecast 2026-2036
Artificial Intelligence (AI) Governance Market Analysis
Explainable AI frameworks are broadening the addressable market for governance tooling by replacing opaque black-box systems with auditable decision trails. Microsoft Corporation leverages its cloud infrastructure to embed governance modules across Azure AI services. IBM Corporation anchors its competitive stance through Watson OpenScale, which specializes in bias detection and model monitoring for regulated industries. Google LLC differentiates via TensorFlow Extended pipelines that integrate fairness constraints into production machine learning workflows.
Artificial Intelligence Governance encompasses the technical systems, policy engines, and audit mechanisms that enforce accountability, transparency, and ethical boundaries across machine learning model lifecycles. Core functional parameters include bias detection thresholds, explainability scorecards, data lineage tracking, and automated compliance reporting against jurisdictional standards. Deployment model segmentation reveals cloud-based governance platforms capturing the fastest expansion as enterprises prioritize scalable, API-first compliance architectures over on-premises installations. Regulatory framework segmentation shows data protection laws and risk management policies commanding the deepest margin pools, since breach penalties and algorithmic liability create urgent, budget-backed demand.
The EU AI Act, alongside FDA guidance on AI-enabled medical devices and Japan's METI governance principles, shapes product standards by mandating conformity assessments before market deployment. NIST's AI Risk Management Framework in the United States further tightens procurement criteria for federal contractors, filtering vendor eligibility. Stakeholders must monitor divergence between binding European obligations and voluntary Anglo-American guidelines, as this regulatory asymmetry will determine which governance platforms achieve cross-border portability.
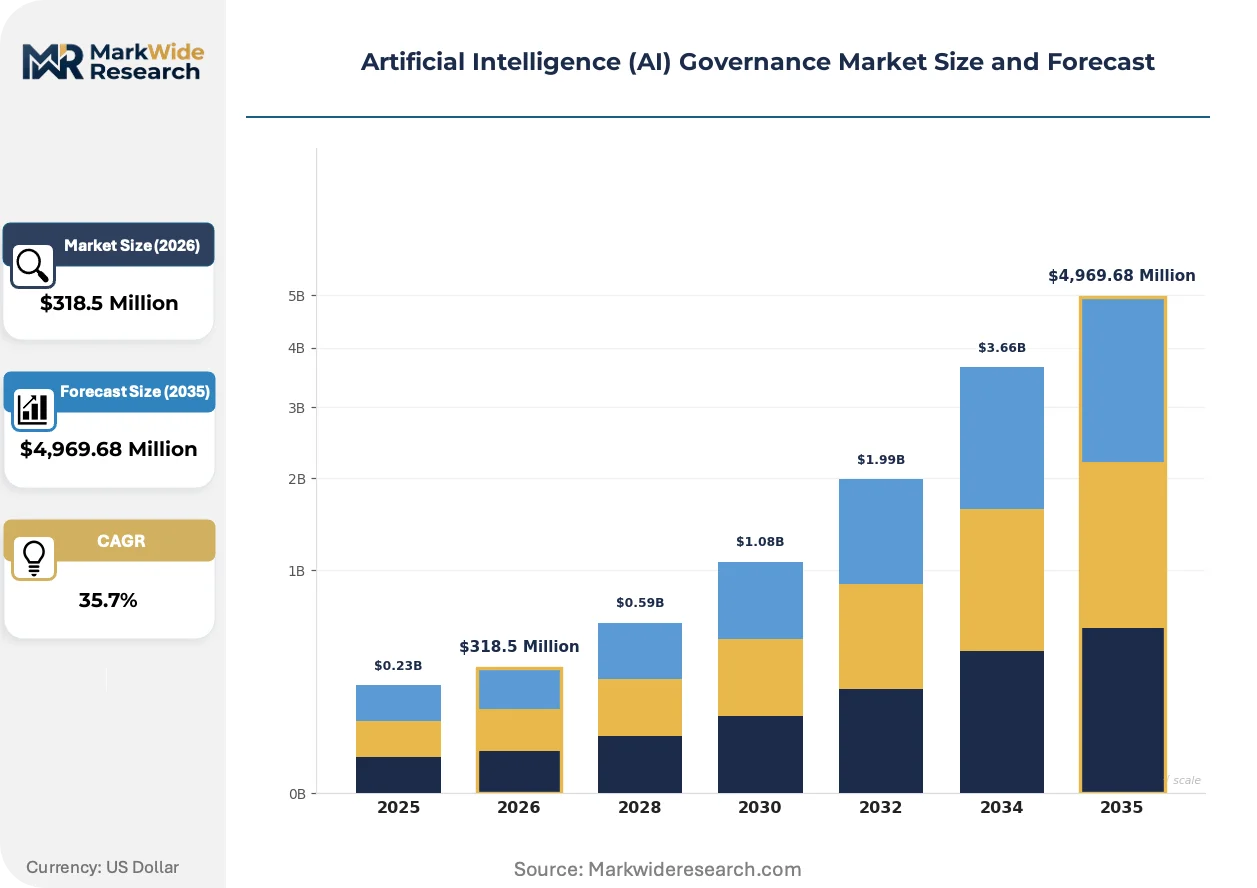
Market Dynamics
Binding algorithmic accountability mandates across the United States, Germany, and Japan are compelling enterprises to rebuild compliance infrastructure from audit trails upward, creating procurement urgency for integrated governance platforms.
Growth Catalysts
- EU AI Act Conformity Assessments:Mandatory pre-deployment audits for high-risk AI systems are forcing financial services and healthcare enterprises to procure bias detection and explainability tooling.
- NIST Risk Management Framework:Federal contractor procurement criteria in the United States now filter vendor eligibility through documented model governance capabilities.
- Algorithmic Liability Litigation:Rising court cases over credit scoring and hiring discrimination are pushing Fortune 500 legal departments to invest in defensible audit mechanisms.
Market Restraints
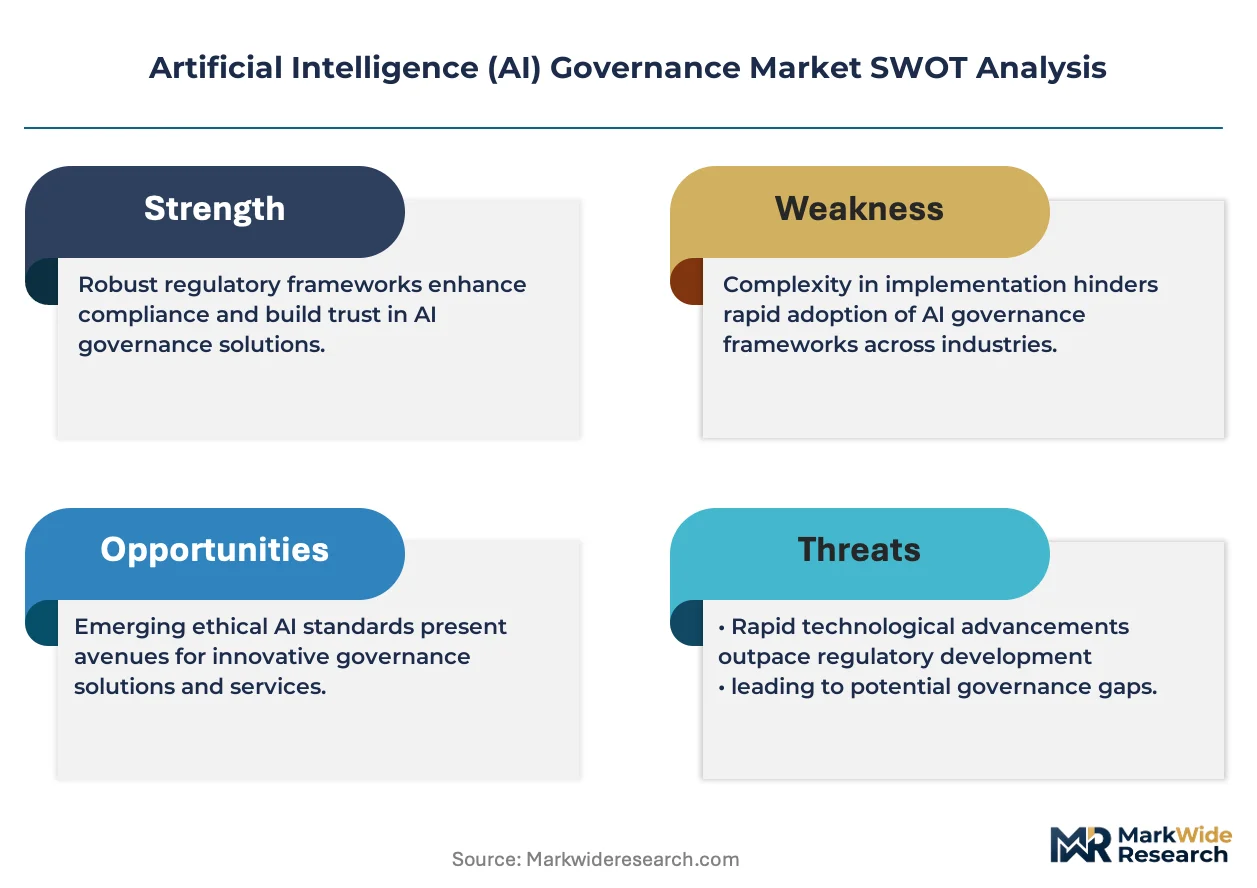
- Cloud Infrastructure Concentration:Three hyperscalers control the underlying compute layer for most governance platforms, creating vendor lock-in risk and pricing power asymmetry.
- Cross-Border Regulatory Friction:Divergence between binding EU obligations and voluntary Anglo-American guidelines limits platform portability and inflates compliance costs.
- Specialized Talent Scarcity:Shortage of professionals combining machine learning engineering with regulatory interpretation is compressing implementation timelines.
Strategic Opportunities
- Japan's METI Governance Principles:Voluntary adoption frameworks are creating early-mover advantage for platforms that localize explainability scorecards to Japanese industrial contexts.
- Edge AI Deployment:Governance tooling for distributed inference on manufacturing floors and autonomous vehicles remains underdeveloped relative to cloud-centric solutions.
- Convergence with Privacy Tech:Integration of differential privacy and federated learning audit trails opens new product categories at the intersection of data protection and model accountability.
Industry Challenges
- Legacy System Integration:Mainframe-based financial institutions face multi-year timelines to embed real-time governance hooks into decades-old core banking architectures.
- Certification Timeline Compression:Third-party conformity assessment bodies lack capacity to process AI system audits at the velocity required by product launch cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Artificial Intelligence (AI) Governance Market |
| Market Size in 2026 | $318.5 Million |
| Market Size in 2035 | $4,969.68 Million |
| CAGR (2026 – 2036) | 35.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Regulatory Framework: Data Protection Laws, Compliance Standards, Ethical Guidelines, Risk Management Policies Deployment Model: On-Premises, Cloud-Based, Hybrid, Edge Computing End User: Corporates, Government Agencies, Educational Institutions, NGOs Technology Type: Machine Learning, Natural Language Processing, Robotics, Computer Vision |
| Companies Covered | Microsoft Corporation, IBM Corporation, SAP SE, Google LLC, FICO Inc., Oracle Inc., Salesforce.com, Inc., Accenture, Infosys Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Artificial Intelligence (AI) Governance Market Emerging Trajectories
Continuous monitoring architectures are displacing point-in-time compliance checks, embedding governance into the operational fabric of machine learning pipelines rather than treating it as a pre-deployment gate.
Real-time model drift detection with automated rollback triggers is electrifying risk management in high-velocity trading and fraud detection environments. Hedge funds and payment processors are deploying these systems within milliseconds of inference. The technology is compressing the window between algorithmic malfunction and containment from days to seconds.
The EU AI Act's risk classification system is restructuring product development roadmaps across medical device and automotive sectors. Manufacturers must now complete conformity assessments before market entry rather than retrofitting compliance post-launch. German automotive suppliers and French health-tech startups are reorganizing engineering teams around documented traceability requirements.
Enterprise buyers are consolidating vendor relationships around platforms that unify data lineage, model monitoring, and regulatory reporting. Point solutions for bias detection or explainability alone are losing procurement cycles to integrated suites. This consolidation is most visible in United States financial services, where procurement committees now mandate single-vendor accountability for algorithmic outcomes.
Artificial Intelligence (AI) Governance Market Segmentation
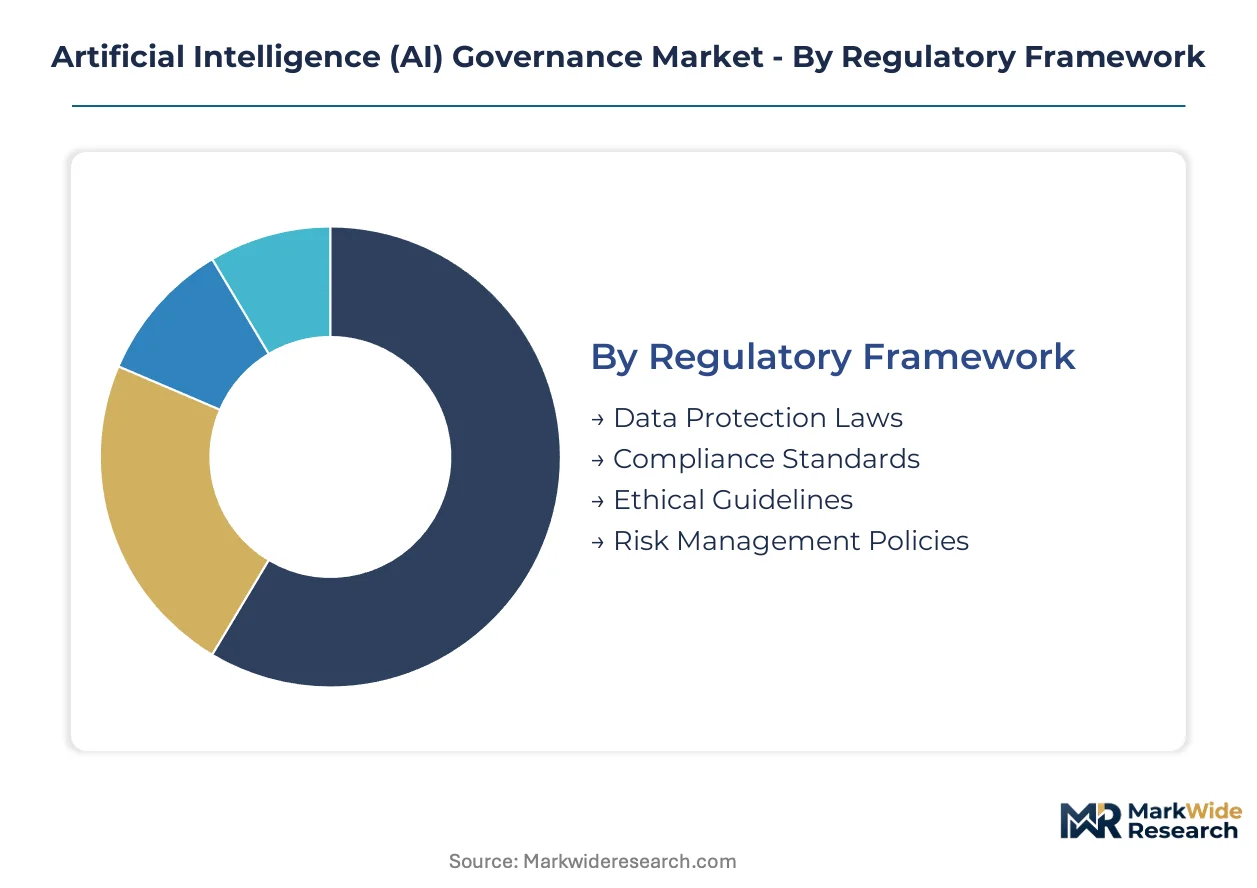
AI governance procurement varies sharply by regulatory exposure and infrastructure maturity. Buyers segment their spending across compliance mandates, deployment architectures, and algorithmic risk profiles rather than treating governance as a uniform capability layer.
Regulatory Framework:
Volume concentrates in breach-penalty regimes where non-compliance carries immediate financial liability. Premium pricing attaches to frameworks requiring third-party conformity assessments.
- Data Protection Laws:GDPR-class regulations drive baseline procurement across all jurisdictions with extraterritorial reach. Financial services firms in Germany and France prioritize automated data lineage tracking to satisfy supervisory authority audit requests.
- Risk Management Policies:Sector-specific liability frameworks command the deepest margin pools. NIST AI RMF adoption by US federal contractors filters vendor eligibility through documented model governance capabilities.
- Compliance Standards:ISO/IEC certification requirements shape procurement in regulated industries seeking defensible audit trails.
- Ethical Guidelines:Voluntary adoption frameworks attract early investment from reputation-sensitive technology firms and consumer-facing brands.
Mature deployment sits with Data Protection Laws. Newer deployment is concentrated in Risk Management Policies.
Deployment Model:
Cost tier separation runs from capital-intensive on-premises installations to consumption-priced cloud architectures. Mid-market buyers increasingly favor hybrid configurations balancing control with scalability.
- Cloud-Based:API-first governance platforms dominate procurement cycles among enterprises prioritizing scalable compliance architectures. US financial services and Japanese automotive suppliers lead adoption of real-time model monitoring delivered through managed services.
- Edge Computing:Distributed inference governance for manufacturing floors and autonomous vehicles remains underdeveloped relative to cloud-centric solutions. German industrial automation firms and Japanese robotics manufacturers are early adopters of localized bias detection.
- On-Premises:Air-gapped installations persist in defense and intelligence applications with classified data handling requirements.
- Hybrid:Split architectures allow sensitive model training on-premises while pushing inference monitoring to cloud infrastructure.
Cloud-Based configurations dominate new procurement. Hybrid deployments are gaining share fastest among mid-cap enterprises.
End User:
Customer type determines functional depth requirements and procurement authority structures. Government buyers mandate documented traceability; corporates prioritize integration speed.
- Corporates:Fortune 500 legal departments drive investment in defensible audit mechanisms following algorithmic liability litigation in credit scoring and hiring discrimination. Procurement committees now mandate single-vendor accountability for algorithmic outcomes.
- Government Agencies:Federal contractor eligibility requirements under NIST frameworks filter vendor selection through demonstrated governance capabilities. US and German procurement offices lead standardized RFP development.
- Educational Institutions:Research ethics boards require explainability tooling for grant-funded machine learning projects involving human subjects.
- NGOs:Human rights organizations deploy bias detection for algorithmic accountability advocacy and public interest litigation support.
Corporate procurement represents established spending. Government agency deployment is expanding most quickly under binding accountability mandates.
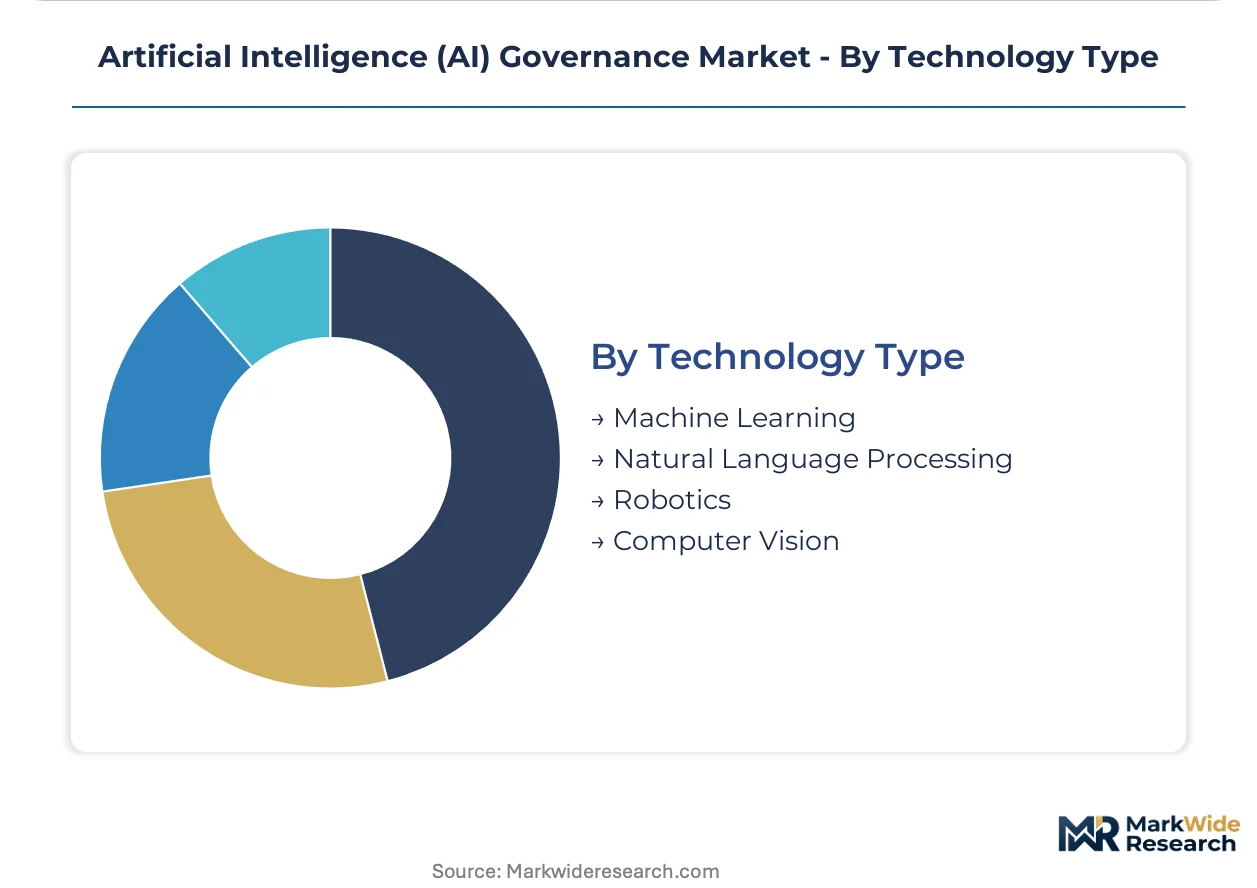
Technology Type:
Application maturity separates legacy statistical methods from generative architectures with emergent governance requirements. Each technology class demands specialized monitoring primitives.
- Machine Learning:Supervised and unsupervised learning systems constitute the core installed base for drift detection and performance degradation monitoring. Financial services fraud detection and healthcare diagnostic applications in the US and Japan drive continuous monitoring architecture adoption.
- Natural Language Processing:Large language model governance requires novel approaches to hallucination detection, prompt injection resistance, and training data toxicity auditing. Enterprise procurement in Germany and Japan is accelerating for customer-facing conversational systems.
- Computer Vision:Facial recognition and medical imaging applications face strict conformity assessment requirements under EU AI Act high-risk system classifications.
- Robotics:Physical system safety integration layers governance into hardware-in-the-loop validation processes.
Machine Learning governance shows mature tooling availability. Natural Language Processing governance is climbing the fastest as generative deployment accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Procurement urgency concentrates in the United States, Germany, and Japan where binding AI accountability mandates are compelling enterprises to rebuild compliance infrastructure. Financial services firms across these markets are expanding procurement of integrated governance platforms to manage algorithmic risk.
United States
Federal contractor eligibility requirements and algorithmic liability litigation are driving Fortune 500 investment in defensible audit mechanisms. NIST AI Risk Management Framework adoption filters vendor selection through documented model governance capabilities. New York and San Francisco financial services clusters lead procurement of real-time model monitoring systems for high-velocity trading environments.
Germany
EU AI Act conformity assessments for high-risk systems are forcing automotive and healthcare enterprises to procure bias detection tooling before market entry. German automotive suppliers in Stuttgart and Munich are reorganizing engineering teams around documented traceability requirements for autonomous vehicle systems.
Japan
METI governance principles and manufacturing sector automation are creating early-mover advantage for platforms localizing explainability scorecards. Tokyo and Osaka industrial automation firms are adopting edge-based governance for distributed inference on manufacturing floors.
United Kingdom
Financial services regulators are aligning supervisory expectations with emerging EU standards while maintaining distinct procurement criteria. London's fintech cluster is driving demand for cloud-based governance platforms that satisfy cross-border data handling requirements.
France
CNIL enforcement patterns and EU AI Act implementation are shaping health-tech startup compliance roadmaps. Paris-based medical device manufacturers are completing conformity assessments for AI-enabled diagnostic systems before market deployment.
Artificial Intelligence (AI) Governance Market Vendor Landscape
Platform consolidation dominates the current landscape as enterprise buyers unify vendor relationships around integrated suites. The vendor base separates into three tiers: hyperscale cloud providers with embedded governance modules, specialized compliance platforms with sector-specific certifications, and point-solution providers facing procurement disadvantage. Strategic archetypes include cloud-native integrators, regulatory specialists, and legacy system modernizers. M&A activity and API-first architecture development represent the dominant competitive vectors as vendors race to capture federal contractor eligibility and EU conformity assessment workflows.
Among hyperscale cloud providers, Microsoft Corporation and Google LLC anchor the infrastructure-integrated tier, embedding governance capabilities directly within managed AI services. IBM Corporation occupies a specialist position through Watson OpenScale, exemplifying the regulatory-focused archetype with bias detection and model monitoring tooling for regulated industries. These three entities represent distinct strategic postures: cloud infrastructure leverage, specialized compliance depth, and open-source pipeline integration.
| Leading Market Players |
|---|
| Microsoft Corporation |
| IBM Corporation |
| SAP SE |
| Google LLC |
| FICO Inc. |
| Oracle Inc. |
| Salesforce.com, Inc. |
| Accenture |
| Infosys Ltd. |
| Others |
Supply Flow & Price Mechanics
Federal contractor procurement committees mandating single-vendor accountability for algorithmic outcomes are compressing supplier rosters and forcing platform providers to absorb compliance certification costs into base pricing. This buyer consolidation dynamic rewards hyperscale cloud providers with embedded governance modules while squeezing point-solution vendors on margin.
Pricing Analysis
Volume concentrates in consumption-priced SaaS tiers while margin pools attach to on-premises installations with bespoke conformity assessment support. Three-tier pricing structure across premium, standard, and economy levels stratifies by integration depth, with premium tiers bundling real-time drift detection and automated rollback capabilities. Cost compression in standard tiers is intensifying because mid-market buyers are consolidating around hybrid deployment models. Government agencies exhibit lowest price sensitivity due to federal procurement guidelines, while mid-cap enterprises in financial services show highest elasticity.
Supply Chain Analysis
Machine learning engineering talent scarcity in the United States, Germany, and India is elongating implementation timelines and inflating professional services costs for governance platform deployments. Component sourcing draws from cloud infrastructure providers in the United States, specialized compliance certification bodies in Germany, and edge computing hardware manufacturers in Japan. Single-source vulnerability concentrates in hyperscaler compute layers where three providers control underlying infrastructure for most governance platforms. Distribution runs through direct enterprise sales teams with API-first onboarding for cloud-based deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform consolidation is accelerating as binding regulatory mandates filter vendor eligibility through documented conformity assessment capabilities, eliminating undercapitalized point-solution providers lacking certification infrastructure.
For Market Incumbents: To counter hyperscaler bundling of governance modules into managed AI services, anchor differentiation through sector-specific certification depth and backward integration into third-party conformity assessment workflows. Invest in localized explainability tooling for Japanese industrial automation and German automotive compliance contexts where regulatory interpretation expertise creates switching costs. For New Entrants and Emerging Players: The mid-market price-point gap between premium integrated suites and economy-tier point solutions creates entry opportunity for hybrid-deployment specialists serving mid-cap financial services firms. Target edge AI governance for manufacturing floors and autonomous vehicles, where real-time monitoring requirements remain underserved by cloud-centric incumbents. Lead with API-first architectures that embed into existing MLOps pipelines without forklift infrastructure replacement. For Investors and Strategic Acquirers: The window for entry favors regulatory specialists with demonstrated EU AI Act conformity assessment workflows and NIST framework documentation capabilities. Long-term viability hinges on cross-border platform portability as regulatory divergence between binding European obligations and voluntary Anglo-American guidelines persists. Monitor certification body capacity expansion as the signal indicating whether audit velocity can match product launch cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unifying data lineage, model monitoring, and regulatory reporting captures procurement cycles from point solutions. |
| Acquisition of Specialist Firm | Absorbing sector-specific compliance platforms accelerates conformity assessment workflow capabilities for regulated industries. |
| Geographic Expansion | Localizing explainability scorecards to Japanese METI governance principles captures early-mover advantage in industrial automation. |
| Strategic Partnership | Aligning with third-party conformity assessment bodies addresses certification timeline compression for high-risk AI system deployments. |
| Product Launch | Introducing continuous monitoring architectures displaces point-in-time compliance checks in high-velocity trading environments. |
Methodological Framework
SEC filings, hyperscaler capex disclosures, and regulatory framework documentation from the EU AI Act and NIST AI Risk Management Framework formed the secondary backbone, cross-referenced against primary interviews with CTOs, IT procurement officers, platform engineers, and integration specialists at financial services firms, automotive suppliers, and healthcare technology providers. Bottom-up sizing of vendor-reported deployment metrics and top-down validation against federal contractor procurement data established market boundary conditions.
Historical trendline analysis of governance platform adoption across cloud-based, edge computing, on-premises, and hybrid deployment models informed projection frameworks. Segmentation dimensions modeled include deployment architecture, regulatory framework exposure, end-user procurement authority structure, and technology type application maturity. CAGRs were derived from elasticity-adjusted penetration curves and vendor capacity expansion announcements, with inputs from algorithmic liability litigation frequency and conformity assessment body queue depth.
Inputs from federal procurement databases and EU notified body certification records were available through the study window; gaps in real-time edge AI deployment metrics introduce uncertainty bands around manufacturing floor governance adoption timelines. Forecasts reflect assumptions regarding regulatory enforcement intensity and hyperscaler pricing power persistence. A small set of triggers—including certification body capacity expansion, METI governance principle binding conversion, and algorithmic liability precedent establishment—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Artificial Intelligence (AI)
Conversation Intelligence Software Market
Artificial Intelligence (AI)
Smart Virtual Personal Assistants Market
Artificial Intelligence (AI)
AI Data Labeling Market
Artificial Intelligence (AI)
Artificial Intelligence Chatbots Market
Artificial Intelligence (AI)
AI As a Service (Aiaas) Market
Artificial Intelligence (AI)
Federated Learning Market
Artificial Intelligence (AI)
Asia-Pacific Generative AI Market
Artificial Intelligence (AI)
AI in Retail Market
Artificial Intelligence (AI)
Europe Decision Intelligence Market
Artificial Intelligence (AI)
Global AI Governance Market
Artificial Intelligence (AI)
AI Task Manager App Market
Artificial Intelligence (AI)
Artificial Intelligence (AI) Market
Artificial Intelligence (AI)
Global Cloud Telecommunication AI Market
Artificial Intelligence (AI)
Global Cognitive Automation Market
Artificial Intelligence (AI)
Global Legaltech Artificial Intelligence (AI) Market
Artificial Intelligence (AI)
AI in Robotics Market