
 United States Artificial Intelligence Market | 2026-2036
United States Artificial Intelligence Market Size, Share, and Industry Trends Forecast 2026-2036
United States Artificial Intelligence Market Intelligence
Specialized AI accelerators using custom silicon is realigning total cost of ownership for large model training. NVIDIA dominates datacenter GPU supply through captive foundry relationships and proprietary interconnect architectures. Microsoft leverages its Azure cloud footprint to bundle inferencing services with enterprise software contracts. Amazon sustains price pressure through in-house Trainium chip development and vertical control over its retail data pipeline.
Artificial intelligence denotes computational systems that learn patterns from structured and unstructured data without explicit programming, typically requiring tensor processing units capable of mixed-precision arithmetic at scale. Its primary purpose is automating perception, prediction, and decision workflows across commercial and governmental operations. Machine learning deployment models currently capture the largest share of enterprise spending, while edge computing installations are expanding fastest as latency-sensitive manufacturing and automotive applications proliferate. Natural language processing applications in financial services command premium pricing due to regulatory compliance requirements and specialized domain adaptation costs.
The National Institute of Standards and Technology AI Risk Management Framework and the Federal Trade Commission's algorithmic fairness enforcement posture are tightening procurement standards for federal and healthcare AI contracts. The Food and Drug Administration's software-as-a-medical-device pathway is creating divergent approval timelines that advantage established healthcare AI vendors with prior 510(k) clearances. Stakeholders must monitor how state-level biometric privacy laws in Illinois, Texas, and California fragment compliance obligations for computer vision deployments.
Market Dynamics
Federal procurement mandates under the NIST AI Risk Management Framework are restructuring vendor qualification requirements, forcing defense contractors and healthcare AI developers to re-engineer compliance architectures before contract eligibility.
Growth Catalysts
- Defense Modernization Mandates:The Department of Defense's accelerated procurement of machine learning systems for autonomous threat detection is channeling multi-billion-dollar contracts toward domestic AI developers with security clearances.
- Healthcare Regulatory Pathways:FDA's software-as-a-medical-device approval track is expanding addressable market for diagnostic AI, particularly in radiology and pathology workflows where prior 510(k) clearances create competitive moats.
- Silicon Infrastructure Buildout:Northern Virginia's data center corridor and California's Bay Area are concentrating hyperscaler investments in tensor processing capacity, reducing latency for enterprise model training.
Market Restraints
- Compute Cost Concentration:NVIDIA's captive foundry relationships and proprietary NVLink interconnect architectures limit supply alternatives for training-grade GPUs, inflating total cost of ownership for large model development.
- State Privacy Fragmentation:Illinois Biometric Information Privacy Act, Texas Capture or Use of Biometric Identifier Act, and California Consumer Privacy Act create conflicting compliance obligations for computer vision deployments across state lines.
- Technical Talent Scarcity:Mixed-precision arithmetic optimization and distributed training engineering skills remain concentrated among a narrow cohort of specialists, constraining deployment velocity.
Strategic Opportunities
- Edge Manufacturing Applications:Latency-sensitive automotive and industrial automation use cases in Michigan and South Carolina manufacturing corridors are driving demand for on-premise inferencing hardware.
- Financial Services NLP Premium:Natural language processing applications in compliance-heavy banking and insurance verticals command pricing power due to specialized domain adaptation requirements and regulatory audit trails.
- FTC Algorithmic Fairness Enforcement:The Commission's intensified scrutiny of discriminatory automated decision-making is creating advisory service opportunities for compliance-focused AI consultancies.
Industry Challenges
- Legacy System Integration Friction:Enterprise AI deployments face architectural incompatibility with decades-old ERP and mainframe systems, particularly in federal agencies and regulated healthcare networks.
- Model Certification Timelines:FDA's divergent 510(k) and De Novo approval pathways for diagnostic algorithms create unpredictable revenue recognition cycles for emerging healthcare AI vendors.
- Supply Chain Reconfiguration Costs:Domestic semiconductor fabrication capacity constraints force reliance on Taiwan and South Korea foundries, exposing training infrastructure to geopolitical disruption risk.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Artificial Intelligence Market |
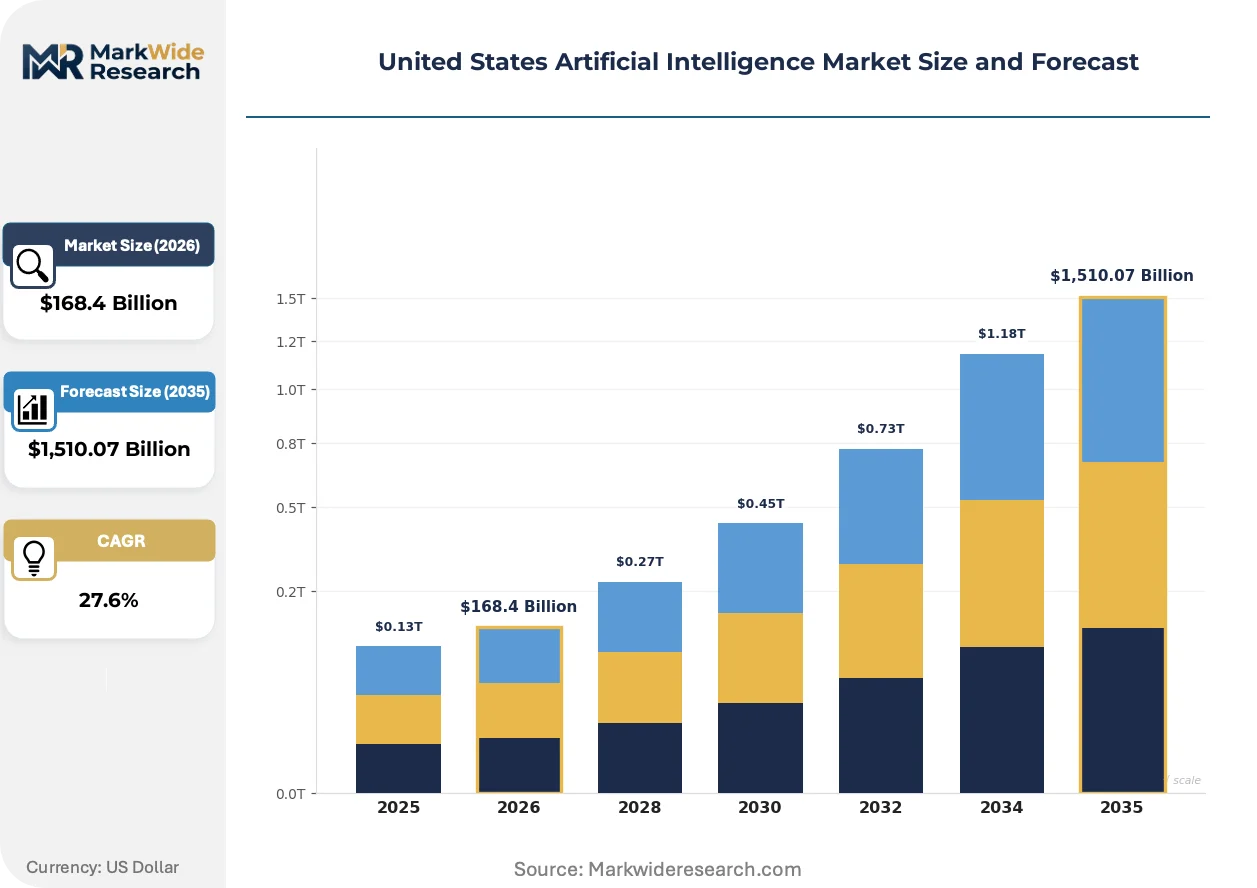
| Market Size in 2026 | $168.4 Billion |
| Market Size in 2035 | $1,510.07 Billion |
| CAGR (2026 – 2036) | 27.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Natural Language Processing, Computer Vision, Robotics, Predictive Analytics Technology: Machine Learning, Deep Learning, Neural Networks, Cognitive Computing End User: Healthcare Providers, Financial Services, Retail, Manufacturing Deployment: On-Premises, Cloud-Based, Hybrid, Edge Computing |
| Companies Covered | Amazon, Tesla, NVIDIA, IBM, Palantir, Microsoft, Meta Platforms, Databricks, Alphabet, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Artificial Intelligence Market Strategic Shifts & Innovations
Computational architectures are fragmenting across cloud, edge, and on-premise deployments as latency requirements and data sovereignty concerns reshape where model training and inferencing occur.
Federated learning frameworks are decentralizing model training across distributed data silos, enabling pharmaceutical consortiums and hospital networks to collaborate on drug discovery and diagnostic algorithms without centralizing sensitive patient records. Healthcare systems in Massachusetts and Pennsylvania are piloting these architectures for multi-site clinical trials. The approach compresses data governance overhead while preserving HIPAA compliance boundaries.
The NIST AI Risk Management Framework is mandating documented risk assessment protocols for federal AI procurements, forcing vendors to implement model cards, bias testing, and red-teaming documentation. Defense contractors bidding on Pentagon machine learning contracts must now submit algorithmic impact assessments. Healthcare AI developers seeking FDA clearance are adopting these standards preemptively to accelerate federal sales cycles.
Enterprise buyers are consolidating AI vendor relationships around bundled cloud-inferencing contracts tied to existing productivity software suites. Financial services procurement teams in New York and Chicago are negotiating multi-year Azure and AWS agreements that embed machine learning APIs into compliance and trading workflows. This behavior concentrates spending among hyperscalers while squeezing standalone AI platform providers on price and integration flexibility.
United States Artificial Intelligence Market Segmentation
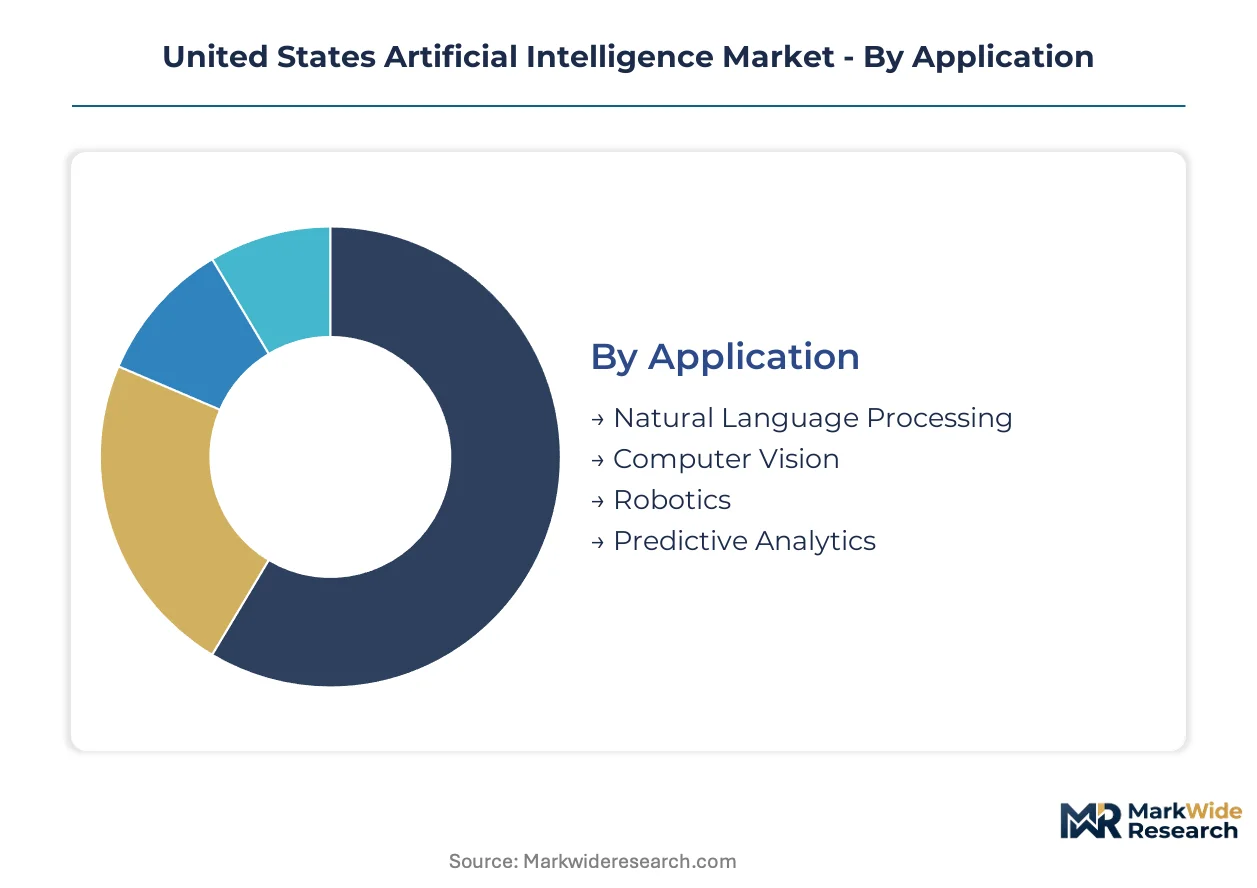
Segmentation reveals how procurement patterns diverge across federal compliance mandates, latency requirements, and vertical-specific regulatory burdens. Understanding these divisions exposes where vendor qualification costs concentrate and where deployment friction varies.
Application:
Upgrade cycles in enterprise AI adoption are shortening as legacy rule-based systems face replacement pressure from transformer architectures and multimodal models.
- Natural Language Processing:Transformer-based systems process unstructured text for contract analysis, customer service automation, and regulatory document review. Financial services procurement in New York and Chicago commands premium pricing due to FINRA audit trail requirements and specialized domain adaptation costs.
- Computer Vision:Convolutional and vision transformer architectures enable defect detection, biometric authentication, and medical imaging analysis. Illinois BIPA and Texas biometric privacy statutes fragment compliance obligations for multi-state retail and banking deployments.
- Robotics:Autonomous navigation and manipulation systems integrate perception models with physical actuation.
- Predictive Analytics:Statistical and machine learning models forecast demand, risk, and equipment failure patterns.
Natural Language Processing sits at the top of the volume ranking, with Computer Vision climbing the fastest.
Technology:
Cost tiers separate research-grade implementations from production deployments, with infrastructure requirements scaling nonlinearly across these categories.
- Machine Learning:Supervised and unsupervised algorithms using structured datasets dominate current enterprise spending. Healthcare providers in Massachusetts and Pennsylvania deploy these for clinical decision support under FDA software-as-a-medical-device pathways.
- Deep Learning:Multi-layer neural architectures require tensor processing units and distributed training infrastructure. Northern Virginia data centers and California's Bay Area concentrate hyperscaler investments in this capacity.
- Neural Networks:Biological-inspired computing structures underpin pattern recognition tasks.
- Cognitive Computing:Systems simulating human reasoning processes for complex decision workflows.
Machine Learning captures the largest spending share, while Deep Learning expands most quickly as model parameter counts scale.
End User:
Customer type determines procurement velocity, with regulated industries facing extended vendor qualification timelines compared to technology-native sectors.
- Healthcare Providers:Hospital systems and diagnostic laboratories deploy AI for radiology, pathology, and clinical documentation. FDA 510(k) clearance requirements and HIPAA compliance boundaries create competitive moats for established vendors with prior regulatory approvals.
- Financial Services:Banks, insurers, and asset managers apply NLP to compliance monitoring and algorithmic trading. The SEC and FINRA intensify scrutiny of model risk management, driving advisory service demand.
- Retail:E-commerce platforms and brick-and-mortar chains optimize inventory and personalization.
- Manufacturing:Automotive and industrial automation in Michigan and South Carolina corridors drive edge inferencing hardware demand.
Healthcare Providers lead procurement volume, with Financial Services gaining share fastest on regulatory compliance spending.
Deployment:
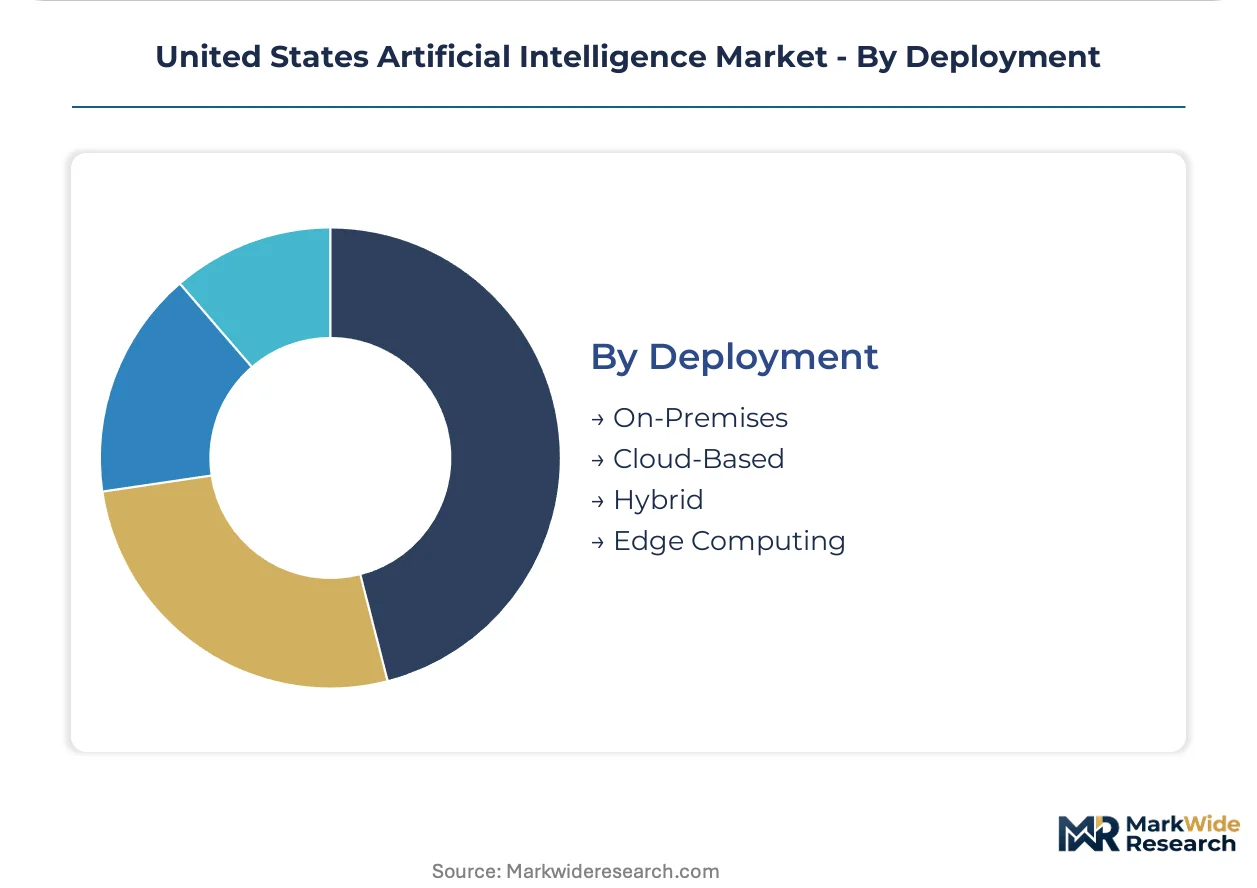
Maturity gradients separate established cloud architectures from emerging edge configurations, with hybrid models capturing transitional workloads.
- On-Premises:Dedicated hardware installations within enterprise data centers address data sovereignty and latency constraints. Defense contractors with security clearances favor this model for Pentagon machine learning contracts under NIST AI Risk Management Framework mandates.
- Cloud-Based:Hyperscaler-managed infrastructure delivers elastic compute for model training and batch inferencing. Microsoft Azure and AWS bundle these services with existing enterprise software contracts, concentrating spending among incumbents.
- Hybrid:Split architectures processing sensitive data locally while leveraging cloud scale for training.
- Edge Computing:Distributed processing at manufacturing floors and vehicle systems minimizes latency for real-time decisions.
Cloud-Based deployment holds the volume lead, with Edge Computing showing the steepest expansion trajectory on manufacturing automation demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
California's Bay Area concentrates the nation's densest cluster of AI research labs and venture deployment, with Northern Virginia's data center corridor forming the primary infrastructure backbone for federal and enterprise workloads.
California
Defense contractors and hyperscalers drive procurement of tensor processing infrastructure across Silicon Valley and San Francisco. The California Consumer Privacy Act imposes stringent data governance requirements on model training pipelines. San Jose and Mountain View host concentrated R&D operations for autonomous systems and large language model development.
Virginia
Pentagon machine learning contracts channel multi-billion-dollar investments into Loudoun County and Fairfax County data center corridors. NIST AI Risk Management Framework mandates reshape vendor qualification for federal procurements. Northern Virginia's fiber-dense infrastructure supports latency-sensitive inferencing for intelligence community applications.
Texas
Energy sector predictive analytics and semiconductor fabrication drive enterprise AI adoption across Houston and Austin metro areas. The Texas Capture or Use of Biometric Identifier Act fragments compliance obligations for computer vision deployments. Dallas-Fort Worth hosts expanding data center capacity serving central U.S. latency requirements.
Massachusetts
Hospital networks and pharmaceutical consortiums deploy federated learning for multi-site clinical trials under FDA software-as-a-medical-device pathways. HIPAA compliance boundaries preserve competitive moats for established diagnostic AI vendors. Greater Boston's biotech corridor concentrates healthcare AI R&D alongside MIT and Harvard research spinouts.
Illinois
Manufacturing automation and financial services NLP applications anchor demand in Chicago and Rockford industrial corridors. The Illinois Biometric Information Privacy Act creates strict liability exposure for computer vision deployments in retail and banking. Chicago's trading floors drive specialized demand for low-latency algorithmic decision systems.
United States Artificial Intelligence Market Key Industry Players
Strategic partnerships dominate the current landscape as hyperscalers bundle inferencing services with existing enterprise software contracts. The vendor base separates into three distinct tiers: cloud-native platforms with captive silicon development, defense-focused contractors with security clearances, and vertical specialists with regulatory pre-approvals. Competitive positioning hinges on M&A activity targeting niche compliance expertise and capacity expansion in domestic data center footprints.
Within the hyperscaler tier, Amazon, Microsoft, and NVIDIA occupy positions defined by infrastructure control and captive supply relationships. Amazon exemplifies vertical integration through in-house chip development and retail data pipeline ownership. Microsoft anchors enterprise bundling strategies across Azure cloud footprints. NVIDIA represents supply-constrained dominance in training-grade accelerator markets. Defense-oriented specialists including Palantir and Anduril sit within a separate tier qualified for Pentagon machine learning procurements.
| Leading Market Players |
|---|
| Amazon |
| Tesla |
| NVIDIA |
| IBM |
| Palantir |
| Microsoft |
| Meta Platforms |
| Databricks |
| Alphabet |
| Others |
Cost & Logistics Intelligence
Spot pricing for H100-class datacenter GPUs cascades through procurement tiers, concentrating cost pressure on training-intensive model developers while hyperscalers with captive silicon development capture margin advantages through in-house accelerator programs.
Pricing Analysis
Input-cost pass-through from foundry capacity constraints drives three-tier pricing stratification across cloud inferencing contracts. Premium tiers attach to NIST AI Risk Management Framework certification and FDA 510(k) clearance documentation, while standard tiers serve enterprise productivity bundles and economy tiers address batch-processing workloads. Pricing pressure stems from hyperscaler bundling strategies that commoditize standalone AI platform services. Federal contractors with security clearances exhibit lowest price sensitivity due to procurement mandate requirements, whereas mid-market software vendors face acute cost compression.
Supply Chain Analysis
Dual-sourcing requirements from Pentagon procurement officers mandate qualified secondary suppliers for tensor processing infrastructure, though Taiwan and South Korea foundries retain effective supply concentration for advanced node fabrication. Raw material dependencies center on high-bandwidth memory modules, specialized photoresists, and rare earth elements for magnetic components. Single-source vulnerability persists at the leading-edge lithography tier where extreme ultraviolet equipment anchors production capacity. Distribution runs through hyperscaler-owned data center corridors in Northern Virginia and California's Bay Area, with edge computing hardware flowing through manufacturing corridors in Michigan and South Carolina.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
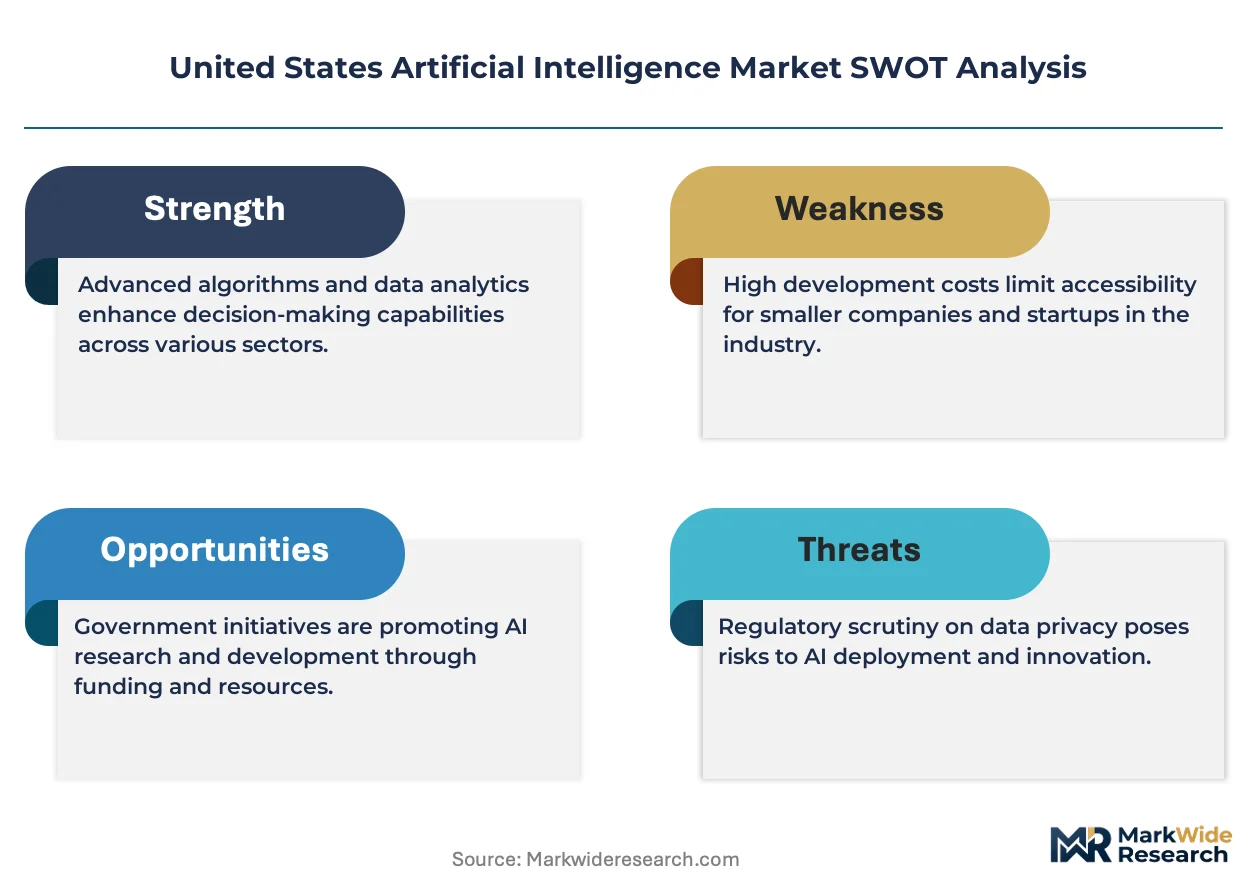
The United States Artificial Intelligence Market functions as a stable compounder, with federal procurement mandates under the NIST AI Risk Management Framework providing predictable demand visibility across defense and healthcare verticals.
For Market Incumbents: Acquire compliance documentation capabilities including algorithmic impact assessment tooling and bias testing infrastructure. Defense contractors should secure additional facility security clearances ahead of Pentagon machine learning contract waves, while healthcare AI developers must prioritize FDA 510(k) pathway expertise to defend against emerging diagnostic algorithm vendors. Vertical integration into custom silicon design offers margin protection against NVIDIA supply constraints. For New Entrants and Emerging Players: Launch via federated learning partnerships with hospital networks in Massachusetts and Pennsylvania, where HIPAA-compliant collaboration tools address unmet demand for multi-site clinical trials. Edge manufacturing applications in automotive corridors present the most penetrable white space, with latency-sensitive inferencing hardware underserved by cloud-centric incumbents. Target compliance advisory services as a go-to-market wedge, bundling NIST framework implementation with software deployment. For Investors and Strategic Acquirers: Asymmetric upside sits with vertical specialists possessing pre-approval regulatory assets in healthcare and defense sectors. Long-term viability favors vendors with demonstrated 510(k) clearance velocity and established security clearance infrastructure. Watch FDA software-as-a-medical-device approval timeline divergence as an inflection indicator for healthcare AI revenue recognition predictability.| Strategic Initiative | Industry Significance |
|---|---|
| Custom Silicon Development | In-house accelerator programs reduce dependency on NVIDIA supply constraints and NVLink architectures. |
| Federated Learning Platform Launch | Enables pharmaceutical consortiums to collaborate on drug discovery without centralizing HIPAA-protected records. |
| NIST Framework Certification Investment | Qualifies vendors for Pentagon machine learning contracts and accelerates federal procurement cycles. |
| Edge Computing Hardware Expansion | Addresses latency requirements in Michigan and South Carolina manufacturing automation corridors. |
| Regulatory Advisory Service Buildout | Captures FTC algorithmic fairness enforcement demand from financial services compliance teams in New York. |
Research Approach
Direct dialogue with defense procurement officers, healthcare AI product managers, hyperscaler platform engineers, and FDA regulatory affairs specialists grounded qualitative findings. Secondary validation drew from SEC hyperscaler capex disclosures, Pentagon budget justification documents, FDA 510(k) clearance databases, and NIST AI Risk Management Framework implementation guidance. Bottom-up deployment estimates across cloud, edge, and on-premise configurations triangulated against top-down federal spending projections.
Segmented outputs across the projection horizon reflect modeled splits by application, technology, end user, and deployment architecture, with additional granularity for regulatory compliance tier and security clearance status. CAGRs derive from fitted growth curves calibrated to historical federal AI procurement trajectories and enterprise software bundle attachment rates. Model inputs include hyperscaler infrastructure expansion announcements, foundry capacity roadmaps, and state-level biometric privacy statute enactment patterns.
Several conditions sit outside the modeled scope, including geopolitical disruption to Taiwan semiconductor supply, abrupt shifts in FDA software-as-a-medical-device approval standards, and federal budget sequestration impacts on Pentagon machine learning programs. Deviation in hyperscaler bundling intensity or NIST framework enforcement rigor would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Artificial Intelligence (AI)
Global Deep Learning Neural Networks (Dnns) Market
Artificial Intelligence (AI)
Conversational AI Market
Artificial Intelligence (AI)
Global Artificial Intelligence Chip Market
Artificial Intelligence (AI)
Emotion AI Software Market
Artificial Intelligence (AI)
Intelligent Assistant Embedded Consumer Devices Market
Artificial Intelligence (AI)
Image Recognition Market
Artificial Intelligence (AI)
Enterprise LLM Market
Artificial Intelligence (AI)
Global Artificial Intelligence (AI) Software Market
Artificial Intelligence (AI)
Cloud Natural Language Processing (NLP) Market
Artificial Intelligence (AI)
Artificial Intelligence (AI) Market
Artificial Intelligence (AI)
Global Citizen Services AI Market
Artificial Intelligence (AI)
Cloud Computing Artificial Intelligence (AI) Market
Artificial Intelligence (AI)
Explainable AI Market
Artificial Intelligence (AI)
Global AI Governance Market
Artificial Intelligence (AI)
AI As a Service (Aiaas) Market
Artificial Intelligence (AI)
Smart Home Digital Assistant [Voice] Market