
 Enterprise LLM Market | 2026-2036
Enterprise LLM Market Size, Share, and Industry Trends Forecast 2026-2036
Enterprise LLM Market Insights
Custom silicon is expanding its role in enterprise AI economics as NVIDIA GPUs replace commodity x86 clusters for training and inference workloads. Anthropic leverages proprietary constitutional AI methods to differentiate its Claude family of models for safety-conscious buyers. Microsoft anchors the commercial distribution layer through its Azure OpenAI Service integration with Office and Dynamics ecosystems. Google competes on multimodal capabilities, embedding Gemini across Workspace and Cloud Vertex AI pipelines.
Enterprise large language models are transformer-based neural networks with billions to trillions of parameters, trained on curated text, code, and multimodal corpora, then fine-tuned for domain-specific tasks through reinforcement learning from human feedback or retrieval-augmented generation architectures. Their primary commercial purpose is automating knowledge work at scale — generating documentation, analyzing unstructured data, powering conversational interfaces, and accelerating software development cycles. Cloud-based deployment leads current adoption because hyperscalers abstract infrastructure complexity and offer consumption-based pricing, while on-premises and private cloud variants grow fastest among banking and government end users with data sovereignty requirements. Solution demand concentrates in content generation and code automation where return on investment metrics are most quantifiable, whereas compliance monitoring and fraud detection applications command premium pricing due to regulatory tailwinds and specialized domain adaptation costs.
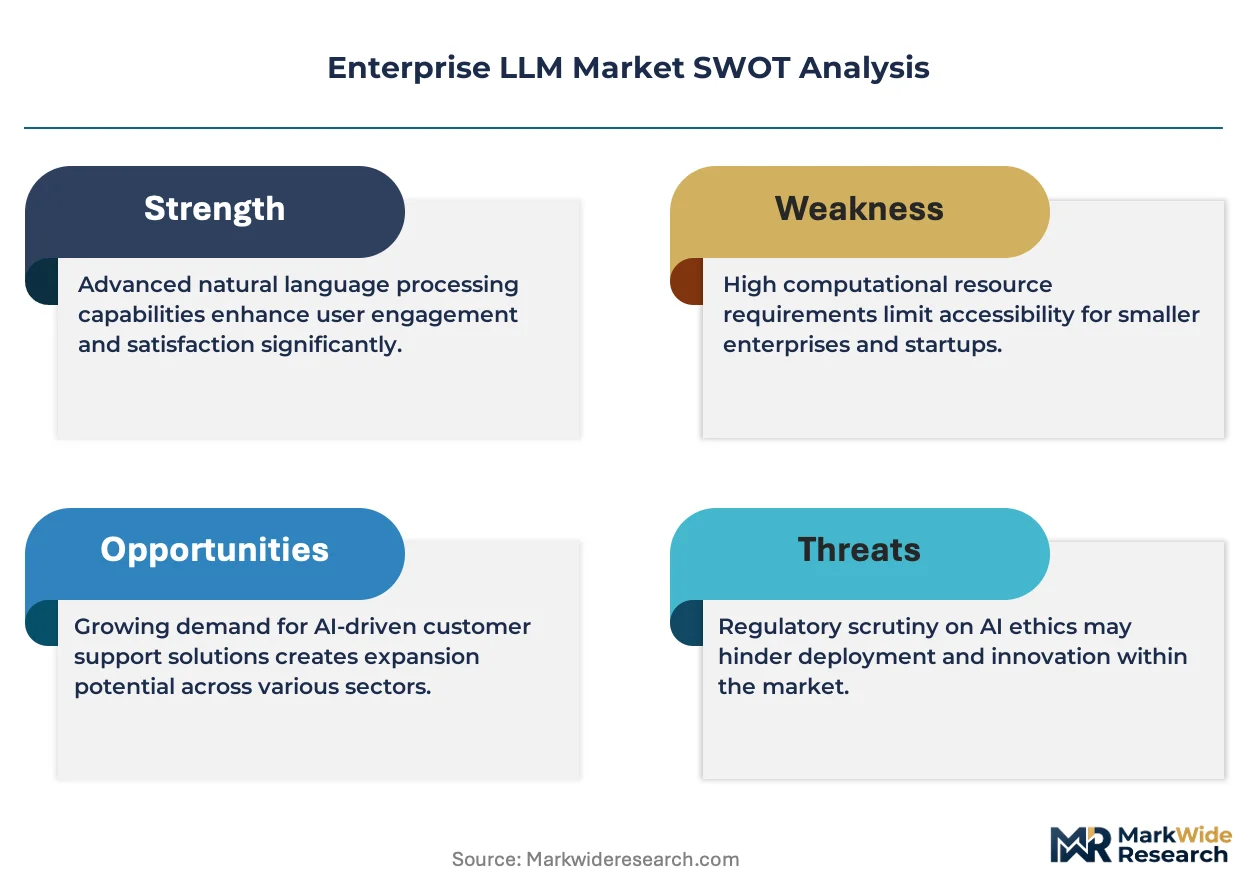
The EU AI Act imposes transparency obligations and systemic risk assessments on general-purpose AI providers, directly shaping product roadmaps for models deployed in European banking and insurance workflows. In the United States, the SEC and FTC scrutinize AI-generated financial advice and discriminatory algorithmic outcomes, while HIPAA constraints limit healthcare data use for model training. China's SAMR and draft algorithmic recommendation regulations create parallel compliance architectures for multinational vendors. Stakeholders must monitor divergence between Brussels-style ex-ante risk classification and Washington's enforcement-driven posture, as this regulatory fragmentation will determine which model architectures and deployment modes achieve cross-border scalability.
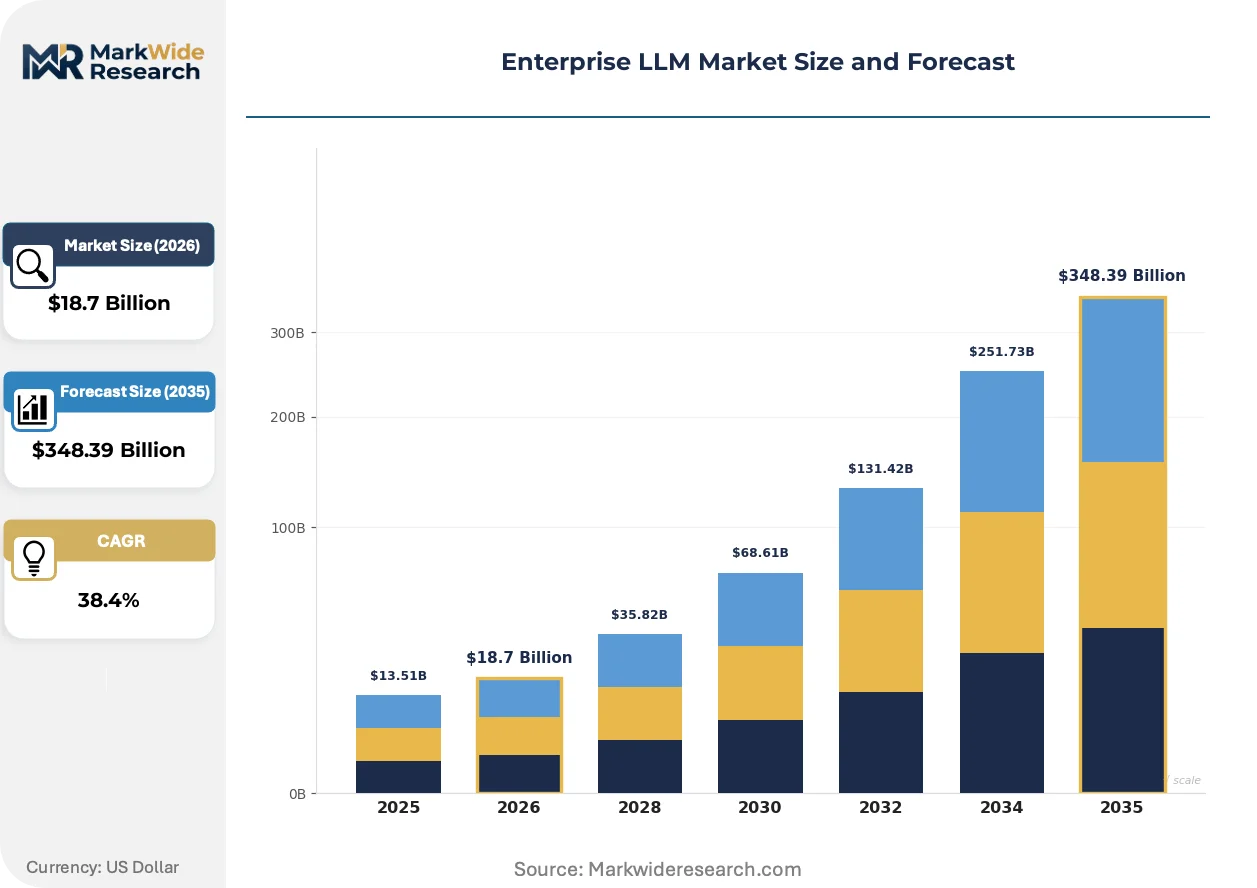
Market Dynamics
Custom silicon deployment is compressing training economics while EU AI Act risk classifications force architectural redesigns for banking and insurance workflows, creating a bifurcation between cloud-native and sovereignty-compliant deployment modes.
Growth Catalysts
- EU AI Act Systemic Risk Mandates:Financial institutions in Germany and France must deploy auditable model architectures, accelerating demand for retrieval-augmented generation pipelines and human-in-the-loop validation systems.
- Healthcare Documentation Automation:HIPAA-compliant fine-tuning services for clinical note generation are expanding addressable spend among US hospital networks and ambulatory care chains.
- Code Synthesis Workloads:Software engineering teams at technology and financial services firms are integrating LLM pair-programming tools into continuous integration pipelines, compressing release cycles.
Market Restraints
- GPU Supply Concentration:Advanced accelerator procurement depends on TSMC's N4 and N3 process nodes, creating allocation bottlenecks for training clusters exceeding ten thousand units.
- Inference Cost Volatility:Electricity pricing in Northern Virginia and Frankfurt data center corridors directly impacts per-token economics for high-throughput applications.
- Regulatory Fragmentation:Divergent ex-ante risk classification in Brussels versus enforcement-driven scrutiny by the SEC and FTC increases compliance architecture costs for cross-border deployments.
Strategic Opportunities
- Sovereign Cloud Deployments:Banking regulators in Switzerland and Singapore are mandating data residency for model training, creating demand for on-premises GPU clusters and private cloud orchestration layers.
- Multimodal Document Processing:Convergence of vision encoders with language models enables automated extraction from scanned contracts and engineering diagrams in construction and logistics verticals.
- India's PLI Scheme for AI:Domestic data center capacity expansion and compute subsidies are lowering barriers for regional model development serving Indic language applications.
Industry Challenges
- Reinforcement Learning from Human Feedback Talent:The scarcity of practitioners capable of designing constitutional AI training protocols and preference dataset curation is constraining model safety refinement timelines.
- Legacy ERP Integration:SAP and Oracle system environments require custom middleware development for real-time LLM orchestration, extending implementation cycles for manufacturing and energy buyers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Enterprise LLM Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $348.39 Billion |
| CAGR (2026 – 2036) | 38.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premises, Cloud-Based, Hybrid, Edge, Private Cloud Solution: Chatbots, Virtual Assistants, Content Generation, Data Analysis, Code Automation, Knowledge Management Application: Customer Support, Compliance Monitoring, Fraud Detection, Sales Enablement, Risk Management End User Industry: Banking, Telecommunications, Manufacturing, Education, Government, Insurance |
| Companies Covered | Anthropic, OpenAI, Microsoft, Google, Amazon Web Services, IBM, NVIDIA, Oracle, Cohere, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Enterprise LLM Market Trends and Innovations
Agentic architectures are displacing single-turn chat interfaces as the dominant interaction paradigm, while regulatory pressure on training data provenance and energy disclosure is reshaping vendor selection criteria.
Retrieval-augmented generation with vector database integration is automating knowledge retrieval for legal research and regulatory compliance teams. Law firms and accounting partnerships in London and New York are deploying these systems to compress document review cycles from weeks to days. The technology is automating first-pass synthesis tasks previously staffed by junior associates, reallocating human capital toward client-facing advisory functions.
The EU AI Act's systemic risk assessment requirements for general-purpose models are mandating pre-deployment safety evaluations and incident reporting mechanisms. Providers serving European banking and insurance workflows must document training data provenance and red-team testing protocols. German automotive manufacturers and French asset managers are prioritizing vendors with established conformity assessment procedures over performance-optimized alternatives.
Consumption-based pricing through API token billing is displacing perpetual license models for enterprise software procurement. Chief information officers at US healthcare systems and UK professional services firms are negotiating spend-commitment tiers with hyperscaler marketplaces. This shift is most visible in financial services, where variable inference costs align budgeting with actual workflow automation uptake rather than upfront capital allocation.
Enterprise LLM Market Segmentation
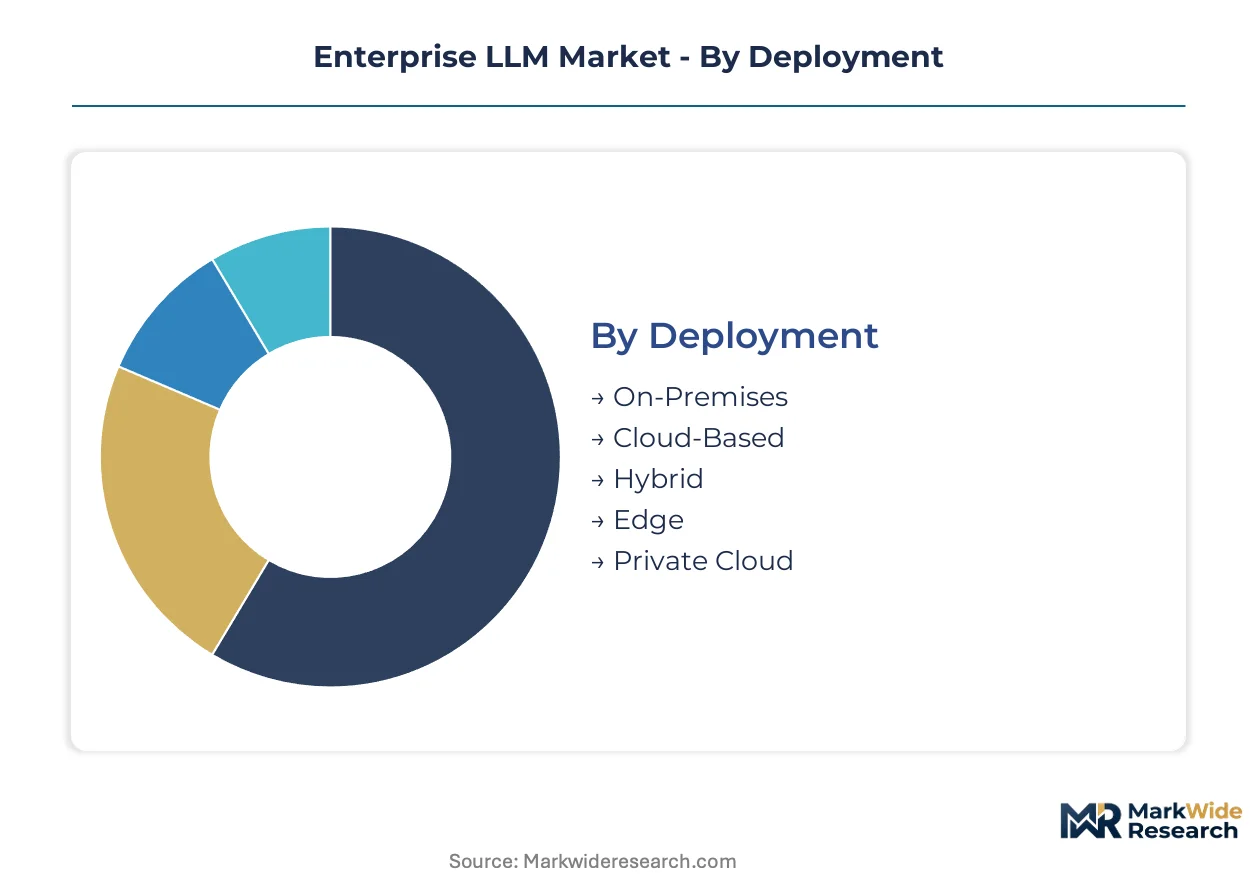
Enterprise LLM procurement patterns diverge sharply across deployment topology, solution architecture, and regulatory exposure. Buyers segment investments by data sovereignty requirements, workflow automation potential, and compliance architecture complexity rather than raw model performance metrics.
Deployment:
Technology stack decisions hinge on inference latency requirements, data residency mandates, and capital expenditure flexibility across infrastructure layers.
- Cloud-Based:Hyperscaler-managed infrastructure abstracts GPU cluster procurement and model serving complexity. US healthcare systems and UK professional services firms concentrate demand here, driven by consumption-based pricing alignment with variable workflow volumes.
- Private Cloud:Dedicated tenant environments on hyperscaler metal satisfy data residency without full infrastructure ownership. German automotive manufacturers and French asset managers prioritize this mode under EU AI Act systemic risk documentation requirements.
- On-Premises:Captive GPU clusters in enterprise data centers serving banking regulators in Switzerland and Singapore with absolute data sovereignty mandates.
- Hybrid:Split architectures training on private infrastructure while serving inference through cloud edge nodes.
- Edge:Model compression and quantization for factory floor and mobile device deployment in manufacturing and logistics corridors.
Mature deployment sits with Cloud-Based configurations. Newer deployment is concentrated in Private Cloud and On-Premises variants.
Solution:
Functional capability modules align pricing tiers with automation depth and domain adaptation requirements.
- Code Automation:LLM pair-programming tools integrated into CI/CD pipelines compress software release cycles. Technology and financial services firms in Northern Virginia and Frankfurt data center corridors drive demand, with electricity pricing directly impacting per-token economics.
- Content Generation:Document synthesis and marketing collateral production with measurable throughput metrics. US hospital networks deploy HIPAA-compliant fine-tuning for clinical note generation.
- Chatbots:Conversational interfaces for customer self-service and internal helpdesk functions.
- Virtual Assistants:Multi-turn dialogue systems with enterprise system orchestration capabilities.
- Data Analysis:Unstructured data extraction and pattern recognition for research and intelligence workflows.
- Knowledge Management:Enterprise search and institutional memory preservation through retrieval-augmented generation pipelines.
Volume concentration favors Code Automation. Margin expansion is steepest in Content Generation with regulatory-compliant vertical variants.
Application:
Workflow integration depth determines implementation complexity and recurring revenue durability for vendors.
- Compliance Monitoring:Automated regulatory surveillance with auditable decision trails commands premium pricing. EU AI Act risk classification mandates accelerate retrieval-augmented generation pipeline adoption in German and French banking workflows.
- Fraud Detection:Real-time transaction anomaly identification with explainable output requirements. Specialized domain adaptation costs support vendor margin structures here.
- Customer Support:Ticket classification and response drafting for high-volume service operations.
- Sales Enablement:Prospect research and proposal generation for B2B revenue teams.
- Risk Management:Document-intensive underwriting and portfolio stress testing automation.
Procurement maturity centers on Customer Support. Compliance Monitoring and Fraud Detection are climbing the fastest as regulatory tailwinds intensify.
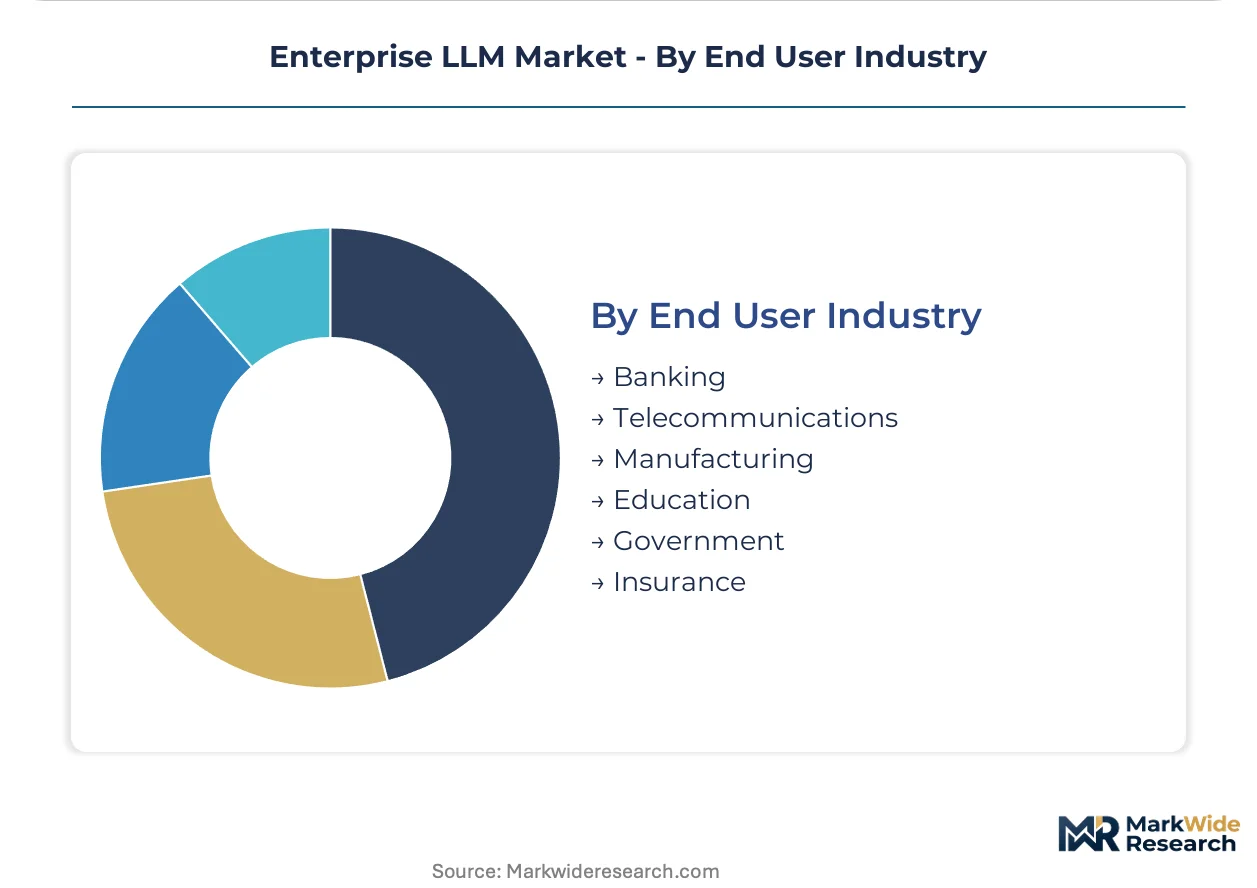
End User Industry:
Sector-specific data governance regimes and automation readiness shape adoption velocity and vendor selection criteria.
- Banking:Systemic risk assessment protocols under EU AI Act mandate auditable architectures. Swiss and Singaporean regulators require data residency for model training, stimulating sovereign cloud and on-premises demand.
- Government:Classified and citizen data handling restrictions favor air-gapped deployments with domestic supply chain verification.
- Insurance:Claims processing automation with regulatory filing integration and actuarial model documentation requirements.
- Telecommunications:Network operations and customer churn prediction with real-time infrastructure telemetry.
- Manufacturing:Engineering diagram analysis and supply chain documentation through multimodal vision-language convergence.
- Education:Personalized tutoring and administrative workflow automation with student privacy constraints.
Established integration sits with Telecommunications. Banking and Government are gaining share fastest through compliance-driven procurement mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cloud infrastructure density and enterprise software spending concentrate demand in the United States, while EU AI Act compliance mandates reshape procurement patterns across European banking corridors. Regulatory fragmentation between Brussels-style risk classification and Washington's enforcement posture determines cross-border scalability for model architectures.
United States
HIPAA-compliant fine-tuning services and SEC scrutiny of AI-generated financial advice drive healthcare and banking procurement. Northern Virginia data center corridors host high-throughput inference workloads where electricity pricing directly impacts per-token economics. Chief information officers at hospital networks negotiate spend-commitment tiers with hyperscaler marketplaces.
Germany
Automotive manufacturers and asset managers prioritize vendors with EU AI Act conformity assessment procedures over performance-optimized alternatives. The KBA and BaFin coordinate systemic risk documentation requirements for model deployments in manufacturing and financial workflows. Frankfurt banking clusters accelerate demand for retrieval-augmented generation pipelines with human-in-the-loop validation systems.
United Kingdom
Law firms and accounting partnerships in London deploy retrieval-augmented generation to compress document review cycles from weeks to days. The Financial Conduct Authority scrutinizes algorithmic outcomes in insurance underwriting automation. Professional services clusters reallocate junior associate labor toward client-facing advisory functions as first-pass synthesis tasks automate.
France
ANSM and CNIL oversight shapes healthcare and data governance requirements for clinical documentation systems. Paris-based asset managers mandate auditable model architectures under EU AI Act systemic risk classifications. French banking workflows prioritize pre-deployment safety evaluations and red-team testing protocol documentation.
Singapore
Monetary Authority of Singapore mandates data residency for model training, stimulating sovereign cloud and on-premises GPU cluster demand. Swiss and Singaporean banking regulators coordinate cross-border compliance architectures for multinational vendors. Domestic data center capacity expansion supports regional model development serving Southeast Asian language applications.
Enterprise LLM Market Competitive Landscape
Strategic partnerships dominate the current landscape as hyperscalers integrate foundation models into productivity software ecosystems. The vendor base organizes around three archetypes: cloud-native infrastructure providers, safety-focused model developers, and silicon manufacturers controlling training economics. Competitive moves concentrate on portfolio diversification into multimodal capabilities and geographic expansion through sovereign cloud deployments. Technology licensing agreements and vertical integration into custom accelerator production represent secondary vectors.
Within the safety-focused model developer tier, Anthropic and Cohere occupy positions emphasizing constitutional AI methods and enterprise customization. Microsoft and Google anchor the commercial distribution layer through Azure and Cloud Vertex AI integrations. NVIDIA sits within the silicon tier, supplying advanced accelerators whose allocation bottlenecks shape training cluster economics for providers exceeding ten-thousand-unit procurement thresholds.
| Leading Market Players |
|---|
| Anthropic |
| OpenAI |
| Microsoft |
| Amazon Web Services |
| IBM |
| NVIDIA |
| Oracle |
| Cohere |
| Others |
Pricing and Supply Chain Analysis
Captive silicon fabrication at NVIDIA and TSMC anchors supply positioning while creating asymmetric pricing power for training cluster procurement. Cloud hyperscalers pass through accelerator scarcity premiums via consumption-based token billing, compressing margins for high-throughput inference workloads in Northern Virginia and Frankfurt corridors.
Pricing Analysis
Volume concentration in cloud-based API consumption runs against margin expansion in sovereign cloud and on-premises deployments. Three-tier pricing structure across premium, standard, and economy levels stratifies by compliance certification depth and data residency guarantees. Pricing pressure stems from electricity cost volatility in hyperscaler data center corridors, with Frankfurt and Northern Virginia buyers absorbing per-token cost fluctuations. Banking and government segments show lowest price sensitivity due to absolute data sovereignty mandates, while mid-market software firms drive standard-tier commoditization.
Supply Chain Analysis
India's PLI scheme for AI compute and domestic data center expansion is reshaping regional sourcing patterns for Indic language model development. Advanced accelerator supply draws from Taiwan's TSMC foundries, NVIDIA's design centers in the United States, and assembly integration in South Korea and Malaysia. Single-source vulnerability concentrates at the N3 and N4 process node layer, where allocation bottlenecks constrain training clusters exceeding ten-thousand-unit thresholds. Distribution runs through hyperscaler marketplaces with spend-commitment tiers, supplemented by direct GPU cluster procurement for sovereign cloud and air-gapped government deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
TSMC foundry allocation scarcity props pricing power for incumbent silicon vendors, constraining training economics for model providers without secured capacity commitments.
For Market Incumbents: Hedge against regulatory fragmentation by architecting dual compliance tracks for EU AI Act systemic risk documentation and SEC enforcement-driven scrutiny. Prioritize backward integration into custom accelerator design to secure TSMC N3 allocation independent of NVIDIA procurement queues. Channel control through Azure and Cloud Vertex AI ecosystem lock-in defends against open-source model commoditization.
For New Entrants and Emerging Players: Capture white-space in sovereign cloud orchestration layers serving Swiss and Singaporean banking regulators with data residency mandates. Target India's PLI-subsidized domestic compute infrastructure for Indic language foundation models with lower capital barriers. Go-to-market positioning as constitutional AI specialists with pre-packaged conformity assessment procedures accelerates European banking procurement cycles.
For Investors and Strategic Acquirers: Exit pathways concentrate in hyperscaler acquisition of safety-focused model developers with established EU AI Act compliance architectures. Long-term viability favors vendors with multimodal capability pipelines and sovereign cloud deployment modes across the analysis window. Watch TSMC foundry allocation announcements as inflection signal for training economics compression.
| Strategic Initiative | Industry Significance |
|---|---|
| Constitutional AI Certification | Pre-packaged EU AI Act conformity assessment accelerates German and French banking procurement. |
| Sovereign Cloud Deployment | On-premises GPU clusters satisfy Swiss and Singaporean regulatory data residency mandates. |
| Multimodal Capability Expansion | Vision-language convergence enables automated extraction from engineering diagrams in manufacturing. |
| Retrieval-Augmented Generation Pipeline | Vector database integration compresses legal document review cycles from weeks to days. |
| Backward Integration into Silicon | Custom accelerator design secures TSMC foundry allocation independent of NVIDIA procurement queues. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with chief information officers at US hospital networks, platform engineers at hyperscaler marketplaces, regulatory affairs leads at German automotive manufacturers, and procurement directors at French asset managers combined with SEC and FTC enforcement records, EU AI Act implementation guidance, TSMC capex disclosures, and hyperscaler earnings reports. Bottom-up deployment topology sizing and top-down enterprise software spend allocation triangulated market boundaries.
Data-stream reconciliation across cloud consumption metrics, on-premises GPU cluster procurement, and private cloud tenant commitments shaped the analytical framework. Segmentation dimensions modeled include deployment topology, solution architecture, application workflow depth, and end-user industry regulatory exposure. CAGRs derived from elasticity-adjusted adoption curves and compliance mandate acceleration timelines. Hyperscaler marketplace spend-commitment tiers and electricity pricing volatility in data center corridors informed inference economics projections.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to TSMC process node allocation shifts and EU AI Act enforcement divergence from SEC scrutiny patterns. Forecasts reflect documented assumptions regarding regulatory implementation timelines and accelerator supply expansion. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Artificial Intelligence (AI)
Robotic Vision Market
Artificial Intelligence (AI)
Global Voice Cloning Market
Artificial Intelligence (AI)
Global Artificial Intelligence-Emotion Recognition Market
Artificial Intelligence (AI)
Global Cognitive Computing Technology Market
Artificial Intelligence (AI)
Smart Home Digital Assistant [Voice] Market
Artificial Intelligence (AI)
Artificial Intelligence (AI) in Radiology Market
Artificial Intelligence (AI)
Computer Vision Market
Artificial Intelligence (AI)
Human-Computer Interaction (HCI) Market
Artificial Intelligence (AI)
Self-Supervised Learning Market
Artificial Intelligence (AI)
AI Search Engine Market
Artificial Intelligence (AI)
Global Artificial Intelligence in E-Commerce Market
Artificial Intelligence (AI)
Artificial Intelligence for IT Operations (Aiops) Market
Artificial Intelligence (AI)
AI Task Manager App Market
Artificial Intelligence (AI)
Generative AI in Coding Market
Artificial Intelligence (AI)
AI in Retail Market
Artificial Intelligence (AI)
Global Cognitive Automation Market