
 Generative AI Market | 2026-2036
Generative AI Market Size, Share, and Industry Trends Forecast 2026-2036
Generative AI Market Intelligence
Media and entertainment demand is decoupling from traditional software licensing as studios adopt real-time generative pipelines for asset production. NVIDIA anchors the hardware layer with GPU architectures purpose-built for transformer training and inference at scale. OpenAI competes through frontier model releases that reset capability benchmarks across text, code, and multimodal tasks. Google leverages its search distribution and proprietary TPU infrastructure to integrate generative outputs directly into consumer and enterprise workflows.
Generative AI denotes computational systems that learn probability distributions from training corpora and synthesize novel outputs—text, image, audio, code, or molecular structures—through autoregressive or diffusion-based sampling, typically requiring billions of parameters and terascale compute. These systems serve industrial and commercial purposes by automating creative production, accelerating scientific discovery, and enabling natural language interfaces for complex software operations. Platform-as-a-Service offerings capture the deepest margin pools by locking in sustained compute consumption and model customization cycles, while Software-as-a-Service layers face commoditization pressure as open-weight models erode differentiation. Deep Learning remains the dominant technology substrate, though Reinforcement Learning from Human Feedback now determines commercial viability for chat and agentic deployments.
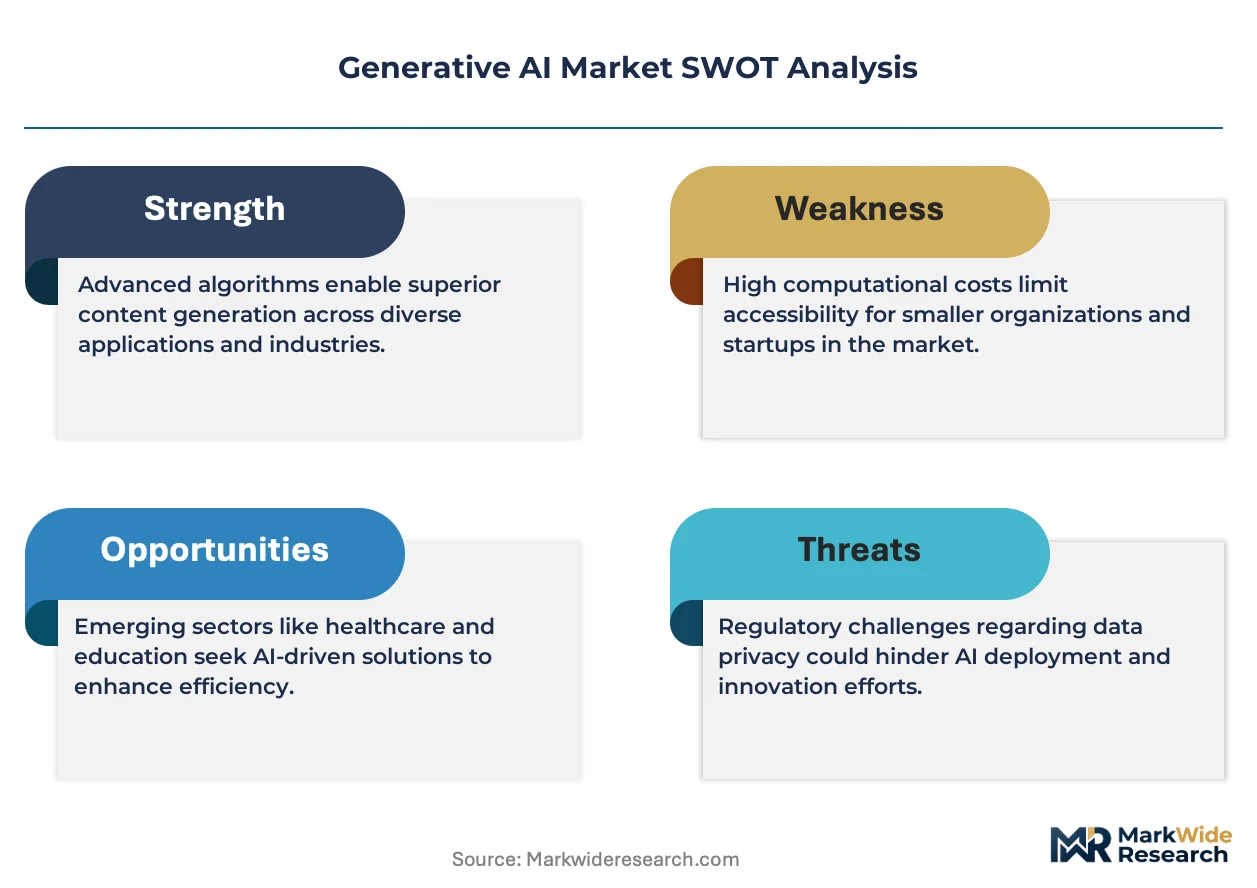
The EU AI Act imposes tiered conformity requirements on general-purpose AI systems, directly shaping product roadmaps for providers seeking European market access. In the United States, the FDA and NIST framework for AI risk management, alongside emerging SEC guidance on algorithmic disclosure for investment advice, fragments compliance burdens across sectors. China's SAMR and cyberspace administration enforce algorithmic recommendation and deep synthesis regulations that constrain model training data sourcing and output distribution. Stakeholders must monitor divergence between Brussels' ex-ante prohibition structure and Washington's sectoral agency approach, as this regulatory fragmentation will determine which model architectures and business models achieve cross-border scalability.
Market Dynamics
Foundation model training clusters concentrate compute demand among hyperscaler cloud providers, creating supply-side bottlenecks for GPU allocation and reshaping how enterprises access generative capabilities.
Growth Catalysts
- EU AI Act tiered compliance:The regulation's risk-based classification system mandates conformity assessments for high-risk applications, creating structured procurement pathways for audited model providers.
- Reinforcement Learning from Human Feedback:This training methodology enables chat and agentic deployments that meet commercial viability thresholds for customer interaction and task completion.
- Financial services automation:Risk assessment and customer interaction workflows accelerate deployment of large language models as institutions seek operational efficiency in regulated environments.
Market Restraints
- GPU supply concentration:NVIDIA's dominance in transformer-optimized architectures creates single-source dependency for training and inference infrastructure.
- Training data sourcing constraints:China's SAMR and cyberspace administration enforce algorithmic recommendation and deep synthesis regulations that limit corpus acquisition and output distribution.
- Energy intensity thresholds:Terascale compute requirements for billion-parameter models impose facility and power constraints on deployment economics.
Strategic Opportunities
- Platform-as-a-Service margin capture:Sustained compute consumption and model customization cycles lock in recurring revenue streams above commoditized Software-as-a-Service layers.
- Scientific discovery acceleration:Molecular structure generation and simulation applications extend addressable demand beyond traditional software markets into pharmaceutical and materials research.
- State-level framework divergence:Emerging United States sectoral approaches by the SEC and FDA create compliance specialization openings for jurisdiction-specific model architectures.
Industry Challenges
- Model transparency auditing:The EU AI Act's documentation requirements for training data provenance and bias assessment demand specialized compliance functions most enterprises lack in-house.
- Cross-border architectural scalability:Divergence between Brussels' ex-ante prohibitions and Washington's agency-by-agency approach fragments product roadmaps and increases development overhead.
- Legacy system integration:Natural language interfaces for complex software operations require substantial reconfiguration of existing enterprise workflows and security architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Generative AI Market |
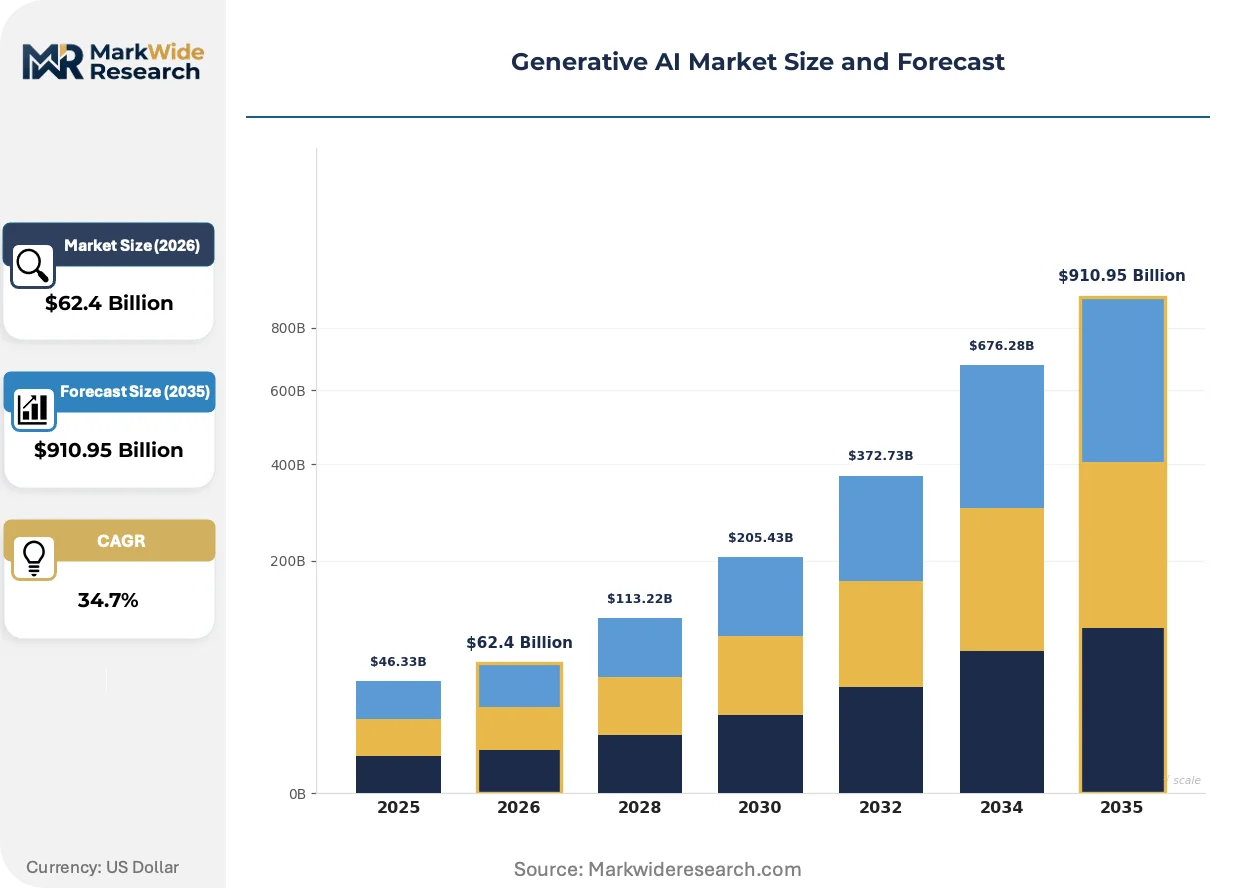
| Market Size in 2026 | $62.4 Billion |
| Market Size in 2035 | $910.95 Billion |
| CAGR (2026 – 2036) | 34.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Content Creation, Image Generation, Code Generation, Music Composition End User: Enterprises, Creative Agencies, Software Developers, Educational Institutions Solution: Platform-as-a-Service, Software-as-a-Service, Customized Solutions, API Integration Technology: Deep Learning, Natural Language Processing, Computer Vision, Reinforcement Learning |
| Companies Covered | Microsoft, OpenAI, NVIDIA, Google, IBM, Amazon Web Services, Anthropic, Meta, Accenture, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Generative AI Market Strategic Shifts & Innovations
Real-time generative pipelines are decoupling media production from traditional asset creation workflows, compressing production timelines and reshaping studio technology procurement priorities.
Diffusion-based image and video synthesis is absorbing rendering workloads previously executed through conventional 3D modeling and physical production stages. Major studios now deploy these pipelines for background generation, character animation, and visual effects compositing. The technology is absorbing capital allocations from established post-production software licenses and physical set construction.
The EU AI Act's tiered conformity framework for general-purpose AI systems directly shapes provider product roadmaps. High-risk application categories trigger mandatory third-party auditing and CE marking requirements. European market access now depends on documentation infrastructure that most foundation model developers are constructing retroactively.
Enterprise procurement of generative capabilities increasingly favors consumption-based pricing tied to inference volume rather than perpetual software licenses. Financial services and media buyers negotiate platform commitments that bundle compute, model access, and customization tooling. This pattern is most visible in the United States, where hyperscaler cloud infrastructure enables flexible scaling without capital-intensive cluster ownership.
Generative AI Market Segmentation
Generative AI deployment patterns diverge sharply by workload type and procurement model. Capital allocation decisions hinge on whether buyers prioritize consumption flexibility, customization depth, or direct infrastructure control.
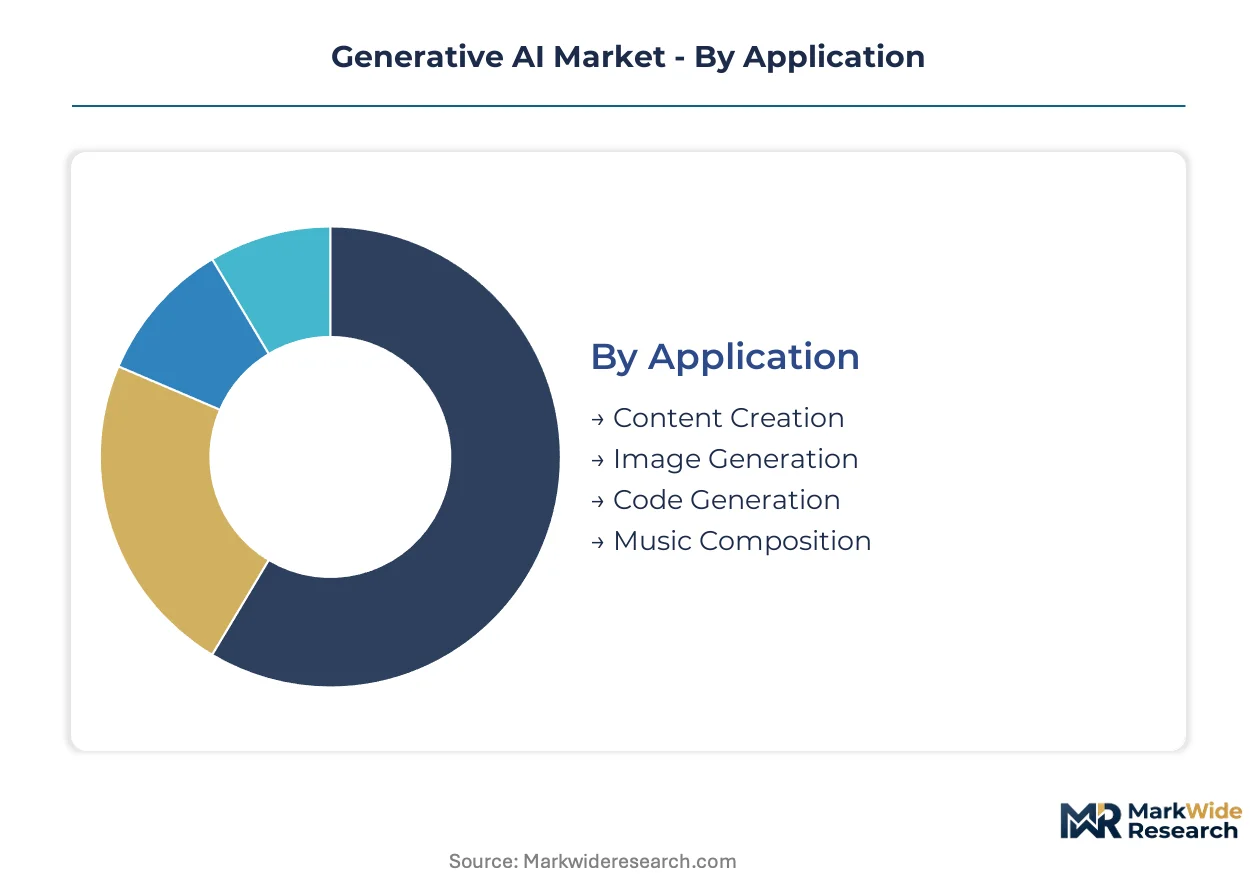
Application:
Capital intensity varies dramatically across use cases, with video and multimodal synthesis demanding orders of magnitude more compute than text-centric workloads.
- Content Creation:Autoregressive and diffusion models automate scriptwriting, marketing copy, and long-form editorial production. Media conglomerates in the United States and South Korea deploy these systems to compress pre-production timelines and reduce freelance writer dependency.
- Image Generation:Latent diffusion architectures synthesize high-resolution visual assets from text prompts. Gaming studios and e-commerce platforms in Japan and France concentrate procurement here, driven by SKU proliferation needs and virtual world asset demands.
- Code Generation:Transformer models trained on software repositories autocomplete functions and generate test suites. Developer tooling vendors integrate these capabilities directly into integrated development environments.
- Music Composition:Neural audio synthesis produces royalty-free soundtracks and adaptive game scores. Streaming services and mobile game publishers in Germany and Brazil represent primary demand nodes.
Most installed capacity flows through Content Creation. Expansion is steepest in Image Generation.
End User:
Procurement sophistication separates buyers with dedicated ML engineering teams from those consuming through managed interfaces.
- Enterprises:Fortune 500 technology, financial services, and pharmaceutical firms operate proprietary fine-tuning pipelines on hyperscaler infrastructure. These buyers negotiate multi-year platform commitments with customized model weights and private deployment options.
- Creative Agencies:Mid-sized production houses access generative capabilities through SaaS subscriptions with usage-based overage pricing. Campaign velocity requirements in the United Kingdom and Italy drive adoption for rapid concept iteration.
- Software Developers:Individual practitioners and venture-backed startups integrate foundation model APIs into application stacks. GitHub Copilot and similar tools have normalized AI-assisted coding workflows across this segment.
- Educational Institutions:Universities and research hospitals deploy models for curriculum development and scientific simulation. Budget constraints favor open-weight models over commercial API access.
Revenue concentration sits with Enterprises. Creative Agencies are climbing the fastest.
Solution:
Margin capture potential inverts between infrastructure ownership and software abstraction layers.
- Platform-as-a-Service:Hyperscalers bundle compute, storage, and model serving into consumption-based contracts. These arrangements lock in sustained GPU utilization and generate recurring revenue through fine-tuning and inference cycles.
- Software-as-a-Service:End-user applications with pre-built interfaces face commoditization pressure as open-weight models erode differentiation. Vendors defend position through workflow integration and proprietary training data.
- Customized Solutions:Systems integrators and boutique AI consultancies build domain-specific deployments for regulated industries. Healthcare and defense buyers in Switzerland and Australia require air-gapped infrastructure and specialized compliance documentation.
- API Integration:Thin-client access to foundation model capabilities enables rapid prototyping without infrastructure investment. Startups and agile enterprises favor this model for speed-to-market.
Platform-as-a-Service commands the deepest margin pools. API Integration is gaining share fastest.
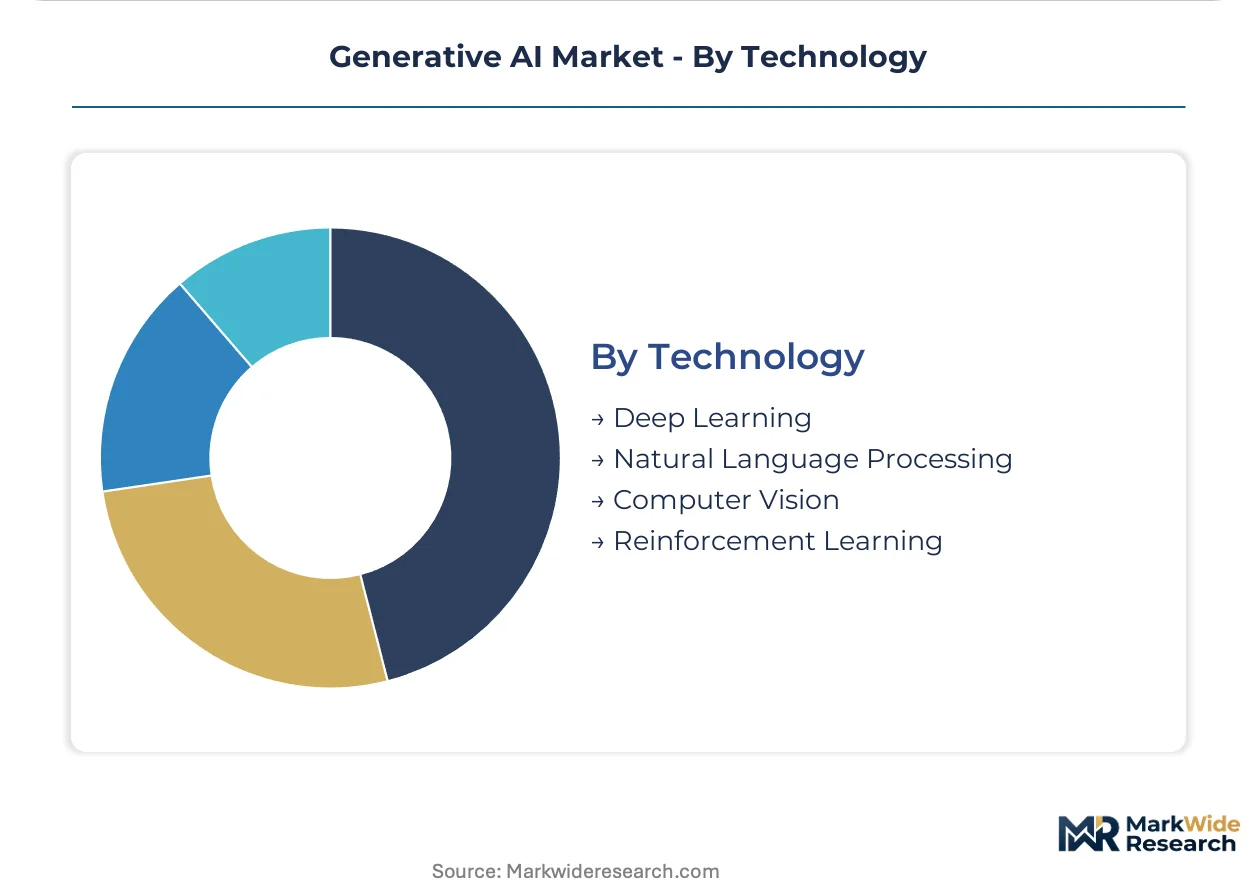
Technology:
Architecture choices determine training cost, inference latency, and output controllability.
- Deep Learning:Multi-layer neural networks with billions of parameters form the substrate for all commercial generative systems. Transformer and diffusion architectures dominate research investment and hyperscaler roadmaps.
- Natural Language Processing:Large language models power text generation, summarization, and conversational interfaces. Enterprise demand in the United States and India concentrates procurement for customer service automation and document analysis.
- Computer Vision:Convolutional and vision transformer architectures enable image classification, object detection, and synthetic media generation. Automotive and retail buyers in Germany and China deploy these for quality inspection and virtual try-on.
- Reinforcement Learning:Human feedback loops align model outputs with user preferences and safety constraints. This methodology now determines commercial viability for chat and agentic deployments.
Deep Learning absorbs the majority of training compute. Reinforcement Learning shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hyperscaler cloud infrastructure in the United States concentrates foundation model training clusters and venture deployment unmatched elsewhere. Regulatory divergence between Brussels and Washington fragments compliance architectures. Demand concentrates visibly where GPU allocation and model serving capabilities lock in enterprise procurement.
United States
Financial services automation and media studio pipelines drive hyperscaler consumption. The SEC issues algorithmic disclosure guidance for investment advice. Seattle and San Francisco Bay Area clusters anchor frontier model development and API distribution.
China
Domestic cloud providers and semiconductor foundries absorb state-directed capital for indigenous AI stack development. SAMR and the cyberspace administration enforce algorithmic recommendation and deep synthesis regulations. Beijing and Shenzhen house the principal training clusters constrained by data sourcing limits.
Germany
Automotive quality inspection and industrial simulation workloads concentrate procurement. The EU AI Act triggers CE marking requirements for high-risk manufacturing applications. Munich and Stuttgart industrial corridors deploy computer vision systems for production line automation.
United Kingdom
Creative agencies and fintech startups accelerate consumption of text and code generation APIs. The Information Commissioner's Office aligns enforcement with GDPR and emerging AI transparency standards. London's Shoreditch and Canary Wharf clusters concentrate developer tooling and financial services deployment.
Japan
Gaming studios and electronics manufacturers integrate diffusion-based asset pipelines. METI coordinates national AI strategy with semiconductor supply security initiatives. Tokyo and Osaka metropolitan areas concentrate R&D partnerships between conglomerates and domestic cloud providers.
Generative AI Market Key Industry Players
Strategic partnerships dominate the current landscape as foundation model developers align with hyperscaler infrastructure and distribution. The vendor structure concentrates among vertically integrated technology conglomerates and specialized research laboratories. Three archetypes prevail: cloud-anchored platforms, frontier research laboratories, and enterprise systems integrators. Competitive moves center on exclusive compute allocation agreements and model customization service expansion.
Within the cloud-anchored platform tier, Microsoft and Amazon Web Services occupy positions binding enterprise consumption to sustained infrastructure utilization. NVIDIA exemplifies the silicon-layer specialist commanding allocation priority across training clusters. These three entities represent the dominant competitive anchors shaping procurement patterns and margin capture architecture.
| Leading Market Players |
|---|
| Microsoft |
| OpenAI |
| NVIDIA |
| IBM |
| Amazon Web Services |
| Anthropic |
| Meta |
| Accenture |
| Others |
Cost & Logistics Intelligence
EU AI Act conformity requirements gate qualified supply access and premium-tier pricing eligibility for foundation model providers seeking European market entry. CE marking obligations for high-risk applications create procurement bifurcation between audited and unaudited model tiers, concentrating margin capture among hyperscaler-backed platforms with compliance infrastructure already deployed.
Pricing Analysis
Distributor margin compression in enterprise SaaS channels is accelerating as hyperscalers bundle compute and model access into direct platform commitments. Consumption-based pricing tied to inference volume now dominates procurement negotiations, with customization depth and private deployment options commanding premium tiers. Price erosion runs through standardized API access as open-weight models commoditize thin-client offerings. Financial services buyers in the United States exhibit lowest price sensitivity due to regulatory compliance requirements, while creative agencies in the United Kingdom and Italy drive hardest volume discount negotiations.
Supply Chain Analysis
Advanced GPU supply rests on Taiwanese semiconductor foundries and NVIDIA's proprietary architecture roadmaps, with South Korean memory fabricators feeding HBM packaging for training clusters. Photolithography equipment and specialty substrates draw from Dutch and Japanese precision engineering suppliers. Single-source vulnerability concentrates in transformer-optimized silicon allocation, where hyperscaler cloud providers lock in multi-year offtake agreements. Distribution runs through direct OEM partnerships and hyperscaler marketplace channels, bypassing traditional enterprise software reseller networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU AI Act's tiered enforcement timeline compounds procurement urgency among European enterprises, accelerating demand for pre-audited model providers with established conformity documentation.
For Market Incumbents: To counter open-weight model commoditization, hyperscaler platforms should deepen API ecosystem lock-in through proprietary fine-tuning tooling and private deployment options. Certification investment in EU AI Act high-risk categories creates defensible procurement pathways against challenger entrants lacking audit infrastructure. Capacity addition in European sovereign cloud regions addresses data residency requirements that increasingly gate public sector contracts. For New Entrants and Emerging Players: Boutique systems integrators represent the most penetrable channel partner type for regulated industry verticals requiring air-gapped infrastructure and specialized compliance documentation. Healthcare and defense buyers in Switzerland and Australia present white-space demand for customized solutions with jurisdictional specificity. A go-to-market angle anchored to FDA or NIST framework alignment captures United States financial services automation budgets. For Investors and Strategic Acquirers: Valuations sit cheapest among domain-specific AI consultancies with established regulatory documentation practices and captive client relationships in regulated verticals. Long-term viability favors acquisition targets with proprietary training data pipelines and fine-tuning infrastructure rather than thin API resellers. The signal to watch is hyperscaler capex allocation shifts toward inference-optimized silicon versus training cluster expansion.| Strategic Initiative | Industry Significance |
|---|---|
| EU AI Act Conformity Investment | CE marking pathways unlock European public sector procurement previously gated to unaudited providers. |
| Hyperscaler Partnership Expansion | Exclusive compute allocation agreements with Microsoft or AWS anchor enterprise platform commitments and recurring revenue. |
| Reinforcement Learning Infrastructure Buildout | Human feedback loop capabilities differentiate commercial chat and agentic deployments from open-weight alternatives. |
| Vertical Fine-Tuning Pipeline Development | Domain-specific model customization for pharmaceutical molecular generation commands premium pricing above generic API access. |
| Sovereign Cloud Region Deployment | European and Middle Eastern data residency requirements increasingly determine public sector and financial services contract eligibility. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary conversations with foundation model developers, hyperscaler platform engineers, enterprise CTOs, and regulatory compliance officers with secondary validation against SEC filings, hyperscaler capex disclosures, and EU AI Act implementation guidance. Bottom-up demand modeling across application segments triangulated against top-down market sizing from training cluster capacity deployment.
Historical reference periods anchored the forecast window to observed foundation model release cycles, hyperscaler infrastructure buildout timelines, and regulatory enforcement phase-ins. Segmentation dimensions modeled include deployment model, organization size, vertical industry, integration complexity, and regional regulatory cluster. CAGRs derived from inference volume elasticity and compute cost decline curves, with inputs from GPU allocation patterns and enterprise procurement survey data.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to regulatory fragmentation between Brussels and Washington, open-weight model capability advances, and energy intensity constraints on terascale deployment. A small set of triggers—including EU AI Act enforcement severity, NVIDIA supply allocation policy shifts, and hyperscaler pricing strategy pivots—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Artificial Intelligence (AI)
Artificial Intelligence (AI) in Retail Market
Artificial Intelligence (AI)
Global Cognitive Computing Technology Market
Artificial Intelligence (AI)
Deep Learning Market
Artificial Intelligence (AI)
Artificial Intelligence (AI) in Sports Market
Artificial Intelligence (AI)
AI-Ready Enterprise Knowledge Graph Market
Artificial Intelligence (AI)
AI Code Assistant Market
Artificial Intelligence (AI)
Artificial Intelligence in Supply Chain Management Market
Artificial Intelligence (AI)
Human-Computer Interaction (HCI) Market
Artificial Intelligence (AI)
AI in Construction Market
Artificial Intelligence (AI)
Automotive Predictive Diagnostic System Market
Artificial Intelligence (AI)
Artificial Intelligence for IT Operations Platform Market
Artificial Intelligence (AI)
Artificial Intelligence and Machine Learning Market
Artificial Intelligence (AI)
Global Voice Assistant Application Market
Artificial Intelligence (AI)
AI Industrial Defect Detection Market
Artificial Intelligence (AI)
Connectivity Constraint Computing Market
Artificial Intelligence (AI)
Europe AI Orchestration Market